
 Philippines Data Center Rack Market | 2026-2036
Philippines Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Data Center Rack Market Insights
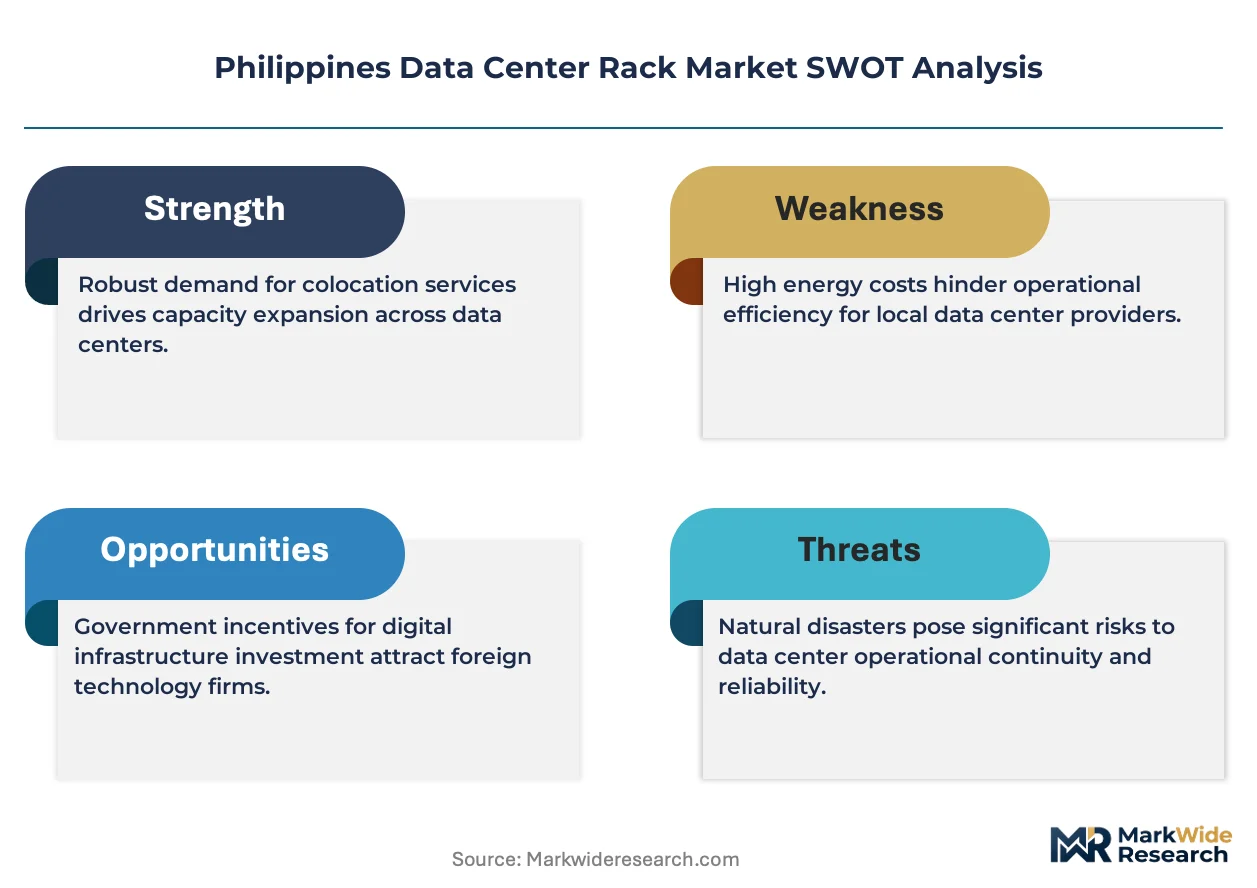
Hyperscale cloud operators is collapsing the traditional enterprise self-build segment as the dominant buyer archetype for data center racks in the Philippines. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments across Luzon. Vertiv Group Corp competes through thermal-optimized rack systems designed for tropical humidity conditions. Eaton Corporation sustains position via modular power distribution units factory-integrated with its rack enclosures.
A data center rack is a standardized metal framework engineered to mount servers, networking equipment, and power distribution hardware, typically fabricated from cold-rolled steel with static load ratings exceeding 1,500 kg and compliance with EIA-310-D dimensional standards. Its primary commercial purpose is to optimize spatial density, cable management, and airflow circulation within climate-controlled facilities. Enclosed rack configurations command premium positioning due to integrated security and dust-sealing requirements in Philippine coastal zones where saline corrosion accelerates hardware degradation. Colocation deployment models absorb the fastest capacity additions as foreign cloud providers lease wholesale space rather than build owned facilities.
The Department of Information and Communications Technology enforces data localization provisions under the National Cybersecurity Plan, mandating domestic storage for government and critical infrastructure data. BIS certification requirements for imported steel structures and the Philippine Electrical Code under the Institute of Integrated Electrical Engineers shape product specifications and import clearance timelines. Stakeholders must monitor regulatory tightening around energy efficiency standards for data centers as the Energy Regulatory Commission develops consumption benchmarking protocols.
Market Dynamics
Hyperscale cloud operators are collapsing the traditional enterprise self-build segment as the dominant buyer archetype for data center racks in the Philippines. This demand concentration is rewiring procurement power toward wholesale colocation providers and away from fragmented corporate IT departments.
Growth Catalysts
- DICT National Broadband Plan:Government-mandated fiber backbone expansion accelerates last-mile connectivity to secondary cities, enabling edge data center deployment outside Metro Manila.
- BPO sector expansion:Contact center operators require redundant rack capacity for 24/7 operations, driving demand for N+1 configurations in Cebu and Clark Freeport zones.
- Fintech transaction growth:Digital payment platforms and neobanks mandate localized data storage under central bank guidelines, stimulating rack deployments in BSP-supervised facilities.
Market Restraints
- Steel import dependency:Cold-rolled steel for rack fabrication relies on Chinese and Korean suppliers, exposing margins to seaborne freight volatility and BIS certification delays.
- Power infrastructure gaps:Grid instability in Visayas and Mindanao limits rack density ambitions outside Luzon, forcing diesel generator redundancy that consumes floor space.
- Saline corrosion:Coastal facility locations in Manila Bay and Cebu City accelerate hardware degradation, necessitating premium enclosed rack configurations that inflate unit economics.
Strategic Opportunities
- Davao corridor development:The southern Philippines remains underserved by hyperscale presence, offering first-mover positioning for tier-2 colocation builds.
- Liquid cooling convergence:Integration of direct-to-chip thermal management with high-density rack designs addresses tropical heat rejection limits for AI training clusters.
- Renewable energy pairing:Green energy certificate trading under ERC frameworks allows rack operators to monetize sustainability credentials for cloud tenant procurement.
Industry Challenges
- Certification bottlenecks:BIS testing protocols for imported steel structures extend lead times by 8-12 weeks, compressing project delivery windows for colocation launches.
- Specialized technician scarcity:Installation and commissioning of precision cooling-integrated rack systems requires skills concentrated in Metro Manila, inflating deployment costs in provincial sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Data Center Rack Market |
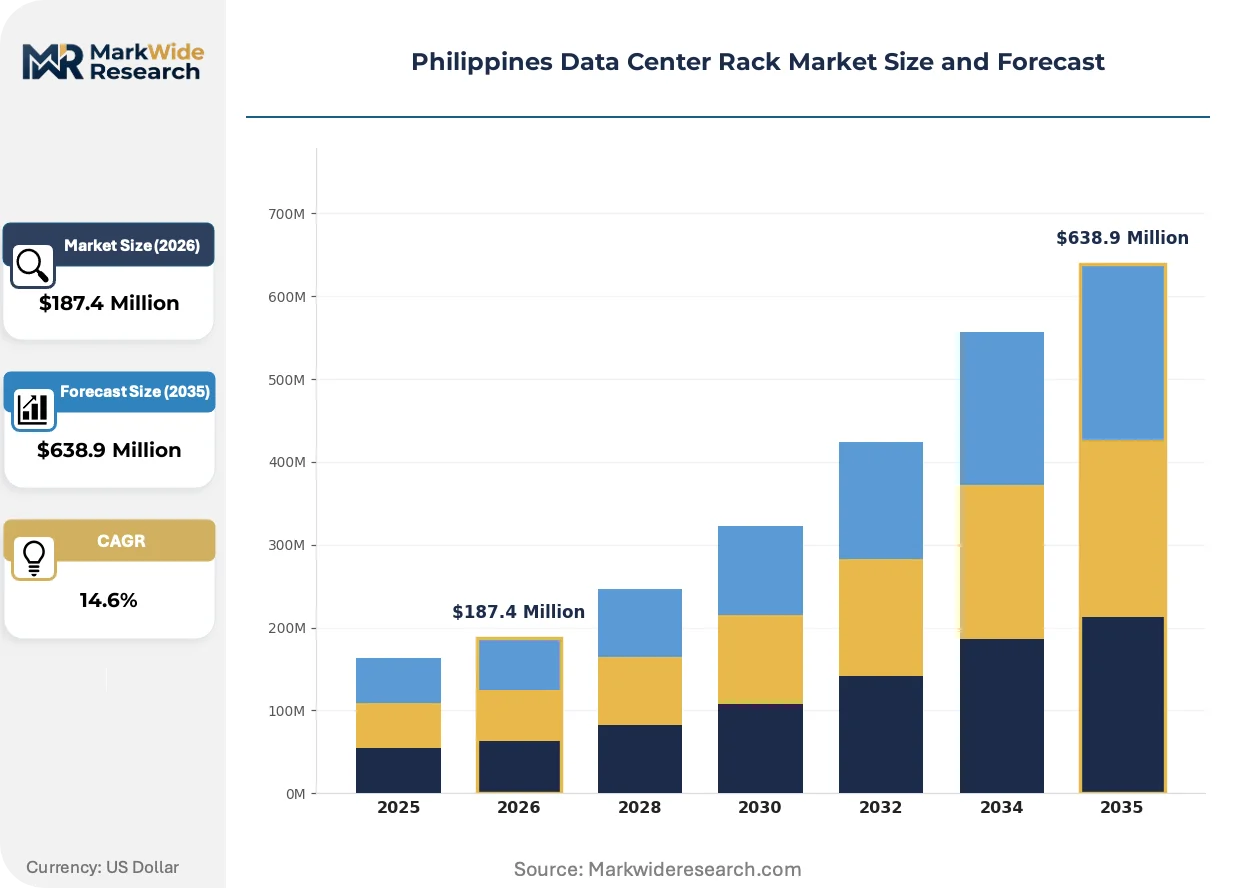
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Server Rack Deployment: On-Premises, Colocation, Edge Data Center, Hybrid End User: IT Companies, Telecom Providers, Financial Institutions, Government Agencies Size: 42U, 24U, 48U, Custom Size |
| Companies Covered | Schneider Electric SE, BTICINO PHILIPPINES INC, Vertiv Group Corp, Eaton Corporation, Black Box Corporation, Dell Inc, Hewlett Packard Enterprise, MFB, Equinix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Data Center Rack Market Trends and Innovations
Active cooling integration and intelligent power distribution are redefining rack architecture as density thresholds climb past 30kW per cabinet. These shifts compress the relevance of legacy air-cooled designs and passive PDU configurations.
Direct liquid cooling is supplanting conventional perimeter CRAC units in hyperscale deployments across Luzon. The technology circulates dielectric fluid through cold plates mounted directly to processor heat spreaders, enabling 50kW-plus rack densities without aisle containment. Cloud operators in the Philippines are adopting this approach ahead of enterprise peers due to tropical ambient temperature constraints that degrade air-cooled efficiency.
The Department of Information and Communications Technology's data localization mandates under the National Cybersecurity Plan are reshaping facility certification requirements. Operators must demonstrate physical security controls and sovereign data segmentation to serve government and financial workloads. This regulatory pressure is fragmenting rack deployment standards, with public-sector-facing facilities requiring enhanced access logging and tamper-evident hardware that private cloud tenants rarely specify.
Wholesale leasing contracts are compressing traditional three-year equipment refresh cycles toward 18-month infrastructure upgrades. Hyperscale tenants negotiate rack-level power and cooling modularity that permits hot-swappable component replacement without aisle shutdown. This behavioral shift concentrates procurement authority with facility engineering teams rather than corporate IT departments, altering vendor sales engagement models across Metro Manila and Cebu.
Philippines Data Center Rack Market Segmentation
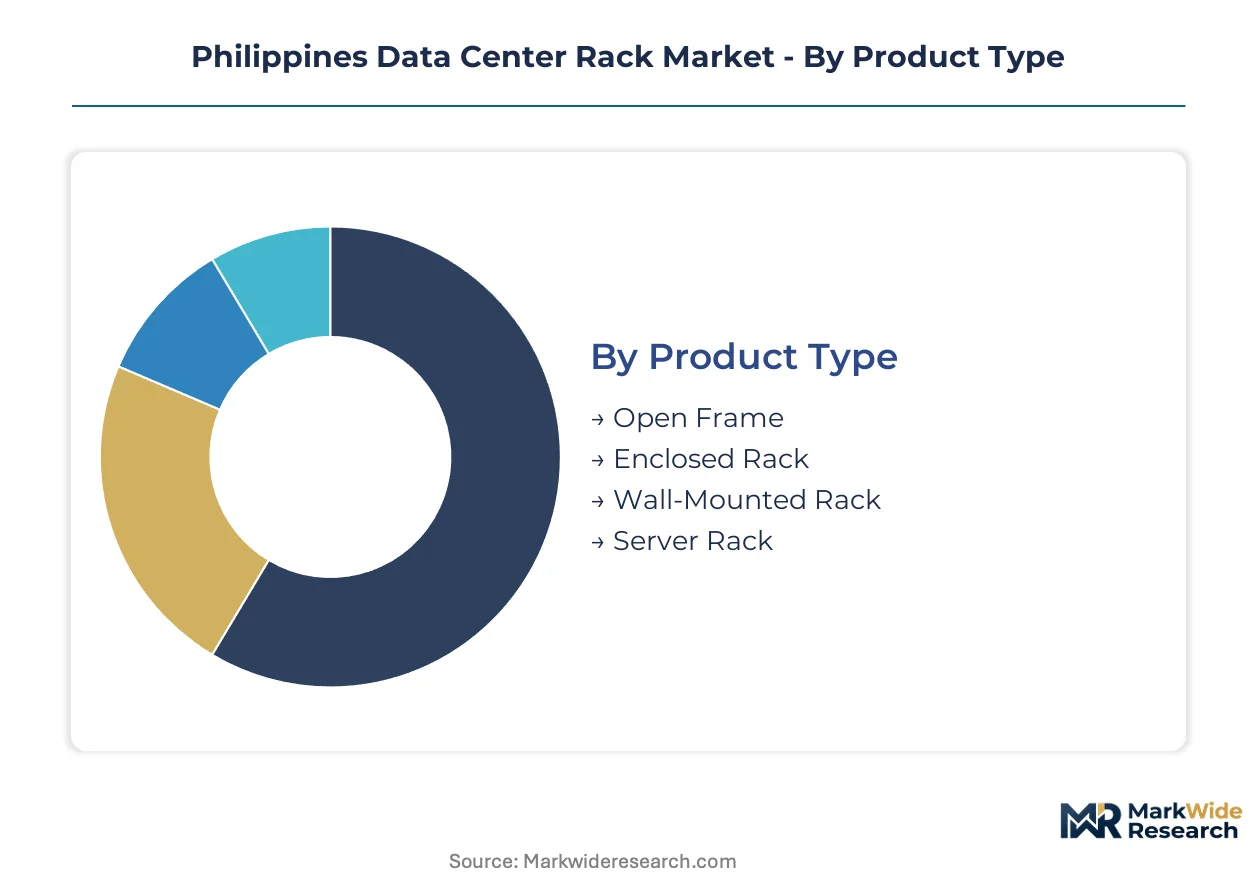
Segmentation in the Philippines data center rack market reveals how procurement authority is migrating from corporate IT departments to facility engineering teams at wholesale colocation providers. Channel dynamics vary sharply across product types and deployment models, with hyperscale tenants driving standardization while edge deployments fragment specifications.
Product Type:
Channel mix splits between direct sales to hyperscale operators for standardized rack systems and distribution through systems integrators for customized enterprise configurations.
- Enclosed Rack:Sealed steel cabinets with integrated cable management and dust filtration address saline corrosion risks in Manila Bay and Cebu coastal facilities. Demand concentrates in BSP-supervised financial data centers where physical security mandates dominate procurement specifications.
- Open Frame:Four-post frameworks without side panels optimize airflow for high-density compute clusters in Luzon hyperscale facilities. DICT data localization requirements are steering government workloads toward enclosed alternatives, compressing open frame share in public-sector channels.
- Wall-Mounted Rack:Compact 12U-18U enclosures serve branch office and retail banking deployments across Visayas island provinces.
- Server Rack:19-inch EIA-310-D compliant frames remain the default specification for enterprise self-build projects in Metro Manila.
Enclosed Rack dominates installed base. Open Frame is where expansion concentrates.
Deployment:
Cost tier segmentation separates capital-intensive owned facilities from operational expenditure models favored by foreign cloud entrants.
- Colocation:Wholesale leasing of rack space by hyperscale tenants now absorbs the majority of new capacity additions across Metro Manila and Cebu. BSP circulars mandating localized data storage for fintech operators are accelerating rack deployments in BSP-supervised colocation facilities.
- Edge Data Center:Modular rack systems deployed in Davao, Iloilo, and Cagayan de Oro address latency requirements for video streaming and gaming platforms. DICT National Broadband Plan fiber extensions are unlocking these secondary city deployments.
- On-Premises:Enterprise-owned facilities persist in BPO contact centers requiring dedicated N+1 redundancy configurations.
- Hybrid:Split workloads across owned and leased infrastructure create complex rack procurement involving both direct vendor relationships and colocation provider specifications.
Colocation captures premium pricing tiers. Edge Data Center is climbing the fastest.
End User:
Customer type determines whether procurement flows through facility engineering teams or corporate IT departments.
- Telecom Providers:PLDT and Globe Telecom are deploying rack infrastructure for 5G core network functions and edge caching nodes. TRAI-equivalent spectrum allocations are driving capital commitments into facility expansion across Luzon.
- Financial Institutions:Neobanks and digital payment platforms under BSP supervision require rack systems with tamper-evident hardware and sovereign data segmentation.
- IT Companies:BPO operators in Cebu and Clark Freeport zones demand redundant rack capacity for 24/7 contact center operations.
- Government Agencies:DICT mandates for domestic data storage are creating dedicated procurement channels with enhanced access logging requirements.
Telecom Providers dominate volume commitments. Financial Institutions is where specification premiums concentrate.
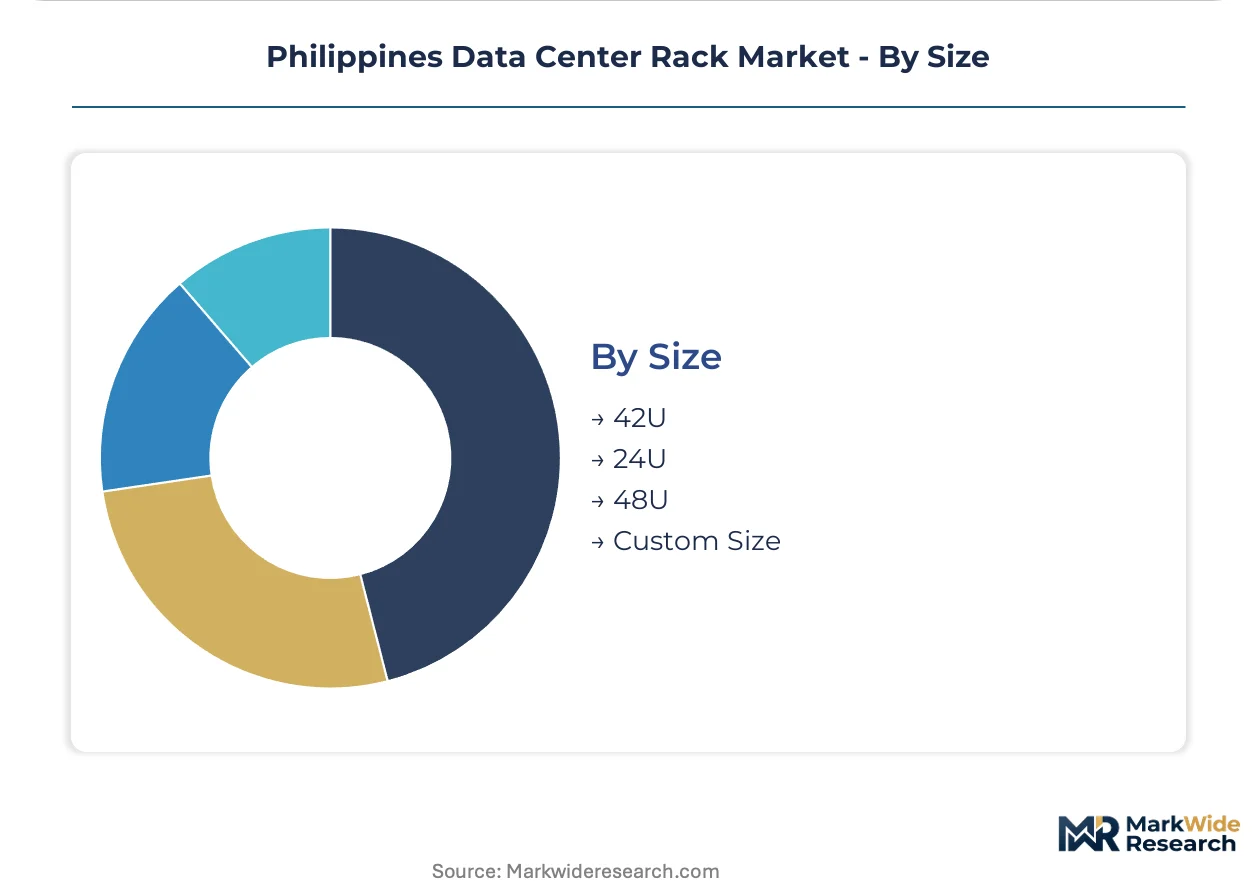
Size:
Volume segmentation reflects density ambitions constrained by Philippine power infrastructure and tropical cooling limits.
- 42U:Standard height for enterprise and colocation deployments balancing floor space efficiency against structural load limits.
- 48U:Extended-height cabinets enable maximum density for AI training clusters in Luzon hyperscale facilities.
- 24U:Half-height configurations serve edge deployments and branch office requirements in secondary cities.
- Custom Size:Non-standard dimensions accommodate legacy equipment migrations and specialized cooling integrations.
42U dominates current installations. 48U is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rack fabrication capacity clusters in Chinese and Korean steel mills serving Philippine colocation builds. Metro Manila and Cebu absorb the majority of deployments, though DICT fiber extensions are unlocking secondary city opportunities.
Metro Manila
Hyperscale cloud operators lease wholesale space across Taguig, Makati, and Quezon City facilities. DICT data localization mandates under the National Cybersecurity Plan require domestic storage for government workloads. The Manila Bay corridor faces saline corrosion risks that inflate demand for enclosed rack configurations with dust-sealing specifications.
Cebu
BPO contact centers drive N+1 redundant rack deployments for 24/7 operations. BSP-supervised fintech operators mandate localized data storage under central bank guidelines. Mactan and Cebu Business Park clusters concentrate colocation capacity serving Visayas island provinces.
Clark Freeport Zone
Disaster recovery and backup facilities exploit seismic stability and power redundancy. BPO operators demand dedicated rack capacity outside Metro Manila congestion zones. The zone's tax incentives attract foreign cloud providers seeking wholesale leasing arrangements.
Davao
The southern Philippines remains underserved by hyperscale presence, offering first-mover positioning for tier-2 builds. DICT National Broadband Plan fiber extensions are reducing latency to secondary cities. Davao del Norte and Davao City industrial zones are emerging as edge data center candidates for gaming and streaming platforms.
Philippines Data Center Rack Market Competitive Landscape
Concentration sits with integrated power and cooling specialists serving hyperscale procurement channels. The market structure favors vendors with factory-integrated thermal management capabilities over standalone rack fabricators. Two strategic archetypes dominate: multinational electrical infrastructure conglomerates with modular PDU integration, and thermal-optimization specialists engineering for tropical humidity. Competitive moves center on capacity expansion into Luzon hyperscale corridors and strategic partnerships with wholesale colocation operators.
Among multinational electrical infrastructure conglomerates, Schneider Electric SE and Eaton Corporation exemplify the integrated power-cooling archetype through factory-integrated modular distribution units. Vertiv Group Corp occupies a position as the thermal-optimization specialist archetype, with engineering focus on high-humidity deployment conditions. These three anchors represent the procurement concentration toward vendors capable of rack-level power and cooling modularity that permits hot-swappable component replacement without aisle shutdown.
| Leading Market Players |
|---|
| Schneider Electric SE |
| BTICINO PHILIPPINES INC |
| Vertiv Group Corp |
| Eaton Corporation |
| Black Box Corporation |
| Dell Inc |
| Hewlett Packard Enterprise |
| MFB |
| Equinix |
| Others |
Pricing and Supply Chain Analysis
Direct liquid cooling adoption is displacing conventional air-cooled rack architectures across Philippine hyperscale facilities, simultaneously shifting supply geography toward Taiwanese and Korean thermal component specialists while compressing pricing premiums for legacy perimeter CRAC-integrated enclosures. This substitution dynamic concentrates procurement leverage with colocation engineering teams capable of specifying factory-integrated power and cooling modularity.
Pricing Analysis
BIS certification requirements dictate the pricing tier structure for imported steel rack structures in the Philippine market. Three-tier pricing structure across premium, standard, and economy levels separates enclosed cabinets with integrated dust sealing and tamper-evident hardware from open-frame configurations and basic server racks. Cost compression in standard-tier open frame units is intensifying because Chinese cold-rolled steel suppliers face freight volatility and extended certification timelines. Wholesale colocation providers exhibit lowest price sensitivity due to pass-through lease structures, while provincial edge deployments in Visayas and Mindanao remain most price-constrained.
Supply Chain Analysis
Strait of Malacca transit underwrites seaborne delivery schedules for cold-rolled steel mill shipments originating from Chinese and Korean fabrication centers serving Philippine colocation builds. Raw material inputs draw from carbon steel coil, zinc-aluminum coating substrates, and precision-machined rail hardware. Single-source vulnerability concentrates in BIS-certified testing laboratories where 8-12 week clearance timelines create project delivery bottlenecks. Distribution runs through direct vendor relationships with hyperscale facility engineering teams and systems integrator channels for customized enterprise configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines data center rack market is positioned within a cyclical recovery phase driven by DICT National Broadband Plan fiber backbone expansion unlocking secondary city edge deployments. Infrastructure capital commitments from hyperscale cloud operators are accelerating procurement velocity beyond replacement-cycle norms.
For Market Incumbents: Compound defensive positioning through captive supply of precision cooling-integrated rack systems and accelerated BIS pre-certification programs for steel enclosure imports. Threat substitution from direct liquid cooling specialists demands thermal engineering investment in dielectric fluid distribution architectures. Capacity addition in Clark Freeport and Davao corridors anchors geographic diversification against Metro Manila congestion.
For New Entrants and Emerging Players: BIS fast-track certification partnerships with DICT-accredited testing laboratories enable market entry ahead of standard clearance timelines. White-space targets concentrate in Davao corridor tier-2 colocation builds and liquid cooling retrofit services for existing Luzon hyperscale facilities. Go-to-market execution should prioritize facility engineering team relationships over traditional corporate IT procurement channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional systems integrators holding established BIS clearance relationships and provincial installation capabilities. Long-term viability framing centers on 5-10 year data localization enforcement trajectory under National Cybersecurity Plan mandates. Acquisition target archetype: thermal-optimization specialists with tropical humidity engineering credentials. Signal to watch: ERC energy efficiency benchmarking protocol finalization as catalyst for premium enclosed rack specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Integration | Enables 50kW-plus rack densities for AI training clusters in tropical ambient conditions. |
| BIS Pre-Certification Investment | Compresses 8-12 week import clearance timelines for steel enclosure deployments. |
| Davao Corridor Capacity Buildout | Captures first-mover positioning in underserved southern Philippines hyperscale market. |
| Renewable Energy Certificate Trading | Monetizes sustainability credentials for cloud tenant procurement under ERC frameworks. |
| Precision Cooling-Integrated Manufacturing | Factory-integrated thermal management differentiates against standalone rack fabricators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of DICT policy circulars, BIS certification registries, and ERC regulatory filings. Primary interviews engaged data center facility engineering directors, colocation procurement leads, BPO IT infrastructure managers, and steel fabrication supply chain specialists. Secondary validation drew from customs import records, hyperscaler capital expenditure disclosures, and National Broadband Plan implementation progress reports. Bottom-up rack deployment tallies triangulate against top-down facility capacity announcements across Metro Manila, Cebu, and emerging secondary markets.
Segmentation dimensions modeled span product type, deployment model, end user vertical, and rack size configuration across the analysis window. Analytical framework incorporates power density trajectories, data localization compliance requirements, and tropical cooling engineering constraints. CAGRs derive from facility pipeline tracking, tenant lease commencement schedules, and import volume trend analysis. Forecast inputs include DICT fiber extension timelines and BSP fintech supervision circular enforcement patterns.
Decision-makers should treat outputs as directional under assumptions of continued DICT infrastructure commitment and stable BIS certification processing capacity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ERC energy efficiency benchmarking protocols and hyperscale tenant density specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Middle East Data Center Rack Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Japan Data Center Market
Data Center Infrastructure
France Data Center Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Data Center Equipment Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
South America Data Center Rack Market