
 Asia-Pacific Data Center Power Market | 2026-2036
Asia-Pacific Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Data Center Power Market Insights
China's GB standards for data center energy efficiency is expanding compliance thresholds for power usage effectiveness across new builds. Schneider Electric leverages its integrated EcoStruxure architecture to anchor medium-voltage and low-voltage portfolios across Southeast Asian deployments. Huawei Digital Power dominates liquid-cooled power supply systems for AI training clusters in Shenzhen and Shanghai. ABB Ltd competes through its Ability Data Center Automation platform, which extends predictive maintenance capabilities to electrical infrastructure.
Asia-Pacific data center power encompasses the generation, conditioning, distribution, and backup of electrical energy specifically engineered to sustain continuous operations of server farms and cloud computing facilities, typically requiring redundancy levels from N+1 to 2N and voltage stability within plus or minus one percent. Its primary commercial purpose is to eliminate downtime for mission-critical digital services ranging from financial transactions to streaming platforms. UPS systems lead the power type category due to their non-negotiable role in bridging milliseconds between grid failure and generator startup, while diesel generators remain the mature baseline despite carbon reduction pressures. Hyperscale operators represent the fastest-growing end user segment as Alibaba, ByteDance, and regional cloud providers scale megawatt-class campuses across Indonesia and Malaysia.
Japan's METI enforces stringent operational efficiency benchmarks that force retrofit investments in aging Tokyo and Osaka facilities, while Singapore's Energy Market Authority imposes moratorium-driven constraints that concentrate development in Johor Bahru across the strait. India's CEA mandates renewable energy quotas for data centers above five megawatt capacity, redirecting procurement toward hybrid solar-diesel architectures. Stakeholders must monitor regulatory divergence between carbon-intensity caps and reliability mandates as they decide between centralized hyperscale builds and distributed edge deployments.
Market Dynamics
Hyperscale cloud operators are compressing deployment timelines for AI training facilities across Southeast Asia, forcing power infrastructure suppliers to pre-certify modular substations and liquid-cooled busways before ground breaks on megawatt-class campuses.
Growth Catalysts
- China's dual carbon goals:Beijing's GB standards for data center energy efficiency are accelerating retrofit demand in aging facilities across the Yangtze River Delta and Pearl River Delta corridors.
- AI training clusters:ByteDance, Alibaba Cloud, and regional providers are commissioning 100-megawatt-plus campuses in Indonesia and Malaysia, requiring high-density power distribution architectures.
- India's PLI scheme:The electronics manufacturing incentive is attracting semiconductor packaging and server assembly operations, creating captive demand for conditioned power infrastructure in Tamil Nadu and Karnataka.
Market Restraints
- Copper and silicon steel volatility:Raw material price swings for transformer cores and busbar systems are compressing margins on fixed-price EPC contracts across the region.
- Singapore land moratorium:The Energy Market Authority's development restrictions have concentrated supply chain capacity in Johor Bahru, creating single-point congestion for cross-strait cable and switchgear logistics.
- Diesel generator carbon intensity:CEA renewable energy quotas for Indian data centers above five megawatts are forcing hybrid architecture complexity without mature battery alternatives at scale.
Strategic Opportunities
- Vietnam's emerging corridor:The Ho Chi Minh City-Da Nang axis offers untapped land and power grid capacity for edge deployments serving ASEAN financial services.
- Liquid cooling convergence:Integration of direct-to-chip thermal management with medium-voltage switchgear is opening integrated power-thermal system sales to AI training operators.
- Japan's METI efficiency mandates:Tokyo and Osaka retrofit requirements are creating aftermarket service contracts for predictive maintenance and power quality optimization.
Industry Challenges
- Medium-voltage commissioning expertise:Shortages of certified technicians for 10-35kV switchgear installation are extending project timelines in Indonesia and the Philippines.
- Legacy UPS synchronization:Integrating modular lithium-ion battery systems with existing static switch infrastructure in 10-15 year old facilities requires custom engineering that fragments supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Data Center Power Market |
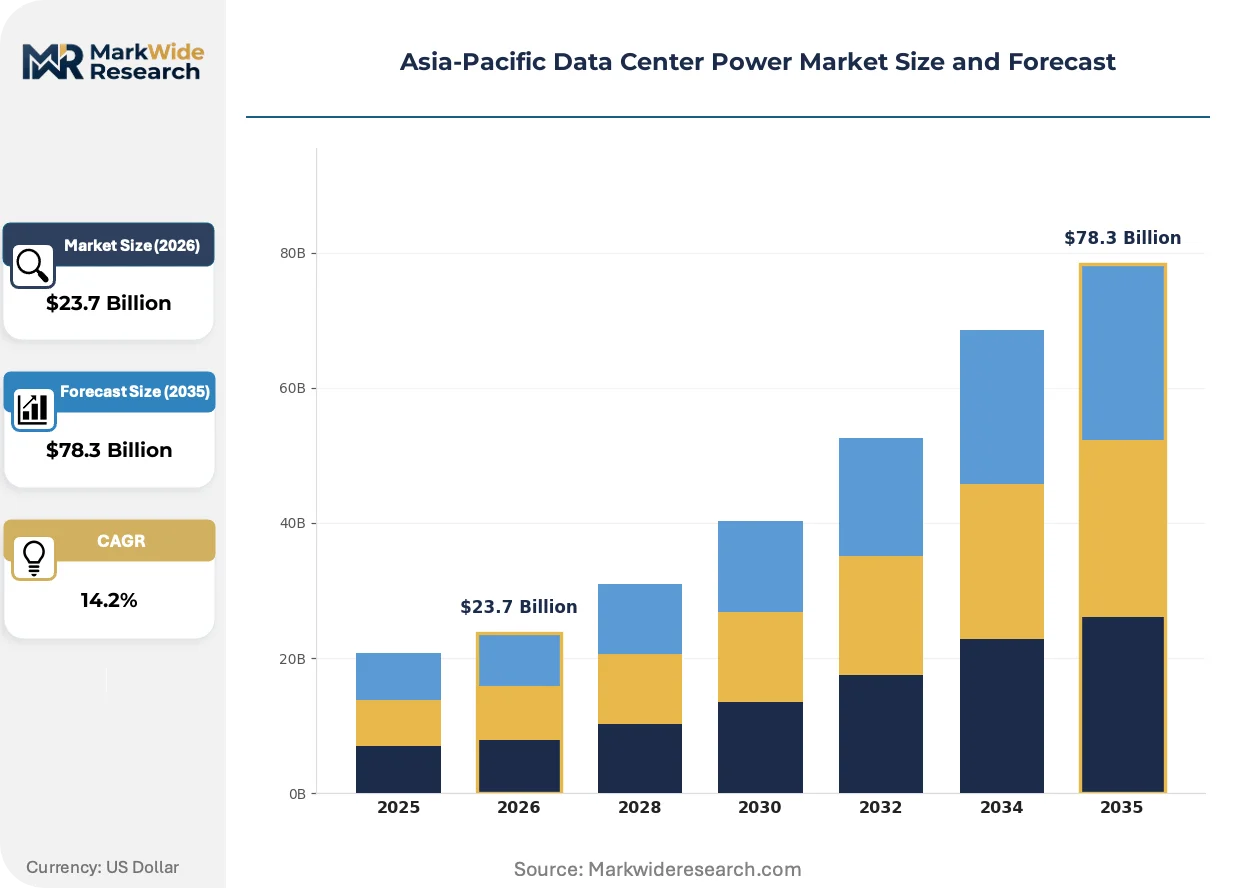
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: UPS, Diesel Generators, Power Distribution Units, Rectifiers End User: Hyperscale Operators, Colocation Providers, Enterprises, Government Agencies Product Type: Cooling Solutions, Power Backup Systems, Racks, Electrical Infrastructure Installation Type: New Build, Retrofit, Modular, Expansion |
| Companies Covered | Huawei Digital Power, ABB Ltd, Schneider Electric, LITEON Technology, Siemens, Eaton Corporation, Delta Electronics, Kehua Data, Vertiv Group Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Data Center Power Market Trends and Innovations
Power infrastructure is converging with thermal management and digital control layers, collapsing what were three separate procurement decisions into unified platform sales. This integration is compressing vendor lists and raising the technical bar for ecosystem participation.
Busway power distribution with integrated tap-off units is expanding into hyperscale halls previously served by traditional cable tray and panelboard architectures. Operators in China's Greater Bay Area are specifying these systems for 50-megawatt AI training floors to enable rapid rack reconfiguration. The technology is expanding into secondary markets as modular construction methods standardize across Southeast Asian deployments.
Japan's METI operational efficiency benchmarks are forcing investments in aging Tokyo and Osaka facilities that exceed simple equipment replacement. The regulation mandates real-time power usage effectiveness monitoring and annual efficiency reporting. Operators are responding by retrofitting transformer tap changers and deploying harmonic filtering to avoid penalties that escalate with facility age.
Hyperscale procurement teams are consolidating vendor relationships from discrete component purchases to multi-year platform agreements spanning medium-voltage switchgear through rack-level PDUs. Channel partners in Singapore and Sydney are losing margin to direct manufacturer engagement on projects above 20 megawatts. This concentration is most visible in financial services verticals where uptime requirements justify premium pricing for single-source accountability.
Asia-Pacific Data Center Power Market Segmentation
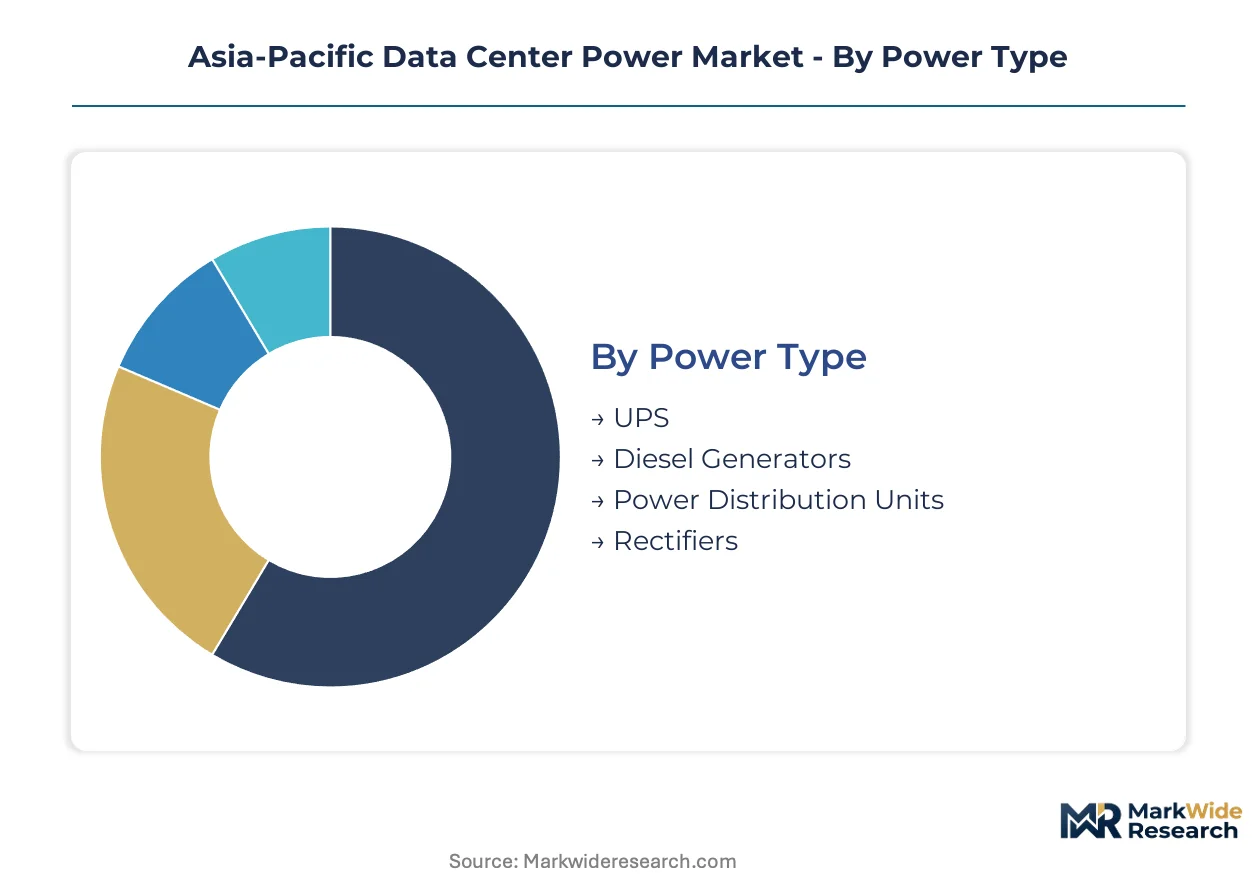
Segmentation in data center power infrastructure reveals how procurement patterns diverge between mission-critical uptime requirements and cost-optimized edge deployments. Understanding these splits enables suppliers to align modular product architectures with specific customer reliability tiers and deployment timelines.
Power Type:
Integration depth varies sharply across this category, with some segments functioning as standalone protection layers while others embed into broader distribution architectures.
- UPS:Double-conversion and line-interactive systems provide millisecond-level ride-through during grid transitions, with lithium-ion battery variants displacing valve-regulated lead-acid in facilities above 10 megawatts. Demand concentrates in Alibaba Cloud and ByteDance campuses across Indonesia's Batam corridor, driven by AI training workloads that cannot tolerate even sub-second interruptions.
- Diesel Generators:These systems remain the non-negotiable baseline for N+1 and 2N redundancy architectures despite carbon reduction pressures. Procurement concentrates in India's Mumbai-Pune corridor where CEA renewable quotas force hybrid solar-diesel configurations without mature battery alternatives at scale.
- Power Distribution Units:Intelligent rack-level PDUs with outlet-level metering embed directly into hyperscale white space designs.
- Rectifiers:AC-DC conversion systems for direct current data halls see niche uptake in telco-anchored facilities.
Volume placements concentrate in UPS systems across new hyperscale builds; the faster expansion belongs to lithium-ion integrated variants displacing legacy battery architectures.
End User:
Customer type determines procurement velocity, with some segments demanding pre-certified modular solutions while others prioritize customization over speed-to-market.
- Hyperscale Operators:Alibaba, ByteDance, and regional cloud providers commission 100-megawatt-plus campuses with compressed deployment timelines, forcing suppliers to pre-certify modular substations before ground breaks. These operators specify busway distribution with integrated tap-off units for rapid rack reconfiguration in China's Greater Bay Area.
- Colocation Providers:Multi-tenant facilities balance standardization against tenant-specific power densities, with Singapore's Energy Market Authority moratorium concentrating development in Johor Bahru across the strait.
- Enterprises:Captive data halls for financial services and manufacturing prioritize uptime over density, extending retrofit cycles.
- Government Agencies:Sovereign cloud and defense-adjacent facilities impose localized supply chain requirements under India's PLI scheme and China's GB standards.
Procurement scale peaks with hyperscale operators; steepest expansion trajectory sits with government agencies mandating domestic content under national semiconductor and cloud sovereignty programs.
Product Type:
Margin structure separates this category, with some segments commanding premium pricing for thermal-electrical integration while others compete as commoditized enclosure hardware.
- Cooling Solutions:Direct-to-chip liquid cooling convergence with medium-voltage switchgear is opening integrated power-thermal system sales to AI training operators in Shenzhen and Shanghai. Huawei Digital Power dominates this segment where thermal management and electrical distribution collapse into unified procurement decisions.
- Power Backup Systems:Battery energy storage systems and flywheel alternatives face deployment barriers in tropical humidity conditions across Southeast Asia.
- Racks:Standardized 19-inch and Open Compute Project enclosures see price pressure from modular construction methods standardizing across Indonesian and Malaysian deployments.
- Electrical Infrastructure:Medium-voltage switchgear and transformer assets anchor long-term service contracts in aging Tokyo and Osaka facilities subject to METI efficiency mandates.
Revenue concentration sits with cooling solutions; the fastest share gains belong to electrical infrastructure retrofit contracts driven by Japan's operational efficiency benchmarks.
Installation Type:
Project modality shapes supplier engagement models, with some segments enabling factory-built standardization while others demand site-specific engineering.
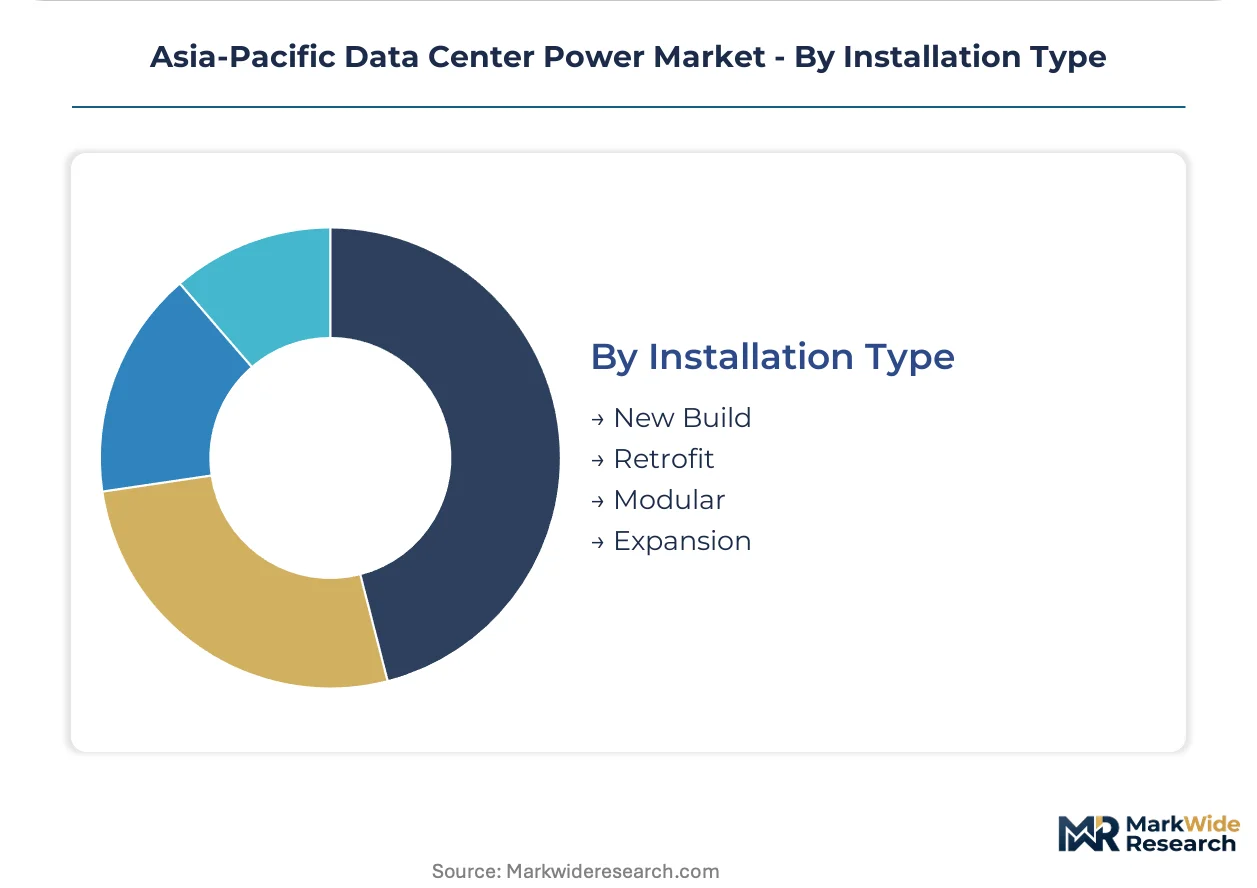
- New Build:Greenfield hyperscale campuses in Vietnam's Ho Chi Minh City-Da Nang axis and Indonesia's Batam corridor enable fully integrated power-thermal designs with pre-fabricated electrical houses. These projects bypass legacy constraints that fragment margins in brownfield environments.
- Retrofit:Aging facilities in Tokyo and Osaka face METI-mandated efficiency investments exceeding simple equipment replacement, requiring harmonic filtering and transformer tap changer upgrades.
- Modular:Prefabricated power modules with integrated switchgear and UPS compress commissioning timelines for edge deployments.
- Expansion:Campus-scale additions in India's Tamil Nadu and Karnataka electronics manufacturing zones create captive demand for conditioned power under PLI scheme incentives.
Project pipelines concentrate in new build deployments; the most rapid scaling belongs to modular installations serving time-compressed AI facility commissioning across Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Batam free trade zone and Malaysia's Iskandar special economic corridor are concentrating hyperscale investment, redirecting supply chain capacity from Singapore's constrained land market across the strait.
China
GB standards for data center energy efficiency are accelerating retrofit demand in aging facilities. The dual carbon goals mandate real-time power usage effectiveness monitoring. Yangtze River Delta and Pearl River Delta corridors host 100-megawatt-plus AI training campuses from ByteDance and Alibaba Cloud.
India
CEA renewable energy quotas for data centers above five megawatts force hybrid solar-diesel architectures. The PLI scheme for electronics manufacturing attracts semiconductor packaging operations. Mumbai-Pune corridor and Tamil Nadu electronics zones create captive demand for conditioned power infrastructure.
Japan
METI operational efficiency benchmarks force investments exceeding simple equipment replacement in Tokyo and Osaka facilities. The regulation mandates annual efficiency reporting and harmonic filtering upgrades. Aging transformer tap changers require aftermarket service contracts for predictive maintenance.
Singapore
Energy Market Authority land moratoriums have concentrated development in Johor Bahru across the strait. Cross-strait cable and switchgear logistics face single-point congestion. Multi-tenant colocation facilities balance standardization against tenant-specific power densities under development restrictions.
Vietnam
Ho Chi Minh City-Da Nang axis offers untapped land and power grid capacity for edge deployments. ASEAN financial services drive demand for rapid rack reconfiguration capabilities. Greenfield campuses enable fully integrated power-thermal designs with pre-fabricated electrical houses.
Asia-Pacific Data Center Power Market Competitive Landscape
European electrical infrastructure producers anchor one tier; Asia-Pacific specialists hold integrated power-thermal positions. The market structures around three strategic archetypes: full-platform providers, component specialists, and emerging liquid-cooling integrators. Consolidation pressures favor multi-year platform agreements over discrete component purchases. Geographic expansion and technology licensing dominate competitive moves as hyperscale procurement teams compress vendor lists.
Within the integrated platform tier, Schneider Electric and ABB Ltd occupy positions spanning medium-voltage switchgear through automation software. Huawei Digital Power exemplifies the Asia-Pacific specialist archetype, anchoring liquid-cooled power supply system deployment for AI training clusters. These three companies represent the concentration trajectory as procurement shifts from discrete purchases to unified platform accountability.
| Leading Market Players |
|---|
| Huawei Digital Power |
| ABB Ltd |
| Schneider Electric |
| LITEON Technology |
| Siemens |
| Eaton Corporation |
| Delta Electronics |
| Kehua Data |
| Vertiv Group Corp. |
| Others |
Pricing and Supply Chain Analysis
Redundancy-grade bifurcation between N+1 and 2N architectures separates premium-priced integrated platforms from commodity component sales, with hyperscale operators in China's Greater Bay Area and Indonesia's Batam corridor commanding volume discounts while smaller colocation facilities in Johor Bahru absorb cross-strait logistics premiums. This tiered structure concentrates procurement leverage among ByteDance and Alibaba Cloud, compressing margins for suppliers locked into fixed-price EPC contracts when copper and silicon steel volatility strikes.
Pricing Analysis
Compressed lead-time premiums dominate hyperscale procurement, with pre-certified modular substations and liquid-cooled busways commanding 15-25 percent markups over standard delivery schedules. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth—UL-listed and GB-compliant systems anchor the top tier, while non-certified regional alternatives serve price-sensitive edge deployments. Cost compression in mid-tier electrical infrastructure is intensifying because fixed-price contracts expose EPC integrators to raw material swings without pass-through mechanisms. Hyperscale operators exhibit lowest price sensitivity, prioritizing single-source accountability and uptime guarantees over per-unit cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with transformer core laminations and high-purity copper busbar feedstock concentrated in Chinese and South Korean metallurgical operations. Manufacturing gravity centers on Shenzhen and Shanghai for liquid-cooled power supply systems, with secondary assembly nodes emerging in Vietnam's northern industrial provinces. Raw material dependencies span silicon steel for magnetic cores, electrolytic copper for conductivity, and rare-earth elements for harmonic filtering components. Tariff exposure runs through cross-strait cable and switchgear logistics bottlenecked at Johor Bahru. Distribution runs through direct manufacturer engagement on projects above 20 megawatts, bypassing traditional channel partners in Singapore and Sydney.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation is accelerating as hyperscale procurement teams compress supplier lists from discrete component purchases to unified platform agreements, forcing sub-scale electrical infrastructure specialists into acquisition targets or exit.
For Market Incumbents: Cement platform dominance by deepening backward integration into transformer core manufacturing and lithium-ion battery module assembly, neutralizing margin erosion from copper volatility. Acquire predictive maintenance software capabilities to capture Japan's METI-mandated efficiency retrofit contracts. Priority lever: pre-certify modular substations for Vietnam's Ho Chi Minh City-Da Nang corridor before ground breaks on greenfield AI campuses. For New Entrants and Emerging Players: Begin with liquid-cooled power-thermal integration for AI training clusters in Shenzhen and Shanghai, where Huawei Digital Power's dominance leaves room for specialized thermal-electrical subsystem suppliers. Target Vietnam's emerging edge deployment corridor with prefabricated electrical houses serving ASEAN financial services. Go-to-market angle: factory-built standardization compressing commissioning timelines against site-engineered alternatives. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists holding liquid-cooling integration capabilities given ByteDance and Alibaba Cloud's 100-megawatt-plus commissioning timelines. Long-term viability favors platforms spanning medium-voltage switchgear through rack-level PDU accountability over discrete component vendors. Signal to watch: hyperscale procurement teams consolidating vendor relationships to sub-10 preferred suppliers per geography.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Substation Pre-Certification | Compresses deployment timelines for AI training campuses in Indonesia and Malaysia. |
| Liquid Cooling-Thermal Integration | Captures unified procurement decisions collapsing power and thermal layers. |
| Predictive Maintenance Platform Deployment | Secures METI-mandated retrofit contracts in aging Tokyo and Osaka facilities. |
| Backward Integration into Core Components | Neutralizes silicon steel and copper volatility compressing EPC margins. |
| Vietnam Manufacturing Footprint Establishment | Positions for Ho Chi Minh City-Da Nang edge deployment demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving data center facility engineers, EPC procurement directors, hyperscale cloud infrastructure planners, and power quality specialists. CEA renewable energy mandates, METI efficiency benchmarks, and Singapore Energy Market Authority development restrictions provided regulatory calibration. Bottom-up project pipeline analysis across China's Yangtze and Pearl River Delta corridors, India's Mumbai-Pune and Tamil Nadu zones, and Southeast Asian hyperscale campuses triangulated against top-down market sizing.
Granularity-level modeling distinguished power type segments by integration depth, end-user categories by procurement velocity, and product types by margin structure across the projection horizon. Installation type splits—new build, retrofit, modular, expansion—were modeled separately given divergent supplier engagement economics. CAGRs derived from capacity-weighted project pipeline analysis, hyperscale capex disclosure patterns, and regulatory mandate implementation timelines. AI training cluster power density requirements and liquid-cooling adoption curves served as sector-specific demand drivers.
Underlying measurement precision varies by segment; hyperscale operator deployments carry tighter precision than fragmented enterprise retrofits. Forecasts reflect assumptions on CEA renewable quota enforcement, METI penalty escalation schedules, and Singapore moratorium duration. Deviation in hyperscale procurement consolidation velocity or raw material price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Indonesia Data Center Rack Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
United States Data Center Server Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market