
 Spain Data Center Rack Market | 2026-2036
Spain Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Data Center Rack Market Insights
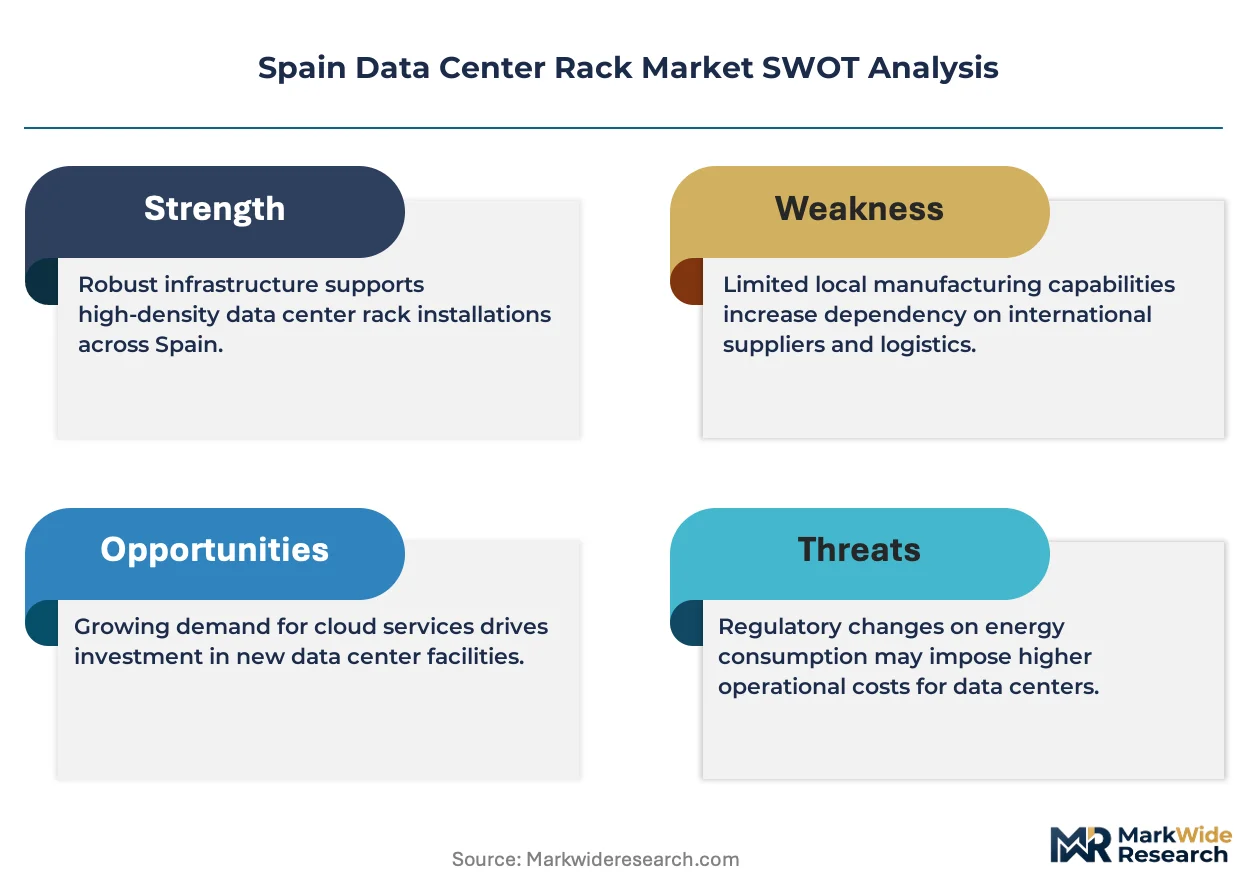
Data center technician and thermal engineering talent is rotating toward Madrid and Barcelona as hyperscale construction accelerates, tightening labor availability for rack integration and commissioning. Schneider Electric leverages its Barcelona service hub to anchor aftermarket support across Iberian facilities. Rittal sustains manufacturing proximity through its Spanish assembly operations, reducing lead times for enclosed rack configurations. Esnova Racks competes on custom fabrication capacity, occupying a niche in non-standard dimensions for legacy data center retrofits.
A data center rack is a standardized metal framework that houses servers, networking equipment, and power distribution units, typically constructed from cold-rolled steel with static load ratings between 1,000 and 3,000 pounds and compliant with EIA-310-D mounting standards. Its primary purpose is to organize hardware vertically, optimize airflow management, and enable scalable infrastructure expansion in controlled environments. Enclosed rack configurations dominate margin pools due to integrated cable management and security features demanded by financial services and government end users. Open frame designs lead volume in colocation settings where cost-per-unit and rapid deployment override physical security requirements. Wall-mounted racks represent a mature segment with limited growth, primarily serving edge computing and telecommunications closets where floor space constraints dictate form factor.
Spain's Ministry for the Digital Transformation and of the Civil Service enforces data center energy reporting thresholds that shape rack-level power monitoring requirements, while CE marking under the EU Low Voltage Directive governs electrical safety compliance for all rack-integrated power distribution. BIS-equivalent Spanish electrical certification bodies validate grounding and insulation standards, creating a compliance gateway for imported rack assemblies. Stakeholders must monitor how Madrid's forthcoming municipal heat reuse mandates could retrofit rack cooling architectures and redirect procurement specifications toward liquid-ready frame designs.
Market Dynamics
Spain's national digital infrastructure plan is compressing hyperscale construction timelines across Madrid and Barcelona, forcing rack procurement cycles to synchronize with accelerated facility commissioning schedules and tightening thermal specification windows.
Growth Catalysts
- EU Energy Efficiency Directives:Tightening rack thermal and power specifications is pulling demand toward liquid-ready frame designs that optimize PUE metrics in hyperscale deployments.
- Cloud provider expansion:Hyperscale facilities in Madrid's Alcobendas corridor are concentrating procurement volumes, creating economies of scale for enclosed rack configurations with integrated cable management.
- Edge computing proliferation:Telecommunications closets and distributed infrastructure nodes are sustaining wall-mounted rack demand where floor space constraints dictate form factor selection.
Market Restraints
- Cold-rolled steel input volatility:Fluctuating steel prices compress margin pools for rack manufacturers serving price-sensitive colocation operators.
- Electrical certification concentration:BIS-equivalent Spanish electrical certification bodies control validation gateways for imported rack assemblies, creating single-point compliance friction.
- Open frame substitution:Cost-per-unit pressures in colocation settings favor open frame designs over enclosed configurations, limiting premium product penetration.
Strategic Opportunities
- Municipal heat reuse mandates:Madrid's forthcoming thermal recovery regulations will retrofit rack cooling architectures and redirect specifications toward liquid-ready frame designs.
- Financial services security requirements:Integrated physical security features in enclosed racks address unmet demand from banking and government end users.
- Barcelona service hub concentration:Proximity to aftermarket support infrastructure creates channel innovation potential for managed rack lifecycle contracts.
Industry Challenges
- Thermal engineering talent scarcity:Data center technician rotation toward hyperscale construction sites in Madrid and Barcelona is tightening labor availability for rack integration and commissioning.
- CE marking compliance timelines:EU Low Voltage Directive electrical safety validation creates extended certification cycles for imported power distribution components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Data Center Rack Market |
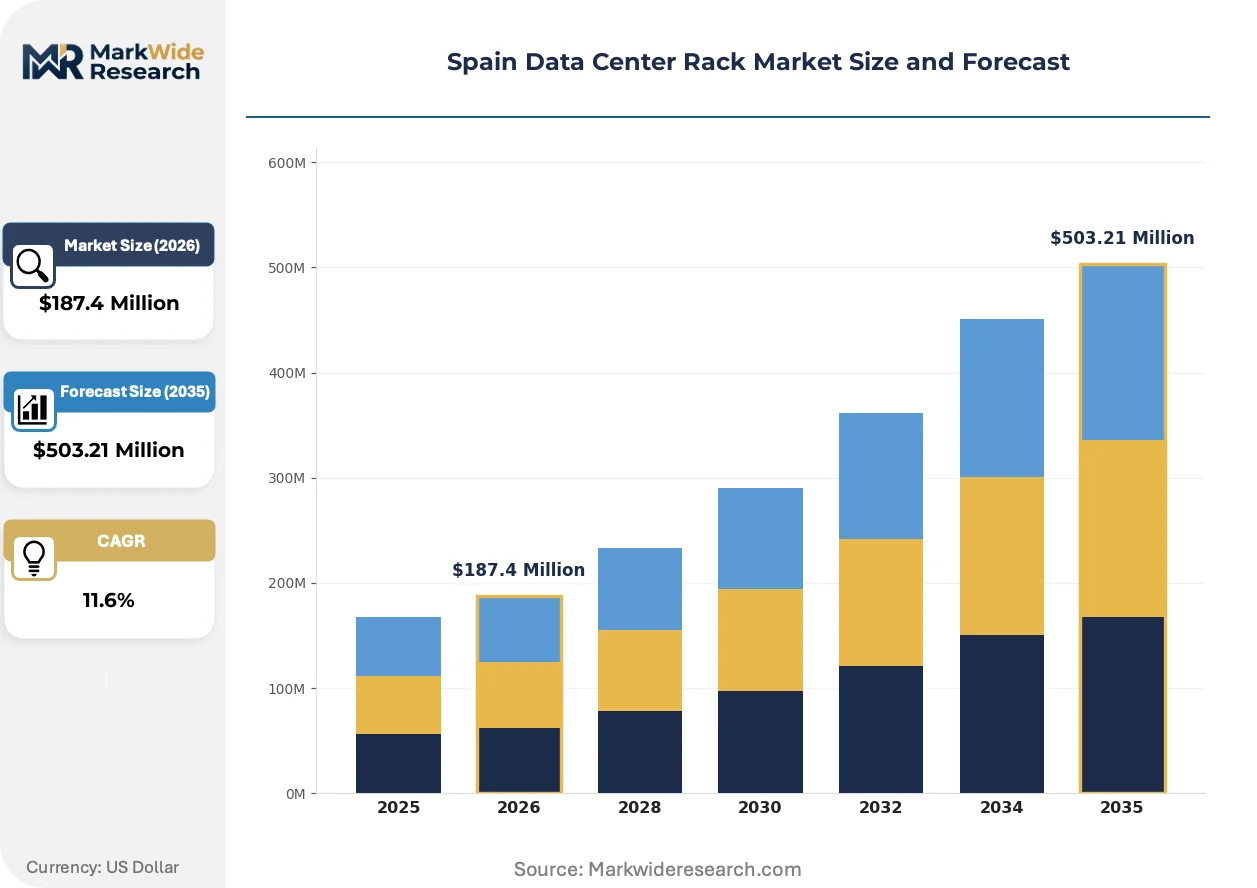
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Data Center Pod Installation Type: Modular, Fixed, Mobile, Custom End User: Telecommunications, Cloud Providers, Enterprises, Colocation Capacity: 1U, 2U, 4U, 8U |
| Companies Covered | Schneider Electric, Vertiv Group Corp, Rittal, Eaton Corporation, nVent Electric, Dell Technologies, Esnova Racks, Espaciorack, STULZ, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Data Center Rack Market Trends and Innovations
Liquid cooling integration is fundamentally altering rack frame architecture as thermal density thresholds exceed air-cooled limits. This shift is compressing traditional design cycles and forcing specification convergence between mechanical infrastructure and IT hardware procurement.
Direct-to-chip liquid cooling manifolds are supplanting conventional perimeter cooling arrangements in high-density deployments. Hyperscale operators in Madrid's Alcobendas corridor are specifying liquid-ready frames for new builds, compressing the market window for air-cooled legacy designs and enabling rack-level thermal autonomy.
Spain's Ministry for the Digital Transformation and of the Civil Service enforces data center energy reporting thresholds that mandate rack-level power monitoring integration. This regulatory pressure is forcing PDU specification changes across all facility tiers, with hyperscale operators retrofitting existing footprints to maintain compliance eligibility for public contracts.
Specification authority is migrating from general contractors to hyperscale engineering teams who now dictate rack thermal and power configurations directly. Traditional distribution channels serving smaller colocation operators are losing influence as procurement concentrates through direct manufacturer relationships with facility engineering departments, particularly visible in Barcelona's Sant Cugat cluster developments.
Spain Data Center Rack Market Segmentation
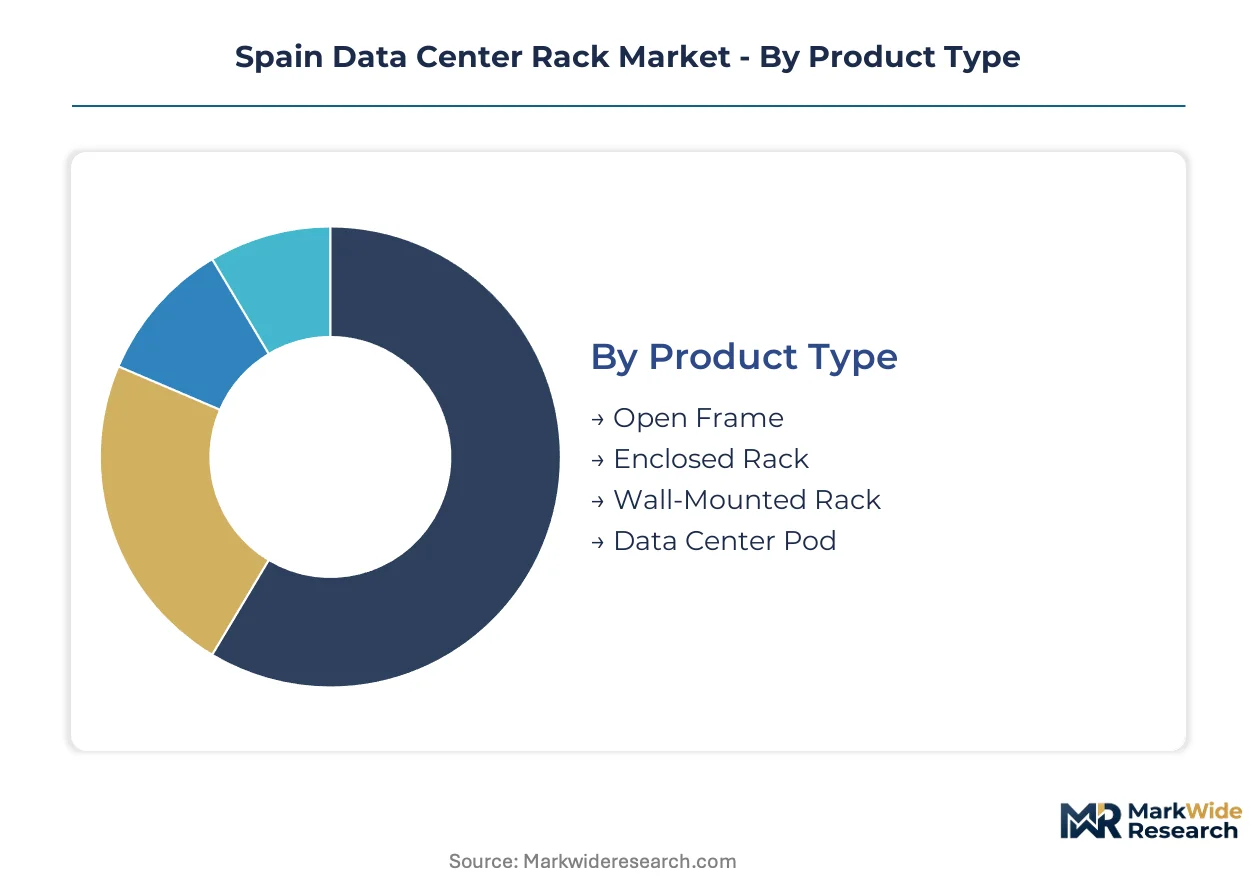
Segmentation in Spain's data center rack market reflects divergent compliance burdens and thermal engineering requirements across facility tiers. Procurement patterns in Madrid's Alcobendas corridor and Barcelona's Sant Cugat cluster concentrate volume in configurations that satisfy EU energy efficiency directives and BIS-equivalent electrical certifications.
Product Type:
CE marking under the EU Low Voltage Directive creates divergent compliance pathways for rack architectures, with enclosed configurations facing extended grounding and insulation validation cycles compared to open frame alternatives.
- Enclosed Rack:Steel-framed cabinets with integrated side panels, front/rear doors, and cable management systems. Demand concentrates in Madrid's financial services sector where physical security mandates and thermal containment specifications override cost-per-unit considerations. Alcobendas hyperscale facilities specify these for compliance with Spain's Ministry for the Digital Transformation energy reporting thresholds.
- Open Frame:Four-post or two-post skeletal structures without enclosing panels, optimizing airflow and accessibility. Barcelona's colocation operators favor these for rapid deployment timelines and reduced material costs, though CE marking compliance for integrated PDUs still creates certification friction.
- Wall-Mounted Rack:Compact hinged or fixed enclosures for telecommunications closets and edge nodes. Sant Cugat distributed infrastructure deployments sustain demand where floor space constraints dictate vertical mounting.
- Data Center Pod:Self-contained modular enclosures integrating rack rows with aisle containment and power distribution. Emerging adoption clusters around liquid-ready thermal specifications ahead of Madrid's forthcoming municipal heat reuse mandates.
Established volume favors Open Frame; emerging adoption favors Data Center Pod.
Installation Type:
Cost tier differentiation separates standardized deployments from custom-engineered solutions, with hyperscale procurement concentrating in modular configurations that compress commissioning timelines.
- Modular:Prefabricated rack assemblies with standardized connection interfaces enabling rapid field assembly. Alcobendas corridor hyperscale facilities specify these to synchronize rack deployment with accelerated facility construction schedules under Spain's national digital infrastructure plan.
- Custom:Dimensionally or thermally modified frames engineered for non-standard facility constraints. Esnova Racks and specialized fabricators serve Barcelona legacy retrofit demand where existing floor loading or aisle dimensions preclude standard catalog offerings.
- Fixed:Permanently anchored rack structures for stable, long-term deployments. Enterprises in Madrid's established data center zones favor these for predictable lifecycle costing.
- Mobile:Castor-mounted or rail-guided rack systems for flexible reconfiguration. Limited adoption concentrates in temporary edge deployments and disaster recovery staging environments.
Procurement volume concentrates in Modular; specification complexity drives Custom margins.
End User:
Customer type determines thermal density requirements and security tiering, with cloud providers dictating rack-level power configurations that cascade through supplier engineering relationships.
- Cloud Providers:Hyperscale operators specifying liquid-ready frames and integrated PDU monitoring for PUE optimization. Madrid and Barcelona construction pipelines concentrate procurement authority with engineering teams rather than traditional distribution channels.
- Colocation:Multi-tenant facility operators balancing cost-per-unit pressures against tenant security requirements. Open frame designs dominate volume, though financial services tenants in Barcelona's Sant Cugat cluster drive enclosed rack premiums.
- Telecommunications:Carrier and ISP infrastructure deployments spanning core facilities and distributed access nodes. Wall-mounted and compact enclosed configurations serve edge proliferation outside Madrid and Barcelona metro zones.
- Enterprises:Corporate captive data centers with heterogeneous legacy infrastructure. Retrofit demand favors custom fabrication for non-standard dimensions and phased thermal upgrades.
Specification authority concentrates with Cloud Providers; margin diversification favors Colocation tenant mix.
Capacity:
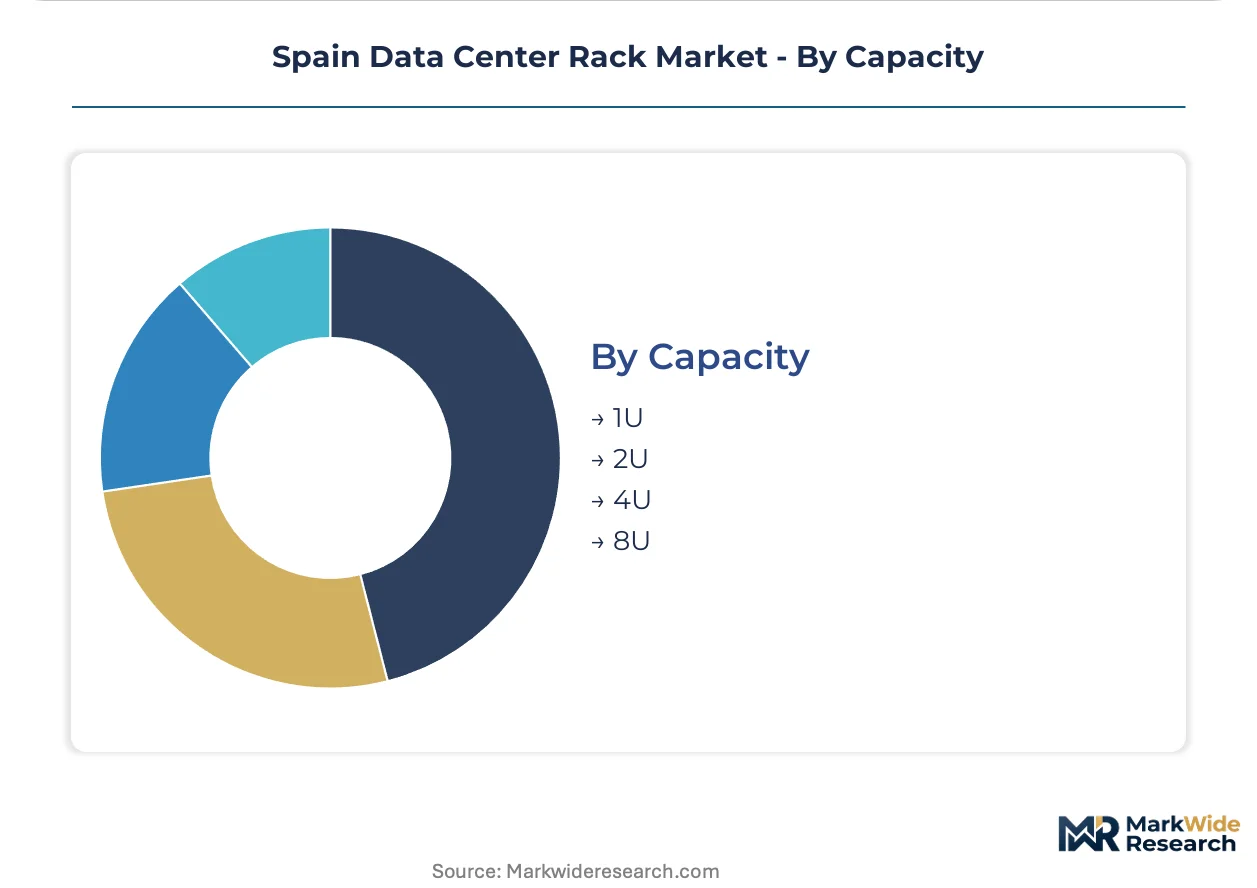
Application-driven form factor selection maps server density to rack unit allocation, with hyperscale deployments compressing legacy 1U-2U server architectures toward higher-density alternatives.
- 4U:Mid-density enclosures accommodating blade servers, storage arrays, and GPU accelerators. Alcobendas AI training clusters specify these for thermal density exceeding air-cooled 1U-2U limits.
- 8U:High-capacity frames for specialized hardware including liquid-cooled manifolds and high-capacity storage. Emerging specification in Barcelona liquid-cooling pilots ahead of regulatory thermal recovery mandates.
- 1U:Single-unit enclosures for minimal footprint network appliances and edge compute nodes. Telecommunications closets sustain residual demand.
- 2U:Standard server enclosures for mainstream compute workloads. Volume erosion accelerates as hyperscale operators consolidate toward 4U+ density configurations.
Legacy infrastructure anchors 2U volume; thermal density trajectories favor 4U and 8U expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's Ministry for the Digital Transformation and of the Civil Service anchors regulatory oversight for data center energy efficiency, with national infrastructure investment compressing construction timelines across the Iberian Peninsula.
Madrid
Hyperscale cloud providers are expanding server deployments in the Alcobendas corridor, driven by Spain's national digital infrastructure plan acceleration. Municipal heat reuse mandates from Madrid's city government will retrofit cooling architectures and redirect procurement toward liquid-ready frame designs. The Alcobendas cluster concentrates procurement volumes for enclosed rack configurations with integrated cable management.
Catalonia
Barcelona's Sant Cugat cluster hosts concentrated hyperscale facility development, tightening labor availability for rack integration and commissioning. CE marking under the EU Low Voltage Directive governs electrical safety compliance for rack-integrated power distribution across the region. Schneider Electric leverages its Barcelona service hub to anchor aftermarket support across Iberian facilities.
Basque Country
Industrial automation and advanced manufacturing demand sustains custom fabrication capacity for non-standard rack dimensions. Spain's BIS-equivalent electrical certification bodies validate grounding and insulation standards for imported assemblies entering through northern ports. Bilbao's logistics infrastructure supports distribution to legacy data center retrofit projects across the region.
Andalusia
Telecommunications infrastructure and edge computing nodes drive wall-mounted rack demand where floor space constraints dictate form factor selection. EU energy efficiency directives shape thermal and power specifications for distributed deployments outside major metro zones. Málaga's emerging tech corridor attracts smaller colocation operators favoring open frame designs for cost-per-unit optimization.
Spain Data Center Rack Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Spain data center rack market. The vendor base concentrates around multinational industrial conglomerates with integrated electrical infrastructure portfolios alongside specialized regional fabricators serving custom retrofit demand. Three strategic archetypes dominate: global diversified industrials with service network scale, European manufacturing specialists with proximity advantages, and domestic custom fabricators occupying non-standard dimension niches. Competitive dynamics center on direct manufacturer relationships with hyperscale engineering teams and aftermarket service contract innovation.
Among global diversified industrials, Schneider Electric and Vertiv Group Corp exemplify the technology leadership archetype through integrated power and thermal infrastructure portfolios. Rittal represents the European manufacturing specialist positioned for lead time advantages in enclosed rack configurations. Domestic fabricator Esnova Racks occupies the custom specialization tier, serving legacy retrofit demand where standard catalog offerings fail. These three anchors illustrate how procurement concentration through hyperscale direct relationships is compressing traditional distribution channel influence.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group Corp |
| Rittal |
| Eaton Corporation |
| nVent Electric |
| Dell Technologies |
| Esnova Racks |
| Espaciorack |
| STULZ |
| Others |
Pricing and Supply Chain Analysis
Hyperscale procurement concentration in Madrid's Alcobendas corridor compresses unit economics for rack manufacturers while elevating price floors for liquid-ready frame configurations. This scale dynamic concentrates supply-side power with integrated electrical infrastructure providers who bundle thermal and power specifications, forcing smaller fabricators toward custom retrofit niches where volume discounts cannot penetrate.
Pricing Analysis
Price spreads between Barcelona and Madrid reflect differential logistics costs and municipal compliance burdens rather than manufacturing origin. Three-tier pricing structure across premium enclosed, standard modular, and economy open-frame levels dominates, with CE certification tier and integrated PDU monitoring as primary differentiation drivers. Cost compression in economy open-frame tiers intensifies because cold-rolled steel input volatility squeezes margin pools for price-sensitive colocation operators. Cloud providers exhibit least price sensitivity due to lifecycle total-cost-of-ownership framing, while telecommunications edge operators anchor the most price-sensitive segment.
Supply Chain Analysis
Bilbao port clearance capacity underwrites supply velocity for rack assemblies entering northern Spain from German and Czech manufacturing hubs. Geographic supply concentration centers on Germany, Czech Republic, and domestic Spanish assembly operations for enclosed configurations, while open-frame skeletal structures draw from Chinese and Turkish steel fabrication. Cold-rolled steel coil, aluminum extrusion, and integrated PDU components constitute critical input dependencies. Single-source vulnerability concentrates in BIS-equivalent Spanish electrical certification validation for imported power distribution units. Distribution runs through direct manufacturer relationships with hyperscale engineering teams, bypassing traditional channel intermediaries in Madrid and Barcelona clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's data center rack market functions as a regulatory-moat arena where CE marking validation and municipal thermal mandates create entrenched switching costs for facility operators. This structural entrenchment favors incumbents with pre-certified product portfolios and established relationships with Spain's Ministry for the Digital Transformation.
For Market Incumbents: Shield market position by deepening backward integration into liquid-cooling manifold production, capturing margin pools that would otherwise leak to specialized thermal component suppliers. Accelerate certification investment for Madrid's forthcoming heat reuse mandates before compliance windows compress. Vertical control over PDU manufacturing insulates against BIS-equivalent validation bottlenecks that currently throttle imported assembly timelines. For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission offers the most viable entry vector for non-EU fabricators seeking Madrid hyperscale procurement access. Target Barcelona's Sant Cugat colocation tenant mix where financial services security requirements sustain enclosed rack premiums unavailable in commodity open-frame competition. Go-to-market positioning should emphasize managed lifecycle contracts leveraging proximity to Schneider Electric's established service hub infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among domestic custom fabricators serving legacy enterprise retrofit demand, where non-standard dimension contracts generate multi-year replacement cycles with limited competitive replication. Long-term viability over the next decade hinges on thermal engineering talent retention and liquid-ready frame design ownership. Acquisition target archetype: mid-scale Spanish fabricators with established Esnova-equivalent custom capacity and municipal permitting relationships. Signal to watch: Madrid city council publication of draft heat reuse technical specifications, which would trigger preemptive procurement acceleration ahead of compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Ready Frame Certification | CE marking for liquid-cooling manifolds secures Madrid hyperscale procurement eligibility ahead of thermal mandate enforcement. |
| Backward Integration into PDU Manufacturing | In-house power distribution production eliminates BIS-equivalent validation friction for imported electrical components. |
| Managed Lifecycle Service Contracts | Aftermarket support bundling leverages Barcelona service hub proximity to capture recurring revenue from Iberian facility operators. |
| Custom Fabrication Capacity Expansion | Non-standard dimension capability addresses Barcelona legacy retrofit demand where standard catalog offerings fail. |
| Thermal Engineering Talent Acquisition | Rack integration and commissioning expertise scarcity tightens as hyperscale construction accelerates in Madrid and Barcelona corridors. |
Research Methodology
The analysis maps enclosed rack, open frame, wall-mounted, and data center pod configurations, each validated through data center engineering directors, facility procurement managers, thermal infrastructure specialists, and electrical certification consultants. Primary interviews with hyperscale operators in Madrid's Alcobendas corridor and Barcelona's Sant Cugat cluster combined with secondary validation against Spain's Ministry for the Digital Transformation energy reporting disclosures, EU Low Voltage Directive technical documentation, and customs import records for cold-rolled steel and aluminum extrusion. Bottom-up unit economics triangulated against top-down facility construction pipeline estimates.
Consistency checks validated volume and value outputs against hyperscaler capex disclosures, EPC contractor procurement timelines, and regional electrical certification body throughput data. Segmentation dimensions modeled span product architecture, installation type, end-user category, and rack unit capacity tier across the projection horizon. CAGRs derived from facility commissioning schedules, thermal density trajectories, and regulatory compliance phase-in assumptions. Forecast inputs incorporated steel price volatility indices and municipal heat reuse mandate probability weightings.
Decision-makers should treat outputs as directional under stable EU energy efficiency directive enforcement and uninterrupted hyperscale construction financing; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Madrid municipal thermal recovery regulations and BIS-equivalent certification body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Data Center Transformation Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
United States Data Center Server Market