
 Stockholm Data Center Market | 2026-2036
Stockholm Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Stockholm Data Center Market Insights
Market Context
Immersion cooling and direct liquid cooling is rewriting thermal management architectures for high-density AI training clusters in the Stockholm region. Equinix leverages its interconnection platform to anchor financial services and cloud exchange traffic across the Nordics. atNorth sustains competitive positioning through its Icelandic and Swedish hydroelectric-powered facilities optimized for HPC workloads. Digital Realty extends its European hyperscale footprint with energy-efficient designs targeting Stockholm's renewable grid.
Technical Definition and Segment Structure
A data center constitutes a dedicated facility housing compute, storage, and network infrastructure with specified power densities exceeding 15 kW per rack and redundant cooling systems maintaining temperatures between 18°C and 27°C, serving enterprise IT outsourcing, cloud service delivery, and digital content distribution. Colocation and cloud services command the dominant revenue share as enterprises migrate from capital-intensive on-premise ownership to operational expenditure models. Edge computing within the technology segment represents the fastest structural expansion, driven by latency-sensitive applications in autonomous systems and real-time analytics requiring distributed Stockholm metro nodes rather than centralized hyperscale campuses.
Regulatory Environment
The Swedish Energy Agency and Boverket enforce stringent PUE reporting and building energy codes that shape facility design standards and operational compliance costs for Stockholm operators. The EU CSRD and national climate reporting obligations mandate granular sustainability disclosures that redirect investment toward carbon-neutral power sourcing and waste heat recovery systems. Stakeholders must monitor forthcoming EU grid interconnection rules and local municipal heat reuse mandates that will determine site selection economics and long-term facility valuations.
Market Dynamics
Direct liquid cooling is compressing thermal design margins for AI training clusters across Stockholm's Kista and Hammarby districts, forcing operators to reconfigure power distribution and rack architectures ahead of density thresholds that legacy air systems cannot sustain.
Growth Catalysts
- EU AI Act compliance deadlines:Swedish hyperscale operators are accelerating facility certifications to meet algorithmic transparency and risk classification requirements for training infrastructure.
- Fintech workload migration:Stockholm's banking and payments sector is consolidating dispersed server estates into carrier-neutral colocation to reduce latency to European clearing systems.
- Immersion cooling adoption:Single-phase dielectric fluid systems are penetrating HPC deployments where rack densities exceed 50 kW, enabling heat capture for municipal district heating networks.
Market Restraints
- Grid interconnection queues:Svenska Kraftnät approval timelines for substation upgrades now extend 24-36 months in Stockholm County, throttling campus expansion velocity.
- Copper and electrical steel volatility:Transformer and busway procurement costs fluctuate with commodity indexes, compressing EPC contractor margins on fixed-price builds.
- Skilled technician scarcity:Certification programs for refrigerant handling and high-voltage switching cannot match facility commissioning schedules across the Mälardalen region.
Strategic Opportunities
- Waste heat recovery mandates:Boverket's forthcoming building code revisions will require thermal export agreements for facilities above 10 MW capacity, creating revenue streams from district heating contracts.
- Edge node distribution:Latency-sensitive gaming and autonomous vehicle telemetry is driving micro-data center deployment in Södertälje and Uppsala logistics corridors.
- Carbon-free power contracting:Long-term power purchase agreements with Vattenfall and Fortum for 24/7 renewable matching are differentiating operator sustainability credentials.
Industry Challenges
- Legacy cooling retrofit complexity:Raised-floor facilities built for 8-12 kW racks require structural reinforcement and containment reconfiguration to support liquid-cooled AI infrastructure.
- CSRD disclosure granularity:Scope 3 emissions tracking across construction materials and decommissioned equipment demands supply chain data systems most operators have not deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stockholm Data Center Market |
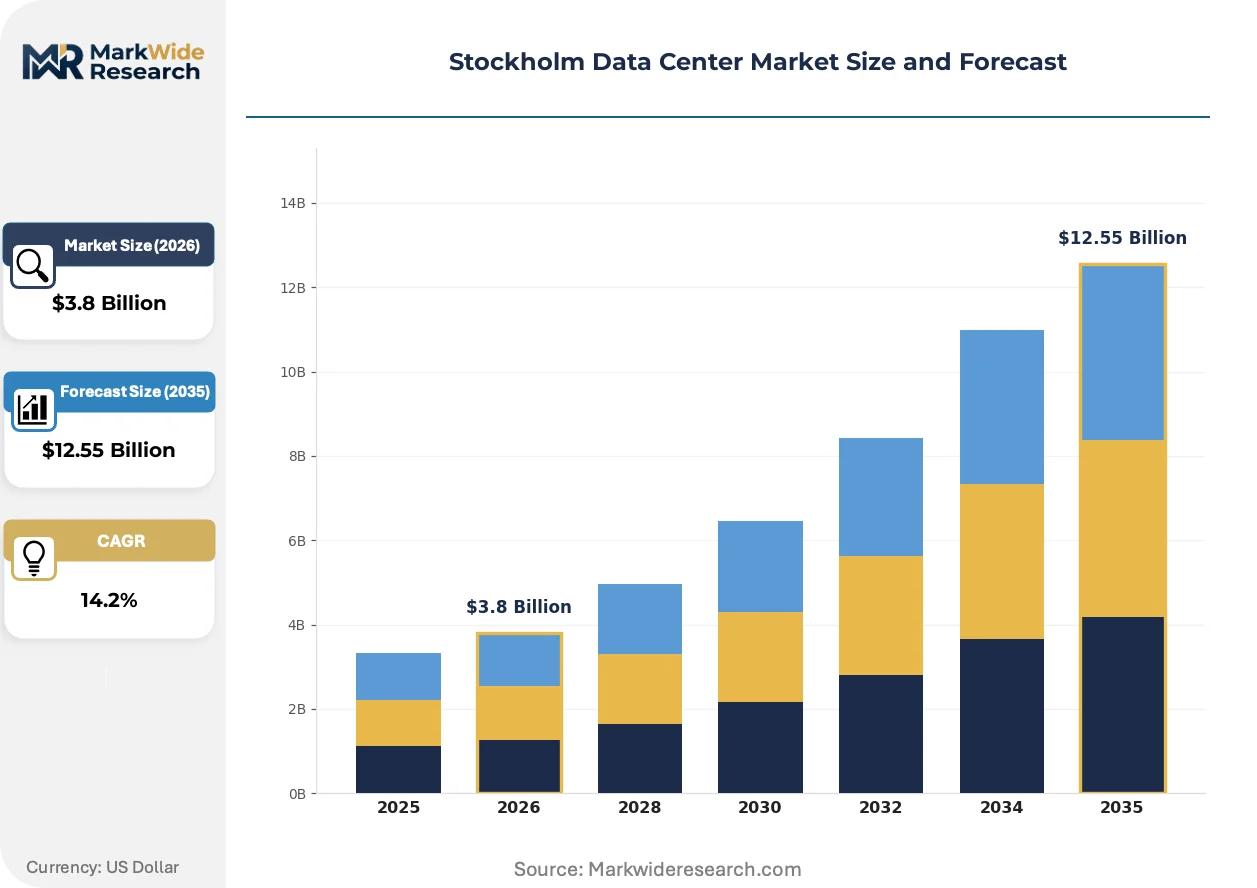
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Dedicated Servers End User: IT Enterprises, E-commerce, Telecommunications, Healthcare Providers Deployment: On-Premise, Off-Premise, Hybrid Cloud, Multi-Cloud Technology: Edge Computing, Virtualization, Network Infrastructure, Power Management |
| Companies Covered | Digital Realty, Equinix, atNorth, GleSYS AB, Multigrid Data Center AB, Bahnhof AB, EcoDataCenter, Interxion, Conapto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stockholm Data Center Market Trends and Innovations
Facility architecture is bifurcating between AI-optimized liquid-cooled campuses and legacy air-cooled estates facing functional obsolescence, with operator investment decisions increasingly governed by heat reuse economics and grid interconnection timelines rather than land availability alone.
Single-phase immersion cooling using synthetic dielectric fluids is rendering obsolete conventional chilled-water CRAH architectures for training clusters exceeding 40 kW per rack. Swedish HPC operators including academic consortia and automotive simulation labs are deploying tank-based systems at commercial scale. The structural consequence is collapsing mechanical infrastructure ratios from 40% of facility cost toward 25%, redirecting capital toward power distribution and fiber densification.
Sweden's national data center tax incentive framework is compressing effective electricity costs for certified facilities, altering locational economics within the Nordic region. Operators achieving PUE thresholds below 1.3 and documented renewable sourcing qualify for reduced energy taxation. The incentive is concentrating new investment in Stockholm's municipal heat network zones where thermal export contracts satisfy dual sustainability and fiscal optimization objectives.
Enterprise procurement of capacity is fragmenting across multi-cloud brokerage platforms rather than direct colocation contracting. Financial services and SaaS developers in Stockholm are aggregating demand through interconnection exchanges, treating physical infrastructure as substitutable commodities ranked by latency and sustainability metrics. This pattern is most pronounced among Series C-stage software ventures optimizing burn rates through short-term flexible commitments rather than 5-10 year lease structures.
Stockholm Data Center Market Segmentation
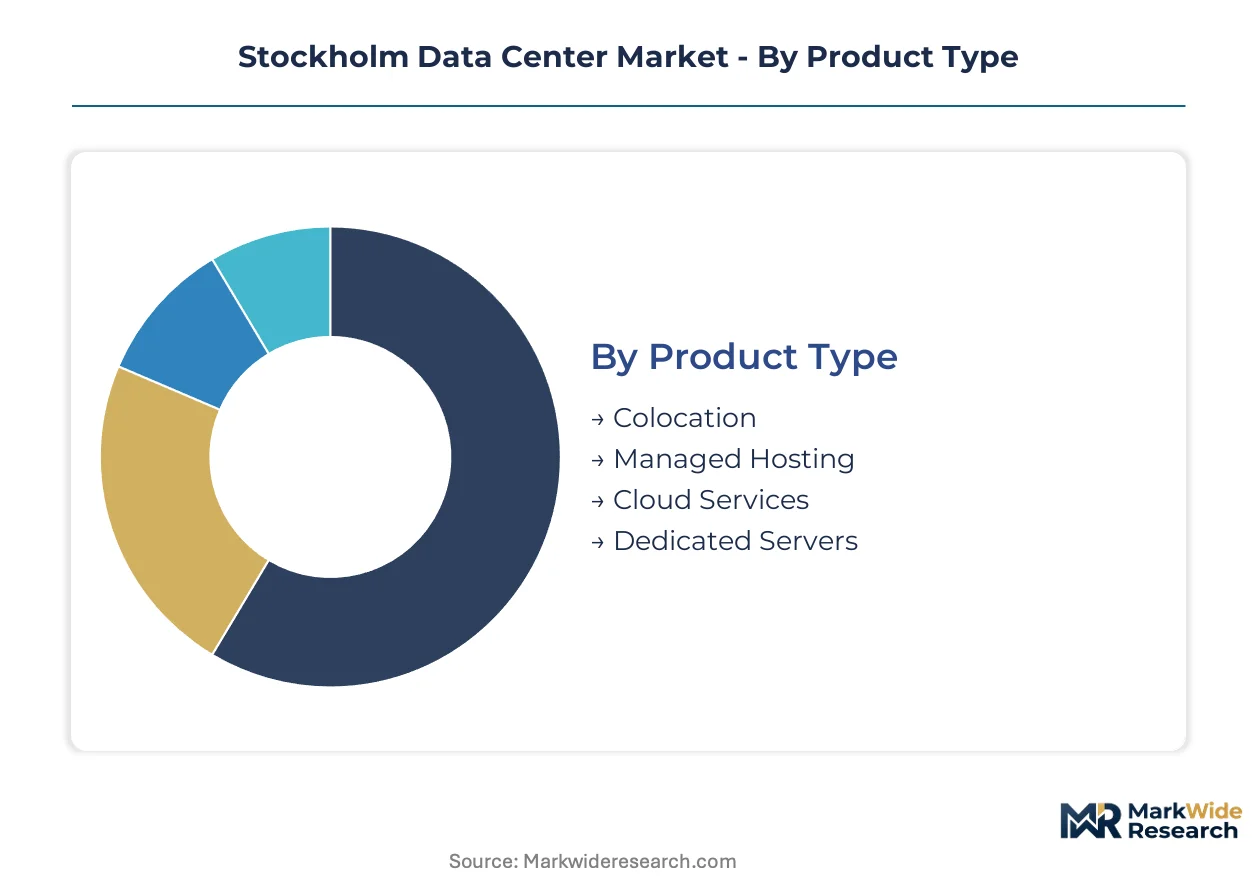
Segmentation in Stockholm's data center market reveals how workload characteristics, compliance requirements, and thermal density demands fragment procurement patterns across Swedish enterprises. Understanding these divisions exposes where facility operators must architect differentiated service tiers and where standardization suffices.
Product Type:
Contract renewal cycles vary dramatically across product categories, with cloud services refreshing monthly while dedicated servers lock capital for 36-60 month terms.
- Colocation:Physical space leasing with power, cooling, and physical security provided by the operator, while tenants supply and manage their own server hardware. Swedish fintech clusters in Kista Science City concentrate demand here, driven by EU AI Act requirements for algorithmic audit trails that favor carrier-neutral interconnection over single-tenant facilities.
- Cloud Services:On-demand compute and storage resources delivered through virtualized platforms with API-driven provisioning. Stockholm's gaming studios and SaaS developers are expanding consumption fastest, optimizing burn rates through operational expenditure models that bypass capital-intensive server ownership.
- Managed Hosting:Operator-owned infrastructure with tenant administrative access, combining hardware control with outsourced maintenance. Healthcare providers and legacy enterprises favor this model where internal IT capacity constraints meet strict data residency requirements under Swedish patient data laws.
- Dedicated Servers:Single-tenant physical machines with guaranteed resource allocation and no virtualization overhead. E-commerce platforms handling seasonal transaction spikes deploy here, matching fixed infrastructure costs to predictable baseline workloads.
Colocation dominates installed base across Stockholm's established facilities. Cloud services represent where expansion concentrates most steeply.
End User:
Procurement sophistication diverges sharply across verticals, with telecommunications carriers negotiating wholesale power rates while healthcare providers prioritize compliance certification over unit economics.
- IT Enterprises:Technology companies consuming infrastructure for software development, testing environments, and customer-facing platform delivery. Stockholm's fintech unicorns and enterprise SaaS vendors drive premium colocation demand in Hammarby Sjöstad's sustainable cluster, where PUE thresholds below 1.3 unlock national tax incentives.
- E-commerce:Online retailers requiring elastic capacity for transaction processing, inventory management, and customer analytics. Peak-load sensitivity during Nordic shopping seasons pushes these users toward hybrid deployments blending cloud burst capacity with dedicated baseline infrastructure.
- Telecommunications:Mobile and fixed-line operators hosting network functions, subscriber databases, and edge caching nodes. 5G core network distribution demands are concentrating investment in micro-data center nodes across Södertälje and Uppsala logistics corridors.
- Healthcare Providers:Hospitals, clinics, and digital health platforms managing electronic patient records and diagnostic imaging archives. Swedish patient data residency regulations and CSRD sustainability disclosure mandates shape vendor selection toward operators with documented renewable sourcing and waste heat recovery systems.
IT enterprises anchor current capacity absorption. Healthcare providers are gaining share fastest as digital health infrastructure accelerates.
Deployment:
Migration velocity separates deployment modes, with multi-cloud strategies pivoting quarterly while on-premise footprints depreciate over decade-long cycles.
- On-Premise:Enterprise-owned facilities with captive power, cooling, and security infrastructure. Legacy Swedish manufacturing and banking groups maintain these estates for core transaction systems, though AI training workloads are forcing consolidation into off-premise liquid-cooled campuses.
- Off-Premise:Third-party facility utilization with no retained enterprise infrastructure. Growth-stage software ventures and foreign market entrants favor this model for immediate Stockholm metro presence without capital deployment.
- Hybrid Cloud:Integrated environments spanning private colocation and public cloud resources with unified orchestration. Financial services firms deploying algorithmic trading platforms require this architecture to satisfy sub-millisecond latency to European clearing systems while retaining sensitive data on Swedish soil.
- Multi-Cloud:Distributed workloads across competing cloud platforms to mitigate vendor lock-in and optimize service-specific pricing. Enterprise procurement through Stockholm interconnection exchanges is fragmenting demand this way, treating physical infrastructure as substitutable commodities ranked by latency and sustainability metrics.
Hybrid cloud holds the largest committed footprint. Multi-cloud configurations are climbing the fastest as brokerage platforms mature.
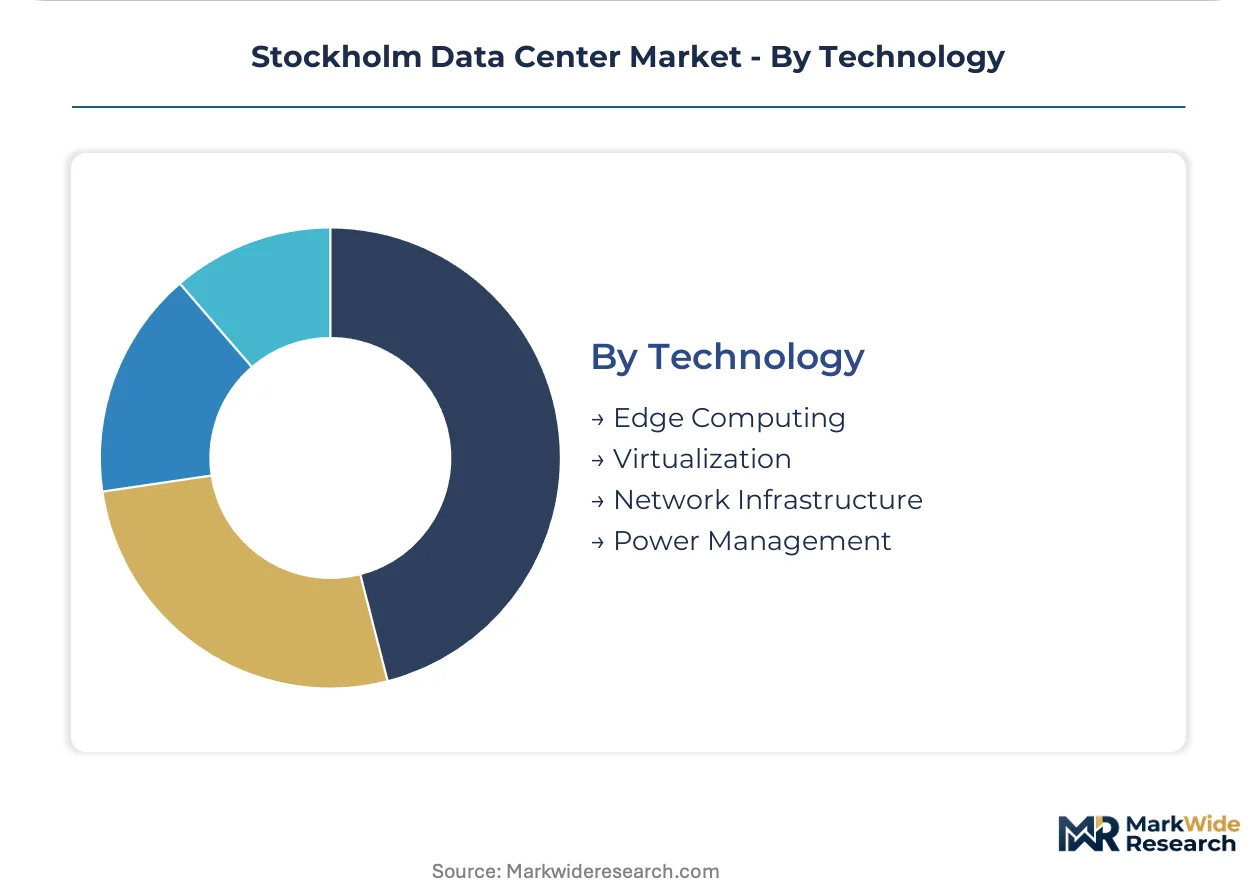
Technology:
Capital intensity and obsolescence risk stratify technology segments, with edge computing hardware refreshing every 24-36 months while power management systems endure 15-year depreciation schedules.
- Edge Computing:Distributed micro-facilities and containerized nodes positioned within 10 milliseconds of end users. Autonomous vehicle telemetry and real-time gaming analytics are concentrating deployment in Stockholm's peripheral logistics corridors rather than centralized hyperscale campuses.
- Virtualization:Software abstraction layers enabling server consolidation and resource pooling across physical hardware. Container orchestration and Kubernetes adoption are displacing legacy hypervisor deployments among cloud-native development teams.
- Network Infrastructure:Fiber densification, switching fabrics, and interconnection platforms enabling traffic exchange. Equinix and atNorth are competing here through Stockholm metro fiber rings connecting Kista Science City to continental European backbones.
- Power Management:Uninterruptible power supplies, switchgear, and intelligent distribution units maintaining 99.999% availability. AI cluster densities exceeding 50 kW per rack are forcing busway and rack PDU reconfigurations that legacy air-cooled facilities cannot accommodate.
Virtualization underpins existing estate operations. Edge computing represents the steepest expansion trajectory as latency requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's data center sector operates as a net capacity exporter, with Stockholm-based facilities serving Nordic, Baltic, and continental European demand while importing specialized cooling equipment and high-voltage electrical components from Germany and the Netherlands.
Kista Science City
Fintech algorithmic trading and AI training clusters drive capacity absorption in this northern Stockholm district. The Swedish Energy Agency enforces PUE reporting thresholds below 1.3 for tax incentive eligibility. Carrier-neutral interconnection exchanges here process clearing traffic for SEB and Klarna, consolidating previously dispersed banking infrastructure.
Hammarby Sjöstad
Sustainable district heating integration attracts hyperscale operators seeking thermal export revenue streams. Boverket building codes mandate waste heat recovery for facilities exceeding 10 MW capacity. EcoDataCenter and atNorth operate liquid-cooled campuses here, feeding captured heat into municipal networks serving 25,000 residential units.
Södertälje Logistics Corridor
Autonomous vehicle telemetry and gaming edge nodes require sub-10 millisecond latency to Stockholm metro users. The Swedish Transport Administration coordinates 5G infrastructure deployment alongside data center zoning. Micro-facilities here process real-time sensor data for Volvo and Scania autonomous trucking trials.
Uppsala Research Triangle
Academic HPC consortia and pharmaceutical simulation workloads concentrate near Uppsala University and SciLifeLab facilities. Swedish Research Council grants require carbon-neutral power sourcing for supercomputing allocations. Tank-based immersion cooling deployments here support protein folding and genomics research at densities exceeding 50 kW per rack.
Mälardalen Industrial Zone
Manufacturing digital twins and automotive design studios demand dedicated server estates with low-latency connectivity to Eskilstuna and Västerås production lines. Regional development agencies offer land allocation priority for facilities achieving documented renewable 24/7 power matching. Bahnhof AB maintains edge presence here for industrial IoT aggregation.
Stockholm Data Center Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. International hyperscale platforms anchor interconnection density and cloud exchange traffic. Nordic specialists leverage hydroelectric power sourcing and thermal export economics. Regional operators defend positions through municipal relationships and latency-optimized metro distribution. Capacity expansion and sustainability certification represent the dominant competitive moves, with operators racing to secure Svenska Kraftnät grid interconnection approvals and Boverket heat reuse compliance ahead of facility commissioning.
Within the international platform tier, Digital Realty and Equinix exemplify scale-driven positioning through Stockholm metro fiber rings and continental European backbone connectivity. Among Nordic specialists, atNorth occupies a position defined by Icelandic and Swedish hydroelectric-powered facility networks optimized for HPC density. These three entities represent divergent strategic archetypes: interconnection-centric platform expansion, renewable-sourced compute specialization, and hybrid Nordic-Swedish thermal optimization.
| Leading Market Players |
|---|
| Digital Realty |
| Equinix |
| atNorth |
| GleSYS AB |
| Multigrid Data Center AB |
| Bahnhof AB |
| EcoDataCenter |
| Interxion |
| Conapto |
| Others |
Pricing and Supply Chain Analysis
The Södertälje logistics corridor's freight cost dynamics concentrate supply chain leverage among transformer and switchgear manufacturers in Germany and the Netherlands, compressing EPC contractor margins while enabling tiered pricing differentiation between liquid-cooled AI campuses and legacy air-cooled facilities.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Stockholm's data center market, with pricing stratifying across premium liquid-cooled tiers, standard colocation, and economy remote-housing levels. Price differentiation rests on PUE certification thresholds below 1.3 and documented 24/7 renewable power matching. Cost compression in standard air-cooled tiers is intensifying because legacy facilities face functional obsolescence against AI density requirements. Growth-stage SaaS ventures exhibit highest price sensitivity, while fintech algorithmic trading platforms prioritize latency guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between Germany and Sweden dominates supply chain risk planning for electrical steel and copper busway procurement. Manufacturing concentrates in Germany, the Netherlands, and Denmark for critical power distribution components. Raw material dependencies center on electrical-grade copper, transformer-grade steel, and synthetic dielectric fluids for immersion cooling systems. Single-source vulnerability persists for high-voltage switchgear rated above 36 kV. Distribution runs through EPC contractor networks with direct OEM relationships, bypassing traditional distribution channels for speed-to-market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stockholm's data center market sits at a platform-economics inflection where interconnection exchange density and API-driven provisioning are displacing direct colocation contracting as the primary demand aggregation mechanism.
For Market Incumbents: Harden interconnection platform dominance through fiber densification investments linking Kista Science City to continental European backbones, while accelerating Boverket heat reuse compliance certifications ahead of municipal mandate timelines. Liquid-cooled retrofit capabilities represent the critical defensive lever against hyperscale entrants with native AI-optimized architectures. For New Entrants and Emerging Players: Micro-data center nodes in Uppsala logistics corridors and Södertälje autonomous vehicle telemetry zones represent the most penetrable entry points, where sub-10 millisecond latency requirements and 5G infrastructure coordination create whitespace unclaimed by established hyperscale campuses. Municipal heat network integration partnerships offer the strongest go-to-market angle for tax incentive eligibility. For Investors and Strategic Acquirers: Carve-out targets emerge from regional industrial conglomerates with captive data center estates facing stranded asset risk from AI workload migration. Long-term viability across the analysis window hinges on grid interconnection queue positioning and documented renewable sourcing contracts. The signal to watch is Svenska Kraftnät approval timeline compression for substation upgrades above 50 MW capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables heat capture for Hammarby Sjöstad municipal district heating networks serving 25,000 residential units. |
| Grid Interconnection Queue Positioning | Secures Svenska Kraftnät approval timelines ahead of competitor campus expansion velocity. |
| Carbon-Free Power Purchase Agreements | Differentiates operator credentials through Vattenfall and Fortum 24/7 renewable matching contracts. |
| Edge Node Distribution in Logistics Corridors | Captures latency-sensitive gaming and autonomous vehicle telemetry demand outside centralized hyperscale zones. |
| CSRD Compliance Data System Deployment | Addresses Scope 3 emissions tracking requirements across construction materials and decommissioned equipment. |
Research Methodology
The analysis maps liquid-cooled AI campuses, legacy air-cooled colocation, edge micro-facilities, and hybrid cloud deployments, each validated through facility engineering directors, EPC contractor procurement leads, Svenska Kraftnät grid planning officers, and fintech infrastructure executives. Primary interview insights triangulate against secondary sources including Boverket building code filings, Swedish Energy Agency PUE compliance databases, Svenska Kraftnät interconnection queue disclosures, and hyperscaler capital expenditure statements. Bottom-up capacity installation tracking and top-down Nordic demand aggregation are reconciled through iterative validation.
Assumptions held fixed across the modeling period include EU AI Act compliance deadline enforcement, Swedish national data center tax incentive framework continuity, and prevailing grid interconnection approval timelines. Segmentation dimensions modeled encompass product type, end-user vertical, deployment architecture, and technology tier including edge computing density thresholds. CAGRs are derived from facility commissioning schedules, power density evolution curves, and interconnection exchange traffic growth patterns.
Macroeconomic conditions sit as an overlay; deviation in Swedish krona exchange rates, EU carbon border adjustment mechanisms, or copper and electrical steel commodity indexes would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement and infrastructure investment pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
China Data Center Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
China Data Center Server Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Los Angeles Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Italy Data Center Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Philippines Data Center Physical Security Market