
 Germany Data Center Server Market | 2026-2036
Germany Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Server Market Insights
Asset-light leasing and pay-per-use financing is fragmenting competitive dynamics in the Germany data center server landscape. Dell Inc leverages its direct-to-operator sales infrastructure to sustain large enterprise relationships across Bavaria and Baden-Württemberg. Super Micro Computer Inc specializes in high-density liquid-cooled platforms that anchor its position with sustainability-focused colocation operators. Huawei Technologies Co Ltd navigates procurement complexity to compete in select German cloud infrastructure tenders.
Germany data center servers comprise compute, memory, storage, and networking subsystems housed in standardized chassis designed for 19-inch rack mounting, typically operating within 10°C to 35°C ambient thresholds and supporting dual redundant power feeds for continuous uptime. Rack servers dominate procurement volumes among Frankfurt-based financial services operators who prioritize density and serviceability. Blade servers represent the fastest-expanding product type as cloud service providers consolidate compute into chassis-based architectures for virtualization workloads. Tower servers occupy a mature niche among smaller SMB deployments where space constraints remain secondary to capital expenditure control.
The EU Green Deal and Germany's Energy Efficiency Act impose escalating power usage effectiveness thresholds and renewable sourcing mandates that reshape server procurement specifications toward lower thermal design power processors. KBA and federal building codes intersect with BSI IT security standards to govern physical infrastructure placement and data sovereignty compliance across federal and enterprise installations. Stakeholders must monitor how forthcoming EU AI Act infrastructure requirements interact with existing CSRD disclosure obligations when sizing next-generation compute deployments.
Market Dynamics
Liquid-cooled server architectures are displacing traditional air-cooled designs across German hyperscale campuses as the EU Green Deal tightens thermal efficiency mandates and operators face mounting power density constraints.
Growth Catalysts
- EU Green Deal mandates:The Energy Efficiency Act and escalating renewable sourcing requirements force operators toward liquid-cooled platforms and grid-interconnected facilities in North Rhine-Westphalia.
- Hyperscale cloud expansion:Frankfurt and Berlin corridors attract concentrated server procurement from cloud service providers building virtualization-dense campuses near major grid nodes.
- AI workload proliferation:Training and inference clusters drive demand for high-density GPU servers with specialized liquid cooling loops and redundant power architectures.
Market Restraints
- Energy cost volatility:German industrial electricity tariffs fluctuate with natural gas import dependencies, compressing operator margins and delaying server refresh cycles.
- Supply concentration in Asian component foundries:Advanced processor and memory module production clusters in Taiwan and South Korea expose procurement timelines to geopolitical friction.
- BSI IT security certification delays:Federal data sovereignty requirements extend server deployment timelines for sensitive government and defense workloads.
Strategic Opportunities
- Bavaria and Baden-Württemberg enterprise segments:Manufacturing and automotive headquarters in southern Germany underinvest in on-premise server modernization relative to northern financial services density.
- Edge computing for industrial IoT:Smart factory deployments in Saxony and Thuringia create demand for ruggedized, low-latency server nodes outside traditional hyperscale corridors.
- CSRD-aligned sustainability reporting:The Corporate Sustainability Reporting Directive creates procurement preference for servers with embedded lifecycle carbon tracking and circular design certifications.
Industry Challenges
- Liquid cooling technician scarcity:Specialized plumbing, coolant chemistry, and leak-detection expertise remains concentrated among legacy mainframe operators and HVAC contractors.
- Legacy virtualization stack integration:VMware and Hyper-V estates in established Frankfurt financial data centers resist seamless migration to container-native server configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Server Market |
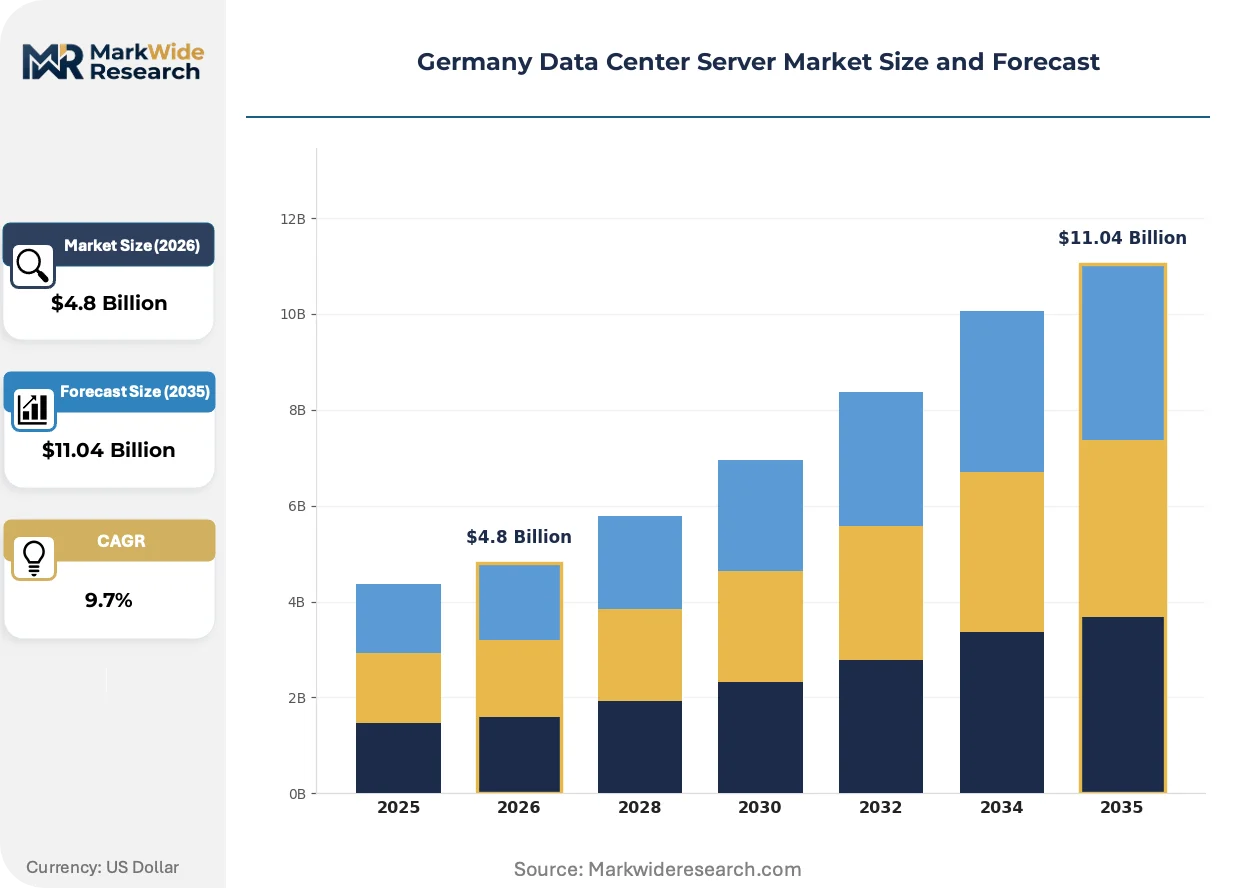
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Micro Servers End User: Enterprises, SMBs, Government, Cloud Service Providers Application: Web Hosting, Data Storage, Cloud Computing, Virtualization Installation Type: On-Premises, Off-Premises, Hybrid, Colocation |
| Companies Covered | Dell Inc, International Business Machines (IBM) Corporation, Lenovo Group Limited, Cisco Systems Inc, Kingston Technology Company Inc, Quanta Computer Inc, Super Micro Computer Inc, Huawei Technologies Co Ltd, Inspur Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Server Market Trends and Innovations
Server infrastructure across Germany is undergoing architectural compression as thermal design power thresholds tighten and procurement specifications embed sustainability metrics directly into vendor selection criteria.
Direct-to-chip liquid cooling is migrating from niche supercomputing installations to standard enterprise procurement specifications. Hyperscale operators in Frankfurt now specify cold-plate or immersion systems for racks exceeding 30 kilowatts. This technology is migrating from custom-engineered solutions toward modular, factory-integrated platforms that reduce deployment complexity and compress commissioning timelines.
The EU AI Act introduces infrastructure transparency requirements that intersect with existing CSRD disclosure obligations. Server deployments supporting high-risk AI systems must document computational resource allocation and energy consumption patterns. German federal agencies and regulated financial institutions face the steepest compliance burden, driving preference for vendors with pre-certified audit trails and embedded telemetry.
Leasing structures now dominate server acquisition patterns among mid-market colocation tenants who previously favored capital purchases. Operating expense treatment and technology refresh flexibility displace depreciation-heavy ownership models. This behavioral shift concentrates most visibly among Munich-based automotive suppliers and Stuttgart manufacturing headquarters managing cyclical capacity demands.
Germany Data Center Server Market Segmentation
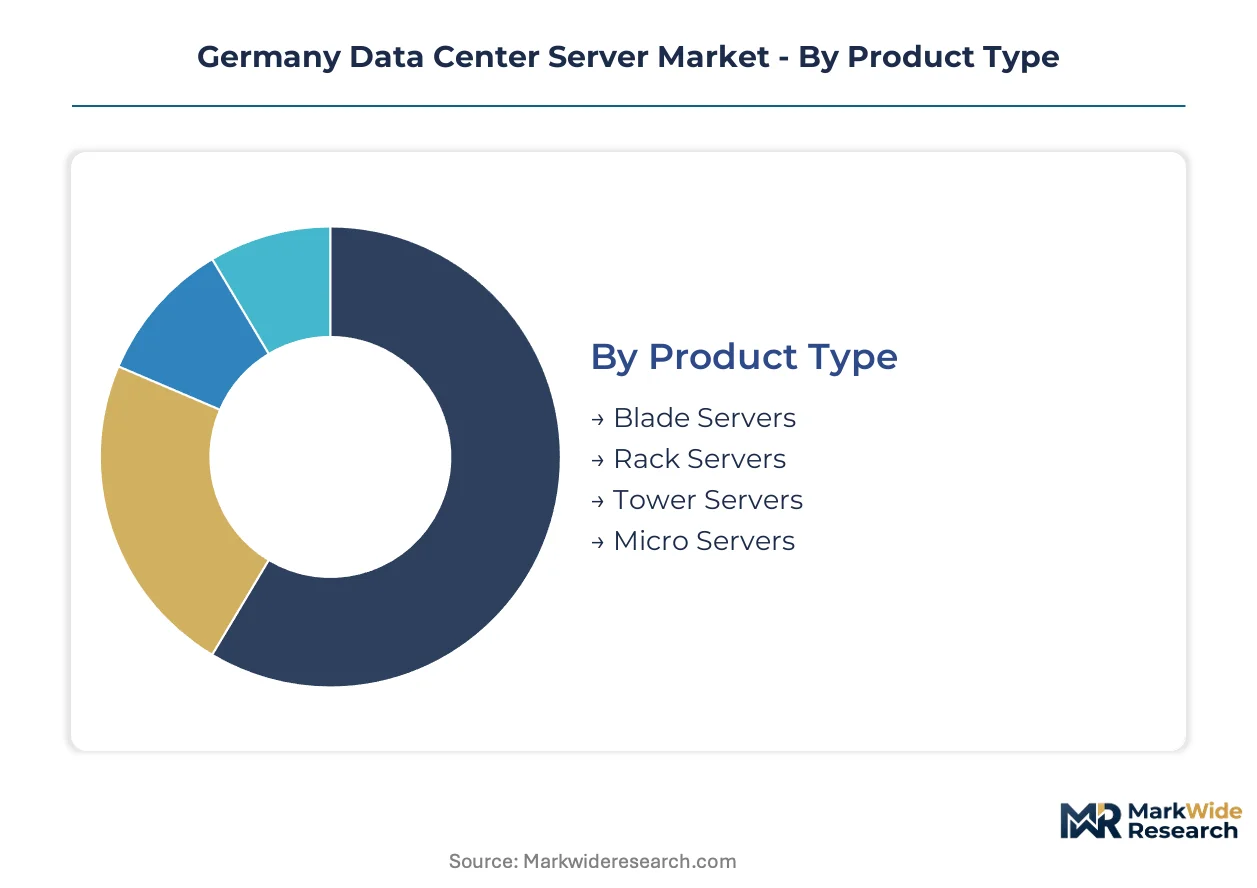
German data center server procurement splits across multiple technical and operational dimensions. Each segmentation axis reveals distinct purchasing behaviors shaped by regulatory pressure, workload density, and facility ownership models.
Product Type:
Server form factor selection tracks directly against thermal density requirements and facility infrastructure maturity across German operator estates.
- Rack Servers:Standardized 19-inch chassis dominate procurement volumes across Frankfurt financial services operators. These units prioritize serviceability and density within raised-floor environments where KBA building codes govern physical infrastructure placement.
- Blade Servers:Chassis-based architectures consolidate compute for virtualization workloads. Cloud service providers in Berlin corridors specify blade systems to maximize rack-level efficiency as EU Green Deal thermal mandates tighten.
- Tower Servers:Standalone vertical enclosures serve smaller SMB deployments where capital expenditure control outweighs space optimization priorities.
- Micro Servers:Compact single-socket nodes address edge computing requirements in Saxony industrial IoT deployments with constrained physical footprints.
The dominant share belongs to Rack Servers, while Blade Servers is closing the gap fastest.
End User:
Procurement authority concentrates differently across organizational scale and regulatory exposure to BSI IT security standards.
- Cloud Service Providers:Hyperscale operators drive volume procurement of liquid-cooled high-density platforms. Frankfurt and Berlin campuses anchor concentrated server deployment near grid interconnections in North Rhine-Westphalia.
- Enterprises:Large manufacturing and automotive headquarters in Bavaria and Baden-Württemberg underinvest in on-premise modernization relative to northern financial services density.
- Government:Federal agencies face extended deployment timelines from BSI IT security certification requirements for sensitive and defense workloads.
- SMBs:Small and medium businesses favor tower configurations and leasing structures to manage cyclical capacity demands without depreciation-heavy ownership.
Cloud Service Providers command the largest procurement volumes, with Enterprises expanding most quickly as CSRD disclosure obligations reshape internal infrastructure strategies.
Application:
Workload type determines server specification priorities across compute, memory, and storage subsystems.
- Cloud Computing:Virtualization-dense deployments require high core-count processors and redundant power architectures. Hyperscale campuses specify these for multi-tenant resource pooling.
- Virtualization:Legacy VMware and Hyper-V estates in established Frankfurt financial data centers resist seamless migration to container-native configurations.
- Data Storage:Capacity-optimized nodes with dense drive bays serve archival and backup workloads across colocation facilities.
- Web Hosting:Standard rack servers with balanced compute-memory ratios address content delivery and application serving requirements.
Cloud Computing absorbs the dominant deployment share, though Virtualization is gaining share fastest as containerization pressures legacy stack refresh cycles.
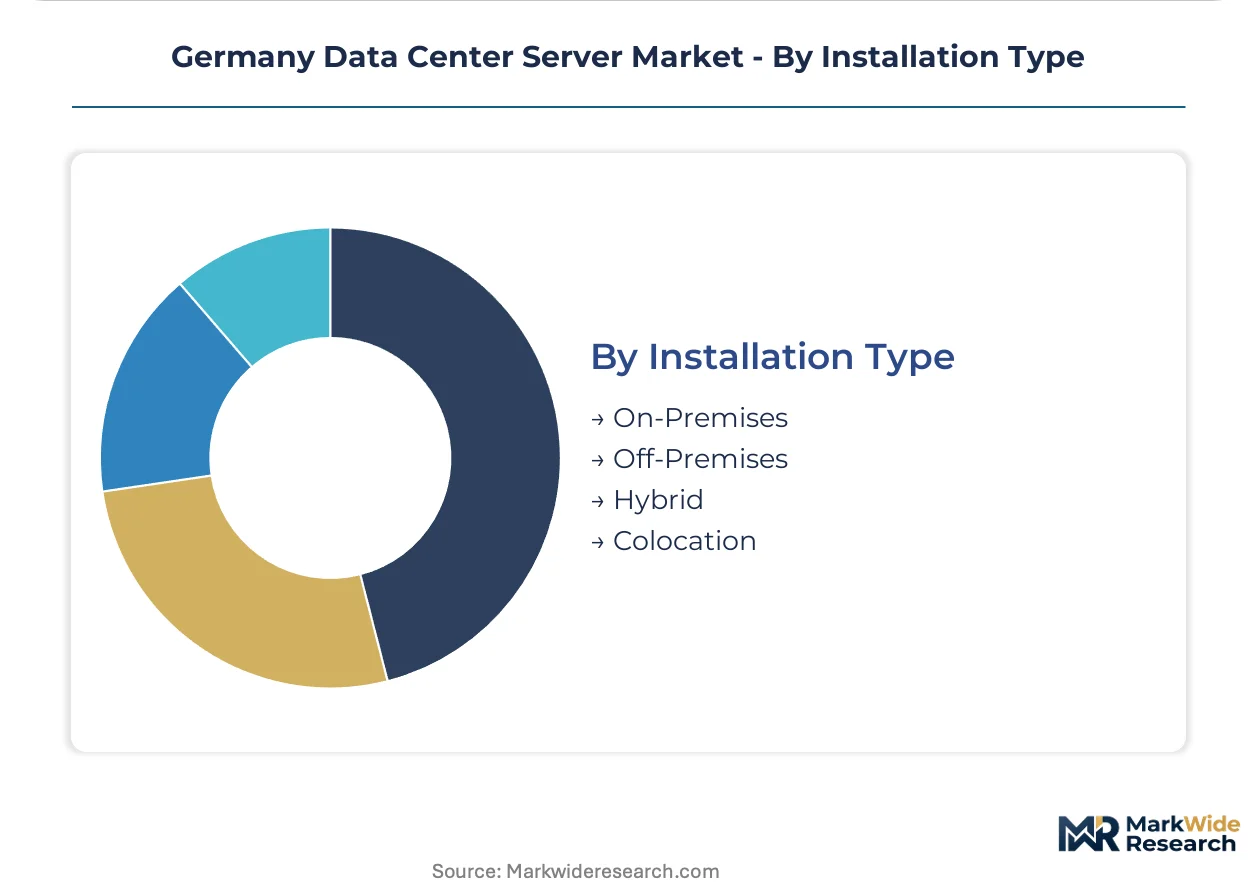
Installation Type:
Facility ownership models fragment across capital availability, regulatory compliance burden, and operational expertise concentration.
- Colocation:Third-party facility leasing dominates among mid-market tenants seeking operating expense treatment and technology refresh flexibility. Munich automotive suppliers concentrate here.
- On-Premises:Captive data centers persist among defense contractors and regulated financial institutions requiring direct control over physical security and data sovereignty compliance.
- Hybrid:Split workload architectures combine owned critical infrastructure with burst capacity from cloud service providers.
- Off-Premises:Fully outsourced server deployment concentrates among SMBs without internal facilities management capabilities.
Colocation holds the dominant position, while Hybrid is climbing the fastest as operators balance sovereignty requirements against cloud scalability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators concentrate server procurement across three distinct German corridors, each shaped by grid access, regulatory pressure, and legacy industrial density. State-level energy policy and BSI security standards fragment deployment timelines and infrastructure specifications.
North Rhine-Westphalia
Frankfurt's financial services density drives rack-server procurement for virtualization workloads. The EU Green Deal's Energy Efficiency Act mandates liquid-cooled architectures for new hyperscale campuses near Cologne and Düsseldorf. Grid interconnections along the Rhine corridor anchor concentrated cloud provider expansion.
Bavaria
Munich automotive headquarters underinvest in on-premise modernization relative to northern financial density. KBA building codes intersect with BSI IT security standards to govern physical infrastructure placement. Manufacturing suppliers in Ingolstadt and Nuremberg favor leasing structures for cyclical capacity management.
Baden-Württemberg
Stuttgart's engineering headquarters generate steady demand for tower servers among SMBs prioritizing capital expenditure control. The state's renewable sourcing mandates reshape procurement specifications toward lower thermal design power processors. Smart factory deployments in Heilbronn create edge-computing demand for ruggedized nodes.
Berlin-Brandenburg
Cloud service providers consolidate compute into blade-server chassis for virtualization workloads. Federal data sovereignty requirements extend deployment timelines for sensitive government workloads. The capital corridor attracts server procurement from providers building density near transmission grid nodes.
Hesse
Frankfurt's concentration of colocation facilities drives third-party facility leasing among mid-market tenants. CSRD disclosure obligations reshape internal infrastructure strategies for enterprises managing cyclical demands. The Rhine-Main metropolitan region anchors hybrid cloud architectures combining owned critical infrastructure with burst capacity.
Germany Data Center Server Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. Direct-to-operator sales infrastructure sustains large enterprise relationships, while sustainability-focused colocation operators drive specification shifts toward liquid-cooled platforms. Three archetypes dominate: full-stack infrastructure vendors, high-density thermal specialists, and Asia-Pacific component integrators. Consolidation pressures intensify through strategic partnerships and portfolio diversification into adjacent cooling and power distribution systems.
Within the full-stack infrastructure tier, Dell Inc and International Business Machines Corporation exemplify channel-controlling players with established direct sales presence. Super Micro Computer Inc occupies a position among thermal-specialist vendors, representing the high-density liquid-cooled platform archetype. Huawei Technologies Co Ltd and Inspur Group anchor the Asia-Pacific integrator segment, navigating procurement complexity to compete in select cloud infrastructure tenders.
| Leading Market Players |
|---|
| Dell Inc |
| International Business Machines (IBM) Corporation |
| Lenovo Group Limited |
| Cisco Systems Inc |
| Kingston Technology Company Inc |
| Quanta Computer Inc |
| Super Micro Computer Inc |
| Huawei Technologies Co Ltd |
| Inspur Group |
| Others |
Pricing and Supply Chain Analysis
Taipei and Hsinchu semiconductor clusters anchor processor and memory module availability, translating their fabrication capacity dominance into pricing leverage over German server integrators facing procurement timeline compression.
Pricing Analysis
Cost-plus contracts with Taiwanese foundries index to wafer pricing and logistics tariffs, embedding volatility into server BOMs. Three-tier pricing structure across liquid-cooled premium, air-cooled standard, and refurbished economy levels differentiates hyperscale cloud providers from SMB tower deployments. Price erosion runs through the standard rack segment as Chinese ODMs expand direct-to-operator channels. Cloud service providers exhibit lowest price sensitivity due to volume guarantees, while Stuttgart manufacturing SMBs negotiate aggressively on capital expenditure.
Supply Chain Analysis
Advanced processor feedstock concentrates in Taiwan and South Korea, with memory module packaging anchored in Chinese facilities. German server assembly draws from these hubs for GPUs, high-bandwidth memory, and custom ASICs. Single-source vulnerability around TSMC's leading-edge nodes exposes procurement timelines to geopolitical friction. Distribution runs through direct OEM relationships with hyperscale operators and channel partners serving mid-market colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German data center server procurement is entering a cyclical recovery phase as hyperscale cloud expansion accelerates and AI workload density forces infrastructure refresh cycles.
For Market Incumbents: Pre-empt margin compression from Chinese ODMs by deepening captive supply relationships with Taiwanese foundries for GPU and high-bandwidth memory allocation. Secure BSI IT security pre-certification for federal and defense workloads to extend deployment timelines that competitors cannot match. For New Entrants and Emerging Players: Establish a beachhead in Bavaria and Baden-Württemberg enterprise segments where manufacturing headquarters underinvest relative to northern financial services density. Target liquid-cooled retrofit opportunities in legacy Frankfurt colocation facilities with modular, factory-integrated platforms that reduce commissioning complexity. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium infrastructure play because EU Green Deal thermal mandates and CSRD disclosure obligations permanently reshape procurement specifications toward lower TDP processors and circular design certifications. Target acquisition archetype: thermal-specialist vendors with pre-certified liquid cooling telemetry and embedded lifecycle carbon tracking. The signal to watch is hyperscale operator RFP language shifting from PUE thresholds to explicit renewable sourcing and coolant chemistry requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Platform Integration | Addresses EU Green Deal thermal mandates while enabling 30+ kilowatt rack densities for AI training clusters. |
| BSI IT Security Pre-Certification | Compresses federal deployment timelines for sensitive government workloads against uncertified competitors. |
| Direct-to-Operator Sales Infrastructure | Bypasses channel margin capture in Bavaria and Baden-Württemberg manufacturing headquarters. |
| Embedded Lifecycle Carbon Tracking | Aligns with CSRD disclosure obligations reshaping enterprise procurement specifications. |
| Taiwanese Foundry Partnership | Secures allocation priority for advanced GPUs and high-bandwidth memory amid supply concentration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center operators, colocation facility managers, server procurement officers, and liquid cooling system integrators; and secondary validation against hyperscaler capex disclosures, BSI certification databases, EU regulatory filings, and customs import records for server components. Bottom-up triangulation of facility-level deployment data with top-down market sizing from vendor shipment disclosures anchored volume estimates.
Forecast inputs span server form factor, cooling architecture, end-user scale, and application workload density across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory. Model inputs include hyperscale cloud provider expansion timelines, EU AI Act infrastructure transparency requirements, and KBA building code enforcement patterns affecting physical infrastructure placement.
Stress conditions across energy tariff volatility, Taiwanese foundry allocation constraints, and BSI certification backlog durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hyperscale procurement continuity and regulatory timeline adherence. Cross-checking against hyperscaler public capex guidance and colocation industry absorption metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Brazil Optical Transceiver Market
Data Center and Networking
Japan Data Center Server Market
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
5G Edge Cloud Network and Services Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
Nvme Over Fiber Channel Market
Data Center and Networking
North America Subscriber Data Management Market
Data Center and Networking
Belgium Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Voice Over Internet Protocol (Voip) Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Internet Protocol Television (IPTV) Content Delivery Network (CDN) Market