
 Israel Data Center Server Market | 2026-2036
Israel Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Data Center Server Market Insights
The National Cyber Directorate's critical infrastructure protection directives are rebalancing the cost-of-entry calculus for foreign cloud operators seeking Israeli government contracts. Dell Inc. leverages its direct sales infrastructure to anchor enterprise relationships across financial and defense verticals. Cisco Systems Inc. sustains dominance in networking-integrated server architectures through its Unified Computing System portfolio.
Data center servers are engineered computing platforms built around x86, ARM, or proprietary processor architectures, typically housed in standardized rack units with redundant power and cooling subsystems, designed to process, store, and distribute digital workloads at enterprise scale. Rack servers occupy the volume core of the Israeli market due to their density flexibility in retrofitted facilities. Blade servers are gaining structural share among financial institutions pursuing space-constrained, high-availability deployments in Tel Aviv's premium real estate market.
Israel's National Cyber Directorate, the Ministry of Finance's Accountant General, and ISO 27001 certification requirements collectively shape procurement standards for sovereign-sensitive workloads. The Bank of Israel's operational resilience guidelines mandate geographic redundancy for financial institutions, directly expanding multi-cloud and colocation deployment footprints. Stakeholders must monitor whether forthcoming critical infrastructure designations extend regulatory capture to additional server categories previously exempt from domestic sourcing requirements.
Market Dynamics
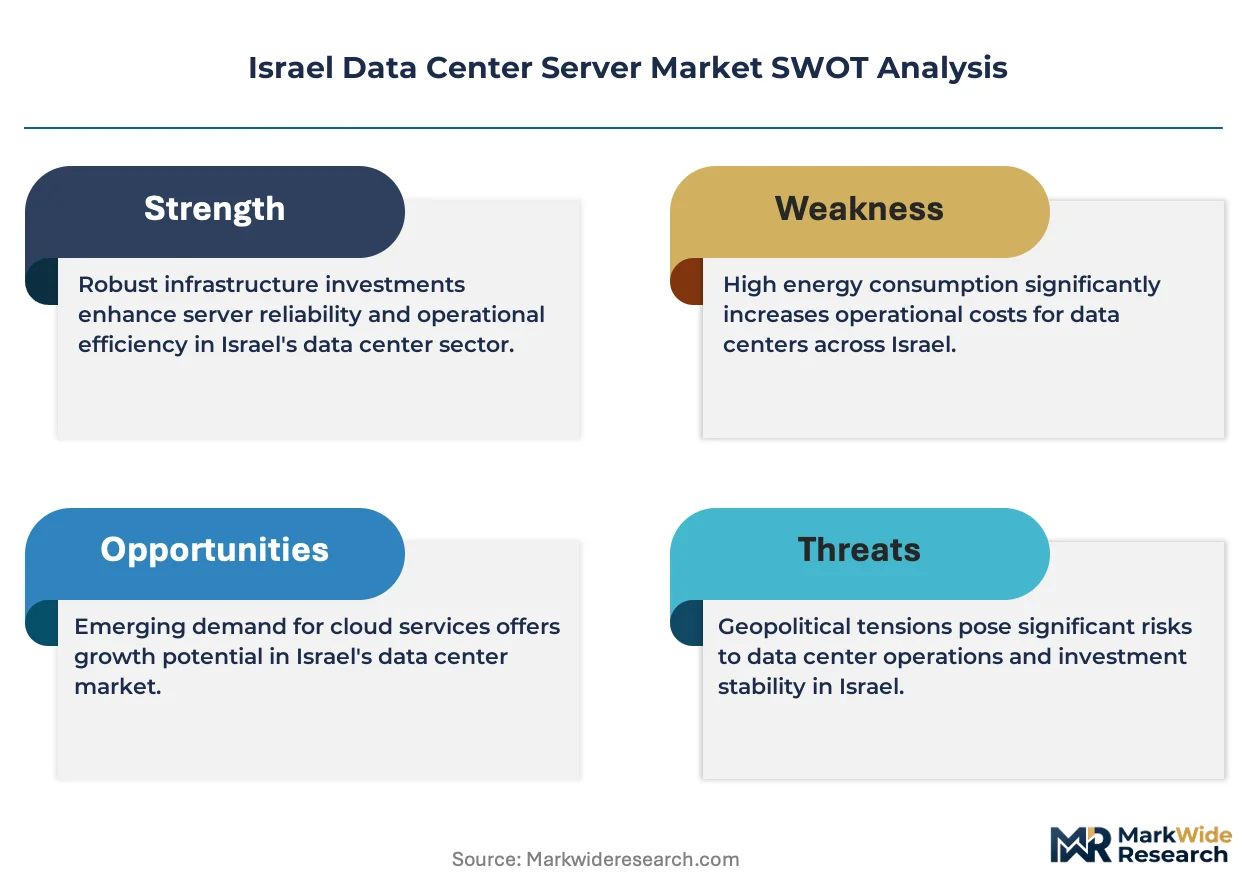
Israel's data center server market is being restructured by sovereign data mandates that require domestic processing of sensitive workloads, forcing foreign cloud operators to establish local infrastructure rather than serve Israeli clients from European hubs.
Growth Catalysts
- National Cyber Directorate Directives:Critical infrastructure protection mandates require localized data residency for government and financial workloads, expanding domestic server deployment footprints.
- AI Workload Expansion:Cloud service providers are building GPU-dense facilities in the Tel Aviv corridor to support generative AI training and inference demand from defense and technology sectors.
- Submarine Cable Proximity:Hyperscale facilities cluster near landing stations for the Blue-Raman and MedNautilus cable systems, reducing latency to European and Asian markets.
Market Restraints
- Real Estate Scarcity:Tel Aviv's premium commercial property market limits facility expansion, pushing power-dense blade server architectures over traditional rack deployments.
- Power Grid Constraints:Israel Electric Corporation infrastructure in central districts faces capacity saturation, capping total available megawatts for new server halls.
- Import Dependency:Specialized AI accelerators and high-core-count processors rely on concentrated Asian manufacturing, exposing procurement timelines to geopolitical shipping disruptions.
Strategic Opportunities
- Beersheba Tech Corridor:Southern development zones offer land and power reserves for secondary facilities, diversifying geographic risk beyond the Tel Aviv metro.
- Defense Sector Integration:Ministry of Defense classified workload requirements create captive demand for air-gapped, domestically manufactured server configurations.
- Liquid Cooling Convergence:Immersion and direct-to-chip cooling technologies enable higher rack densities where floor space is constrained, unlocking premium pricing for thermal management solutions.
Industry Challenges
- Certification Bottlenecks:ISO 27001 and Bank of Israel operational resilience audits create six-to-twelve month procurement delays for financial institutions deploying multi-cloud architectures.
- Legacy System Interoperability:Mainframe-dependent government agencies face integration complexity when migrating to x86 and ARM-based server environments, extending deployment timelines.
- Specialized Talent Scarcity:Data center engineering and critical facility operations expertise concentrates in the Tel Aviv metro, constraining expansion into secondary Israeli markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Data Center Server Market |
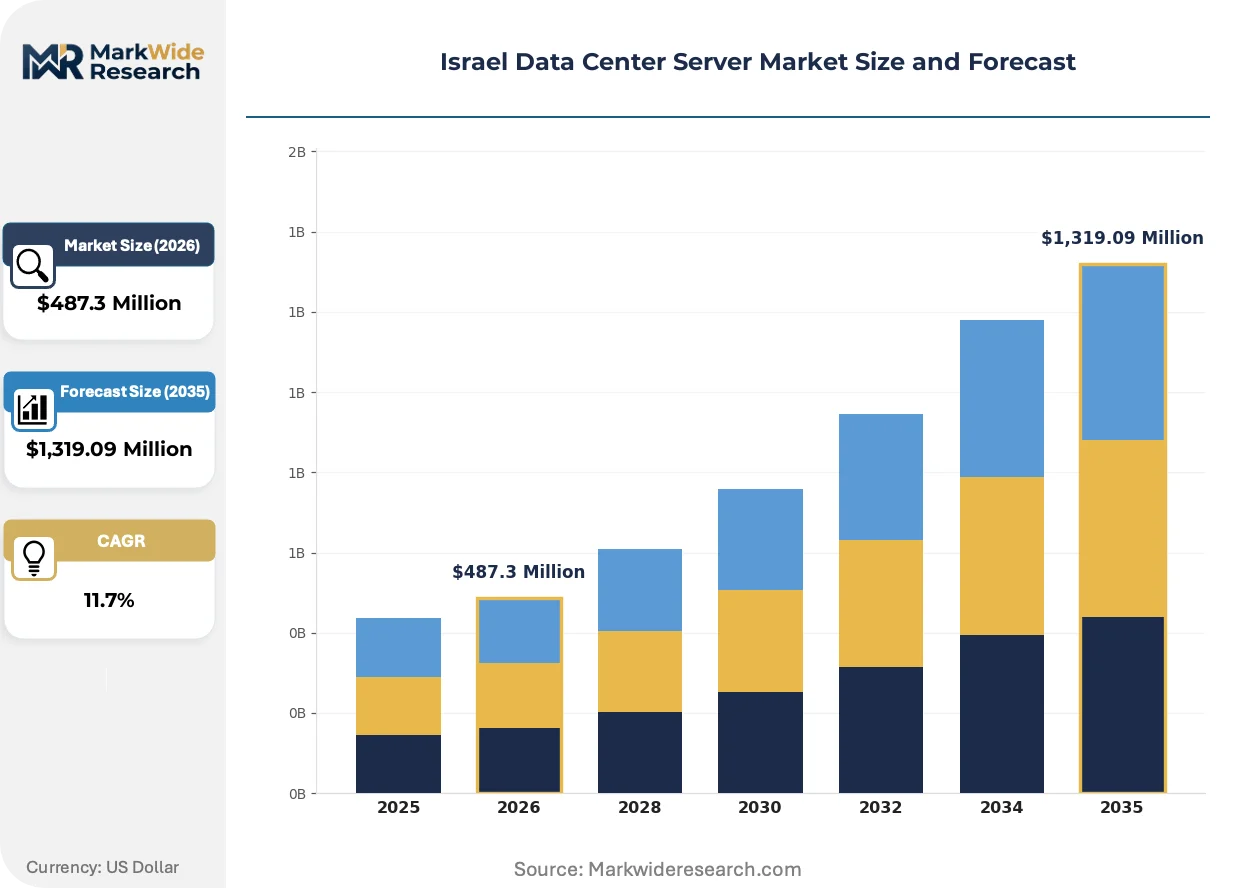
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Modular Servers End User: Telecommunication Providers, Financial Institutions, Cloud Service Providers, Government Agencies Deployment: On-Premise, Colocation, Hybrid, Multi-Cloud Form Factor: 1U, 2U, 4U, Custom |
| Companies Covered | Cisco Systems Inc., Lenovo Group Limited, Dell Inc., Quanta Computer Inc., Broadcom Inc., Hewlett Packard Enterprise, Supermicro Computer Inc., IBM, Intel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Data Center Server Market Trends and Innovations
Server architectures in Israel are compressing toward higher-density, liquid-cooled configurations as power and space constraints intensify, while regulatory pressure accelerates domestic manufacturing and certification capabilities.
Arm-based processors are consolidating market share in Israeli edge and cloud-native deployments, offering performance-per-watt advantages over x86 in thermally constrained facilities. Financial institutions and telecommunications operators are adopting these chips for containerized workloads. This consolidation is compressing Intel's historical dominance in the Israeli enterprise segment.
Israel's National Cyber Directorate has expanded critical infrastructure designations to cover cloud service provider facilities, mandating physical security standards and personnel screening protocols previously limited to defense installations. The directive requires biometric access controls and air-gapped management networks for designated facilities. Colocation operators in Tel Aviv and Haifa are retrofitting existing halls to meet these requirements ahead of enforcement deadlines.
Consumption-based server procurement is displacing traditional capital purchase models among Israeli mid-market enterprises, with financial buyers preferring operational expenditure structures that align costs to actual compute utilization. Managed service providers are bundling hardware, facility, and support into single-contract offerings. This pattern is most pronounced in healthcare and retail verticals where IT capital budgets face competing digital transformation priorities.
Israel Data Center Server Market Segmentation
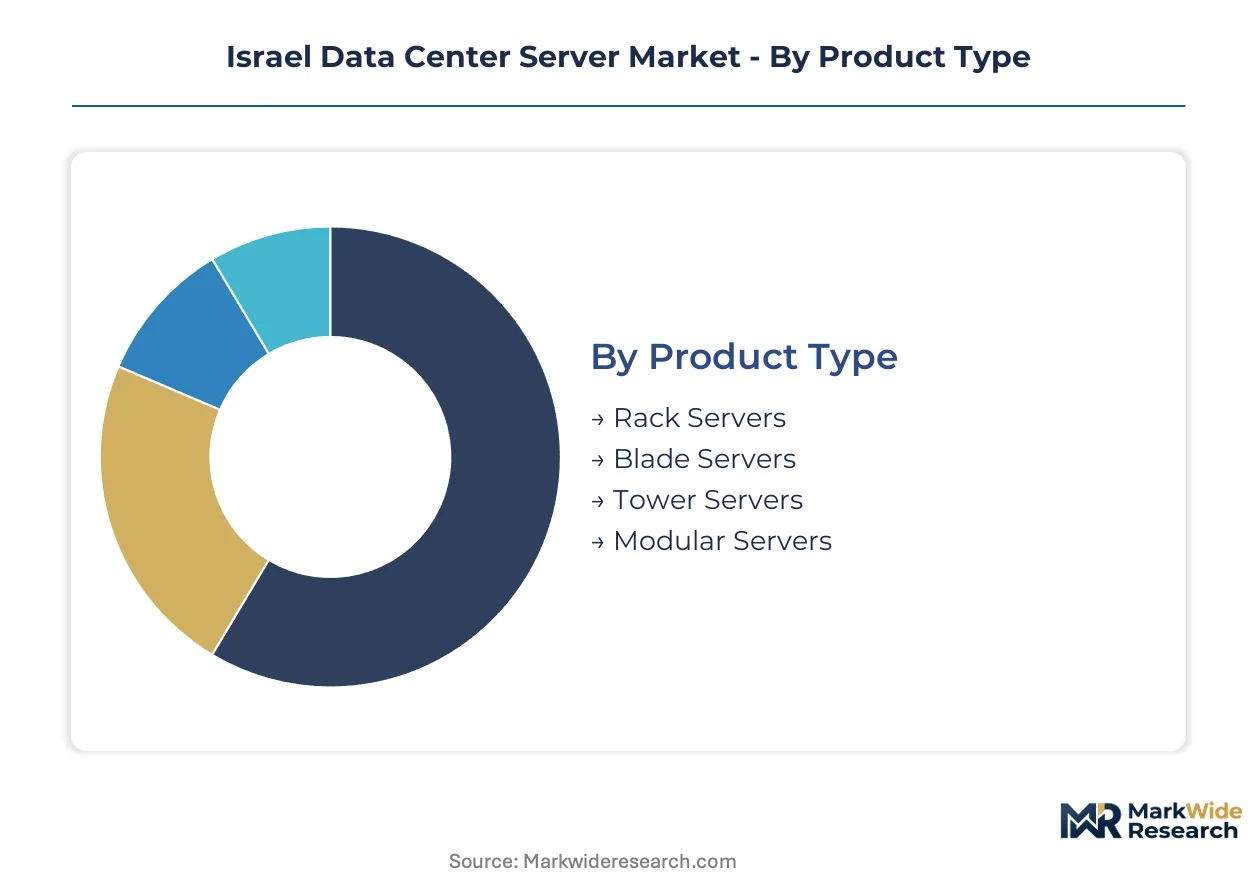
Server procurement patterns across Israeli enterprises diverge sharply between density-optimized hyperscale deployments and legacy infrastructure refresh cycles. Understanding these segment boundaries clarifies where capital concentrates versus where operational expenditure models are displacing ownership.
Product Type:
Rack servers anchor volume procurement, while blade architectures command premium positioning in space-constrained Tel Aviv facilities.
- Rack Servers:Standardized 19-inch enclosures accommodate 1U through 4U configurations with hot-swappable drive bays and redundant power supplies. Financial institutions in Ramat Gan and Herzliya deploy these for core banking virtualization, constrained by existing raised-floor footprints rather than power density limits.
- Blade Servers:Shared chassis architectures consolidate networking, storage, and compute into half-height or full-height server modules. Cloud service providers cluster these in Tel Aviv's submarine cable landing zones, maximizing processing per square meter where commercial real estate commands the country's highest premiums.
- Tower Servers:Vertical standalone units serve branch office and small datacenter requirements without rack infrastructure. Regional healthcare providers and municipal government offices in Haifa and Jerusalem maintain these for low-density workloads.
- Modular Servers:Composable infrastructure disaggregates compute, memory, and storage into independently scalable resource pools. Early adoption concentrates among defense contractors meeting Ministry of Defense classified workload specifications.
Today's leader: Rack Servers. Tomorrow's challenger: Blade Servers.
End User:
Procurement authority and security clearance levels determine server specification stringency across buyer categories.
- Telecommunication Providers:Bezeq, Partner, and Cellcom operate edge facilities requiring NEBS-compliant chassis for central office environments. 5G core network virtualization drives x86 server refresh cycles with sub-50ms latency requirements.
- Financial Institutions:Bank Leumi, Bank Hapoalim, and Discount Bank face Bank of Israel operational resilience mandates mandating geographic redundancy. These institutions deploy high-availability clusters across Tel Aviv and Beersheba with synchronous replication.
- Cloud Service Providers:AWS, Microsoft Azure, and Google Cloud have established Israeli regions to satisfy National Cyber Directorate data residency requirements. Their facilities drive GPU-dense configurations for AI training workloads from domestic technology unicorns.
- Government Agencies:The Ministry of Finance, National Security Council, and classified defense units require air-gapped infrastructure with domestically sourced or audited supply chains. Procurement flows through the Government Procurement Administration with extended vendor qualification timelines.
Cloud Service Providers currently absorb the dominant share of annual server shipments. Government Agencies are climbing the fastest as critical infrastructure designations expand.
Deployment:
Ownership models are bifurcating between capital-retentive government operators and expenditure-flexible commercial enterprises.
- On-Premise:Facility-owned and operated server halls with dedicated power, cooling, and security infrastructure. The Israel Defense Forces and intelligence community maintain these exclusively for classified processing.
- Colocation:Leased rack space in third-party facilities with shared mechanical and electrical systems. Mid-market enterprises in Tel Aviv's Diamond Exchange district favor this model to bypass real estate acquisition barriers.
- Hybrid:Orchestrated workloads spanning owned infrastructure and public cloud resources. Healthcare providers adopt this pattern to keep patient data on-premise while bursting analytics to cloud.
- Multi-Cloud:Distributing workloads across two or more hyperscale providers to mitigate vendor concentration risk. Fintech startups leverage this for regulatory arbitrage and resilience.
Colocation currently dominates new capacity additions. Multi-Cloud is gaining share fastest among venture-backed technology firms.
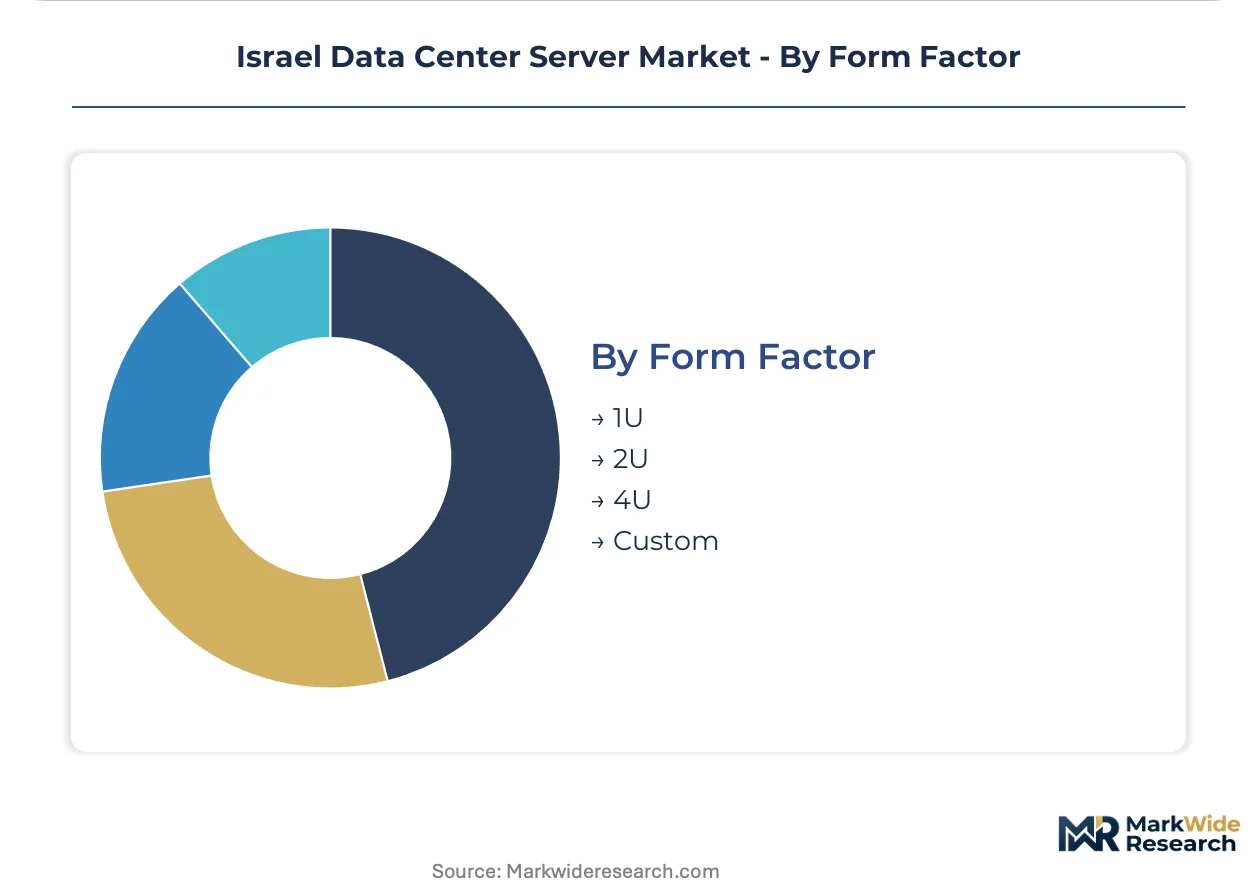
Form Factor:
Vertical space allocation directly correlates with thermal design power and processor core density requirements.
- 1U:Single rack unit servers maximize horizontal density for web serving and lightweight virtualization. These populate Tel Aviv colocation facilities where floor space pricing exceeds power costs.
- 2U:Dual rack units accommodate dual-socket configurations with expanded memory channels and accelerator slots. Enterprise database workloads and AI inference engines concentrate here.
- 4U:Quad rack units house multi-GPU nodes for training large language models and computer vision networks. Nvidia H100 and AMD MI300X deployments require this footprint for adequate thermal headroom.
- Custom:Non-standard dimensions for specialized defense applications, liquid-cooled immersion tanks, or OCP-compliant open rack architectures. The Ministry of Defense specifies these for signals intelligence processing.
2U configurations currently ship in highest volume. 4U GPU-dense nodes are expanding most quickly as generative AI demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's data center server industry traces its lineage to the country's defense technology ecosystem, where classified computing requirements spawned domestic capabilities that later commercialized into enterprise infrastructure supply.
Tel Aviv Metropolitan Corridor
Hyperscale cloud facilities cluster near submarine cable landing stations for Blue-Raman and MedNautilus systems. The National Cyber Directorate mandates biometric access controls and air-gapped management networks for designated critical infrastructure. Ramat Gan and Herzliya host financial institution server halls with synchronous replication across primary and backup sites.
Beersheba Tech Corridor
Southern development zones offer land reserves and power capacity unavailable in central districts. The Ministry of Defense operates classified processing facilities with domestically audited supply chains. Secondary data center construction accelerates here as operators seek geographic redundancy beyond the Tel Aviv metro.
Haifa Bay Area
Industrial port infrastructure supports import-dependent hardware logistics for specialized AI accelerators. The Israel Electric Corporation maintains transmission capacity for industrial-scale server deployments. Colocation operators retrofit existing facilities to meet expanded critical infrastructure designations.
Jerusalem
Government agencies concentrate procurement authority for sovereign-sensitive workloads through the Government Procurement Administration. The Ministry of Finance's Accountant General shapes certification requirements for fiscal systems. Legacy mainframe-dependent ministries face extended timelines migrating to modern server architectures.
Israel Data Center Server Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with established government and enterprise relationships. Market concentration reflects procurement complexity where certification timelines and security clearance requirements filter out smaller participants. Three archetypes dominate: defense-integrated domestic suppliers, multinational server OEMs with localized support infrastructure, and contract manufacturers serving hyperscale cloud operators. Capacity expansion and strategic partnerships with colocation operators constitute the primary competitive moves as foreign cloud providers establish Israeli regions.
Among multinational server OEMs, Dell Inc. and Cisco Systems Inc. occupy positions anchored by direct sales infrastructure and networking-integrated architectures respectively. Hewlett Packard Enterprise represents the enterprise-focused tier with high-availability cluster deployments for financial resilience mandates. Lenovo Group Limited sits within the scale-driven manufacturing segment serving volume procurement from cloud service providers establishing GPU-dense facilities.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| Lenovo Group Limited |
| Dell Inc. |
| Quanta Computer Inc. |
| Broadcom Inc. |
| Hewlett Packard Enterprise |
| Supermicro Computer Inc. |
| IBM |
| Intel Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive supply of liquid-cooled thermal management subsystems anchors both the cost position and pricing power of Israeli server deployments, as foreign hyperscalers face National Cyber Directorate mandates requiring localized assembly and extended vendor qualification timelines.
Pricing Analysis
The bundled-vs-unbundled service split separates capital-retentive government buyers from expenditure-flexible commercial operators. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 27001 and Bank of Israel resilience tiers commanding substantial premiums. Cost compression in standard rack configurations is intensifying because cloud service providers negotiate volume scale discounts for GPU-dense deployments. Government agencies exhibit lowest price sensitivity due to classified workload requirements, while mid-market healthcare providers face acute budget constraints favoring consumption-based procurement.
Supply Chain Analysis
Dual-sourcing requirements from the National Cyber Directorate mandate multi-supplier qualification for critical infrastructure components, extending procurement timelines. Taiwan, South Korea, and the United States concentrate advanced processor and AI accelerator manufacturing. High-bandwidth memory modules, specialized networking ASICs, and precision cooling components feed from concentrated Asian fabrication. Single-source vulnerability around Nvidia H100 and AMD MI300X allocations exposes Israeli deployments to geopolitical shipping disruptions. Distribution runs through Haifa port logistics with final integration at Tel Aviv metro facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Israel data center server market represents a late-cycle quality story as sovereign data mandates shift demand toward premium-certified, domestically integrated configurations with extended security vetting.
For Market Incumbents: Anticipate margin compression from Arm-based processor alternatives by accelerating certification investment for liquid-cooled, high-density architectures. Defensive consolidation through backward integration into thermal management assembly within the Beersheba Tech Corridor captures geographic redundancy premiums. Channel control over government procurement pathways remains essential as the National Cyber Directorate expands critical infrastructure designations.
For New Entrants and Emerging Players: Colocation operators in secondary Israeli markets present the most penetrable white-space target, as Tel Aviv power saturation pushes capacity southward. Defense contractor supply chain partnerships unlock Ministry of Defense classified workload specifications requiring air-gapped, domestically audited configurations. A managed service bundling approach—combining hardware, facility, and sovereign compliance—aligns with mid-market healthcare and retail procurement preferences.
For Investors and Strategic Acquirers: Roll-up economics work for regional colocation specialists because Tel Aviv real estate scarcity creates captive demand for geographically diversified facility footprints. Long-term viability rests on exposure to AI workload density expansion and regulatory capture from expanding critical infrastructure designations. Watch National Cyber Directorate enforcement deadlines as the signal for accelerated domestic integration requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables GPU-dense AI training configurations within Tel Aviv's thermally constrained facilities. |
| Beersheba Facility Expansion | Diversifies geographic risk beyond power-saturated central districts with available land reserves. |
| National Cyber Directorate Certification | Unlocks government and financial procurement pathways requiring biometric access and air-gapped management. |
| Arm-Based Processor Integration | Captures performance-per-watt advantages for containerized workloads in space-constrained deployments. |
| Defense Sector Partnership | Secures Ministry of Defense classified demand with domestically audited supply chain requirements. |
Research Methodology
Coverage spans Israel's Tel Aviv metropolitan corridor, Beersheba Tech Corridor, Haifa Bay Area, and Jerusalem, with primary inputs from each. Data collection combined structured interviews with data center engineering directors, colocation facility operators, cloud service provider procurement leads, and National Cyber Directorate compliance officers with secondary validation. Sources included hyperscaler capex disclosures, Israel Electric Corporation transmission capacity filings, Bank of Israel operational resilience guidelines, and customs records for server hardware imports. Bottom-up facility-level capacity estimates triangulated against top-down national infrastructure projections.
Rate-of-change decomposition anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user category, deployment model, and form factor, with sovereign certification tier as an industry-specific overlay. CAGRs derived from facility construction pipelines, power allocation approvals, and workload migration patterns observed across financial and defense verticals. AI training demand curves and submarine cable capacity expansion informed density assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to National Cyber Directorate enforcement timing and geopolitical disruptions to Asian semiconductor supply. Deviation in Ministry of Defense classified workload specifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Nigeria Data Center Power Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Global Software-Defined Data Center Market
Data Center Infrastructure
Middle East Data Center Rack Market