
 Jakarta Data Center Market | 2026-2036
Jakarta Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Jakarta Data Center Market Insights
Indonesia's island of Java is fragmenting into competing data center clusters as Jakarta's core saturates and secondary nodes emerge in Batam and Surabaya. PT DCI Indonesia leverages its domestic land-bank and power access to anchor capacity builds across Greater Jakarta. Equinix competes through interconnection density and enterprise channel control in the capital's premium colocation segment. BDx Indonesia differentiates via modular deployment speed and hyperscale-tailored design for international cloud operators.
Jakarta data centers constitute mission-critical facilities engineered to house servers, storage systems, and network equipment within controlled environments maintaining temperatures between 18°C and 27°C and power usage effectiveness ratios typically below 1.5. Their primary commercial purpose is enabling digital service continuity for enterprises, cloud platforms, and telecommunications operators across Southeast Asia's largest economy. Colocation and hyperscale deployments capture the dominant share of new capacity investment as international cloud providers seek certified facilities. Edge and modular formats represent the fastest-growing structural category, driven by latency-sensitive applications in financial services and content delivery networks requiring distributed infrastructure closer to end users.
Indonesia's Ministry of Communication and Informatics enforces data localization mandates under GR 71/2019, compelling foreign platforms to store citizen data within national borders and directly stimulating domestic facility construction. BIS electrical safety standards and Ministry of Energy and Mineral Resources directives on renewable power quotas shape facility design and operational compliance requirements. Stakeholders must monitor regulatory evolution around cross-border data flows and carbon intensity benchmarks to align capital deployment with enforceable compliance timelines.
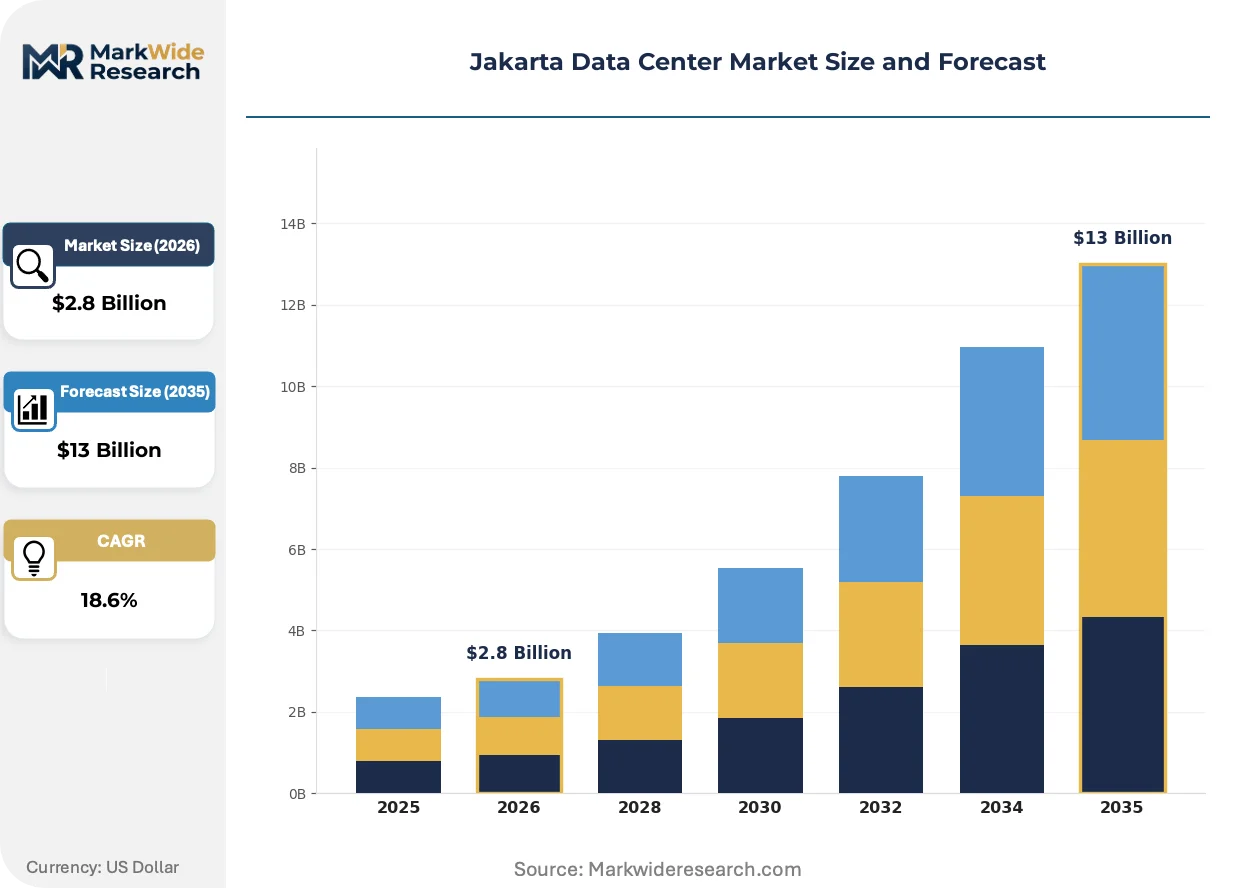
Market Dynamics
Jakarta's data center market is experiencing acute land and power scarcity in its core business district, forcing operators to secure capacity in peripheral corridors and driving modular deployment architectures as the dominant build format.
Growth Catalysts
- Data Localization Mandates:Indonesia's Ministry of Communication and Informatics enforces GR 71/2019, compelling foreign cloud platforms to store citizen data within national borders and directly stimulating domestic facility construction.
- Hyperscale Cloud Expansion:International cloud service providers are accelerating certified facility deployment to serve Southeast Asia's largest digital economy, with colocation and hyperscale formats capturing dominant investment flows.
- Financial Services Latency Requirements:Edge and modular data center formats are expanding rapidly to support banking and trading applications requiring distributed infrastructure closer to end users across Greater Jakarta.
Market Restraints
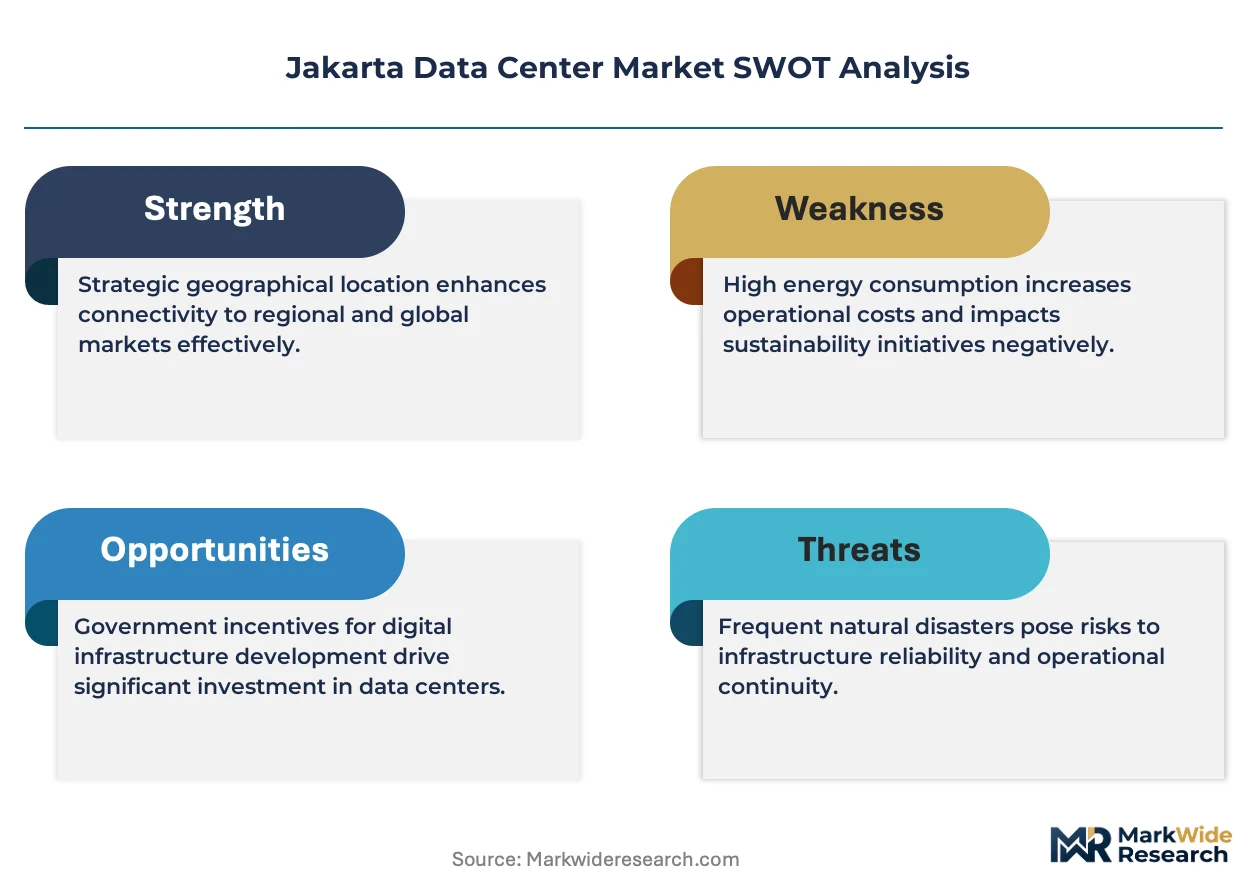
- Limited Grid Power Access:Central Jakarta faces constrained utility infrastructure, forcing operators to secure dedicated substations in Tangerang-Bekasi corridors where transmission capacity remains contested.
- Land Banking Concentration:Domestic land-holders with pre-positioned industrial zones command structural leverage over foreign entrants seeking build-ready parcels with fiber connectivity.
- Renewable Power Quotas:Ministry of Energy and Mineral Resources directives mandate escalating clean energy ratios, complicating procurement for facilities dependent on coal-heavy grid baseload.
Strategic Opportunities
- Secondary Node Development:Batam and Surabaya offer underpenetrated capacity zones with submarine cable landing advantages and lower land costs than saturated Jakarta core markets.
- Liquid Cooling Convergence:Integration of immersion cooling with high-density GPU clusters enables operators to capture artificial intelligence training workloads exceeding traditional air-cooled limits.
- Carbon Intensity Benchmarking:Anticipated regulatory evolution around enforceable sustainability timelines creates first-mover advantage for facilities securing renewable power purchase agreements ahead of compliance deadlines.
Industry Challenges
- Certification Timeline Compression:Tier III and IV uptime institute certifications require 18-24 month validation cycles, delaying revenue recognition for pre-leased capacity builds.
- Specialized Engineering Talent Scarcity:Critical facility operations demand certified professionals in mechanical and electrical systems engineering, with domestic training pipelines failing to match deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jakarta Data Center Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Center Type: Colocation, Hyperscale, Edge, Modular End User: IT & Telecom, Retail, Healthcare, Government Service Type: Infrastructure as a Service, Disaster Recovery, Managed Hosting, Network Services Operation Model: On-premises, Off-premises, Hybrid, Cloud-based |
| Companies Covered | XL Axiata Tbk PT (Princeton Digital Group), Equinix, PT DCI Indonesia, Edgnex Data Centers, Digital Realty, Telkomsigma, GTN Data Center (Edge Connex), BDx Indonesia, NTT Communications Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jakarta Data Center Market Trends and Innovations
Modular prefabrication and liquid cooling architectures are compressing traditional construction timelines while regulatory pressure on carbon intensity forces operational recalibration across facility portfolios.
Immersion cooling systems submerge server components in dielectric fluid, extracting heat more efficiently than conventional air handlers. Hyperscale operators deploying artificial intelligence training clusters are adopting this technology fastest. Traditional raised-floor air-cooled designs are rendering obsolete for workloads exceeding 30 kilowatts per rack.
Indonesia's Ministry of Communication and Informatics continues tightening data localization enforcement under GR 71/2019, with audit mechanisms expanding to cover metadata and transaction logs previously exempted. Foreign platform operators must now maintain fully redundant domestic infrastructure rather than relying on edge caching nodes. Enterprise colocation customers are responding by demanding contractual guarantees of exclusive Indonesian territory data residency.
Enterprise buyers are consolidating vendor relationships around operators offering bundled interconnection, cloud on-ramp, and managed services under single master agreements. Traditional pure-play colocation contracts with separate cross-connect procurement are losing share to integrated platform offerings. This consolidation pattern is most visible among financial services institutions in Jakarta's central business district seeking operational simplification.
Jakarta Data Center Market Segmentation
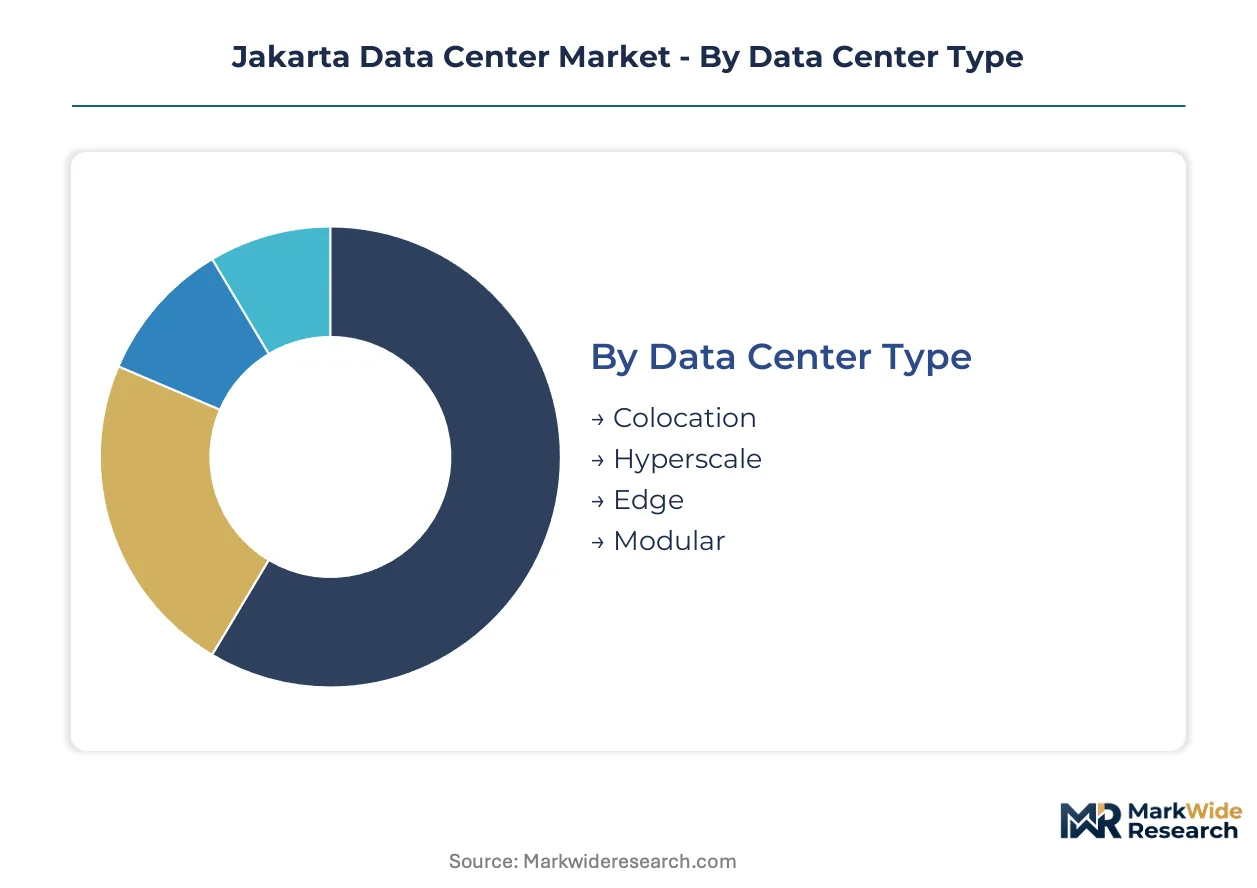
Jakarta's data center market fragments across facility architecture, customer verticals, and service delivery models. Understanding these divisions reveals where capital concentrates and which configurations capture regulatory tailwinds from Indonesia's data localization mandates.
Data Center Type:
Facility formats span from centralized hyperscale campuses to distributed edge nodes, each serving distinct latency and scale requirements across Greater Jakarta.
- Colocation:Multi-tenant facilities where enterprises lease rack space, power, and cooling from third-party operators. Banking and financial services institutions in Jakarta's central business district drive premium demand for certified Tier III facilities with cross-connect density to cloud on-ramps.
- Hyperscale:Purpose-built campuses exceeding 10 megawatts designed for single cloud tenant occupancy. International cloud providers expanding under GR 71/2019 compliance requirements anchor these builds in Tangerang-Bekasi corridors where land and substation access remain available.
- Edge:Compact facilities deployed within 10 kilometers of end users to minimize latency for real-time applications. Content delivery networks and securities trading platforms deploy these across Jakarta's peripheral districts.
- Modular:Prefabricated units enabling rapid capacity deployment without traditional construction timelines. Operators facing land scarcity in core Jakarta increasingly favor this format for speed-to-market advantages.
The dominant share belongs to colocation, while hyperscale is closing the gap fastest.
End User:
Demand concentration varies sharply by sector, with regulatory pressure and digital transformation maturity determining procurement patterns.
- IT & Telecom:Domestic telecommunications operators and international cloud platforms constitute the foundational demand base. These buyers prioritize fiber-dense locations with submarine cable landing station proximity.
- Retail:E-commerce platforms and omnichannel retailers require elastic capacity for transaction spikes during promotional periods. GR 71/2019 enforcement compels foreign retail platforms to maintain domestic primary infrastructure rather than edge caching alone.
- Healthcare:Hospital networks and telemedicine providers demand HIPAA-equivalent data protection standards. The Ministry of Health's electronic medical record mandates are accelerating facility certification requirements.
- Government:National and provincial agencies require sovereign data assurance for citizen services. Government procurement favors operators with domestic ownership structures and established security clearances.
IT and Telecom commands the largest installed base, though retail is expanding most quickly as e-commerce penetration deepens.
Service Type:
Commercial offerings stratify by operational responsibility transfer, from pure infrastructure rental to fully managed outcomes.
- Infrastructure as a Service:Self-service compute and storage provisioning with metered consumption. Enterprise buyers migrating from captive data centers favor this model for capital efficiency.
- Disaster Recovery:Secondary site replication and failover orchestration ensuring business continuity. Financial institutions under Bank Indonesia operational resilience mandates drive stringent recovery point objective requirements.
- Managed Hosting:Operator assumption of hardware procurement, maintenance, and platform management. Mid-market enterprises lacking internal infrastructure expertise concentrate demand here.
- Network Services:Cross-connects, internet exchange access, and software-defined WAN integration. Interconnection revenue per square meter exceeds pure space rental by substantial margins in Jakarta's premium facilities.
Infrastructure as a Service retains the volume lead, yet Disaster Recovery is gaining share fastest as regulatory resilience requirements tighten.
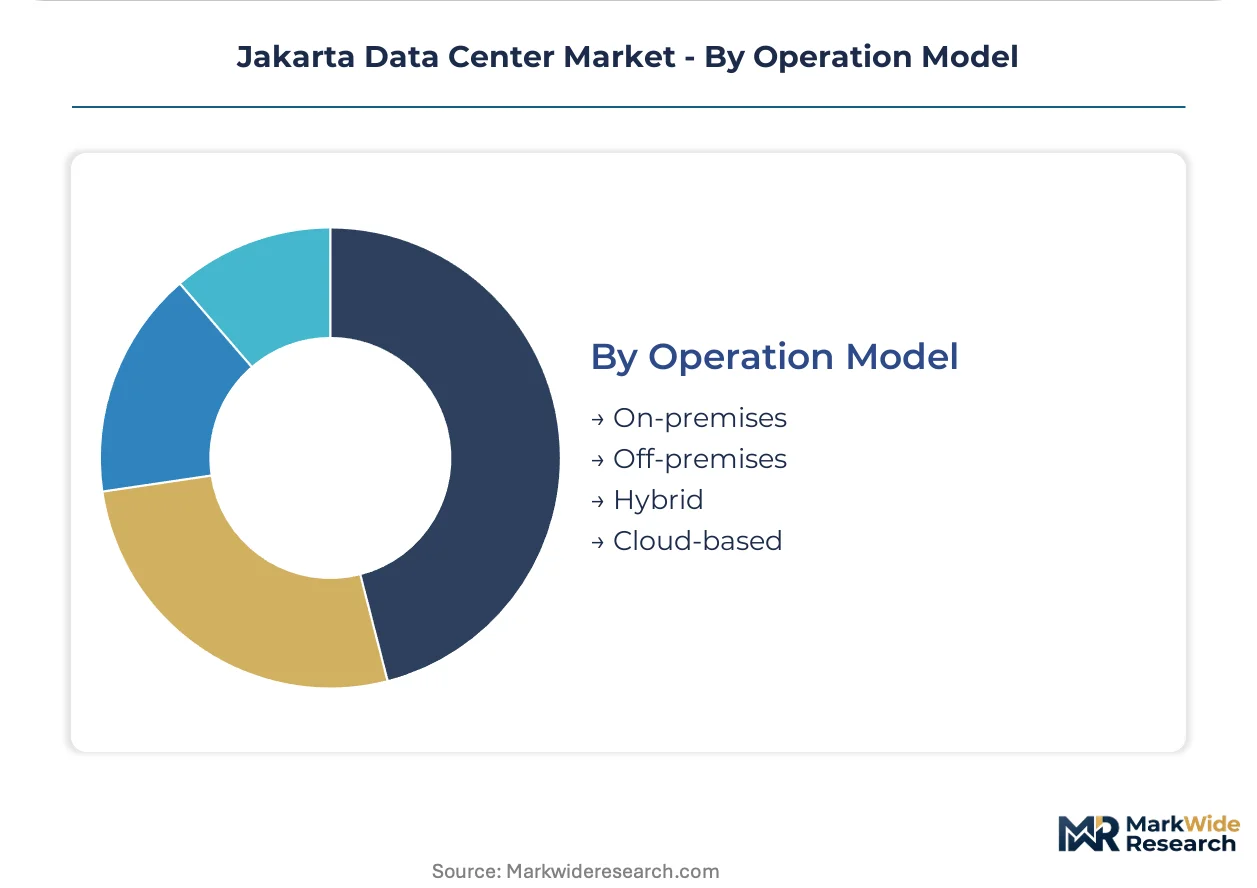
Operation Model:
Deployment location and control architecture determine cost structures and compliance postures for Jakarta-based workloads.
- On-premises:Customer-owned facilities with full operational control. State-owned enterprises and defense-adjacent organizations maintain this model for security classification requirements.
- Off-premises:Complete workload migration to third-party operator facilities. Cost reduction and GR 71/2019 compliance motivate enterprises to abandon aging captive data centers.
- Hybrid:Orchestrated distribution across owned and leased infrastructure with unified management planes. This architecture dominates among enterprises with legacy system interdependencies.
- Cloud-based:Native public cloud consumption with no physical infrastructure involvement. Startups and digital-native enterprises default to this model, though GR 71/2019 requires Indonesian region selection.
Hybrid deployments hold the current majority, while off-premises migration is accelerating most steeply as colocation supply expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center consumption patterns diverge sharply across Southeast Asian markets, with Indonesia mandating strict data localization while Singapore emphasizes cross-border connectivity and the Philippines prioritizes disaster-resilient distributed architectures.
Singapore
Financial services and maritime logistics drive demand for low-latency connectivity to global submarine cable networks. The Infocomm Media Development Authority enforces moratoriums on new hyperscale builds to manage power grid constraints. Data center operators concentrate in the Jurong and Loyang industrial estates, expanding through brownfield redevelopment rather than greenfield construction.
Malaysia
Iskandar Malaysia and Greater Kuala Lumpur attract overflow capacity from Singapore-constrained operators seeking lower land and power costs. The Malaysian Communications and Multimedia Commission implements data protection standards aligned with regional digital economy frameworks. Cyberjaya's technology park hosts expanding cloud availability zones serving ASEAN financial institutions.
Thailand
E-commerce platforms and digital banking services generate demand for Tier III certified facilities in Bangkok's eastern corridor. The National Broadcasting and Telecommunications Commission enforces cybersecurity notification requirements for critical information infrastructure. Eastern Economic Zone incentives draw hyperscale investments to Chonburi and Rayong provinces with dedicated power substations.
Vietnam
Foreign-invested manufacturing and domestic fintech applications stimulate facility construction around Ho Chi Minh City and Hanoi. The Ministry of Information and Communications mandates domestic data storage for online services under the Cybersecurity Law. Thu Duc City and Bac Ninh province emerge as primary clusters with improving submarine cable landing diversity.
Philippines
Business process outsourcing and remittance platforms require resilient infrastructure across geographically dispersed nodes. The Department of Information and Communications Technology promotes common tower policies to accelerate connectivity deployment. Cebu and Davao complement Metro Manila as secondary data center locations addressing seismic and typhoon risk distribution.
Jakarta Data Center Market Competitive Landscape
Capability concentration sits with domestic land-bank holders possessing pre-positioned industrial zones and power access agreements; scale advantage sits with international operators deploying capital through hyperscale campus developments. The Jakarta market exhibits tiered structure with three to four substantial domestic platforms controlling peripheral corridor land positions alongside global colocation specialists dominating premium central business district capacity. Strategic archetypes separate into land-anchored domestic developers, interconnection-dense global operators, and hyperscale-tailored modular specialists. Capacity expansion and certification-driven pre-leasing constitute the dominant competitive moves as operators race to capture GR 71/2019 compliance demand.
Among Indonesia-based developers, PT DCI Indonesia occupies the land-anchored archetype with established positions across Greater Jakarta corridors. Equinix represents the interconnection-dense global operator segment with premium colocation presence in the capital's core. BDx Indonesia exemplifies the hyperscale-tailored modular specialist category serving international cloud platform requirements. These three anchors illustrate the structural segmentation between domestic land control, global connectivity density, and rapid deployment speed.
| Leading Market Players |
|---|
| XL Axiata Tbk PT (Princeton Digital Group) |
| Equinix |
| PT DCI Indonesia |
| Edgnex Data Centers |
| Digital Realty |
| Telkomsigma |
| GTN Data Center (Edge Connex) |
| BDx Indonesia |
| NTT Communications Corporation |
| Others |
Pricing and Supply Chain Analysis
The Tangerang-Bekasi logistics corridor's escalating land and substation costs compress margins for modular deployments while amplifying price premiums for Tier III-certified capacity in Jakarta's saturated core. Supply concentration among domestic land-bank holders with pre-positioned industrial zones grants structural pricing power over foreign entrants seeking fiber-connected parcels.
Pricing Analysis
Long-term offtake contracts dominate hyperscale deployments as international cloud providers secure 10-15 megawatt commitments to satisfy GR 71/2019 compliance timelines. Price differentiation separates Tier IV uptime institute certifications from uncertified facilities, with volume scale and renewable power purchase agreements commanding additional premiums. Pricing pressure stems from renewable power quota mandates under Ministry of Energy and Mineral Resources directives, which inflate operational costs for coal-dependent operators. Financial services institutions in the central business district exhibit the least price sensitivity, prioritizing latency guarantees and cross-connect density over per-kilowatt economics.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU and semiconductor manufacturing equipment constrain hyperscale operators' ability to deploy artificial intelligence training clusters at planned density. Supply concentration centers on China for prefabricated modular units, Singapore for precision cooling components, and Japan for uninterruptible power supply systems. Critical dependencies include dielectric fluids for immersion cooling, lithium-ion battery systems, and submarine cable landing station access. Single-source vulnerability runs through China-dominated modular fabrication, where tariff exposure and logistics chokepoints threaten deployment timelines. Distribution feeds from operator-direct sales teams to enterprise procurement committees, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Jakarta's data center market fragments into specialized niches as GR 71/2019 enforcement splits demand between compliance-driven hyperscale builds and latency-sensitive edge deployments. This fragmentation creates distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Pre-empt land banking exhaustion in peripheral corridors by securing substation access agreements in Batam and Surabaya before grid capacity constraints replicate Jakarta's scarcity. Defend Tier III certification premiums against modular specialists through backward integration into captive renewable power generation, insulating margin structures from Ministry of Energy and Mineral Resources quota escalation. For New Entrants and Emerging Players: Build out liquid cooling integration capabilities to capture artificial intelligence training workloads exceeding 30 kilowatts per rack, where incumbent air-cooled designs face technical obsolescence. Target Surabaya's underpenetrated capacity zone with submarine cable landing advantages and lower land costs than saturated Jakarta markets. Lead with modular deployment speed as the primary go-to-market angle, compressing traditional 24-month construction timelines to 8-12 months for pre-leased capacity. For Investors and Strategic Acquirers: Domestic land-bank holders with established power access agreements and GR 71/2019 compliance track records represent the most defensible acquisition archetype across a 5-10 year holding period. Monitor Bank Indonesia operational resilience mandate enforcement as the critical inflection signal; accelerated disaster recovery requirements would reshape colocation demand toward certified facilities with redundant infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Capacity Expansion | Compresses deployment timelines to capture GR 71/2019 compliance demand before competitors secure substation access. |
| Renewable Power Purchase Agreement | Locks in carbon intensity benchmarks ahead of Ministry of Energy and Mineral Resources enforcement timelines. |
| Liquid Cooling Technology Licensing | Enables capture of artificial intelligence training clusters exceeding traditional air-cooled density limits. |
| Secondary Node Joint Venture | Distributes seismic and typhoon risk across Batam and Surabaya while accessing submarine cable diversity. |
| Tier IV Certification Investment | Commands premium pricing from financial institutions under Bank Indonesia operational resilience mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center operators, cloud platform procurement leads, and Ministry of Communication and Informatics regulatory officials; and secondary validation through operator capex disclosures, submarine cable landing station databases, and GR 71/2019 enforcement audit records. Facility engineering directors and enterprise IT infrastructure heads provided operational perspective on certification requirements and deployment timelines. Bottom-up capacity build tracking triangulated against top-down cloud provider expansion announcements to reconcile supply and demand estimates.
Forecast inputs considered facility type segmentation across colocation, hyperscale, edge, and modular formats; end-user verticals spanning IT and telecom, retail, healthcare, and government; and service delivery models from pure infrastructure rental to fully managed outcomes. CAGRs derived from power consumption trajectories, cloud provider regional expansion commitments, and data localization compliance deadlines modeled across the projection horizon. Submarine cable capacity additions and renewable power grid interconnection timelines served as industry-specific demand and supply anchors.
Stress conditions across land availability, substation commissioning delays, and GR 71/2019 audit enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud provider capex continuity and regulatory enforcement consistency. Material shifts in Ministry of Energy and Mineral Resources renewable quota timelines or Bank Indonesia operational resilience mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Italy Data Center Power Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Power Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Nigeria Data Center Server Market