
 Singapore Data Center Physical Security Market | 2026-2036
Singapore Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Physical Security Market Insights
The Singapore data center physical security market is pivoting around a widening split between AI-augmented integrated platforms and standalone perimeter hardware. Premium tiers now bundle biometric access control with real-time video analytics, while commodity segments compete on camera density and basic intrusion detection pricing. Schneider Electric leverages its building management integration to anchor high-margin bundled contracts. Johnson Controls competes through its fire-safety-to-physical-security convergence architecture. Axis Communications AB dominates the surveillance camera sub-layer with open-platform IP camera systems that sustain developer ecosystem loyalty.
Singapore data center physical security encompasses the hardware, software, and protocols that prevent unauthorized physical access to server facilities, typically requiring N+1 redundancy in power and cooling alongside multi-factor authentication at every entry point. Its primary purpose is to eliminate single points of physical compromise that could expose tenant data or trigger regulatory penalties. Access control systems and biometric systems represent the fastest-expanding margin pools, driven by financial institutions demanding zero-trust physical architectures. CCTV systems remain the largest revenue category but face commoditization as camera hardware costs decline and software value concentrates in video analytics layers. Perimeter security shows structural maturity with slower growth except at hyperscale campuses where vehicle barriers and drone detection add incremental spend.
Singapore's Cybersecurity Act and the Infocomm Media Development Authority's data center standards shape procurement requirements, mandating audit trails and biometric verification for critical infrastructure operators. The country's national cybersecurity regulator enforces incident reporting timelines that force operators to upgrade from passive recording to real-time threat response systems. Stakeholders must weigh the capital efficiency of cloud-managed security platforms against the operational control of on-premise deployments as tenant compliance requirements diversify across financial, government, and telecommunications verticals.
Market Dynamics
Singapore's Cybersecurity Act enforcement is compressing procurement cycles as data center operators race to deploy biometric access control and real-time video analytics before audit deadlines. The regulatory pressure is collapsing the traditional separation between physical security and IT infrastructure teams.
Growth Catalysts
- Biometric Mandates:The Cybersecurity Act requires multi-factor authentication at every critical infrastructure entry point. Financial institutions are driving zero-trust physical architectures across Jurong and Tanjong Koyang facilities.
- Hyperscale Campus Expansion:Cloud service providers are bundling integrated physical-digital security into new construction contracts. Vehicle barriers and drone detection systems add incremental deployment spend at these campuses.
- Cloud-Managed Platforms:Operators are migrating from on-premise security management to cloud-native platforms. This shift reduces capital intensity while enabling centralized compliance reporting for multi-tenant facilities.
Market Restraints
- Camera Hardware Commoditization:Declining unit costs for IP cameras are compressing margins in the CCTV segment. Value is concentrating in video analytics software layers rather than hardware procurement.
- Supply Concentration Risk:Specialist biometric sensor suppliers face capacity constraints as demand surges. Lead times for facial recognition terminals have extended across Southeast Asian manufacturing hubs.
- Integration Complexity:Legacy access control systems require expensive retrofitting to interface with modern AI-augmented platforms. Building management system incompatibility creates deployment friction in older facilities.
Strategic Opportunities
- Fire-Safety Convergence:Integrated platforms combining fire suppression monitoring with physical access control are opening premium contract tiers. Johnson Controls and Schneider Electric are anchoring bundled offerings in this space.
- Edge Data Center Security:Distributed edge facilities outside traditional corridors lack standardized protection. Modular security pods with pre-integrated biometric and surveillance systems address this white space.
- IMDA Standards Alignment:The Infocomm Media Development Authority's data center certification program rewards operators with audit-ready physical security documentation. Compliance consulting services represent an adjacent revenue stream.
Industry Challenges
- Cyber-Physical Skill Gap:Security operations centers require analysts fluent in both network intrusion detection and physical breach response. Singapore's technical training pipeline has not scaled to meet this hybrid demand.
- Legacy System Interoperability:Facilities built under earlier building codes contain proprietary access control protocols. API translation layers add cost and latency to real-time threat response architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Physical Security Market |
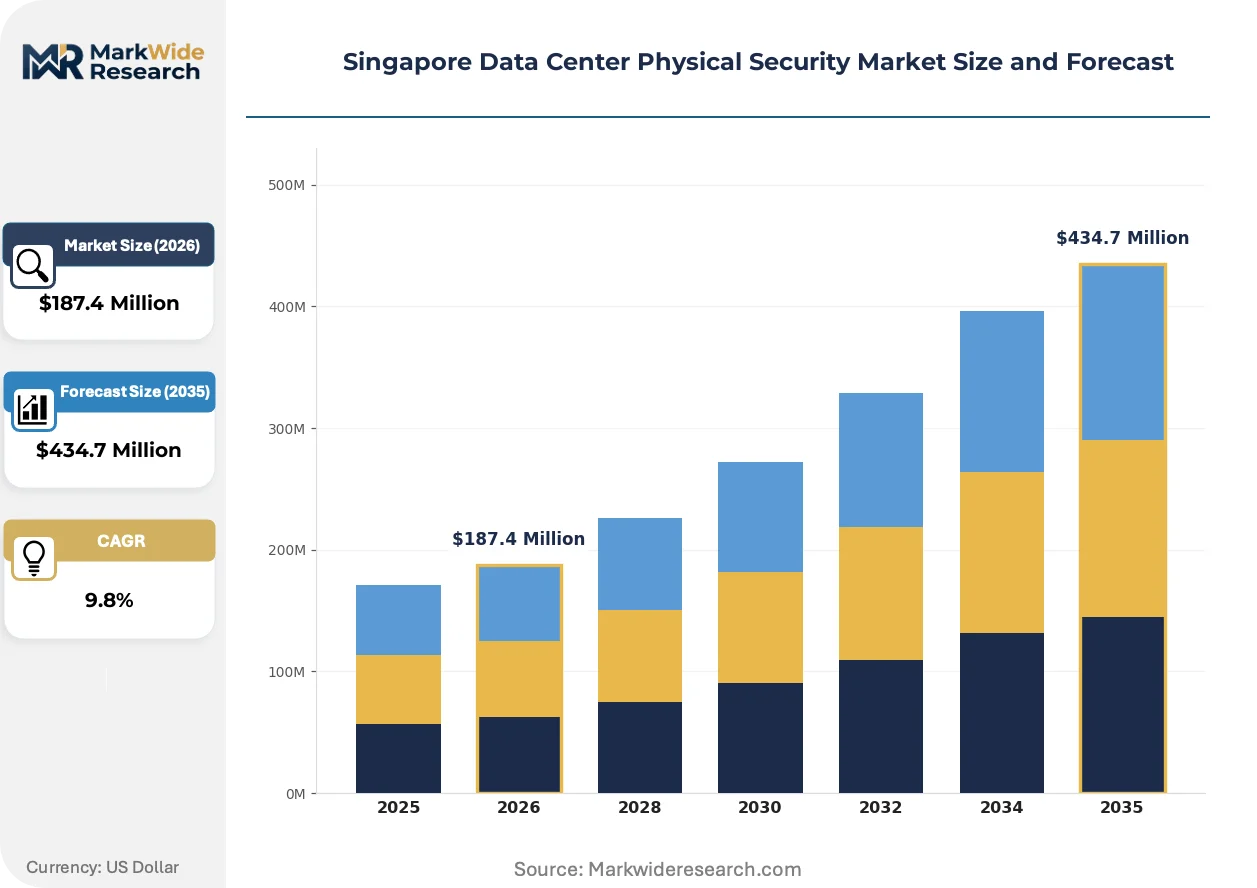
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Systems, Access Control Systems, Intrusion Detection, Perimeter Security Technology: Biometric Systems, Surveillance Cameras, RFID, Video Analytics End User: Telecommunications, Financial Institutions, Cloud Service Providers, Government Application: Physical Intrusion Prevention, Data Protection, Risk Management, Compliance |
| Companies Covered | Axis Communications AB, Schneider Electric, Johnson Controls, Bosch Sicherheitssysteme GmbH, ASSA ABLOY, ABB Ltd, Cisco Systems Inc, Dahua Technology, Genetec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Physical Security Market Trends and Innovations
AI-augmented video analytics is collapsing the distinction between surveillance recording and active threat detection. Singapore operators are reconfiguring security operations centers around predictive rather than reactive protocols.
Edge-based video analytics is consolidating processing power at the camera layer rather than centralizing in server rooms. Hyperscale operators are deploying this architecture across Jurong campuses to reduce bandwidth load and enable sub-second threat response. The shift is compressing demand for traditional network video recorder hardware while expanding software licensing revenue pools.
Singapore's Cybersecurity Act enforcement is mandating real-time incident reporting with strict timeline requirements. Data center operators must upgrade from passive recording systems to automated alert generation with audit trail integrity. Financial services tenants are driving the fastest compliance adoption, with government facilities following under parallel critical infrastructure designations.
Subscription-based security-as-a-service models are displacing capital-intensive ownership structures among mid-tier colocation providers. These operators prefer operational expenditure treatment for biometric and surveillance deployments. The shift is most visible in Tanjong Koyang corridor facilities where private equity-backed operators prioritize cash flow predictability over asset ownership.
Singapore Data Center Physical Security Market Segmentation
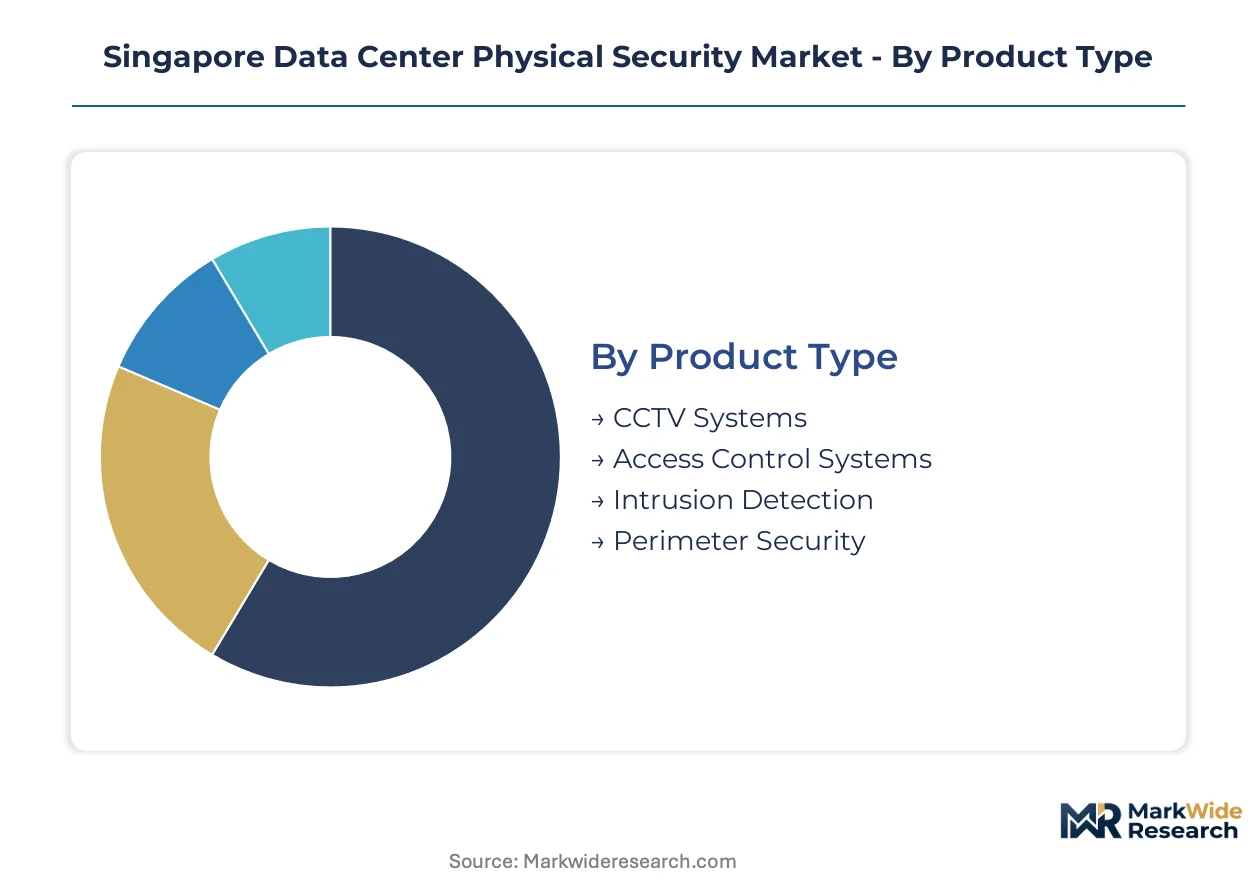
Singapore data center operators configure security procurement around integration depth rather than standalone component performance. Procurement teams weigh whether systems operate as isolated silos or feed unified command platforms that satisfy Cybersecurity Act audit requirements.
Product Type:
Standalone perimeter hardware dominates legacy deployments across older facilities, while integrated platforms now anchor new construction in Jurong and Tanjong Koyang corridors.
- CCTV Systems:IP camera networks with centralized network video recorders form the visual backbone of facility monitoring. Camera density requirements are tightening across financial institution colocation contracts in the Tanjong Koyang corridor, though hardware margins compress as unit costs decline.
- Access Control Systems:Multi-factor authentication gates with credential verification at every entry point enforce zero-trust physical architectures. Financial institutions and cloud service providers are driving replacement cycles as Cybersecurity Act mandates eliminate single-factor legacy systems.
- Intrusion Detection:Sensor networks detecting unauthorized entry through vibration, thermal, or motion signatures. Modular deployments suit edge facilities lacking permanent security staffing.
- Perimeter Security:Vehicle barriers, fencing, and drone detection systems protecting facility boundaries. Hyperscale campuses add incremental spend here as vehicle ramming threats receive regulatory attention.
CCTV Systems leads volumes today; Access Control Systems is gaining share fastest.
Technology:
Cost tier stratification separates biometric premiums from commoditized surveillance hardware, with middleware analytics capturing expanding margin pools.
- Biometric Systems:Facial recognition and fingerprint terminals delivering non-repudiable identity verification. Lead times from Southeast Asian manufacturing hubs have extended as Singapore facility demand surges ahead of audit deadlines.
- Surveillance Cameras:Fixed and PTZ IP cameras with varying resolution and low-light performance specifications. Open-platform systems sustain developer ecosystem loyalty through API accessibility.
- RFID:Contactless credentialing for personnel and asset tracking within facility zones. Government facilities favor this modality for its audit trail granularity.
- Video Analytics:AI-augmented software layers transforming passive recording into predictive threat detection. Edge-based processing architectures reduce bandwidth load while enabling sub-second response protocols.
Surveillance Cameras leads volumes today; Video Analytics is climbing the fastest.
End User:
Customer type determines compliance stringency, with financial and government verticals imposing zero-trust architectures that telecommunications operators treat as optional.
- Telecommunications:Carrier-neutral facilities prioritizing uptime continuity over biometric sophistication. Legacy access control retrofitting creates deployment friction in older exchange buildings.
- Financial Institutions:Banks and payment processors mandating multi-factor authentication at every critical infrastructure entry point. Zero-trust physical architectures are standard across their Jurong and Tanjong Koyang deployments.
- Cloud Service Providers:Hyperscale operators bundling integrated physical-digital security into new construction contracts. Vehicle barriers and drone detection add incremental deployment spend at their campuses.
- Government:Critical infrastructure operators under parallel designation to financial facilities. Real-time incident reporting timelines force upgrades from passive recording to automated alert generation.
Cloud Service Providers leads volumes today; Financial Institutions is expanding most quickly.
Application:
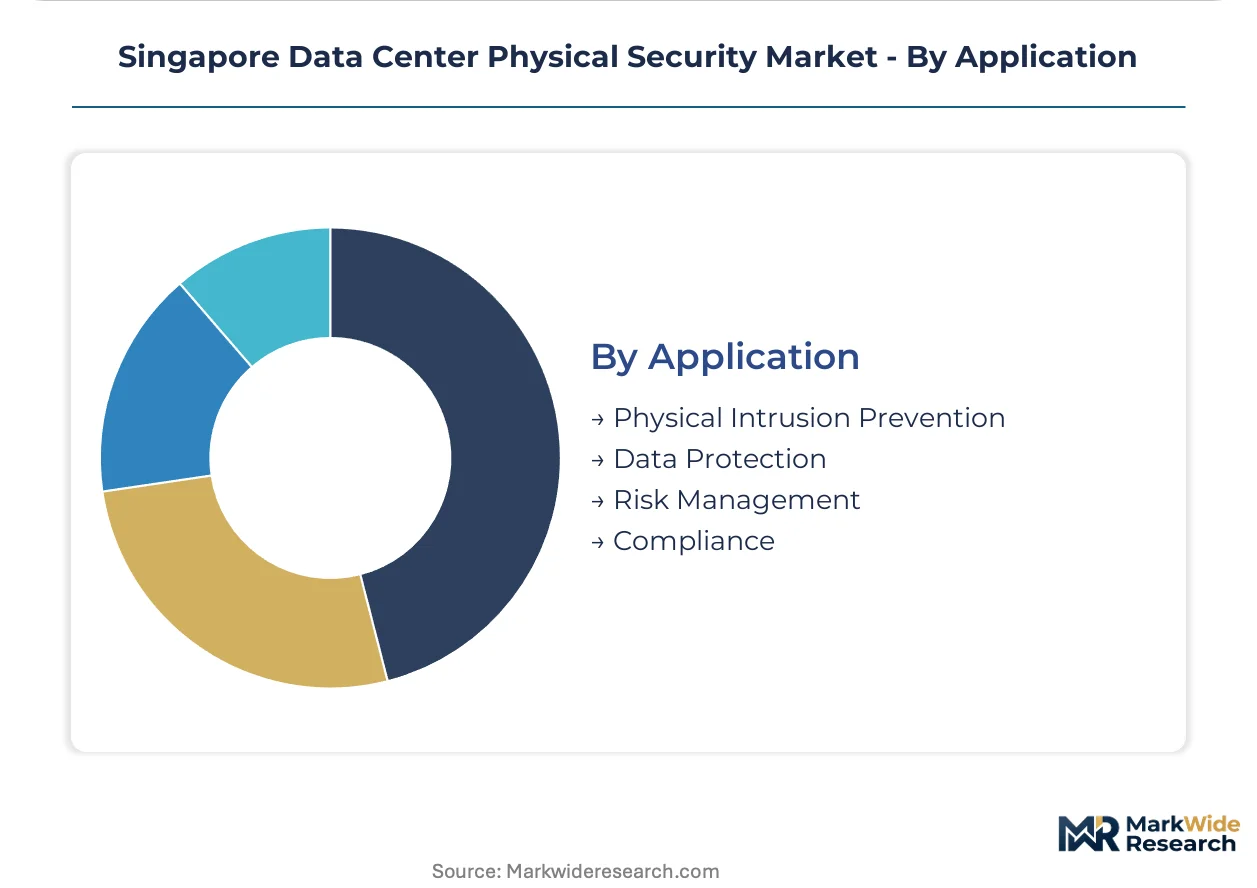
Maturity differentiation separates established intrusion prevention from emerging compliance automation, with risk management emerging as the integration layer.
- Physical Intrusion Prevention:Barrier and detection systems blocking unauthorized facility access. N+1 redundancy requirements extend to security power and cooling alongside server infrastructure.
- Data Protection:Access logging and audit trails preventing physical compromise of tenant data. Cybersecurity Act enforcement is collapsing traditional separations between physical security and IT infrastructure teams.
- Risk Management:Unified threat assessment combining physical breach probability with business impact quantification. Mid-tier colocation providers are adopting subscription-based security-as-a-service models here.
- Compliance:Automated documentation satisfying IMDA certification and Cybersecurity Act audit requirements. Compliance consulting services represent an adjacent revenue stream for systems integrators.
Physical Intrusion Prevention leads volumes today; Compliance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's cybersecurity workforce concentration anchors physical security procurement across Southeast Asian data center corridors. The Cybersecurity Act enforcement timeline compresses regional deployment cycles as neighboring markets observe Singapore's compliance precedents. Technical talent pipelines from the National University of Singapore and Nanyang Technological University feed specialist demand for integrated physical-digital security roles.
Jurong Data Center Corridor
Hyperscale cloud campuses dominate procurement volumes in this western Singapore cluster. The Cybersecurity Act mandates biometric verification at every critical infrastructure entry point, forcing retrofitting of legacy facilities built under earlier building codes. Financial institutions and cloud service providers co-locate here, driving integrated security platform deployments with real-time video analytics.
Tanjong Koyang Corridor
Private equity-backed colocation operators prioritize subscription-based security-as-a-service models in this emerging eastern hub. IMDA data center certification requirements shape procurement specifications, with audit-ready documentation becoming a contract prerequisite. Camera density requirements tighten across financial institution tenant contracts as zero-trust physical architectures become standard.
Central Business District Fringe
Legacy telecommunications exchange buildings create retrofit friction in this mature sub-market. Proprietary access control protocols from earlier building codes require expensive API translation layers for AI-augmented platform integration. Carrier-neutral facilities here prioritize uptime continuity over biometric sophistication, creating a two-tier security market.
Changi Logistics and Technology Zone
Edge data center deployments outside traditional corridors lack standardized protection frameworks in this northeastern precinct. Modular security pods with pre-integrated biometric and surveillance systems address this white space. Government facilities under critical infrastructure designation drive real-time incident reporting system upgrades.
Singapore Data Center Physical Security Market Competitive Landscape
Top-tier vendors anchor high-margin bundled contracts, while mid-tier specialists compete on component pricing and integration flexibility. The market structure concentrates around building management convergence and open-platform surveillance ecosystems. Two strategic archetypes dominate: integrated building-to-security platform providers and specialized biometric sensor manufacturers. Competitive moves center on fire-safety-to-physical-security convergence architectures and cloud-native security management platform migrations.
Within the integrated platform tier, Schneider Electric and Johnson Controls represent building management convergence archetypes, anchoring premium contract tiers through bundled fire suppression and access control offerings. Axis Communications AB occupies a distinct position as an open-platform surveillance specialist, sustaining developer ecosystem loyalty through API accessibility. Bosch Sicherheitssysteme GmbH exemplifies the European engineering-led approach to perimeter security hardware. These three anchors illustrate the market's tripartite segmentation: building integration, open-platform software, and engineered hardware.
| Leading Market Players |
|---|
| Axis Communications AB |
| Schneider Electric |
| Johnson Controls |
| Bosch Sicherheitssysteme GmbH |
| ASSA ABLOY |
| ABB Ltd |
| Cisco Systems Inc |
| Dahua Technology |
| Genetec |
| Others |
Pricing and Supply Chain Analysis
Biometric sensor module costs from Southeast Asian manufacturing hubs cascade through three distinct pricing tiers as systems integrators bundle hardware with compliance documentation and managed services for Singapore data center operators facing Cybersecurity Act deadlines.
Pricing Analysis
Bundled fire-safety-to-security convergence contracts command premium positioning against unbundled perimeter hardware procurement. Three-tier pricing structure across premium, standard, and economy levels separates integrated platform providers from standalone camera suppliers and commodity intrusion detection vendors. Price differentiation hinges on Cybersecurity Act certification tier and after-sales service bundling. Cost compression in the CCTV segment is intensifying because camera hardware costs decline faster than software value accretion. Mid-tier colocation operators exhibit highest price sensitivity as private equity backers prioritize operational expenditure treatment over capital deployment.
Supply Chain Analysis
Single-source vulnerability sits with facial recognition terminal suppliers concentrated in China, Taiwan, and South Korea. Specialist biometric sensor production draws from semiconductor wafer foundries, precision optics manufacturing, and edge AI processor fabrication. Supply chain risk centers on extended lead times as Singapore facility demand surges ahead of regulatory audit deadlines. Distribution runs through systems integrators with IMDA certification credentials who anchor bundled procurement contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore data center physical security functions as a stable compounder where regulatory mandate enforcement generates predictable replacement cycles and recurring compliance service revenue.
For Market Incumbents: Deepen integration between building management systems and security platforms to defend against cloud-native entrants offering subscription-based alternatives. Anchor premium contract tiers through captive supply of fire suppression monitoring hardware. Invest in IMDA certification documentation capabilities to capture adjacent compliance consulting revenue streams. For New Entrants and Emerging Players: Enter via modular security pod deployments targeting edge data center facilities in Changi Logistics and Technology Zone outside established Jurong and Tanjong Koyang corridors. White space exists in standardized protection frameworks for distributed edge infrastructure lacking permanent security staffing. Position through security-as-a-service models emphasizing operational expenditure treatment for private equity-backed colocation operators. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier specialists lack capital to bridge legacy system interoperability gaps for AI-augmented platform integration. Long-term viability favors vertically integrated providers controlling both biometric hardware supply and cloud-native management software layers. Monitor hyperscale campus construction announcements as inflection indicators for integrated security procurement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Safety Convergence Platform | Johnson Controls and Schneider Electric anchor premium bundled contracts combining suppression monitoring with access control. |
| Cloud-Native Security Management Migration | Mid-tier colocation operators in Tanjong Koyang prioritize operational expenditure treatment over asset ownership structures. |
| Edge-Based Video Analytics Deployment | Hyperscale operators across Jurong campuses reduce bandwidth load while enabling sub-second threat response protocols. |
| Biometric Terminal Capacity Expansion | Southeast Asian manufacturing hubs face capacity constraints as Singapore demand surges ahead of Cybersecurity Act deadlines. |
| IMDA Certification Alignment Services | Systems integrators capture adjacent revenue streams through audit-ready physical security documentation offerings. |
Research Methodology
Bottom-up data center operator modeling reconciled against top-down security vendor shipment tracking forms the analytical core. Primary interviews with facility security directors, systems integration specialists, biometric sensor procurement managers, and IMDA compliance officers combined with secondary validation against Cybersecurity Act enforcement notices, IMDA certification databases, and vendor SEC filings. Trade data from Singapore customs records and hyperscaler capital expenditure disclosures provided supply-side triangulation.
Historical trendline analysis across installed base replacement cycles and new construction permitting data established baseline growth parameters. Segmentation modeling incorporated product type, technology tier, end-user vertical, and corridor-specific deployment patterns throughout the forecast period. CAGRs were derived from regression analysis against regulatory mandate timelines and hyperscale campus construction pipelines. Forecast inputs included biometric authentication penetration rates and cloud-managed platform adoption curves.
Inputs from facility operators and systems integrators were available through the study window; gaps in proprietary vendor pricing data introduce uncertainty bands around margin estimates. Forecasts reflect assumptions regarding Cybersecurity Act enforcement consistency and hyperscale construction schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Philippines Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Power Market