
 Shanghai Data Center Market | 2026-2036
Shanghai Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Shanghai Data Center Market Insights
Liquid cooling infrastructure is expanding across Shanghai facilities as thermal loads from AI training clusters render traditional air-cooled designs uneconomical at scale. GDS Holdings Limited anchors the premium colocation segment through captive land banks in Lingang and Jiading. China Telecom Corporation Ltd leverages its state-backed fiber backbone to dominate interconnection pricing. VNET Group Inc. competes on hyperscale build velocity, sustaining delivery timelines that private operators struggle to match.
A data center constitutes a dedicated facility housing computing, storage, and networking equipment with redundant power, cooling, and connectivity infrastructure designed for continuous operation, typically maintaining availability above 99.99% through N+1 or 2N redundant systems. These facilities serve as the physical backbone for cloud computing, enterprise IT, and digital service delivery across industries. Colocation services command the largest revenue pool in Shanghai, though edge computing deployments are accelerating fastest as latency-sensitive applications proliferate. Managed services capture disproportionate margins due to operational complexity and staffing scarcity. Hybrid solutions are gaining traction among enterprises navigating data sovereignty requirements.
MIIT enforces GB standards for data center power usage effectiveness, while Shanghai municipal authorities impose local energy consumption quotas that restrict expansion in core districts. The country's dual carbon goals are forcing operators to secure renewable power purchase agreements or face permit denials. Stakeholders must monitor regulatory tightening on water usage for cooling, as Yangtze River basin conservation policies threaten conventional evaporative systems.
Market Dynamics
MIIT's GB standards for power usage effectiveness are compressing facility designs across Shanghai, forcing operators to abandon conventional air-cooled architectures before their depreciation cycles complete. The Pudong New Area absorbs the majority of new capacity as fiber density and municipal energy quotas align.
Growth Catalysts
- Dual carbon goals:National decarbonization mandates are accelerating renewable power purchase agreements, with Shanghai municipal authorities denying permits to facilities lacking verified green energy sourcing.
- Financial services expansion:Securities firms and payment processors are multiplying colocation footprints to host latency-sensitive trading infrastructure and AI-driven risk analytics clusters.
- Lingang cluster concentration:Captive land banks in this Pudong sub-district enable hyperscale campus development with direct submarine cable landing access.
Market Restraints
- Input cost volatility:Copper and silicon carbide pricing swings for electrical infrastructure compress margins on fixed-price colocation contracts.
- Supply concentration risk:Domestic cooling equipment vendors dominate precision HVAC procurement, creating single-source dependency for liquid cooling retrofits.
- Technical limitation:Legacy raised-floor designs in older Songjiang facilities cannot accommodate immersion cooling tank loads without structural reinforcement.
Strategic Opportunities
- Jiading district expansion:Industrial zone rezoning permits larger contiguous land parcels than core Pudong, enabling campus-style development with on-site substations.
- Edge computing convergence:5G base station co-location with micro data centers is creating distributed processing nodes for autonomous vehicle telemetry.
- Water conservation mandates:Yangtze River basin policies are accelerating adoption of closed-loop cooling systems that eliminate evaporative water loss.
Industry Challenges
- Specialized technician scarcity:Liquid cooling system commissioning requires certified thermal engineers whose training pipelines lag facility construction timelines.
- Legacy integration friction:Hybrid cloud architectures demand seamless interconnection between on-premise enterprise racks and public cloud regions, complicating cross-connect provisioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shanghai Data Center Market |
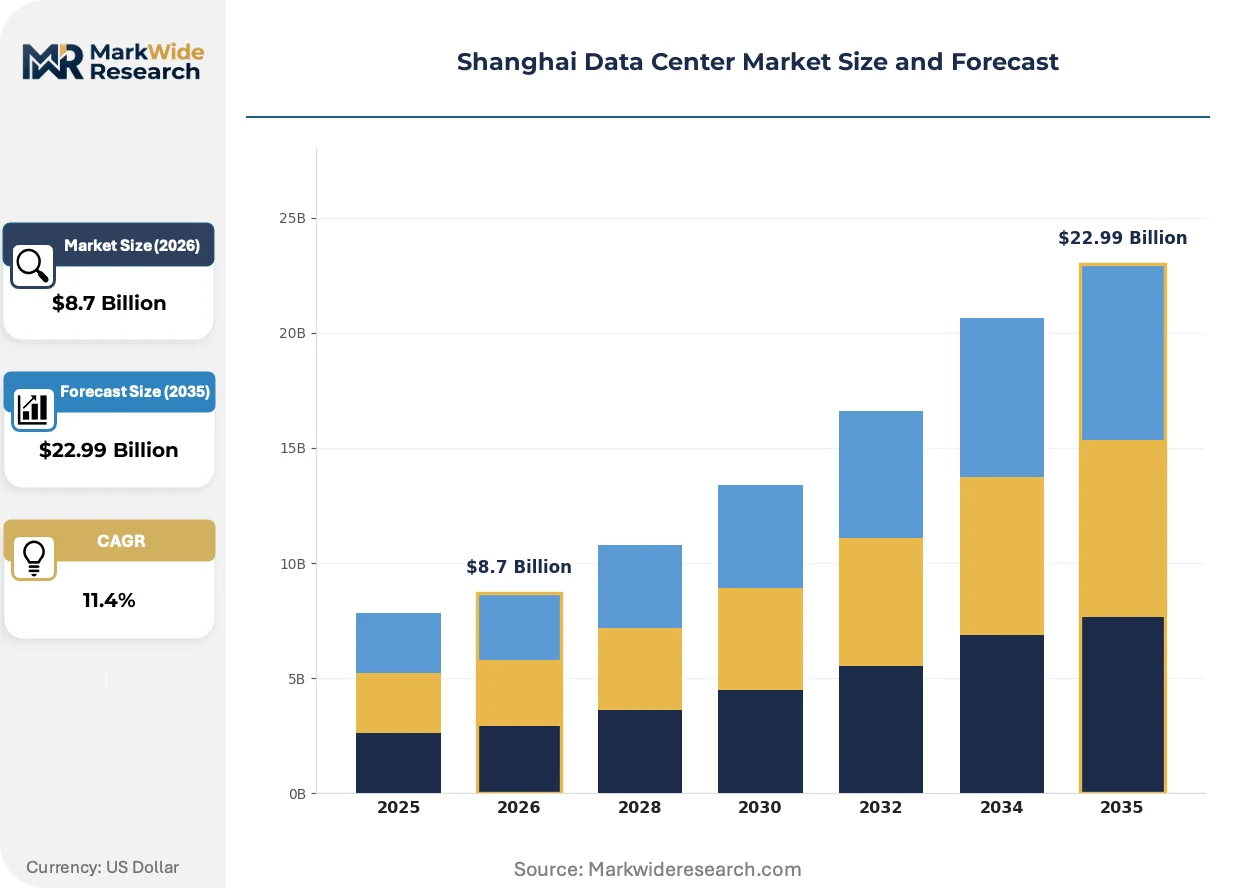
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Hybrid Solutions Deployment Model: On-Premises, Off-Premises, Hybrid, Edge Computing End User: Enterprises, SMEs, Government, Internet Service Providers Power Rating: High Density, Mid Density, Low Density, Others |
| Companies Covered | China Telecom Corporation Ltd, Equinix, GDS Holdings Limited, NTT Ltd, KDDI Telehouse, Princeton Digital Group, UCloud, VNET Group Inc., WinTriX DC Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shanghai Data Center Market Trends and Innovations
Liquid cooling architectures are displacing conventional designs as thermal densities from GPU clusters exceed 50kW per rack. Regulatory pressure on energy efficiency is accelerating equipment refresh cycles beyond historical depreciation schedules.
Immersion cooling is expanding into hyperscale facilities as the primary thermal management approach for AI training infrastructure. Cloud operators and colocation providers are retrofitting existing white space to accommodate dielectric fluid tanks. This shift is expanding into the premium colocation segment, compressing demand for traditional chilled-water CRAH units.
MIIT's GB 40879 standard enforcement is mandating real-time power monitoring and annual PUE disclosure for facilities exceeding defined capacity thresholds. Non-compliant operators face permit suspensions and exclusion from government cloud procurement lists. Shanghai-based providers are responding by deploying AI-driven cooling optimization platforms to maintain sub-1.3 PUE ratings.
Consumption patterns among enterprise buyers are fragmenting from monolithic colocation contracts toward modular, term-flexible arrangements. Financial services firms are unbundling managed services from rack space, sourcing operational support through specialized third-party providers. This behavioral shift is most pronounced among hedge funds and quantitative trading shops in Lujiazui requiring rapid capacity scaling.
Shanghai Data Center Market Segmentation
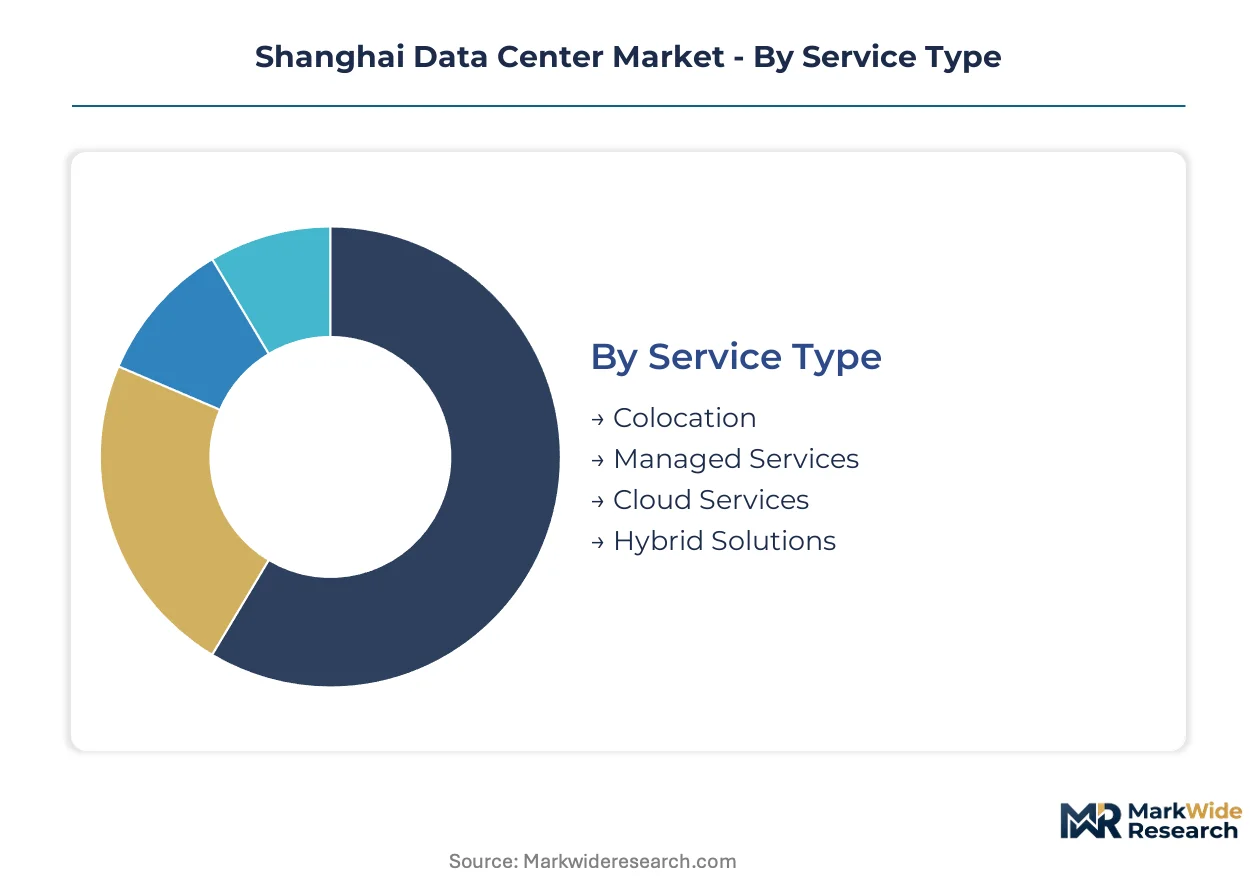
Segmentation in the Shanghai data center market reveals how buyer priorities diverge across service maturity, infrastructure control, and computational intensity. Understanding these fault lines exposes where margin pools concentrate and which technology transitions will reshape competitive positioning over the forecast window.
Service Type:
Buyer procurement decisions in Shanghai increasingly hinge on operational control versus capital efficiency trade-offs, with financial services firms unbundling rack space from managed support.
- Colocation:Physical rack space leasing with redundant power and cooling infrastructure delivered by third-party operators. Securities firms in Lujiazui dominate demand for premium cabinet density to host latency-sensitive trading systems. MIIT's GB 40879 PUE enforcement is compressing supply to facilities achieving sub-1.3 efficiency ratings.
- Managed Services:Operational outsourcing covering remote hands, hardware maintenance, and network monitoring. Hedge funds and quantitative trading shops are sourcing these capabilities through specialized third-party providers rather than bundled colocation contracts, fragmenting vendor relationships.
- Cloud Services:On-demand compute and storage resources delivered through hyperscale operator platforms.
- Hybrid Solutions:Architectures combining on-premise infrastructure with public cloud interconnectivity.
Volume sits with Colocation; growth tilts toward Hybrid Solutions.
Deployment Model:
Facility location decisions are increasingly shaped by municipal energy quota availability and fiber density rather than historical proximity to enterprise headquarters.
- Off-Premises:Third-party facility deployment removing capital burden from enterprise balance sheets. The Pudong New Area absorbs the majority of new capacity as fiber density and municipal energy quotas align, with Lingang cluster concentration enabling direct submarine cable landing access.
- Edge Computing:Distributed micro data centers positioned for sub-10 millisecond latency requirements. 5G base station co-location with these facilities is creating processing nodes for autonomous vehicle telemetry across Shanghai's port and logistics corridors.
- On-Premises:Enterprise-owned and operated facilities within corporate-controlled real estate.
- Hybrid:Split workloads across owned infrastructure and third-party facilities.
Off-Premises commands current capacity absorption; Edge Computing exhibits the steepest expansion trajectory.
End User:
Customer scale determines contract structure flexibility, with large enterprises extracting volume pricing while smaller buyers face minimum commitment floors.
- Enterprises:Large organizations with dedicated IT infrastructure requirements spanning multiple racks or private cages. Financial services expansion is multiplying colocation footprints to host AI-driven risk analytics clusters, with securities firms and payment processors leading procurement.
- Government:State agencies and public sector entities with data sovereignty and security compliance mandates. MIIT permit suspensions and exclusion from government cloud procurement lists threaten non-compliant operators, concentrating demand on verified facilities.
- SMEs:Small and medium enterprises with fractional rack or single-cabinet requirements.
- Internet Service Providers:Telecommunications carriers and content delivery networks requiring interconnection density.
Enterprises anchor revenue concentration; Government procurement is tightening compliance requirements fastest.
Power Rating:
Thermal density specifications are diverging as AI training clusters force infrastructure retrofit decisions ahead of historical depreciation cycles.
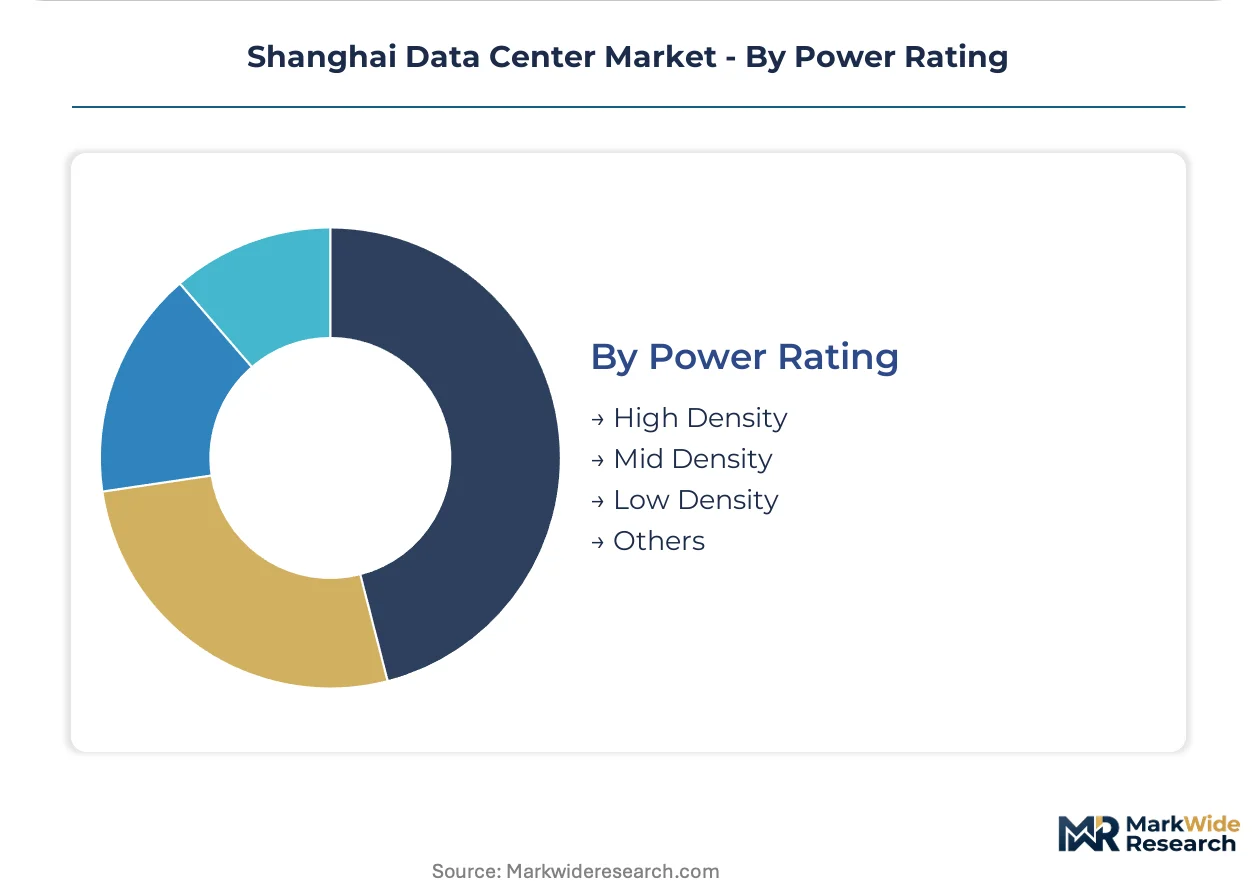
- High Density:Racks exceeding 30kW power draw requiring liquid cooling or immersion architectures. Liquid cooling infrastructure is expanding across Shanghai facilities as thermal loads from GPU clusters render traditional air-cooled designs uneconomical at scale.
- Mid Density:10-30kW rack configurations supporting conventional chilled-water CRAH units.
- Low Density:Sub-10kW legacy deployments in raised-floor configurations.
- Others:Specialized power configurations including modular containerized deployments.
High Density captures premium pricing; Mid Density faces the most acute retrofit pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services and AI compute workloads concentrate capacity expansion in Pudong New Area, where MIIT energy quotas and submarine cable access align. Municipal authorities in Shanghai enforce stricter land-use and power-efficiency standards than provincial peers, redirecting hyperscale development toward Lingang and Jiading industrial zones.
Pudong New Area
Securities firms and payment processors drive colocation demand for latency-sensitive trading infrastructure. MIIT's GB 40879 PUE enforcement denies permits to facilities exceeding 1.3 efficiency thresholds. Lujiazui's fiber density anchors premium cabinet deployments, while Lingang cluster concentration enables direct submarine cable landing access for international connectivity.
Jiading District
Industrial zone rezoning permits larger contiguous land parcels than core Pudong, attracting campus-style development with on-site substations. Shanghai municipal energy consumption quotas restrict expansion in core districts, redirecting operators toward this western periphery. Captive land banks here support hyperscale build velocity that private operators struggle to match in saturated central zones.
Songjiang District
Legacy raised-floor facilities face structural retrofit pressure as AI training clusters exceed 50kW per rack. Yangtze River basin water conservation policies threaten conventional evaporative cooling systems. Older white space cannot accommodate immersion cooling tank loads without reinforcement, accelerating equipment refresh cycles ahead of historical depreciation schedules.
Baoshan District
Port logistics corridors generate edge computing demand for autonomous vehicle telemetry and 5G base station co-location. Shanghai's dual carbon goals force operators to secure renewable power purchase agreements or face permit denials. Industrial heritage sites offer brownfield redevelopment opportunities with existing grid infrastructure.
Shanghai Data Center Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-backed carriers dominating interconnection pricing while independent operators compete on build velocity. The market structures around three tiers: state-owned telecommunications incumbents with captive fiber backbones, hyperscale-focused developers with captive land banks, and international platforms emphasizing cross-border connectivity. Strategic moves concentrate on liquid cooling retrofits ahead of regulatory deadlines and modular capacity expansion to capture fragmented financial services demand.
Within the state-affiliated tier, China Telecom Corporation Ltd anchors interconnection pricing through its fiber backbone dominance. GDS Holdings Limited occupies the premium colocation segment through captive land banks in Lingang and Jiading. VNET Group Inc. exemplifies hyperscale build velocity specialization, sustaining delivery timelines that private operators struggle to match.
| Leading Market Players |
|---|
| China Telecom Corporation Ltd |
| Equinix |
| GDS Holdings Limited |
| NTT Ltd |
| KDDI Telehouse |
| Princeton Digital Group |
| UCloud |
| VNET Group Inc. |
| WinTriX DC Group |
| Others |
Pricing and Supply Chain Analysis
MIIT's GB 40879 power usage effectiveness standard gates both qualified supply and premium-tier pricing access, as Shanghai municipal authorities deny permits to facilities exceeding 1.3 PUE thresholds. This regulatory filtering concentrates certified capacity in Pudong New Area and Jiading District, where compliant operators command pricing premiums over legacy Songjiang facilities facing retrofit pressure.
Pricing Analysis
Volume concentrates in standard colocation contracts while margins accrue to managed services and high-density liquid cooling deployments. Pricing stratifies across premium, standard, and economy tiers based on certification grade and fiber proximity to Lujiazui financial district. Cost compression in legacy air-cooled facilities is intensifying because MIIT enforcement accelerates equipment refresh cycles. Hedge funds and quantitative trading shops in Pudong exhibit least price sensitivity, while SMEs face minimum commitment floors that push them toward economy-tier providers.
Supply Chain Analysis
GB 40879 certification and MIIT permitting gating concentrate qualified equipment supply among domestic vendors with state-backed verification pathways. Precision HVAC and liquid cooling hardware draws from China, Germany, and USA manufacturing bases. Copper busbar, silicon carbide power electronics, and dielectric cooling fluids anchor raw material dependencies. Single-source vulnerability persists in domestic cooling equipment procurement for immersion cooling retrofits. Distribution runs through direct operator procurement with state-owned carrier interconnection pricing setting reference benchmarks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shanghai's data center market operates as a supply-constrained environment where municipal energy quotas prop pricing power by capping permissible capacity expansion in core districts.
For Market Incumbents: Deploy captive land bank monetization to secure Jiading and Lingang expansion rights ahead of rezoning completion. Consolidate interconnection pricing power through fiber backbone control against hyperscale build velocity threats. Deepen liquid cooling certification pipelines to address specialized technician scarcity threatening commissioning timelines. For New Entrants and Emerging Players: Edge computing convergence with 5G base station co-location offers the most penetrable white space for autonomous vehicle telemetry processing. Target Baoshan District brownfield redevelopment with existing grid infrastructure for distributed micro data center deployment. Pursue modular capacity contracting to capture fragmented financial services demand unbundling rack space from managed services. For Investors and Strategic Acquirers: MIIT permit suspension announcements for non-compliant operators are the leading indicator that certified capacity scarcity will deepen. Long-term viability favors operators with verified renewable power purchase agreements and sub-1.3 PUE ratings. Target acquisition archetypes include Jiading land bank holders with on-site substation permits. Watch Yangtze River basin water conservation policy tightening as the signal for closed-loop cooling technology inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | MIIT GB 40879 compliance secures permit continuity and premium pricing access. |
| Renewable Power Purchase Agreement | Dual carbon goal alignment prevents municipal permit denials in Shanghai. |
| Edge Computing Infrastructure Partnership | 5G base station co-location captures autonomous vehicle telemetry demand. |
| Captive Land Bank Acquisition | Jiading rezoning enables campus-scale development with substation control. |
| Specialized Technician Training Pipeline | Liquid cooling commissioning certification addresses talent scarcity bottleneck. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with data center operators, municipal planning officials, and financial services IT procurement leads. MIIT GB standard documentation, Shanghai municipal energy quota disclosures, and hyperscaler capex announcements provided validation layers. Bottom-up facility capacity tracking and top-down market sizing triangulated volume estimates.
Granularity-level modeling operated at district-zone resolution across Pudong, Jiading, Songjiang, and Baoshan, with service type segmentation by colocation, managed services, cloud, and hybrid architectures. Power rating tiers from low-density legacy to high-density liquid cooling were modeled separately. CAGRs derived from capacity absorption rates against municipal quota constraints. Forecast inputs included submarine cable landing timelines and Yangtze River basin water policy evolution.
Several conditions sit outside the modeled scope, including specific MIIT enforcement timing variations and international connectivity tariff adjustments. Forecasts reflect assumptions regarding dual carbon goal implementation pace and renewable energy grid integration rates. A model refresh is warranted upon material change in Shanghai municipal energy quota allocation methodology.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Ireland Data Center Power Market
Data Center Infrastructure
Denmark Data Center Server Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
Indonesia Data Center Power Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
Russia Data Center Market