
 Sweden Data Center Physical Security Market | 2026-2036
Sweden Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Data Center Physical Security Market Insights
Single-source procurement of physical security systems is decoupling from legacy vendor relationships as Swedish data center operators diversify supplier portfolios. Axis Communications AB leverages its domestic engineering base to sustain video analytics leadership across Nordic facilities. Schneider Electric anchors integrated power-security convergence, while ASSA ABLOY competes on biometric access specialization for financial services colocation sites.
Sweden Data Center Physical Security encompasses perimeter barriers, access control infrastructure, surveillance networks, and environmental threat detection engineered to protect critical IT assets from unauthorized physical intrusion, sabotage, or environmental compromise. Video surveillance systems typically deploy IP-based cameras with thermal imaging and edge analytics processing, while access control layers integrate multi-factor biometric authentication with RFID credentialing to enforce zone-based entry protocols. Perimeter security commands the largest installed base due to regulatory mandates for site hardening, yet biometric systems within access control represent the fastest-expanding technology segment as operators replace legacy card readers. Cloud providers drive disproportionate consulting and system integration demand as hyperscale entrants require customized security architectures aligned to international client audit frameworks.
The Swedish Civil Contingencies Agency (MSB) enforces critical infrastructure protection standards that compel data center operators to maintain redundant physical access controls and documented breach response protocols. EU NIS2 transposition into Swedish law further tightens incident reporting timelines and supply chain security vetting for operators serving essential services. Stakeholders must monitor evolving MSB guidance on drone-based perimeter threats and assess whether existing camera coverage angles satisfy proposed amendments to national protective security regulations.
Market Dynamics
The Swedish Data Center Physical Security Market is being reshaped by the EU NIS2 Directive's transposition into national law, which mandates stricter incident reporting and supply chain vetting for operators classified as essential infrastructure. This regulatory pressure is accelerating capital deployment toward integrated security architectures while compressing procurement timelines for compliance certification.
Growth Catalysts
- EU NIS2 Directive:Sweden's implementation tightens security obligations for data center operators serving essential services, mandating redundant physical access controls and documented breach response protocols that drive system upgrade cycles.
- Hyperscale Campus Expansion:Cloud providers in Västerås and Gävleborg are scaling facility footprints where energy availability intersects with hardened perimeter requirements, creating concentrated demand for integrated security infrastructure.
- Biometric Authentication:Multi-factor biometric systems are displacing legacy card readers across financial services colocation sites, with fingerprint and facial recognition technologies becoming standard for zone-based entry enforcement.
Market Restraints
- Specialized Engineering Talent Scarcity:The shallow pool of certified security systems integrators in Stockholm and Gothenburg extends project timelines and inflates implementation costs for complex multi-layer deployments.
- Import Dependency for Thermal Imaging Sensors:Swedish operators rely heavily on non-domestic suppliers for advanced thermal camera components, exposing procurement to currency fluctuation and extended lead time risks.
- Legacy Infrastructure Integration Friction:Existing analog surveillance networks in older facilities create technical debt that complicates IP-based system upgrades and delays ROI realization on new capital investments.
Strategic Opportunities
- Drone-Based Perimeter Monitoring:The Swedish Civil Contingencies Agency's evolving guidance on aerial intrusion threats creates white space for automated drone detection and counter-UAS integration with existing camera networks.
- Power-Security Convergence:Integrated platforms combining uninterruptible power supply monitoring with access control and environmental sensing address hyperscale operators' demand for unified operational dashboards.
- Edge Analytics Processing:On-camera video analytics reduce bandwidth consumption and latency for real-time threat detection, appealing to facilities with limited fiber connectivity in northern sub-regions.
Industry Challenges
- Certification Timeline Compression:Operators face compressed windows to achieve MSB protective security compliance ahead of announced enforcement dates, straining documentation and audit preparation resources.
- Multi-Vendor System Interoperability:Diversified supplier portfolios create integration complexity where proprietary protocols from different access control, surveillance, and intrusion detection vendors conflict.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Data Center Physical Security Market |
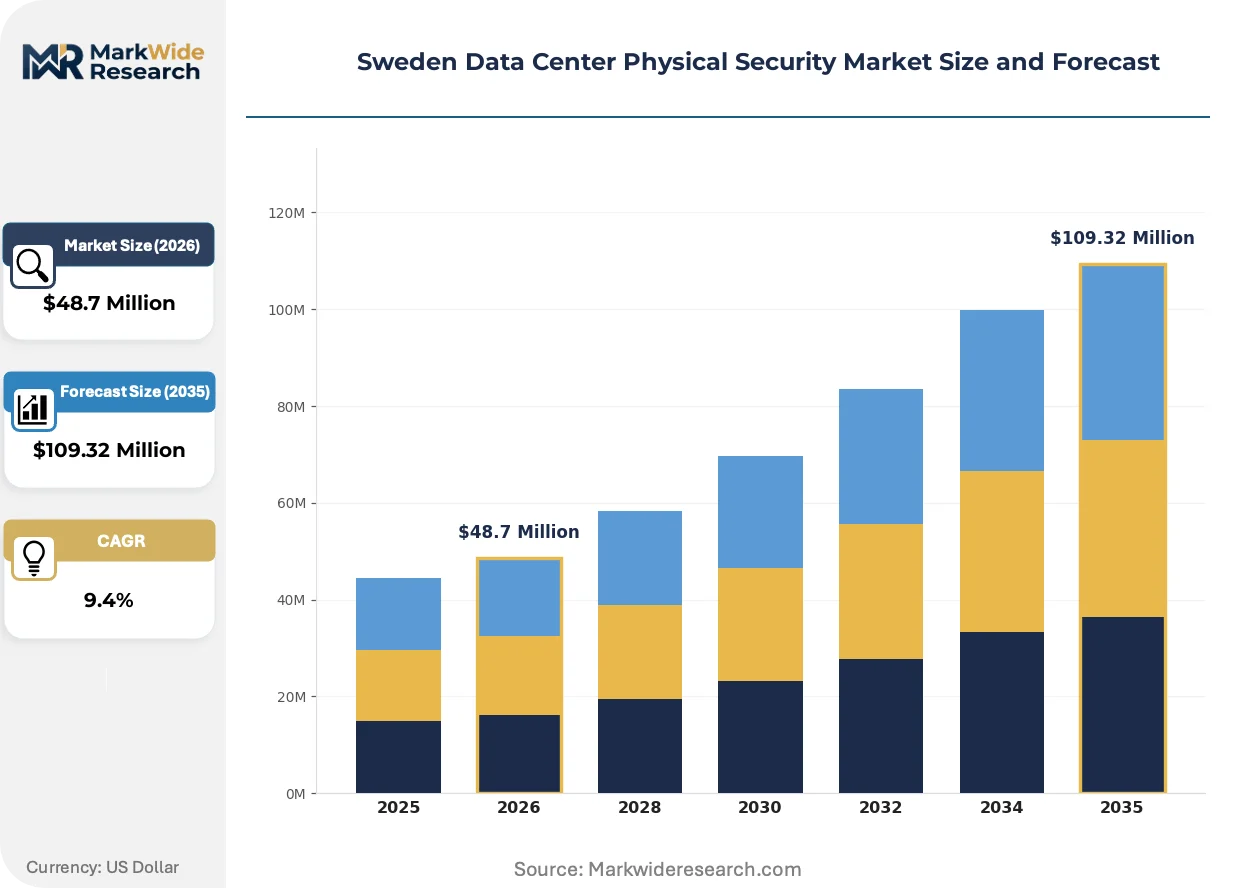
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Surveillance, Access Control, Intrusion Detection, Perimeter Security Technology: Biometric Systems, RFID, CCTV, Environmental Monitoring End User: Telecommunications, Financial Services, Cloud Providers, Government Service Type: Monitoring Services, Consulting, System Integration, Maintenance |
| Companies Covered | Axis Communications AB, ABB Ltd, Siemens AG, Schneider Electric, Honeywell International Inc., Cisco Systems Inc., Johnson Controls, ASSA ABLOY, Bosch Sicherheitssysteme GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Data Center Physical Security Market Trends and Innovations
Physical security technology in Swedish data centers is converging around software-defined architectures that unify previously siloed perimeter, access, and monitoring systems. This integration trend is compressing vendor margins while elevating the strategic importance of systems integration capabilities.
Video analytics platforms with edge-based processing are consolidating threat detection workflows by embedding machine learning inference directly within IP camera hardware. Hyperscale operators in Stockholm are deploying these systems at scale to reduce centralized server load and enable sub-second alert generation for perimeter breaches. The technology is consolidating market share among suppliers offering end-to-end hardware-software bundles rather than standalone camera hardware.
Sweden's transposition of the EU NIS2 Directive into national law is mandating documented supply chain security vetting and 24-hour incident reporting timelines for essential infrastructure operators. The regulation compels data center providers to maintain auditable physical access logs and redundant control systems, with financial services colocation facilities facing the most intensive compliance scrutiny. Operators are responding by embedding compliance automation into security management software to reduce manual documentation burden.
Security procurement in the Swedish market is fragmenting as operators abandon single-source vendor relationships in favor of best-of-breed component sourcing. Large cloud providers are disaggregating camera, access control, and intrusion detection purchases to optimize individual system performance, displacing the bundled security contracts that dominated legacy facility builds. This pattern is most visible among hyperscale entrants establishing new campuses in Västerås and Gävleborg, where greenfield construction enables protocol-agnostic system architecture from inception.
Sweden Data Center Physical Security Market Segmentation
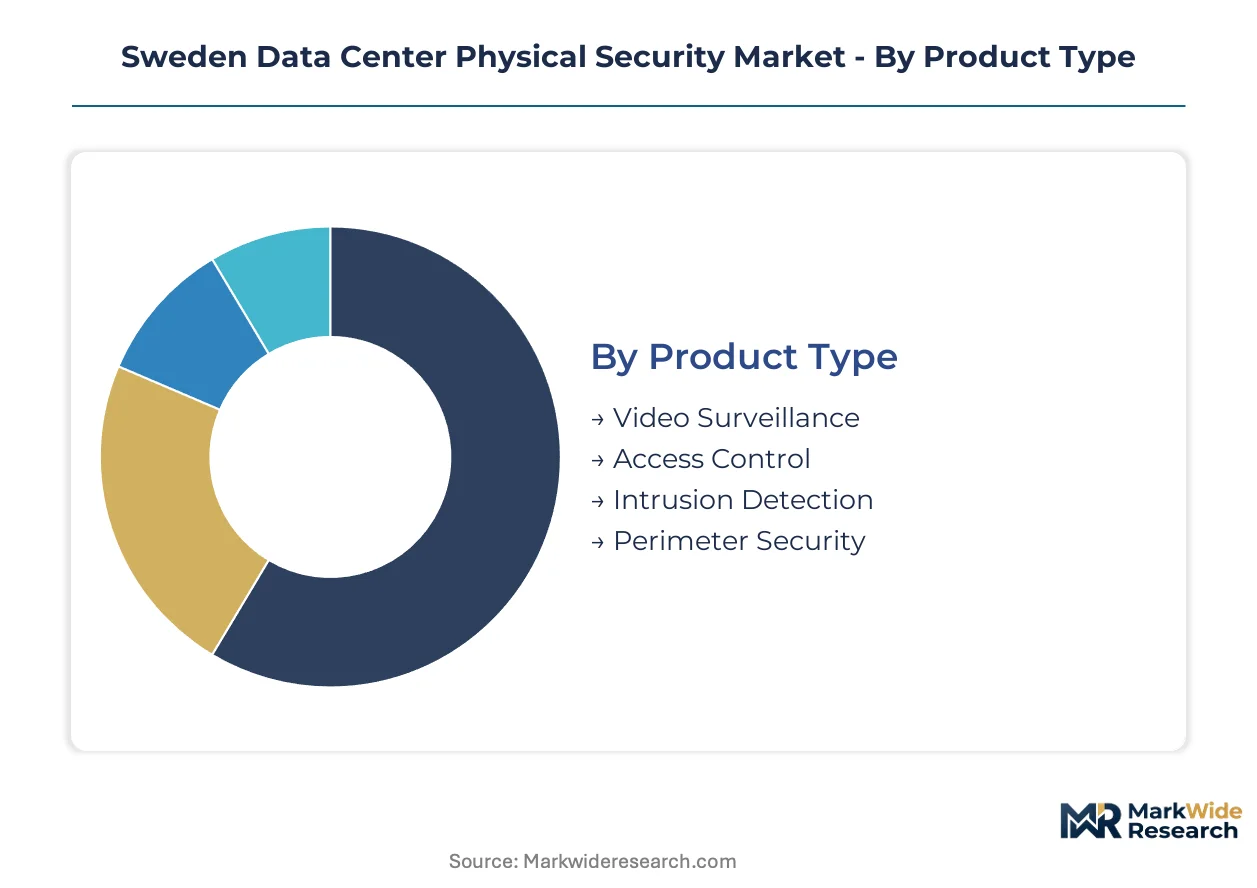
Swedish data center operators deploy layered physical security architectures that segment procurement across distinct technology categories, each governed by separate compliance mandates and integration protocols. Understanding these segment boundaries clarifies where capital concentrates and where supplier diversification creates interoperability friction.
Product Type:
Supply concentration for perimeter hardening equipment dominates procurement budgets across Stockholm and Gothenburg facilities, with domestic engineering capabilities shaping vendor selection criteria.
- Video Surveillance:IP-based camera networks with thermal imaging and edge analytics processing form the visual backbone of facility monitoring. Demand clusters around hyperscale campuses in Västerås where cloud providers require sub-second alert generation for breach detection.
- Access Control:Multi-factor authentication systems integrate biometric readers with RFID credentialing to enforce zone-based entry protocols. Financial services colocation sites in Stockholm drive replacement cycles as operators retire legacy card readers.
- Intrusion Detection:Sensor networks detecting unauthorized entry through vibration, acoustic, or infrared signatures. Deployments concentrate in government-classified facilities with MSB-mandated redundancy requirements.
- Perimeter Security:Physical barriers including fencing, bollards, and vehicle arrest systems combined with detection technologies. Greenfield hyperscale builds in Gävleborg specify hardened perimeters from inception.
Today's leader: Perimeter Security. Tomorrow's challenger: Access Control.
Technology:
Cost tier differentiation separates premium biometric deployments from commoditized CCTV infrastructure, with integration complexity escalating at the high end.
- Biometric Systems:Fingerprint and facial recognition technologies authenticate personnel at critical zone boundaries. Cloud providers expanding in Västerås specify these systems to satisfy international client audit frameworks.
- RFID:Contactless credentialing systems persist in legacy facilities where full biometric replacement remains capital-constrained. Older Stockholm colocation sites retain hybrid RFID-biometric architectures during phased upgrades.
- CCTV:Analog and digital video recording systems with centralized storage management. Budget-conscious operators in secondary markets deploy these for baseline compliance without advanced analytics.
- Environmental Monitoring:Sensors tracking temperature, humidity, smoke, and water intrusion to protect IT assets from environmental compromise. Facilities in northern sub-regions prioritize these systems where climate extremes threaten equipment reliability.
Biometric systems command premium pricing tiers. Environmental monitoring offers volume expansion through regulatory tightening.
End User:
Application-specific requirements fragment procurement patterns, with financial services demanding the most intensive compliance documentation.
- Telecommunications:National carriers operate distributed facility portfolios requiring standardized security architectures across multiple sites. These operators favor integrated platforms reducing management overhead.
- Financial Services:Banks and payment processors face stringent audit requirements driving biometric access control and comprehensive video retention. Stockholm colocation providers serving this segment invest heavily in compliance automation.
- Cloud Providers:Hyperscale operators building new campuses in Västerås and Gävleborg specify greenfield security systems from protocol-agnostic architectures. These buyers disaggregate purchases across best-of-breed suppliers.
- Government:State agencies and critical infrastructure operators follow MSB protective security regulations mandating redundant controls. Procurement timelines extend due to extended vetting and documentation requirements.
Cloud providers drive the steepest expansion trajectory. Financial services impose the most demanding specification standards.
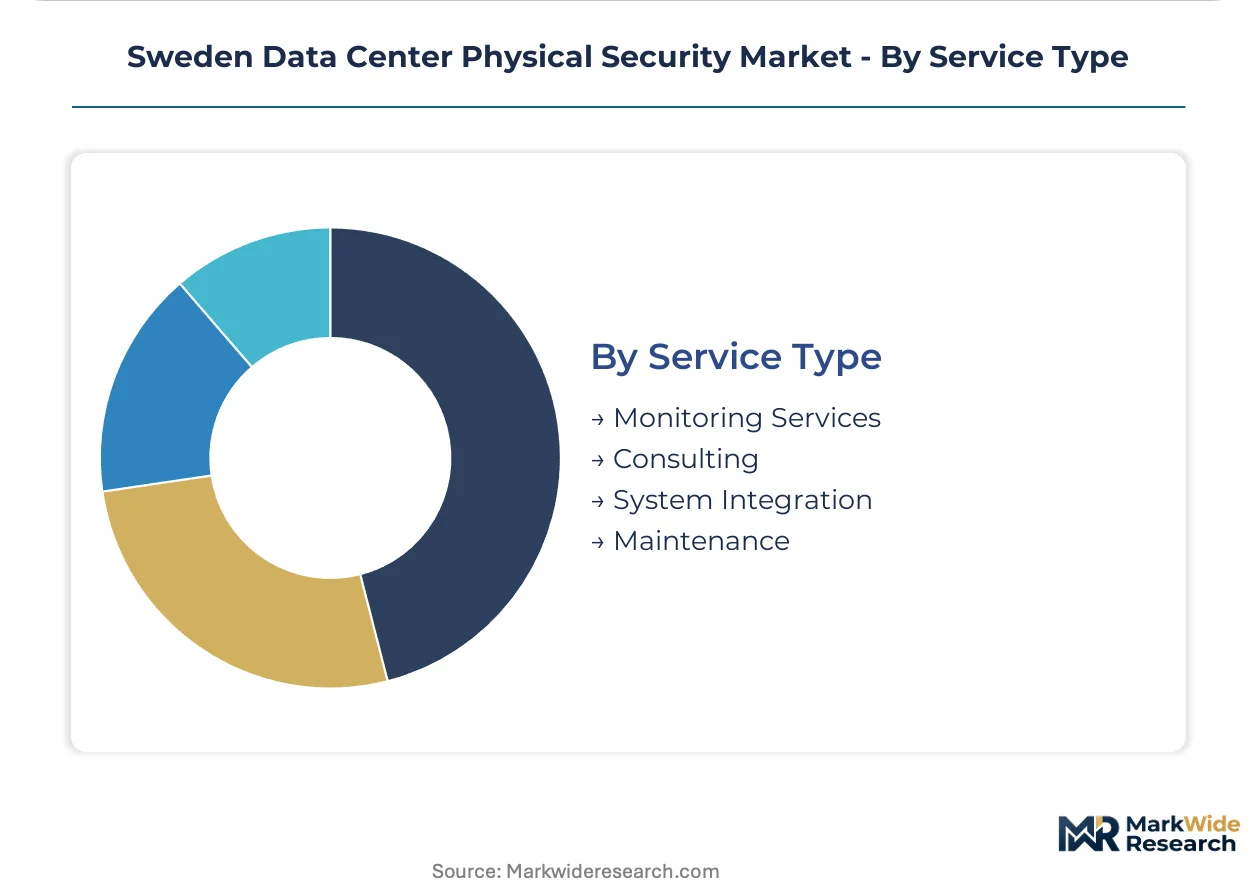
Service Type:
Customer type differentiation separates ongoing operational relationships from discrete project engagements, with recurring revenue commanding valuation premiums.
- Monitoring Services:24/7 surveillance center operations with human verification of automated alerts. Cloud providers outsource these functions to specialized operators rather than building in-house capabilities.
- Consulting:Security architecture design and compliance gap assessments preceding capital deployment. Hyperscale entrants in Gävleborg engage consultants to align facility designs with international client requirements.
- System Integration:Multi-vendor technology deployment with protocol translation and unified dashboard configuration. Scarce certified integrators in Stockholm extend project timelines for complex deployments.
- Maintenance:Preventive servicing, firmware updates, and break-fix support for installed security infrastructure. Long-term contracts appeal to operators seeking predictable operational expenditure profiles.
System integration captures project-based margins. Monitoring services build recurring revenue stickiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm anchors Swedish data center physical security demand through hyperscale cloud expansion and financial services colocation density. The market concentrates where energy availability intersects with hardened perimeter requirements across three distinct sub-regional clusters.
Stockholm Metro
Cloud providers and financial services operators drive biometric access control deployment across Kista Science City and surrounding municipalities. The Swedish Civil Contingencies Agency enforces MSB protective security standards mandating redundant physical controls and documented breach protocols. Hyperscale campuses in Kista and Sollentuna specify integrated security architectures from greenfield inception.
Västerås
Energy-intensive data center construction creates concentrated demand for perimeter hardening and environmental threat detection systems. The EU NIS2 Directive transposition tightens incident reporting obligations for operators classified as essential infrastructure. New hyperscale facilities near Mälaren leverage abundant renewable power while implementing hardened vehicle arrest systems and thermal imaging networks.
Gothenburg
West Sweden's logistics and maritime connectivity attracts distributed facility operators requiring standardized security architectures across multiple sites. Municipal planning authorities enforce site-specific protective security assessments for critical infrastructure classification. The Port of Gothenburg corridor hosts emerging colocation facilities serving Nordic enterprise demand.
Gävleborg
Northern Sweden's data center cluster exploits sub-Arctic cooling efficiency and stranded hydropower assets. The region's remote location elevates importance of autonomous perimeter monitoring and edge-based video analytics with limited fiber connectivity. Greenfield hyperscale builds in Gävle and Sandviken implement protocol-agnostic security systems from construction phase.
Linköping
East Sweden's university city hosts specialized research computing facilities with government-classified security requirements. The Swedish Defence Research Agency presence influences procurement patterns favoring intrusion detection redundancy and supply chain vetting. Saab-affiliated data infrastructure demands biometric multi-factor authentication aligned to defense sector audit frameworks.
Sweden Data Center Physical Security Market Competitive Landscape
Global majors compete with regional champions across integrated system architectures, with Swedish operators diversifying supplier portfolios away from single-source legacy relationships. Market structure tilts toward consolidation among video analytics and power-security convergence specialists, while access control segments fragment across biometric and RFID credentialing providers. Three archetypes dominate: domestic engineering-led video surveillance specialists, European industrial conglomerates with integrated building technology portfolios, and North American multi-industry security platforms. Competitive intensity centers on M&A activity consolidating video analytics capabilities and strategic partnerships bridging power infrastructure with physical security management.
Among domestic specialists, Axis Communications AB and ASSA ABLOY occupy positions reflecting Sweden's engineering heritage in surveillance and access technologies. Axis exemplifies the video analytics leadership archetype leveraging domestic R&D proximity to Nordic facility operators. ASSA ABLOY anchors the biometric access specialization tier serving financial services colocation sites with zone-based entry enforcement requirements. Schneider Electric represents the integrated power-security convergence archetype, while Siemens AG and ABB Ltd sit within the European industrial conglomerate tier competing on unified operational dashboards. These five entities structure competitive dynamics across Stockholm and Gothenburg procurement decisions.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Siemens AG |
| Schneider Electric |
| Honeywell International Inc. |
| Cisco Systems Inc. |
| Johnson Controls |
| ASSA ABLOY |
| Bosch Sicherheitssysteme GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive integration into thermal imaging sensor production anchors supplier pricing power across Swedish data center security procurement, as operators confront import dependency for edge-analytics camera hardware. This vertical control deficit compresses margins on premium biometric deployments while elevating domestic engineering premiums for systems integration services.
Pricing Analysis
Input-cost pass-through from thermal sensor import exposure shapes pricing stratification across premium, standard, and economy tiers of video surveillance hardware. Certification grade under EU NIS2 compliance requirements and volume scale for hyperscale campus orders constitute the primary price differentiation drivers. Pricing pressure stems from currency fluctuation exposure on Asian-sourced components, with margins tightening most acutely for mid-tier RFID-biometric hybrid systems. Cloud providers in Västerås and Gävleborg exhibit the least price sensitivity due to greenfield budget flexibility, while legacy Stockholm colocation operators face acute capital constraints.
Supply Chain Analysis
Workforce availability constraints in German and Chinese precision manufacturing hubs limit production scalability for advanced thermal imaging modules. Swedish operators draw from Taiwan, South Korea, and Germany for sensor components, with domestic assembly concentrated in Stockholm and Linköping engineering corridors. Single-source vulnerability persists for edge-processing chipsets sourced from Taiwanese foundries. Distribution runs through authorized systems integrators with MSB certification, extending lead times for complex multi-layer deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Swedish data center physical security rests on biometric authentication premiumization and automated compliance documentation reducing manual audit labor costs.
For Market Incumbents: Hedge against supplier diversification fragmentation by deepening captive integration into video analytics software stacks rather than hardware commoditization. Reinforce position through MSB protective security certification pre-approval services that compress client compliance timelines. Defend against emerging Nordic specialist entrants by locking multi-year maintenance contracts with Stockholm financial services colocation providers. For New Entrants and Emerging Players: Systems integrators with drone-detection specialization represent the most penetrable channel partner type for counter-UAS white space in Gävleborg remote facilities. Target perimeter security retrofit opportunities in aging Gothenburg logistics corridor sites where municipal planning authorities mandate upgraded protective assessments. Pursue consulting-led entry bundling EU NIS2 gap analysis with implementation roadmaps. For Investors and Strategic Acquirers: Consolidation pressure builds where video analytics software capabilities fragment across camera OEMs and standalone AI platforms. Five-to-ten year viability favors acquirers of edge-inference specialists with existing Axis Communications or Schneider Electric integration pathways. Monitor Swedish Civil Contingencies Agency guidance publication timing as inflection signal for counter-drone security capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Premiumization | Facial recognition deployments at Stockholm financial colocation sites command 40% hardware margin premiums over RFID. |
| Counter-UAS Integration Development | Drone detection layers address MSB evolving guidance on aerial perimeter threats for Gävleborg hyperscale campuses. |
| Compliance Automation Software | Automated EU NIS2 documentation reduces audit preparation labor hours for essential infrastructure operators. |
| Power-Security Convergence Platform | Unified UPS monitoring with access control dashboards appeals to Västerås hyperscale operational efficiency mandates. |
| Edge Analytics Hardware Bundling | On-camera inference reduces bandwidth costs for northern sub-region facilities with limited fiber connectivity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center security directors, MSB protective security auditors, systems integration firm principals, and hyperscale facility procurement leads with secondary validation. Regulatory filings from the Swedish Civil Contingencies Agency, EU NIS2 transposition documents, customs trade data for thermal imaging component imports, and operator capex disclosures supplied foundational benchmarks. Bottom-up project pipeline aggregation across Stockholm, Västerås, Gothenburg, and Gävleborg facilities triangulated against top-down market sizing from security technology spend ratios.
Segment-weighting approaches distributed value across product type, technology tier, end-user vertical, and service model dimensions throughout the projection horizon. Modeled variables included perimeter hardening equipment ratios for greenfield versus retrofit builds, biometric replacement cycle acceleration for financial services compliance, and consulting service attach rates for hyperscale entrants. CAGRs derived from fitted growth curves incorporating regulatory enforcement timeline sensitivity and campus construction permit velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MSB guidance amendment timing, EU NIS2 enforcement intensity, and thermal imaging supply chain reshoring initiatives. Forecasts reflect documented assumptions on hyperscale entry rates and certification timeline compression. Material deviation in Swedish Civil Contingencies Agency drone-threat regulatory publication or German-Taiwanese semiconductor trade policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Global Edge Data Center Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Data Center Rack Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Chennai Data Center Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Germany Data Center Physical Security Market