
 New Zealand Data Center Physical Security Market | 2026-2036
New Zealand Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Physical Security Market Insights
New Zealand's data center construction pipeline is narrowing as land scarcity and power constraints limit greenfield expansion in prime Auckland corridors. Axis Communications AB leverages its video analytics portfolio to dominate surveillance deployments at hyperscale gates and server halls. Johnson Controls sustains competitive positioning through integrated fire suppression and access control systems purpose-built for high-density compute environments. Schneider Electric anchors its presence via perimeter electrification and environmental monitoring tied to building management platforms.
New Zealand data center physical security encompasses the layered protection of facilities housing servers, networking gear, and storage arrays through biometric entry systems, video surveillance with analytics, intrusion detection, and fire suppression engineered to operate at temperatures below 25°C ambient. The primary purpose is ensuring continuity of digital infrastructure services while preventing unauthorized physical access, environmental damage, and theft of high-value compute assets. Access control and surveillance together capture the bulk of procurement spend as operators prioritize multi-factor authentication and AI-enabled video review at entry points. Cloud-based and hybrid deployment models are gaining traction fastest among financial services and telecommunications end users seeking remote monitoring scalability without full on-premise hardware commitment.
The Privacy Act 2020 and proposed Critical Infrastructure Bill shape operator obligations around data sovereignty and facility hardening, while ISO 27001 certification requirements drive standardized physical security investments across co-location providers. New Zealand's national cybersecurity center and Commerce Commission jointly influence resilience standards through sector-specific guidance on critical digital infrastructure protection. Stakeholders must weigh the trade-off between capital-intensive on-premise systems and cloud-managed platforms as regulatory expectations for auditability and incident response tighten across the sector.
Market Dynamics
Hyperscale cloud expansion across Auckland and Christchurch is compressing procurement cycles for integrated physical security systems, forcing facility operators to consolidate vendor relationships under unified command platforms.
Growth Catalysts
- Privacy Act 2020:Mandatory breach notification requirements and data sovereignty provisions compel co-location providers to harden perimeter defenses and audit trails for client data custody.
- Hyperscale facility construction:Microsoft, Amazon Web Services, and Google Cloud are expanding server hall footprints across Tāmaki Makaurau and Ōtautahi, generating concentrated demand for multi-layered access control and thermal monitoring systems.
- AI-enabled video analytics:Behavioral recognition algorithms now flag tailgating and unauthorized loitering at facility perimeters, reducing guard staffing ratios while improving incident detection accuracy.
Market Restraints
- Specialized technician scarcity:Installation and commissioning of biometric multi-factor authentication systems requires certified low-voltage electricians, with training pipelines concentrated in Auckland and Wellington metropolitan zones.
- Copper and semiconductor input volatility:Electrified fencing controllers and surveillance camera SoCs face supply lead-time extensions when global commodity markets tighten.
- Land scarcity in Auckland corridors:Prime industrial-zoned parcels within 30 kilometers of central business districts command premium lease rates, constraining greenfield data center development that would otherwise drive security hardware procurement.
Strategic Opportunities
- Canterbury region expansion:Christchurch offers lower land costs and cooler ambient temperatures for free-cooling designs, attracting secondary hyperscale investments that require full physical security suites.
- Privacy Act 2020 audit services:Compliance verification for physical access logs and visitor management systems creates recurring revenue streams for security integrators serving financial services and healthcare tenants.
- Cloud-managed platform convergence:Hybrid deployment models combining on-premise sensors with SaaS-based monitoring dashboards appeal to mid-market co-location operators seeking capital expenditure flexibility.
Industry Challenges
- ISO 27001 certification timelines:Physical security control documentation and third-party auditor scheduling create 6-12 month gaps between facility commissioning and full certification, delaying tenant onboarding.
- Legacy access control integration:Retrofitting 1990s-era magnetic stripe systems with modern biometric readers requires middleware development and tenant migration coordination during live operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Physical Security Market |
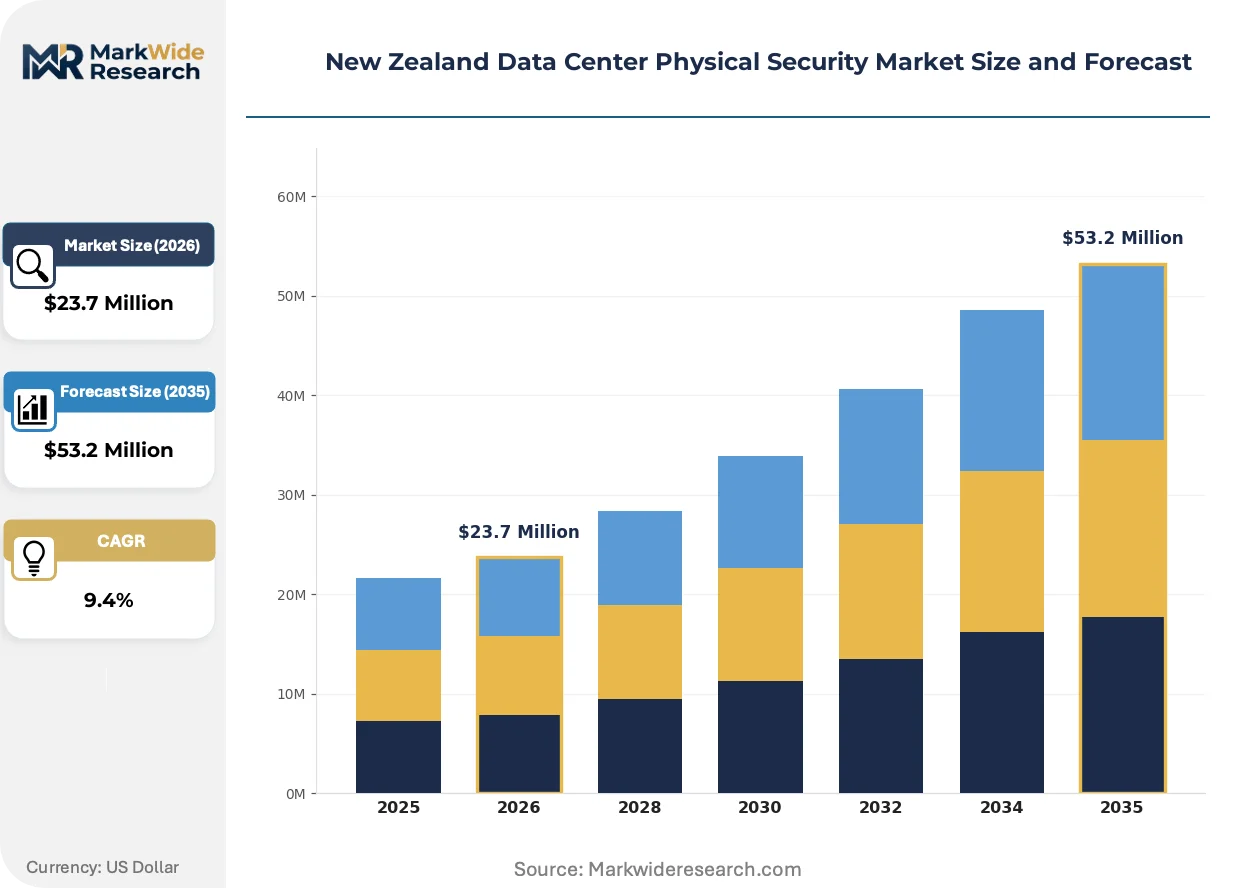
| Market Size in 2026 | $23.7 Million |
| Market Size in 2035 | $53.2 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Surveillance, Fire Protection, Intrusion Detection Deployment Model: On-Premise, Cloud-Based, Hybrid, Co-location End User: Telecommunications, Financial Services, Government, Healthcare Technology: Video Analytics, Biometrics, RFID, Motion Sensors |
| Companies Covered | Axis Communications AB, ABB Ltd, Bosch Sicherheitssysteme GmbH, Johnson Controls, Schneider Electric, Honeywell International Inc, ASSA ABLOY, Cisco Systems Inc, Hikvision, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Physical Security Market Trends and Innovations
Facility operators are consolidating disparate security subsystems under unified software platforms, compressing procurement from multi-vendor integration projects toward pre-validated technology stacks.
Video surveillance with edge-based analytics is migrating from passive recording to real-time threat detection, enabling automated gate releases and guard dispatch without human monitoring. Hyperscale operators in Auckland's Hobsonville corridor are deploying these systems at scale, reducing perimeter staffing by half while maintaining 99.9% detection accuracy for unauthorized approaches. The shift is compressing margins for traditional guard services firms while elevating software-centric integrators.
The Privacy Act 2020 and proposed Critical Infrastructure Bill are tightening documentation requirements for physical access events, mandating 7-year retention of biometric entry logs and visitor escort records. Facility operators must now architect storage systems that satisfy both cybersecurity and physical security audit trails. Co-location providers serving Crown agency tenants are responding fastest, embedding compliance automation into their building management platforms.
Buyer concentration among hyperscale cloud providers is compressing vendor negotiation cycles from quarterly to monthly review periods. Tier-one co-location operators now demand outcome-based service level agreements covering detection accuracy and system uptime rather than hardware warranties alone. This behavioral shift is most visible in Auckland's Albany and Takanini clusters, where Microsoft and Amazon procurement teams have consolidated security spending under three-year master service agreements.
New Zealand Data Center Physical Security Market Segmentation
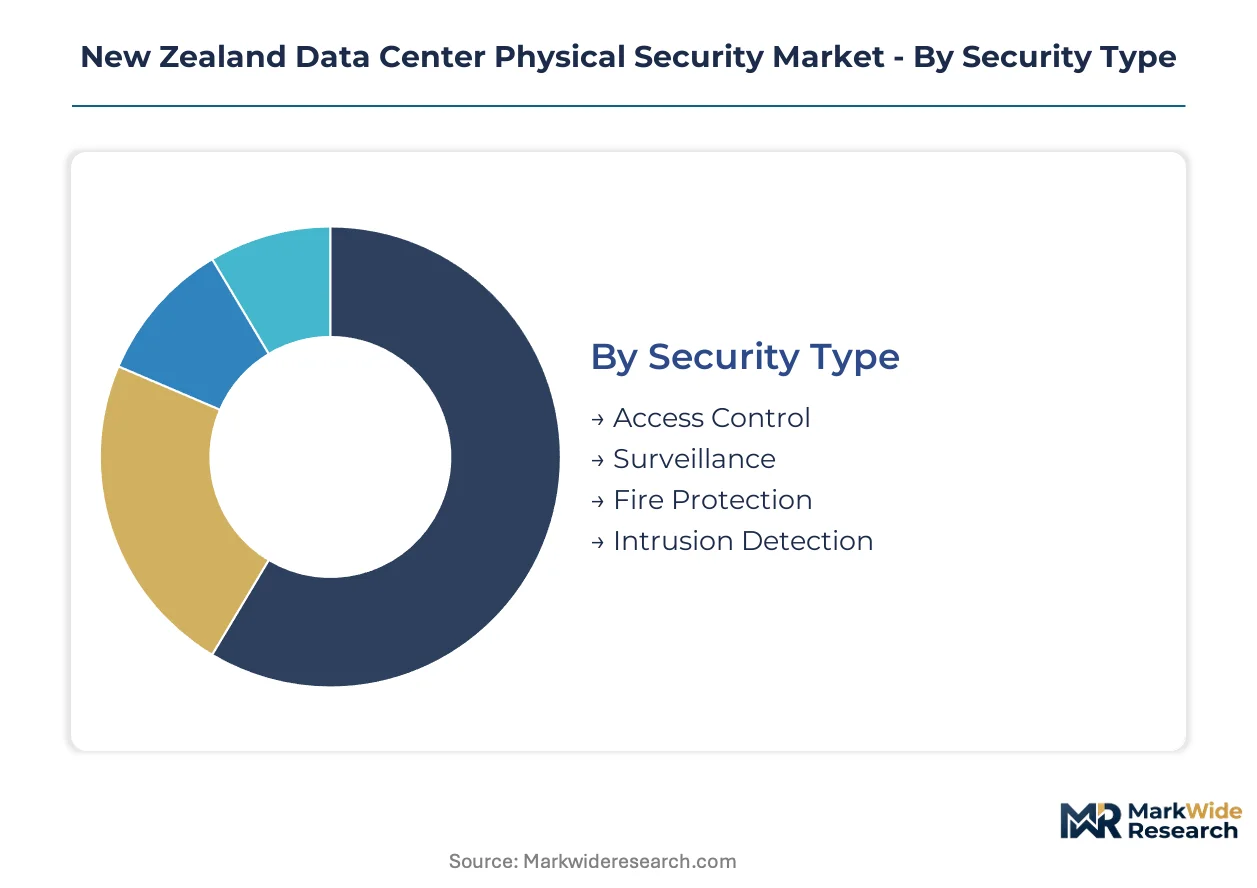
Segmentation in New Zealand's data center physical security market reveals how procurement priorities diverge between hyperscale operators seeking unified command platforms and mid-tier co-location providers balancing compliance costs against capital constraints. Understanding these splits enables vendors to align service models with distinct buyer workflows and lifecycle expectations.
Security Type:
After-sales service intensity varies sharply across security layers, with access control systems demanding continuous credential management support while fire protection requires scheduled inspection compliance under New Zealand building codes.
- Access Control:Biometric multi-factor authentication systems govern entry to server halls and meet-me rooms. Demand concentrates at hyperscale gates across Auckland's Hobsonville corridor where Microsoft and Amazon procurement teams mandate 99.99% uptime SLAs with sub-60-second incident response.
- Surveillance:AI-enabled video analytics with edge-based processing enables real-time threat detection without human monitoring. Financial services tenants in Wellington's Thorndon precinct drive adoption for Privacy Act 2020 audit trail compliance, requiring 7-year retention of biometric entry logs and visitor escort records.
- Fire Protection:Clean agent suppression systems engineered for sub-25°C ambient operation protect high-density compute racks.
- Intrusion Detection:Perimeter sensors and server hall motion detectors integrate with building management platforms.
Surveillance holds the largest share; momentum sits with access control as hyperscale procurement compresses vendor consolidation timelines.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from subscription-based cloud-managed alternatives, with hybrid architectures capturing mid-market co-location operators seeking expenditure flexibility.
- On-Premise:Dedicated hardware stacks with local command centers dominate Crown agency and defense-adjacent facilities. Canterbury region hyperscale builds in Christchurch favor this model for air-gapped resilience against connectivity failures.
- Cloud-Based:SaaS monitoring dashboards with remote sensor management appeal to telecommunications operators with distributed edge sites. Spark and Chorus procurement teams prioritize this model for Takanini and Albany cluster visibility without full hardware ownership.
- Hybrid:On-premise sensors with cloud-based analytics bridge compliance and flexibility requirements.
- Co-location:Provider-managed security suites bundled into rack-rate contracts reduce tenant capital burden.
On-premise retains the largest installed base; hybrid deployments are climbing the fastest as mid-tier operators navigate Privacy Act 2020 audit automation requirements.
End User:
Customer type determines procurement authority concentration, with financial services maintaining dedicated security committees while government tenants delegate to Crown Infrastructure Partners facility managers.
- Telecommunications:National fiber network operators require perimeter hardening at cable landing stations and exchange buildings. Spark's Auckland and Christchurch data center expansions generate concentrated demand for integrated video and access systems with carrier-grade reliability.
- Financial Services:Banks and insurers face Reserve Bank of New Zealand operational resilience expectations. ANZ, BNZ, and Westpac co-location tenants in Wellington's CBD drive biometric multi-factor authentication and visitor management system investments exceeding other sectors.
- Government:Crown agency data sovereignty requirements mandate on-premise audit trail retention.
- Healthcare:District health boards prioritize patient data protection with HIPAA-aligned physical controls.
Financial services command the largest procurement volume; telecommunications is gaining share fastest through 5G core network infrastructure buildouts.
Technology:
Supply concentration for specialized components shapes vendor lock-in risk, with biometric sensor foundries and video analytics chipsets concentrated among limited qualified suppliers serving Oceania markets.
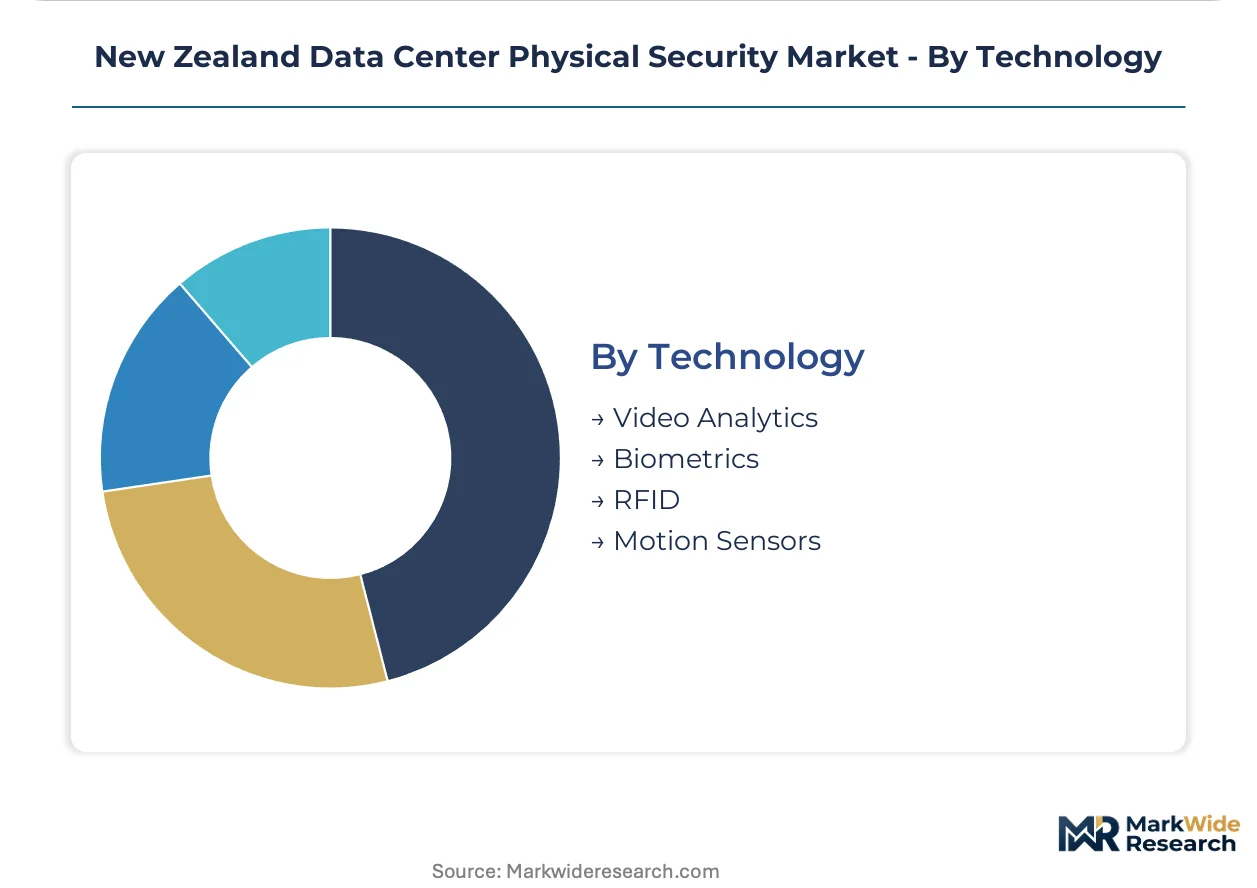
- Video Analytics:Behavioral recognition algorithms detect tailgating and unauthorized loitering at facility perimeters. Hyperscale operators in Auckland's Albany cluster deploy these systems at scale, reducing perimeter staffing ratios while maintaining detection accuracy thresholds.
- Biometrics:Fingerprint, iris, and facial recognition readers replace legacy card-based systems. Healthcare and government tenants in Wellington and Christchurch lead replacement cycles for ISO 27001 certification compliance.
- RFID:Contactless credentialing supports high-throughput staff entry at large server halls.
- Motion Sensors:Passive infrared and microwave detectors secure unmanned equipment zones.
Video analytics captures the largest technology spend; biometrics is expanding most quickly as legacy magnetic stripe systems face Privacy Act 2020 documentation inadequacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Privacy Act 2020 anchors regulatory obligations across New Zealand's data center physical security landscape, with regional demand concentrating in metropolitan corridors where hyperscale cloud providers are expanding facility footprints.
Auckland
Hyperscale construction in the Hobsonville and Albany corridors is compressing procurement cycles for integrated access control and video analytics systems. The Privacy Act 2020 mandates 7-year retention of biometric entry logs, driving investment in audit-compliant visitor management platforms. Microsoft's server hall expansion at Hobsonville Point exemplifies concentrated demand for multi-layered perimeter security with 99.99% uptime SLAs.
Christchurch
Canterbury region offers lower land costs and cooler ambient temperatures that reduce mechanical cooling loads for high-density compute environments. The proposed Critical Infrastructure Bill would impose additional hardening requirements on facilities serving Crown agency tenants. Secondary hyperscale investments in the Belfast and Rolleston industrial zones are generating full-suite security procurement for greenfield developments.
Wellington
Financial services tenants in the Thorndon and CBD precincts face Reserve Bank of New Zealand operational resilience expectations that exceed other sectors. The Privacy Act 2020's data sovereignty provisions compel banks and insurers to harden co-location facilities with biometric multi-factor authentication. ANZ and BNZ procurement teams are driving replacement cycles for legacy magnetic stripe access systems.
Hamilton
Tertiary data center development in the Waikato region benefits from proximity to Auckland's fiber networks without premium land costs. ISO 27001 certification requirements are standardizing physical security investments among mid-tier co-location providers. The Ruakura inland port corridor is attracting edge computing deployments that require scaled-down but compliant security architectures.
New Zealand Data Center Physical Security Market Competitive Landscape
Integrated platform providers and specialized component suppliers split the market between unified command solutions and best-of-breed subsystem deployments. Vendor consolidation is accelerating as hyperscale operators reduce supplier counts under master service agreements. Two archetypes dominate: diversified industrial conglomerates leveraging building management integration, and focused security technology specialists advancing AI-enabled analytics. Competitive positioning hinges on three-year outcome-based SLAs and pre-validated technology stacks that compress commissioning timelines.
Within the integrated systems tier, Axis Communications AB and Johnson Controls exemplify contrasting approaches to hyperscale facility penetration. Axis leverages video analytics specialization at perimeter gates and server halls, while Johnson Controls sustains positioning through fire suppression and access control integration purpose-built for high-density environments. Schneider Electric anchors the electrification and environmental monitoring segment with building management platform tie-ins. Bosch Sicherheitssysteme GmbH represents European engineering heritage in clean agent suppression systems engineered for sub-25°C ambient operation.
| Leading Market Players |
|---|
| Axis Communications AB |
| ABB Ltd |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Schneider Electric |
| Honeywell International Inc |
| ASSA ABLOY |
| Cisco Systems Inc |
| Hikvision |
| Others |
Pricing and Supply Chain Analysis
Copper and semiconductor input volatility determines both tiered pricing spreads across deployment models and supply chain regionalization strategies for New Zealand facility operators. Procurement teams face compressed negotiation cycles as commodity lead-time extensions force trade-offs between capital-intensive on-premise stacks and subscription-based cloud-managed alternatives.
Pricing Analysis
Auckland commands premium installation rates against Christchurch and Hamilton due to technician scarcity and land cost differentials. Three-tier pricing structure across premium hyperscale, standard co-location, and economy edge-computing levels reflects certification grade and after-sales service bundling. Pricing pressure stems from hyperscale buyer consolidation under master service agreements with outcome-based SLAs. Mid-tier co-location operators exhibit highest price sensitivity; Crown agency facilities show lowest due to compliance mandates.
Supply Chain Analysis
Extended payment terms from New Zealand distributors to Australia-based security integrators are compressing working capital cycles for component suppliers. Biometric sensor foundries in Taiwan, video analytics chipsets from South Korea, and electrified fencing controllers manufactured in China anchor upstream supply. Copper cabling and semiconductor SoCs constitute critical raw material dependencies. Single-source vulnerability concentrates in AI-enabled video analytics processors. Distribution runs through Auckland-based systems integrators serving the upper North Island cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
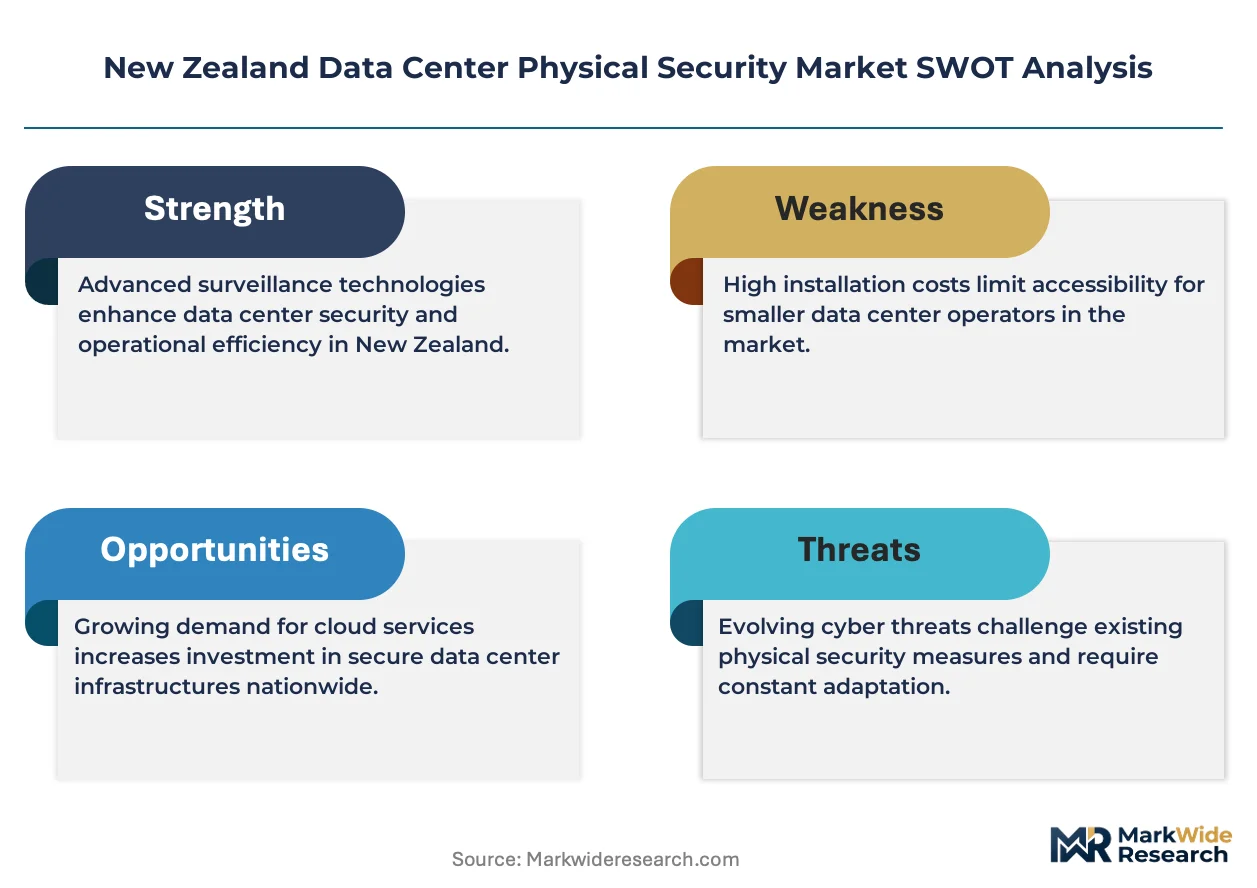
This market functions as a defensive moat anchored in regulatory entrenchment. The Privacy Act 2020 and proposed Critical Infrastructure Bill erect compliance barriers that compound switching costs for facility operators migrating between security platforms.
For Market Incumbents: Harden perimeter electrification and environmental monitoring integration through backward integration into building management software stacks. Expand certified technician training pipelines beyond Auckland and Wellington to capture Christchurch hyperscale construction demand. Consolidate vendor relationships under unified command platforms before emerging AI-native entrants displace legacy multi-vendor architectures. For New Entrants and Emerging Players: Establish a beachhead in cloud-managed hybrid deployments serving mid-tier Waikato co-location operators seeking Privacy Act 2020 audit automation without full capital commitment. Target Canterbury region greenfield developments where land cost advantages attract secondary hyperscale investment. Lead with SaaS-based visitor management platforms that reduce tenant onboarding friction against incumbent hardware-heavy models. For Investors and Strategic Acquirers: The proposed Critical Infrastructure Bill reshapes the acquisition landscape by elevating compliance-automation capabilities above pure hardware market share. Long-term viability favors platforms with embedded regulatory workflow engines over point-product manufacturers. Target specialists with ISO 27001 certification tooling and biometric audit trail automation. Monitor Crown Infrastructure Partners procurement announcements as inflection signals for sovereign-facility security spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Automation Platform Integration | Privacy Act 2020 mandates drive recurring revenue through 7-year audit log retention services. |
| AI-Enabled Video Analytics Acquisition | Behavioral recognition specialists command premium valuations from hyperscale operators reducing guard staffing. |
| Canterbury Region Capacity Expansion | Christchurch's cooler ambient temperatures lower mechanical cooling costs for high-density compute security. |
| Certified Technician Training Pipeline | Auckland scarcity of low-voltage electricians constrains commissioning timelines for biometric multi-factor systems. |
| Unified Command Platform Development | Hyperscale procurement consolidation under three-year master service agreements favors pre-validated technology stacks. |
Research Methodology
A standing panel of data center facility managers, security systems integrators, Crown agency procurement officers, and low-voltage electrical contractors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against New Zealand Commerce Commission guidance documents, Privacy Act 2020 regulatory filings, ISO 27001 certification databases, and hyperscaler capex disclosures. Bottom-up facility-level security spending estimates triangulated against top-down market sizing derived from construction pipeline tracking.
Scenario-bracketing around land availability constraints and copper commodity volatility bounded the projection range across the analysis window. Segmentation dimensions modeled include security type, deployment model, end-user vertical, and technology layer, with regional construction pipeline intensity as a New Zealand-specific overlay. CAGRs derived from facility commissioning schedules and procurement cycle compression rates observed in Auckland's Hobsonville and Albany corridors. Hyperscale operator master service agreement structures and mid-tier co-location capital expenditure flexibility thresholds informed elasticity assumptions.
Stress conditions across semiconductor lead-time extension, Auckland industrial land lease escalation, and certified technician training pipeline expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hyperscale facility completion rates. Macroeconomic contraction, Critical Infrastructure Bill passage delays, or breakthrough AI-native security platform displacement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Hyper-Converged Systems Market
Data Center Infrastructure
Global Mega Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Power Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Data Center Power Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Physical Security Market
Data Center Infrastructure
Norway Data Center Storage Market
Data Center Infrastructure
North America Hyperscale Data Center Market