
 Low-Cost Energy Data Center Market | 2026-2036
Low-Cost Energy Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Cost Energy Data Center Market Analysis
Wholesale power purchasing agreements for data center campuses is narrowing as renewable energy developers and facility operators forge direct contractual relationships. Microsoft leverages long-term offtake structures to lock in wind and solar supply for its expanding server farm network. Google sustains a competitive edge through in-house carbon-free energy matching protocols that govern its data center siting decisions across multiple continents.
Low-cost energy data centers are facilities engineered to minimize operational expenditure through high-efficiency power usage effectiveness ratios, typically targeting PUE values below 1.2 via advanced cooling architectures and on-site renewable generation. These installations serve cloud computing, artificial intelligence training, and enterprise colocation workloads where electricity constitutes the dominant cost line item. Containerized solutions lead deployment velocity for hyperscale entrants seeking rapid capacity scaling without permanent construction commitments. Liquid cooling technology is capturing accelerated investment as thermal densities from GPU-intensive AI clusters exceed the practical limits of conventional air-handling systems.
The EPA enforces Energy Star certification thresholds that shape equipment procurement standards for federal-adjacent data center projects in the United States. EMA and REACH frameworks in Europe govern chemical disclosure and environmental impact assessments for cooling fluids and battery storage components deployed at facility scale. Stakeholders must monitor how evolving carbon border adjustments and locality-specific renewable portfolio standards reshape total cost of ownership calculations for new data center developments.
Market Dynamics
Direct renewable power procurement is compressing wholesale electricity spreads for hyperscale data center operators, forcing facility developers to secure long-term offtake agreements before breaking ground or face stranded capacity risk.
Growth Catalysts
- EU Green Deal carbon neutrality mandates:European operators must match 100% of facility consumption with renewable sources by 2030, accelerating clean energy infrastructure deployment.
- Liquid immersion cooling systems:These architectures handle GPU thermal densities exceeding 50kW per rack that conventional air-handling cannot address.
- India PLI scheme incentives:State-level data center policies in Maharashtra and Telangana attract hyperscale investment through land allocation and power tariff concessions.
Market Restraints
- Grid interconnection queues:Transmission upgrade timelines in Texas and Virginia extend 18-36 months, delaying facility energization.
- Fluorinated gas supply concentration:Three chemical conglomerates control 80% of dielectric fluid production for two-phase immersion cooling.
- EPA Energy Star certification thresholds:Federal-adjacent projects face equipment procurement restrictions that limit vendor flexibility.
Strategic Opportunities
- Telangana and Karnataka state corridors:Underserved Indian markets offer land and renewable energy cost arbitrage versus saturated Mumbai-Delhi axes.
- Waste heat recovery integration:District heating networks in Nordic cities create dual-revenue streams from server thermal output.
- CE marking and CSRD alignment:Early compliance with European sustainability disclosure rules opens preferential procurement channels with carbon-conscious enterprise buyers.
Industry Challenges
- Electrical trades specialization:High-voltage DC distribution and busbar installation expertise remains scarce in secondary US markets.
- Modular container certification:Factory-built units face divergent building code interpretations across German Länder, fragmenting deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Cost Energy Data Center Market |
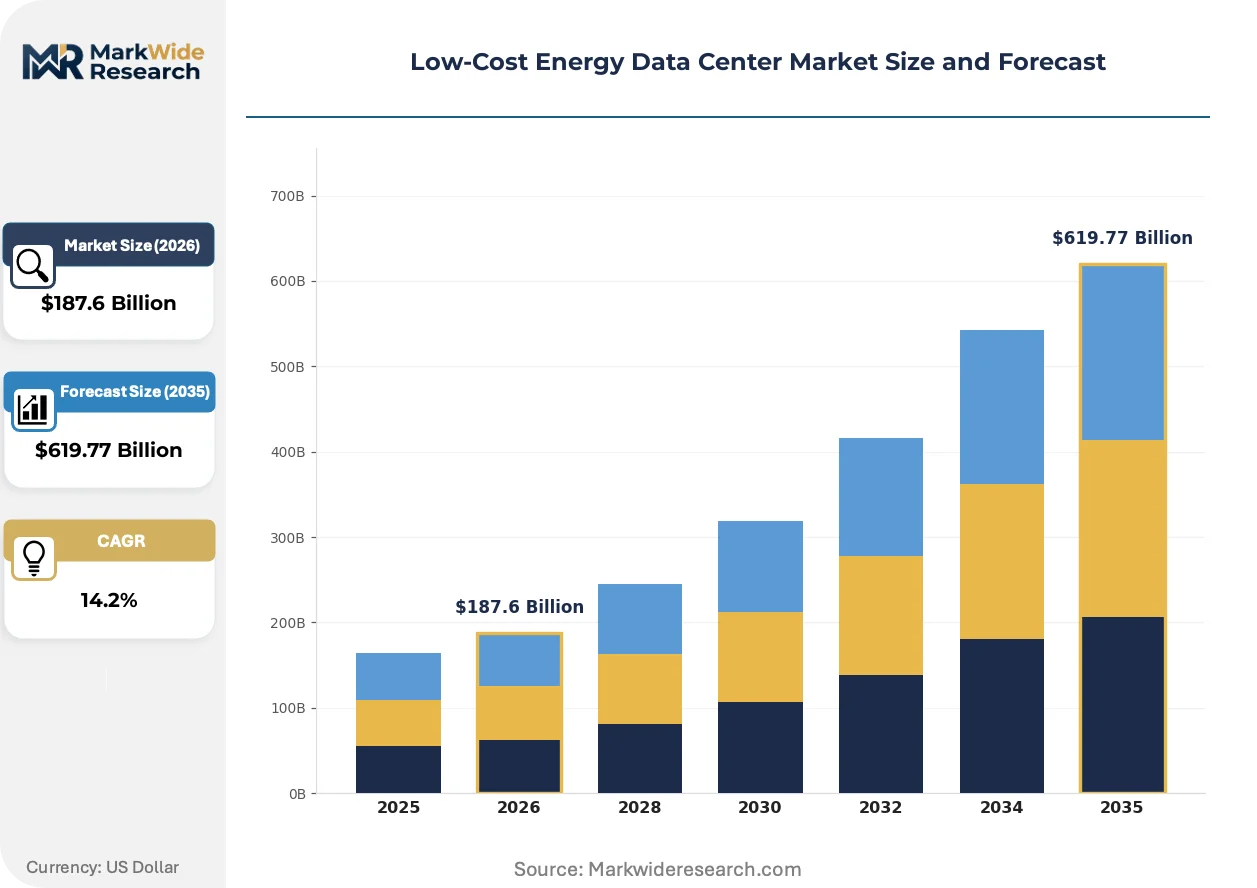
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $619.77 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Containerized Solutions, Micro Data Centers, Edge Systems Technology: Liquid Cooling, Air Cooling, Renewable Energy Sources, Hybrid Systems End User: SMBs, Large Enterprises, Cloud Service Providers, Telecom Operators Installation: On-Premise, Co-location Facilities, Remote Locations, Managed Services |
| Companies Covered | Schneider Electric, ABB, Eaton, Vertiv, Delta Electronics, Equinix, Microsoft, Google, Amazon Web Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Cost Energy Data Center Market Emerging Trajectories
Cooling technology divergence and renewable procurement sophistication are bifurcating the competitive landscape between legacy air-cooled facilities and next-generation liquid-cooled campuses designed for AI training clusters.
Single-phase liquid immersion cooling is rendering obsolete raised-floor air-handling architectures in high-density compute zones. Hyperscale operators deploying NVIDIA H100 clusters are specifying direct-to-chip and tank-based immersion as baseline requirements. Conventional precision air conditioning vendors face margin compression as thermal design power thresholds render their equipment economically uncompetitive for new AI-optimized builds.
REACH chemical disclosure frameworks are forcing cooling fluid reformulation across European installations. Manufacturers must submit comprehensive toxicity dossiers for synthetic dielectric fluids before facility deployment authorization. German and Dutch operators are accelerating adoption of natural ester-based alternatives to preempt regulatory friction under evolving ECHA substance evaluation protocols.
Power purchase agreement structures are unbundling from traditional utility intermediaries. Large cloud buyers negotiate directly with offshore wind and solar developers for 15-20 year offtake contracts with physical delivery requirements. This pattern concentrates most visibly in Denmark and the Netherlands, where submarine cable projects enable direct renewable matching without grid-level energy attribute certificate trading.
Low-Cost Energy Data Center Market Segmentation
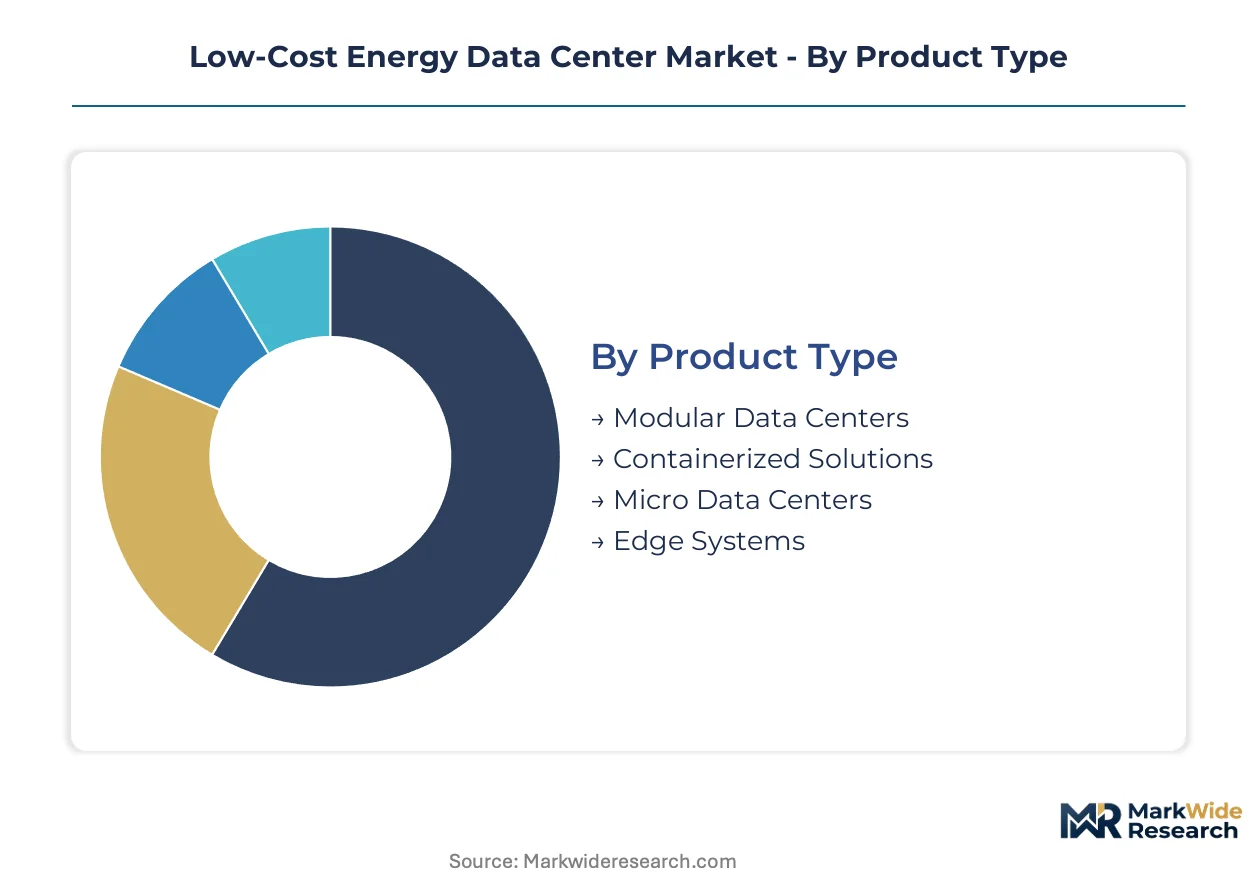
Segmentation reveals how capital deployment cycles vary dramatically across facility types and cooling architectures. Procurement patterns for hyperscale cloud operators differ fundamentally from enterprise colocation buyers in contract duration, technology specification, and geographic flexibility.
Product Type:
Containerized solutions turn over fastest—deployed in 12-18 month cycles—while modular builds stretch across 24-36 month construction timelines. Micro data centers and edge systems occupy intermediate refresh positions tied to 5G rollout velocity.
- Modular Data Centers:Factory-built power and cooling modules integrate on-site with prefabricated structural components. Demand concentrates in Northern Virginia and Frankfurt where hyperscale operators seek rapid capacity scaling without permanent construction commitments. Long-term offtake agreements for renewable power often precede module procurement decisions.
- Containerized Solutions:Standardized 20-foot and 40-foot ISO containers house complete IT infrastructure with integrated cooling and power distribution. Cloud service providers in India and Texas deploy these for temporary capacity surges during GPU cluster ramp-ups. The format eliminates building code delays and enables relocation when power costs shift across markets.
- Micro Data Centers:Self-contained units under 100kW capacity serve retail banking and manufacturing distributed computing needs.
- Edge Systems:Sub-10kW installations position compute within 10 milliseconds of end users for autonomous vehicle and industrial IoT latency requirements.
Modular data centers dominate installed base. Containerized solutions are where expansion concentrates.
Technology:
Cost tier differentiation separates legacy air-cooled facilities from premium liquid-cooled deployments commanding 40-60% higher capital intensity per megawatt.
- Liquid Cooling:Direct-to-chip and immersion architectures handle thermal densities exceeding 50kW per rack that conventional systems cannot address. Hyperscale operators deploying NVIDIA H100 clusters in Denmark and Singapore specify liquid cooling as baseline for new AI-optimized builds. REACH chemical disclosure frameworks in Europe force cooling fluid reformulation toward natural ester-based alternatives.
- Air Cooling:Raised-floor precision air conditioning remains economically viable for legacy enterprise workloads under 15kW per rack density. Secondary US markets and established European facilities continue air-cooled refreshes where GPU clusters are absent. Conventional vendors face margin compression as thermal design power thresholds render their equipment uncompetitive for new AI builds.
- Renewable Energy Sources:On-site solar and wind generation with battery storage reduces grid dependency for facilities in renewable-rich locations.
- Hybrid Systems:Combined grid and on-site generation with intelligent load balancing optimizes cost across variable electricity pricing environments.
Air cooling retains majority installed base. Liquid cooling is climbing the fastest as AI training cluster deployment accelerates.
End User:
Volume concentration follows cloud service providers, though margin profiles favor telecom operators with captive real estate and power infrastructure.
- Cloud Service Providers:Hyperscale buyers negotiate directly with offshore wind and solar developers for 15-20 year offtake contracts with physical delivery requirements. Microsoft and Google sustain competitive positioning through in-house carbon-free energy matching protocols that govern siting decisions across multiple continents. Procurement teams specify liquid cooling and modular formats as standard for new campuses.
- Large Enterprises:Fortune 500 manufacturers and financial institutions pursue hybrid cloud strategies with owned facilities for sensitive workloads. Colocation preferences concentrate in Tier II Indian cities and Nordic markets where renewable power costs compress operational expenditure. Sustainability disclosure requirements under CSRD drive European enterprise buyers toward certified green facilities.
- SMBs:Small and medium businesses rely predominantly on managed services and colocation to avoid capital intensity of facility ownership.
- Telecom Operators:Mobile network operators deploy edge data centers to support 5G core network functions and low-latency consumer services.
Cloud service providers dominate capacity expansion. Large enterprises represent the most price-sensitive procurement segment.
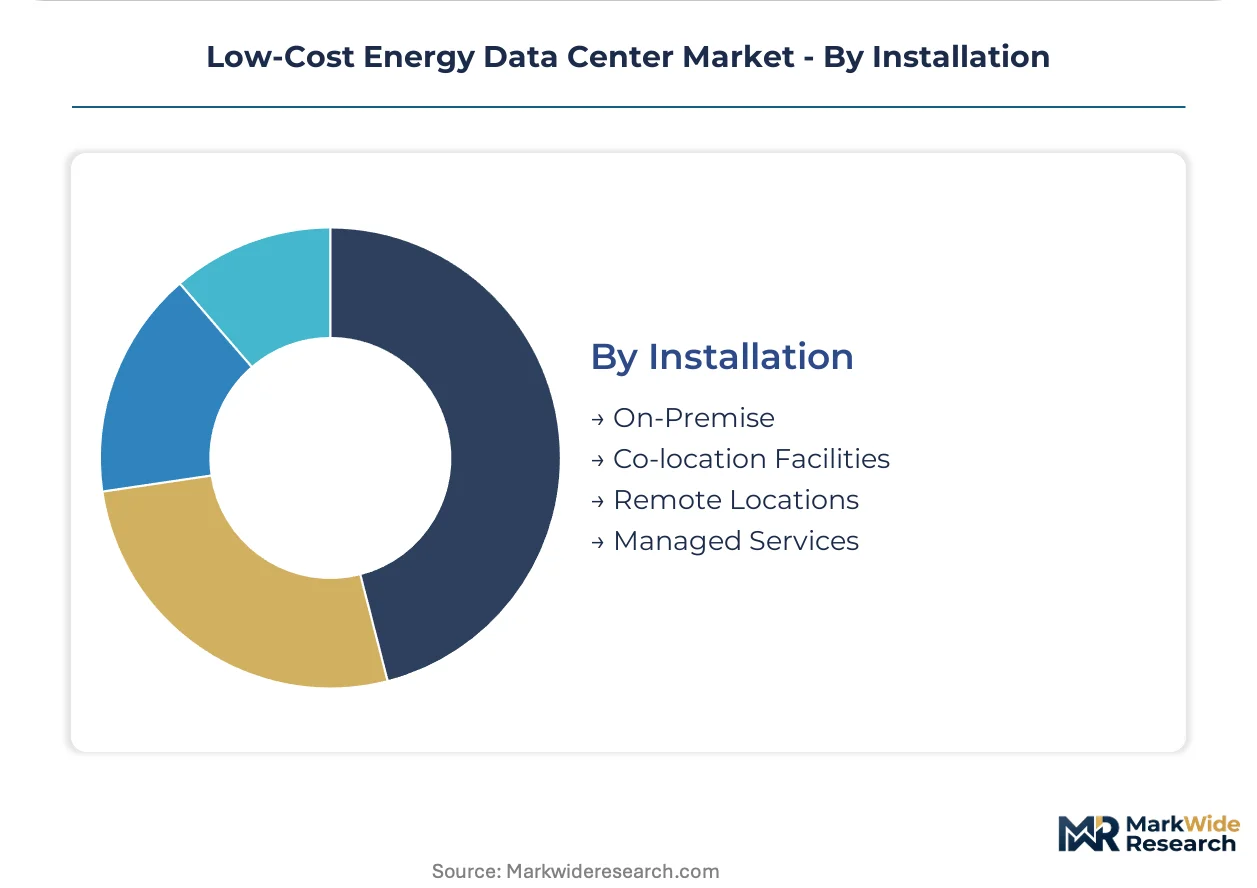
Installation:
Customer type determines installation preference—managed services attract SMBs seeking operational simplicity, while cloud providers favor direct control through on-premise or remote location builds.
- Co-location Facilities:Multi-tenant data centers offer power, cooling, and physical security without capital ownership burdens. Wholesale colocation in Ashburn and Amsterdam attracts hyperscale operators seeking rapid scaling without construction risk. Retail colocation serves enterprise buyers requiring smaller footprints with managed service overlays.
- On-Premise:Owned facilities maintain complete operational control for defense contractors and regulated financial institutions with data sovereignty requirements. US federal-adjacent projects face EPA Energy Star certification thresholds that shape equipment procurement standards and limit vendor flexibility. Capital intensity restricts this format to organizations with balance sheet capacity for 15-20 year asset lifecycles.
- Remote Locations:Desert and arctic deployments exploit natural cooling and stranded renewable power assets outside urban transmission constraints.
- Managed Services:Fully outsourced infrastructure operations transfer staffing and uptime risk to specialized operators for predictable monthly expenditure.
Co-location facilities dominate new capacity activation. On-premise installations retain steady share among regulated industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submarine cable interconnects and cross-border transmission corridors are underwriting geographic concentration in low-cost energy data center deployment. Denmark's Kriegers Flak offshore wind hub and the Netherlands' COBRAcable link enable direct renewable procurement that bypasses wholesale market volatility. India is emerging as a hyperscale destination through state-level power tariff concessions and dedicated data center parks.
United States
Hyperscale cloud operators are concentrating new capacity in Texas and Virginia where stranded renewable assets meet favorable interconnection economics. The EPA enforces Energy Star certification thresholds that shape equipment procurement standards for federal-adjacent projects. Northern Virginia's Loudoun County maintains the densest concentration of commissioned megawatts globally, though grid interconnection queues now extend 18-36 months.
Denmark
Offshore wind capacity exceeding 2.3 GW powers direct corporate renewable procurement at sub-wholesale rates. The country's national energy regulator oversees power purchase agreement frameworks that enable physical delivery without grid-level certificate trading. Copenhagen and Odense host liquid-cooled AI training clusters exploiting district heating integration for dual-revenue thermal recovery.
India
The PLI scheme and state-level data center policies in Maharashtra and Telangana are drawing hyperscale investment through land allocation and power tariff concessions. The Central Electricity Authority governs grid connectivity standards for large-load industrial consumers. Mumbai's Navi Mumbai corridor and Hyderabad's IT clusters represent the primary concentration zones for commissioned and pipeline capacity.
Germany
REACH chemical disclosure frameworks and evolving ECHA substance evaluation protocols are forcing cooling fluid reformulation toward natural ester-based alternatives. The country's federal system produces divergent building code interpretations across Länder, fragmenting modular container certification timelines. Frankfurt's Rhine-Main region remains the continental hub, though energy costs are pushing new development toward Nordic markets.
Singapore
Moratorium lifting on new data center permits is releasing pent-up demand from financial services and cloud operators. The country's national environmental agency imposes strict power usage effectiveness thresholds as a condition of operating license renewal. Tuas and Changi North industrial zones are absorbing the initial wave of post-moratorium capacity with liquid-cooled specifications for tropical operating conditions.
Low-Cost Energy Data Center Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying power distribution and thermal management subsystems. The market structure bifurcates between consolidated electrical infrastructure conglomerates and fragmented cooling technology specialists. Strategic archetypes include integrated facility powerhouses, modular container fabricators, and liquid cooling component innovators. Dominant competitive moves center on long-term renewable offtake partnerships and vertical integration into cooling fluid supply chains.
Within the integrated infrastructure tier, Schneider Electric and ABB exemplify platform-scale capability spanning power distribution, thermal management, and digital monitoring systems. Among hyperscale operators, Microsoft and Google occupy positions defined by proprietary carbon-free energy matching protocols that govern multi-continental siting decisions. These entities represent the demand-side concentration that shapes upstream procurement specifications and technology roadmaps.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Vertiv |
| Delta Electronics |
| Equinix |
| Microsoft |
| Amazon Web Services |
| Others |
Supply Flow & Price Mechanics
Three chemical conglomerates controlling dielectric fluid production for two-phase immersion cooling sit upstream of margin pools concentrated with hyperscale facility operators. Their grip on fluorinated gas supply forces cooling system integrators into long-term offtake negotiations before breaking ground on AI-optimized campuses.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud operators negotiating 15-20 year power purchase agreements from price-sensitive enterprise colocation buyers seeking shorter-term contracts. Price differentiation hinges on renewable energy certification grade and liquid cooling performance tier. Pricing pressure intensifies as stranded renewable assets in Texas and Virginia compress wholesale electricity spreads. Enterprise colocation segments exhibit highest price sensitivity, while AI training cluster deployments show lowest sensitivity due to thermal density requirements.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows constrain GPU cluster deployment velocity for liquid-cooled facilities. Supply concentrates in Taiwan for advanced server components, China for battery storage systems, and Germany for precision cooling hardware. Raw material dependencies span rare earth elements for magnetic bearings, synthetic dielectric fluids for immersion tanks, and high-purity copper for busbar distribution. Single-source vulnerability in fluorinated gas production creates procurement risk. Distribution runs through integrated facility powerhouses and specialized cooling component vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud computing substitution threatens legacy enterprise colocation incumbents as direct renewable procurement and modular deployment erode traditional facility economics.
For Market Incumbents: Build renewable energy matching protocols as a moat against cloud provider vertical integration. Secure long-term offtake agreements for offshore wind and solar before breaking ground on new campuses. Invest in liquid cooling certification under REACH frameworks to preempt regulatory friction from synthetic dielectric fluid restrictions.
For New Entrants and Emerging Players: Telangana and Karnataka state corridors in India offer underpenetrated land and power cost arbitrage versus saturated Mumbai-Delhi axes. Target district heating integration partnerships in Nordic cities for dual-revenue thermal recovery streams. Lead with containerized solutions to bypass fragmented building code interpretations across German Länder.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular container fabricators facing margin compression from liquid cooling transition. Five-to-ten year viability hinges on backward integration into natural ester-based cooling fluid supply chains. Watch for EPA Energy Star threshold revisions as inflection indicators for federal-adjacent procurement restrictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Renewable Power Purchase Agreement | Direct offtake with offshore wind developers in Denmark bypasses wholesale market volatility for hyperscale campuses. |
| Liquid Cooling Technology Licensing | Immersion system patents enable margin capture from NVIDIA H100 cluster specifications in Singapore and Northern Virginia. |
| Backward Integration into Natural Ester Fluids | In-house production of REACH-compliant cooling fluids preempts ECHA substance evaluation protocol disruptions. |
| State-Level Data Center Park Partnership | Maharashtra and Telangana land allocation agreements compress energization timelines for Indian hyperscale entry. |
| District Heating Network Integration | Copenhagen and Odense thermal recovery partnerships create dual-revenue streams from AI training cluster waste heat. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hyperscale facility procurement directors, liquid cooling system engineers, renewable energy project developers, and state-level data center policy officers. Secondary validation drew from EIA power generation data, FERC interconnection queue filings, EU Green Deal implementation trackers, and CEA grid connectivity standards. Bottom-up capacity installation tallies triangulated against top-down renewable procurement disclosure analysis.
Calibration against commissioned megawatt tracking and pipeline project databases anchored volume estimates across the analysis window. Segmentation dimensions spanned facility type, cooling architecture, end-user category, and installation model. CAGRs derived from facility construction cycle velocity and renewable energy cost compression curves. GPU cluster thermal density thresholds and PUE improvement trajectories informed technology adoption pacing.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments and carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on interconnection queue resolution timelines and REACH chemical disclosure evolution. Material shifts in EPA Energy Star certification thresholds or fluorinated gas supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Japan Data Center Construction Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
North America Containerized Data Center Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
Philippines Data Center Power Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
Scientific Data Management System Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
Shanghai Data Center Market
Data Center Infrastructure
Data Terminal Market
Data Center Infrastructure
North America Hosting Infrastructure Services Market