
 Ireland Data Center Rack Market | 2026-2036
Ireland Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Data Center Rack Market Insights
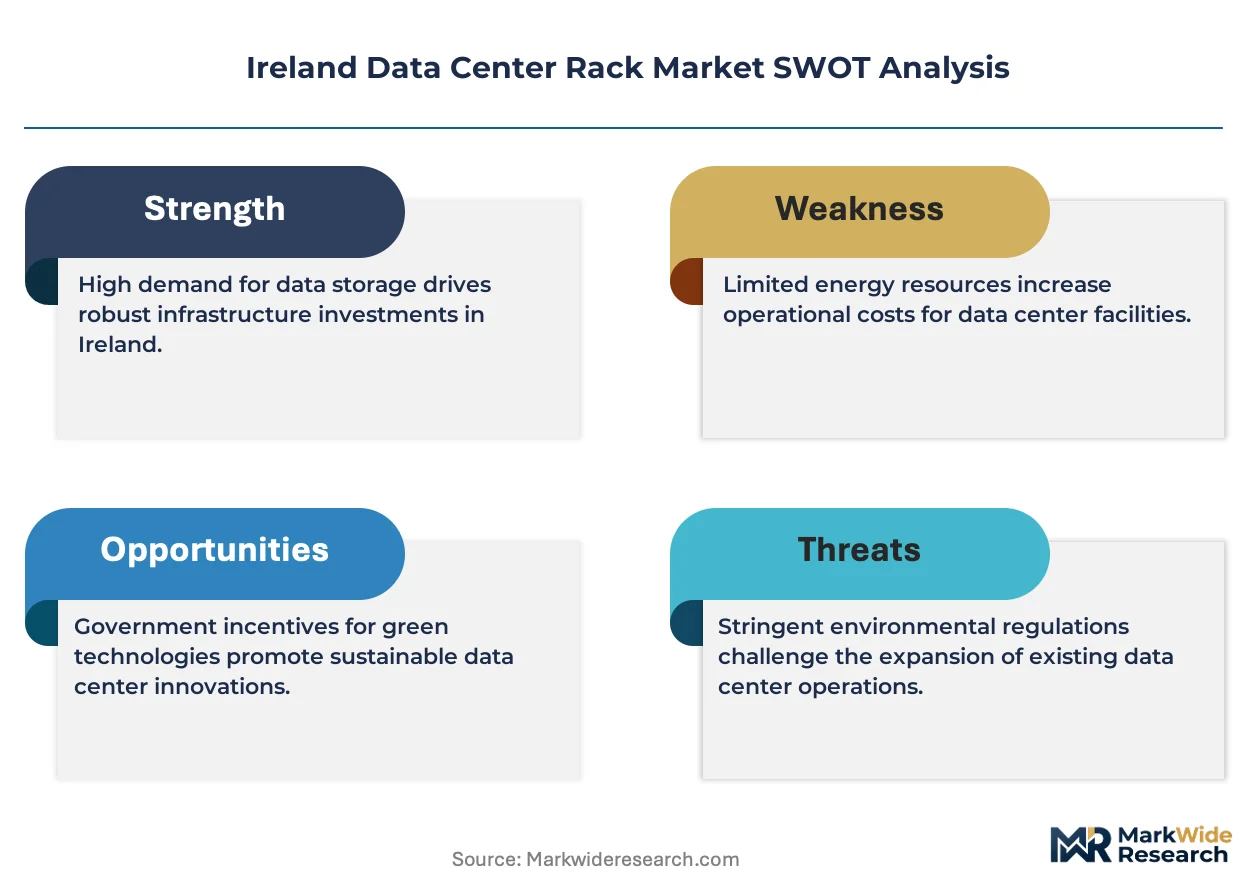
Project finance tied to green bond issuance is fragmenting competitive access in the Ireland data center rack landscape. Schneider Electric SE leverages its integrated power and cooling portfolio to anchor large-scale deployments near Dublin. Eaton Corporation competes through advanced power distribution units embedded within rack architectures. Rittal GMBH & Co.KG specializes in modular enclosure systems that sustain margin pools in enterprise and colocation segments.
A data center rack is a standardized metal frame engineered to mount servers, networking equipment, and power infrastructure, typically conforming to 19-inch EIA width specifications and vertical unit heights measured in rack units. The structure enables organized cable management, thermal regulation, and scalable density in facilities ranging from edge nodes to hyperscale campuses. Enclosed racks and rack cabinets dominate installed value across Irish colocation facilities, where physical security and airflow containment prove critical. Open frame racks represent the fastest-growing configuration among cloud service providers optimizing for rapid equipment swap-out and minimal capital deployment. Liquid cooling mechanisms are displacing legacy air-cooling designs in high-density racks as thermal loads from AI training clusters intensify.
Ireland's national planning framework and the EU Energy Efficiency Directive jointly mandate power usage effectiveness thresholds that filter rack procurement specifications for new facilities. The Commission for Regulation of Utilities enforces grid connection standards that delay or accelerate data center projects depending on regional substation capacity. The EU F-Gas Regulation restricts refrigerant choices in cooling-integrated rack systems, pushing vendors toward alternative thermal architectures. Stakeholders must monitor substation build-out timelines in County Kildare and Cork Harbour to align rack supply commitments with energized facility schedules.
Market Dynamics
Hyperscale cloud deployments are compressing procurement cycles and forcing rack vendors to pre-integrate liquid cooling architectures before grid connection permits finalize. This demand velocity is restructuring supplier qualification timelines across the Greater Dublin Area.
Growth Catalysts
- EU Energy Efficiency Directive:Mandated power usage effectiveness thresholds are filtering procurement specifications toward cooling-integrated rack systems in new Irish facilities.
- AI training clusters:Thermal loads from machine learning infrastructure are accelerating displacement of air-cooled designs by liquid-cooled rack architectures.
- County Kildare substation build-out:Grid capacity expansion is enabling synchronized rack supply commitments with energized hyperscale schedules.
Market Restraints
- Steel and aluminum input volatility:Rack enclosure manufacturing faces margin compression from commodity price swings in structural metals.
- F-Gas Regulation restrictions:The EU framework limits refrigerant choices in cooling-integrated systems, forcing costly thermal architecture redesigns.
- Regional substation capacity:Commission for Regulation of Utilities connection standards create project delays that freeze rack procurement timelines.
Strategic Opportunities
- Cork Harbour expansion:Secondary cluster development outside Dublin offers first-mover positioning for modular enclosure suppliers.
- Green bond project finance:Climate-aligned capital structures are creating procurement preference for vendors with verified circular material credentials.
- Edge node distributed architectures:Latency-sensitive workloads are generating demand for compact rack configurations in regional Irish towns.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design expertise remains concentrated among a narrow specialist pool.
- Legacy air-cooled retrofit complexity:Existing colocation facilities face disruptive downtime risks when upgrading to high-density thermal architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Data Center Rack Market |
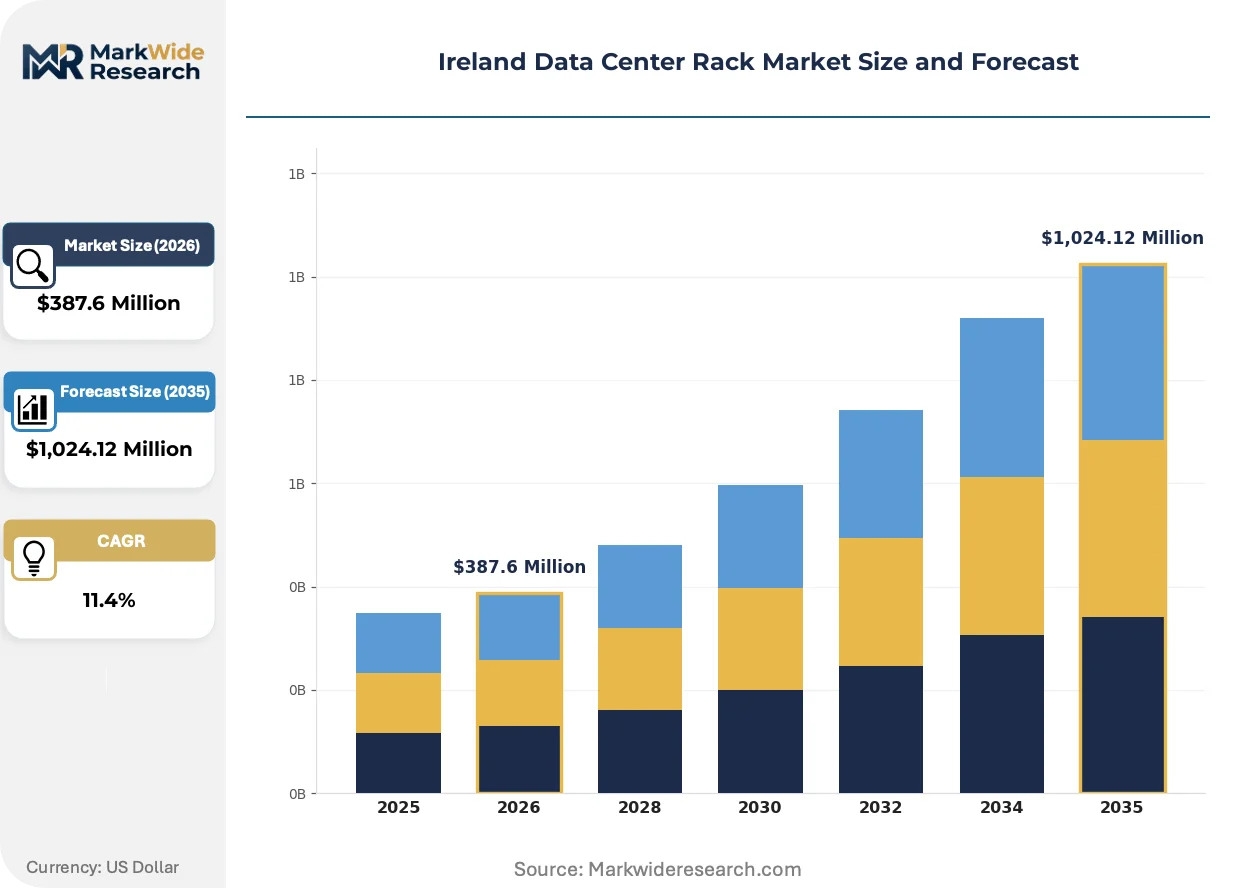
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Racks, Enclosed Racks, Wall-Mount Racks, Rack Cabinets End User: Cloud Service Providers, Colocation Providers, Enterprises, Government Agencies Form Factor: 2U, 4U, 6U, 12U Cooling Mechanism: Air Cooling, Liquid Cooling, Passive Cooling, Hybrid Cooling |
| Companies Covered | Schneider Electric SE, Eaton Corporation, Hewlett Packard Enterprise (HPE), Rittal GMBH & Co.KG, Black Box Corporation, Vertiv Group Corp., Dell Inc., nVent Electric PLC, Econnex Comparison, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Data Center Rack Market Trends and Innovations
Liquid cooling integration is digitizing rack specification workflows and collapsing traditional design-review cycles. Vendors now compete on thermal simulation accuracy rather than enclosure commoditization.
Direct-to-chip liquid cooling is digitizing thermal management precision in high-density deployments. Hyperscale operators in Dublin are specifying factory-integrated coolant distribution units to compress on-site commissioning timelines. This architecture is digitizing rack procurement from discrete component sourcing to system-level performance contracting.
The EU F-Gas Regulation is restricting hydrofluorocarbon refrigerants in cooling-integrated rack systems. Irish facility operators are pivoting toward dielectric fluid immersion and two-phase evaporative designs to maintain thermal performance. Rack vendors serving the Greater Dublin Area are re-engineering product lines to eliminate regulated refrigerants entirely.
Cloud service providers are consolidating rack procurement under multi-year framework agreements with embedded thermal performance guarantees. Colocation operators are responding by unbundling power and cooling infrastructure from space leases. This contracting evolution is most visible among edge facility developers in Cork seeking operational flexibility.
Ireland Data Center Rack Market Segmentation
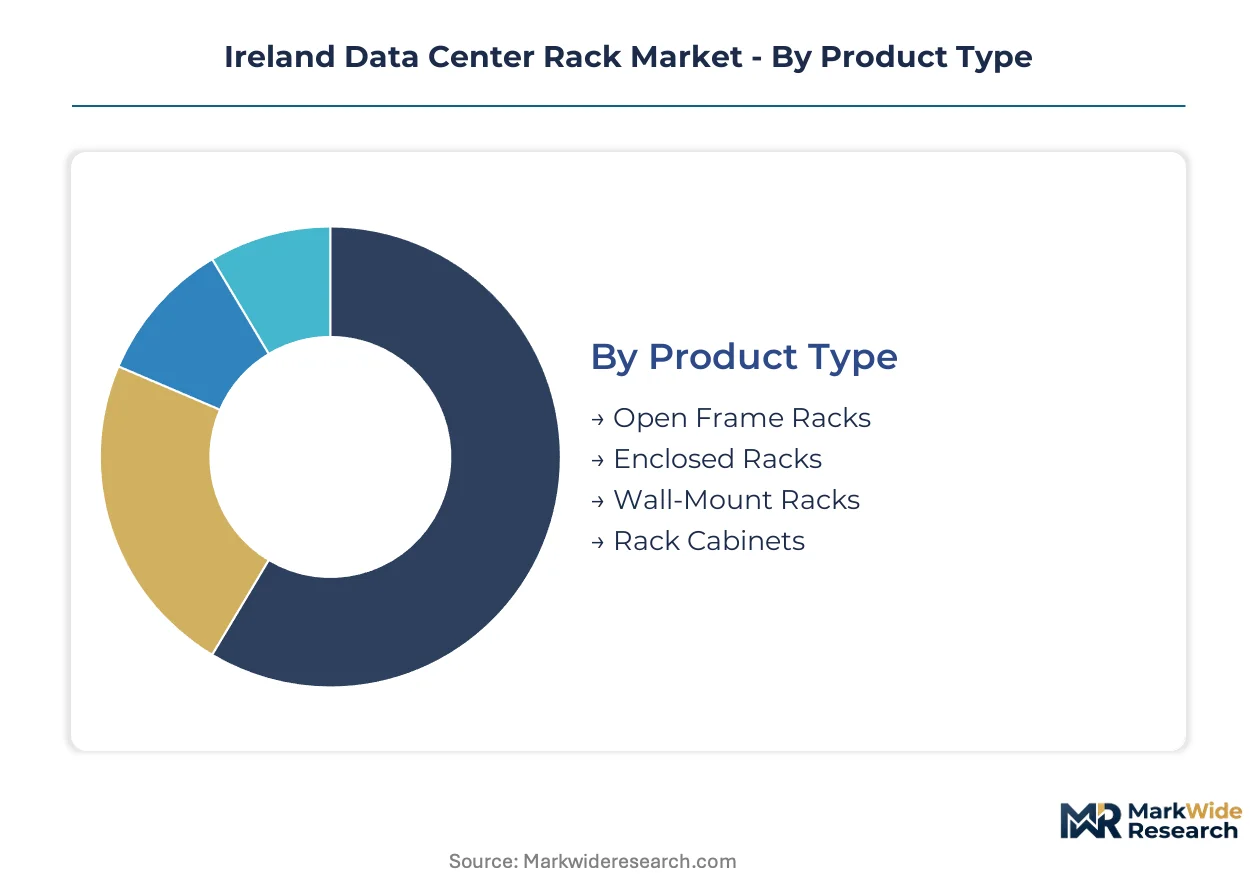
Rack configuration choices in Ireland directly determine thermal compliance trajectories and grid connection feasibility. Procurement patterns across Dublin and Cork clusters reveal divergent priorities between hyperscale velocity and enterprise security requirements.
Product Type:
Mature enclosure formats dominate installed base value while emerging open architectures capture cloud procurement momentum.
- Open Frame Racks:These skeletal steel frameworks expose mounted equipment for unrestricted airflow and tool-free equipment swaps. Amazon Web Services and Microsoft Azure procurement teams across the Greater Dublin Area specify these for rapid deployment cycles where physical security is handled at facility perimeter rather than rack level.
- Enclosed Racks:Lockable metal housings with integrated side panels and front/rear doors protect equipment in multi-tenant colocation environments. Demand concentrates among Equinix and Interxion facilities in Dublin where customer equipment segregation and dust filtration prove critical for SLA compliance.
- Wall-Mount Racks:Compact vertical enclosures secured to structural walls serve edge computing nodes in regional Irish towns with constrained floor space.
- Rack Cabinets:Fully integrated enclosures with factory-installed cable management and power distribution suit enterprise data halls requiring standardized deployment templates.
Enclosed Racks retain volume leadership; Open Frame Racks hold the steepest expansion curve.
End User:
Customer type segmentation tracks capital deployment velocity from hyperscale self-build through managed service intermediaries.
- Cloud Service Providers:Hyperscale operators deploy standardized rack configurations across multi-megawatt campuses. AWS and Microsoft Azure procurement in County Kildare and Cork Harbour drives demand for liquid-cooling-ready frames with pre-integrated busway power feeds.
- Colocation Providers:Multi-tenant facility operators balance flexibility against density optimization. Interxion and Equinix specifications across Dublin prioritize hot-aisle containment compatibility and customer-accessible cable pathways.
- Enterprises:Corporate captive facilities in Cork and Galway favor modular enclosure systems supporting phased capacity expansion without facility reconfiguration.
- Government Agencies:Public sector deployments under Ireland's National Broadband Plan specify security-certified rack systems for edge node installations in regional towns.
Cloud Service Providers retain volume leadership; Government Agencies hold the steepest expansion curve.
Form Factor:
Vertical unit height selection maps directly to power density stratification across Irish facility tiers.
- 2U:Compact two-unit frames accommodate network appliances and storage controllers at the periphery of hyperscale halls. Dublin edge facilities deploy these for switching fabrics where port density outracks server mounting.
- 4U:Mid-height configurations balance equipment accessibility against floor space efficiency. Enterprise customers in Cork colocation suites specify these for mixed server and storage workloads.
- 6U:Intermediate frames support GPU-accelerated nodes in AI training clusters where thermal load per rack position escalates.
- 12U:Full-height enclosures maximize vertical space utilization in high-density hyperscale deployments across the Greater Dublin Area.
12U retains volume leadership; 2U holds the steepest expansion curve.
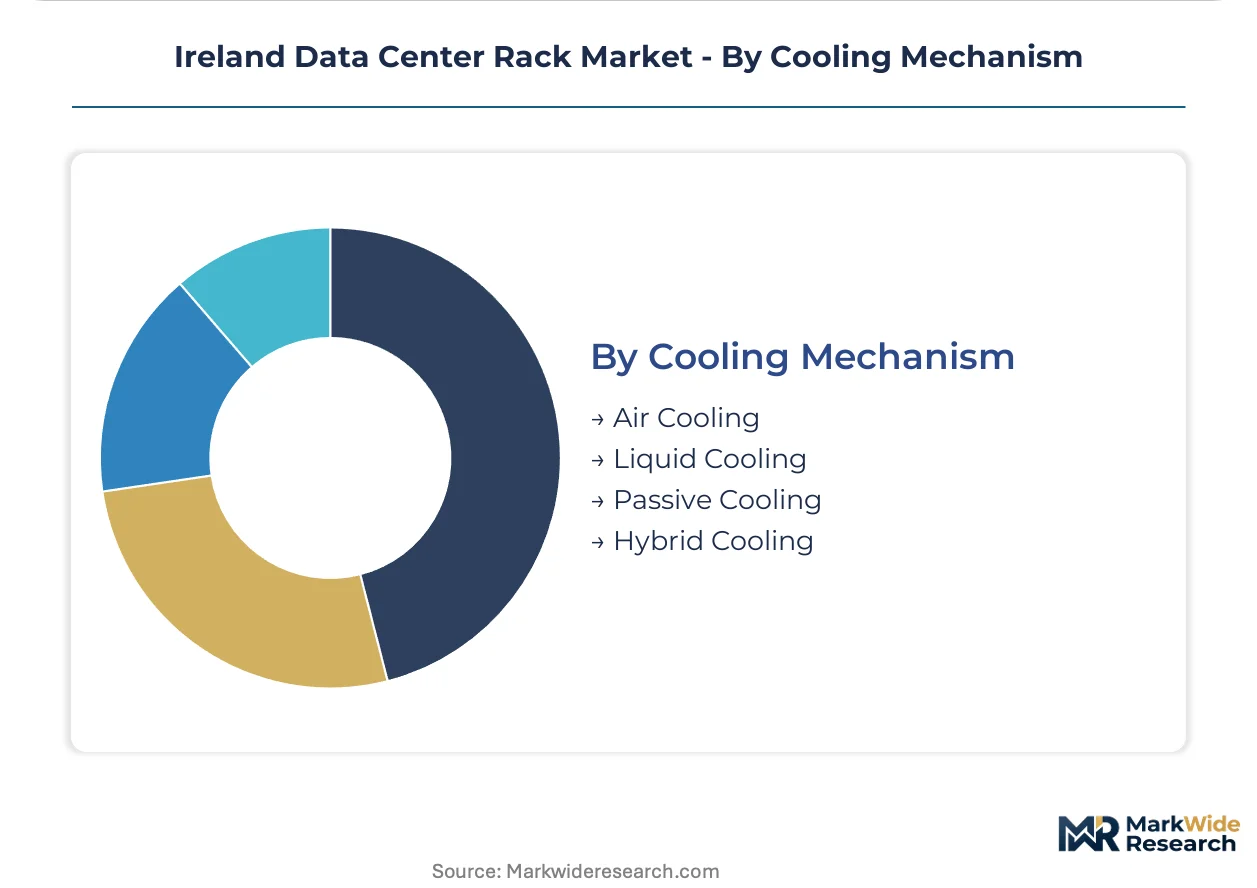
Cooling Mechanism:
Thermal architecture segmentation reflects EU F-Gas Regulation compliance pressure and AI workload density thresholds.
- Liquid Cooling:Direct-to-chip and immersion systems circulate dielectric fluid to capture heat at source. Hyperscale operators in Dublin specify factory-integrated coolant distribution units to satisfy power usage effectiveness mandates under Ireland's national planning framework.
- Air Cooling:Conventional forced-air systems using perimeter CRAC units retain installed base dominance in legacy colocation facilities. Cork Harbour developers face retrofit complexity when upgrading existing halls to support AI training clusters.
- Passive Cooling:Natural convection and thermal mass designs serve low-power edge nodes in rural Irish deployments with limited mechanical infrastructure.
- Hybrid Cooling:Combined air and liquid architectures allow phased thermal upgrades without full facility reconstruction.
Air Cooling retains volume leadership; Liquid Cooling holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland's data center rack market operates as a net import zone, with European and North American manufacturers supplying the bulk of enclosure systems. Domestic fabrication capacity remains limited, creating dependency on cross-channel logistics and just-in-time inventory models.
Greater Dublin Area
Hyperscale cloud deployments by Amazon Web Services and Microsoft Azure dominate rack procurement volumes. The EU Energy Efficiency Directive filters specifications toward liquid-cooling-ready frames. County Kildare substation build-outs enable synchronized supply commitments with energized facility schedules.
Cork Harbour
Secondary cluster development attracts modular enclosure suppliers seeking first-mover positioning. The Commission for Regulation of Utilities enforces grid connection standards that accelerate or delay project timelines. Edge facility developers here unbundle power infrastructure from space leases to secure operational flexibility.
Galway
Enterprise captive facilities favor phased capacity expansion through modular rack systems. Ireland's national planning framework mandates power usage effectiveness thresholds for new builds. Regional data halls here serve pharmaceutical and medical technology firms with security-certified enclosure requirements.
Limerick-Shannon
Aviation and logistics sector demand drives edge node installations with compact wall-mount configurations. The National Broadband Plan specifies standardized rack systems for public sector edge deployments. Shannon Free Zone proximity enables rapid equipment staging for western Ireland connectivity projects.
Ireland Data Center Rack Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the Ireland data center rack supply structure. The vendor base stratifies between full-stack infrastructure providers and enclosure-focused fabricators. Three archetypes dominate: integrated power-cooling platform vendors, modular enclosure specialists, and electrical distribution component suppliers. Competitive moves center on pre-integrated thermal architecture offerings and framework agreements with embedded performance guarantees.
Within the integrated platform tier, Schneider Electric SE and Eaton Corporation anchor procurement relationships with hyperscale operators. Rittal GMBH & Co.KG occupies a position among modular enclosure specialists serving colocation and enterprise segments. These three names exemplify the strategic segmentation between full-system integration and component-level specialization that defines vendor positioning across Irish facilities.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Eaton Corporation |
| Hewlett Packard Enterprise (HPE) |
| Rittal GMBH & Co.KG |
| Black Box Corporation |
| Vertiv Group Corp. |
| Dell Inc. |
| nVent Electric PLC |
| Econnex Comparison |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum input volatility determines both tier spreads and supply chain shape across the Ireland data center rack landscape. Commodity price swings compress margins for enclosure fabricators while hyperscale procurement teams exploit volume leverage to lock in long-term contract pricing.
Pricing Analysis
Cloud service provider buyers anchor three-tier pricing structure across premium, standard, and economy levels in the Ireland market. Premium tiers capture liquid-cooling-ready frames with factory-integrated busway feeds demanded by AWS and Microsoft Azure in County Kildare. Standard tiers serve colocation operators like Equinix prioritizing hot-aisle containment compatibility. Economy tiers address enterprise captive facilities in Galway with modular expansion capability. Price differentiation rests on thermal performance certification and volume scale commitment. Pricing pressure stems from green bond project finance favoring vendors with verified circular material credentials. Enterprise segments exhibit highest price sensitivity due to phased capital deployment constraints.
Supply Chain Analysis
Extended payment terms from hyperscale operators strain working capital for European enclosure fabricators serving Irish deployments. Supply concentrates in Germany, the Netherlands, and China for precision-formed steel chassis and aluminum extrusions. Raw material dependencies span cold-rolled steel from ArcelorMittal European mills, aluminum from Rusal and Norsk Hydro smelters, and copper busbar from German foundries. Single-source vulnerability concentrates in specialized coolant distribution unit components for liquid-cooled architectures. Distribution runs through direct OEM relationships for hyperscale campuses and channel partners for enterprise and colocation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as AI training cluster demand splits procurement specifications between liquid-cooling-ready hyperscale frames and retrofit-compatible hybrid architectures for legacy facilities.
For Market Incumbents: Pre-empt margin erosion by securing captive supply of precision-formed steel through backward integration into European mill relationships. Anchor framework agreements with embedded thermal performance guarantees before green bond project finance locks in competitor circular material credentials. Threat substitution emerges from modular enclosure specialists like Rittal capturing colocation preference through rapid configuration flexibility. For New Entrants and Emerging Players: Cork Harbour's secondary cluster development offers first-mover positioning for compact wall-mount configurations serving edge node distributed architectures. The Limerick-Shannon corridor underpenetration by liquid-cooling specialists creates white-space for dielectric fluid immersion systems targeting aviation and logistics sector latency requirements. Go-to-market angle should leverage unbundled power infrastructure contracts to secure operational flexibility preference among regional facility developers. For Investors and Strategic Acquirers: The EU F-Gas Regulation reshapes the acquisition landscape toward thermal engineering capabilities eliminating regulated refrigerants entirely. Long-term viability centers on vendors with demonstrated direct-to-chip and two-phase evaporative design expertise. Target acquisition archetype: modular enclosure specialists with factory-integrated coolant distribution unit production. Signal to watch: substation energization timelines in County Kildare and Cork Harbour accelerating synchronized rack supply commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Architecture Pre-Integration | Factory-installed coolant distribution units compress commissioning timelines for AWS and Microsoft Azure hyperscale deployments. |
| Green Bond Circular Material Certification | Verified sustainable steel and aluminum sourcing unlocks climate-aligned capital structures for Dublin and Cork projects. |
| County Kildare Substation Synchronization | Aligned rack supply commitments with Commission for Regulation of Utilities grid connection schedules reduce project delay risk. |
| F-Gas Compliant Thermal Redesign | Elimination of hydrofluorocarbon refrigerants from cooling-integrated systems maintains EU regulatory compliance trajectory. |
| Edge Node Compact Configuration Development | Wall-mount and reduced-form-factor enclosures capture National Broadband Plan public sector edge deployment specifications. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Data center facility operators, thermal engineering specialists, procurement leads at hyperscale cloud providers, and grid interconnection planners at the Commission for Regulation of Utilities provided operational perspective. Secondary sources include EU Energy Efficiency Directive implementation guidance, F-Gas Regulation compliance databases, Ireland national planning framework documents, and substation build-out disclosures from ESB Networks. Bottom-up rack shipment tracking and top-down facility capacity modeling triangulate market sizing.
Calibration against historical procurement cycles and energized facility schedules validates projection assumptions across the analysis window. Segmentation dimensions span rack configuration type, end-user archetype, vertical unit height, and cooling mechanism architecture. CAGRs derive from facility pipeline analysis and vendor order book trajectories. Key forecast inputs include AI training cluster thermal load projections and County Kildare substation capacity expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by electrical distribution component suppliers would shift outcomes. Macroeconomic commodity volatility, accelerated EU regulatory tightening, or breakthrough passive cooling technology advancement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Global Cloud Computing Data Center IT Asset Disposition (ITAD) Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Data Center Rack Power Distribution Unit Market
Data Center Infrastructure
South America Data Center Rack Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
South America Data Center Server Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
US Data Center Rack Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
Micro Data Center Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
UK Data Center Rack Market