
 Norway Data Center Storage Market | 2026-2036
Norway Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Storage Market Insights
Modular storage rack configurations is consolidating buyer preference across Norwegian colocation facilities, replacing monolithic arrays with disaggregated compute-storage units that scale incrementally. Green Mountain AS leverages its hydro-powered campus near Rjukan to anchor sustainability-sensitive contracts with European cloud providers. Bulk Infrastructure Group AS competes through deep-water cooling integration and fiber backhaul density along Norway's western fjord corridor. AQ Compute Data Center differentiates via direct liquid-cooled enclosures that trim mechanical overhead in Oslo-region edge nodes.
Norway data center storage encompasses electromechanical and solid-state media systems engineered for enterprise-grade durability, typically rated between one and five million hours mean time between failures, designed to retain petabyte-scale datasets under controlled temperature and humidity regimes for mission-critical continuity. Solid State Drives and Software-Defined Storage are capturing margin pools as latency-sensitive workloads displace mechanical spindles in financial and research applications; Hard Disk Drives sustains volume dominance in archival and backup tiers where cost-per-gigabyte governs procurement. Hybrid deployments across on-premises and managed service configurations are accelerating as Norwegian enterprises balance sovereignty requirements with operational flexibility.
Datatilsynet, Norway's national data protection authority, enforces GDPR-aligned residency mandates that steer procurement toward domestically sited storage infrastructure, while the Norwegian Water Resources and Energy Directorate regulates power allocation for large-scale facility expansion. The Norwegian Communications Authority oversees submarine cable landing permissions that determine latency arbitrage potential for storage-replication architectures. Stakeholders must monitor evolving carbon accounting rules under the EU Green Deal's border-adjustment mechanisms and assess whether Oslo-region land constraints will push capacity toward Tromsø or Kristiansand.
Market Dynamics
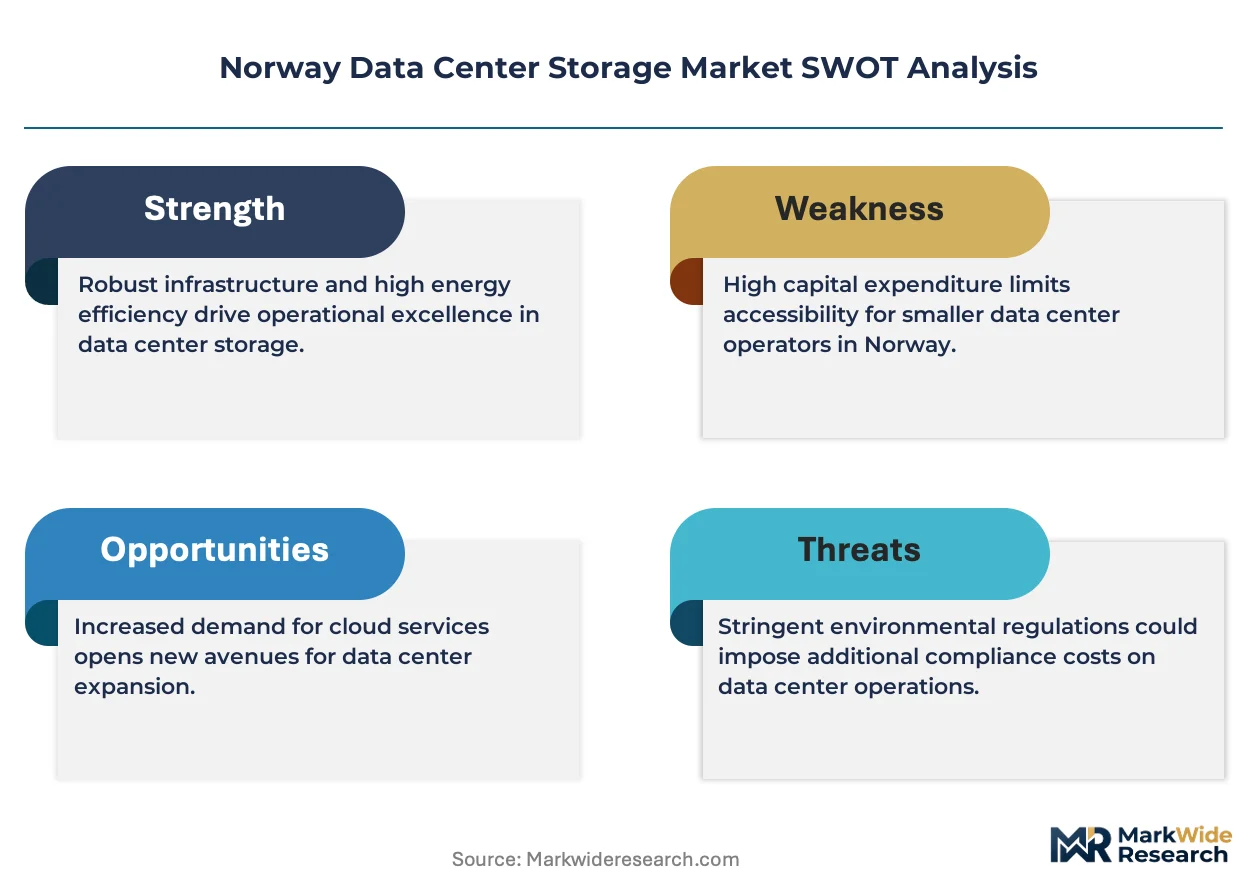
Hydroelectric surplus is compressing power costs for Norwegian data center operators while GDPR residency mandates from Datatilsynet force storage localization. This dual pressure accelerates facility buildouts along subsea cable landing points.
Growth Catalysts
- Seismic Data Retention Mandates:Norwegian oil and gas regulators now require multi-decade seismic archive preservation, expanding petabyte-scale storage demand from Equinor and Aker BP operations.
- EU Green Deal Border Adjustments:Carbon accounting rules under the EU Green Deal's CBAM mechanism reward Norwegian hydro-powered facilities with compliance advantages over coal-dependent continental competitors.
- Subsea Fiber Expansion:New cable systems landing at Stavanger and Kristiansand reduce replication latency to Frankfurt and London, enabling active-active storage architectures for financial services clients.
Market Restraints
- Land Scarcity in Oslo Corridor:Zoning restrictions around the capital limit brownfield expansion, pushing greenfield development toward secondary sites with inferior fiber density.
- Lithium-Ion Supply Concentration:Battery-backed UPS systems depend on Asian cell manufacturers, exposing Norwegian operators to shipping bottlenecks through the Suez corridor.
- Mechanical HDD Input Volatility:Rare earth magnet prices for spindle motors fluctuate with Chinese export quotas, compressing margins on archival tier deployments.
Strategic Opportunities
- Tromsø Edge Positioning:Arctic latitudes offer natural cooling advantages and emerging satellite ground station density for space-data storage processing.
- Direct Liquid Cooling Convergence:Integration of immersion cooling with AI training clusters enables 40kW+ rack densities previously impossible with air-cooled mechanical storage.
- PLI-Style Norwegian Incentives:Proposed state data center investment schemes modeled on EU recovery funds could offset construction costs for hyperscale anchor tenants.
Industry Challenges
- Specialized Technician Shortage:Direct liquid cooling infrastructure demands certified thermal engineers scarce in the domestic labor pool, forcing reliance on Finnish and German contractors.
- Legacy SAN Migration Complexity:Financial institutions in Oslo maintain aging Fibre Channel networks that resist API-driven software-defined storage orchestration without multi-year parallel run phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Storage Market |
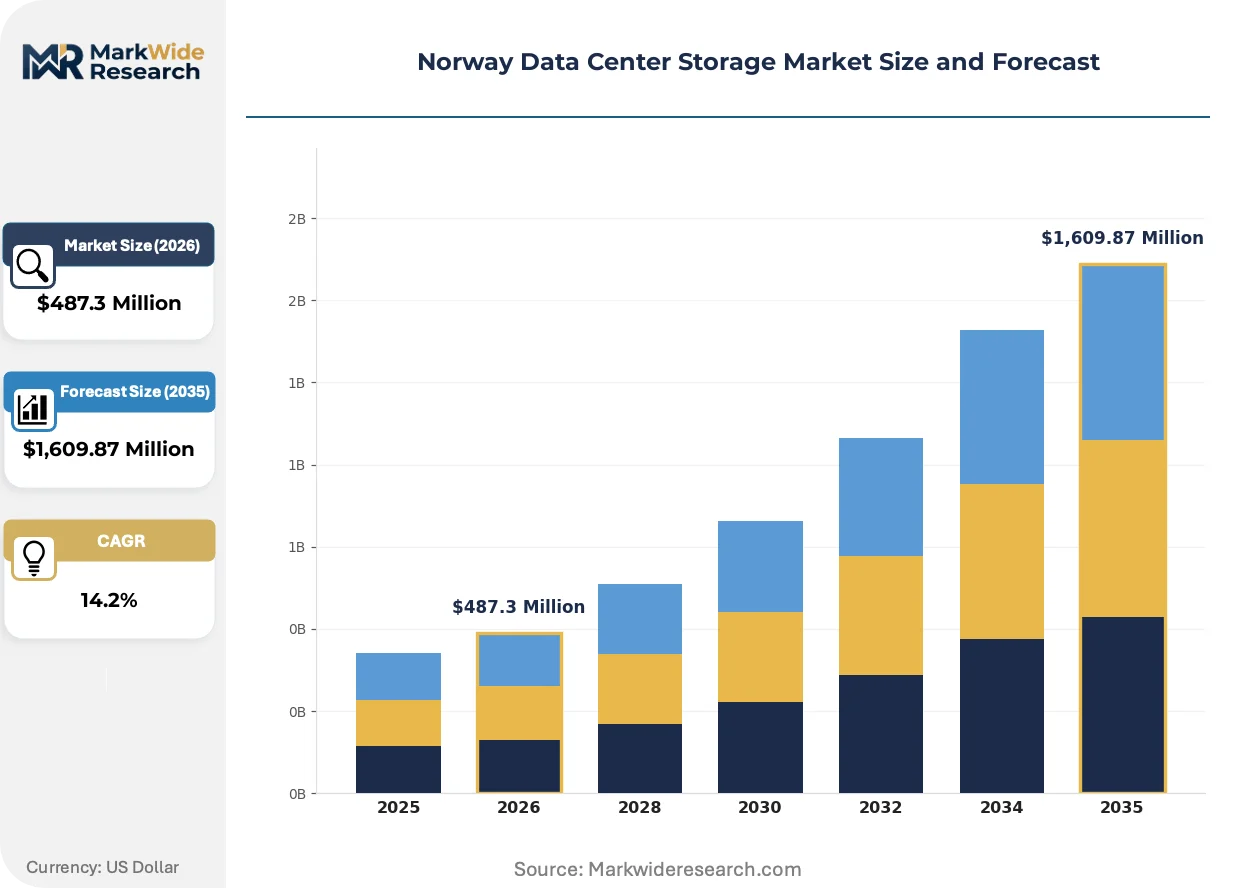
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,609.87 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Solid State Drives, Hard Disk Drives, Hybrid Storage, Tape Storage Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Small Enterprises, Large Enterprises, Government Agencies, Research Institutions Technology: NAND Flash, RAID, Object Storage, Software-Defined Storage |
| Companies Covered | Storespeed AS, AQ Compute Data Center, Green Mountain AS, GlobalConnect AB, Blix Solutions AS, Stack Infrastructure Inc, Orange Business Services AS, BlueFjords, Bulk Infrastructure Group AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Storage Market Trends and Innovations
Storage architecture is fragmenting into disaggregated, composable units that break traditional server-storage coupling. Norwegian facilities are early adopters of this decomposition, driven by renewable energy abundance and latency-sensitive workload growth.
NVMe-oF fabrics are overtaking traditional SAS interconnects in high-performance tiers. These protocols enable microsecond-latency access to pooled flash resources across rack-scale deployments. Quantitative trading firms and genomics research institutes in the Oslo-Stavanger corridor are adopting NVMe-oF at twice the rate of mechanical storage refreshes. The technology is overtaking legacy Fibre Channel as the default interconnect for latency-governed workloads, compressing switching infrastructure upgrade cycles from five to three years.
Datatilsynet's forthcoming guidance on cross-border data transfers tightens interpretation of GDPR Article 44. Norwegian enterprises must maintain primary storage copies within national jurisdiction or face administrative fines. Cloud providers are responding with sovereign cloud architectures that ring-fence Norwegian customer data from global replication pools. Financial services and public health research segments face the steepest compliance burden, accelerating procurement of domestically sited colocation.
Consumption-based storage contracts are displacing capital-intensive ownership models among mid-market Norwegian enterprises. Managed service providers now meter actual IOPS and capacity utilization rather than provisioning peak-load reserves. This shift transfers capacity planning risk from CIOs to facility operators, concentrating buyer power among the three dominant Norwegian colocation groups. Manufacturing and maritime logistics verticals show the fastest contract structure conversion, prioritizing operational expenditure predictability over asset control.
Norway Data Center Storage Market Segmentation
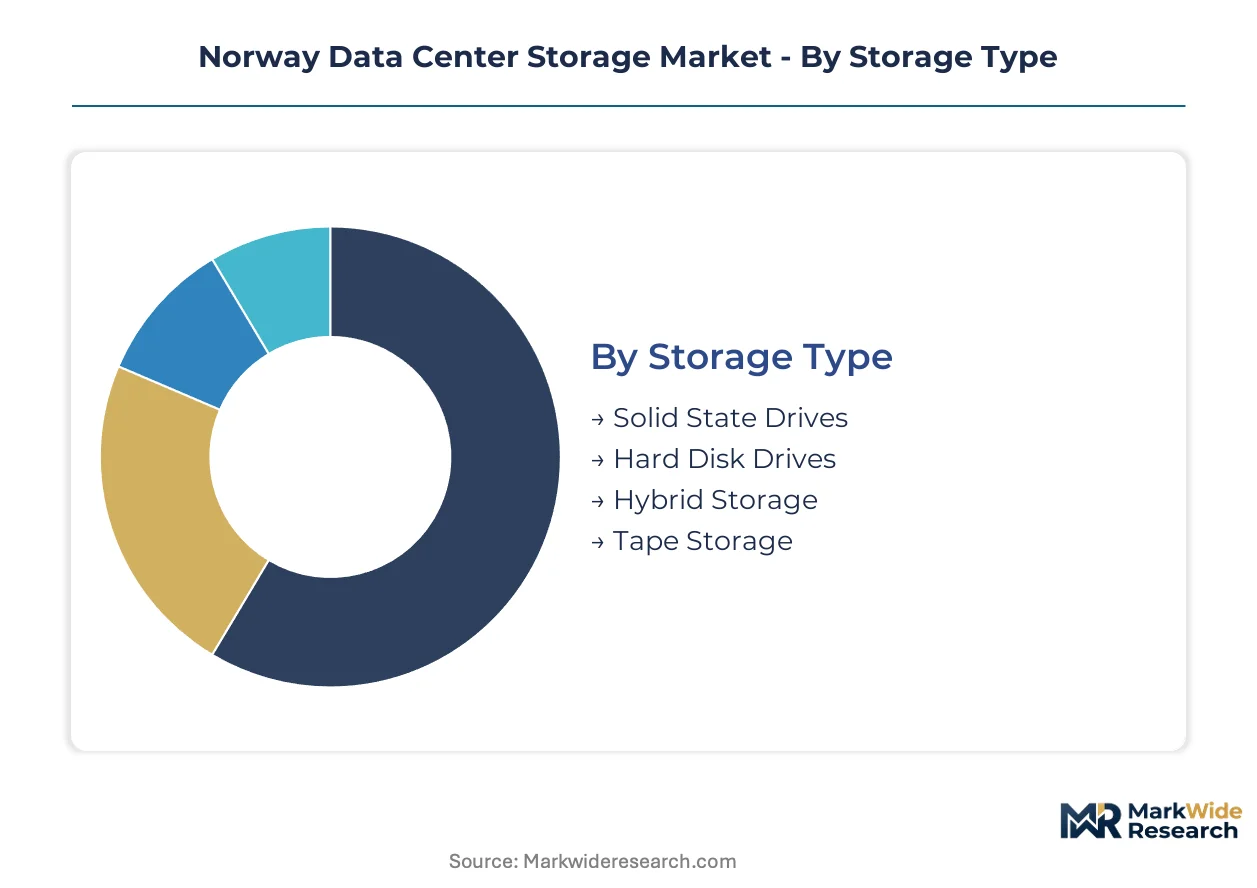
Storage procurement in Norway fractures across four decision axes: media physics, infrastructure location, organizational scale, and control abstraction. Buyers weight Datatilsynet residency mandates against latency requirements and TCO horizons, creating divergent specification patterns across the Oslo-Stavanger corridor.
Storage Type:
Capital allocation splits between performance tiers and archival economics, with hydroelectric power costs altering total ownership calculations for spin-up versus always-on media.
- Solid State Drives:NAND-based non-volatile storage delivers sub-millisecond latency for transactional databases and real-time seismic processing. Norwegian financial services firms in Oslo deploy NVMe SSDs for high-frequency trading infrastructure where microseconds determine arbitrage profitability. Datatilsynet's strict data localization requirements accelerate domestic flash capacity buildouts.
- Hard Disk Drives:Electromechanical platters with helium-sealed enclosures dominate cost-per-gigabyte optimization for petabyte-scale oil and gas archives. Equinor's multi-decade seismic retention mandates sustain HDD procurement volumes along the western fjord corridor despite mechanical failure rates exceeding solid-state alternatives.
- Hybrid Storage:Automated tiering software migrates hot data to flash and cold data to mechanical spindles. Mid-market enterprises leverage hybrid arrays to balance performance SLAs with budget constraints.
- Tape Storage:Linear Tape-Open cartridges provide air-gapped immutability for regulatory compliance and ransomware recovery. Government agencies specify tape for long-term national archive preservation.
Hard Disk Drives leads on scale; Solid State Drives leads on momentum.
Deployment Model:
Operational control preferences divide along data sovereignty sensitivity and internal technical capacity, reshaping facility operator contract structures.
- On-Premises:Enterprise-owned infrastructure within self-managed facilities or owned cages in colocation sites. Large oil and gas operators maintain on-premises storage for reservoir simulation clusters requiring direct hardware access.
- Cloud-Based:Hyperscale provider resources consumed via API without physical infrastructure ownership. Cloud-based deployments accelerate among SaaS startups prioritizing speed over compliance granularity.
- Hybrid:Synchronized workloads spanning owned infrastructure and public cloud resources. Norwegian healthcare networks deploy hybrid architectures to keep patient records on-premises while bursting analytics to cloud.
- Managed Services:Outsourced storage operations with consumption-based billing and guaranteed SLAs. Small enterprises lacking dedicated storage engineers convert fastest to managed service contracts.
On-Premises retains the largest installed base; Managed Services climbs the fastest.
End User:
Organizational scale determines procurement sophistication, with compliance burden and technical staffing driving divergent vendor engagement patterns.
- Large Enterprises:Multi-petabyte deployments with dedicated storage architects and custom RFP processes. Energy majors and financial institutions negotiate direct contracts with facility operators for sovereign cloud configurations.
- Government Agencies:Procurement governed by public tender regulations and national security classification requirements. Defense and civilian archives specify domestic encryption and physical access controls.
- Research Institutions:University and government laboratory deployments emphasizing high-throughput parallel access for simulation workloads. CERN-affiliated physics groups and marine biology institutes drive demand for high-performance parallel file systems.
- Small Enterprises:Sub-100TB deployments typically consuming managed services or colocation bundles. Regional maritime suppliers and software consultancies prioritize predictable monthly expenditure over infrastructure control.
Large Enterprises leads on scale; Research Institutions leads on momentum.
Technology:
Control plane abstraction versus hardware-level redundancy creates divergent architectural commitments across Norwegian facilities.
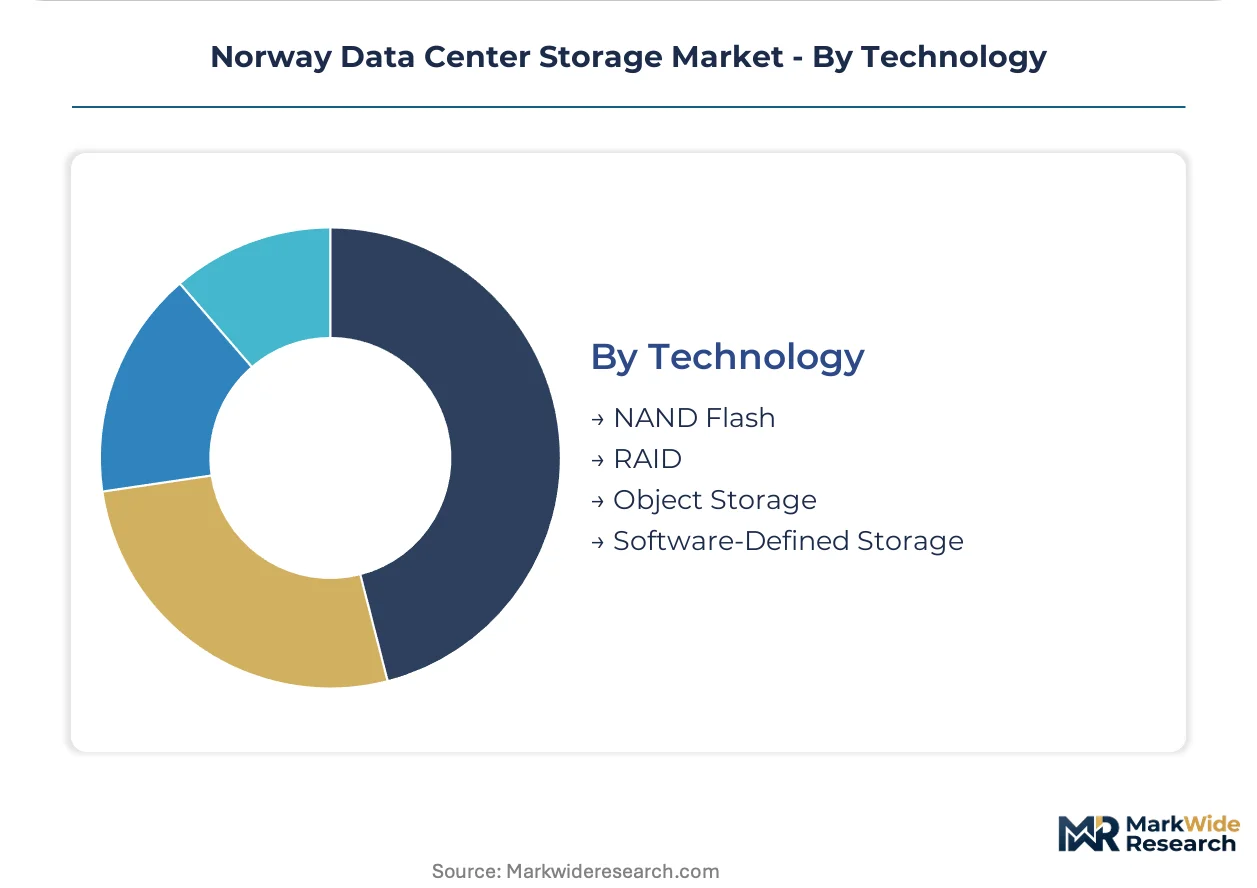
- Software-Defined Storage:Decoupled control and data planes enabling commodity hardware consumption and programmatic provisioning. Green Mountain AS and Bulk Infrastructure Group AS deploy SDS layers to standardize multi-vendor hardware pools.
- Object Storage:Flat-namespace architectures optimized for unstructured data growth and cloud-native application integration. Genomics pipelines and media archives adopt S3-compatible object stores for exabyte-scale expansion.
- NAND Flash:Solid-state media technology underlying performance-tier deployments, with QLC densification reducing cost-per-bit. Direct liquid-cooled enclosures from AQ Compute Data Center accommodate flash thermal density in edge configurations.
- RAID:Legacy redundant array configurations persisting in Fibre Channel SAN environments resistant to migration. Oslo financial institutions maintain RAID-6 mechanical arrays during multi-year parallel run phases.
RAID leads on legacy installed base; Software-Defined Storage leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center storage infrastructure in Norway traces its modern lineage to hydroelectric-powered server farms established in the early 2000s, when Nordic governments first marketed renewable electricity surplus to international computing operators. The sector now concentrates along subsea cable corridors where latency arbitrage meets carbon-advantaged power economics.
Oslo-Stavanger Corridor
Equinor's seismic data retention mandates and Aker BP's reservoir modeling clusters drive petabyte-scale procurement across this southern axis. Datatilsynet's GDPR enforcement tightens storage localization requirements for financial services firms headquartered in Oslo. Hyperscale facilities densify near Sandefjord and Drammen, exploiting fiber density and grid interconnection capacity.
Western Fjord Region
Deep-water cooling integration and submarine cable landings at Kristiansand anchor facility economics along Norway's southwestern coast. The Norwegian Water Resources and Energy Directorate regulates power allocation for large-scale expansion near Rjukan and Telemark. Green Mountain AS operates hydro-powered campuses that supply sustainability-sensitive contracts to European cloud providers.
Trøndelag and Central Norway
Research institutions and marine biology institutes in Trondheim generate demand for high-throughput parallel file systems. EU Green Deal border-adjustment mechanisms reward hydro-powered facilities with compliance advantages over continental competitors. Edge computing nodes emerge near Ålesund to serve maritime logistics and fisheries analytics.
Tromsø and Arctic Norway
Natural cooling advantages and emerging satellite ground station density reshape Tromsø's positioning for space-data storage processing. Proposed state data center investment schemes could offset construction costs for hyperscale anchor tenants in this high-latitude zone. Latency to continental European markets remains the primary constraint on active-active replication architectures.
Norway Data Center Storage Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sustainability certification and latency performance dimensions. The Norwegian market structures around three tiers: hydro-powered facility operators with renewable energy contracts, fiber-dense colocation specialists with subsea cable access, and edge-computing providers serving latency-sensitive workloads. Consolidation pressures intensify as sovereign cloud requirements and carbon accounting rules favor operators with captive renewable supply. Capacity expansion and strategic partnerships dominate competitive moves, with facility operators securing long-term power purchase agreements and interconnection rights.
Among Norwegian facility operators, Green Mountain AS exemplifies the renewable-powered tier through its hydroelectric campus positioning, while Bulk Infrastructure Group AS represents fiber-density specialization along western corridor routes. AQ Compute Data Center anchors the liquid-cooled edge segment in Oslo-region deployments. These three operators collectively illustrate how sustainability credentials, cooling innovation, and subsea connectivity define competitive differentiation in a market governed by Datatilsynet residency mandates and EU Green Deal compliance mechanics.
| Leading Market Players |
|---|
| Storespeed AS |
| AQ Compute Data Center |
| Green Mountain AS |
| GlobalConnect AB |
| Blix Solutions AS |
| Stack Infrastructure Inc |
| Orange Business Services AS |
| BlueFjords |
| Bulk Infrastructure Group AS |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up facility operators across the Oslo-Stavanger corridor anchor supply-side discipline through long-term power purchase agreements, compressing procurement volatility while enabling consumption-based contract structures that transfer capacity risk from enterprise buyers to colocation providers.
Pricing Analysis
Consumption-based metering with guaranteed SLAs governs Norwegian data center storage contracts, replacing capital-intensive ownership models. Price differentiation rests on sustainability certification tier and fiber proximity to subsea cable landing points. Cost compression in archival HDD tiers intensifies because rare earth magnet prices fluctuate with Chinese export quotas. Small maritime logistics enterprises exhibit highest price sensitivity; Equinor and Aker BP demonstrate lowest sensitivity due to regulatory retention mandates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell manufacturers for UPS battery systems, exposing Norwegian operators to Suez corridor shipping bottlenecks. NAND flash fabrication concentrates in South Korea, Taiwan, and Japan; mechanical HDD spindle motors draw from Chinese rare earth processing. Tariff exposure runs through EU Green Deal border-adjustment mechanisms on carbon-intensive component imports. Distribution runs through hyperscale facility operators with captive renewable energy contracts and direct interconnection rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian data center storage represents a late-cycle quality story as Datatilsynet enforcement shifts procurement toward sovereign-certified facilities with hydroelectric power provenance and domestic encryption standards.
For Market Incumbents: Extend long-term power purchase agreements with Statnett grid operators to lock in renewable cost advantages against emerging Tromsø competitors. Secure direct liquid cooling certification partnerships with Finnish and German thermal engineering contractors to address domestic technician scarcity. Defensive positioning against hyperscale cloud providers requires deepening fiber backhaul density along western fjord corridors. For New Entrants and Emerging Players: Direct liquid-cooled edge enclosures for AI training clusters offer the most penetrable white-space entry point, as AQ Compute Data Center's Oslo-region deployments demonstrate 40kW+ rack density feasibility. Tromsø's satellite ground station corridor presents geographic arbitrage for space-data processing workloads underserved by southern latency constraints. Go-to-market execution should anchor on sovereign cloud architectures with ring-fenced Norwegian data residency. For Investors and Strategic Acquirers: European hyperscale cloud providers are the most active acquirer in this space, seeking hydro-powered facility assets to satisfy EU Green Deal compliance mechanics and carbon accounting transparency. Long-term viability hinges on captive renewable supply and subsea cable interconnection rights rather than speculative greenfield development. Monitor Datatilsynet cross-border data transfer guidance enforcement intensity as the inflection signal for domestic colocation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Power Purchase Agreement | Statnett grid interconnection locks in hydroelectric cost advantages against continental coal-dependent competitors. |
| Direct Liquid Cooling Certification | Finnish and German thermal engineering partnerships address domestic technician scarcity for high-density AI clusters. |
| Sovereign Cloud Architecture | Ring-fenced Norwegian data pools satisfy Datatilsynet GDPR Article 44 residency mandates for financial services. |
| Subsea Cable Interconnection Rights | Stavanger and Kristiansand landing permissions enable active-active replication architectures for Frankfurt-London latency arbitrage. |
| Arctic Edge Facility Development | Tromsø's natural cooling advantages and satellite ground station density capture space-data processing growth. |
Research Methodology
Bottom-up oil and gas operator modeling reconciled against top-down facility capacity tracking forms the analytical core of this study. Primary interviews with data center facility operators, Datatilsynet compliance officers, subsea cable infrastructure planners, and enterprise storage procurement managers combined with secondary validation from Norwegian Water Resources and Energy Directorate power allocation filings, Norwegian Communications Authority submarine cable permits, and EU Green Deal CBAM mechanism documentation. Top-down hyperscale capex disclosure triangulation against bottom-up colocation contract value completes the volume reconciliation.
Input-output matrices map storage type, deployment model, end user scale, and control abstraction technology across the projection horizon. Segmentation dimensions include media physics tier, infrastructure location sovereignty, organizational procurement sophistication, and software-defined versus hardware-defined control planes. CAGRs derive from facility power allocation trajectories, seismic data retention mandate compliance curves, and NVMe-oF adoption velocity in quantitative trading and genomics workloads. Forecast inputs incorporate Datatilsynet enforcement intensity scenarios and EU Green Deal carbon border adjustment implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion supply chain disruption through Suez corridor logistics, Chinese rare earth export quota volatility, and Oslo-region land scarcity pushing development toward secondary fiber-constrained sites. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Connected Distribution Center Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Fault Tolerant Servers Market
Data Center Infrastructure
Chile Data Center Processor Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Europe Automated Storage and Retrieval System Market
Data Center Infrastructure
Data Center Substation Market