
 Germany Data Center Physical Security Market | 2026-2036
Germany Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Physical Security Market Insights
BSI IT-Grundschutz certification is unwinding the vendor landscape for German data center operators, forcing security integrators to demonstrate systematic documentation of physical access controls and environmental monitoring. Bosch Sicherheitssysteme GmbH leverages its domestic manufacturing footprint to anchor premium surveillance deployments across Frankfurt and Berlin facilities. Siemens AG competes through deep integration of building automation with physical security protocols, while Axis Communications AB specializes in network camera architectures optimized for low-latency edge analytics in colocation environments.
Germany data center physical security encompasses layered protection systems—perimeter barriers, biometric authentication, video analytics, and environmental threat detection—engineered to maintain operational continuity for facilities processing classified and commercial workloads. Surveillance cameras with 4K resolution and AI-powered anomaly detection now constitute the dominant technology spend, though access control systems represent the fastest-growing segment as zero-trust principles migrate from cyber to physical domains. Among end users, cloud service providers command the largest installation pipeline, while integrated systems solutions capture expanding margin pools by consolidating formerly siloed monitoring, access, and fire suppression functions under unified management platforms.
Germany's Federal Office for Information Security (BSI) mandates IT-Grundschutz compliance for critical infrastructure, directly shaping procurement specifications and supplier pre-qualification criteria for data center operators. The EU NIS2 Directive, transposed into German national law, extends physical security audit obligations to medium-sized digital service providers previously exempt from such oversight. Stakeholders must monitor how forthcoming amendments to the BSI Act will redefine liability boundaries between facility owners and contracted security service providers.
Market Dynamics
The BSI IT-Grundschutz certification regime is compressing procurement timelines for German data center operators, forcing security integrators to restructure documentation workflows and accelerate compliance documentation before facility commissioning deadlines.
Growth Catalysts
- Hyperscale facility construction:Cloud service providers are expanding footprints across Bavaria and Hesse, generating concentrated demand for perimeter hardening and biometric access layers in new builds.
- EU NIS2 Directive transposition:Extended physical security audit obligations now apply to medium-sized digital service providers previously exempt, widening the addressable operator base.
- Zero-trust architecture migration:Principles from cybersecurity domains are migrating into physical access control specifications, accelerating replacement cycles for legacy card-based systems.
Market Restraints
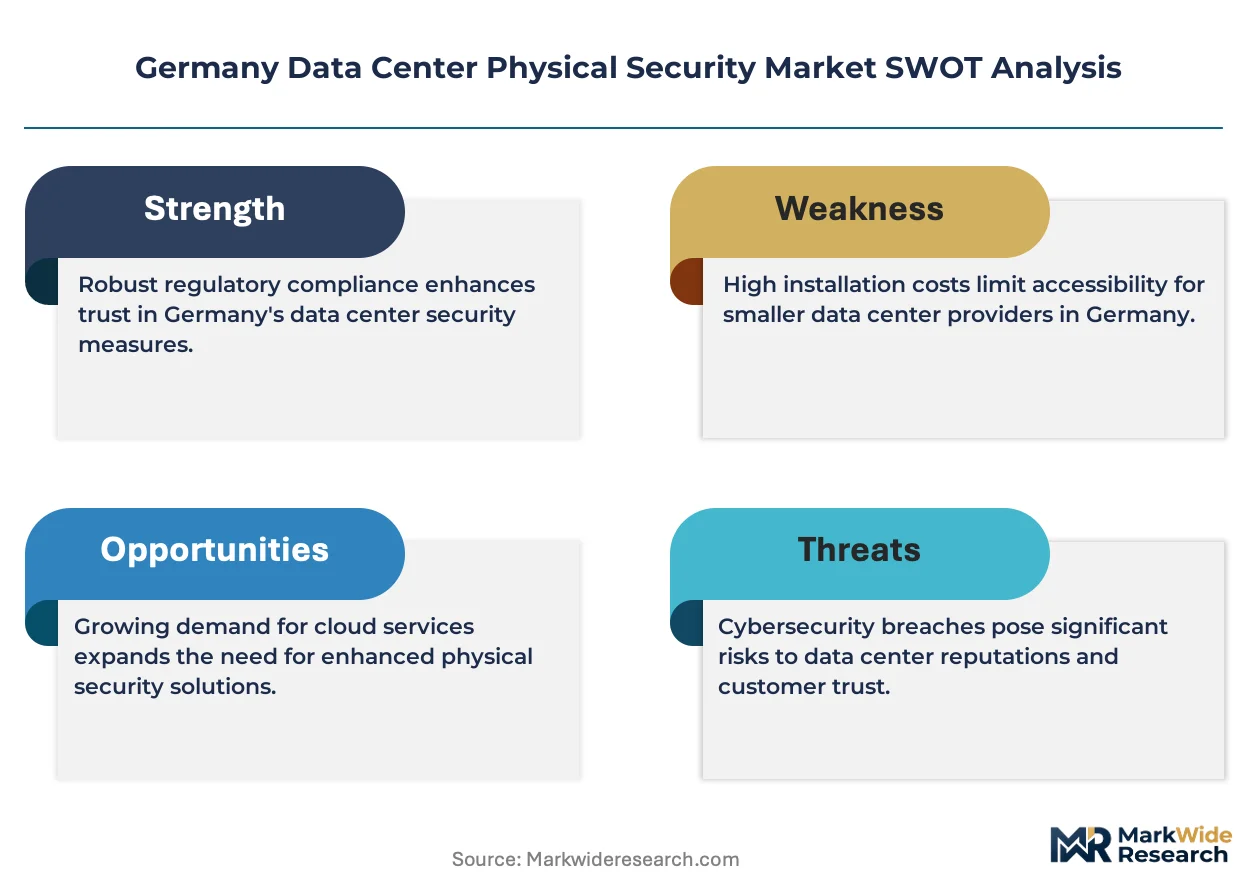
- Specialized engineering talent scarcity:Certified security system designers with BSI documentation experience command premium compensation, inflating project delivery costs.
- Component supply concentration:Advanced biometric sensors and edge analytics chipsets depend on concentrated Asian manufacturing nodes, exposing lead time volatility.
- Certification timeline friction:IT-Grundschutz compliance documentation extends facility commissioning schedules by six to twelve months, delaying revenue recognition for operators.
Strategic Opportunities
- Eastern German state expansion:Saxony and Thuringia offer underpenetrated colocation markets with lower land costs and available grid capacity for Tier III facilities.
- Building automation convergence:Integration of fire suppression, environmental monitoring, and access control under unified management platforms creates margin expansion for systems integrators.
- BSI Act amendment anticipation:Forthcoming liability boundary redefinitions between facility owners and contracted security service providers will reshape service contract structures.
Industry Challenges
- Multi-vendor integration complexity:Operators struggle to harmonize disparate surveillance, access, and environmental monitoring systems into coherent incident response workflows.
- Documentation audit readiness:Systematic evidence collection for BSI assessors requires dedicated compliance personnel that mid-sized operators struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Physical Security Market |
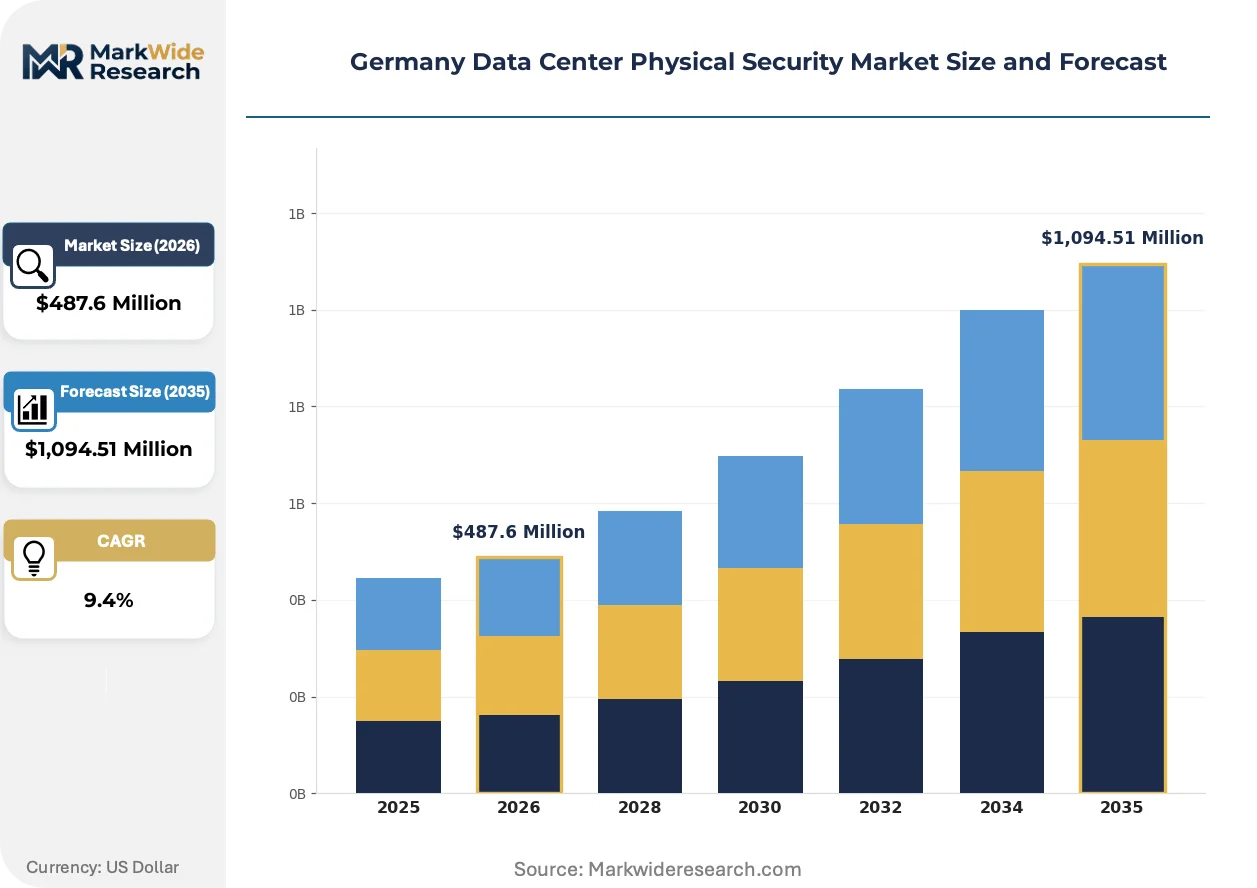
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,094.51 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Cameras, Access Control Systems, Intrusion Detection, Fire Suppression End User: Telecommunications Providers, Cloud Service Providers, Financial Sector, Retail Chains Solution: Integrated Systems, Standalone Devices, Monitoring Services, Cloud-Based Solutions Installation: New Builds, Upgrades, Retrofit Projects, Onsite Services |
| Companies Covered | Bosch Sicherheitssysteme GmbH, Axis Communications AB, Schneider Electric, Johnson Controls, ABB Ltd, Securitas Technology, Honeywell International Inc., Siemens AG, Genetec, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Physical Security Market Trends and Innovations
Artificial intelligence is penetrating physical security architectures at the edge, compressing response latency and enabling predictive threat detection before perimeter breaches materialize.
AI-powered video analytics with embedded anomaly detection is displacing rule-based motion detection in hyperscale Frankfurt facilities. Cloud service providers mandate sub-second alert generation for perimeter intrusions, forcing camera manufacturers to relocate processing from central servers to device edge. This architectural shift is displacing traditional network video recorder deployments and compressing infrastructure capital requirements for new builds.
The BSI IT-Grundschutz certification catalog is tightening documentation requirements for physical access control systems across critical infrastructure classifications. German data center operators must now demonstrate systematic testing of failover procedures and environmental threat response protocols. Colocation providers serving financial services clients face the most stringent audit frequencies, driving investment in automated compliance monitoring tools.
Consolidated facility management contracts are compressing vendor fragmentation in the Rhine-Main cluster. Hyperscale operators now demand single-accountability structures for security, fire suppression, and building automation from primary contractors. This procurement consolidation is most visible among cloud service providers with multi-megawatt deployments, who prioritize operational simplicity over best-of-breed component selection.
Germany Data Center Physical Security Market Segmentation
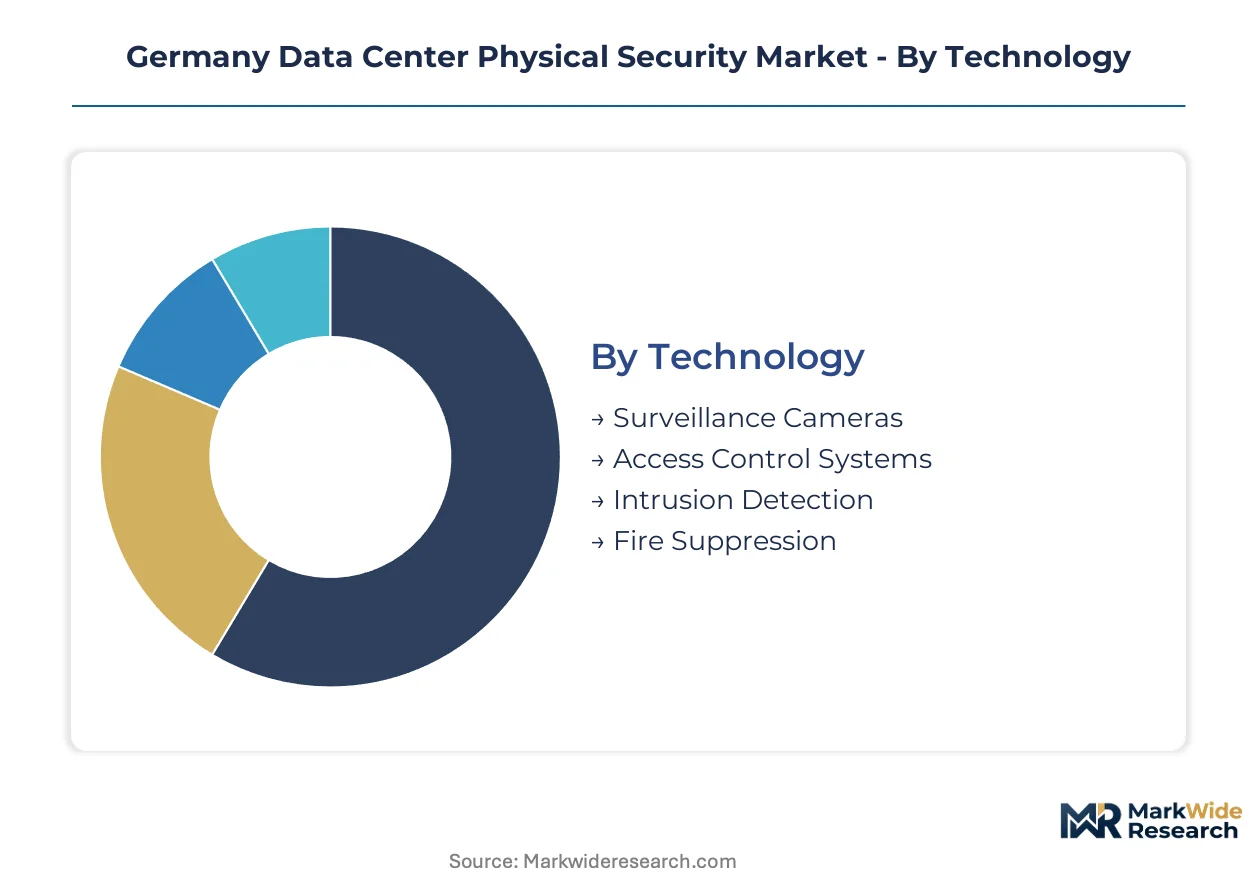
German data center operators structure procurement around BSI IT-Grundschutz compliance tiers, with certification requirements dictating technology selection and integration depth across facility classifications. Segmentation reveals how regulatory pressure concentrates investment in unified platforms while fragmenting spend across specialized point solutions.
Technology:
BSI documentation requirements differentiate procurement specifications across technology categories, with critical infrastructure classifications mandating redundant coverage and systematic failover testing.
- Surveillance Cameras:4K resolution devices with AI-powered edge analytics now dominate hyperscale deployments in Frankfurt's Rhine-Main cluster. Cloud service providers mandate sub-second intrusion alert generation, displacing centralized network video recorder architectures with on-device processing.
- Access Control Systems:Biometric authentication layers—fingerprint, iris, and facial recognition—are replacing legacy card-based systems as zero-trust principles migrate from cyber to physical domains. Financial sector facilities in Hesse drive replacement cycles through the strictest audit frequencies.
- Intrusion Detection:Perimeter hardening systems combining seismic sensors, microwave barriers, and thermal imaging protect Bavarian hyperscale campuses.
- Fire Suppression:Clean agent and water mist systems integrate with building automation protocols for environmental threat response.
Surveillance cameras handle the majority of throughput; access control systems are expanding most quickly on share.
End User:
Customer scale determines integration complexity, with multi-megawatt operators consolidating vendors under single-accountability contracts while mid-sized providers fragment procurement across specialized suppliers.
- Cloud Service Providers:Hyperscale construction across Bavaria and Hesse generates concentrated demand for perimeter hardening and biometric layers. These operators prioritize operational simplicity over best-of-breed selection, driving consolidated facility management contracts.
- Telecommunications Providers:Legacy infrastructure modernization programs in North Rhine-Westphalia upgrade surveillance and access systems to meet tightened BSI timelines. Carrier-neutral facilities face compressed commissioning schedules.
- Financial Sector:Colocation providers serving banks and insurers face the most stringent BSI audit frequencies, driving investment in automated compliance monitoring tools.
- Retail Chains:Distributed edge data centers supporting omnichannel operations require standardized security architectures across smaller-footprint facilities.
Cloud service providers command the largest installation pipeline; financial sector clients show the steepest compliance-driven upgrade intensity.
Solution:
Margin pools concentrate where monitoring, access, and fire suppression functions consolidate under unified management platforms rather than siloed point solutions.
- Integrated Systems:Unified platforms consolidating surveillance, access control, and environmental monitoring capture expanding margin pools. Systems integrators leverage building automation convergence to anchor multi-year service contracts.
- Standalone Devices:Point solutions retain relevance in retrofit scenarios where legacy infrastructure constrains platform migration. Mid-sized operators in Saxony and Thuringia favor this approach to limit capital commitment.
- Monitoring Services:Remote oversight contracts address certified security system designer scarcity by externalizing compliance documentation.
- Cloud-Based Solutions:Software-defined security management enables centralized policy enforcement across distributed facility portfolios.
Integrated systems dominate new build specifications; cloud-based solutions are gaining share fastest among multi-site operators.
Installation:
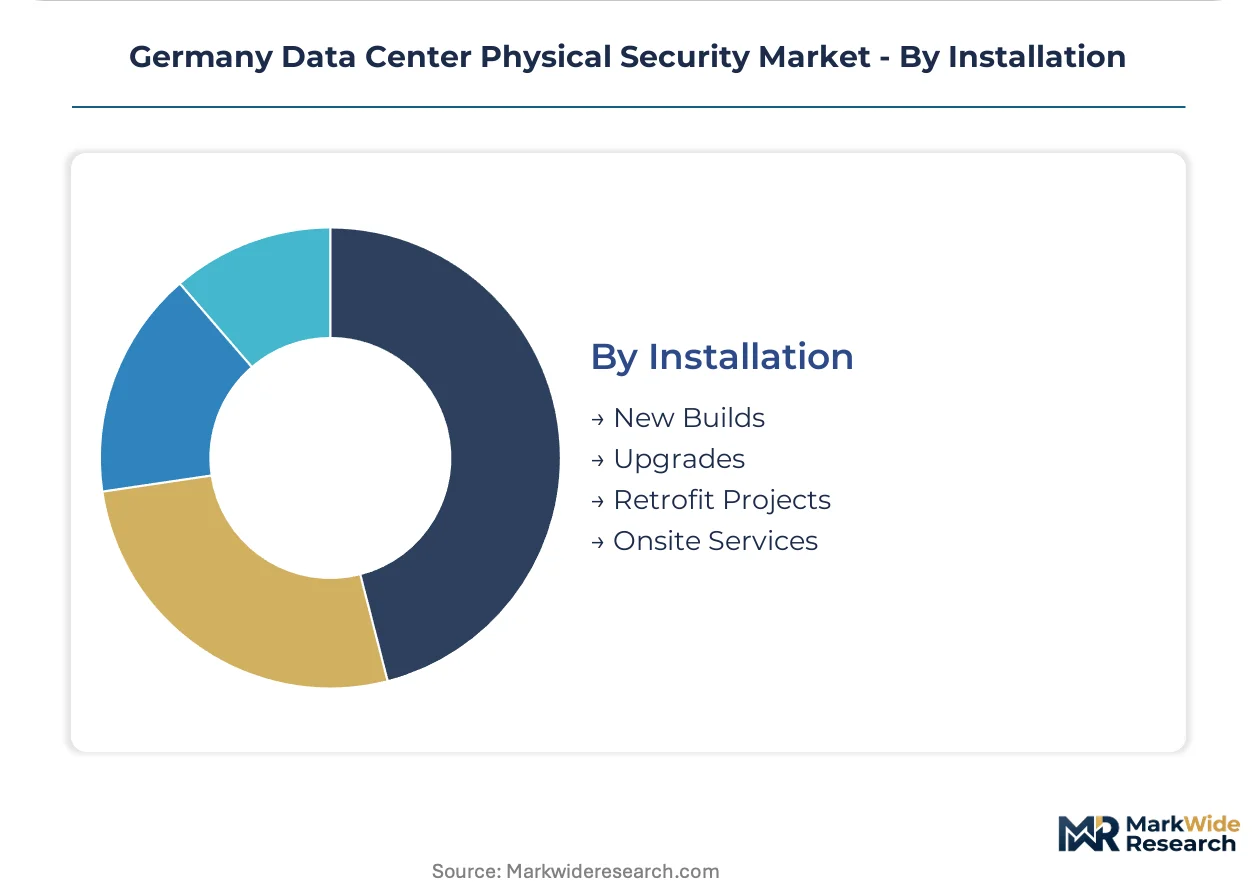
Project type shapes supplier qualification criteria, with greenfield developments enabling architectural optimization while retrofits constrain technology selection through infrastructure lock-in.
- New Builds:Greenfield hyperscale facilities across the Rhine-Main cluster embed security architecture from foundation phase, enabling edge-native camera deployments and unified building automation integration.
- Upgrades:Partial system refreshes address BSI compliance gaps without full platform replacement, common among Tier II facilities seeking Tier III certification.
- Retrofit Projects:Legacy infrastructure in older Frankfurt facilities constrains biometric system deployment, requiring creative engineering for cable routing and power distribution.
- Onsite Services:Maintenance and compliance documentation support addresses talent scarcity, with certified personnel commanding premium compensation.
New builds absorb the majority of capital deployment; retrofit projects face the steepest timeline and engineering constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt Rhine-Main grid interconnect anchors Germany's data center density, channeling hyperscale investment into Bavaria and Hesse while eastern states attract greenfield expansion with available power capacity.
Bavaria
Hyperscale campuses near Munich drive perimeter hardening demand across the Isar Valley. The BSI IT-Grundschutz certification timeline compresses procurement for new builds. Edge analytics deployment concentrates in the Munich-Unterhaching corridor where cloud providers cluster.
Hesse
Financial sector colocation in Frankfurt generates the strictest audit frequencies nationwide. The EU NIS2 Directive transposition tightens physical security obligations for medium-sized operators. Biometric access layers dominate retrofit specifications in the Taunus data center belt.
North Rhine-Westphalia
Telecommunications infrastructure modernization upgrades legacy surveillance systems across Cologne-Düsseldorf. Carrier-neutral facilities face compressed commissioning schedules under BSI documentation requirements. The Rhine-Ruhr industrial corridor attracts distributed edge deployments serving manufacturing clients.
Saxony
Underpenetrated colocation markets offer lower land costs for Tier III greenfield projects. Grid availability exceeds demand in the Leipzig-Chemnitz axis. State development agencies incentivize facility construction with streamlined permitting for critical infrastructure classification.
Berlin-Brandenburg
Government cloud procurement concentrates physical security investment around the capital region. Federal data sovereignty requirements mandate domestic certification for facility operators. The BER airport logistics zone anchors emerging hyperscale interest with dark fiber connectivity.
Germany Data Center Physical Security Market Competitive Landscape
Listed leaders compete with private specialists across compliance documentation depth, forcing tiered positioning between scale-driven integrators and certification-focused boutiques. The vendor base splits between building automation conglomerates and surveillance-native specialists. Three archetypes dominate: domestic manufacturing anchors, systems integration platforms, and network camera architects. Competitive moves concentrate on consolidated facility management contracts and edge-native hardware deployment.
Among Germany-based security conglomerates, Bosch Sicherheitssysteme GmbH and Siemens AG occupy positions anchored by domestic manufacturing footprints and building automation integration capabilities. Axis Communications AB represents the network camera specialization archetype within this landscape. These three entities exemplify the strategic divergence between hardware-native production and platform-level systems convergence.
| Leading Market Players |
|---|
| Bosch Sicherheitssysteme GmbH |
| Axis Communications AB |
| Schneider Electric |
| Johnson Controls |
| ABB Ltd |
| Securitas Technology |
| Honeywell International Inc. |
| Siemens AG |
| Genetec |
| Others |
Pricing and Supply Chain Analysis
Long-term facility management contracts lock in supply access for biometric sensors and edge analytics chipsets while anchoring price visibility across multi-year deployment cycles. German operators under BSI IT-Grundschutz timelines favor consolidated procurement structures that bundle hardware, installation, and compliance documentation under single-accountability terms.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud providers from mid-sized colocation operators, with multi-megawatt deployments commanding substantial hardware cost reductions and extended service terms. Price differentiation hinges on BSI certification grade and after-sales documentation support, where financial sector facilities pay premiums for automated compliance monitoring. Cost compression in standalone device procurement is intensifying because certified security system designers command premium compensation. Mid-sized operators in Saxony and Thuringia show the highest price sensitivity, while Frankfurt Rhine-Main hyperscalers prioritize operational simplicity over unit cost optimization.
Supply Chain Analysis
Inbound logistics costs from Asian manufacturing nodes for advanced biometric sensors and edge analytics chipsets expose German integrators to container availability volatility on Asia-Europe trade lanes. Component supply concentrates in China, South Korea, and Taiwan for AI-enabled camera modules and access control chipsets. Raw material dependencies include rare earth elements for sensor magnetics, specialized semiconductors for edge processing, and optical-grade glass for surveillance lenses. Single-source vulnerability in thermal imaging sensor production creates concentrated risk exposure. Distribution runs through authorized systems integrators with BSI documentation capabilities rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany data center physical security sits in early-cycle expansion, with EU NIS2 Directive transposition extending compliance obligations to previously exempt medium-sized operators and widening the addressable base substantially.
For Market Incumbents: Secure consolidated facility management contract structures before hyperscale procurement decisions finalize, locking in multi-year service revenue streams. Anchor premium positioning through deep BSI IT-Grundschutz documentation expertise, as mid-sized operators struggle to retain certified compliance personnel internally. Counter emerging competition from building automation conglomerates by accelerating edge-native hardware deployment timelines. For New Entrants and Emerging Players: Compliance documentation as a service represents a critical service-layer gap where incumbents under-serve mid-sized operators facing talent scarcity. Target Saxony and Thuringia greenfield developments with lower land costs and streamlined state permitting incentives. Penetrate through remote monitoring contracts that externalize BSI audit readiness for Tier II facilities seeking Tier III certification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among systems integrators with unified platform deployments spanning surveillance, access control, and environmental monitoring. Long-term viability centers on vendors with demonstrated BSI certification track records and established relationships with Frankfurt Rhine-Main hyperscale operators. Watch hyperscale construction permit approvals as the primary inflection indicator for hardware demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| BSI Certification Investment | Accelerates pre-qualification for critical infrastructure procurement pipelines in Frankfurt Rhine-Main. |
| Edge-Native Hardware Deployment | Compresses alert latency for cloud providers mandating sub-second intrusion detection response. |
| Unified Platform Integration | Captures margin expansion by consolidating siloed surveillance, access, and fire suppression functions. |
| Eastern State Geographic Expansion | Accesses underpenetrated Saxony and Thuringia colocation markets with available grid capacity. |
| Automated Compliance Monitoring Tools | Addresses financial sector audit frequency demands in Hesse colocation facilities. |
Research Methodology
Desk research of BSI technical guidelines, EU NIS2 transposition documents, and hyperscaler facility construction disclosures preceded structured interviews with data center security directors, systems integration project managers, BSI certification auditors, and biometric hardware procurement leads. Secondary validation drew from customs import records for security equipment, Federal Network Agency infrastructure filings, and colocation provider annual reports. Bottom-up deployment estimates across technology categories triangulated against top-down facility construction pipeline assessments.
Variance decomposition across technology, end user, solution, and installation type segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include BSI compliance tier, facility scale classification, and regional grid availability cluster. CAGRs were derived from installation pipeline tracking and replacement cycle analysis. Forecast inputs incorporated hyperscale construction permit timelines and BSI documentation completion rates.
Forecasts assume regulatory continuity in BSI IT-Grundschutz and EU NIS2 enforcement regimes; material policy shifts would require re-modeling. Specific risk factors include BSI Act amendment liability redefinitions, component supply disruptions from concentrated Asian manufacturing nodes, and hyperscale construction delays from grid interconnection bottlenecks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Data Center in Middle East Market
Data Center Infrastructure
Data Center IT Asset Disposition Market
Data Center Infrastructure
North America Data Center Infrastructure Management Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Germany Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Smart Data Center Market
Data Center Infrastructure
Malaysia Data Center Server Market