
 Data Center Rack Market | 2026-2036
Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Rack Market Intelligence
Chinese steel and aluminum capacity is restructuring global supply dynamics for rack enclosures and mounting infrastructure. Schneider Electric leverages vertical integration across power and thermal systems to sustain pricing power in premium rack configurations. Rittal anchors European manufacturing with precision sheet-metal capabilities and localized fabrication across Germany, Italy, and Spain. Eaton competes through channel density in North American enterprise and federal verticals.
A data center rack is a standardized metal framework, typically constructed from cold-rolled steel with perforated or solid doors, designed to house servers, networking equipment, and power distribution units in 19-inch or 23-inch mounting widths. Its primary purpose is to organize hardware vertically, enable cable management, and facilitate airflow for thermal control in computing environments. Enclosed racks command margin pools in enterprise and colocation settings where physical security and acoustic containment matter, while open frame variants lead in hyperscale cloud deployments where density and cooling efficiency override enclosure needs. Wall-mount and compact 1U-2U formats are accelerating in edge computing and telecommunications closets as latency-sensitive workloads decentralize from core facilities.
FCC equipment authorization rules shape electromagnetic compatibility requirements for rack-integrated power and networking gear in US deployments, while EU Ecodesign and RoHS frameworks restrict hazardous substances and mandate energy efficiency disclosures for rack systems sold in Europe. China's GB standards and MIIT directives govern structural load ratings and data center PUE thresholds that indirectly dictate rack density specifications. Stakeholders must monitor evolving thermal load ratings and regional certification divergence as AI servers push power per rack beyond traditional air-cooling thresholds.
Market Dynamics
AI server power densities are forcing rack architectures to accommodate liquid cooling manifolds and 100+ kW thermal loads, compressing legacy air-cooled designs into obsolescence across hyperscale and enterprise facilities.
Growth Catalysts
- EU Ecodesign mandates:Energy efficiency disclosure requirements for rack systems sold in Europe are accelerating replacement cycles in German and French colocation facilities.
- Hyperscale AI deployment:Cloud providers are expanding rack footprints to support GPU-intensive training clusters in Northern Virginia and Dallas-Fort Worth corridors.
- Steel capacity restructuring:Chinese aluminum and cold-rolled steel output shifts are lowering enclosure material costs for rack manufacturers serving Asian markets.
Market Restraints
- Copper and aluminum volatility:Input cost swings for busbar and thermal management components are compressing margin predictability for mid-tier rack suppliers.
- Supply concentration in East Asian sheet metal:Precision fabrication capacity clusters in Taiwan and South Korea create single-source vulnerability for high-density enclosure orders.
- Air-cooling thermal ceiling:Conventional HVAC-dependent rack designs face technical obsolescence as AI servers exceed 30 kW per chassis.
Strategic Opportunities
- Edge computing decentralization:Latency-sensitive workloads in secondary US metros and European Tier-2 cities are driving wall-mount and micro-rack demand outside core facilities.
- US IRA clean energy credits:Federal tax incentives for energy-efficient data center infrastructure are improving project economics for sustainable rack deployments.
- Liquid cooling convergence:Rear-door heat exchangers and immersion tank integration with standard 19-inch frames are opening premium configuration tiers.
Industry Challenges
- Thermal engineering talent scarcity:Rack vendors face recruitment gaps for computational fluid dynamics specialists capable of optimizing 100+ kW cabinet airflow.
- Multi-standard certification complexity:Divergent FCC electromagnetic compatibility, EU RoHS substance restrictions, and China GB structural load ratings extend product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Rack Market |
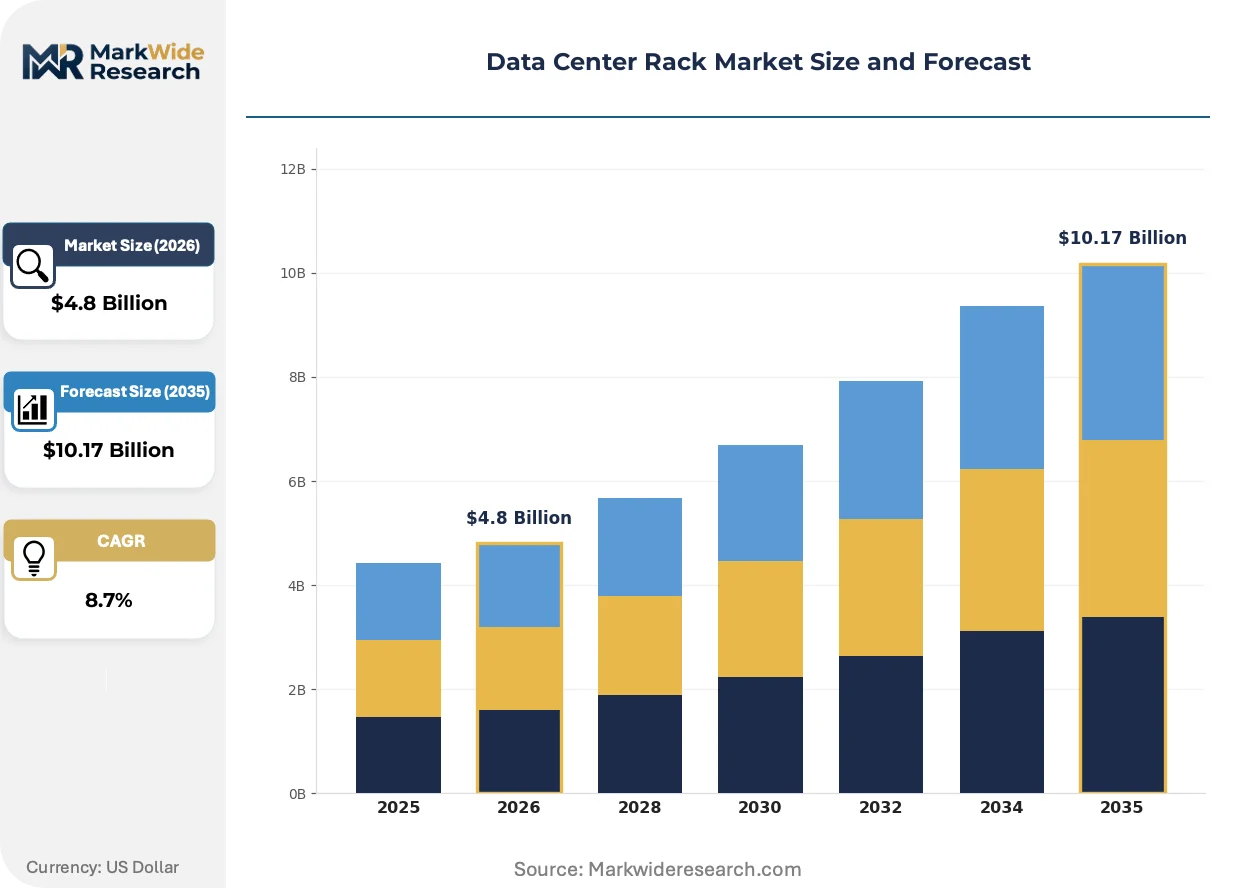
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Server Racks, Open Frame Racks, Enclosed Racks, Wall-Mount Racks Installation Type: On-Premises, Off-Site, Modular, Custom End User: Telecommunications, Cloud Providers, Enterprises, Colocation Facilities Size: 1U, 2U, 3U, 4U |
| Companies Covered | Schneider Electric, Hewlett Packard Enterprise, Rittal, Eaton, Vertiv Group Corp., Chatsworth Products, Dell Inc., Legrand, Panduit Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Rack Market Strategic Shifts & Innovations
Data center rack evolution is pivoting from passive enclosure functions to active thermal and power management integration, driven by AI workload densities and sustainability mandates.
Immersion cooling infrastructure is converging with traditional rack form factors to enable direct liquid contact with server components. Hyperscale operators in Singapore and the Netherlands are piloting sealed tank designs that repurpose standard 42U footprints. This convergence is compressing the distinction between rack and cooling system procurement.
China's MIIT directives on data center PUE thresholds are mandating real-time energy monitoring integration in rack-level power distribution units. Domestic operators must embed metering hardware that feeds provincial energy consumption dashboards. Rack suppliers serving the Chinese market are responding with pre-certified intelligent PDU configurations.
Leasing structures for rack-and-power bundles are displacing traditional capital purchase models in European colocation. Facility operators in Frankfurt and Amsterdam now offer metered rack-as-a-service contracts that transfer cooling efficiency risk to vendors. This shift is most visible among mid-market enterprises seeking to avoid stranded asset exposure during technology transitions.
Data Center Rack Market Segmentation
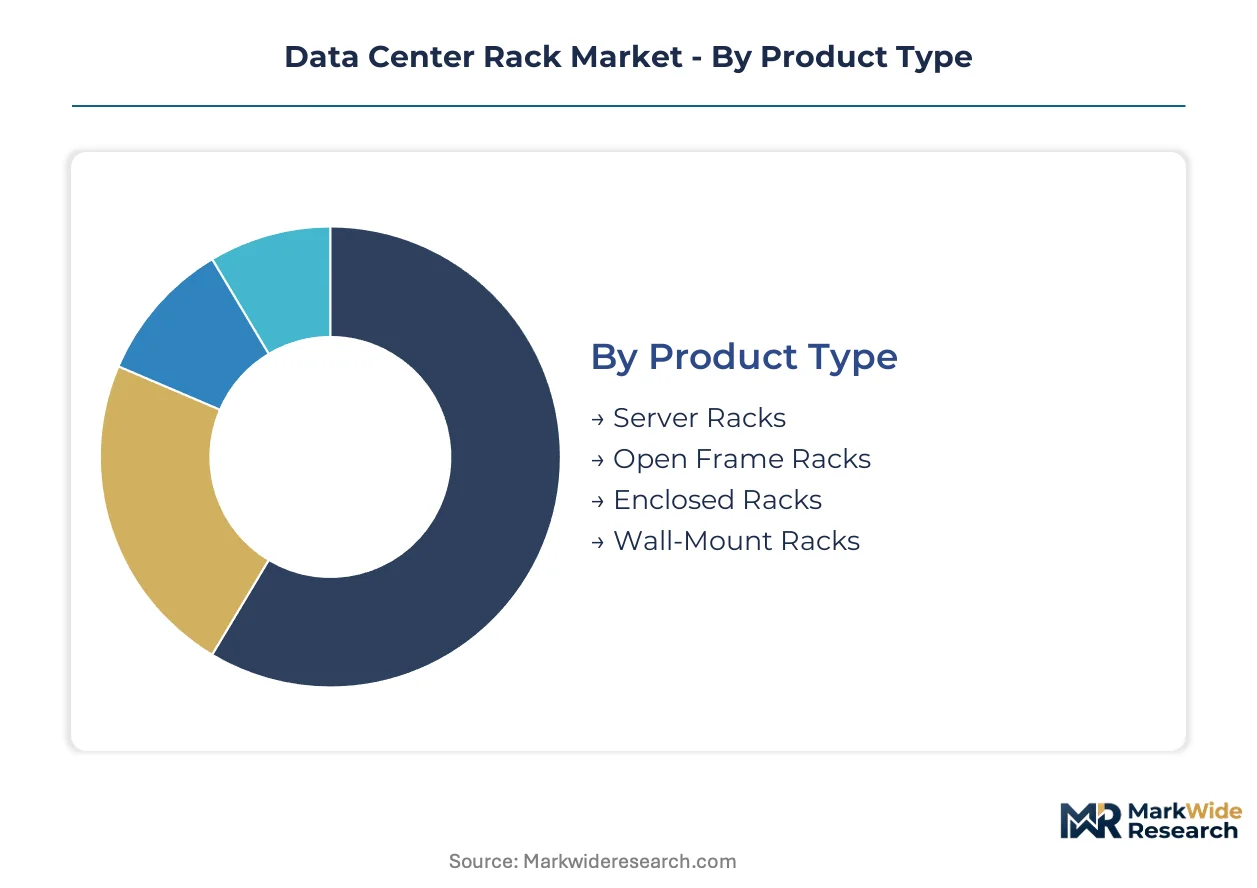
Data center rack segmentation reveals how procurement patterns diverge across deployment environments. Upgrade cycles and replacement timelines vary sharply between hyperscale cloud facilities and legacy enterprise server rooms.
Product Type:
Replacement cycles differ dramatically by enclosure architecture, with thermal load tolerance driving upgrade urgency more than physical wear.
- Server Racks:Standard 19-inch or 23-inch mounting frames constructed from cold-rolled steel, designed for high-density server deployment. Northern Virginia and Dallas-Fort Worth corridors concentrate procurement as cloud providers expand GPU-intensive training clusters. AI power densities above 30 kW per chassis are forcing premature replacement of air-cooled units.
- Enclosed Racks:Perforated or solid-door cabinets providing physical security and acoustic containment for enterprise and colocation settings. German and French facilities accelerate replacement cycles under EU Ecodesign mandates requiring energy efficiency disclosures.
- Open Frame Racks:Four-post designs maximizing airflow and cable access for hyperscale deployments where cooling efficiency overrides enclosure needs.
- Wall-Mount Racks:Compact vertical enclosures for telecommunications closets and edge computing sites in secondary US metros and European Tier-2 cities.
Server racks sit at the top of the volume ranking, with wall-mount racks climbing the fastest.
Installation Type:
Cost tier differentiation separates capital-intensive permanent builds from flexible operational expenditure models.
- On-Premises:Fixed infrastructure within enterprise-owned facilities requiring long-term depreciation schedules and facility-specific thermal engineering. Enterprises in regulated industries favor this model despite higher upfront capital requirements.
- Modular:Prefabricated rack-and-power units enabling rapid deployment and reconfiguration. Frankfurt and Amsterdam colocation operators now offer metered rack-as-a-service contracts transferring cooling efficiency risk to vendors.
- Off-Site:Third-party data center deployments where customers lease space without infrastructure ownership.
- Custom:Bespoke configurations for specialized workloads including liquid cooling manifolds and immersion tank integration.
On-premises retains the largest installed base, though modular installations are expanding most quickly.
End User:
Customer type determines specification priorities, with cloud providers demanding density optimization while enterprises emphasize physical security.
- Cloud Providers:Hyperscale operators procuring thousands of racks annually with standardized specifications for GPU-intensive AI workloads. Singapore and Netherlands facilities pilot sealed immersion cooling tanks repurposing standard 42U footprints.
- Enterprises:Corporate IT departments balancing legacy application support with gradual cloud migration. Mid-market enterprises seek to avoid stranded asset exposure during technology transitions.
- Colocation Facilities:Multi-tenant operators offering shared infrastructure with tiered service levels.
- Telecommunications:Network operators deploying edge infrastructure for latency-sensitive applications.
Cloud providers dominate procurement volume, with telecommunications gaining share fastest.
Size:
Application requirements dictate vertical space allocation, with compute density trends compressing traditional height preferences.
- 42U:Full-height cabinets serving as the standard for enterprise and hyperscale server deployment. China's MIIT directives on PUE thresholds mandate real-time energy monitoring integration in rack-level power distribution units.
- 48U:Extended-height configurations maximizing vertical space utilization in facilities with adequate ceiling clearance.
- 24U:Mid-size enclosures for departmental server rooms and smaller colocation deployments.
- 12U:Compact formats for edge computing sites and telecommunications closets.
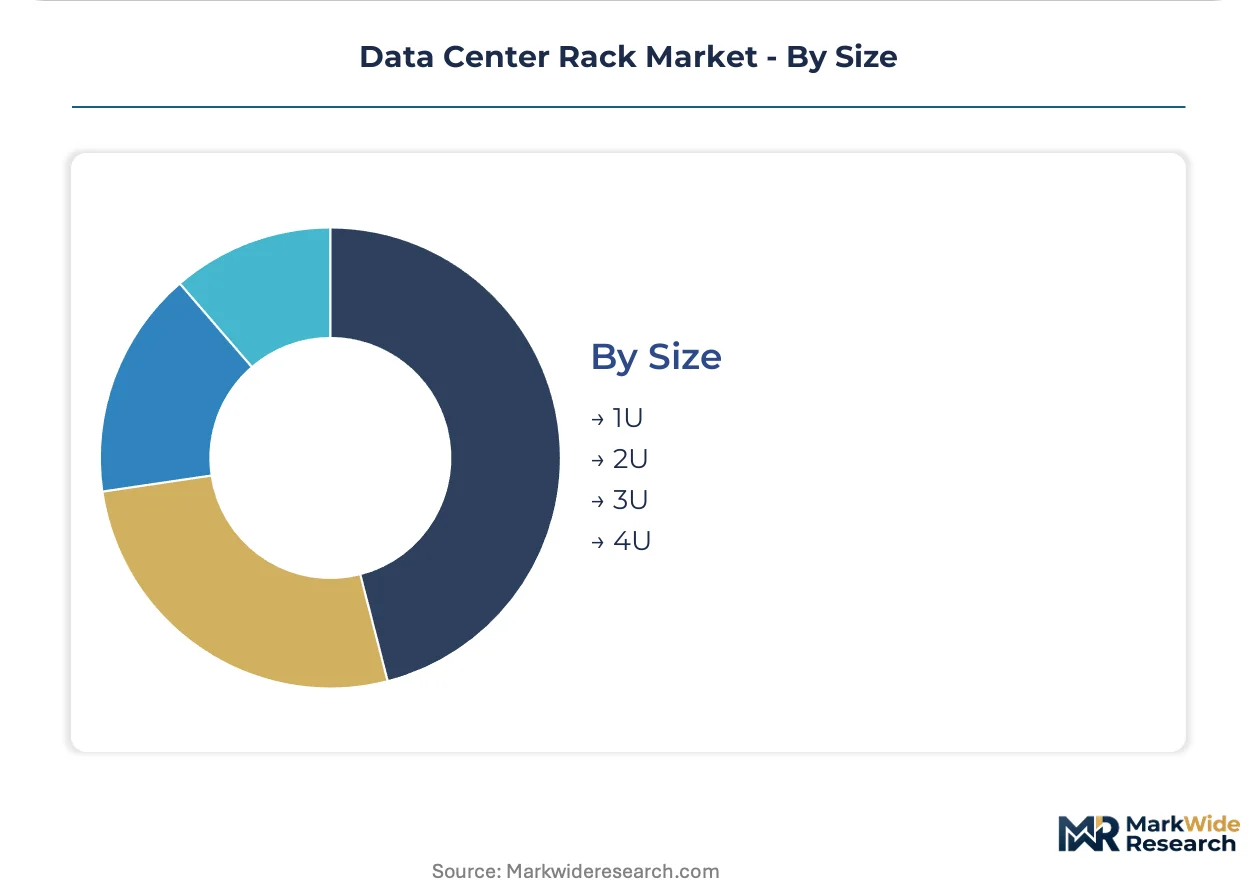
42U maintains volume leadership, while 12U formats show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping rack manufacturing footprints as producers migrate toward jurisdictions with favorable energy efficiency codes and steel input costs. Compliance cost gaps between EU Ecodesign jurisdictions and emerging Asian production bases are accelerating capacity relocation decisions.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth corridors are driving rack procurement for GPU-intensive AI training clusters. FCC equipment authorization rules govern electromagnetic compatibility for integrated power and networking gear. These Texas and Virginia data center clusters now absorb the majority of domestic 42U and 48U server rack deployments.
Germany
EU Ecodesign mandates are compressing replacement cycles in Frankfurt and Munich colocation facilities through mandatory energy efficiency disclosures. Rittal anchors European precision sheet-metal fabrication across Germany, Italy, and Spain. The Rhine-Main region around Frankfurt concentrates demand for enclosed rack configurations with acoustic containment specifications.
China
MIIT directives on data center PUE thresholds mandate real-time energy monitoring integration in rack-level power distribution units. GB standards govern structural load ratings that indirectly dictate rack density specifications. Yangtze River Delta and Pearl River Delta manufacturing clusters supply cold-rolled steel enclosures for domestic and export markets.
Singapore
Tropical climate constraints and land scarcity are accelerating liquid cooling rack adoption for AI workloads. The country's national energy regulator imposes strict data center efficiency standards that favor immersion cooling infrastructure. Sealed tank designs repurposing standard 42U footprints are now piloting in Singapore facilities alongside traditional air-cooled deployments.
Netherlands
Amsterdam colocation operators are pioneering metered rack-as-a-service contracts that transfer cooling efficiency risk to vendors. EU RoHS substance restrictions apply to all rack systems sold in Dutch facilities. The Amsterdam metro area serves as a secondary European hub for hyperscale deployments requiring rapid modular rack configuration.
Data Center Rack Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue liquid cooling integration and edge-computing form factors. The vendor base stratifies across three tiers: integrated infrastructure conglomerates with captive power and thermal portfolios, precision sheet-metal specialists with regional fabrication networks, and modular system integrators serving colocation-as-a-service transitions. Dominant competitive moves include backward integration into power distribution components and geographic expansion through local assembly partnerships.
Within the integrated infrastructure tier, Schneider Electric exemplifies the vertically diversified archetype spanning power, thermal, and enclosure systems. Rittal occupies a position among European precision fabricators with multi-country manufacturing footprints. Eaton represents the channel-dense North American enterprise specialist with federal vertical penetration.
| Leading Market Players |
|---|
| Schneider Electric |
| Hewlett Packard Enterprise |
| Rittal |
| Eaton |
| Vertiv Group Corp. |
| Chatsworth Products |
| Dell Inc. |
| Legrand |
| Panduit Corp. |
| Others |
Cost & Logistics Intelligence
Cold-rolled steel futures on the Shanghai Futures Exchange cascade through three distinct pricing tiers for rack enclosures, compressing margins for mid-tier fabricators while amplifying pricing power for vertically integrated producers with captive metal supply.
Pricing Analysis
Distributor margins spanning 15-25 percent separate direct-to-hyperscale OEM contracts from channel-served enterprise deployments. Three-tier pricing structure across premium liquid-cooled configurations, standard air-cooled cabinets, and economy open-frame designs stratifies procurement economics. Cost compression in the standard tier is intensifying because Chinese aluminum output shifts are lowering input costs for Asian-market suppliers. Cloud providers exhibit lowest price sensitivity due to volume scale, while mid-market enterprises negotiate hardest on per-unit rack economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for rack manufacturers serving multi-continental deployment schedules. Precision fabrication capacity clusters in Taiwan, South Korea, and Germany supply high-density enclosure orders with tight thermal tolerances. The supply chain rests on cold-rolled steel, aluminum extrusions, and copper busbar as core material inputs. Single-source vulnerability in Taiwanese sheet-metal stamping creates structural risk for liquid-cooled manifold orders. Distribution runs through direct OEM relationships for hyperscale volumes and value-added resellers for enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where AI-driven thermal density specifications are forcing premature replacement of legacy air-cooled infrastructure.
For Market Incumbents: Lock in captive supply of precision sheet-metal capacity across Germany, Italy, and Spain to defend margin position against Chinese cost-competitive entrants. Accelerate certification investment for FCC electromagnetic compatibility and EU Ecodesign energy efficiency disclosures to create switching costs. The threat of liquid-cooled manifold specialists capturing premium configuration tiers demands preemptive R&D allocation to rear-door heat exchanger integration. For New Entrants and Emerging Players: US IRA clean energy credits in the United States open a window for sustainable rack deployments targeting mid-market enterprises seeking to avoid stranded asset exposure. White-space opportunities concentrate in wall-mount and micro-rack formats for European Tier-2 cities and secondary US metros. Edge computing decentralization represents the most penetrable demand vector. A go-to-market angle anchored in metered rack-as-a-service contracts transfers cooling efficiency risk and accelerates customer acquisition. For Investors and Strategic Acquirers: Asymmetric upside sits with precision sheet-metal specialists possessing liquid-cooled manifold engineering capabilities and multi-country fabrication footprints. Long-term viability hinges on thermal engineering talent depth and regional certification breadth rather than commodity enclosure volume. The acquisition target archetype combines European precision fabrication with Asian cost-competitive steel sourcing. Watch hyperscaler capex announcements for GPU-intensive training clusters as the inflection signal for premium rack demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Distribution Components | Captive PDU production secures margin pools in intelligent metering configurations required by China's MIIT directives. |
| Liquid Cooling Manifold Certification | UL and CE marking for rear-door heat exchangers unlocks premium-tier procurement from Northern Virginia hyperscale operators. |
| Regional Assembly Partnership Expansion | Local fabrication in Dallas-Fort Worth and Frankfurt compresses logistics costs for time-sensitive AI cluster deployments. |
| Intelligent PDU Platform Launch | Real-time energy monitoring integration addresses Chinese PUE threshold mandates and European Ecodesign disclosure requirements. |
| Edge Computing Form Factor Development | Compact 12U and wall-mount designs capture latency-sensitive workload decentralization in secondary metros. |
Research Approach
Bottom-up data center operator modeling reconciled against top-down rack manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hyperscale procurement directors, colocation facility operators, thermal engineering specialists, and sheet-metal fabrication plant managers combined with secondary validation against SEC filings, customs trade data, hyperscaler capex disclosures, and MIIT energy consumption dashboards. Triangulation between demand-side deployment schedules and supply-side capacity utilization rates ensures cross-verified volume estimates.
Input-output matrices map rack unit demand to AI server deployment trajectories, cloud provider expansion timelines, and enterprise refresh cycles across the projection horizon. Segmentation dimensions include enclosure architecture, installation type, end-user category, and vertical space allocation. CAGRs derive from regression analysis of historical replacement cycles against AI power density inflection points. Forecast inputs incorporate liquid cooling adoption curves and regional PUE regulatory thresholds without year-specific assumptions.
Revisions become necessary when hyperscaler capex plans shift, steel and aluminum input costs experience sustained volatility, or liquid cooling technology standards crystallize differently than modeled. Forecasts reflect documented assumptions around thermal load trajectories and certification timeline convergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Rack Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Data Center in Japan Market
Data Center Infrastructure
Hong Kong Data Center Construction Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Europe Data Center Colocation Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
Global Cloud Infrastructure Service Market
Data Center Infrastructure
Vietnam Data Center Rack Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
Netherlands Data Center Physical Security Market
Data Center Infrastructure
United States Data Center Market