
 Norway Data Center Server Market | 2026-2036
Norway Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Server Market Insights
EU Green Deal carbon-border adjustments are repositioning data center build-out economics in Norway, favoring operators with documented renewable power sourcing. Dell Technologies leverages its Nordic distribution network to sustain rapid configuration turnaround for enterprise rack deployments. Green Mountain AS anchors its competitive stance through hydroelectric-powered facilities near Rjukan and Stavanger. Hewlett Packard Enterprise differentiates via liquid-cooled server architectures suited to Norway's ambient temperature advantages.
A data center server is a high-availability computing device engineered with redundant power supplies, ECC memory, and enterprise-grade processors to host virtualized workloads and persistent data storage for networked client systems. These systems typically operate at 200-240V input with N+1 redundancy and thermal design power envelopes exceeding 150W per CPU, serving as the foundational infrastructure for cloud computing, enterprise resource planning, and artificial intelligence training pipelines. Rack servers dominate Norwegian enterprise procurement due to standardization benefits and density optimization in existing facilities, while blade server configurations are gaining traction among colocation providers seeking to maximize compute per square meter in Oslo's constrained real estate environment. Hybrid deployment models capture expanding margin pools as regulated industries balance sovereignty requirements with burst-capacity needs.
Norwegian Water Resources and Energy Directorate permitting processes govern hydroelectric allocation for data center loads, while BIS-equivalent electrical safety standards and EU F-Gas Regulation constrain cooling system refrigerant selection. These frameworks elevate capital requirements for new entrants while insulating incumbent operators with certified infrastructure. Stakeholders must monitor proposed revisions to national grid tariff structures that could alter the cost calculus of baseload server operations versus intermittent renewable sourcing.
Market Dynamics
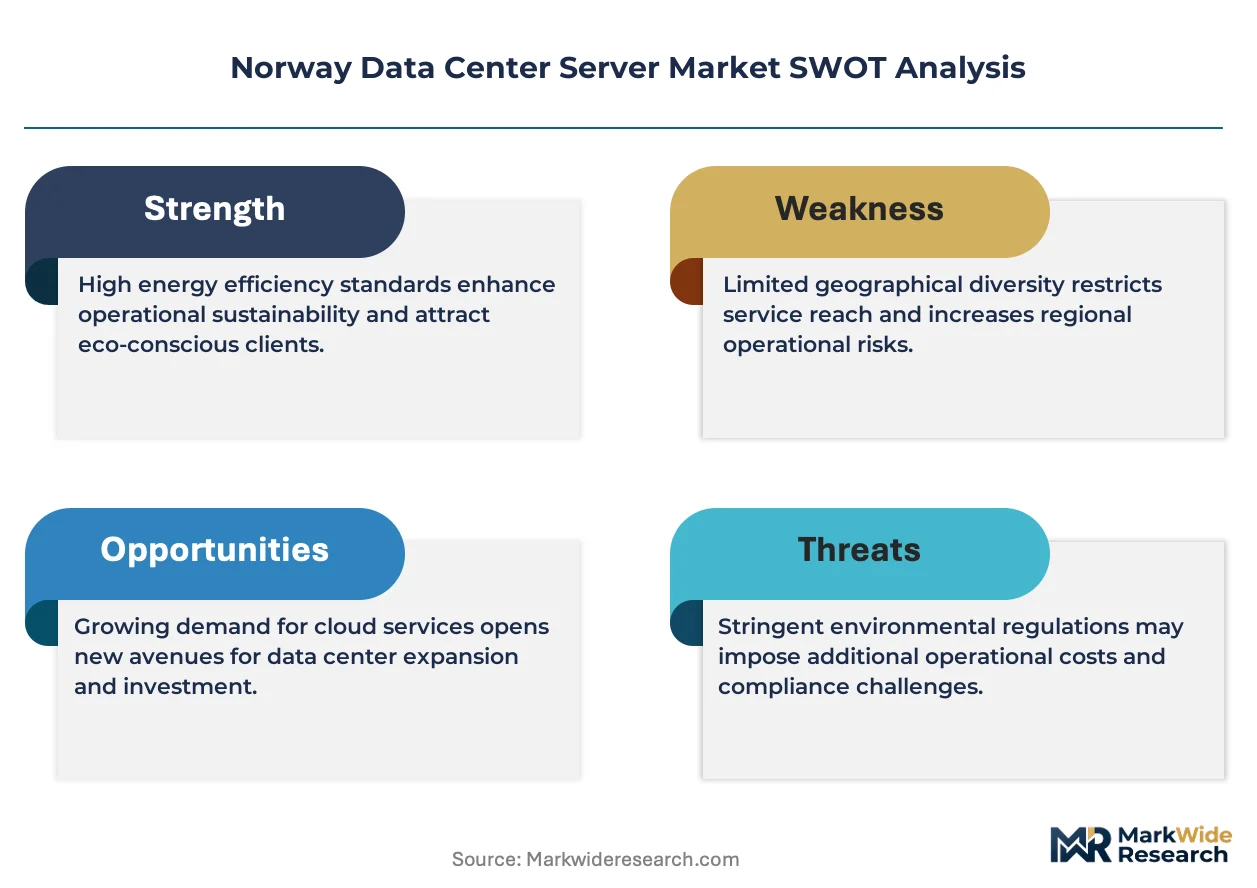
Hydroelectric power allocation under Norwegian Water Resources and Energy Directorate permitting is concentrating server deployment decisions around grid interconnection points with documented renewable sourcing. This structural force elevates capital barriers for new entrants while rewarding incumbent operators with certified infrastructure.
Growth Catalysts
- Real-time payment infrastructure:Norwegian financial institutions are expanding server deployments to support instant settlement systems. This creates sustained demand for low-latency compute clusters in the Oslo corridor.
- EU AI Act compliance:Automated decision-making systems require documented hosting infrastructure. Nordic facilities with certified audit trails capture migration flows from less regulated jurisdictions.
- Liquid cooling adoption:Ambient temperature advantages enable free cooling architectures. Operators near Rjukan and Stavanger leverage this to reduce mechanical refrigeration dependency.
Market Restraints
- Grid tariff uncertainty:Proposed revisions to national grid tariff structures could alter baseload server economics. Intermittent renewable sourcing becomes cost-competitive against firm hydroelectric contracts.
- F-Gas Regulation constraints:EU F-Gas Regulation limits cooling system refrigerant selection. Legacy fluorinated gas infrastructure faces accelerated obsolescence and replacement capex.
- Oslo real estate scarcity:Constrained commercial space in the metropolitan corridor limits facility expansion. Colocation providers compete for finite square meterage with residential and commercial development.
Strategic Opportunities
- Edge compute in northern Norway:Troms and Finnmark offer sub-20ms latency to Arctic shipping routes. Subsea cable landing stations create interconnection nodes for maritime logistics applications.
- EU Green Deal carbon-border alignment:Documented renewable power sourcing qualifies Norwegian exports for preferential treatment. Carbon-intensive compute from continental Europe faces competitive displacement.
- Blade server density optimization:Colocation providers maximize compute per square meter in space-constrained facilities. Standardized blade configurations reduce deployment timelines versus custom rack builds.
Industry Challenges
- Electrical certification timelines:BIS-equivalent electrical safety standards require extended approval cycles for imported equipment. Equipment vendors face working capital compression during customs clearance.
- Legacy system integration:Financial institutions maintain mainframe-dependent core banking systems. Hybrid cloud architectures require middleware development for transaction integrity across environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Server Market |
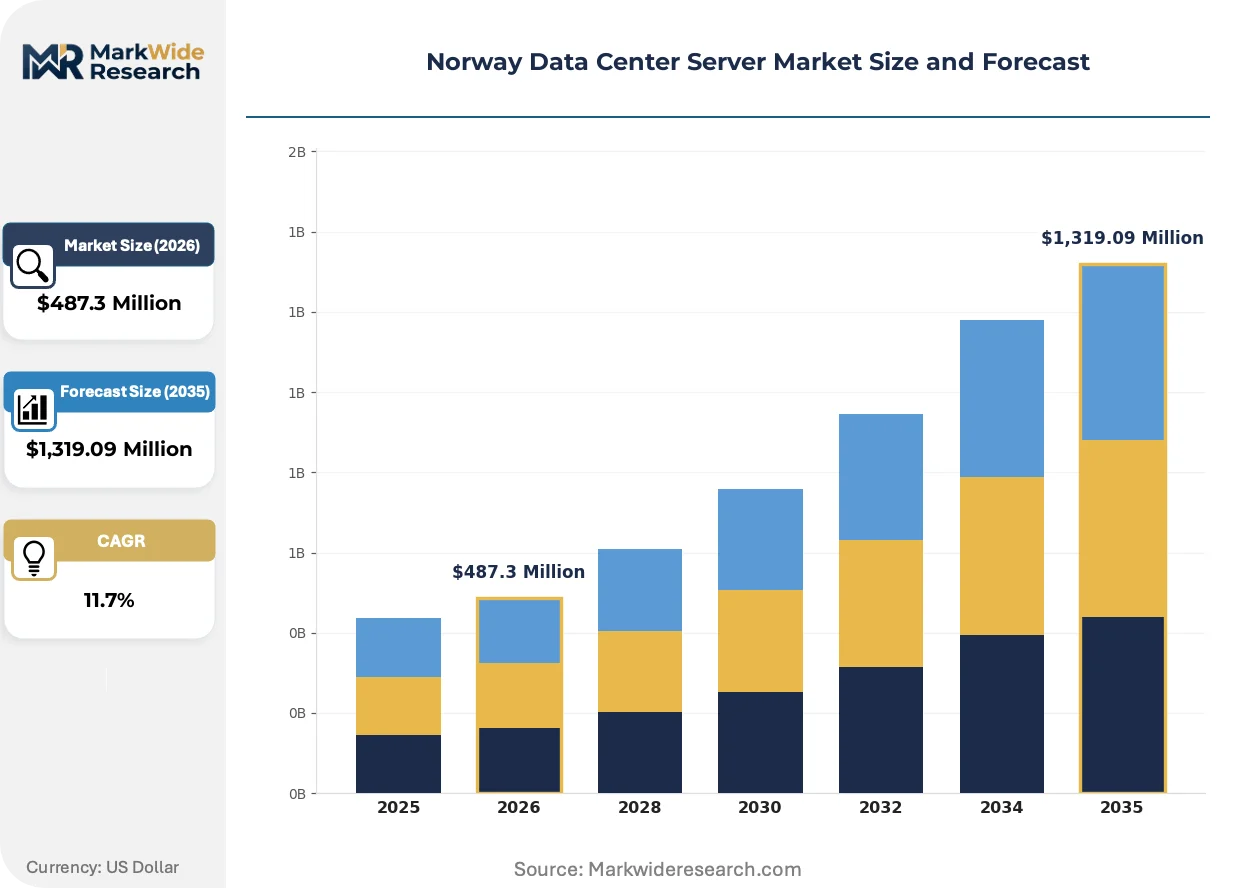
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Server Type: Rack Servers, Blade Servers, Tower Servers, Microservers Deployment Model: On-Premises, Cloud, Hybrid, Colocation Service Type: Managed Services, Unmanaged Services, Professional Services, Cloud Services End User: IT Enterprises, Government, BFSI, Healthcare |
| Companies Covered | Cisco Systems, Fujitsu, Dell Technologies, Equinix, IBM, Hewlett Packard Enterprise, Supermicro, Green Mountain AS, Lenovo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Server Market Trends and Innovations
Server architecture decisions in Norway are converging around thermal efficiency and regulatory documentation requirements. Operators prioritize technologies that reduce mechanical cooling load while generating auditable compliance records.
Direct liquid cooling is integrating high-density GPU clusters into existing facilities without mechanical refrigeration expansion. AI training workloads from European enterprises adopt this architecture to bypass F-Gas Regulation constraints on traditional chillers. The technology is compressing facility design cycles from 24 months to 14 months for comparable compute density.
EU AI Act documentation mandates are forcing hosting providers to implement immutable audit logging for automated decision systems. Financial services and public sector procurement now require chain-of-custody verification for training data and model weights. Norwegian facilities with pre-certified compliance frameworks capture premium positioning against uncertified competitors.
Consumption-based billing models are displacing traditional colocation lease structures among mid-market enterprises. Buyers prefer metered compute with burst capacity guarantees over fixed rack commitments. This shift concentrates in Oslo's financial services cluster where treasury functions demand operational expenditure treatment for infrastructure.
Norway Data Center Server Market Segmentation
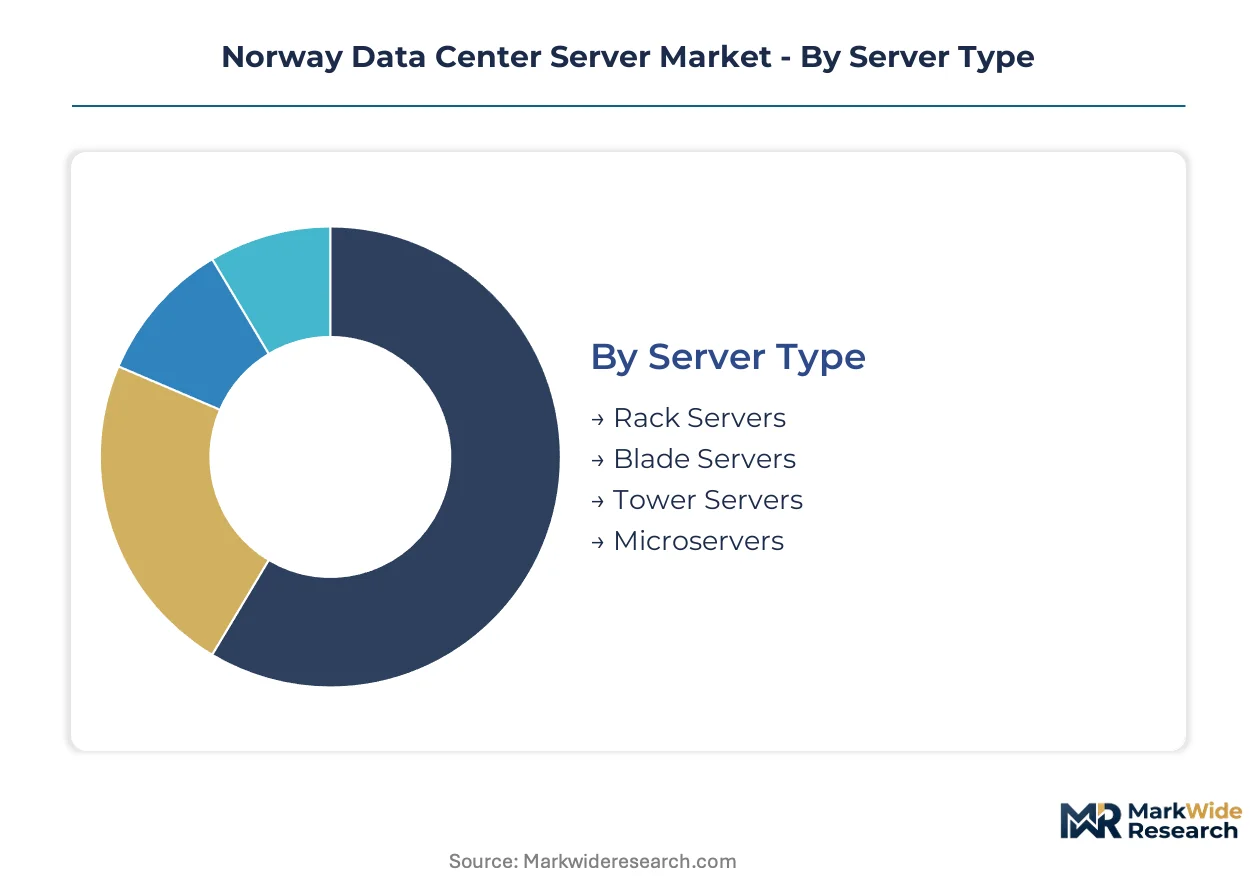
Server procurement in Norway diverges sharply between standardized configurations for rapid deployment and engineered-to-order systems for specialized workloads. Segmentation reveals how hydroelectric access, EU AI Act compliance, and real estate constraints reshape buying patterns across deployment models and service tiers.
Server Type:
Standardization dominates at the commodity end while liquid-cooled variants command premium positioning for AI training clusters.
- Rack Servers:These units mount in 19-inch cabinets with standardized rail kits and hot-swappable components. Norwegian enterprises in the Oslo corridor favor rack configurations for their interoperability with existing raised-floor facilities and rapid procurement cycles through Dell Technologies' Nordic distribution network.
- Blade Servers:Shared infrastructure enclosures consolidate power, cooling, and networking across multiple server nodes. Colocation providers in space-constrained Oslo facilities adopt blade architectures to maximize compute per square meter while meeting EU F-Gas Regulation constraints through consolidated cooling loops.
- Tower Servers:Standalone pedestal configurations serve branch office deployments and small-scale edge computing in northern Norway municipalities.
- Microservers:Ultra-dense, low-power nodes target distributed edge workloads and lightweight container orchestration near subsea cable landing stations.
Leading the category by volume: Rack Servers. Growing fastest: Blade Servers.
Deployment Model:
Cost tier stratification separates capital-intensive ownership from operational expenditure models favored by financial services treasury functions.
- On-Premises:Enterprise-owned facilities with dedicated electrical infrastructure and N+1 redundancy. BFSI institutions in Oslo maintain on-premises deployments for core banking systems requiring sub-millisecond latency and sovereign data control under EU AI Act documentation mandates.
- Cloud:Hyperscaler-hosted compute with metered consumption billing. Mid-market enterprises prefer cloud for burst capacity and operational expenditure treatment, though Norwegian Water Resources and Energy Directorate permitting creates regional availability constraints.
- Hybrid:Orchestrated workloads spanning owned infrastructure and cloud resources. Regulated industries deploy hybrid architectures to balance transaction integrity requirements with elastic demand spikes from real-time payment infrastructure.
- Colocation:Leased space in third-party facilities with shared power and cooling infrastructure. Green Mountain AS and comparable operators near Rjukan attract tenants seeking documented hydroelectric sourcing for EU Green Deal carbon-border alignment.
Highest capital commitment: On-Premises. Most rapid volume expansion: Hybrid.
Service Type:
Customer type determines service bundling — financial institutions demand outcome-based managed services while technology firms self-operate unmanaged infrastructure.
- Managed Services:Full-stack operational responsibility including hardware maintenance, security patching, and capacity planning. IT Enterprises with limited in-house infrastructure expertise contract managed services to meet EU AI Act audit trail requirements without dedicated platform engineering teams.
- Unmanaged Services:Raw infrastructure access with tenant-operated software layers. Technology companies and cloud-native startups favor unmanaged colocation for cost control and custom architecture autonomy.
- Professional Services:Project-based consulting for migration, integration, and optimization engagements.
- Cloud Services:Abstracted platform and software layers with consumption-based billing and automatic scaling.
Widest margin pool: Managed Services. Steepest expansion trajectory: Cloud Services.
End User:
Application criticality drives specification divergence — transaction systems demand fault tolerance while analytics workloads prioritize throughput density.
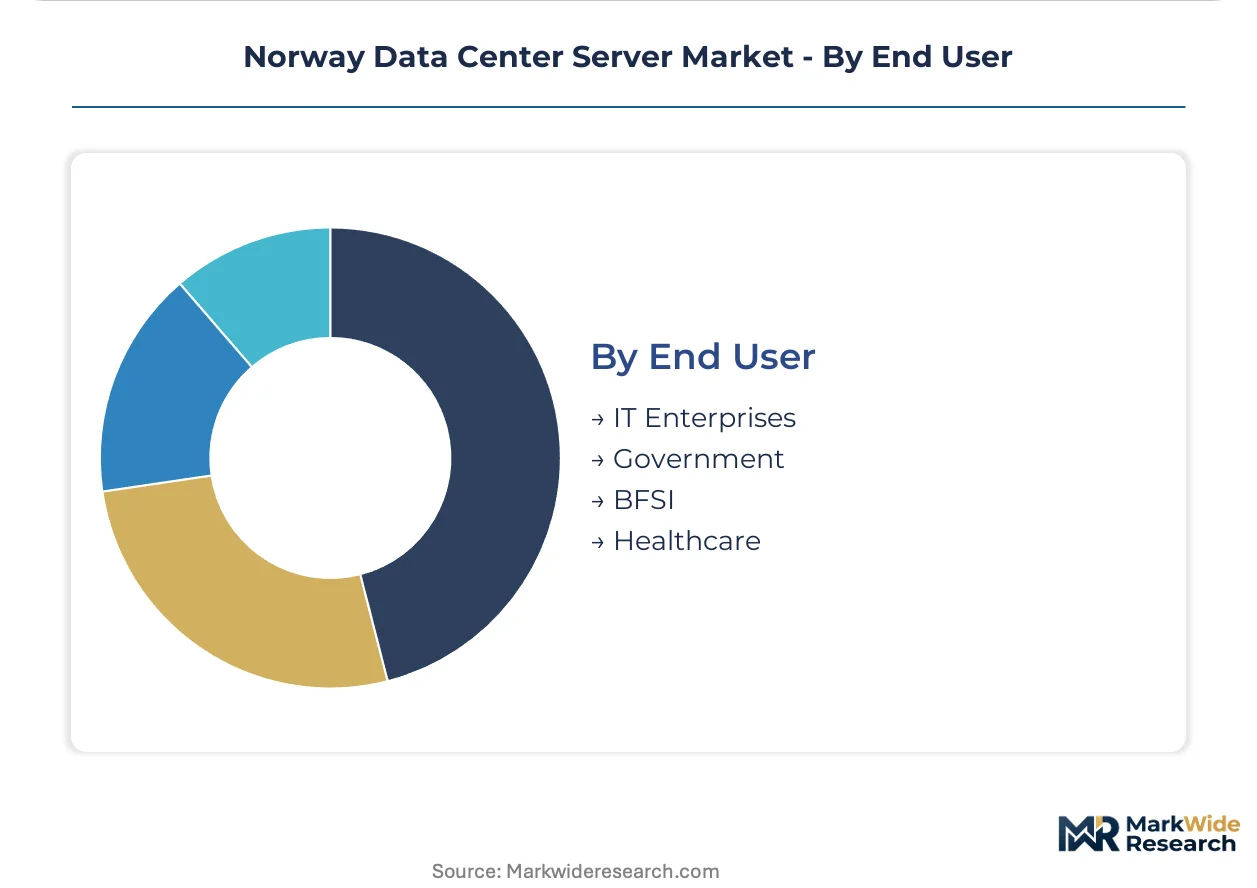
- BFSI:Banking, financial services, and insurance institutions operate the most demanding latency and availability requirements. Norwegian banks expanding real-time payment infrastructure deploy specialized server configurations with redundant power feeds and immutable logging for EU AI Act compliance.
- IT Enterprises:Technology companies and corporate IT departments span diverse workload profiles from enterprise resource planning to AI model training. This segment shows highest adoption of liquid-cooled architectures to bypass F-Gas Regulation constraints on mechanical refrigeration.
- Government:Public sector procurement emphasizes certified supply chains and data sovereignty for citizen services and national security applications.
- Healthcare:Medical imaging, electronic health records, and research computing drive demand for high-memory configurations and HIPAA-equivalent data protection.
Most stringent compliance requirements: BFSI. Fastest infrastructure refresh cycles: IT Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center deployment concentrates around Norway's hydroelectric-rich corridors where Norwegian Water Resources and Energy Directorate permitting accelerates renewable power allocation for compute loads.
Oslo Metropolitan Corridor
Financial institutions drive server procurement for real-time payment infrastructure with sub-millisecond latency requirements. EU AI Act documentation mandates favor facilities with certified audit trails in this zone. Fiber density and renewable energy access converge in Oslo's Fornebu and Nydalen districts where colocation providers compete for constrained commercial real estate.
Rjukan Industrial Valley
Heavy industry legacy infrastructure repurposes for data center loads seeking documented hydroelectric sourcing. Norwegian Water Resources and Energy Directorate grid interconnection permits process faster here due to existing transmission capacity. Green Mountain AS anchors operations near this Telemark cluster leveraging ambient temperature advantages for free cooling architectures.
Stavanger Energy Hub
North Sea oil and gas sector data processing creates demand for high-availability compute with sovereign data controls. EU F-Gas Regulation constraints on cooling refrigerants favor liquid-cooled deployments in this region. Subsea cable landing stations at Tananger create interconnection nodes for maritime logistics and energy sector applications.
Troms Arctic Edge
Sub-20 millisecond latency to Arctic shipping routes positions this northern zone for maritime logistics edge compute. Tromsø municipal utilities offer competitive power tariffs to attract data center investment away from the Oslo corridor. Cold ambient temperatures year-round eliminate mechanical refrigeration for a significant portion of annual operating hours.
Bergen Western Gateway
Subsea cable connectivity to the UK and continental Europe makes this Norway's primary data transit hub. Financial services backup and disaster recovery operations favor the geographic separation from Oslo's concentration risk. Local grid constraints limit hyperscale expansion but attract boutique colocation for compliance-sensitive workloads.
Norway Data Center Server Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Norway's data center server market. The vendor base spans three distinct tiers: global hardware manufacturers with Nordic distribution networks, regional colocation operators with certified renewable infrastructure, and specialized system integrators serving regulated industries. Consolidation pressures favor operators with documented hydroelectric sourcing and pre-certified EU AI Act compliance frameworks. Strategic moves center on liquid cooling technology partnerships and edge compute node establishment in northern municipalities.
Among global hardware manufacturers, Dell Technologies and Hewlett Packard Enterprise represent the diversified infrastructure archetype with established Nordic configuration and support capabilities. Green Mountain AS occupies a distinct position as a regional pure-play operator leveraging hydroelectric-powered facilities near Rjukan and Stavanger. These three entities exemplify the competitive tension between scale-driven global supply chains and sustainability-certified local infrastructure.
| Leading Market Players |
|---|
| Cisco Systems |
| Fujitsu |
| Dell Technologies |
| Equinix |
| IBM |
| Hewlett Packard Enterprise |
| Supermicro |
| Green Mountain AS |
| Lenovo |
| Others |
Pricing and Supply Chain Analysis
Sovereign-wealth-backed infrastructure operators and family-owned regional colocation specialists dominate Norway's data center ownership structure, embedding supply discipline through long-dated power purchase agreements while compressing margin pools for equipment vendors competing on standardized rack configurations.
Pricing Analysis
Premium pricing attaches to configurations with sub-14-day lead times through Dell Technologies' Nordic distribution network, while spot inventory of prior-generation Intel Xeon processors trades at discount to clear working capital. Three-tier pricing structure across certified-liquid-cooled, standard-air-cooled, and legacy-refresh configurations separates hyperscale tenants from mid-market enterprises and branch-office deployments. Cost compression in standard rack configurations is intensifying because Norwegian Water Resources and Energy Directorate permitting delays extend facility commissioning timelines, stretching vendor receivables cycles. Financial services buyers in Oslo exhibit lowest price sensitivity due to EU AI Act compliance premiums, while municipal governments in northern Norway negotiate hardest on per-unit capital expenditure.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Germany feed Norwegian procurement through hub-and-spoke patterns, with final-mile configuration occurring at Dell Technologies' Nordic assembly facility near Copenhagen. Server manufacturing concentrates in Taiwan, China, and Mexico, with memory modules sourcing from South Korean fabs and power supply units from Chinese contract manufacturers. Single-source vulnerability sits with Intel and AMD processor allocation, where foundry capacity constraints at TSMC create 26-week order horizons for high-core-count SKUs. Distribution runs through value-added resellers with certified BIS-equivalent electrical safety capabilities, bypassing direct hyperscaler relationships that dominate continental European procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Norway data center server market functions as a cost-of-compliance arena where EU AI Act documentation mandates and Norwegian Water Resources and Energy Directorate permitting create defensive moats for operators with pre-certified infrastructure and documented hydroelectric sourcing.
For Market Incumbents: Anchor competitive position through exclusive liquid-cooling technology partnerships that bypass EU F-Gas Regulation constraints on mechanical refrigeration, while securing 10-year power purchase agreements at Rjukan and Stavanger grid interconnection points to lock in renewable sourcing credentials against tariff uncertainty. Threat of intermittent renewable sourcing cost-competitiveness demands accelerated certification investment for immutable audit logging capabilities. For New Entrants and Emerging Players: Begin with edge compute deployments in Troms and Finnmark municipalities where sub-20ms Arctic shipping latency remains uncontested by Oslo corridor incumbents, leveraging municipal utility tariff competition and ambient temperature advantages that eliminate mechanical cooling capex. White-space concentration in maritime logistics applications near Tananger subsea cable landing stations offers the most penetrable entry vector, with go-to-market positioning around consumption-based billing models that displace fixed colocation leases among mid-market treasury functions. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional pure-play operators with certified hydroelectric infrastructure in Telemark and Rogaland counties, where grid tariff uncertainty may force asset restructuring among overleveraged facilities lacking long-dated power contracts. Long-term viability over the coming decade hinges on EU Green Deal carbon-border alignment credentials that qualify Norwegian compute exports for preferential treatment against continental European carbon-intensive alternatives. Signal to monitor: proposed revisions to national grid tariff structures that would invert baseload server economics toward intermittent renewable sourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Technology Partnership | Enables GPU cluster deployment without EU F-Gas Regulation mechanical refrigeration constraints. |
| Hydroelectric Power Purchase Agreement | Locks documented renewable sourcing for EU Green Deal carbon-border alignment certification. |
| Immutable Audit Logging Implementation | Captures EU AI Act compliance premiums from financial services migration flows. |
| Edge Compute Node Establishment | Exploits Troms ambient temperature advantages and Arctic shipping route latency positioning. |
| Consumption-Based Billing Platform | Aligns with financial services treasury demand for operational expenditure infrastructure treatment. |
Research Methodology
Document review covered Norwegian Water Resources and Energy Directorate permitting databases, EU F-Gas Regulation implementation guidance, and hyperscaler capex disclosures, complemented by interviews with data center facility directors, IT procurement officers at BFSI institutions, Dell Technologies Nordic channel partners, and Green Mountain AS operations executives. Secondary validation drew from SEC filings of listed server manufacturers, Norwegian grid operator tariff consultation documents, and EU AI Act compliance framework publications. Bottom-up equipment shipment analysis triangulated against top-down facility power allocation permits.
Cross-referencing historical deployment patterns against panel input from colocation operators and enterprise infrastructure architects shaped the analytical framework across the projection horizon. Segmentation modeling incorporated server type, deployment model, service tier, and end-use vertical dimensions alongside regional hydroelectric grid interconnection capacity as a Norway-specific constraint variable. CAGRs derived from power allocation permit trajectories and real-time payment infrastructure investment disclosures.
Underlying measurement precision varies by segment; Oslo metropolitan corridor deployments carry tighter precision than northern Norway edge compute projections due to permitting transparency differentials. Forecasts reflect documented assumptions around grid tariff stability and EU AI Act enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
France Data Center Storage Market
Data Center Infrastructure
Norway Data Center Construction Market
Data Center Infrastructure
Public Cloud System Infrastructure Service Market
Data Center Infrastructure
Data Center Generator Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Europe Data Center Physical Security Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Switzerland Data Center Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
Israel Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Vietnam Data Center Market