
 Global Edge Data Center Market | 2026-2036
Global Edge Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Global Edge Data Center Market Foresight
Aftermarket service revenue is fragmenting across distributed infrastructure operators as edge deployments multiply. Schneider Electric leverages its integrated power and cooling portfolio to capture recurring maintenance contracts. Vertiv anchors its position through thermal management specialization for compact deployments. Huawei Technologies competes on modular prefabrication capabilities that compress deployment timelines for telecommunications providers.
Edge data centers are compact, geographically distributed computing facilities typically housing 100 kilowatts to 2 megawatts of IT capacity, positioned within 10-20 milliseconds of latency from end users to support real-time processing. These facilities employ precision cooling, redundant power architectures, and software-defined networking to enable localized computation for latency-sensitive workloads. Colocation deployments command the widest addressable customer base as enterprises avoid capital-intensive facility ownership. AI & Machine Learning applications are pulling the fastest capacity growth as inference workloads migrate closer to data sources. Micro Data Centers occupy a specialized niche in manufacturing environments where space constraints and harsh conditions predominate.
The EU AI Act imposes risk-based compliance tiers on automated decision-making infrastructure, compelling facility operators to document data governance and physical security controls. ISO 27001 and IEC 62443 standards govern information security and operational technology cybersecurity for distributed computing assets, creating certification barriers for new entrants. The U.S. EPA and state-level public utility commissions are tightening energy efficiency disclosure requirements for data center power usage effectiveness ratios. Stakeholders must weigh sovereign data residency mandates against modular standardization economics when selecting deployment geographies.
Market Dynamics
Latency requirements from autonomous vehicle manufacturers and real-time AI inference workloads are compressing deployment timelines and reshaping facility specifications across distributed compute infrastructure.
Growth Catalysts
- EU AI Act compliance mandates:Risk-based tiers for automated decision-making infrastructure compel facility operators to upgrade physical security and data governance controls, expanding retrofit demand.
- Telecommunications 5G densification:Mobile network operators require localized compute nodes within 10-20 milliseconds of end users to support ultra-reliable low-latency communications.
- Germany's Frankfurt-Rhine-Main corridor concentration:Enterprise demand clusters in this latency-optimized zone, pulling adjacent facility investment across the Rhine-Main metropolitan region.
Market Restraints
- Precision cooling supply concentration:Thermal management component fabrication concentrates among limited specialized suppliers, creating input bottlenecks for compact deployments.
- F-Gas Regulation phase-down schedules:Europe's hydrofluorocarbon reduction mandates constrain refrigerant options for edge cooling systems, elevating engineering complexity.
- Power usage effectiveness disclosure requirements:U.S. EPA and state utility commission mandates impose reporting burdens that disadvantage smaller distributed operators lacking measurement infrastructure.
Strategic Opportunities
- India's smart city infrastructure programs:Municipal digitization initiatives create demand for micro data centers in urban environments with severe space constraints.
- Industrial IoT convergence with edge AI:Manufacturing environments require ruggedized compact compute for predictive maintenance and quality inspection workloads.
- Japan's METI energy efficiency incentives:Subsidies for low-carbon distributed computing accelerate deployment of liquid-cooled edge facilities in Tokyo-Osaka corridors.
Industry Challenges
- OT/IT cybersecurity skill convergence:IEC 62443 implementation requires professionals fluent in both operational technology and information security protocols, a combination scarce in labor markets.
- ISO 27001 certification timeline compression:Accelerated facility deployment schedules conflict with multi-month audit and documentation requirements for information security management.
- Legacy building integration complexity:Retrofitting existing commercial and industrial structures for redundant power architectures and precision cooling often exceeds greenfield construction costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Edge Data Center Market |
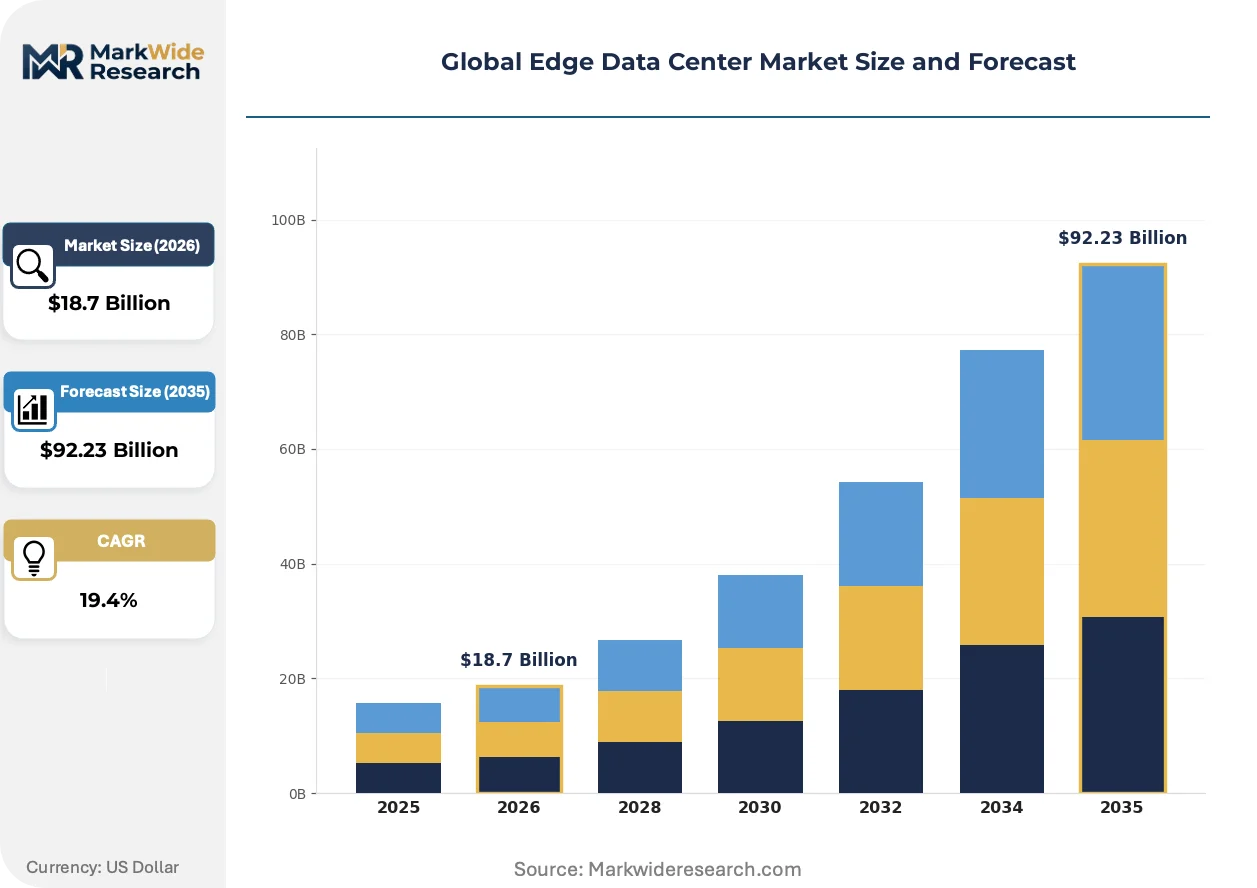
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Colocation, Hyperscale, Micro Data Centers, Modular Units Application: Content Delivery, IoT Analytics, AI & Machine Learning, Virtual Reality, Autonomous Systems End User: Telecommunications Providers, Cloud Service Operators, Manufacturing Firms, Public Sector Agencies, Financial Institutions Solution Type: Infrastructure Management, Cooling Systems, Security & Compliance, Power Supply, Network Connectivity |
| Companies Covered | Schneider Electric, Vertiv, Huawei Technologies, Equinix, Eaton, Dell Technologies, Hewlett Packard Enterprise Company, Digital Realty, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Edge Data Center Market Shifts & Advancements
Modular prefabrication and software-defined infrastructure are compressing traditional data center construction timelines while regulatory pressure on energy disclosure intensifies facility design constraints.
Immersion cooling systems are collapsing thermal management footprints for high-density AI inference racks. Autonomous vehicle manufacturers are adopting these systems for roadside compute nodes. Deployment timelines compress from months to weeks as factory-integrated cooling eliminates on-site mechanical commissioning.
CSRD mandates in Europe require granular energy consumption disclosure from distributed computing assets. Facility operators must install continuous monitoring infrastructure to report scope emissions. Colocation providers in Germany and France are restructuring contracts to pass compliance costs through to enterprise tenants.
Enterprise buyers are unbundling after-sales service contracts from initial hardware procurement. Manufacturing and automotive end-users now source maintenance separately through third-party service integrators. This fragmentation is most pronounced in Germany's industrial corridor, where specialized thermal management technicians command premium contracting rates.
Global Edge Data Center Market Segmentation
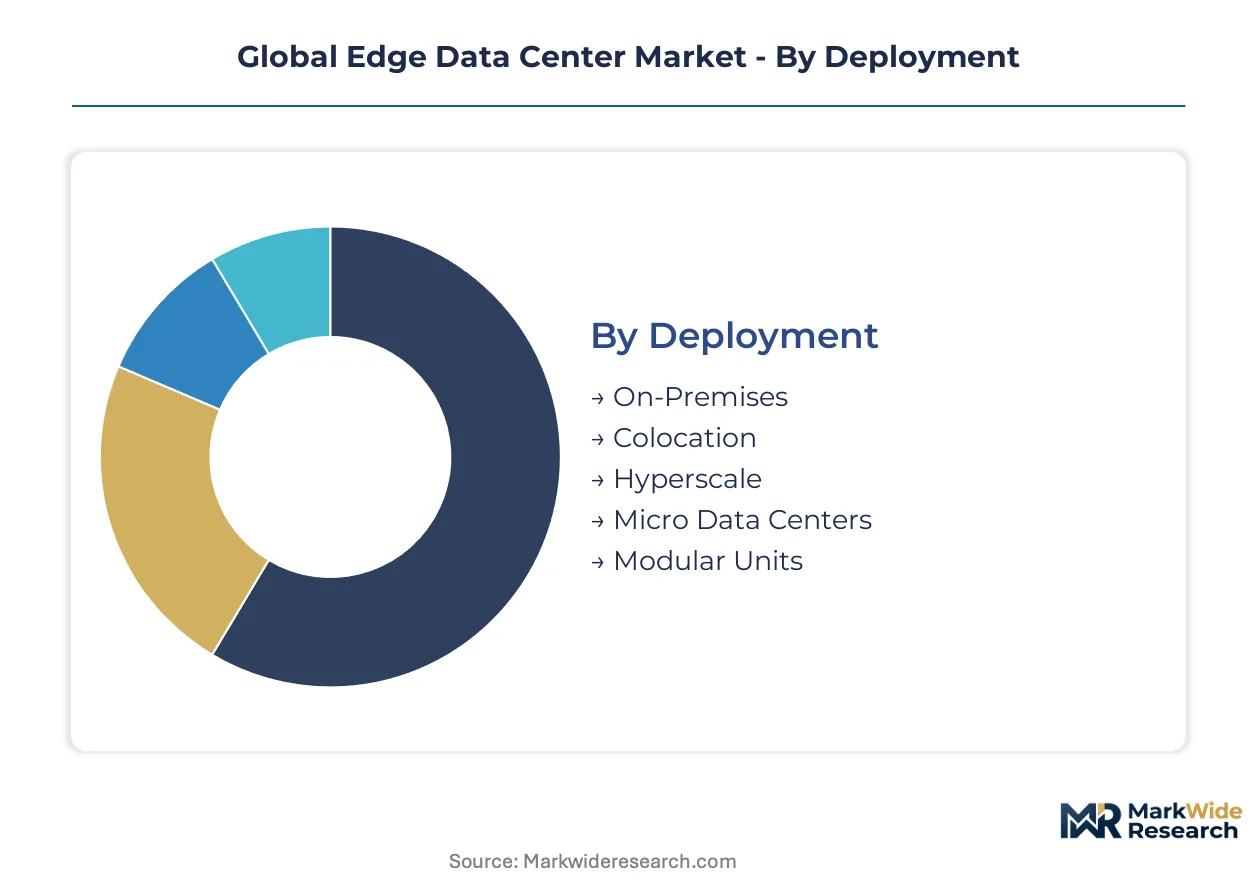
Edge data center segmentation reveals how latency requirements, capital constraints, and workload characteristics fragment infrastructure procurement patterns. Deployment models diverge sharply between enterprises avoiding facility ownership and operators optimizing for sovereign control. Application-specific thermal and power densities further stratify equipment specifications across distributed compute environments.
Deployment:
Use-case spectrum spans capital-intensive facility ownership to operational expenditure models that externalize construction risk.
- Colocation:Third-party facility access with shared power and cooling infrastructure enables enterprises to deploy IT equipment without land acquisition or construction. Demand concentrates among financial institutions in Germany's Frankfurt-Rhine-Main corridor seeking proximity to latency-optimized network exchanges while avoiding EU AI Act compliance capital burdens.
- Micro Data Centers:Self-contained units housing 100 kilowatts to 2 megawatts of IT capacity in compact footprints serve manufacturing environments with severe space constraints. India's smart city infrastructure programs are pulling adoption for municipal digitization in dense urban cores where traditional facility construction is impractical.
- On-Premises:Enterprise-owned facilities deliver complete operational control over physical security and data governance.
- Hyperscale:Massive distributed nodes deployed by cloud operators aggregate regional inference workloads.
- Modular Units:Factory-integrated prefabricated systems compress deployment timelines for telecommunications providers.
Established volume favors Colocation; emerging adoption favors Micro Data Centers.
Application:
Workload thermal profiles and latency sensitivity stratify facility engineering requirements.
- AI & Machine Learning:Inference workloads at the edge require high-density compute racks generating substantial heat loads. Autonomous vehicle manufacturers in Japan's Tokyo-Osaka corridors are deploying liquid-cooled nodes to meet METI energy efficiency incentive criteria while supporting real-time decision-making.
- Content Delivery:Caching and streaming optimization workloads prioritize network proximity over compute density. Streaming service operators distribute infrastructure to minimize latency for end-users across fragmented metropolitan markets.
- IoT Analytics:Sensor data aggregation and preliminary processing in manufacturing environments.
- Virtual Reality:Ultra-low latency rendering for immersive experiences drives sub-10 millisecond placement requirements.
- Autonomous Systems:Safety-critical compute for robotics and transportation infrastructure.
Revenue concentration tilts toward Content Delivery; steepest expansion trajectory belongs to AI & Machine Learning.
End User:
Customer procurement sophistication and compliance obligations reshape vendor engagement models.
- Telecommunications Providers:5G densification programs require localized compute nodes within 10-20 milliseconds of subscribers. Mobile network operators in Germany specify modular prefabrication to accelerate ultra-reliable low-latency communications rollout timelines.
- Manufacturing Firms:Industrial IoT convergence demands ruggedized compact compute for predictive maintenance. Automotive producers in Germany's industrial corridor are unbundling after-sales service contracts to source specialized thermal management technicians separately.
- Cloud Service Operators:Hyperscale distributed infrastructure deployment for regional inference aggregation.
- Public Sector Agencies:Sovereign data residency mandates drive facility ownership preferences.
- Financial Institutions:Low-latency trading and risk computation requirements.
Contract value concentrates with Telecommunications Providers; margin expansion favors Manufacturing Firms.
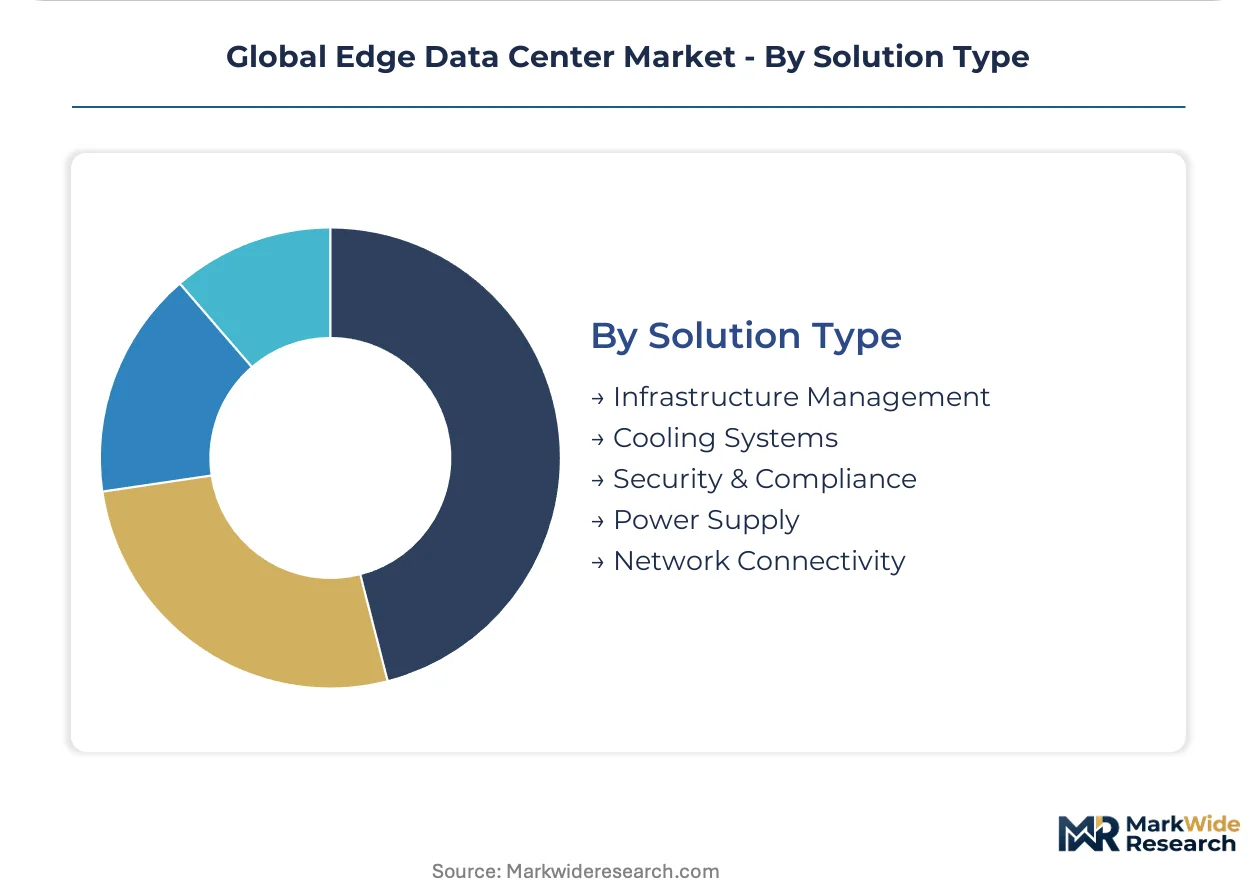
Solution Type:
Component-level procurement patterns reflect operational technology and information technology convergence pressures.
- Cooling Systems:Precision thermal management components from limited specialized suppliers create input bottlenecks for compact deployments. Europe's F-Gas Regulation phase-down schedules constrain refrigerant options, elevating engineering complexity for edge facility operators.
- Security & Compliance:Physical and cyber infrastructure protection governed by ISO 27001 and IEC 62443 standards. EU AI Act risk-based tiers compel facility operators to document data governance controls, expanding retrofit demand across automated decision-making infrastructure.
- Infrastructure Management:Software-defined monitoring and orchestration platforms.
- Power Supply:Redundant architectures and uninterruptible systems for mission-critical uptime.
- Network Connectivity:Software-defined networking enabling localized traffic routing.
Supply constraints concentrate in Cooling Systems; compliance urgency elevates Security & Compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's smart city programs demonstrate acute price sensitivity, while autonomous vehicle manufacturers in Japan absorb substantial premiums for sub-10 millisecond latency compliance.
United States
Telecommunications providers accelerate 5G densification across metropolitan corridors. EPA disclosure mandates for power usage effectiveness ratios impose measurement infrastructure costs on distributed operators. Dallas-Fort Worth and Northern Virginia sub-markets concentrate hyperscale edge investments for regional inference aggregation.
Germany
Financial institutions in the Frankfurt-Rhine-Main corridor prioritize latency-optimized network proximity. EU AI Act risk-based tiers compel facility operators to document data governance and physical security controls. Stuttgart's automotive manufacturing belt drives demand for ruggedized micro data centers in space-constrained industrial environments.
Japan
Autonomous vehicle manufacturers deploy liquid-cooled roadside compute nodes for real-time decision-making. METI energy efficiency incentives subsidize low-carbon distributed computing in Tokyo-Osaka corridors. Yokohama's port automation cluster exemplifies industrial IoT convergence with edge AI for predictive maintenance.
India
Municipal digitization initiatives under smart city programs create demand for compact urban deployments. CEA grid reliability standards shape power architecture specifications for distributed infrastructure. Bangalore's technology corridor concentrates telecommunications provider demand for modular prefabricated systems.
United Kingdom
Content delivery operators distribute infrastructure to minimize streaming latency across fragmented metropolitan markets. CSRD mandates require granular energy consumption disclosure from distributed computing assets. London's financial district drives colocation demand for sovereign data residency compliance.
Global Edge Data Center Market Competitive Landscape
Capability concentration sits with integrated power-cooling specialists; scale advantage sits with telecommunications-anchored modular fabricators. The vendor base stratifies across three tiers: diversified industrial conglomerates with cross-portfolio service integration, pure-play thermal management specialists, and telecommunications equipment providers with prefabrication expertise. Dominant competitive moves include vertical integration into recurring maintenance contracts and geographic clustering around latency-optimized metropolitan corridors.
Within the integrated infrastructure tier, Schneider Electric exemplifies the diversified conglomerate archetype through its combined power and cooling portfolio. Vertiv occupies a specialist position anchored in thermal management for compact deployments. Huawei Technologies represents the telecommunications-anchored modular fabricator archetype with factory-integrated prefabrication capabilities.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv |
| Huawei Technologies |
| Equinix |
| Eaton |
| Dell Technologies |
| Hewlett Packard Enterprise Company |
| Digital Realty |
| IBM |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp corridor freight costs cascade through thermal management component pricing, amplifying margin compression for precision cooling suppliers while forcing tiered contract structures that separate premium liquid-cooled deployments from standard air-cooled configurations across European edge infrastructure procurement.
Pricing Analysis
After-sales service revenue tiers spanning multi-year maintenance contracts drive lifetime value capture for integrated infrastructure vendors. Three-tier pricing structure across premium liquid-cooled, standard precision-air, and economy modular configurations segments buyers by latency sensitivity and compliance burden. Cost compression in standard-tier colocation runs through unbundled procurement patterns where manufacturing end-users source thermal management separately. Automotive manufacturers in Germany absorb premium pricing for sub-10 millisecond compliance, while India's smart city programs demonstrate acute price sensitivity that favors economy modular units.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for edge infrastructure OEMs. Precision cooling component fabrication concentrates in Germany, China, and Japan, with refrigerant compressors and heat exchangers drawing from overlapping supplier bases. Rare earth elements for high-efficiency power electronics rest on concentrated mining and refining capacity. Single-source vulnerability in immersion cooling fluid formulations threatens deployment timelines for autonomous vehicle roadside nodes. Distribution runs through telecommunications equipment providers with captive prefabrication capabilities and industrial distributors serving manufacturing retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge data center infrastructure sits in early-cycle expansion as autonomous vehicle manufacturers accelerate localized compute node deployment timelines, creating penetration headroom before standardization consolidates procurement patterns.
For Market Incumbents: Entrench recurring revenue streams by capturing multi-year thermal management service contracts across Germany's automotive manufacturing belt. Deepen backward integration into precision cooling component production to offset F-Gas Regulation compliance cost pass-through. Defend against modular prefabrication specialists by anchoring integrated power-cooling portfolios to EU AI Act certification documentation services. For New Entrants and Emerging Players: Mid-market commercial buildings in India's Tier-2 smart cities represent the most penetrable entry point for compact urban deployments with severe space constraints. Retrofit-focused micro data centers for legacy manufacturing facilities in Japan's industrial corridors offer second-mover positioning before liquid-cooled standardization matures. Partner with municipal digitization contractors as channel anchors rather than competing for direct enterprise procurement. For Investors and Strategic Acquirers: Specialist thermal management engineering firms with IEC 62443 implementation capabilities command scarcity premiums as OT/IT cybersecurity skill convergence tightens labor markets. Long-term viability across the analysis window hinges on regulatory compliance service integration rather than hardware shipment volumes. Watch for METI subsidy program expansions as inflection indicators for Japanese deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | Factory-integrated cooling compresses deployment timelines for telecommunications providers pursuing 5G densification. |
| Liquid Cooling Technology Licensing | Immersion systems transfer to autonomous vehicle manufacturers seeking roadside compute node thermal efficiency. |
| EU AI Act Compliance Certification | Documentation services capture retrofit demand from automated decision-making infrastructure operators. |
| Backward Integration into Power Electronics | Captive supply of uninterruptible systems defends margin position against component cost volatility. |
| Smart City Infrastructure Partnership | Municipal digitization contracts in India anchor volume before price-sensitive procurement standardizes. |
Research Methodology
A spread of perspectives from data center facility operators, telecommunications network planners, thermal management engineers, and municipal smart city procurement officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings of publicly traded infrastructure vendors, hyperscaler capex disclosure reports, and EU regulatory implementation guidance documents. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed deployment type, application workload thermal profile, end-user procurement sophistication, and solution component category. CAGRs derived from installed base growth rates adjusted for technology substitution effects and regulatory compliance retrofit cycles. Forecast inputs incorporated METI subsidy program allocations and F-Gas Regulation phase-down schedules as policy-driven demand modifiers.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting infrastructure financing costs or energy price volatility impacting power usage effectiveness ratios would shift the trajectory. Forecasts reflect documented assumptions regarding 5G densification timelines and autonomous vehicle regulatory approval pathways. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
North America Hyperscale Data Center Market
Data Center Infrastructure
Data Center As a Service Market
Data Center Infrastructure
Norway Data Center Server Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Asia-Pacific Hosting Infrastructure Services Market
Data Center Infrastructure
United States (US) Data Center Construction Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Data Center Rack Solutions Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Data Center Transformation Market