
 Poland Data Center Power Market | 2026-2036
Poland Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Power Market Insights
Lithium-ion battery chemistry is pivoting away from traditional valve-regulated lead-acid systems in Polish data center UPS configurations, cutting footprint and maintenance burdens while raising upfront capital requirements. Schneider Electric SE leverages its European manufacturing footprint to anchor supply chains serving Warsaw's expanding hyperscale corridor. ABB Ltd competes through integrated medium-voltage and low-voltage power distribution architectures tailored to large-scale deployments. Eaton Corporation specializes in intelligent power management software layers that differentiate its hardware offerings beyond commodity specifications.
Data center power encompasses the generation, conditioning, distribution, and backup electricity infrastructure sustaining continuous operations for server, storage, and networking equipment, typically requiring redundancy levels from N+1 to 2N and operational voltages spanning 400V AC to 800V DC in advanced designs. UPS Systems dominate product type revenue due to mandatory uptime commitments, while Generators retain structural importance as final-line defense against grid instability despite lengthening runtime compression targets. Edge Computing applications represent the fastest-growing segment as latency-sensitive workloads proliferate beyond core Warsaw facilities, though Colocation retains the deepest margin pools given multi-tenant density economics.
Poland's Office of Electronic Communications enforces telecommunications infrastructure resilience standards that directly shape backup power duration and switching-time requirements for carrier-neutral facilities. BIS-aligned product certification and EU CE marking under the Low Voltage Directive govern equipment import and installation protocols, while the EU Green Deal's decarbonization timelines are forcing diesel generator displacement strategies across new builds. Stakeholders must monitor grid interconnection queue dynamics and renewable power purchase agreement availability as these factors will determine site selection economics and long-term operating cost structures more than equipment procurement decisions alone.
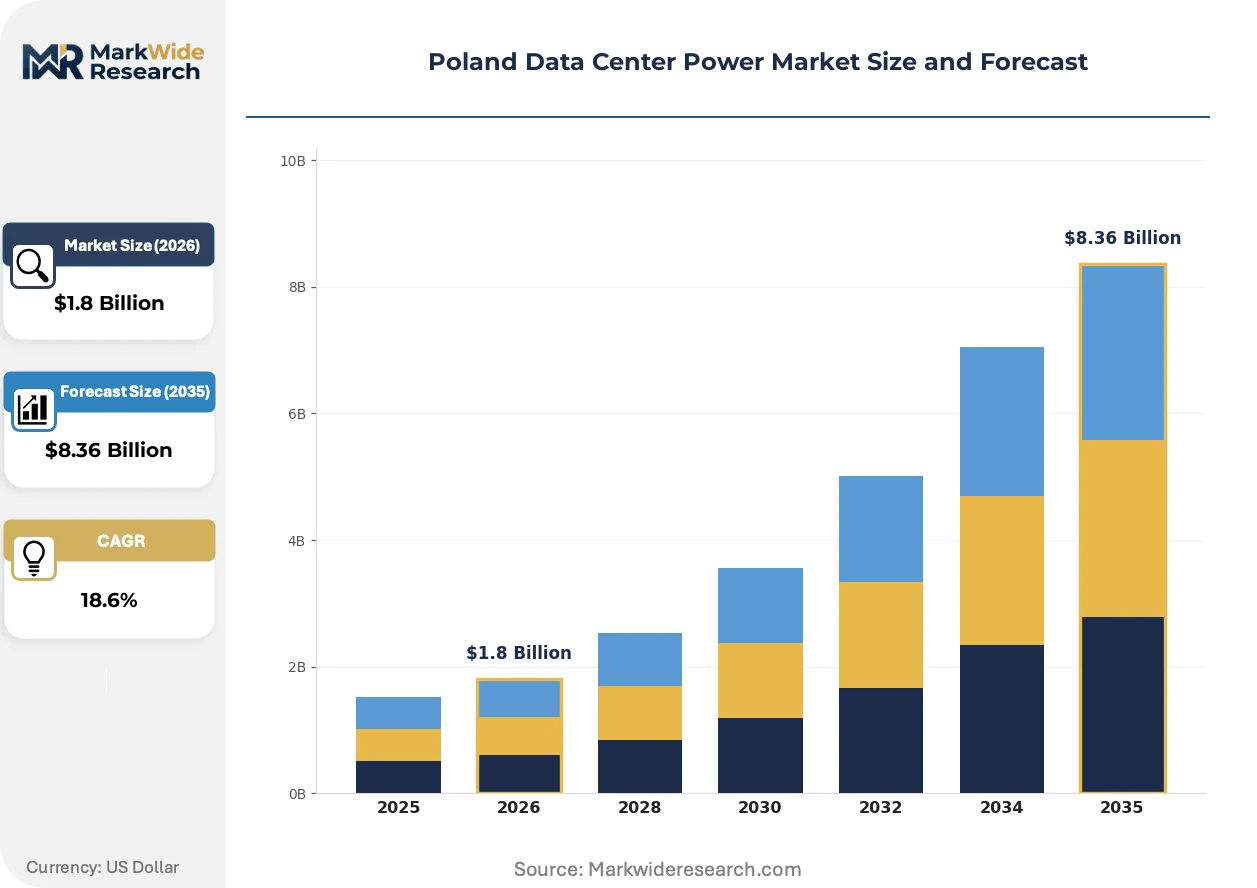
Market Dynamics
The EU Green Deal's diesel displacement mandates are compressing backup power runtimes and forcing lithium-ion chemistry adoption across Polish data center builds, reshaping capital allocation toward battery energy storage systems and away from conventional generator architectures.
Growth Catalysts
- EU Green Deal Decarbonization Timeline:Binding emission reduction targets accelerate diesel-to-lithium transitions in backup power configurations, creating replacement demand across existing facilities.
- Hyperscale Cloud Expansion:Warsaw metropolitan cluster attracts multi-hundred-megawatt commitments from international operators requiring redundant power infrastructure.
- Telecommunications Resilience Mandates:Poland's Office of Electronic Communications enforces strict uptime standards that mandate extended battery runtime and sub-10ms switching capabilities.
Market Restraints
- Lithium Supply Concentration:Cathode active material processing concentrates in East Asian supply chains, exposing Polish operators to price volatility and geopolitical disruption risks.
- Grid Interconnection Queues:Transmission network reinforcement lags behind data center power demand in Masovian Voivodeship, delaying project commissioning timelines.
- CE Marking Complexity:Low Voltage Directive compliance testing for 800V DC architectures extends equipment certification cycles by four to six months versus traditional AC systems.
Strategic Opportunities
- Edge Computing Proliferation:Latency-sensitive manufacturing and logistics applications in Kraków and Wrocław secondary markets drive distributed power infrastructure demand outside Warsaw core.
- Renewable Power Purchase Agreements:Corporate renewable energy procurement frameworks enable long-term cost hedging and sustainability positioning for colocation providers.
- Modular UPS Convergence:Containerized power skids integrating lithium storage with intelligent power management software reduce site construction duration and labor intensity.
Industry Challenges
- High-Voltage DC Skill Scarcity:Specialized electrical engineering expertise for 400V to 800V DC architectures remains concentrated among Warsaw-based contractors, constraining deployment velocity.
- Legacy Infrastructure Integration:Retrofitting existing facilities with lithium-ion systems requires fire suppression system redesign and structural load assessment, complicating brownfield projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Power Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: UPS Systems, Generators, PDU, Cooling Solutions Application: Colocation, Cloud Services, Enterprise Data Centers, Edge Computing Technology: AI Optimization, Renewable Energy Integration, Lithium-ion Battery, Power Distribution End User: Telecommunications, Financial Services, E-commerce, Healthcare |
| Companies Covered | ABB Ltd, Schneider Electric SE, Vertiv Group Corp., Eaton Corporation, Caterpillar Inc., Cummins Inc., Rolls-Royce PLC, Delta Electronics, Rittal GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Power Market Trends and Innovations
Power distribution architectures are fragmenting from centralized monolithic designs toward modular, software-defined configurations that match capacity increments to actual server deployment timelines rather than speculative overbuilding.
Distributed energy resources are decentralizing backup power from single-point diesel generator farms toward battery-centric microgrids with renewable firming capabilities. Hyperscale operators in Warsaw's Pruszków corridor are deploying 10-15 minute lithium systems as primary backup, relegating generators to extreme contingency. This topology compresses fuel storage requirements and enables participation in grid ancillary services markets.
EU Green Deal implementation is forcing diesel runtime compression targets across new Polish data center builds. The F-Gas Regulation simultaneously constrains synthetic refrigerant options for thermal management, indirectly shaping power system thermal integration strategies. Colocation providers are responding with dual-circuit chilled water designs that reduce UPS heat rejection loads.
Buying patterns among Polish enterprise customers are fragmenting from traditional capital purchase models toward power-as-a-service arrangements. Equipment vendors are unbundling hardware from long-term service contracts, creating transparent lifecycle cost structures. This shift is most pronounced among financial services tenants in Warsaw's Mokotów district, where CFO scrutiny of balance sheet treatment drives preference for operational expenditure classification.
Poland Data Center Power Market Segmentation
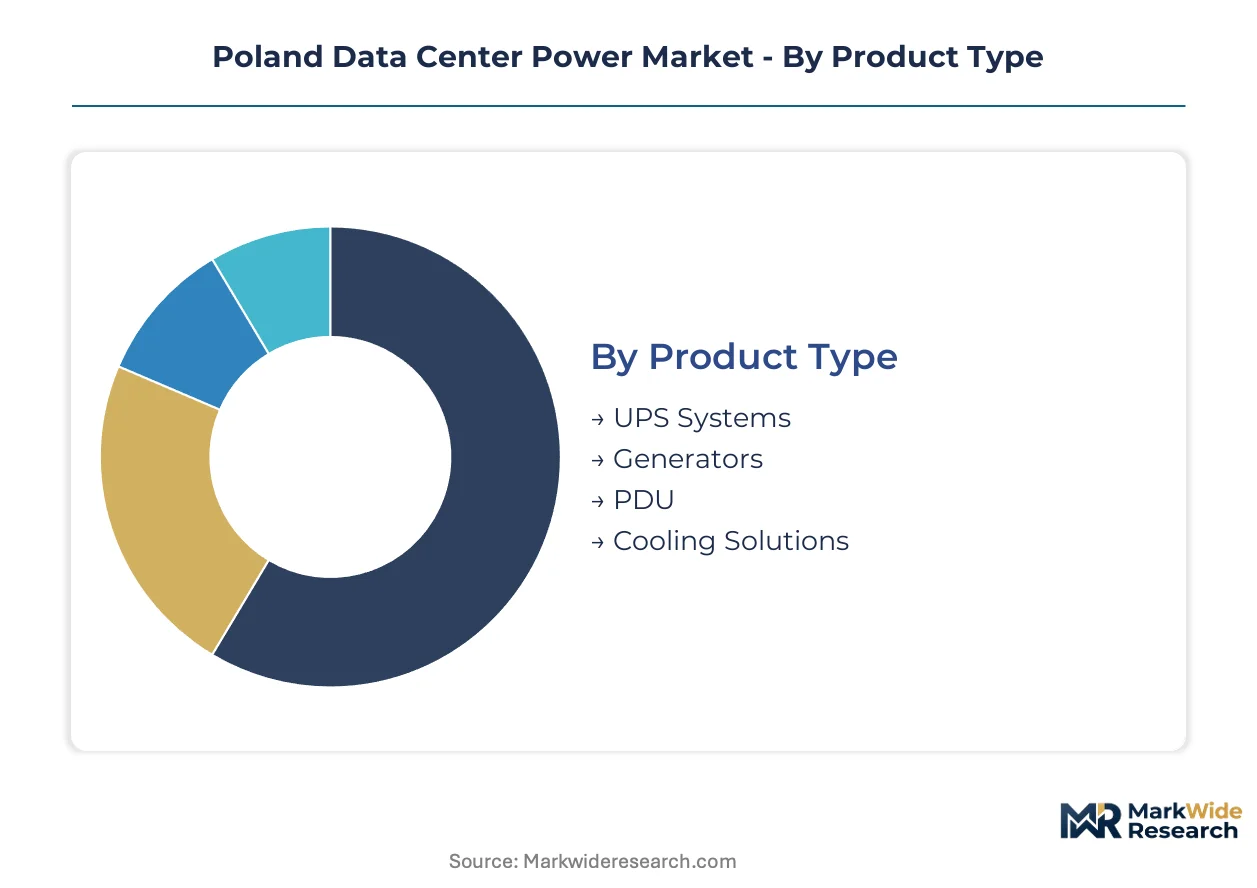
Segmentation in Poland's data center power market reveals how infrastructure investment priorities diverge between hyperscale operators optimizing for scale and enterprise tenants prioritizing resilience certification. Understanding these splits illuminates where procurement budgets concentrate and which technology transitions command capital allocation.
Product Type:
Replacement cycles accelerate as EU Green Deal mandates force diesel-to-lithium transitions across Warsaw's expanding hyperscale corridor, compressing traditional generator dominance while elevating battery-centric architectures.
- UPS Systems:Double-conversion and modular uninterruptible power supply configurations dominate capital expenditure, with lithium-ion chemistry displacing valve-regulated lead-acid systems in facilities above 10MW capacity. Warsaw's Mokotów and Pruszków clusters drive concentrated demand as hyperscale operators mandate sub-10ms switching and 10-15 minute runtime capabilities under Poland's Office of Electronic Communications resilience standards.
- Generators:Diesel reciprocating engines retain structural importance as final-line contingency defense, though runtime compression targets shrink fuel storage requirements from 48-72 hours toward 8-24 hours. Masovian Voivodeship grid interconnection delays extend generator commissioning timelines, forcing operators to maintain larger spinning reserves than planned.
- PDU:Power distribution units with intelligent metering and remote switching capabilities reduce manual intervention requirements in multi-tenant colocation environments.
- Cooling Solutions:Dual-circuit chilled water architectures integrate with UPS heat rejection loads, responding to F-Gas Regulation constraints on synthetic refrigerants.
Volume placements concentrate in UPS Systems; the faster expansion belongs to Cooling Solutions.
Application:
Cost tier differentiation separates capital-intensive hyperscale builds from margin-optimized colocation offerings, with edge deployments commanding premium pricing for distributed resilience.
- Colocation:Multi-tenant facilities in Warsaw's metropolitan cluster generate the deepest margin pools through density economics and cross-connect revenue streams. Providers differentiate through tiered resilience certification, with Tier III and Tier IV designs commanding 40-60% pricing premiums over Tier II equivalents.
- Cloud Services:Hyperscale operators including AWS, Microsoft Azure, and Google Cloud anchor demand with multi-hundred-megawatt commitments requiring N+1 to 2N redundancy architectures. These deployments standardize on 400V AC distribution with pilot 800V DC trials, compressing equipment certification cycles under CE marking and Low Voltage Directive protocols.
- Enterprise Data Centers:Financial services and telecommunications operators in Warsaw maintain captive facilities for regulatory compliance and data sovereignty requirements.
- Edge Computing:Latency-sensitive manufacturing and logistics applications in Kraków and Wrocław secondary markets drive distributed infrastructure demand beyond the capital region.
Revenue concentration sits with Colocation; steepest expansion trajectory belongs to Edge Computing.
Technology:
Supply concentration in East Asian cathode active material processing shapes technology adoption timelines, exposing Polish operators to lithium price volatility and geopolitical disruption risks.
- Lithium-ion Battery:Nickel-manganese-cobalt and lithium-iron-phosphate chemistries dominate new build specifications, cutting footprint and maintenance burdens while raising upfront capital requirements 30-50% over lead-acid equivalents. Fire suppression system redesigns and structural load assessments complicate brownfield retrofits.
- Power Distribution:Medium-voltage and low-voltage integrated architectures from ABB and Schneider Electric anchor large-scale deployments, with intelligent power management software layers differentiating hardware offerings beyond commodity specifications.
- AI Optimization:Predictive load forecasting and dynamic voltage-frequency scaling reduce energy consumption in variable-demand environments.
- Renewable Energy Integration:Corporate power purchase agreements enable long-term cost hedging and sustainability positioning for colocation providers seeking EU Green Deal compliance.
Deployment scale favors Power Distribution; technology transition momentum concentrates in Lithium-ion Battery.
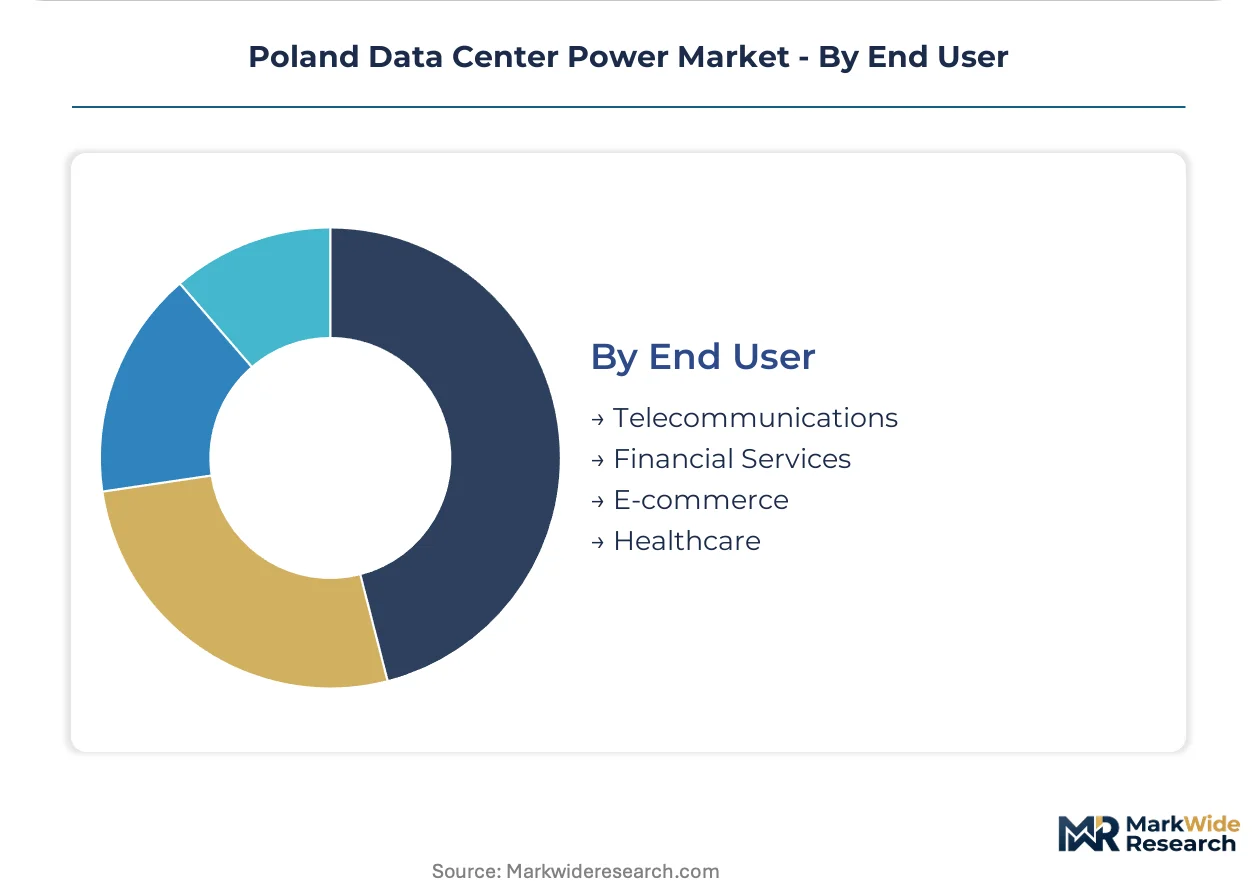
End User:
Customer type segmentation reflects divergent uptime requirements, with financial services and telecommunications operators facing the strictest regulatory mandates.
- Telecommunications:Poland's Office of Electronic Communications enforces binding telecommunications infrastructure resilience standards that directly shape backup power duration and switching-time requirements. Carrier-neutral facilities must maintain extended battery runtime capabilities and sub-10ms transfer specifications.
- Financial Services:Warsaw's banking and insurance sectors drive demand for Tier III and Tier IV certified facilities, with CFO scrutiny of balance sheet treatment accelerating power-as-a-service procurement models over capital purchase arrangements.
- E-commerce:Fulfillment network operators prioritize distributed edge capacity for last-mile latency reduction.
- Healthcare:Medical data processing requirements under national electronic health record mandates create specialized demand for HIPAA-equivalent resilience certification.
Contract value concentrates in Telecommunications; procurement innovation leadership belongs to Financial Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center power demand concentrates in Poland's Warsaw metropolitan cluster and surrounding Masovian Voivodeship, where hyperscale cloud operators anchor multi-hundred-megawatt commitments. Secondary markets in Kraków and Wrocław are emerging as edge computing nodes for latency-sensitive manufacturing applications.
Masovian Voivodeship
Hyperscale cloud operators including AWS, Microsoft Azure, and Google Cloud drive concentrated UPS and generator demand across Warsaw's Pruszków and Mokotów corridors. Poland's Office of Electronic Communications enforces telecommunications infrastructure resilience standards mandating sub-10ms switching and extended battery runtime. The Warsaw metropolitan cluster hosts the deepest colocation density, with Tier III and Tier IV facilities commanding premium pricing over Tier II equivalents.
Lesser Poland Voivodeship
Kraków's manufacturing and logistics base generates distributed edge computing demand for latency-sensitive industrial automation workloads. EU Green Deal decarbonization timelines accelerate diesel-to-lithium transitions in backup power configurations across new builds. The Kraków Technology Park and surrounding industrial zones attract modular data center deployments serving automotive and electronics supply chains.
Lower Silesian Voivodeship
Wrocław's logistics hub status and shared services center concentration create steady enterprise data center demand from financial services and e-commerce operators. CE marking under the Low Voltage Directive governs 800V DC equipment certification cycles, extending lead times versus traditional AC systems. The Wrocław metropolitan area functions as a secondary node in national telecommunications resilience planning.
Pomeranian Voivodeship
Gdańsk's port logistics and maritime services generate specialized edge computing requirements for supply chain visibility and customs processing applications. Grid interconnection queue delays in northern Poland constrain transmission network reinforcement timelines relative to data center power demand growth. The Tricity metropolitan area benefits from submarine cable landing stations supporting international connectivity.
Silesian Voivodeship
Katowice's industrial heritage and energy infrastructure density position the region for potential data center development leveraging existing transmission assets. F-Gas Regulation constraints on synthetic refrigerants indirectly shape thermal management integration strategies for power system heat rejection. The region's coal-phase transition creates stranded energy assets that may convert to data center load under renewable power purchase agreement frameworks.
Poland Data Center Power Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors align with hyperscale operators and colocation providers to secure multi-year supply commitments. The market structures around three tiers: integrated European electrical conglomerates with full power distribution portfolios, specialized UPS and thermal management specialists, and generator manufacturers adapting to runtime compression mandates. Two competitive moves define positioning: geographic anchoring through Warsaw-based service networks, and technology convergence between lithium-ion storage and intelligent power management software layers.
Within the integrated electrical systems tier, Schneider Electric SE and ABB Ltd represent the dominant positioning archetypes, with the former leveraging European manufacturing footprints to anchor supply chains and the latter competing through medium-voltage and low-voltage architecture integration. Eaton Corporation occupies a distinct position specializing in software-differentiated power management layers. These three companies exemplify how hardware commoditization pressures are forcing competitive differentiation toward intelligent control systems and lifecycle service bundling rather than equipment specifications alone.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Eaton Corporation |
| Caterpillar Inc. |
| Cummins Inc. |
| Rolls-Royce PLC |
| Delta Electronics |
| Rittal GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
European electrical conglomerates with integrated manufacturing footprints anchor supply behavior and pricing discipline across Poland's data center power market, leveraging captive production of medium-voltage switchgear and lithium-ion storage systems to resist commoditization pressure while EU Green Deal mandates compress buyer negotiation leverage.
Pricing Analysis
Volume placements concentrate in UPS systems serving hyperscale operators, while margin pools deepen in colocation Tier III and Tier IV certification tiers. Three-tier pricing structure across premium, standard, and economy levels separates Tier IV certified installations with 2N redundancy from Tier II commodity configurations. Cost compression in lead-acid replacement cycles is intensifying because lithium-ion chemistry raises upfront capital requirements 30-50% over legacy systems. Financial services tenants in Warsaw's Mokotów district demonstrate lowest price sensitivity due to CFO-mandated operational expenditure classification, whereas regional edge computing operators in Kraków and Wrocław exhibit highest sensitivity to capital deployment timing.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands feed hub-and-spoke patterns into Warsaw's Pruszków and Mokotów corridors, with final-mile installation crews concentrated among Warsaw-based electrical contractors. Cathode active material processing draws from China, South Korea, and Japan, exposing Polish operators to lithium carbonate price volatility and geopolitical disruption risks. Power distribution equipment hinges on German and French manufacturing footprints for medium-voltage switchgear and low-voltage panel assemblies. Single-source vulnerability concentrates in East Asian lithium refining capacity. Distribution runs through authorized service networks with CE marking compliance testing extending equipment certification cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's data center power market sits in a technology-transition phase as lithium-ion battery chemistry displaces valve-regulated lead-acid systems across backup power architectures, forcing capital reallocation and supplier consolidation.
For Market Incumbents: Lock in multi-year service contracts with hyperscale operators in Masovian Voivodeship before modular UPS convergence accelerates hardware commoditization. Secure backward integration into lithium-ion storage assembly through European manufacturing partnerships to reduce East Asian supply chain exposure. Prioritize intelligent power management software R&D to differentiate beyond commodity electrical specifications.
For New Entrants and Emerging Players: Capture edge computing infrastructure demand in Kraków and Wrocław secondary markets where latency-sensitive manufacturing applications outpace established supplier coverage. Target Tier II colocation retrofit opportunities in Silesian Voivodeship's stranded energy asset conversions. Deploy containerized power skids with integrated lithium storage and remote monitoring capabilities as primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Warsaw-based electrical contractors with 800V DC installation expertise in Masovian Voivodeship, where skill scarcity constrains deployment velocity and creates acquisition arbitrage. Long-term viability centers on suppliers with software-defined power management layers rather than pure hardware manufacturers. Monitor grid interconnection queue clearance rates as inflection indicator for project commissioning velocity and equipment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Chemistry Transition | EU Green Deal diesel displacement mandates force battery-centric backup architectures across new Polish builds. |
| Modular UPS Convergence | Containerized power skids reduce site construction duration for hyperscale operators in Warsaw's Pruszków corridor. |
| Intelligent Power Management Software | Predictive load forecasting layers differentiate Eaton and Schneider Electric offerings beyond hardware specifications. |
| Renewable Power Purchase Agreements | Corporate procurement frameworks enable long-term cost hedging for colocation providers seeking EU Green Deal compliance. |
| 800V DC Architecture Trials |
Research Methodology
Multi-period observation of hyperscale capex commitments, grid interconnection queue dynamics, and lithium-ion import volumes anchored the trend analysis, supplemented by interviews with data center facility directors, electrical engineering contractors, colocation procurement managers, and utility interconnection planners. Primary fieldwork combined with secondary validation against SEC filings from listed electrical equipment manufacturers, EU Green Deal implementation trackers, and Poland's Office of Electronic Communications regulatory disclosures. Bottom-up equipment shipment analysis triangulated against top-down power demand projections from transmission network operators.
Segment-weighting approaches distributed total market value across product type, application, technology, and end user dimensions, with additional modeling of regional Voivodeship concentration patterns. Growth trajectories were derived through installed base replacement cycle analysis and new build pipeline tracking across the projection horizon. Forecast inputs incorporated EU Green Deal decarbonization timeline enforcement, renewable power purchase agreement availability, and lithium supply chain concentration risk premiums.
The model holds under stable EU regulatory enforcement and continued hyperscale cloud expansion; deviation in grid reinforcement timelines or East Asian supply chain disruption would shift equipment deployment schedules. Forecasts reflect documented assumptions regarding technology transition velocity and capital availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Taiwan Data Center Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Germany Data Center Construction Market
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
United Kingdom Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Data Center Transfer Switches and Switchgears Market
Data Center Infrastructure
Russia Data Center Rack Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market