
 Vietnam Data Center Market | 2026-2036
Vietnam Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Market Insights
Cloud service providers and e-commerce platforms is redrawing procurement patterns across Vietnam's digital infrastructure landscape. Viettel IDC leverages its military-affiliated fiber backbone to dominate government and defense contracts. FPT Telecom sustains R&D intensity in edge computing nodes across secondary cities. ST Telemedia Global Data Centres anchors foreign direct investment through its Singapore-linked capital pool.
A data center constitutes a dedicated facility housing servers, storage systems, networking equipment, and power infrastructure designed to process, store, and distribute digital information with guaranteed uptime exceeding 99.98%. These installations employ precision cooling, redundant uninterruptible power supply configurations, and multi-layered physical security to maintain continuous operations for mission-critical workloads. Colocation services capture established revenue streams from enterprises seeking capital expenditure avoidance, while hyperscale deployments absorb the fastest capacity additions from international cloud operators. Edge computing segments within the technology dimension are gaining traction as latency-sensitive applications proliferate across manufacturing zones and smart city corridors.
Vietnam's Ministry of Information and Communications enforces data localization mandates through the Cybersecurity Law, compelling foreign platforms to establish domestic infrastructure. The country's national technical standards on information security, administered by the Vietnam Information Security Association in coordination with state agencies, shape certification requirements for facility operators. BIS-equivalent electrical and fire safety protocols govern construction permits for large-scale installations. Stakeholders must weigh land acquisition constraints in Danang against power grid reliability in emerging secondary markets when committing capital to greenfield developments.
Market Dynamics
Vietnam's data center sector is being fundamentally restructured by the Cybersecurity Law's data localization mandates, which compel foreign cloud platforms to establish domestic infrastructure rather than serving the market from Singapore or Hong Kong nodes.
Growth Catalysts
- Red River Delta concentration:Hyperscale deployments cluster near Hanoi's fiber-rich corridor, leveraging Viettel's military-grade backbone for latency-sensitive government workloads.
- E-commerce platform expansion:Shopee, Lazada, and Tiki are procuring dedicated capacity to handle flash-sale traffic spikes and real-time inventory synchronization.
- Submarine cable investments:New APG and AAE-1 landing stations in Danang and Quy Nhon are eliminating international bandwidth bottlenecks that previously throttled cross-border data flows.
Market Restraints
- Power grid reliability gaps:Secondary markets outside Hanoi and Ho Chi Minh City suffer voltage instability that forces diesel generator overprovisioning, raising opex by 15-25%.
- Land acquisition constraints:Danang's coastal zoning restrictions limit greenfield expansion despite its strategic cable landing position.
- Liquid cooling infrastructure immaturity:Local HVAC contractor capacity for precision cooling remains concentrated in two metropolitan areas, extending deployment timelines for high-density racks.
Strategic Opportunities
- Bac Ninh industrial corridor:Samsung and Foxconn manufacturing clusters are generating edge computing demand for predictive maintenance and quality control systems.
- Green building certification tailwinds:Vietnam Green Building Council standards are unlocking preferential electricity tariffs for facilities achieving LEED Silver or equivalent ratings.
- AI inference localization:Convergence of GPU-as-a-service models with manufacturing automation is creating captive demand for tier-2 cities currently unserved by hyperscale presence.
Industry Challenges
- Certification timeline compression:BIS-equivalent electrical and fire safety approvals for multi-megawatt facilities now average 14-18 months, delaying revenue recognition.
- Cross-connect interoperability:Legacy copper infrastructure in older Hanoi buildings complicates fiber migration for enterprises seeking seamless cloud on-ramps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Market |
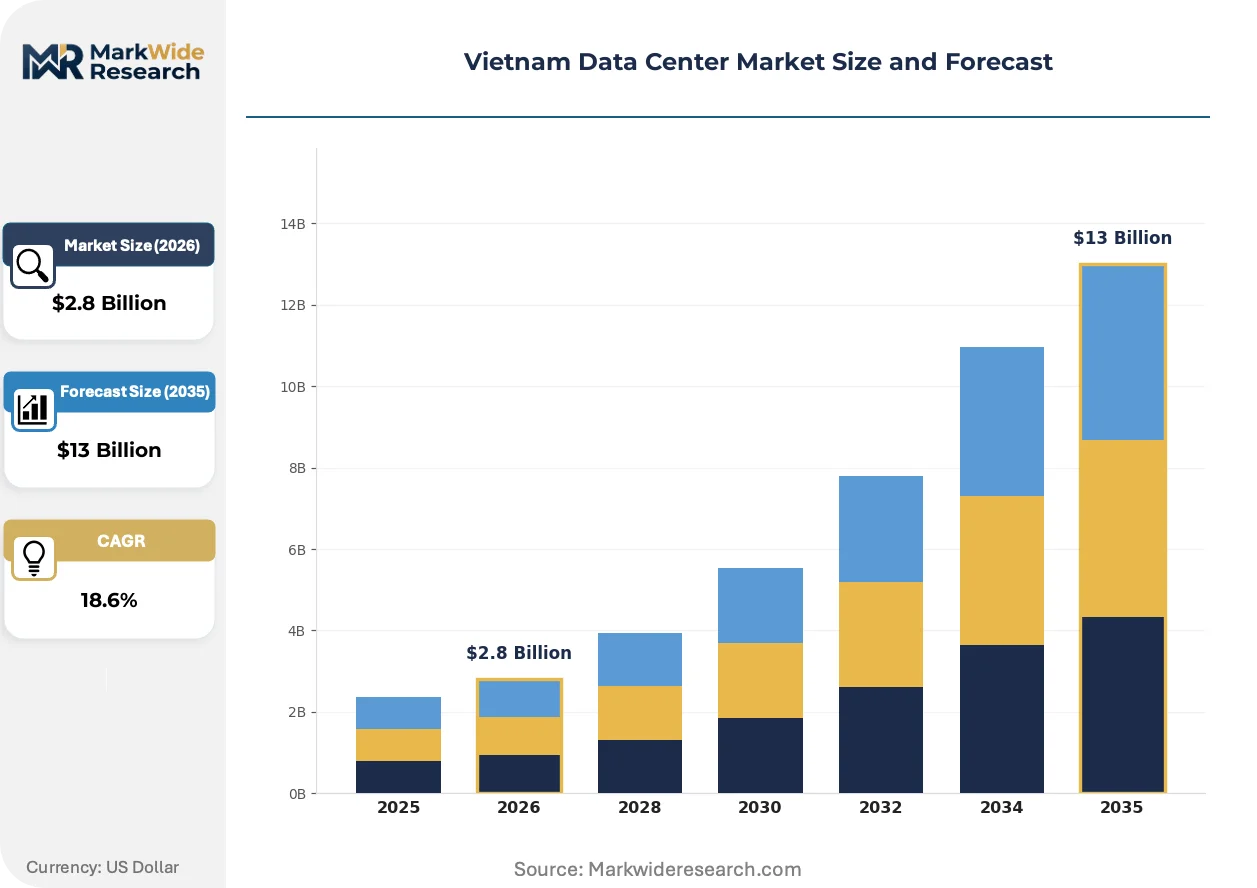
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Colocation, Hyperscale, Enterprise, Managed Services Technology: Cloud Computing, Edge Computing, Virtualization, Network Security End User: BFSI, Telecommunications, Healthcare, E-commerce Capacity: Small Scale, Medium Scale, Large Scale, Ultra Scale |
| Companies Covered | Viettel IDC, VNPT, FPT Telecom, CMC Telecom, NTT Global Data Centers, ST Telemedia Global Data Centres, VNG Corporation, DTS Communication, Telehouse, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Market Trends and Innovations
Modular infrastructure architectures are disrupting Vietnam's traditional build-to-suit model, enabling faster deployment cycles and reducing stranded capacity risk for operators navigating uncertain demand trajectories.
Immersion cooling is decomposing conventional raised-floor designs in high-performance computing environments. Domestic cryptocurrency mining operations adopted single-phase dielectric fluids during 2021-2022, establishing local contractor expertise that hyperscale operators now leverage for AI training clusters. This technology compression is collapsing the historical 18-month facility commissioning window to under 9 months for GPU-dense deployments.
Vietnam's Ministry of Information and Communications is tightening enforcement of the Cybersecurity Law's data localization provisions through periodic compliance audits. Foreign SaaS providers without domestic infrastructure face service blocking risks, accelerating direct investment into certified facilities. E-commerce and fintech verticals are absorbing the fastest capacity additions as they scramble to meet evolving interpretation of "core data" storage requirements.
Enterprise buyers are consolidating vendor relationships around integrated colocation-cloud bundles rather than maintaining separate contracts for rack space and connectivity. Systems integrators in Ho Chi Minh City are capturing margin by packaging cross-connects, managed firewalls, and direct cloud exchange access into single procurement vehicles. This bundling behavior concentrates purchasing power among three domestic operators with end-to-end fiber ownership.
Vietnam Data Center Market Segmentation
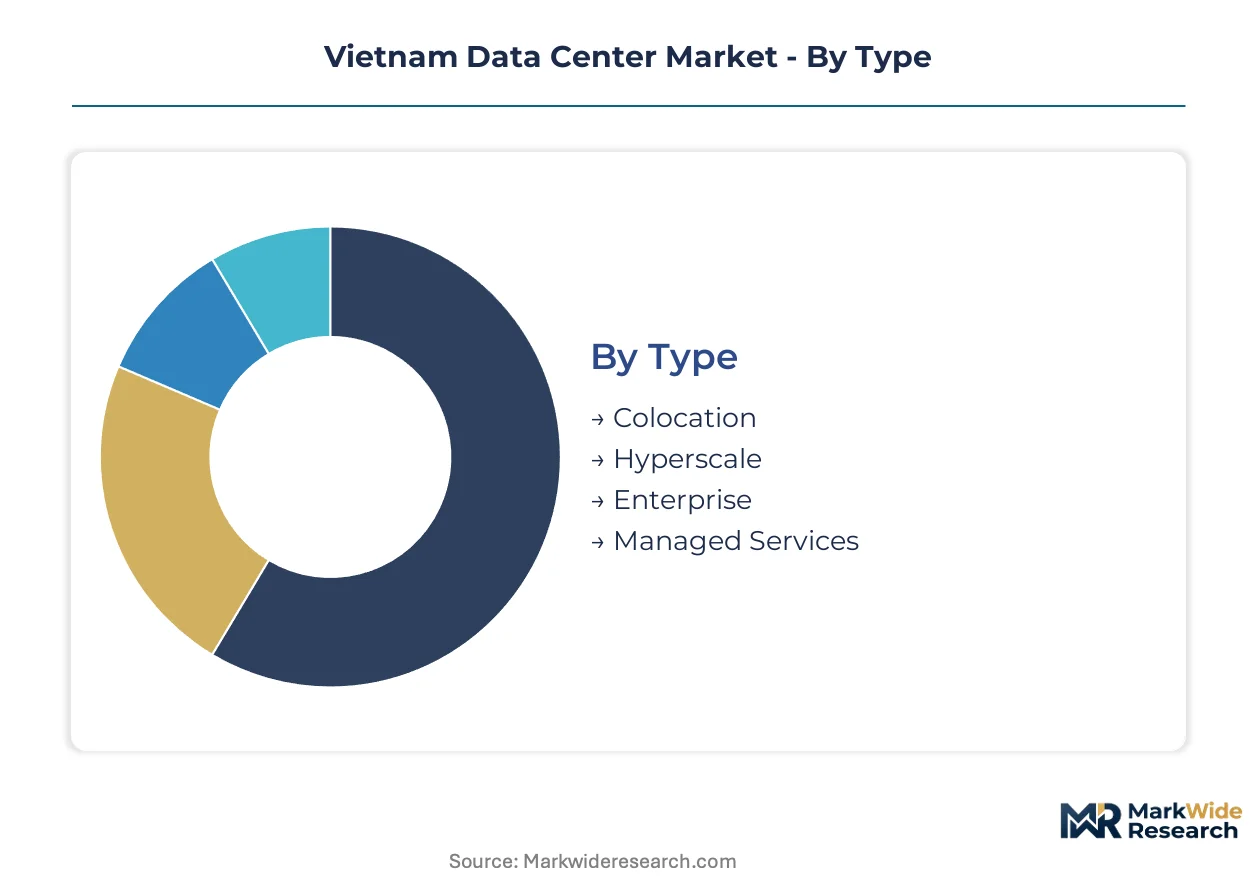
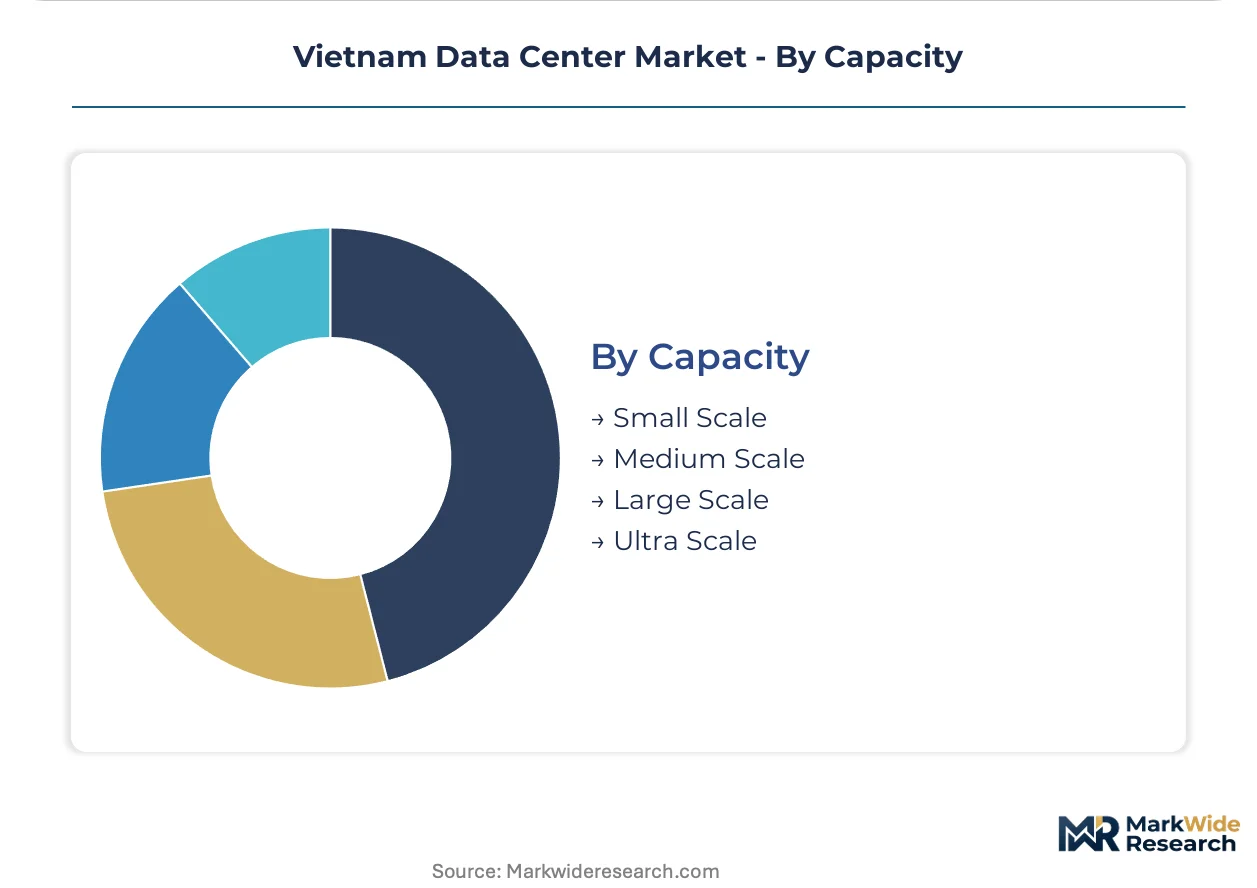
Segmentation reveals how Vietnam's data center market fragments across facility ownership models, infrastructure technologies, customer verticals, and operational scale tiers. Each dimension carries distinct substitution pressures from cloud-native alternatives and edge computing architectures.
Type:
Substitution pressure concentrates most intensely on enterprise-owned facilities as CFOs favor operating-expense models over capital-intensive builds.
- Colocation:Third-party facilities where enterprises lease rack space, power, and cooling while retaining hardware ownership. Demand concentrates among mid-market manufacturers in Binh Duong industrial zones seeking compliance without construction risk. The Ministry of Information and Communications' data localization audits are accelerating procurement from certified colocation operators.
- Hyperscale:Purpose-built facilities exceeding 10MW designed for single-tenant cloud operators with standardized rack densities and modular expansion capabilities. AWS, Google, and Microsoft are absorbing capacity near the Red River Delta corridor to serve government cloud workloads under Cybersecurity Law mandates.
- Enterprise:Captive facilities built and operated by large organizations for internal workloads. Banking conglomerates in Ho Chi Minh City maintain these for core banking systems despite rising opex burdens from diesel generator overprovisioning.
- Managed Services:Outsourced operations where vendors assume full infrastructure responsibility including hardware refresh and security patching. Fintech startups lacking internal IT depth are driving adoption in Hanoi.
Colocation anchors the volume base while hyperscale gains share at the steepest rate.
Technology:
Cost tier separation distinguishes capital-light virtualization approaches from infrastructure-heavy edge deployments requiring distributed real estate.
- Cloud Computing:On-demand resource provisioning through virtualized infrastructure pools. Viettel IDC and FPT Telecom are expanding sovereign cloud stacks to capture public sector workloads subject to data residency requirements.
- Edge Computing:Distributed processing nodes positioned within 50km of data sources to minimize latency. Manufacturing automation in Bac Ninh's Samsung supplier ecosystem is generating demand for predictive maintenance and quality control systems.
- Virtualization:Software abstraction enabling multiple operating environments on shared hardware. Enterprise IT departments leverage this to defer hardware refresh cycles amid budget constraints.
- Network Security:Segmented traffic inspection, DDoS mitigation, and zero-trust access controls delivered as infrastructure-layer services. Cybersecurity Law enforcement is elevating this from optional add-on to procurement prerequisite.
Cloud computing dominates current deployment value while edge computing climbs the fastest as latency requirements harden.
End User:
Application-specific requirements create divergent infrastructure specifications across regulated and consumer-facing verticals.
- BFSI:Banking, financial services, and insurance institutions with stringent uptime requirements and regulatory audit obligations. State Bank of Vietnam guidelines on operational risk are mandating geographic redundancy for core banking systems.
- Telecommunications:Mobile network operators and fixed-line providers deploying infrastructure for subscriber services and internal IT. Viettel and VNPT are verticalizing into data center operations to monetize excess fiber capacity.
- Healthcare:Hospital systems and health insurers managing electronic medical records and claims processing. Patient data protection rules under the Law on Cybersecurity are compelling domestic infrastructure for telemedicine platforms.
- E-commerce:Online retail platforms handling flash-sale traffic spikes and real-time inventory synchronization. Shopee, Lazada, and Tiki are procuring dedicated capacity in Ho Chi Minh City to serve southern Vietnam's consumer density.
E-commerce anchors the volume base while healthcare gains share at the steepest rate as regulatory enforcement tightens.
Capacity:
Customer type stratification separates hyperscale cloud operators demanding megawatt-scale blocks from SME requirements measured in single racks.
- Small Scale:Facilities below 1MW serving local businesses and branch office consolidation. Provincial banks in secondary cities deploy these for regulatory compliance without metropolitan cost structures.
- Medium Scale:Installations between 1-5MW targeting regional enterprises and SaaS providers. Danang's emerging tech corridor is attracting this tier despite land acquisition constraints.
- Large Scale:5-20MW facilities designed for national cloud operators and e-commerce platforms. Hanoi and Ho Chi Minh City concentration reflects fiber density and skilled technician availability.
- Ultra Scale:Campus-style developments exceeding 20MW with phased expansion capabilities. International cloud providers are securing land positions in Bac Ninh and Long An provinces ahead of demand maturation.
Large scale anchors the volume base while ultra scale gains share at the steepest rate as foreign direct investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Delta fiber corridor anchors Vietnam's data center geography, with submarine cable landings at Danang and Quy Nhon underwriting international bandwidth capacity for the national market.
Red River Delta
Hyperscale deployments concentrate along Hanoi's military-grade fiber backbone, driven by government cloud workloads under Cybersecurity Law mandates. The Ministry of Information and Communications enforces data localization audits that compel domestic infrastructure investment. Bac Ninh industrial corridor hosts Samsung and Foxconn manufacturing clusters generating edge computing demand for predictive maintenance systems.
Southeast Region
Ho Chi Minh City absorbs dedicated capacity procurement from Shopee, Lazada, and Tiki for flash-sale traffic management and real-time inventory synchronization. State Bank of Vietnam guidelines mandate geographic redundancy for core banking systems held by financial institutions. Thu Duc City emerging tech zone attracts medium-scale facilities despite land acquisition constraints and premium pricing.
Central Coast
Danang's strategic APG and AAE-1 cable landing position draws emerging data center investment despite coastal zoning restrictions limiting greenfield expansion. The Vietnam Information Security Association coordinates national technical standards on information security that shape certification requirements. Quy Nhon submarine station eliminates historical international bandwidth bottlenecks for cross-border data flows.
North Central and Central Highlands
Secondary markets outside major metros suffer voltage instability forcing diesel generator overprovisioning, raising operational expenditure by 15-25%. Provincial banks deploy small-scale facilities for regulatory compliance without metropolitan cost structures. Thanh Hoa and Nghe An provinces remain underserved by hyperscale presence despite manufacturing automation growth.
Mekong Delta
Can Tho and surrounding provinces represent latent demand for edge computing nodes serving agricultural IoT and logistics platforms. Vietnam Green Building Council standards unlock preferential electricity tariffs for facilities achieving LEED Silver ratings. Long An province secures land positions for ultra-scale campus developments ahead of demand maturation.
Vietnam Data Center Market Competitive Landscape
Listed leaders compete with private specialists across fiber ownership and government contract access, creating a tiered structure where military-affiliated operators dominate sovereign workloads while foreign-invested facilities capture hyperscale cloud demand. Three archetypes define competitive positioning: state-linked incumbents with captive backbone infrastructure, regional telecom verticals monetizing excess fiber capacity, and Singapore-capitalized foreign operators anchoring international investment. Capacity expansion and strategic fiber interconnection constitute the dominant competitive moves, with operators racing to secure power-secure land positions in Bac Ninh and Long An provinces.
Within the state-linked tier, Viettel IDC exemplifies military-affiliated market presence through backbone dominance, while VNPT occupies a position as legacy telecom vertical expanding into data center operations. ST Telemedia Global Data Centres represents the foreign-capitalized archetype, anchoring Singapore-linked investment flows into certified facilities serving international cloud operators under localization mandates.
| Leading Market Players |
|---|
| Viettel IDC |
| VNPT |
| FPT Telecom |
| CMC Telecom |
| NTT Global Data Centers |
| ST Telemedia Global Data Centres |
| VNG Corporation |
| DTS Communication |
| Telehouse |
| Others |
Pricing and Supply Chain Analysis
Long-term power purchase agreements anchor data center procurement contracts in Vietnam, locking hyperscale operators into fixed-rate electricity structures that stabilize operating expenditure visibility while constraining flexibility to exploit renewable energy price declines. These contractual arrangements bind facility operators to state utility EVN's tariff schedules, with Cybersecurity Law compliance costs embedded as non-negotiable premiums in colocation pricing.
Pricing Analysis
Volume-discount tiering structures separate hyperscale commitments exceeding 5MW from mid-market colocation deployments and single-rack SME arrangements. Pricing stratifies across LEED-certified premium facilities, standard Tier III constructions, and economy-grade Tier II installations in secondary provinces. Cost compression in the economy tier intensifies as provincial banks and manufacturers prioritize regulatory compliance over performance specifications. Hyperscale cloud operators exhibit lowest price sensitivity due to localization mandate urgency, while domestic SMEs face acute budget constraints.
Supply Chain Analysis
Inventory lead times for precision cooling equipment and uninterruptible power supply systems extend deployment schedules, particularly for liquid-cooled GPU clusters where domestic contractor capacity concentrates in Hanoi and Ho Chi Minh City. Supply chains draw from China for electrical switchgear, South Korea for server hardware, and Singapore for fiber interconnect components. Single-source vulnerability permeates diesel generator procurement, with European manufacturers dominating the 2MW-plus segment. Distribution runs through systems integrators in Ho Chi Minh City that bundle cross-connects, managed security, and cloud exchange access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among three domestic operators with end-to-end fiber ownership, compressing vendor options for enterprise procurement teams and elevating negotiation leverage for bundled colocation-cloud contracts.
For Market Incumbents: Compound defensive positioning through captive renewable energy generation in Bac Ninh and Long An provinces, insulating against EVN tariff volatility while meeting Vietnam Green Building Council standards for preferential electricity rates. Deepen fiber backbone control through strategic interconnection with submarine cable landing stations at Danang and Quy Nhon, foreclosing new entrant access to international bandwidth. For New Entrants and Emerging Players: Managed security services for fintech startups represent an under-served layer where incumbent operators bundle infrastructure without specialized compliance expertise. Target Hanoi-based SaaS providers facing Cybersecurity Law audit pressure with sovereign cloud certification as the primary go-to-market wedge, leveraging faster procurement cycles than hyperscale competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among colocation operators with government contract exposure, where Viettel IDC's military affiliation secures multi-year offtake visibility. Long-term viability hinges on land-bank positions in power-secure provinces ahead of AI inference demand maturation. Monitor Ministry of Information and Communications enforcement actions against foreign platforms lacking domestic infrastructure as the signal for accelerated foreign direct investment inflows.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Interconnection | Direct fiber links to APG and AAE-1 landing stations eliminate cross-border latency penalties for cloud operators. |
| Green Building Certification | LEED Silver ratings unlock EVN preferential tariffs that compress operating expenditure for certified facilities. |
| Edge Computing Node Deployment | Bac Ninh manufacturing clusters generate captive demand for predictive maintenance infrastructure near Samsung suppliers. |
| Sovereign Cloud Stack Development | Viettel IDC and FPT Telecom capture public sector workloads through Cybersecurity Law-compliant virtualization platforms. |
| Modular Infrastructure Architecture | Prefabricated power and cooling modules collapse commissioning timelines for GPU-dense AI training clusters. |
Research Methodology
The analysis maps colocation, hyperscale, edge computing, and managed services segments, each validated through facility operators, cloud platform engineers, enterprise IT procurement officers, and Ministry of Information and Communications regulatory specialists. Primary interview data triangulates against secondary sources including EVN electricity tariff filings, Vietnam Information Security Association certification records, submarine cable capacity disclosures, and Vietnam Green Building Council project databases. Bottom-up facility capacity tallies reconcile with top-down cloud provider capex allocations across the analysis window.
Consistency checks validate projected capacity additions against hyperscaler land-positioning announcements and provincial industrial zone development permits. Segmentation dimensions span facility ownership model, infrastructure technology tier, end-user vertical, and operational capacity scale. CAGRs derive from modeled power consumption trajectories, submarine cable bandwidth expansion schedules, and manufacturing automation adoption curves in key industrial corridors.
Underlying assumptions cover Cybersecurity Law enforcement intensity, EVN grid reliability improvements, and liquid cooling contractor capacity expansion, with deviation risk concentrated in regulatory interpretation shifts and international bandwidth pricing volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Brazil Data Center Rack Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
India Data Center Construction Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Delhi-NCR Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Brazil Data Center Server Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Denmark Data Center Physical Security Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Multi-Tenant Data Center Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market