
 Global IoT Fleet Management Market | 2026-2036
Global IoT Fleet Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Fleet Management Market Intelligence
The gap between premium integrated platforms and commodity tracking services is consolidating around data sovereignty and real-time analytics depth. Verizon Connect leverages its cellular infrastructure to anchor North American enterprise accounts with bundled connectivity and compliance tools. Geotab competes through open-ecosystem telematics that sustain third-party developer loyalty and hardware flexibility.
IoT fleet management encompasses the deployment of connected sensors, GPS modules, and edge gateways aboard commercial vehicles to capture telemetry on location, engine diagnostics, driver behavior, and cargo conditions for centralized analysis. Cloud-based deployment leads solution architecture, while edge computing grows fastest where latency-sensitive applications such as collision avoidance and cold-chain integrity require local processing. Route optimization and fuel management concentrate margin pools as fuel-price volatility pushes operators toward algorithmic dispatch and consumption analytics.
The United States Federal Motor Carrier Safety Administration hours-of-service rules and the European Union's Green Deal emissions frameworks shape hardware specifications and data-retention requirements across jurisdictions. China's MIIT mandates domestic cybersecurity certifications for connected vehicle platforms, creating localized compliance barriers for foreign suppliers. Fleet operators and technology vendors must monitor evolving cross-border data-localization rules as they architect multi-territory deployments.
Market Dynamics
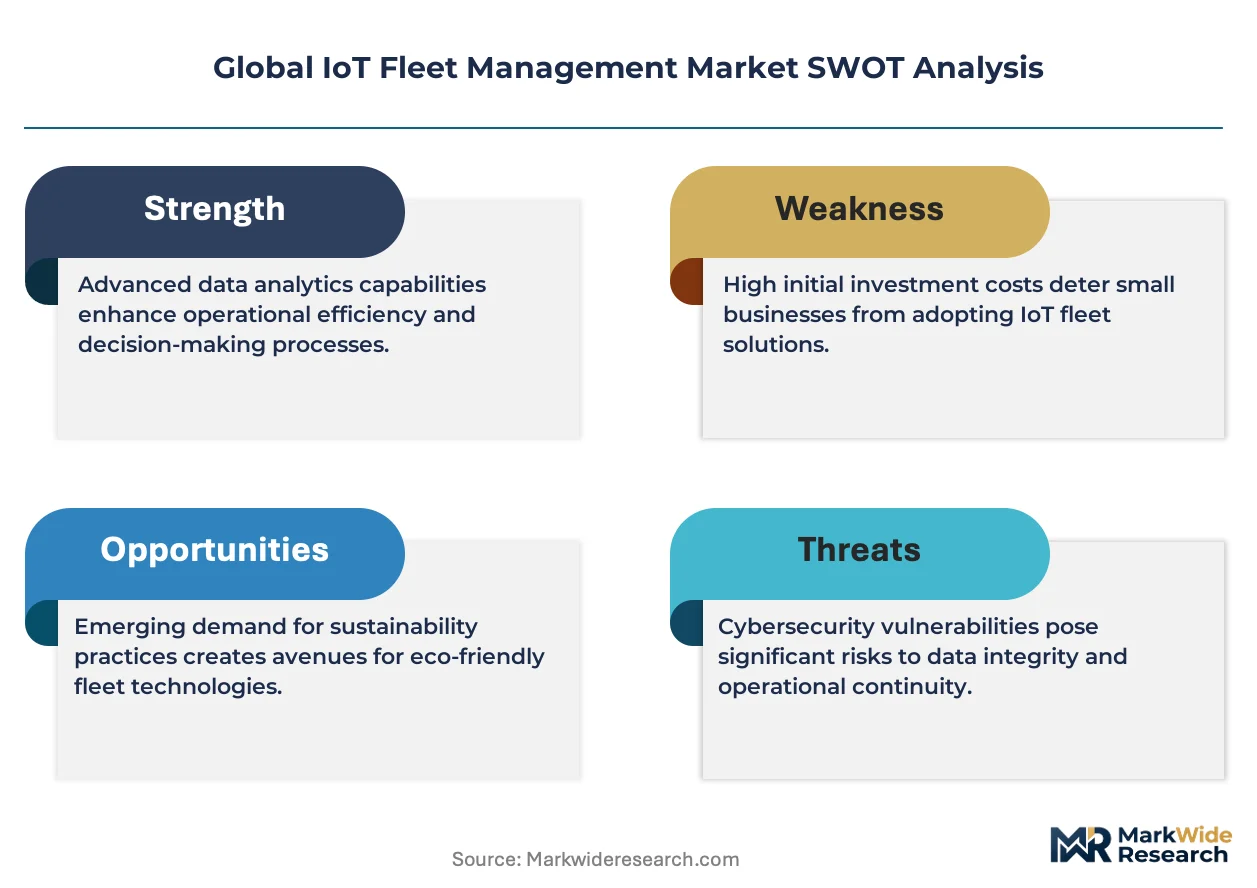
Fleet operators face mounting pressure to reconcile real-time visibility demands with fragmented data sovereignty requirements across jurisdictions. The collision of edge computing latency requirements and cloud-scale analytics is forcing architectural choices that reshape vendor selection criteria and deployment timelines.
Growth Catalysts
- Fuel-efficiency mandates:The United States Federal Motor Carrier Safety Administration hours-of-service rules and the EU Green Deal emissions frameworks compel sensor deployment for compliance documentation and route optimization.
- Edge analytics proliferation:Cold-chain logistics operators in Germany deploy local processing gateways to maintain cargo integrity alerts without cloud latency.
- Cellular infrastructure densification:5G network rollouts across China enable high-frequency telemetry transmission for collision-avoidance systems in dense urban corridors.
Market Restraints
- Semiconductor supply concentration:GPS module and edge gateway production concentrates in East Asian foundries, exposing fleet hardware procurement to geopolitical disruption risks.
- Cybersecurity certification fragmentation:China's MIIT domestic certification requirements create localized compliance barriers that inflate platform adaptation costs for foreign telematics vendors.
- Legacy fleet retrofit economics:Aging diesel vehicle populations in Eastern European logistics fleets carry prohibitive installation costs for integrated sensor suites.
Strategic Opportunities
- India logistics digitization:The country's PLI scheme incentives for automotive electronics manufacturing create localized production advantages for telematics hardware serving domestic fleet operators.
- Predictive maintenance convergence:Machine learning algorithms fused with engine diagnostic sensors enable failure prediction models that reduce unplanned downtime for long-haul operators.
- Subscription-based platform models:Cloud-native fleet management vendors bypass capital-intensive hardware sales through software-as-a-service pricing that accelerates adoption among small and mid-sized carriers.
Industry Challenges
- Embedded systems engineering scarcity:Fleet operators and vendors compete for limited talent pools capable of integrating automotive-grade sensors with enterprise cloud architectures.
- Multi-jurisdiction data localization:Cross-border fleet deployments require architectural segmentation to satisfy divergent data-retention rules across the United States, European Union, and China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Fleet Management Market |
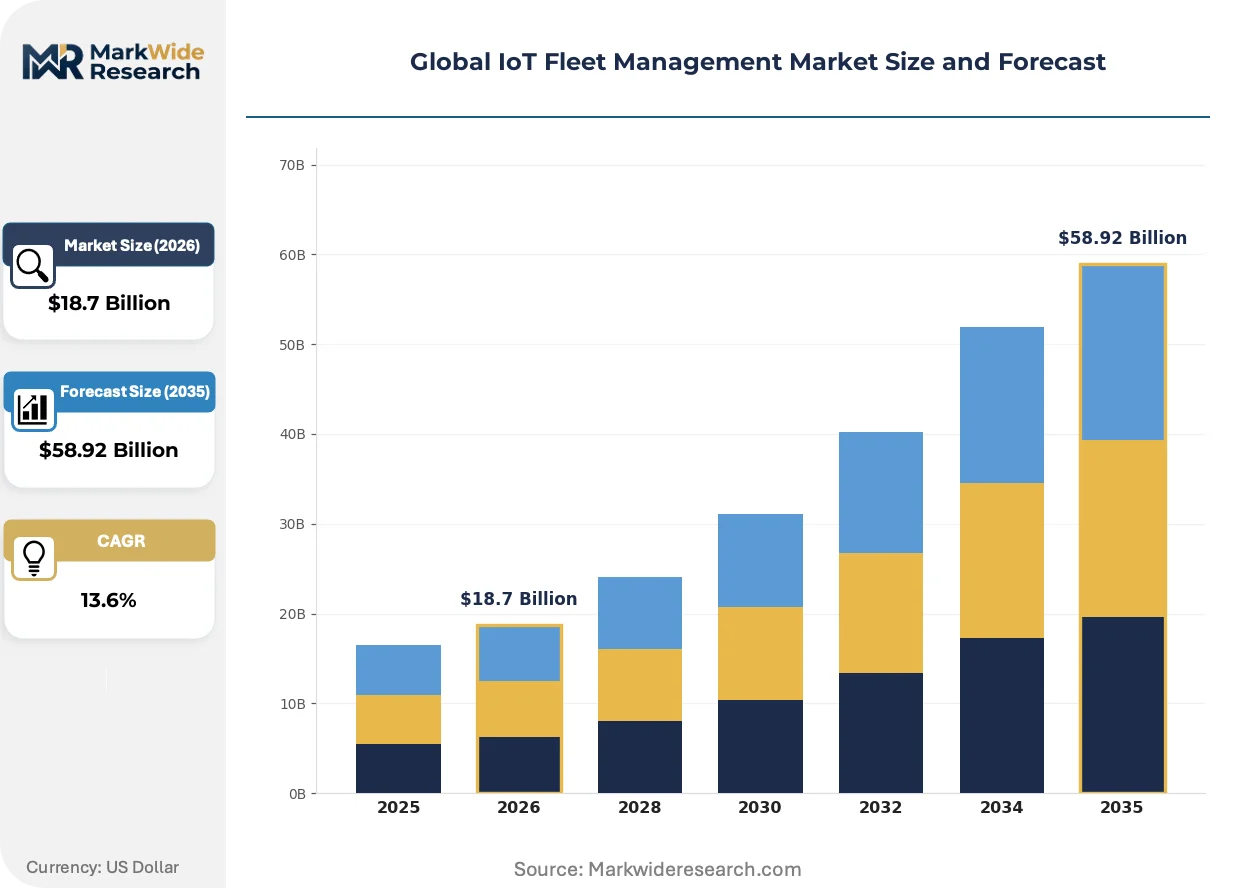
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $58.92 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution Offering: Vehicle Tracking, Asset Monitoring, Driver Behavior, Route Optimization, Fuel Management Application: Logistics, Public Transportation, Delivery Services, Waste Management, Field Service Management End User: Fleet Operators, Third-Party Logistics, Last Mile Providers, Service Contractors |
| Companies Covered | Verizon Connect, AT&T, Geotab, Samsara, Trimble, Cisco Systems, IBM, Omnitracs, Fleet Complete, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Fleet Management Market Strategic Shifts & Innovations
Telematics platforms are converging with autonomous vehicle perception stacks, blurring the boundary between fleet management and advanced driver-assistance systems. This fusion is redrawing competitive boundaries between traditional fleet software vendors and automotive technology suppliers.
Digital twin technology is integrating vehicle telemetry streams with simulation engines to model fleet-wide fuel consumption and maintenance schedules. Large logistics operators in the United States and Germany pilot these systems to compress optimization cycles from quarterly to weekly intervals. The technology is integrating predictive analytics directly into dispatch workflows, reducing planner intervention in routine routing decisions.
The EU AI Act risk-classification framework imposes documentation and human-oversight requirements on automated fleet dispatch algorithms. Logistics software vendors serving European markets must rearchitect decision engines to maintain audit trails and operator override capabilities. Cold-chain and hazardous-material carriers face the most stringent compliance timelines given the safety-critical nature of their routing decisions.
Third-party logistics providers now demand API-first platform architectures that unbundle telematics hardware from analytics software. This procurement pattern favors modular vendors over vertically integrated incumbents and accelerates switching between analytics providers without hardware replacement. The shift is most pronounced in North American and Western European contract logistics segments where carrier flexibility directly impacts customer retention rates.
Global IoT Fleet Management Market Segmentation
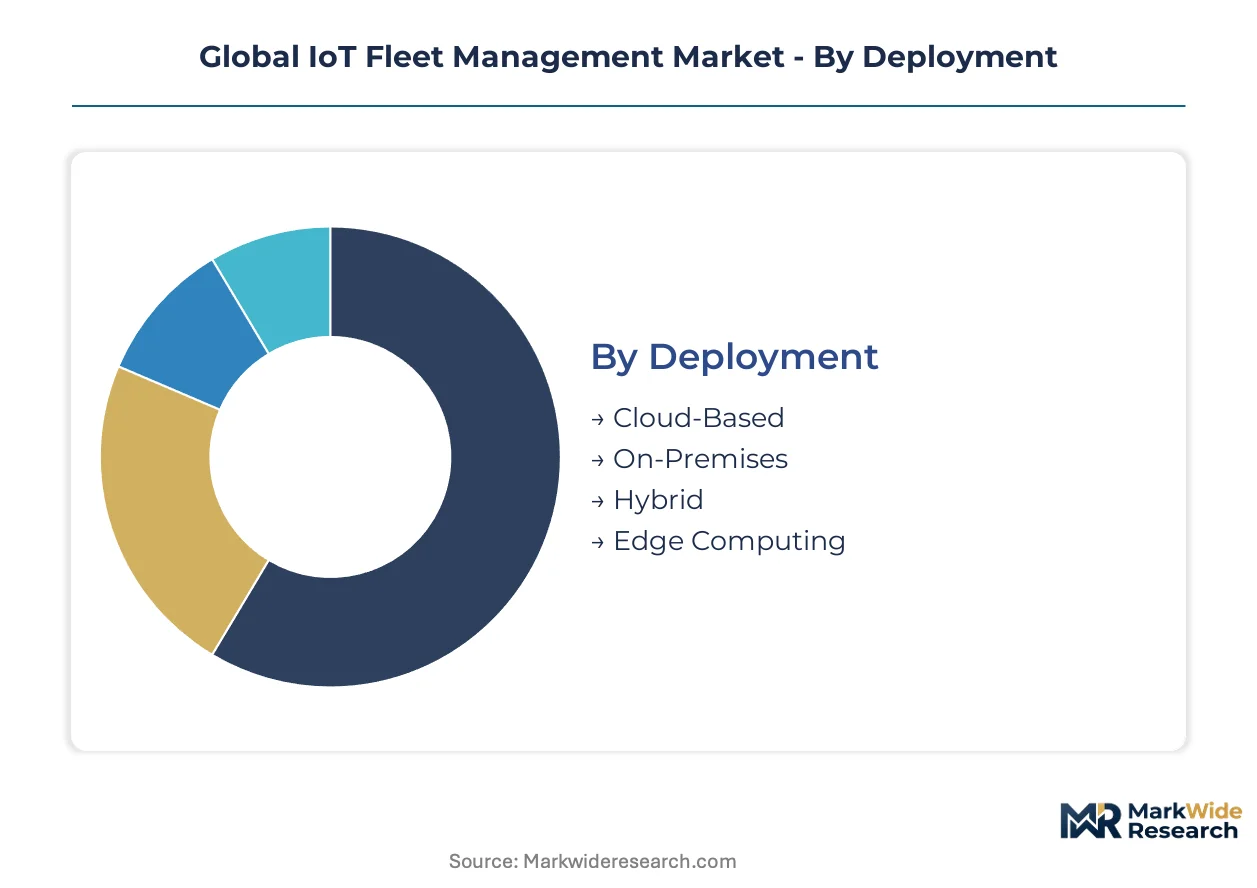
IoT fleet management architectures fragment across deployment models, solution depth, and operational use cases. Procurement decisions hinge on latency tolerance, regulatory jurisdiction, and the trade-off between capital intensity and subscription flexibility.
Deployment:
Latency requirements and data sovereignty rules determine whether operators centralize processing or distribute intelligence to the vehicle edge.
- Cloud-Based:Centralized telemetry aggregation enables fleet-wide analytics without local infrastructure. Logistics operators in the United States and Germany favor this model for cross-border visibility, though GDPR and state-level privacy laws force architectural segmentation.
- Edge Computing:Local processing gateways execute collision-avoidance algorithms and cold-chain alerts without round-trip latency. Chinese carriers deploy these systems in dense urban corridors where 5G densification supports high-frequency sensor transmission.
- Hybrid:Split architectures retain sensitive diagnostics on-vehicle while pushing aggregated metrics to cloud dashboards. This configuration satisfies China's MIIT cybersecurity mandates while preserving analytics scale.
- On-Premises:Self-hosted platforms serve defense contractors and government fleets with air-gapped security requirements.
Cloud-Based leads on scale; Edge Computing leads on momentum.
Solution Offering:
Margin concentration follows fuel-price volatility and insurance premium pressures, not hardware commoditization.
- Fuel Management:Algorithmic consumption analytics and idle-time monitoring compress diesel expenditure for long-haul operators. European Union Green Deal compliance documentation drives adoption among German and French logistics fleets facing emissions audit requirements.
- Route Optimization:Real-time dispatch engines integrate traffic, weather, and delivery windows to minimize kilometers per stop. Last-mile providers in the United States deploy these tools to counter driver shortage costs and customer delivery-window compression.
- Vehicle Tracking:GPS-based location services form the commodity base layer of fleet telematics.
- Driver Behavior:Acceleration, braking, and cornering telemetry inform insurance scoring and safety coaching programs.
- Asset Monitoring:Cargo-condition sensors protect high-value or temperature-sensitive shipments.
Fuel Management leads on scale; Route Optimization leads on momentum.
Application:
Operational intensity and regulatory exposure determine sensor deployment density and analytics sophistication.
- Logistics:Multi-modal freight operators coordinate thousands of assets across jurisdictions with divergent hours-of-service rules. United States Federal Motor Carrier Safety Administration electronic logging device mandates created baseline connectivity requirements that now extend to predictive maintenance.
- Delivery Services:Parcel and food-delivery fleets optimize stop sequencing against narrow customer windows. Chinese and Indian urban operators face municipal restrictions on vehicle types and emission zones that route optimization engines must incorporate dynamically.
- Public Transportation:Municipal bus and rail systems prioritize passenger safety and schedule adherence over fuel efficiency.
- Waste Management:Heavy-duty vocational fleets track bin-fill sensors and hydraulic system health.
- Field Service Management:Utility and telecom technicians require job-site arrival verification and parts-inventory integration.
Logistics leads on scale; Delivery Services leads on momentum.
End User:
Balance-sheet structure and customer contractual risk determine preference for capital expenditure versus subscription procurement.
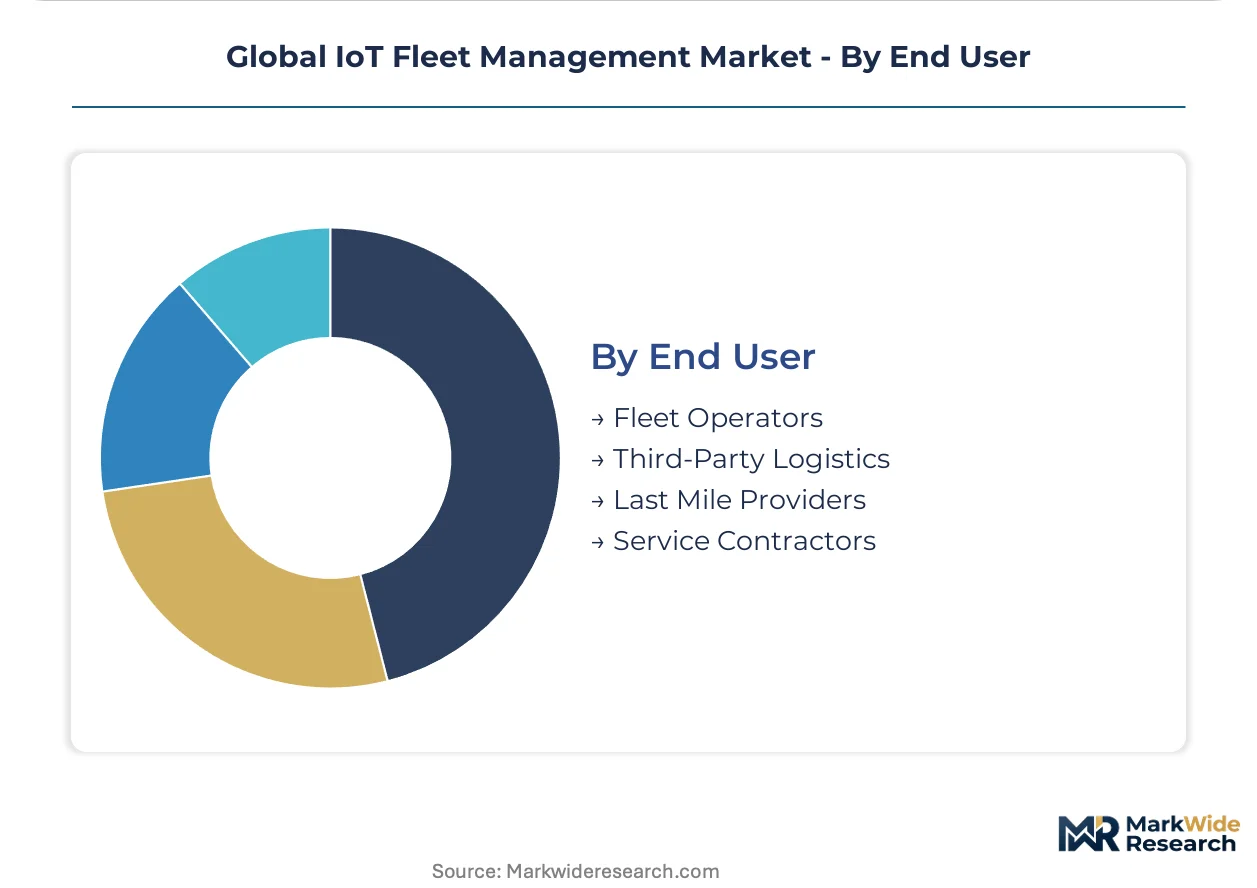
- Third-Party Logistics:Contract carriers face customer-mandated visibility requirements that force rapid platform adoption. German and Dutch 3PLs serving automotive OEMs deploy API-first architectures to satisfy just-in-sequence delivery tracking demands.
- Last Mile Providers:E-commerce fulfillment specialists operate thin margins that favor software-as-a-service pricing over hardware ownership. Indian quick-commerce startups leverage subscription telematics to scale fleet visibility without balance-sheet strain.
- Fleet Operators:Asset-owning carriers with captive maintenance infrastructure prefer integrated platforms.
- Service Contractors:HVAC, plumbing, and electrical technicians prioritize job-site routing and customer notification automation.
Third-Party Logistics leads on scale; Last Mile Providers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers cluster in Detroit, Stuttgart, and Shenzhen anchor the three dominant development ecosystems for connected vehicle platforms. These talent concentrations determine where platform vendors establish solution centers and compliance engineering teams. Regional regulatory divergence forces multi-territory operators to maintain parallel architecture tracks.
United States
Fleet digitization accelerates around the Federal Motor Carrier Safety Administration's electronic logging device mandates and hours-of-service enforcement. The FMCSA rules compel long-haul carriers to maintain tamper-proof connectivity for compliance documentation. Detroit anchors hardware engineering for integrated telematics platforms serving North American enterprise accounts.
Germany
Automotive OEM logistics networks drive demand for just-in-sequence delivery tracking and emissions compliance documentation. The EU Green Deal framework imposes binding carbon reduction targets that force freight operators to deploy fuel analytics and route optimization engines. Stuttgart hosts engineering centers where platform vendors integrate edge gateways with cold-chain integrity systems.
China
5G network densification enables high-frequency telemetry transmission for collision-avoidance systems in dense urban freight corridors. The Ministry of Industry and Information Technology mandates domestic cybersecurity certifications that create localized compliance barriers for foreign telematics vendors. Shenzhen concentrates hardware manufacturing for GPS modules and edge gateways serving domestic fleet operators.
India
Quick-commerce startups and e-commerce fulfillment specialists scale fleet visibility through subscription telematics to avoid balance-sheet strain from hardware ownership. The Production-Linked Incentive scheme for automotive electronics manufacturing creates localized production advantages for domestic telematics hardware. Bangalore anchors software development centers where vendors build cloud-native dispatch platforms for last-mile operators.
United Kingdom
Third-party logistics providers serving European automotive supply chains demand API-first platform architectures that unbundle hardware from analytics software. The Driver and Vehicle Standards Agency enforces tachograph compliance that extends digital logging requirements to smaller fleet operators. Midlands logistics clusters pilot predictive maintenance convergence with engine diagnostic sensors for contract freight carriers.
Global IoT Fleet Management Market Key Industry Players
Top-tier vendors anchor cellular infrastructure and enterprise software ecosystems, while mid-tier specialists compete through hardware flexibility and developer ecosystems. The market structures around three concentration points: telecommunications carriers with captive connectivity assets, open-platform telematics vendors sustaining third-party developer loyalty, and cloud-native software vendors bypassing hardware sales through subscription pricing. Strategic moves center on bundling connectivity with compliance tools and rearchitecting decision engines for EU AI Act documentation requirements.
Within the telecommunications-anchored tier, Verizon Connect and AT&T occupy positions that leverage cellular infrastructure to bundle connectivity with regulatory compliance documentation. Geotab exemplifies the open-ecosystem archetype where hardware flexibility sustains third-party developer loyalty across modular deployments. These three vendors represent distinct competitive vectors: captive infrastructure, platform openness, and developer ecosystem depth.
| Leading Market Players |
|---|
| Verizon Connect |
| AT&T |
| Geotab |
| Samsara |
| Trimble |
| Cisco Systems |
| IBM |
| Omnitracs |
| Fleet Complete |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up telematics specialists anchor supply-side pricing discipline through captive hardware sourcing and long-term connectivity contracts with cellular carriers. Their bundled service models compress procurement friction for fleet operators while extracting margin through subscription lock-in and compliance-tool add-ons.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive pricing architecture in fleet telematics. Three-tier pricing structure across premium, standard, and economy levels separates enterprise integrated platforms from modular API-first offerings and commodity GPS tracking. Price differentiation rests on certification grade—FMCSA ELD compliance versus EU Green Deal emissions documentation—and volume scale across multi-thousand-vehicle deployments. Pricing pressure stems from API-first procurement patterns favoring software-only subscriptions that bypass hardware margin capture. Small and mid-sized carriers exhibit highest price sensitivity, while automotive OEM logistics networks accept premium tiers for just-in-sequence delivery tracking.
Supply Chain Analysis
China's MIIT domestic cybersecurity certifications reshape sourcing patterns for foreign platform vendors seeking market access. GPS module and edge gateway production concentrates in China, Taiwan, and South Korea, drawing from semiconductor foundry capacity and automotive-grade sensor manufacturing clusters. Raw material dependencies span lithium-ion cells for vehicle gateways, rare-earth magnets for GPS antennas, and specialized polymers for ruggedized enclosures. Single-source vulnerability runs through East Asian semiconductor fabrication exposed to geopolitical disruption. Distribution runs through direct enterprise sales for large fleet operators and channel partners serving small-carrier segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in IoT fleet management hinges on predictive maintenance convergence compressing unplanned downtime costs for long-haul operators while premium-tier compliance bundles capture EU Green Deal documentation demand.
For Market Incumbents: To counter API-first platform vendors unbundling hardware from analytics, Verizon Connect and AT&T should deepen captive supply of edge gateways through backward integration into automotive-grade sensor manufacturing. Certification investment in China's MIIT cybersecurity framework preserves market access against domestic competitors. Channel control through exclusive cellular connectivity contracts reinforces enterprise account retention against modular substitutes. For New Entrants and Emerging Players: Cloud-native subscription platforms offer the most penetrable entry vector, targeting Indian quick-commerce startups and Eastern European mid-sized carriers with SaaS pricing that avoids balance-sheet strain. White-space concentration sits in predictive maintenance algorithms for aging diesel fleets where legacy retrofit economics have stalled integrated sensor deployment. Go-to-market execution should prioritize API-first architectures that satisfy third-party logistics provider procurement patterns in North American contract logistics. For Investors and Strategic Acquirers: Telecommunications carriers with captive connectivity assets are the most active acquirer in this space, seeking to bundle cellular infrastructure with compliance documentation tools. Long-term viability favors platform vendors sustaining third-party developer ecosystems through hardware flexibility. Acquisition target archetypes include edge-analytics specialists with cold-chain integrity algorithms and cloud-native dispatch platforms serving last-mile density. The signal to watch is EU AI Act enforcement timelines forcing rearchitecture of automated dispatch engines for audit-trail compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies telematics hardware with third-party logistics APIs serving German automotive OEM just-in-sequence networks. |
| Acquisition of Specialist Firm | Captures edge-analytics capabilities for collision-avoidance systems in China's 5G-densified urban corridors. |
| Product Launch | Introduces predictive maintenance modules reducing unplanned downtime for US long-haul FMCSA-regulated fleets. |
| Strategic Partnership | Links cellular carriers with cold-chain sensor vendors to satisfy EU Green Deal emissions audit requirements. |
| Geographic Expansion | Establishes localized production under India's PLI scheme for automotive electronics serving domestic last-mile operators. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with fleet operations directors, telematics platform product managers, cellular carrier enterprise sales leads, and automotive OEM logistics procurement officers. Secondary validation draws from FMCSA regulatory filings, EU Green Deal implementation directives, MIIT certification databases, and SEC disclosures from publicly traded fleet technology vendors. Bottom-up vehicle-unit deployment estimates triangulate against top-down market value assessments.
Granularity-level modeling distinguishes cloud-based, edge, hybrid, and on-premises deployment architectures while tracking fuel management, route optimization, vehicle tracking, driver behavior, and asset monitoring solution offerings across logistics, delivery services, public transportation, waste management, and field service management applications. CAGRs derive from logistic curve penetration modeling of electronic logging device mandates and emissions compliance deadlines. Forecast inputs incorporate 5G network densification timelines and semiconductor supply concentration risk scenarios.
The model assumes a particular technology adoption path; alternative pathways for autonomous vehicle perception stack integration would alter the outlook. Forecasts reflect assumptions around regulatory enforcement consistency, supply chain disruption frequency, and fleet operator digitization budget cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Autonomous Warehouse Charging Infrastructure Market
Smart Transportation Solutions
Smart Parking Technologies Market
Smart Transportation Solutions
Automotive V2X Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market