
 North America Smart Transportation Market | 2026-2036
North America Smart Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Transportation Market Analytics
The gap between premium integrated mobility platforms and commodity point-solution vendors is hardening across procurement cycles. Siemens Mobility leverages its rail signaling heritage to dominate turnkey transit automation contracts in major US metropolitan areas. Cisco Systems, Inc. anchors its position through edge-network infrastructure that sustains real-time data throughput for connected vehicle corridors. Cubic Corporation differentiates via fare-payment system integration that controls transit agency wallet share across North American cities.
North America Smart Transportation encompasses the hardware, software, and communication infrastructure enabling real-time data exchange between vehicles, infrastructure, and centralized management platforms, typically operating across sub-50 millisecond latency thresholds for safety-critical V2X messaging. The primary purpose is to optimize throughput, reduce emissions, and prevent collisions across multimodal surface transportation networks. Traffic Management Systems and Vehicle-to-Everything (V2X) command disproportionate capital allocation as municipalities prioritize congestion relief and pedestrian safety. Fleet Management Software occupies expanding margin pools as private logistics operators demand predictive maintenance integration with route optimization.
The US Department of Transportation, Transport Canada, and the Federal Communications Commission collectively shape market access through spectrum allocation rules, infrastructure grant eligibility, and cross-border interoperability mandates that elevate cybersecurity and data governance standards. California's Advanced Clean Trucks regulation and Ontario's automated vehicle testing permits create divergent compliance pathways that fragment vendor development roadmaps. Stakeholders must monitor how pending US reauthorization of surface transportation funding reweights rail versus roadway investment priorities.
Market Dynamics
AI-driven traffic signal optimization is forcing municipal procurement departments to abandon legacy point-solution vendors in favor of integrated mobility platforms capable of sub-50 millisecond V2X latency. This technology shift is compressing vendor qualification timelines while elevating cybersecurity mandates across US and Canadian transit agencies.
Growth Catalysts
- USDOT Smart City Challenge funding:Federal grant eligibility criteria now mandate real-time data interoperability, compelling transit agencies to upgrade legacy traffic management infrastructure.
- California Advanced Clean Trucks regulation:Fleet electrification mandates in the state's congested urban corridors are accelerating procurement of predictive maintenance-integrated fleet management software.
- Edge-network infrastructure deployment:Connected vehicle corridors across Ontario's Greater Toronto Area require sustained real-time data throughput, driving capital allocation toward communication infrastructure upgrades.
Market Restraints
- 5.9 GHz spectrum uncertainty:FCC rulemaking delays on dedicated short-range communications spectrum allocation create investment paralysis for V2X hardware vendors.
- Silicon supply concentration:Edge computing chipsets for traffic signal controllers depend on concentrated Asian foundry capacity, exposing North American deployments to supply disruption.
- Interoperability fragmentation:Divergent compliance pathways between California's automated vehicle testing permits and Ontario's multimodal integration standards splinter vendor development roadmaps.
Strategic Opportunities
- Mid-sized US metropolitan areas:Cities between 500,000 and 2 million population remain underpenetrated for turnkey transit automation, presenting white space for integrated platform vendors.
- Predictive maintenance convergence:AI-driven traffic signal optimization platforms are merging with fleet health monitoring, creating new margin pools for vendors with dual capabilities.
- Canada's Connectivity and Automation framework:Federal policy mandates for cross-border interoperability with US corridors create regulatory tailwinds for vendors meeting elevated cybersecurity standards.
Industry Challenges
- Cybersecurity certification timelines:Transport Canada's data governance standards and USDOT grant requirements impose extended validation cycles that delay platform deployment.
- Legacy traffic signal integration:Municipal agencies operate decades-old signal hardware that requires costly retrofitting to achieve sub-50 millisecond V2X messaging compatibility.
- Multimodal data standardization:Absence of unified protocols between rail signaling, roadway traffic management, and fare-payment systems complicates turnkey contract execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Transportation Market |
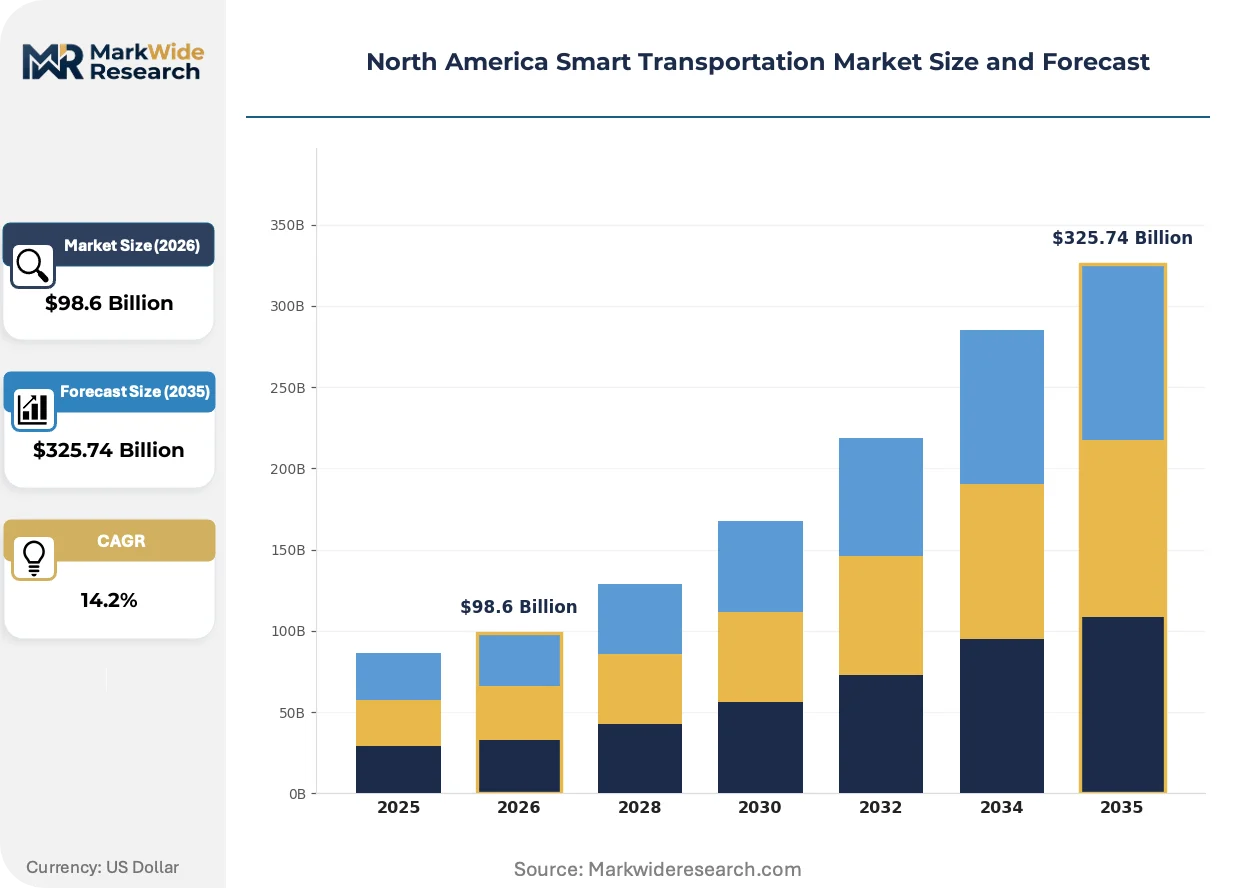
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $325.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Management Systems, Smart Ticketing Solutions, Fleet Management Software, Vehicle-to-Everything (V2X) Application: Public Transit, Freight Logistics, Connected Vehicles, Smart Infrastructure Technology: IoT, Artificial Intelligence, Cloud Computing, GPS Tracking End User: Government Agencies, Transport Operators, Private Fleet Owners, Automotive Manufacturers |
| Companies Covered | IBM Corporation, Siemens Mobility, Cisco Systems, Inc., Alstom SA, Cubic Corporation, Thales Group, Hitachi Ltd., TransCore, Iteris, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Transportation Market Evolving Landscape
Edge computing architectures are reshaping competitive positioning across North American smart transportation procurement. Three distinct vectors are redirecting capital allocation and vendor qualification requirements.
Edge-network infrastructure is electrifying real-time traffic signal control by processing V2X messaging at roadside units rather than centralized data centers. Municipal transit agencies in California's congested corridors are deploying these architectures aggressively to achieve pedestrian safety mandates. The technology is compressing latency thresholds below 50 milliseconds, rendering legacy cloud-dependent platforms obsolete for safety-critical applications.
The USDOT's surface transportation reauthorization debate is reshaping rail versus roadway investment priorities. Congressional deliberations over funding weights are compelling integrated mobility vendors to diversify capabilities across both transit modes. Rail signaling heritage providers are responding by acquiring V2X communication specialists to maintain eligibility for multimodal contracts.
Outcome-based maintenance contracts are displacing traditional hardware procurement across Canadian fleet operators. Logistics providers in Ontario's Greater Toronto Area now demand predictive maintenance integration with route optimization software, unbundling equipment sales from service agreements. This behavioral shift is most visible among private operators subject to the province's automated vehicle testing permit requirements.
North America Smart Transportation Market Segmentation
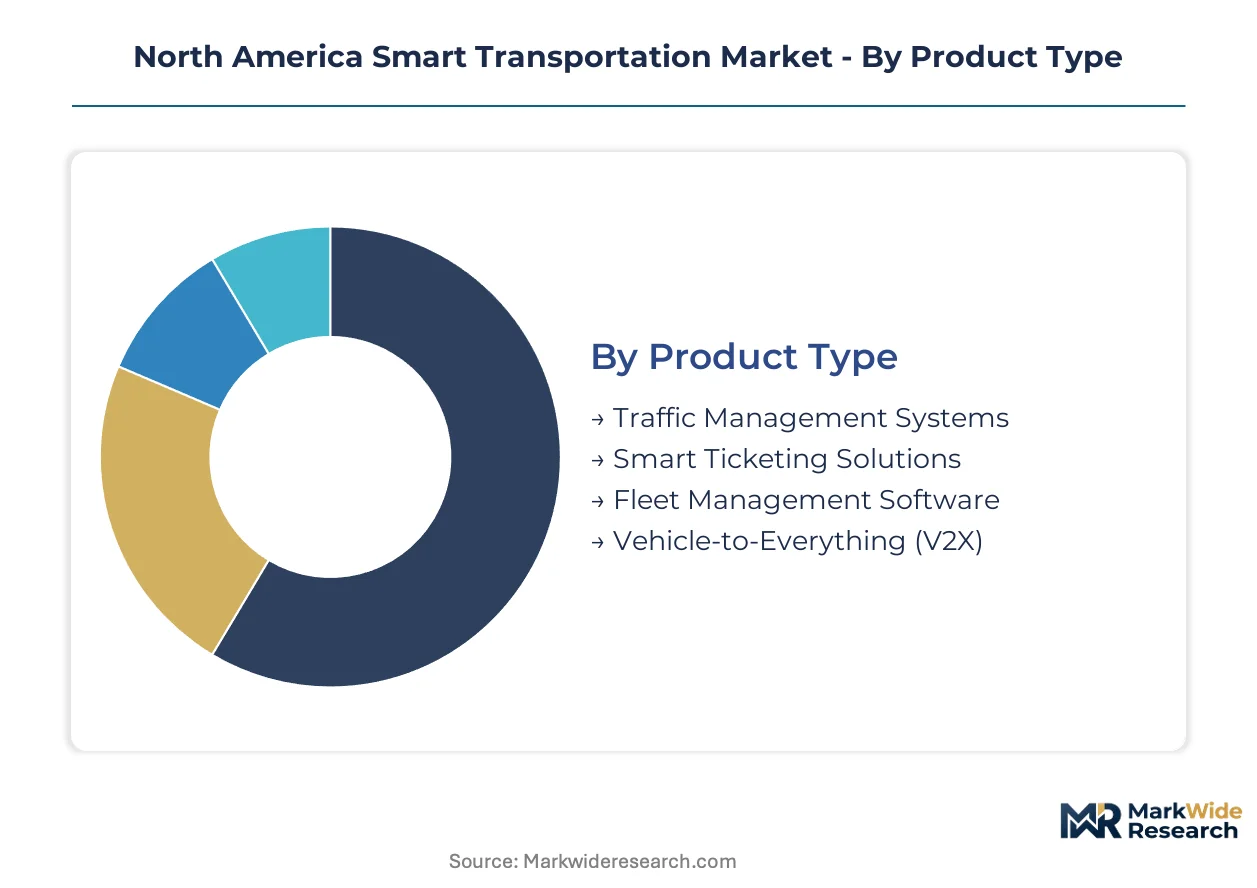
Smart transportation procurement in North America diverges sharply by capital intensity and integration complexity. Municipal agencies prioritize unified platforms over point solutions, while private operators chase predictive capabilities that compress total cost of ownership.
Product Type:
Traffic Management Systems and V2X infrastructure demand the heaviest upfront capital deployment, with roadside unit networks requiring fiber backhaul and edge computing installations across thousands of signalized intersections.
- Traffic Management Systems:Centralized platforms coordinating signal timing, incident detection, and dynamic lane allocation across urban corridors. California's congested metropolitan areas are concentrating procurement here, driven by USDOT Smart City Challenge eligibility criteria mandating real-time interoperability.
- Vehicle-to-Everything (V2X):Dedicated short-range communication hardware enabling sub-50 millisecond messaging between vehicles, infrastructure, and pedestrians. Ontario's Greater Toronto Area multimodal projects are absorbing capacity, though FCC spectrum uncertainty constrains vendor investment timelines.
- Smart Ticketing Solutions:Contactless fare collection and account-based payment systems with open-loop bank card integration.
- Fleet Management Software:Predictive maintenance and route optimization platforms for electrified commercial vehicle fleets.
Most installed capacity flows through Traffic Management Systems. Expansion is steepest in V2X as connected vehicle corridors proliferate.
Application:
Public Transit commands the largest share of municipal capital budgets, while Freight Logistics offers superior margin capture for vendors with predictive maintenance integration.
- Public Transit:Rail signaling automation, bus rapid transit corridors, and multimodal interchange coordination. Canadian cities under the Connectivity and Automation framework are prioritizing cross-border interoperability with US corridors, elevating cybersecurity certification requirements.
- Freight Logistics:Predictive maintenance-integrated route optimization for long-haul and last-mile electrified fleets. California's Advanced Clean Trucks regulation is compressing procurement cycles as operators retrofit for zero-emission mandates.
- Connected Vehicles:Passenger vehicle integration with roadside infrastructure for collision avoidance and traffic flow optimization.
- Smart Infrastructure:Sensor networks, digital signage, and adaptive lighting systems supporting multimodal safety.
Public Transit absorbs the majority of current deployment spending. Freight Logistics is climbing the fastest as private operators unbundle equipment sales from outcome-based service agreements.
Technology:
Artificial Intelligence and IoT sensor networks concentrate R&D investment, with edge-processing architectures displacing cloud-dependent platforms for latency-critical safety applications.
- Artificial Intelligence:Machine learning models for traffic signal optimization, incident prediction, and demand forecasting. US metropolitan areas between 500,000 and 2 million population present underpenetrated white space for AI-driven platform vendors.
- IoT:Distributed sensor networks capturing vehicle counts, pedestrian presence, and environmental conditions. Ontario's automated vehicle testing permit requirements are standardizing data formats across provincial deployments.
- Cloud Computing:Centralized data aggregation and analytics platforms for non-time-critical operational intelligence.
- GPS Tracking:Satellite-based fleet positioning and geofencing for route compliance and asset recovery.
IoT sensor networks represent the dominant installed base. Artificial Intelligence is gaining share fastest as municipalities abandon legacy signal timing for adaptive optimization.
End User:
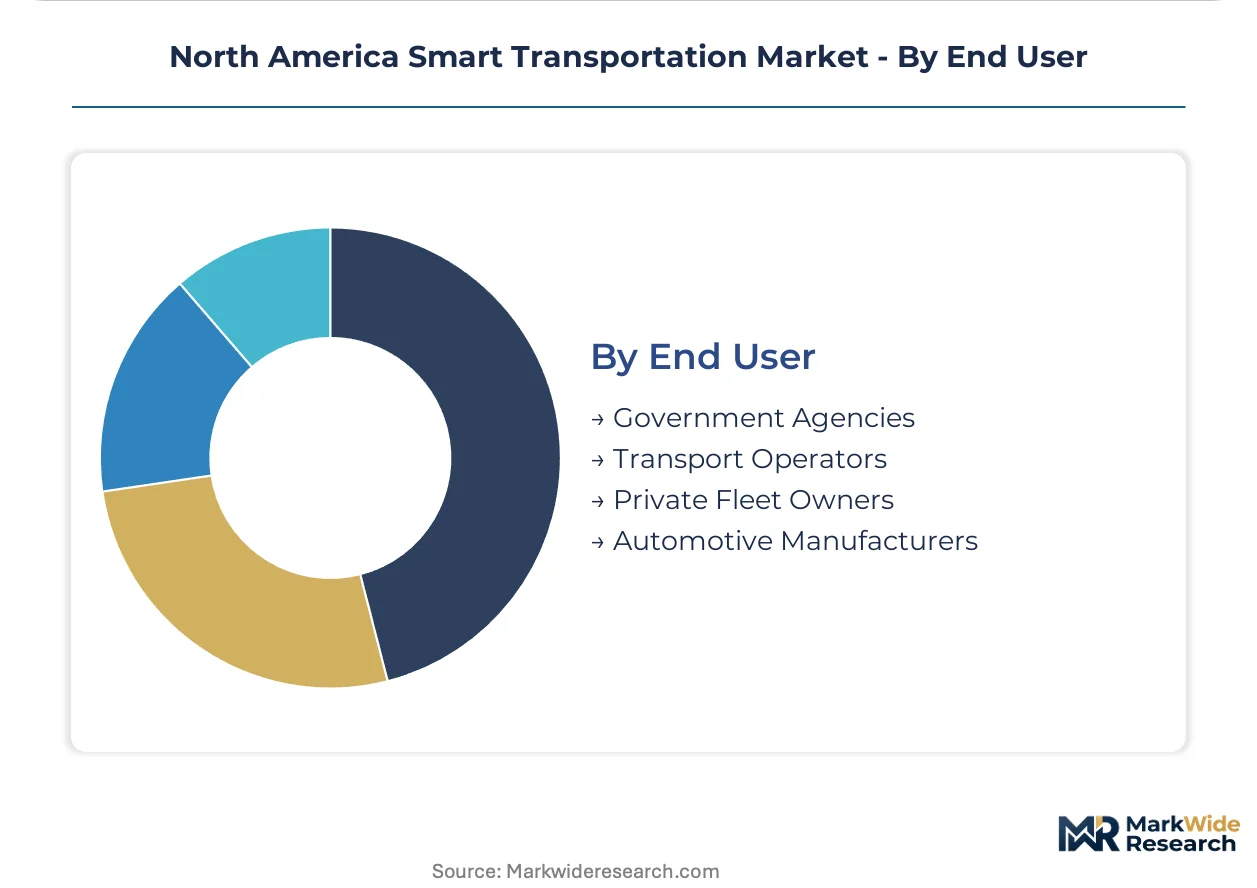
Government Agencies control procurement volume through federal grant programs, while Transport Operators capture recurring revenue via long-term service contracts.
- Government Agencies:Municipal, state, and federal transportation departments funding infrastructure modernization. USDOT surface transportation reauthorization debates are reweighting rail versus roadway investment priorities, compelling vendor diversification across both modes.
- Transport Operators:Public transit authorities and toll road concessionaires managing operational technology. Toronto-area agencies are consolidating fare-payment system integration to control vendor wallet share across multimodal networks.
- Private Fleet Owners:Logistics companies and delivery services procuring predictive maintenance and route optimization software.
- Automotive Manufacturers:OEMs integrating V2X communication modules and connected vehicle platforms.
Government Agencies channel the majority of capital expenditure. Transport Operators are expanding most quickly as outcome-based maintenance contracts displace traditional hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands substantially greater procurement volume than Canada, though both jurisdictions face converging pressure from federal interoperability mandates and spectrum allocation uncertainty.
United States
California's congested urban corridors and Texas metropolitan expansion drive concentrated demand for AI-driven traffic signal platforms. The USDOT Smart City Challenge funding criteria mandate real-time data interoperability, compelling municipal agencies to abandon legacy point-solution vendors. Los Angeles and Houston transit authorities are deploying edge-network infrastructure to achieve sub-50 millisecond V2X latency thresholds.
Canada
Ontario's Greater Toronto Area multimodal integration projects absorb the majority of Canadian capital allocation for connected vehicle corridors. Transport Canada's Connectivity and Automation in Transportation policy framework imposes elevated cybersecurity certification requirements that filter vendor qualification. Toronto-area agencies are consolidating fare-payment system integration to control vendor wallet share across multimodal networks.
Mexico
Mexico City Metro and Nuevo León industrial corridors are emerging as procurement centers for fleet management software serving cross-border logistics. The country's national transportation regulator is developing automated vehicle testing protocols aligned with USMCA trade agreement technology chapters. Monterrey-based logistics operators are adopting predictive maintenance platforms to comply with California-bound freight electrification mandates.
North America Smart Transportation Market Competitive Landscape
Top-tier vendors anchor integrated mobility platforms, while commodity point-solution providers face compression in municipal procurement cycles. The vendor base stratifies across three functional tiers: rail signaling heritage operators, edge-network infrastructure specialists, and fare-payment system integrators. Dominant competitive moves include portfolio diversification across transit modes and strategic partnerships to achieve cybersecurity certification compliance.
Among diversified technology conglomerates, IBM Corporation and Cisco Systems, Inc. occupy positions reflecting enterprise software and network infrastructure heritage respectively. Siemens Mobility exemplifies the rail signaling archetype extending into turnkey transit automation. Cubic Corporation represents the fare-payment integration specialist segment controlling transit agency wallet share.
| Leading Market Players |
|---|
| IBM Corporation |
| Siemens Mobility |
| Cisco Systems, Inc. |
| Alstom SA |
| Cubic Corporation |
| Thales Group |
| Hitachi Ltd. |
| TransCore |
| Iteris, Inc. |
| Others |
Value Network & Pricing Analysis
Embedded systems engineers concentrated in California's Bay Area and Ontario's Waterloo corridor command wage premiums that compress margin spreads between integrated mobility platforms and commodity point-solution vendors. Labor-cost differentials between these talent clusters and mid-sized US metropolitan areas drive tiered pricing architectures that separate premium turnkey vendors from regional system integrators.
Pricing Analysis
The bundled-vs-unbundled service split separates outcome-based maintenance contracts from traditional hardware procurement across North American transit agencies. Three-tier pricing structure across premium, standard, and economy levels reflects cybersecurity certification grade and after-sales service bundling. Pricing pressure stems from FCC spectrum uncertainty delaying V2X hardware vendor investment timelines. Municipal procurement departments exhibit highest price sensitivity, while private fleet operators absorb premium tiers for predictive maintenance integration.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for edge computing chipsets powering traffic signal controllers. Raw material dependencies center on advanced semiconductors, fiber optic cable, and lithium-ion battery cells for electrified fleet infrastructure. Tariff exposure on Asian foundry output creates procurement risk for North American deployment timelines. Distribution runs through systems integrators with rail signaling heritage and cybersecurity certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance convergence and mid-sized metropolitan white space, justified by outcome-based contract structures that unbundle equipment sales from recurring service revenue.
For Market Incumbents: Deploy backward integration into edge computing hardware to secure chipset supply against Taiwan foundry concentration. Acquire V2X communication specialists to maintain multimodal contract eligibility under USDOT surface transportation reauthorization debates. Counter commodity point-solution vendors through cybersecurity certification investment that filters municipal procurement shortlists. For New Entrants and Emerging Players: Launch via outcome-based maintenance contracts targeting US metropolitan areas between 500,000 and 2 million population. Penetrate white space in AI-driven traffic signal optimization for cities abandoned by legacy point-solution vendors. Exploit divergent compliance pathways between California and Ontario to anchor regional specialization before cross-border expansion. For Investors and Strategic Acquirers: Valuations sit cheapest among fare-payment system integrators lacking predictive maintenance capabilities. Five-to-ten-year viability favors vendors with dual rail signaling and V2X communication competencies. Monitor FCC 5.9 GHz spectrum rulemaking as inflection indicator for V2X hardware vendor investment resumption.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | Elevated Transport Canada data governance standards filter vendor qualification timelines. |
| Backward Integration into Edge Hardware | Taiwan foundry concentration exposes North American deployments to supply disruption. |
| Outcome-Based Maintenance Contracts | Ontario logistics operators now unbundle equipment sales from service agreements. |
| Multimodal Platform Diversification | USDOT reauthorization debates reweight rail versus roadway investment priorities. |
| Mid-Sized Metropolitan Geographic Expansion | Cities between 500,000 and 2 million population remain underpenetrated for turnkey transit automation. |
Research Methodology
Multiple input streams — municipal procurement officer interviews, vendor qualification document analysis, federal grant allocation databases, and connected vehicle corridor deployment records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured perspectives from transit agency technology directors, state DOT planning officers, fleet operator logistics managers, and edge-network infrastructure engineers. Secondary validation drew from USDOT Smart City Challenge filings, Transport Canada policy framework documents, FCC spectrum allocation dockets, and California Air Resources Board regulatory submissions.
Historical deployment trajectories were cross-referenced against expert panel assessments of procurement cycle compression and cybersecurity mandate escalation. Segmentation modeling spanned product type, application, technology, and end user dimensions across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle acceleration, and federal funding authorization patterns. Industry-specific forecast inputs incorporated V2X latency threshold adoption curves and predictive maintenance software penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FCC spectrum rulemaking delays or Taiwan supply disruption scenarios. Forecasts reflect documented assumptions regarding federal grant continuity and municipal debt capacity for infrastructure modernization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Europe Smart Transportation Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Vehicle As a Service Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Automotive Digital Mapping Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Intelligent Airways Transportation Market