
 Europe Connected Cars Market | 2026-2036
Europe Connected Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Connected Cars Market Foresight
The EU AI Act is broadening the compliance burden for autonomous and connected vehicle systems across European road networks. Continental AG leverages its sensor integration expertise to anchor supply relationships with major OEM programs. Robert Bosch GmbH sustains R&D intensity in V2X communication modules through dedicated engineering centers in Stuttgart and Dresden. NXP Semiconductors dominates automotive-grade chipset supply for telematics control units deployed under E-Mark certification requirements.
Connected cars integrate onboard sensors, cellular modems, and edge computing platforms to enable real-time data exchange between vehicles, infrastructure, and cloud services. These systems typically operate over 4G/5G networks with sub-100 millisecond latency thresholds for safety-critical V2X applications. Telematics and V2X communication segments lead current revenue generation due to mandatory eCall regulations and fleet digitization mandates. Infotainment systems occupy mature margin pools where Harman International and Aptiv plc compete on software-defined cockpit architectures. Electric vehicles represent the fastest-growing vehicle type segment as battery platforms natively accommodate high-bandwidth connectivity hardware.
EMA, ECHA, and CE marking frameworks collectively govern electromagnetic compatibility, chemical substance restrictions, and product safety attestations for connected automotive electronics sold within Europe. REACH compliance obligations and the EU Green Deal's circular economy requirements are forcing material disclosure and end-of-life recycling protocols across semiconductor and wiring component supply chains. Stakeholders must monitor how the EU AI Act's risk classification system for autonomous decision-making will reshape homologation timelines and data governance investments.
Market Dynamics
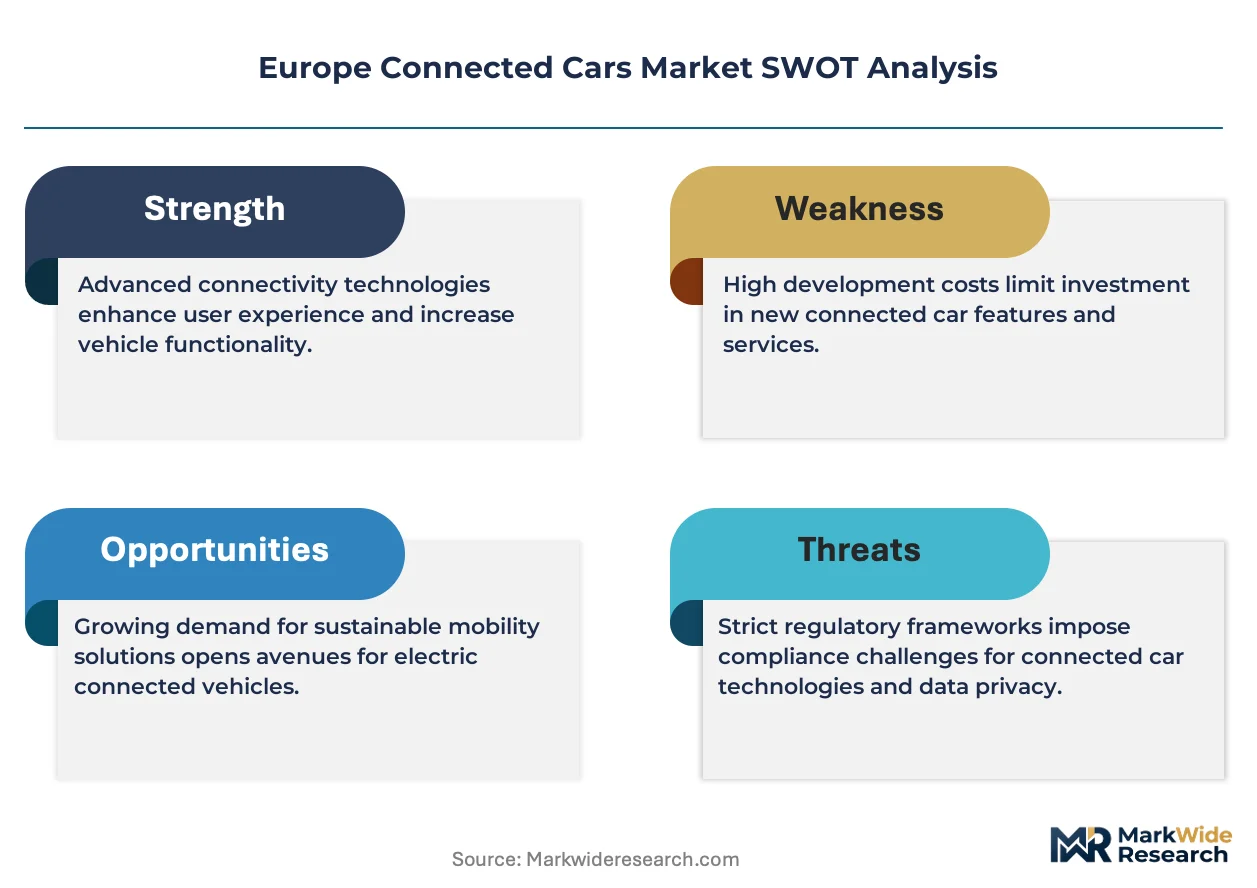
Fleet digitization mandates and the EU AI Act's risk classification system are restructuring how automotive OEMs architect vehicle connectivity stacks and data governance frameworks.
Growth Catalysts
- Regulatory Mandates:The EU's mandatory eCall regulation requires automatic emergency response systems in all new vehicles, creating baseline demand for cellular-connected telematics hardware.
- Fleet Electrification:Battery electric vehicle platforms natively integrate high-bandwidth connectivity modules to enable remote diagnostics and over-the-air software updates.
- V2X Infrastructure Deployment:Germany's federal transport ministry is accelerating roadside unit installation along the A9 and A81 corridors to enable vehicle-to-infrastructure communication.
Market Restraints
- Semiconductor Supply Concentration:Automotive-grade chipset fabrication concentrates in Taiwan and South Korea, exposing European OEMs to geopolitical supply disruptions.
- REACH Compliance Costs:Chemical substance disclosure requirements for wiring harnesses and printed circuit boards force expensive supply chain audits and material substitutions.
- Cellular Module Pricing Volatility:5G NR modem procurement costs fluctuate with memory component spot markets, compressing margins for Tier 1 telematics suppliers.
Strategic Opportunities
- Eastern European Manufacturing:Poland and Czechia offer assembly cost advantages for V2X communication modules serving German OEM supply chains.
- Software-Defined Vehicle Architectures:Centralized compute platforms converging infotainment and ADAS functions enable subscription-based feature monetization.
- EU Green Deal Incentives:Circular economy funding supports end-of-life electronics recycling infrastructure for telematics control units.
Industry Challenges
- Embedded Systems Engineering Talent:Shortages of automotive cybersecurity specialists delay secure boot and encryption implementation for connected vehicle gateways.
- Homologation Timeline Compression:E-Mark certification requirements for electromagnetic compatibility extend product validation cycles as radio protocols proliferate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Connected Cars Market |
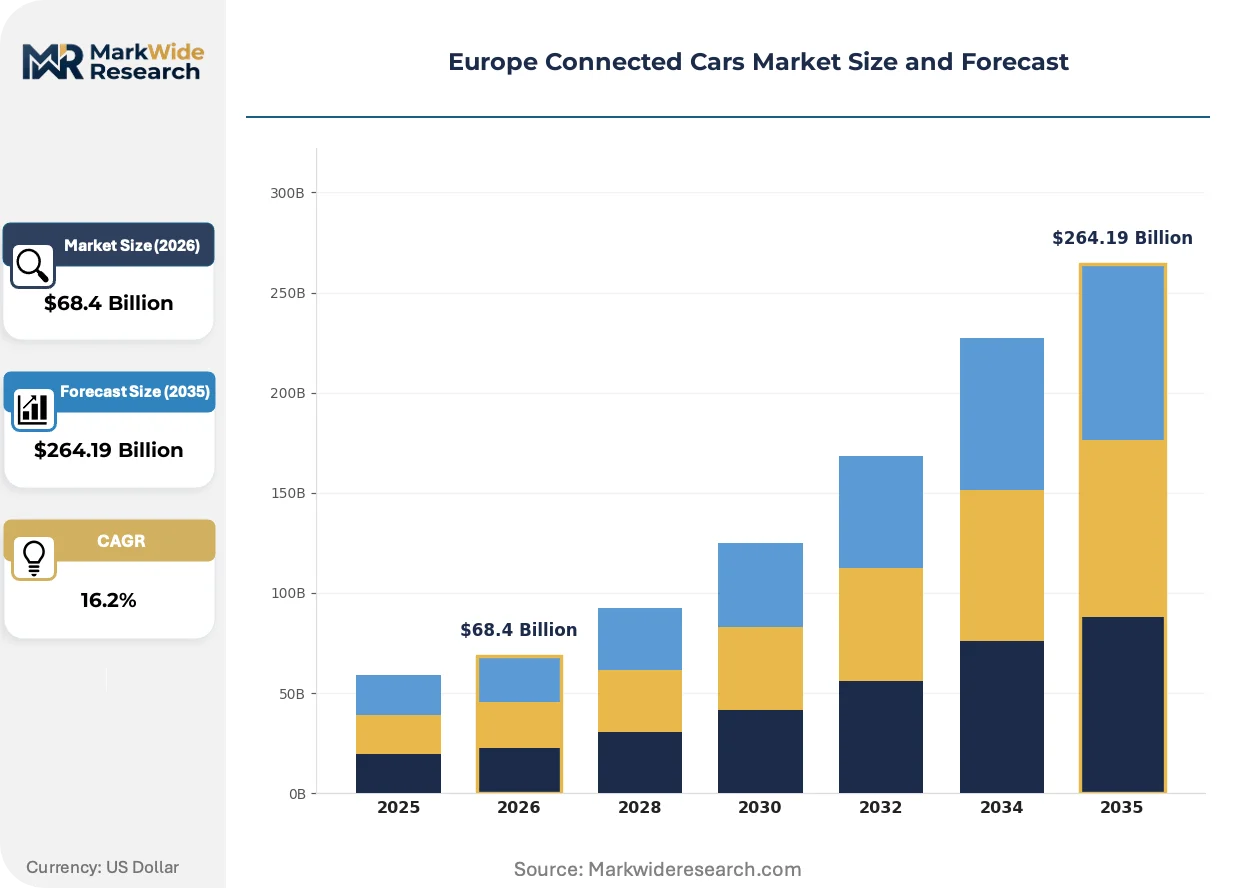
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $264.19 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Telematics, V2X Communication, Infotainment Systems, Advanced Driver Assistance Systems Customer Type: Fleet Operators, Individual Consumers, OEMs, Aftermarket Providers Vehicle Type: Sedans, SUVs, Trucks, Electric Vehicles Service Type: Navigation, Remote Diagnostics, Over-the-Air Updates, Emergency Services |
| Companies Covered | Denso Corporation, NXP Semiconductors, Continental AG, Volkswagen, BMW, Robert Bosch GmbH, Aptiv plc, Stellantis, Harman International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Connected Cars Market Shifts & Advancements
Edge computing migration and AI-driven predictive maintenance are redefining where vehicle data processing occurs and how fleet operators extract value from connected platforms.
Automotive-grade edge processors with dedicated neural network accelerators are overtaking cloud-dependent architectures for latency-critical functions. German premium OEMs are embedding these chips directly into domain controllers for real-time sensor fusion. This shift is overtaking traditional telematics gateway designs that route all data to remote servers.
REACH substance restrictions are forcing material transitions in wiring insulation and connector housings. ECHA's expanded candidate list now covers additional flame retardants common in automotive cable assemblies. Suppliers serving the French and Italian markets are accelerating halogen-free compound qualification to maintain CE marking eligibility.
Fleet procurement departments are consolidating telematics vendor relationships around integrated platform providers. Multi-brand logistics operators in the Netherlands and Belgium are replacing point solutions with unified APIs spanning vehicle tracking, driver behavior scoring, and predictive maintenance. This consolidation is most visible among refrigerated transport fleets where temperature monitoring integration drives supplier selection.
Europe Connected Cars Market Segmentation
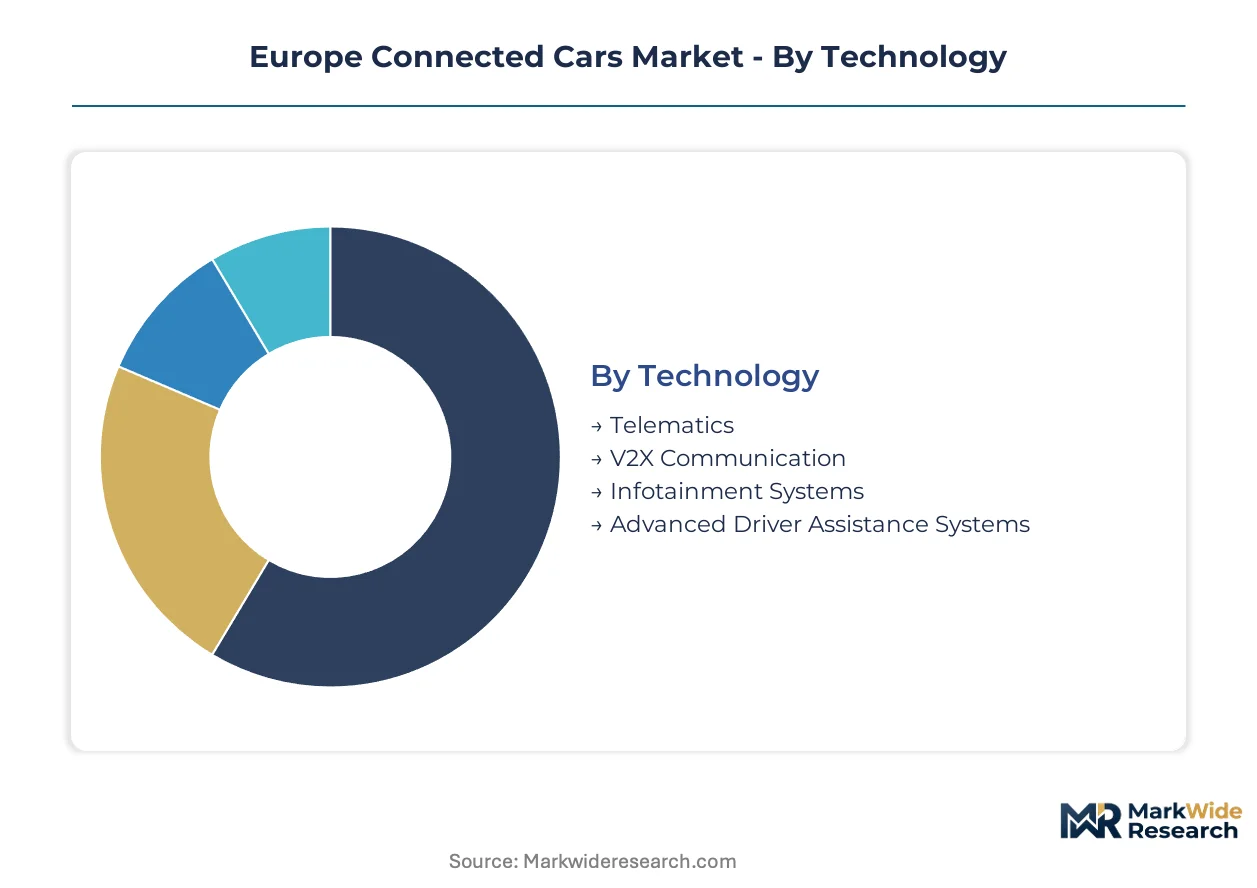
Segmentation in the Europe Connected Cars Market reveals how technology specialization, procurement authority, and vehicle architecture determine where value concentrates across the value chain. Understanding these divisions exposes where regulatory mandates intersect with commercial incentives.
Technology:
The customization-vs-standardization spectrum across this category runs from mandatory regulatory hardware to discretionary consumer features.
- Telematics:Cellular-connected control units integrate GPS, accelerometers, and eCall emergency response modules. Fleet operators in Germany and the Netherlands deploy these for regulatory compliance and fuel optimization. Mandatory eCall regulations ensure baseline demand regardless of vehicle price tier.
- V2X Communication:Dedicated short-range and cellular vehicle-to-everything protocols enable real-time hazard warnings and cooperative maneuvering. Germany's A9 and A81 corridor deployments are accelerating roadside unit integration. The EU AI Act's risk classification system is reshaping how OEMs architect these safety-critical data flows.
- Infotainment Systems:Software-defined cockpit platforms converge navigation, media, and vehicle settings through centralized displays.
- Advanced Driver Assistance Systems:Sensor fusion platforms combining radar, lidar, and camera inputs for partial automation.
Most installed capacity flows through Telematics. Expansion is steepest in V2X Communication.
Customer Type:
Procurement authority in this category shifts from centralized fleet purchasing departments to fragmented individual decision-making.
- Fleet Operators:Multi-vehicle logistics and transport companies negotiate enterprise telematics contracts with unified API requirements. Refrigerated transport fleets in Belgium prioritize temperature monitoring integration alongside standard tracking.
- OEMs:Vehicle manufacturers specify embedded connectivity hardware during platform development, locking in supplier relationships years before production.
- Individual Consumers:End-users activate subscription services post-purchase, creating recurring revenue pools for infotainment and navigation upgrades.
- Aftermarket Providers:Independent installers retrofit connectivity modules to existing vehicle fleets, serving price-sensitive segments outside factory warranty coverage.
Procurement volume concentrates with Fleet Operators. Margin expansion is strongest among OEMs.
Vehicle Type:
Platform architecture in this category determines native connectivity bandwidth and sensor integration capacity.
- Electric Vehicles:Battery platforms accommodate high-voltage power distribution and thermal management systems that natively support edge computing hardware. Germany's premium OEMs are embedding neural network accelerators directly into domain controllers. Remote diagnostics and over-the-air software updates are standard features rather than options.
- SUVs:Larger chassis dimensions enable redundant sensor arrays and expanded antenna configurations for V2X applications.
- Sedans:Volume production platforms prioritize cost-optimized telematics modules meeting baseline regulatory requirements.
- Trucks:Commercial vehicle regulations mandate specific connectivity functions for hours-of-service logging and platooning coordination.
Production volume flows through Sedans. Technology adoption is advancing fastest in Electric Vehicles.
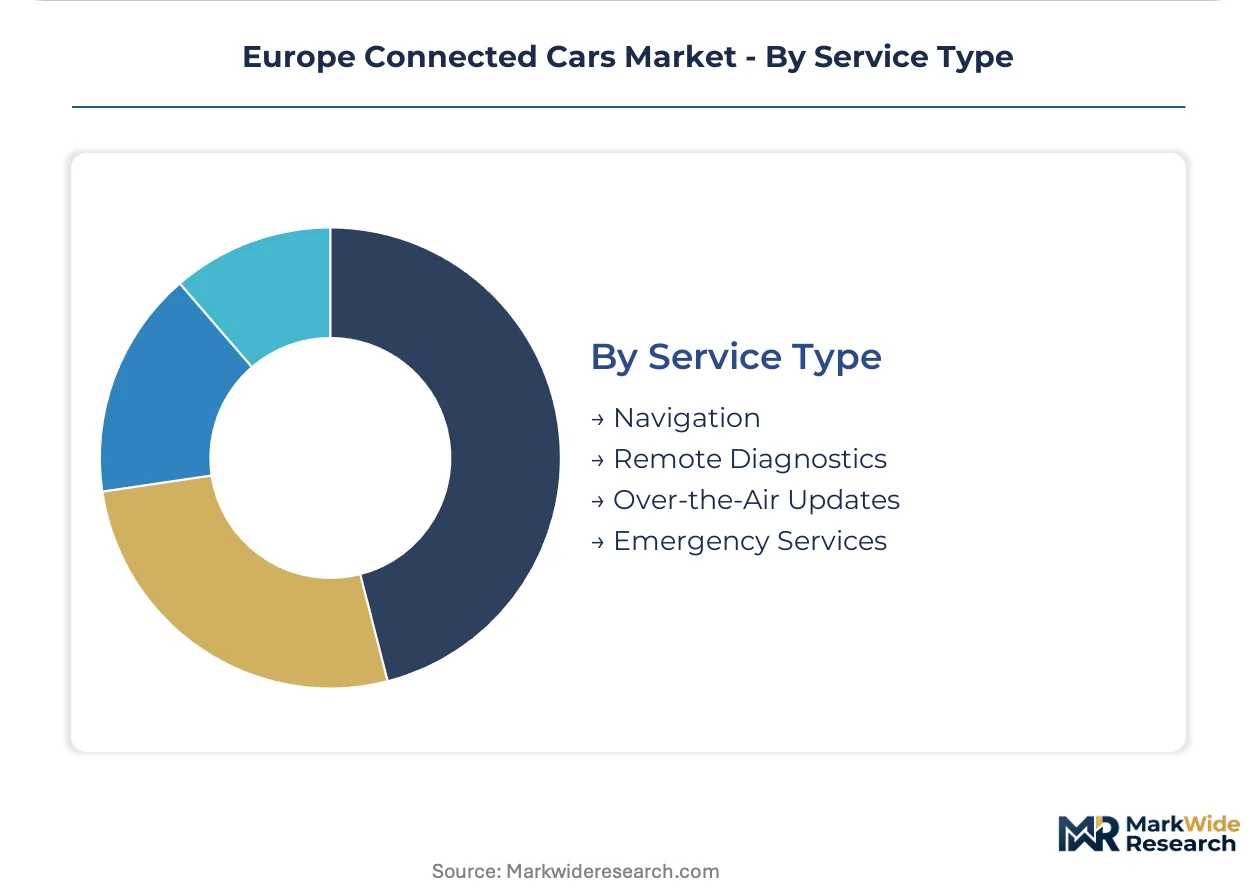
Service Type:
Revenue model maturity in this category spans one-time hardware sales through recurring subscription monetization.
- Remote Diagnostics:Predictive maintenance algorithms process edge-computed sensor data to flag component degradation before failure. Fleet operators in the Netherlands are consolidating vendor relationships around unified platforms spanning diagnostics, tracking, and driver scoring.
- Over-the-Air Updates:Software distribution networks enable feature activation and security patching without dealership visits.
- Navigation:Real-time traffic and route optimization services compete with smartphone-mirrored alternatives.
- Emergency Services:eCall automatic crash notification is mandatory across all new vehicle registrations under EU regulation.
Regulatory mandate ensures Emergency Services penetration. Commercial momentum is building in Remote Diagnostics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Stuttgart, Munich, and Wolfsburg anchor European connected vehicle development. These clusters concentrate embedded systems specialists, V2X protocol engineers, and automotive cybersecurity professionals. Workforce density here outpaces other European technology corridors.
Germany
Premium OEM platform development drives embedded connectivity hardware demand across Baden-Württemberg and Bavaria. The EU AI Act's risk classification system is reshaping homologation timelines for autonomous driving functions. Stuttgart's engineering centers host intensive R&D in V2X communication modules serving A9 and A81 corridor deployments.
United Kingdom
Fleet digitization mandates from logistics operators in the Midlands and Southeast create concentrated telematics procurement. GDPR compliance frameworks govern cross-border data flows from connected vehicle gateways. London's technology corridor hosts software-defined vehicle architecture development for subscription-based feature monetization.
France
Refrigerated transport fleets in the Île-de-France and Hauts-de-France regions prioritize temperature monitoring integration alongside standard vehicle tracking. REACH compliance obligations from ECHA force material transitions in wiring insulation and connector housings. Paris-based automotive suppliers accelerate halogen-free compound qualification to maintain CE marking eligibility.
Netherlands
Multi-brand logistics operators in Rotterdam and Amsterdam consolidate telematics vendor relationships around unified API platforms. The EU Green Deal's circular economy requirements support end-of-life electronics recycling infrastructure development. Eindhoven's semiconductor ecosystem feeds automotive-grade chipset demand for telematics control units.
Poland
Assembly cost advantages attract V2X communication module manufacturing serving German OEM supply chains. CE marking frameworks govern electromagnetic compatibility attestations for exported automotive electronics. Warsaw and Krakow technology parks host engineering operations supporting connected vehicle platform integration.
Europe Connected Cars Market Competitive Landscape
The competitive structure tilts toward diversified automotive suppliers with embedded electronics capabilities. Tier 1 systems integrators and semiconductor specialists dominate upstream positions while OEMs control final architecture decisions. Three archetypes prevail: sensor-integrated module suppliers, automotive-grade chipset fabricators, and software-defined cockpit platform providers. Strategic moves concentrate on backward integration into semiconductor sourcing and geographic expansion into Eastern European assembly locations.
Among diversified automotive suppliers, Continental AG, Robert Bosch GmbH, and NXP Semiconductors occupy anchor positions within their respective archetypes. Continental AG represents the sensor-integrated module supplier category with its Stuttgart and Dresden engineering footprint. Robert Bosch GmbH exemplifies sustained R&D intensity in communication technologies. NXP Semiconductors anchors the automotive-grade chipset fabricator tier through E-Mark certification compliance.
| Leading Market Players |
|---|
| Denso Corporation |
| NXP Semiconductors |
| Continental AG |
| Volkswagen |
| BMW |
| Robert Bosch GmbH |
| Aptiv plc |
| Stellantis |
| Harman International |
| Others |
Supply & Pricing Matrix
EU Green Deal circular economy mandates gate qualified supply and premium-tier pricing access for connected vehicle electronics, forcing material disclosure protocols and end-of-life recycling investments that separate certified suppliers from commodity competitors serving price-sensitive aftermarket channels.
Pricing Analysis
Bundled subscription services dominate over unbundled hardware sales across European connected car platforms. Three-tier pricing structure across premium, standard, and economy levels reflects E-Mark certification grade and volume scale commitments from fleet operators. Pricing pressure stems from 5G NR modem procurement cost volatility tied to memory component spot markets. Aftermarket providers exhibit highest price sensitivity, while OEMs absorb premium pricing for embedded connectivity hardware locked into platform development cycles.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for automotive-grade chipset delivery. Semiconductor fabrication concentrates in Taiwan and South Korea, exposing European OEMs to geopolitical supply disruptions. Wiring harness production draws from Poland and Czechia assembly operations serving German OEM corridors. REACH compliance audits and material substitution requirements constitute the primary regulatory restriction. Distribution runs through Tier 1 systems integrators with direct OEM platform engineering relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Connected Cars Market functions as a stable compounder, with mandatory eCall regulations and fleet digitization mandates generating baseline demand that insulates against cyclical automotive production swings.
For Market Incumbents: Anchor defensive positions through backward integration into automotive-grade chipset sourcing and certification investment in E-Mark electromagnetic compatibility testing. Emerging cybersecurity specialists threaten secure boot implementation timelines, making captive supply of encryption-enabled telematics gateways essential for platform lock-in with German premium OEMs. For New Entrants and Emerging Players: Begin with refrigerated transport fleets in Belgium and the Netherlands, where temperature monitoring integration requirements create white-space unaddressed by generic tracking providers. Target aftermarket retrofit channels for price-sensitive segments outside factory warranty coverage, leveraging unified API platforms to displace point-solution vendors. For Investors and Strategic Acquirers: Valuations sit cheapest among Eastern European V2X module assemblers with CE marking capabilities and German OEM supply relationships. Long-term viability hinges on software-defined vehicle architecture transitions enabling subscription monetization. Watch for EU AI Act risk classification implementation as the inflection signal for homologation timeline compression and data governance investment spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized compute platforms from Aptiv and Harman enable recurring subscription revenue from feature activation. |
| Battery Supply Agreement | Electric vehicle platforms from BMW and Volkswagen natively integrate high-bandwidth connectivity hardware for remote diagnostics. |
| Geographic Manufacturing Footprint | Poland and Czechia assembly operations lower V2X module costs for Tier 1 suppliers serving Stuttgart engineering centers. |
| Charging Infrastructure Partnership | Grid integration agreements with Eindhoven semiconductor ecosystem support edge computing deployment for telematics control units. |
| Platform Standardization | OEM convergence on unified APIs accelerates fleet procurement consolidation around integrated telematics providers in Rotterdam logistics corridors. |
Research Methodology
Coverage spans Germany, France, the Netherlands, the United Kingdom, and Poland, with primary inputs from each market cluster combining interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations managers, and automotive cybersecurity specialists. Secondary validation draws from vehicle production databases, IHS Markit registration data, ECHA substance restriction filings, and EU regulatory impact assessments. Bottom-up segment sizing and top-down macroeconomic triangulation cross-verify volume and value estimates.
Rate-of-change decomposition separates baseline regulatory demand from discretionary technology adoption across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, connectivity technology tier, customer procurement authority, and regional production cluster. CAGRs derive from installed base growth, content-per-vehicle trajectories, and service monetization attach rates. Forecast inputs incorporate EU AI Act implementation timelines and V2X roadside unit deployment schedules along German transport corridors.
Caveats apply where semiconductor supply disruptions, REACH substance restriction expansions, or EU AI Act risk classification delays could materially shift the outlook. Forecasts reflect documented assumptions about regulatory enforcement consistency and fleet electrification pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Contactless Ticketing Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
North America Smart Transportation Market