
 Automotive Platooning Systems Market | 2026-2036
Automotive Platooning Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Platooning Systems Market Analysis
German automotive suppliers is repositioning around embedded V2V chipsets and radar integration for highway truck convoys. Continental AG leverages its sensor portfolio to dominate the radar layer in European platooning trials. Robert Bosch GmbH sustains R&D intensity in AI-driven gap-control algorithms. ZF Friedrichshafen AG anchors its position through integrated braking and steering actuators purpose-built for convoy synchronization.
Automotive platooning systems coordinate multiple vehicles into electronically linked convoys using dedicated short-range communication, radar, and sensor fusion to maintain constant inter-vehicle gaps below 15 meters at highway speeds. The primary purpose is to reduce aerodynamic drag, cut fuel consumption by 5-10% per truck, and enable partial driver monitoring rather than full manual control. V2V communication infrastructure claims the largest share of deployed capital because every platooning truck requires DSRC or C-V2X radios with sub-10-millisecond latency. Sensor fusion is displacing single-sensor architectures as fleets demand redundancy for safety certification. AI algorithms represent the fastest-growing technology segment as machine learning models optimize gap distance dynamically based on load weight, road grade, and weather conditions.
The U.S. DOT, the European Commission's F-Gas Regulation framework, and Japan's METI each shape platooning system requirements through vehicle automation classification and emissions verification protocols. U.S. DOT guidelines on automated driving system demonstration determine which corridor pilots receive federal support, while EU type-approval rules under the MDR and CE marking pathways govern cross-border truck platooning legality. Stakeholders must monitor how regulators reconcile liability assignment between lead and following vehicles before committing to fleet-wide deployment architectures.
Market Dynamics
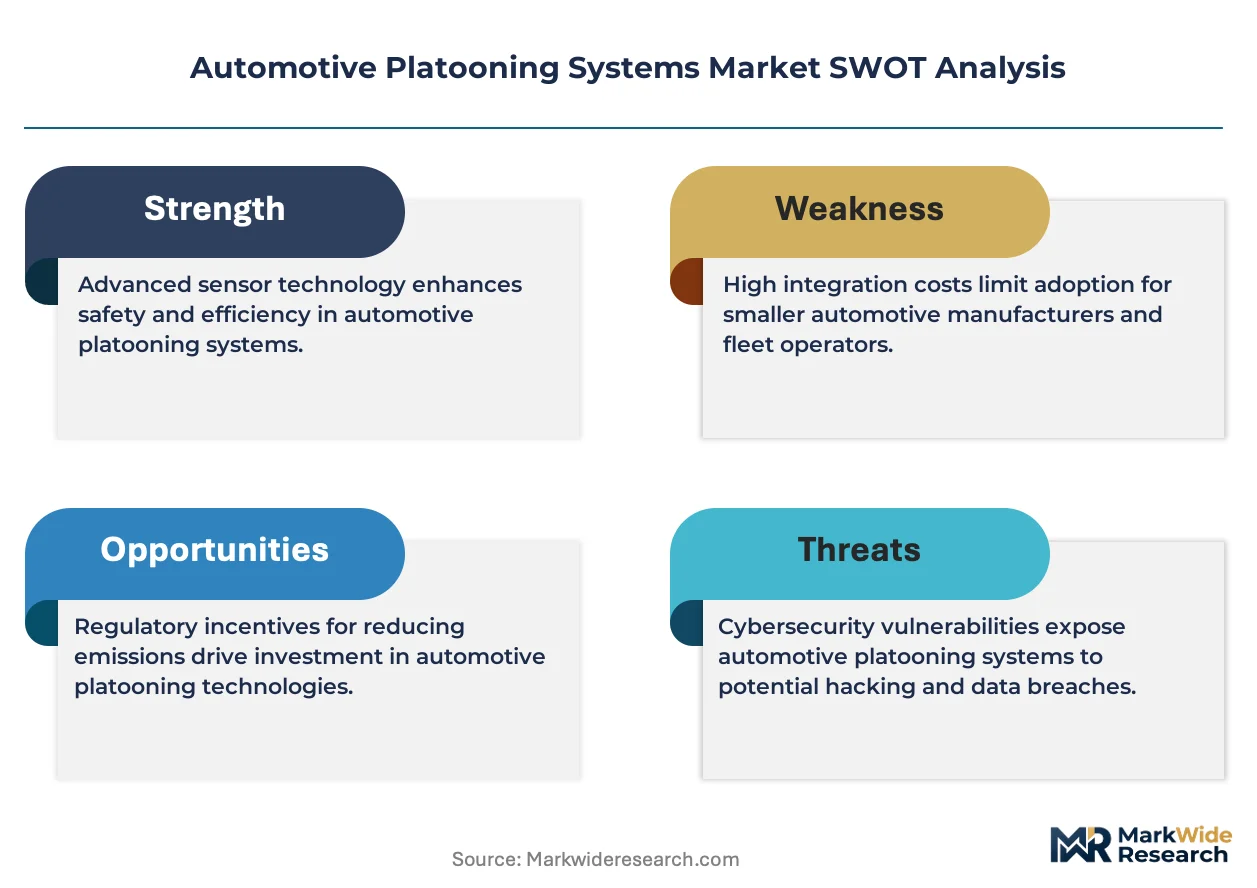
V2V communication latency requirements below 10 milliseconds are forcing a wholesale architecture shift from single-sensor to redundant sensor-fusion stacks, compressing supplier margins while elevating certification costs for fleet operators.
Growth Catalysts
- F-Gas Regulation:The EU's emissions verification protocols under this framework are accelerating truck platooning trials as fleets seek fuel efficiency credits to offset carbon penalties.
- Long-haul freight corridors:Concentrated freight density along interstate highways in the United States creates natural deployment environments for multi-truck convoys with predictable route profiles.
- DSRC-to-C-V2X migration:Cellular vehicle-to-everything radios are displacing dedicated short-range communication hardware, reducing per-unit chipset costs while maintaining sub-10-millisecond latency thresholds.
Market Restraints
- Lidar sensor cost volatility:Supply concentration for automotive-grade lidar components in Asian manufacturing clusters creates input price instability for sensor-fusion system integrators.
- Cross-border liability fragmentation:EU type-approval rules under MDR and CE marking pathways generate regulatory friction for fleets operating multi-country routes without harmonized lead-follow vehicle assignment protocols.
- Platooning-to-autonomous substitution:Single-truck Level 4 automation development threatens to bypass convoy economics entirely by eliminating driver costs rather than merely reducing them.
Strategic Opportunities
- Japan METI automation incentives:Japan's Ministry of Economy, Trade and Industry funding for connected vehicle infrastructure creates a deployment-ready market for C-V2X hardware vendors.
- AI-driven dynamic gap control:Machine learning convergence with real-time load-weight sensors enables variable inter-vehicle spacing that optimizes aerodynamic efficiency across terrain grades.
- Maintenance channel disintermediation:Direct-to-fleet over-the-air software update platforms are bypassing traditional dealer networks for platooning algorithm upgrades and safety patches.
Industry Challenges
- Functional safety engineer scarcity:ISO 26262 certification expertise for automotive embedded systems remains concentrated among a limited pool of specialists, extending development timelines.
- Legacy fleet integration complexity:Retrofitting existing Class 8 trucks with platooning actuators requires brake-by-wire and steer-by-wire conversions that conflict with OEM warranty terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Platooning Systems Market |
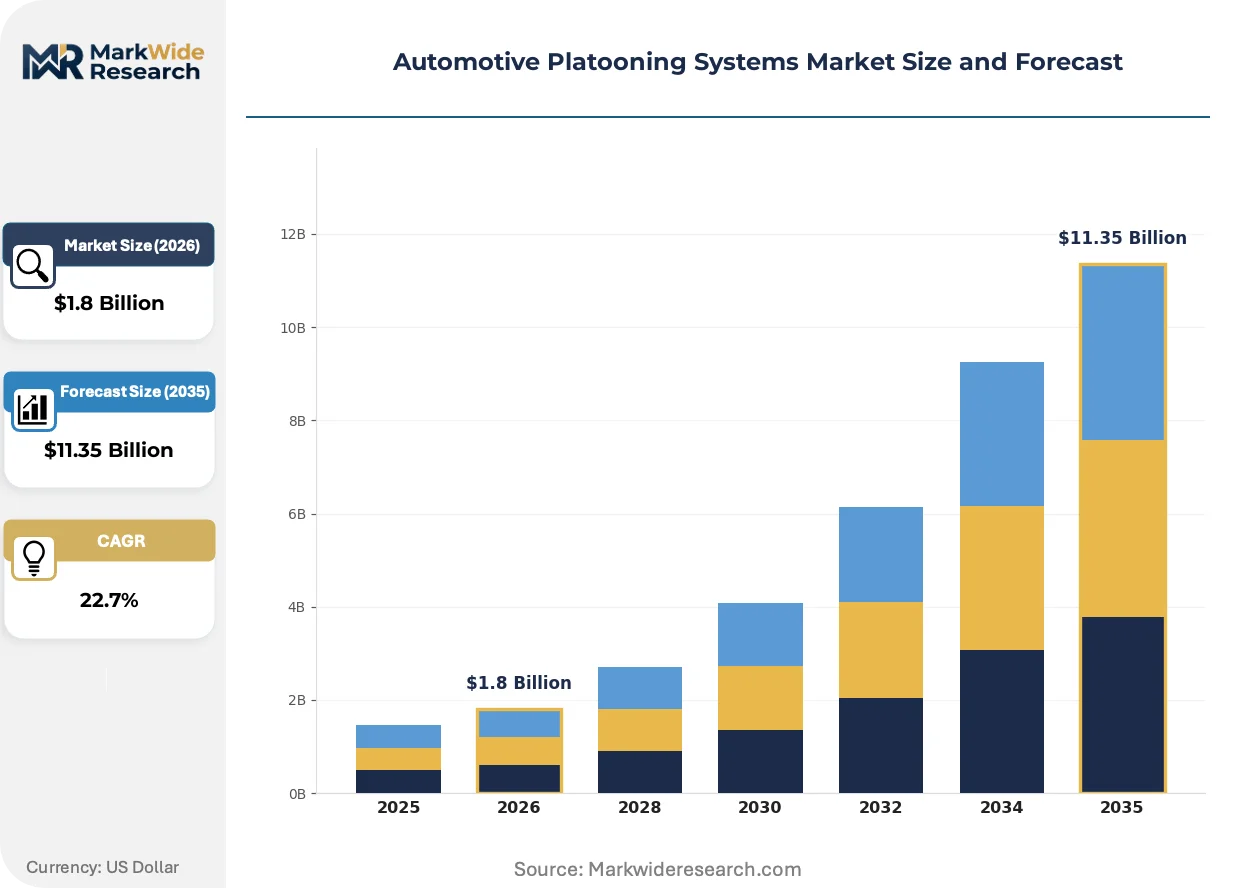
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: V2V Communication, Sensor Fusion, Radar Systems, AI Algorithms Vehicle Type: Trucks, Buses, Vans, Passenger Cars End User: Logistics Companies, Public Transport Agencies, Fleets, Private Users Application: Highway Transportation, Urban Mobility, Freight Services, Autonomous Driving |
| Companies Covered | Continental AG, Peloton Technology, Mercedes-Benz Group AG, Scania AB, IVECO Group, AB Volvo, Daimler Truck AG, Robert Bosch GmbH, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Platooning Systems Market Emerging Trajectories
Sensor fusion architectures are compressing the competitive window for single-sensor suppliers while regulatory clarity on automated driving system liability is unlocking fleet procurement cycles previously frozen by legal uncertainty.
Multi-layer perception stacks combining radar, camera, and lidar inputs are rewriting safety certification pathways for highway convoy operations. Tier-1 suppliers in Germany are integrating these stacks into turnkey modules for North American truck OEMs. The shift is compressing development cycles from 48 months to 24 months for new platooning system launches.
The U.S. Department of Transportation's evolving automated vehicle policy framework is mandating standardized event data recorders for all automated driving system demonstrations. Fleet operators must now document every disengagement and handoff event to maintain federal pilot program eligibility. Long-haul carriers operating the I-10 corridor are restructuring insurance coverage to accommodate these disclosure requirements.
Freight procurement through dedicated contract carriage is displacing spot-market brokerage for platooning-enabled fleets. Large shippers in the United States are negotiating multi-year volume commitments that amortize the capital cost of convoy hardware across predictable route densities. This concentration of buyer power is squeezing margins for smaller fleet operators unable to guarantee minimum utilization rates.
Automotive Platooning Systems Market Segmentation
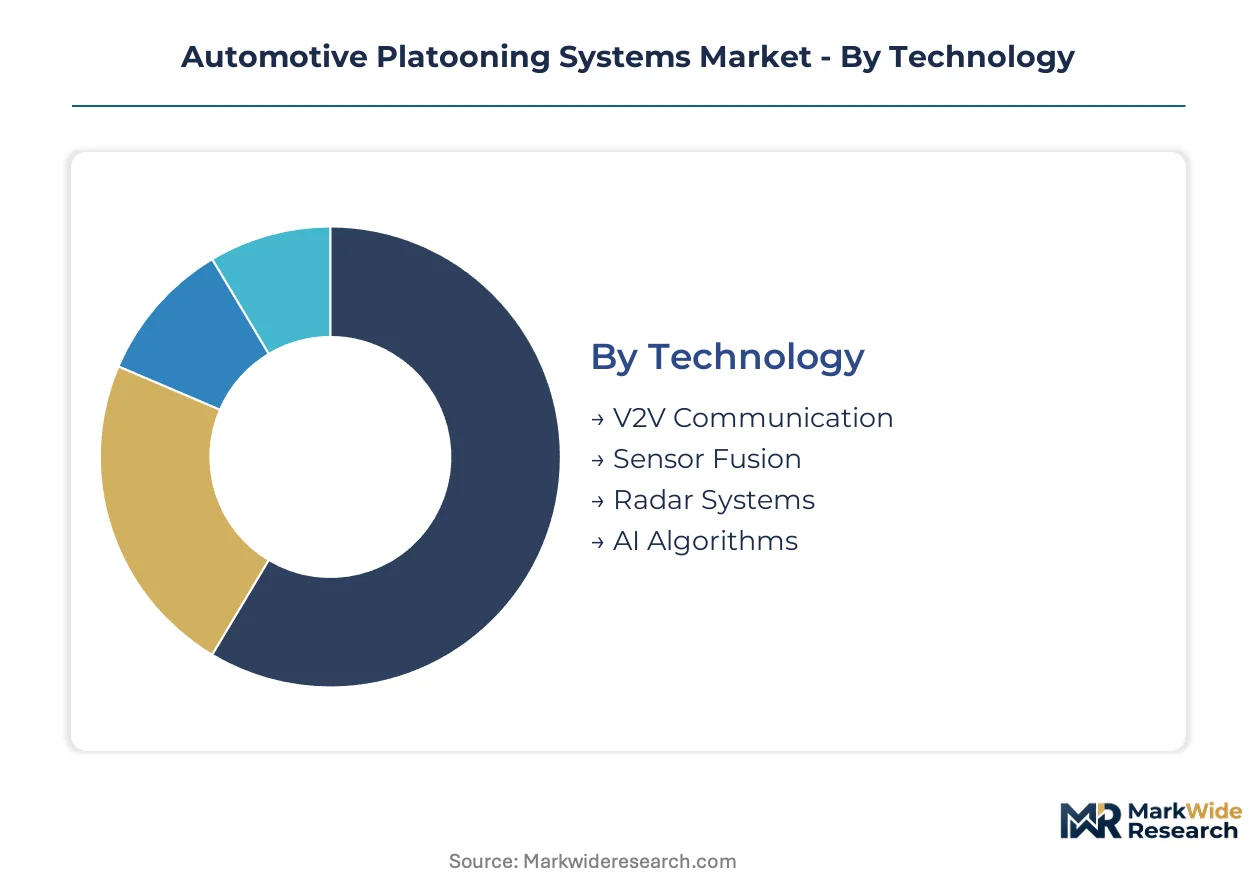
Fleet procurement cycles in automotive platooning systems diverge sharply by technology readiness and vehicle class, with long-haul operators prioritizing fuel efficiency gains while urban transit authorities weigh safety redundancy against infrastructure costs.
Technology:
Capital allocation decisions among fleet operators hinge on latency performance and certification complexity rather than upfront hardware expense.
- V2V Communication:Dedicated short-range communication and C-V2X radios enable sub-10-millisecond vehicle-to-vehicle data exchange. Demand concentrates along United States interstate corridors where the U.S. DOT mandates standardized event data recorders for federal pilot program eligibility.
- Sensor Fusion:Multi-layer perception stacks integrate radar, camera, and lidar inputs for safety redundancy. German Tier-1 suppliers dominate this segment as North American truck OEMs compress development cycles from 48 months to 24 months for convoy system launches.
- Radar Systems:Continental AG leverages its sensor portfolio to anchor highway truck convoy trials across European long-haul routes.
- AI Algorithms:Machine learning models optimize inter-vehicle gap distance dynamically based on load weight, road grade, and weather conditions.
Volume sits with V2V Communication; growth tilts toward AI Algorithms.
Vehicle Type:
Payload economics and route predictability determine which vehicle classes justify platooning hardware investment.
- Trucks:Class 8 long-haul tractors generate the primary revenue base for platooning system vendors. Fleet operators along the I-10 and I-95 corridors in the United States host the majority of live commercial trials, cutting fuel expenditures by 5-10% per vehicle through aerodynamic drag reduction.
- Buses:Public transit agencies in Japan evaluate platooning for dedicated bus rapid transit lanes with METI automation incentives supporting C-V2X infrastructure deployment.
- Vans:Last-mile delivery fleets in urban Germany test short-range convoy configurations for parcel distribution hubs.
- Passenger Cars:Premium German automotive manufacturers integrate platooning as a convenience feature for highway cruising assist systems.
Trucks capture the dominant installed base; buses are climbing the fastest as transit agencies seek operational efficiency.
End User:
Contract structure and route density separate viable platooning adopters from marginal use cases.
- Logistics Companies:Large United States shippers negotiate multi-year volume commitments that amortize convoy hardware costs across predictable route densities, displacing spot-market brokerage for platooning-enabled fleets.
- Fleets:Dedicated contract carriage operators restructure insurance coverage to accommodate U.S. DOT disclosure requirements for automated driving system demonstrations.
- Public Transport Agencies:Municipal operators in the European Union weigh platooning against emissions verification protocols under the F-Gas Regulation framework.
- Private Users:Individual passenger car owners represent a nascent segment with limited current hardware penetration.
Logistics Companies hold the revenue concentration; Fleets are gaining share fastest as procurement shifts toward direct-to-fleet software update platforms.
Application:
Regulatory clarity on liability assignment varies dramatically by operating environment, freezing some procurement cycles while unlocking others.
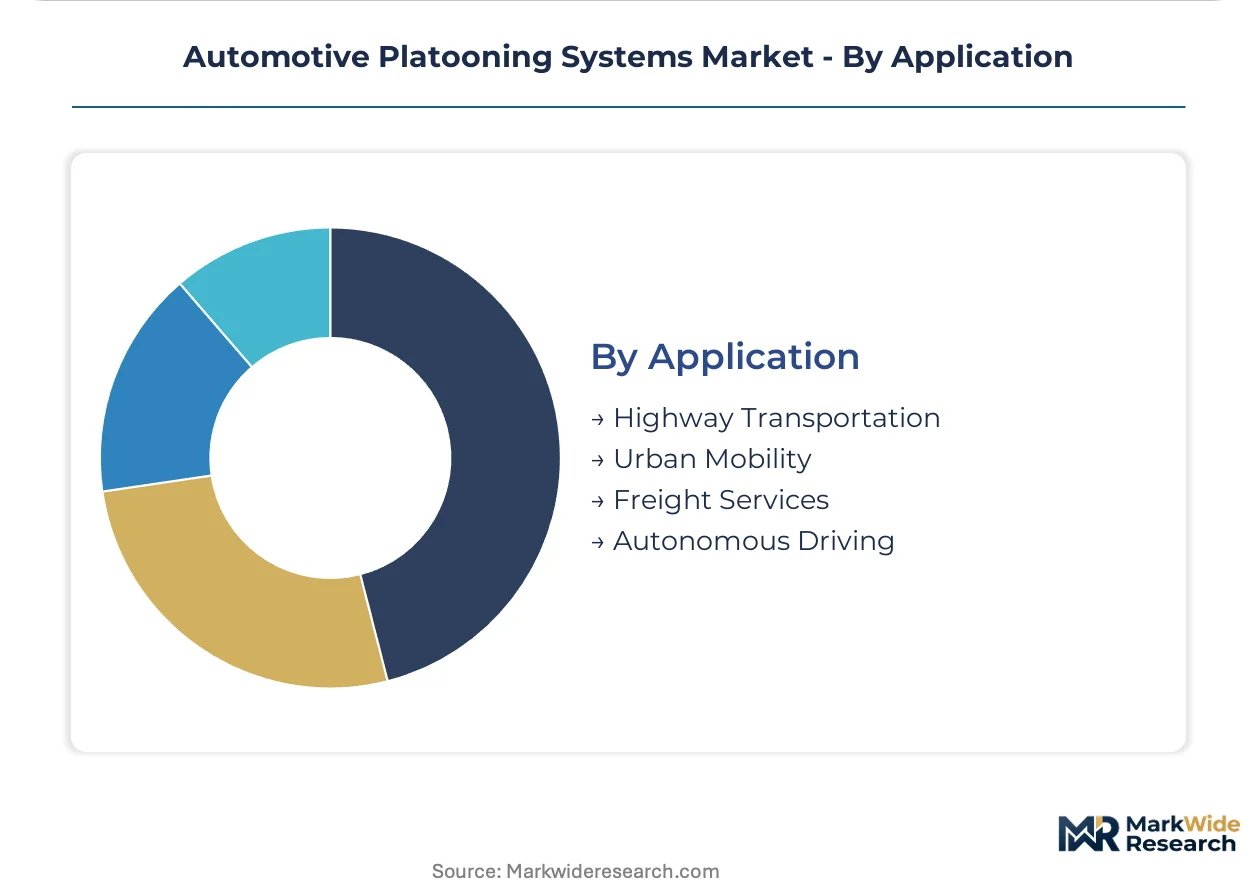
- Highway Transportation:Interstate convoy operations at constant speeds above 55 mph deliver maximum aerodynamic efficiency gains. The U.S. DOT's evolving automated vehicle policy framework accelerates pilot program approvals for multi-truck convoys on interstate highways.
- Freight Services:Predictable long-haul corridors with concentrated freight density create natural deployment environments for convoy synchronization.
- Urban Mobility:Stop-and-go traffic patterns degrade platooning efficiency, limiting adoption to dedicated bus rapid transit corridors with signal priority infrastructure.
- Autonomous Driving:Single-truck Level 4 automation development threatens to bypass convoy economics entirely by eliminating driver costs rather than merely reducing them.
Highway Transportation dominates current deployment; Freight Services show the steepest expansion trajectory as procurement concentrates through dedicated contract carriage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in the United States anchor the sensor-fusion supply chain for automotive platooning systems. Federal highway corridors concentrate deployment trials where fuel efficiency gains justify hardware investment. Regulatory frameworks in three distinct geographies determine cross-border fleet economics.
United States
The I-10 and I-95 interstate corridors host live commercial platooning trials as fleet operators target 5-10% fuel savings per truck. NHTSA guidelines on automated driving system demonstrations determine federal pilot program eligibility for multi-truck convoys. Long-haul carriers operating between Texas and California are restructuring insurance coverage to accommodate DOT disclosure requirements for disengagement events.
Germany
Automotive Tier-1 suppliers dominate radar integration and embedded V2V chipset development for highway truck convoys. KBA type-approval rules under EU MDR and CE marking pathways govern cross-border platooning legality for fleets serving multi-country routes. The Stuttgart-Munich industrial corridor concentrates R&D activity in AI-driven gap-control algorithms and integrated braking actuators.
Japan
METI automation incentives fund connected vehicle infrastructure deployment for dedicated bus rapid transit lanes. The country's national automotive regulator verifies emissions protocols under domestic standards aligned with international harmonization efforts. The Nagoya-Tokyo corridor hosts validation trials where C-V2X hardware vendors test sub-10-millisecond latency thresholds in live traffic conditions.
China
MIIT standards for cellular vehicle-to-everything radios are accelerating DSRC-to-C-V2X migration timelines for domestic truck manufacturers. The country's national telecommunications regulator coordinates spectrum allocation for dedicated automotive safety applications. The Yangtze River Delta manufacturing cluster supplies automotive-grade lidar components that feed sensor-fusion stacks for North American and European integrators.
Canada
Cross-border freight density along the Windsor-Quebec corridor creates natural deployment environments for convoy synchronization with US interstate networks. Transport Canada coordinates automated vehicle policy alignment with NHTSA frameworks to ensure regulatory continuity for international fleet operators. Ontario-based engineering consultancies specialize in ISO 26262 functional safety certification for embedded automotive systems.
Automotive Platooning Systems Market Vendor Landscape
Global majors compete with regional champions across embedded systems integration and V2V communication hardware. The vendor base organizes into three tiers: diversified automotive conglomerates with full-stack capabilities, specialized sensor and actuator suppliers, and software-focused algorithm developers. Strategic moves concentrate on sensor-fusion stack partnerships and direct-to-fleet software update platforms that bypass traditional dealer networks.
Within the diversified Tier-1 tier, Continental AG, Robert Bosch GmbH, and ZF Friedrichshafen AG exemplify the integrated braking, steering, and radar architecture approach dominating European and North American highway trials. These Germany-based automotive suppliers occupy positions where sensor portfolio breadth determines convoy system certification timelines. Peloton Technology and Scania AB represent specialized players focused on commercial vehicle fleet applications rather than passenger car convenience features.
| Leading Market Players |
|---|
| Continental AG |
| Peloton Technology |
| Mercedes-Benz Group AG |
| Scania AB |
| IVECO Group |
| AB Volvo |
| Daimler Truck AG |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
The EU's F-Gas Regulation emissions verification protocols gate qualified supply and premium-tier pricing access for platooning system vendors, as fleets seeking fuel efficiency credits demand certified hardware that meets cross-border type-approval standards under KBA and CE marking pathways.
Pricing Analysis
Warranty and over-the-air software update bundling separates premium-tier suppliers from unbundled hardware vendors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and sensor-fusion redundancy depth. Cost compression in the economy tier is intensifying because legacy fleet retrofit complexity extends integration timelines. Small regional fleet operators exhibit the highest price sensitivity, while large logistics companies with dedicated contract carriage amortize hardware across multi-year volume commitments.
Supply Chain Analysis
Functional safety engineer scarcity in Germany, Japan, and the United States constrains ISO 26262 certification throughput for embedded automotive systems. Automotive-grade lidar components draw from the Yangtze River Delta cluster, while DSRC and C-V2X chipsets rest on Taiwanese and South Korean semiconductor fabrication. Single-source vulnerability in Asian lidar manufacturing creates input price instability. Distribution runs through Tier-1 supplier partnerships with North American and European truck OEMs, bypassing traditional dealer networks for direct-to-fleet software deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is supply-constrained by ISO 26262 functional safety certification capacity, which props pricing for qualified Tier-1 suppliers and extends development timelines for new entrants.
For Market Incumbents: Anticipate displacement pressure from single-truck Level 4 automation development by deepening vertical integration into AI-driven gap-control algorithms and embedded V2V chipsets. Anchor market position through captive supply of radar and sensor-fusion stacks that compress certification timelines for fleet operators. Prioritize direct-to-fleet software update platforms that bypass dealer networks and lock in recurring revenue attachment. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels offer the lowest-friction entry path for C-V2X hardware vendors targeting mid-size logistics operators on the I-10 corridor. White-space concentrates in bus rapid transit deployments for Japanese municipal agencies under METI automation incentives. Target aftermarket retrofit services for existing Class 8 fleets unable to secure OEM-integrated platooning packages. For Investors and Strategic Acquirers: The first major cross-border liability harmonization agreement between EU member states is the leading indicator that fleet-wide deployment architectures will unlock. Long-term viability favors vertically integrated sensor-fusion specialists with captive braking and steering actuator production. Target acquisition candidates with ISO 26262 certification expertise and established Tier-1 supplier relationships. Monitor NHTSA pilot program expansion approvals as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Fusion Stack Integration | Continental AG and Robert Bosch GmbH compress development cycles from 48 months to 24 months for convoy system launches. |
| C-V2X Hardware Certification | MIIT standards in China accelerate DSRC-to-C-V2X migration timelines for domestic and export truck manufacturers. |
| Direct-to-Fleet Software Platform | Peloton Technology and specialized vendors bypass dealer networks for over-the-air algorithm upgrades and safety patches. |
| Cross-Border Type-Approval Investment | KBA and EU MDR compliance unlocks multi-country route economics for fleet operators serving European long-haul corridors. |
| AI-Driven Dynamic Gap Control R&D | ZF Friedrichshafen AG anchors market position through machine learning convergence with real-time load-weight sensors. |
Methodological Framework
Multi-period observation of NHTSA pilot program approvals, EU F-Gas Regulation enforcement patterns, and METI infrastructure deployment timelines anchored the trend analysis, supplemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, fleet operations directors, and aftermarket distributors. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from diversified automotive conglomerates, and U.S. DOT automated vehicle policy disclosures. Bottom-up unit economics for sensor-fusion stacks and V2V communication hardware triangulated against top-down fleet procurement surveys.
Segment-weighting across vehicle class, technology layer, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions included Class 8 truck versus bus versus van deployments, V2V communication versus sensor fusion versus AI algorithm revenue allocation, and U.S. interstate corridor versus EU cross-border versus Japan BRT lane adoption patterns. CAGRs derived from installed base penetration curves and replacement cycle assumptions. Key inputs incorporated DSRC-to-C-V2X migration velocity, ISO 26262 certification queue lengths, and dedicated contract carriage procurement concentration.
The model holds under sustained federal pilot program support and stable semiconductor supply; deviation in cross-border liability harmonization timelines or lidar component trade restrictions would shift fleet procurement cycles. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
North America Vehicle Tolling System Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Global Smart Highway Market
Smart Transportation Solutions
Physical Internet (PI) Market