
 Smart Parking Systems Market | 2026-2036
Smart Parking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parking Systems Market Intelligence
Municipal procurement channels is reshaping how parking technology reaches end users. Siemens Mobility leverages deep relationships with city transport authorities across multiple continents. Cisco Systems, Inc. anchors its position through edge computing infrastructure that underpins real-time occupancy networks. SKIDATA AG specializes in ticketless flow management for high-throughput commercial and airport environments.
Smart parking systems integrate ultrasonic, camera, and magnetic field sensors with cloud-based analytics platforms to detect, monitor, and monetize vehicle occupancy in structured and surface parking assets. These systems reduce search time, curb emissions from circling traffic, and enable dynamic pricing for asset owners. Sensor-based and IoT technology segments lead deployment volume, though cloud computing architectures capture expanding margin pools as cities consolidate multi-site data. Mobile applications and ticketless parking solutions within the solution dimension are growing fastest, driven by consumer preference for frictionless entry and exit.
The EU Green Deal and F-Gas Regulation shape equipment standards for sensor manufacturing and data center cooling in European deployments, while the FCC governs wireless spectrum allocation for IoT sensor networks in United States installations. Municipalities in California, Texas, and New York face divergent state-level procurement rules that fragment vendor qualification pathways. Stakeholders must weigh interoperability standards against proprietary ecosystem lock-in when selecting platform partners for multi-decade infrastructure commitments.
Market Dynamics
Municipal procurement of sensor-based infrastructure is accelerating under EU Green Deal mobility targets, while IoT-enabled payment solutions concentrate demand in California's urban corridors. This dual-channel dynamic splits vendor strategies between long-cycle government contracts and rapid-deployment commercial rollouts.
Growth Catalysts
- EU Green Deal mobility targets:German cities are procuring ultrasonic and camera-based occupancy detection systems to meet emissions reduction mandates for urban traffic.
- Edge computing infrastructure:Real-time data processing at parking facility perimeters enables sub-second occupancy updates for dynamic pricing algorithms.
- California urban corridor density:Los Angeles and San Francisco operators are deploying ticketless flow management to reduce entry-exit friction in high-throughput commercial garages.
Market Restraints
- Wireless spectrum allocation constraints:FCC licensing timelines for IoT sensor networks in dense urban environments create deployment bottlenecks for multi-site operators.
- Sensor hardware supply concentration:Magnetic field sensor fabrication relies on concentrated Asian semiconductor foundry capacity, exposing procurement to geopolitical disruption.
- Legacy payment system interoperability:Municipal parking authorities face technical debt from decades-old revenue collection infrastructure that resists API-based integration.
Strategic Opportunities
- Airport commercial parking modernization:High-throughput environments in Dubai and Singapore are adopting license plate recognition fused with mobile payment wallets.
- Cloud analytics platform consolidation:Multi-site parking asset owners are migrating from on-premise servers to centralized data lakes for predictive maintenance.
- India smart city mission funding:Bengaluru and Mumbai municipal corporations are tendering for integrated parking management under centrally sponsored urban transformation schemes.
Industry Challenges
- Embedded systems firmware expertise scarcity:Parking technology vendors struggle to recruit engineers capable of optimizing ultrasonic sensor arrays for low-power edge deployment.
- Multi-vendor integration complexity:Asset owners face technical risk when binding proprietary sensor hardware with third-party payment gateway APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parking Systems Market |
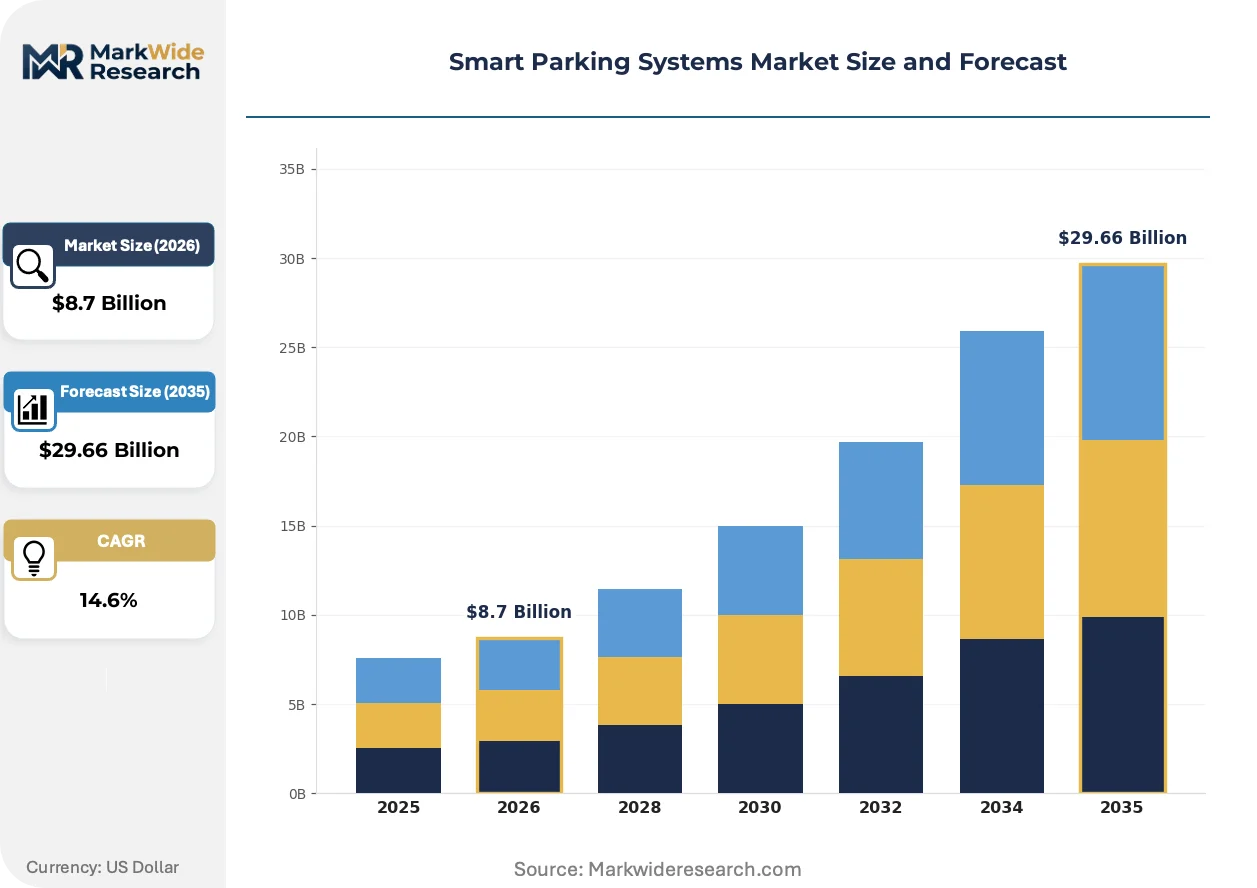
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, RFID, Sensor-Based, Cloud Computing Application: Urban Parking, Commercial Centers, Airports, Event Venues End User: Municipalities, Corporations, Parking Operators, Property Owners Solution: Mobile Applications, Ticketless Parking, Reservation Systems, Payment Solutions |
| Companies Covered | ParkMobile, Smart Parking Ltd., IPS Group, Siemens Mobility, Cisco Systems, Inc., SKIDATA AG, Swarco AG, Streetline, Amano McGann, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parking Systems Market Strategic Shifts & Innovations
Sensor fusion architectures and cloud-native software stacks are rewriting competitive boundaries in parking technology. Vendors must now orchestrate hardware, connectivity, and analytics layers rather than dominating single technology silos.
Computer vision is hybridizing with ultrasonic detection in next-generation occupancy systems. Airport and shopping mall operators in Germany and the Netherlands are piloting dual-mode sensors that combine camera-based vehicle classification with acoustic distance measurement. This convergence is compressing hardware vendor margins while expanding software licensing opportunities for analytics platforms.
The EU F-Gas Regulation is restricting refrigerant choices for data center cooling in European parking management deployments. Edge computing nodes hosting real-time video analytics now face equipment redesign timelines to comply with phasedown schedules. German and French facility operators are accelerating procurement of liquid-cooled server racks ahead of enforcement milestones.
Frictionless entry expectations are displacing traditional ticket-and-pay models in premium commercial segments. Corporate campus and hospital parking buyers in California and Texas are unbundling hardware purchase from software subscription, shifting capital expenditure to operational budgets. This preference compression is visible most acutely in Austin and Dallas-Fort Worth medical center expansions.
Smart Parking Systems Market Segmentation
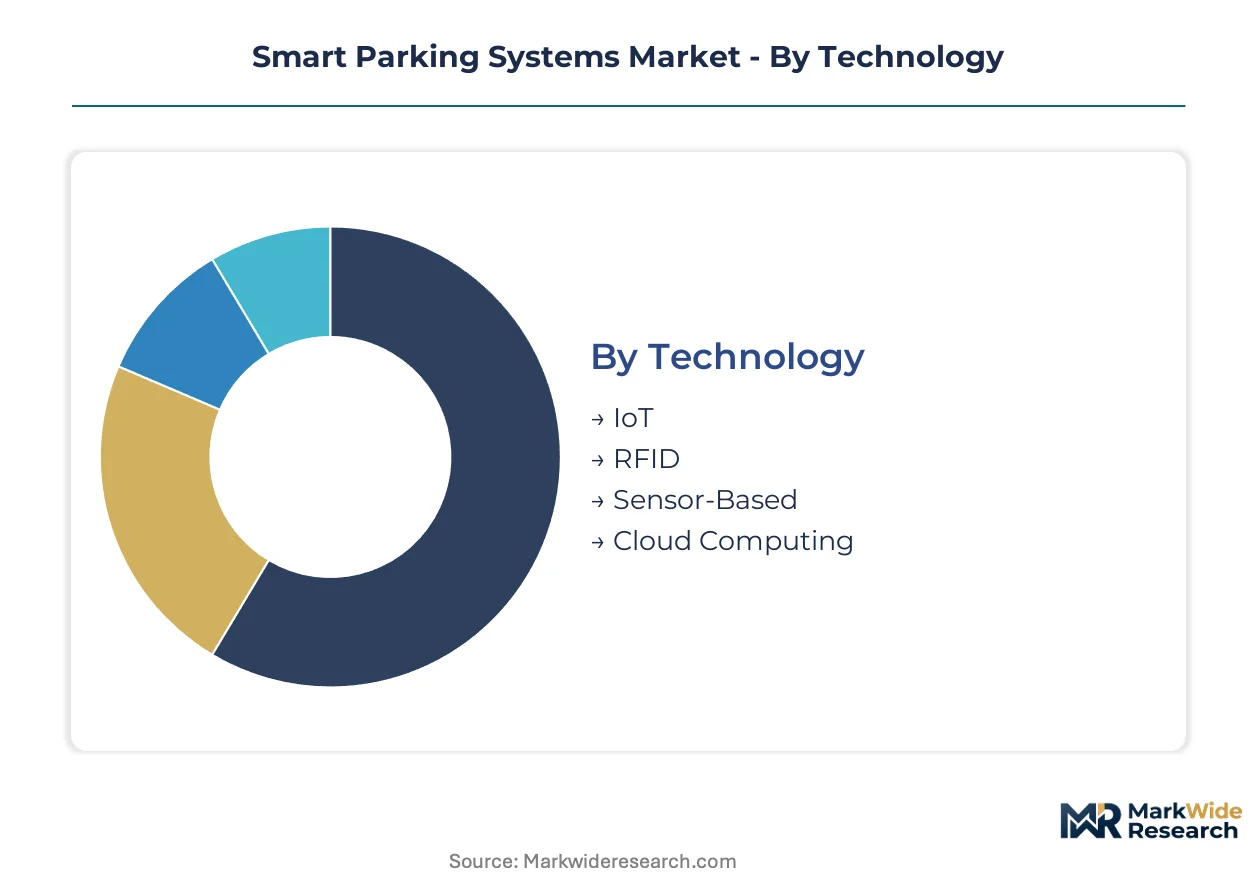
Smart parking systems fragment across four intersecting dimensions that determine deployment architecture and procurement pathways. Technology choices lock in sensor hardware lifecycles, while end-user categories split between municipal budget cycles and commercial ROI horizons. Solution preferences increasingly separate frictionless consumer experiences from legacy infrastructure retrofit constraints.
Technology:
Mature sensor architectures coexist with emerging cloud-native stacks, creating divergent margin profiles across the technology spectrum.
- Sensor-Based:Ultrasonic, camera, and magnetic field arrays form the physical detection layer in structured parking assets. German cities under EU Green Deal mandates are procuring these systems to monitor occupancy and curb circling emissions in dense urban cores.
- Cloud Computing:Centralized data lakes enable predictive maintenance algorithms and dynamic pricing across multi-site portfolios. Multi-asset owners in California are migrating from on-premise servers to capture analytics margin expansion.
- IoT:Wireless sensor networks transmit real-time occupancy data to edge nodes for sub-second processing. FCC spectrum allocation timelines in dense US urban corridors constrain deployment velocity for multi-site operators.
- RFID:Radio-frequency identification enables hands-free access control in high-throughput commercial environments. Airport operators in Dubai and Singapore deploy RFID fused with license plate recognition for seamless entry-exit flows.
Sensor-Based retains volume leadership; Cloud Computing holds the steepest expansion curve.
Application:
Application demand concentrates in settings where throughput pressure and revenue optimization intersect most acutely.
- Commercial Centers:Shopping mall and retail garage operators deploy ticketless flow management to reduce entry friction during peak hours. Los Angeles and San Francisco garage operators prioritize mobile payment wallet integration.
- Airports:High-throughput commercial parking facilities require license plate recognition fused with real-time occupancy dashboards. Singapore Changi and Dubai International are modernizing legacy revenue collection infrastructure.
- Urban Parking:Municipal surface lots and on-street zones integrate with citywide mobility platforms under emissions reduction targets. German cities procure ultrasonic detection to meet EU Green Deal mobility benchmarks.
- Event Venues:Stadium and arena parking demands surge-handling capacity with pre-booked reservation systems. Texas medical center expansions in Austin and Dallas-Fort Worth unbundle hardware purchase from software subscription.
Commercial Centers anchor current revenue concentration; Airports demonstrate the most aggressive modernization timelines.
End User:
End-user procurement patterns split between long-cycle government tenders and rapid-deployment commercial contracts.
- Municipalities:City transport authorities issue multi-year sensor infrastructure tenders under federally sponsored urban transformation schemes. Bengaluru and Mumbai municipal corporations tender integrated parking management under India's smart city mission funding.
- Parking Operators:Third-party facility managers prioritize interoperability across proprietary hardware and third-party payment gateway APIs. Technical debt from decades-old revenue collection infrastructure resists API-based integration.
- Corporations:Corporate campus buyers in California and Texas shift capital expenditure to operational budgets through software subscription models. Frictionless entry expectations displace traditional ticket-and-pay models in premium commercial segments.
- Property Owners:Real estate asset holders consolidate multi-site data into centralized analytics platforms for yield optimization. Edge computing nodes hosting real-time video analytics face equipment redesign timelines under EU F-Gas Regulation phasedown schedules.
Municipalities dominate procurement volume; Parking Operators show the fastest adoption of platform consolidation strategies.
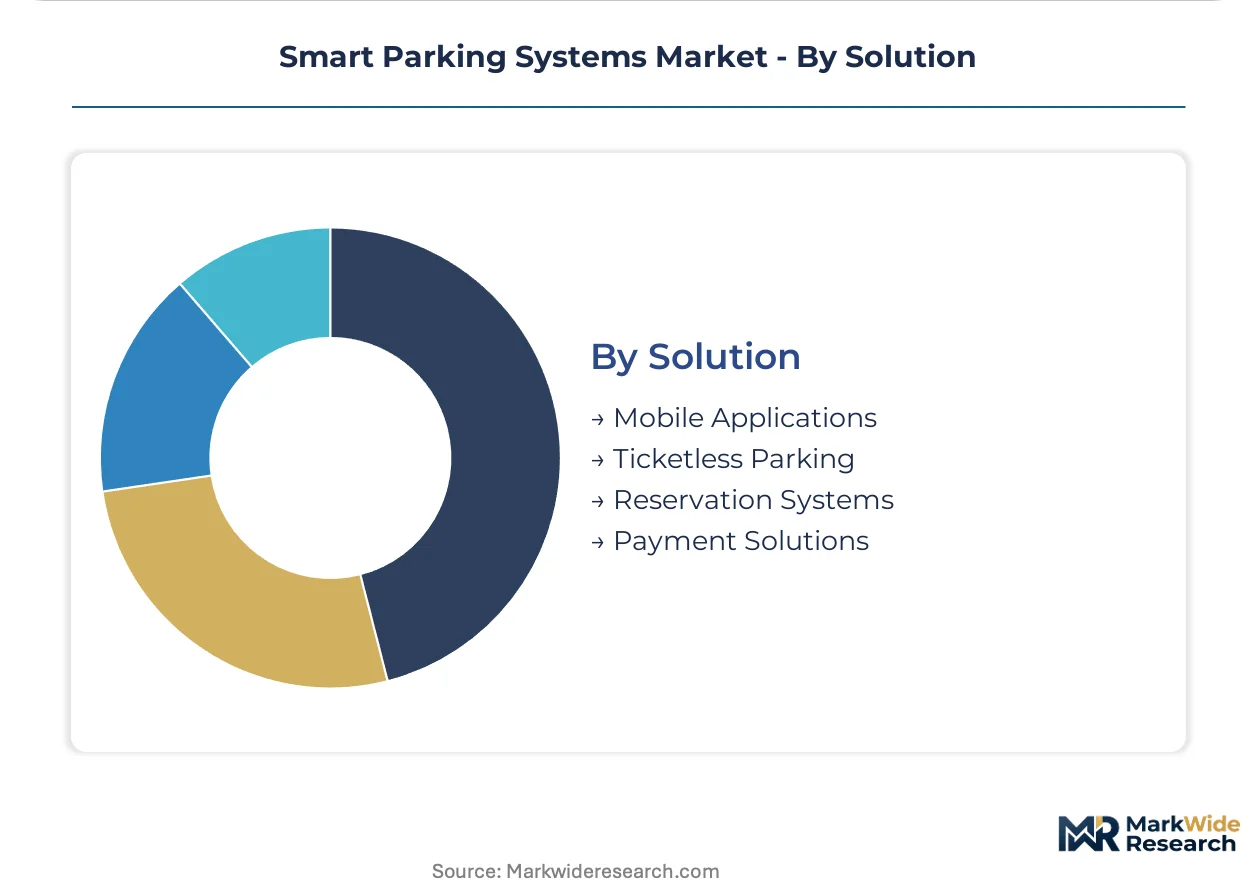
Solution:
Solution preferences trace consumer friction tolerance and the unbundling of hardware from software monetization.
- Mobile Applications:Smartphone-based entry, exit, and payment orchestration eliminates physical ticket infrastructure. Consumer preference for frictionless experiences drives fastest uptake in California urban corridors.
- Ticketless Parking:License plate recognition and automatic payment settlement remove all physical interaction points. German and Dutch airport and shopping mall operators pilot dual-mode sensors combining computer vision with acoustic distance measurement.
- Payment Solutions:IoT-enabled transaction processing concentrates demand in high-density commercial zones. API integration challenges with legacy municipal revenue systems create deployment friction.
- Reservation Systems:Pre-booked space allocation with guaranteed availability targets event venue and airport segments. Bengaluru and Mumbai smart city tenders emphasize integrated reservation platforms.
Mobile Applications capture the steepest consumer adoption slope; Ticketless Parking commands premium pricing in high-throughput environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Autobahn digital infrastructure corridor underwrites Germany's central role in European smart parking deployment, while interstate highway networks and municipal fiber backbones shape demand patterns across the United States.
United States
California's urban corridor density and Texas medical center expansions drive ticketless flow management procurement. The FCC governs wireless spectrum allocation for IoT sensor networks in dense urban environments. Los Angeles and San Francisco garage operators prioritize mobile payment wallet integration for frictionless entry-exit.
Germany
Municipal transport authorities procure ultrasonic and camera-based occupancy detection systems under EU Green Deal mobility targets. The EU F-Gas Regulation restricts refrigerant choices for data center cooling in edge computing nodes. Berlin and Munich facility operators accelerate liquid-cooled server rack procurement ahead of enforcement milestones.
India
Bengaluru and Mumbai municipal corporations tender integrated parking management under centrally sponsored urban transformation schemes. The country's national urban development mission provides funding for smart city infrastructure. Maharashtra and Karnataka state governments concentrate deployment in high-density commercial zones.
Singapore
Changi Airport and downtown commercial districts demand license plate recognition fused with real-time occupancy dashboards. The country's national standards body sets interoperability requirements for sensor network deployment. The city-state's compact urban geography enables rapid multi-site platform consolidation.
United Arab Emirates
Dubai International Airport modernization drives high-throughput commercial parking technology procurement. The country's telecommunications regulator oversees IoT network licensing for urban sensor deployment. Dubai's smart city initiative concentrates demand in premium commercial and hospitality assets.
Smart Parking Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in sensor hardware and edge computing modules. The vendor base splits between consolidated multinational infrastructure conglomerates and fragmented regional software developers. Two strategic archetypes dominate: municipal contract specialists with deep transport authority relationships, and commercial rapid-deployment vendors serving high-throughput private assets. Competitive moves concentrate on strategic partnerships for interoperability certification and geographic expansion into smart city funding jurisdictions.
Within the municipal contract specialist tier, Siemens Mobility and Cisco Systems, Inc. occupy positions anchored in multi-continent transport authority relationships. SKIDATA AG exemplifies the high-throughput commercial archetype through its ticketless flow management specialization. ParkMobile represents the mobile-first payment platform segment that is displacing traditional revenue collection infrastructure.
| Leading Market Players |
|---|
| ParkMobile |
| Smart Parking Ltd. |
| IPS Group |
| Siemens Mobility |
| Cisco Systems, Inc. |
| SKIDATA AG |
| Swarco AG |
| Streetline |
| Amano McGann, Inc. |
| Others |
Cost & Logistics Intelligence
Taiwanese semiconductor foundry capacity anchors magnetic field sensor fabrication, concentrating procurement leverage among ultrasonic and camera-based occupancy detection vendors. This geographic concentration cascades into tiered hardware pricing, where municipal buyers in Germany and California face divergent cost structures based on volume scale and integration complexity.
Pricing Analysis
Volume-discount tiering structures separate enterprise-grade platform subscriptions from transactional per-space SaaS models. Three-tier pricing stratifies across premium analytics suites, standard occupancy monitoring, and economy sensor-only deployments. Price differentiation centers on edge computing integration depth and API interoperability certification. Cost compression in the economy tier is intensifying because Asian foundry output expansion is flooding basic ultrasonic module supply. Municipal transport authorities exhibit highest price sensitivity due to multi-year budget cycles, while airport operators in Dubai and Singapore absorb premium pricing for sub-second latency guarantees.
Supply Chain Analysis
Upstream feedstock for IoT sensor networks draws from Taiwanese semiconductor foundries, South Korean memory fabrication, and Chinese printed circuit board assembly. Critical inputs span magnetic field sensing elements, edge computing processors, and low-power wireless transceivers. Single-source vulnerability concentrates in advanced ultrasonic sensor MEMS fabrication, where two foundries control specialty wafer supply. Distribution runs through municipal procurement channels in EU member states and direct commercial sales to parking operators in US urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
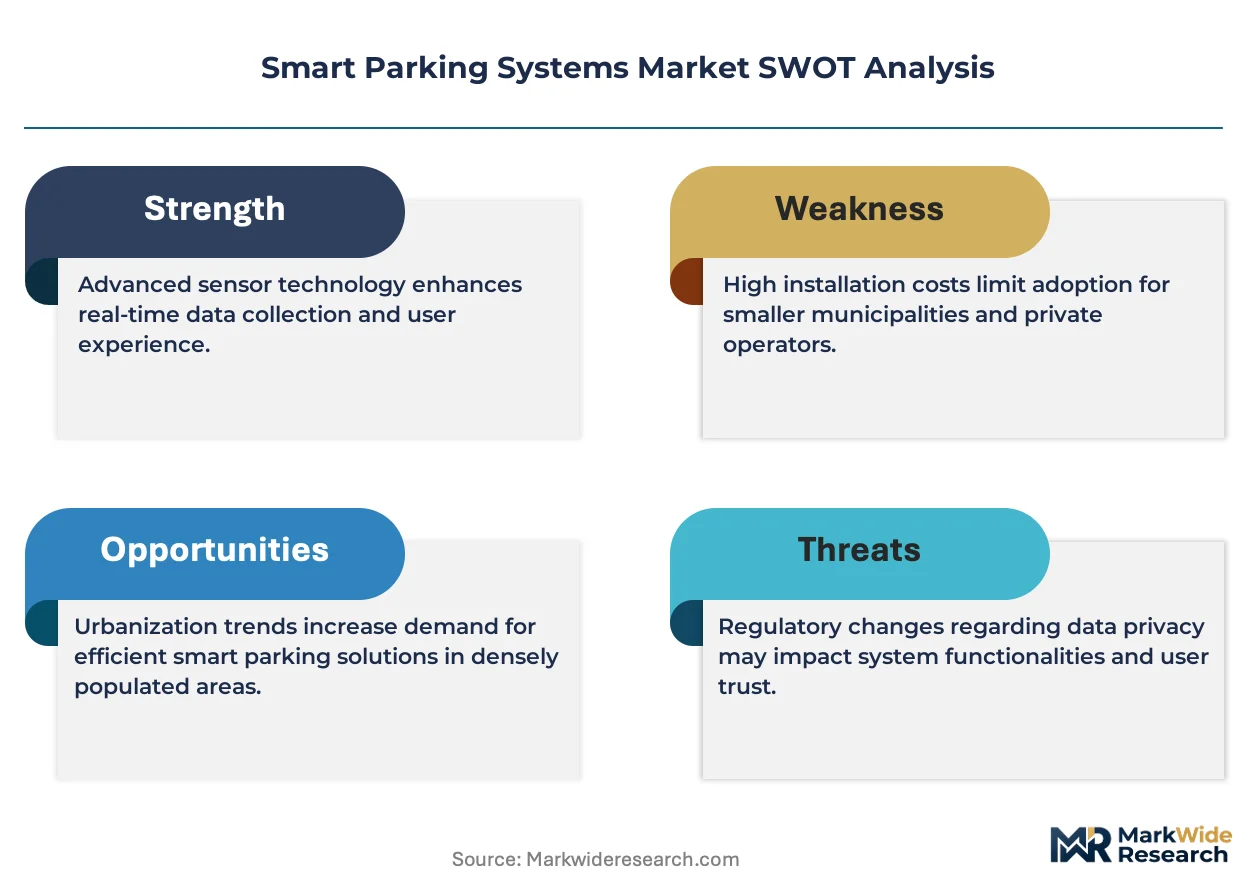
Smart parking systems sit in early-cycle expansion as EU Green Deal mobility mandates force municipal infrastructure replacement waves. India's smart city mission funding and California's urban corridor density together create dual-front adoption acceleration.
For Market Incumbents: Build switching-cost moats through deep API integration with legacy municipal revenue systems. Siemens Mobility and Cisco Systems should anchor multi-site platform consolidation contracts before cloud-native challengers displace on-premise server architectures. Threat vectors include software-first entrants unbundling hardware from subscription analytics. Priority lever rests in certification investment for EU F-Gas Regulation compliance on edge computing cooling systems.
For New Entrants and Emerging Players: Build out white-space penetration in India's Bengaluru and Mumbai municipal tender pipelines, where centrally sponsored urban transformation schemes concentrate unmet demand. Texas medical center expansions in Austin and Dallas-Fort Worth offer rapid-deployment commercial contracts with frictionless entry expectations displacing legacy ticket infrastructure. Go-to-market angle should emphasize mobile-first payment wallet integration over hardware-heavy sensor deployment.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because parking asset digitization follows predictable municipal budget cycles with recurring SaaS monetization tailwinds. Acquisition target archetype: regional software developers with smart city tender relationships but lacking edge computing hardware partnerships. Signal to watch is FCC wireless spectrum allocation velocity in dense US urban environments, which gates IoT sensor network deployment speed for multi-site operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies proprietary sensor hardware with third-party payment gateway APIs for municipal operators. |
| Geographic Expansion | Targets India's smart city mission funding corridors in Maharashtra and Karnataka states. |
| Product Launch | Introduces liquid-cooled edge computing nodes ahead of EU F-Gas Regulation enforcement milestones. |
| Strategic Partnership | Fuses license plate recognition with mobile payment wallets for Dubai airport modernization. |
| Acquisition of Specialist Firm | Captures embedded systems firmware expertise scarce in ultrasonic sensor array optimization. |
Research Approach
The analysis maps sensor-based detection, IoT connectivity, cloud analytics, and RFID access control segments, each validated through city transport authority procurement officers, parking facility operators, edge computing infrastructure vendors, and mobile payment platform developers. Primary interview intelligence triangulates against SEC 10-K filings, EU tender documentation databases, smart city mission funding disclosures, and customs records for sensor hardware trade flows. Bottom-up unit deployment estimates reconcile with top-down addressable parking asset calculations.
Assumption sets held municipal procurement cycle timing and FCC spectrum allocation timelines fixed while varying IoT sensor network penetration rates and cloud migration velocity across commercial asset portfolios. Segmentation dimensions modeled span technology architecture, application setting, end-user procurement type, and solution delivery model. CAGRs derive from parking space inventory growth, sensor replacement cycles, and software subscription attach rate trajectories. Forecast inputs incorporate EU Green Deal mobility target compliance deadlines and India's centrally sponsored urban transformation scheme disbursement schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native software entrants or hyperscaler platform providers would shift outcomes beyond modeled ranges. Cross-checking against municipal capital expenditure budget disclosures and smart city mission funding allocation reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market