
 Car Sharing Market | 2026-2036
Car Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Car Sharing Market Analysis
Subscription bundling with public transit passes is repositioning how urban buyers evaluate mobility costs. Zipcar Inc anchors its position through university and corporate campus partnerships. Turo Inc leverages peer-to-peer host networks to sustain inventory without capital-heavy fleet ownership. Enterprise CarShare competes through integrated airport and downtown location density.
Car sharing denotes short-term vehicle rental services where users access automobiles by the hour or minute through digital platforms, typically requiring smartphone authentication and GPS-enabled fleet tracking for real-time availability and remote unlocking. The primary commercial purpose is to provide on-demand automotive access without ownership burdens, serving commuters, tourists, and business travelers in congested urban corridors. One-way service models are capturing the fastest growth as free-floating deployments reduce return-trip friction for spontaneous trips. Electric vehicle segments within fleet composition are expanding rapidly where municipal low-emission zones restrict internal combustion engine access. Corporate user categories generate higher utilization rates and longer average trip durations than individual consumer accounts.
European regulators enforce the EU Green Deal and F-Gas Regulation to compel fleet operators toward zero-emission vehicle procurement, while the EPA and NHTSA in the United States set tailpipe and safety standards that shape permissible fleet composition. China's MIIT implements dual carbon goals that pressure operators to accelerate electric vehicle integration in metropolitan deployments. Stakeholders must monitor how fragmented municipal permitting regimes for curbside parking and charging infrastructure allocation determine viable operating geographies.
Market Dynamics
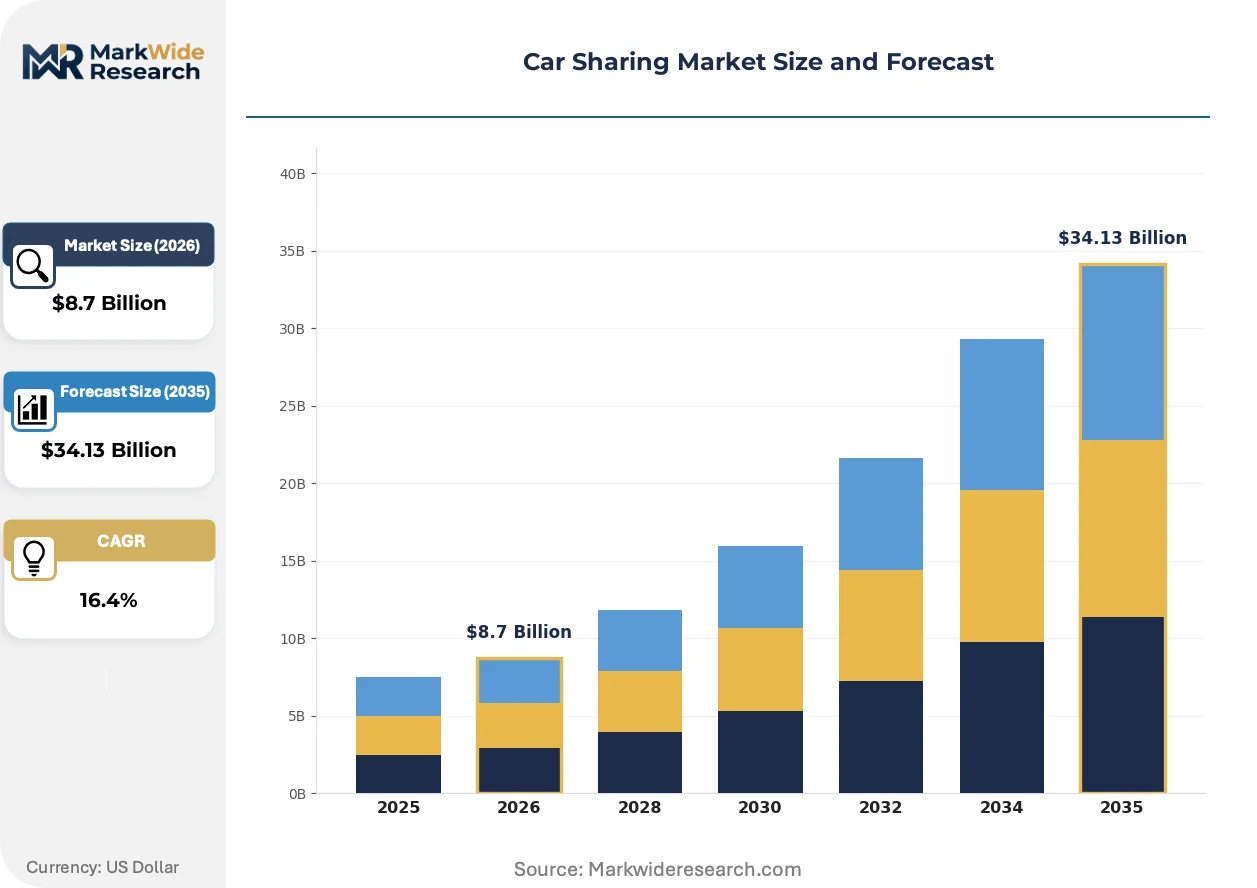
Fleet electrification mandates are compressing operator margins while simultaneously unlocking access to municipal low-emission zones. The EU Green Deal and China's dual carbon goals are forcing capital reallocation toward zero-emission vehicle procurement ahead of utilization economics.
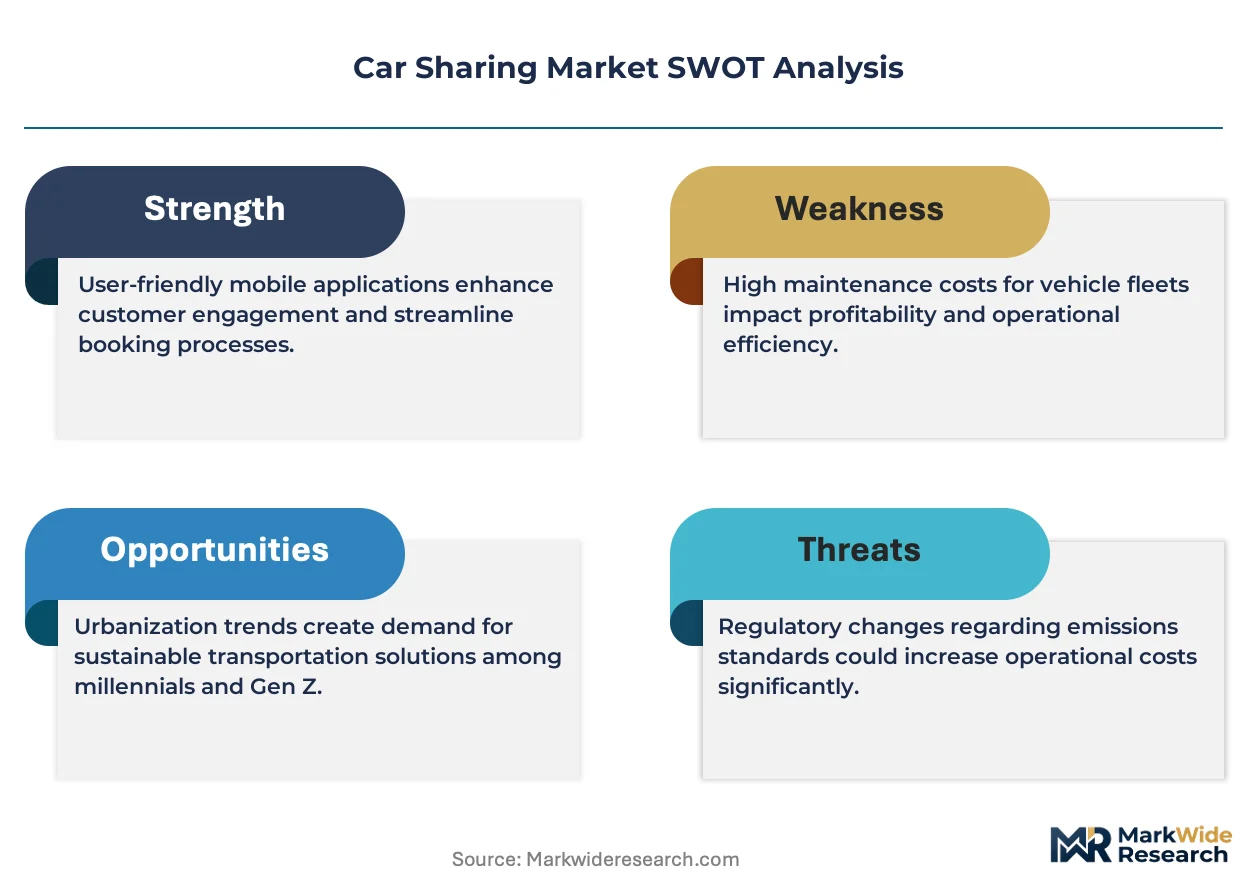
Growth Catalysts
- EU Green Deal:Zero-emission vehicle procurement mandates unlock operating rights in city-center low-emission zones across Germany, France, and the Netherlands.
- Parking scarcity:Dense metropolitan clusters in China and the United States generate structural demand for on-demand vehicle access without ownership burdens.
- Telematics integration:GPS-enabled fleet tracking and smartphone authentication reduce per-transaction operational overhead and enable free-floating deployments.
Market Restraints
- Lithium-ion battery cost volatility:Electric vehicle fleet procurement exposes operators to raw material price swings in cobalt and nickel supply chains concentrated in the Democratic Republic of Congo and Indonesia.
- Municipal permitting fragmentation:Curbside parking allocation and charging infrastructure siting decisions vary block-by-block, creating geographic operating uncertainty.
- Public transit substitution:Subscription bundling with metro and bus passes in European cities reduces standalone car-sharing appeal for daily commuters.
Strategic Opportunities
- Corporate campus expansion:Enterprise accounts in the United States generate higher utilization rates and longer trip durations than individual consumer segments.
- One-way free-floating models:Spontaneous trip origination without return-trip obligations captures demand from tourists and business travelers in congested urban corridors.
- F-Gas Regulation phase-down:European fleet operators accelerating electric vehicle integration gain preferential charging infrastructure allocation from municipal authorities.
Industry Challenges
- Charging infrastructure deployment timelines:Grid connection permits and utility upgrade schedules delay fleet electrification rollouts in high-density metropolitan zones.
- Vehicle damage and liability attribution:Peer-to-peer host networks face unresolved insurance complexity when individual owners list private vehicles on digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Sharing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer, Round Trip, One-Way, Monthly Subscription Customer Type: Corporate Users, Individual Consumers, Fleet Operators, Students Technology: Mobile App, Web Platform, GPS Tracking, RFID Systems Vehicle Type: Electric Vehicles, SUVs, Compact Cars, Luxury Vehicles |
| Companies Covered | Enterprise CarShare, Free2Move, Zipcar Inc, SOCAR Group, Zoomcar Ltd, Turo Inc, Share Now GmbH, GIG Carshare, Getaround Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Sharing Market Emerging Trajectories
Digital authentication and real-time availability systems are compressing transaction friction to the point of spontaneous mobility decisions. Three developments are consolidating competitive positioning around fleet composition, regulatory compliance, and user experience design.
Telematics-enabled remote unlocking is consolidating control over vehicle access authentication. Fleet operators and peer-to-peer platforms deploy GPS tracking with smartphone-based keyless entry, eliminating physical key exchange. Urban commuters and corporate account managers adopt these systems for immediate reservation-to-departure intervals measured in minutes rather than hours.
China's MIIT dual carbon goals are accelerating electric vehicle integration timelines for metropolitan deployments. Domestic operators face procurement quotas that prioritize battery-electric models over plug-in hybrids. Fleet composition in Beijing, Shanghai, and Shenzhen is shifting toward zero-emission vehicles to maintain operating licenses under municipal low-emission zone restrictions.
Subscription bundling with public transit passes is displacing standalone car-sharing memberships in European metropolitan corridors. Urban buyers evaluate mobility costs through integrated monthly expenditures rather than per-trip pricing. This pattern concentrates in Germany and the Netherlands where transit authorities negotiate corporate rates combining rail, bus, and on-demand vehicle access.
Car Sharing Market Segmentation
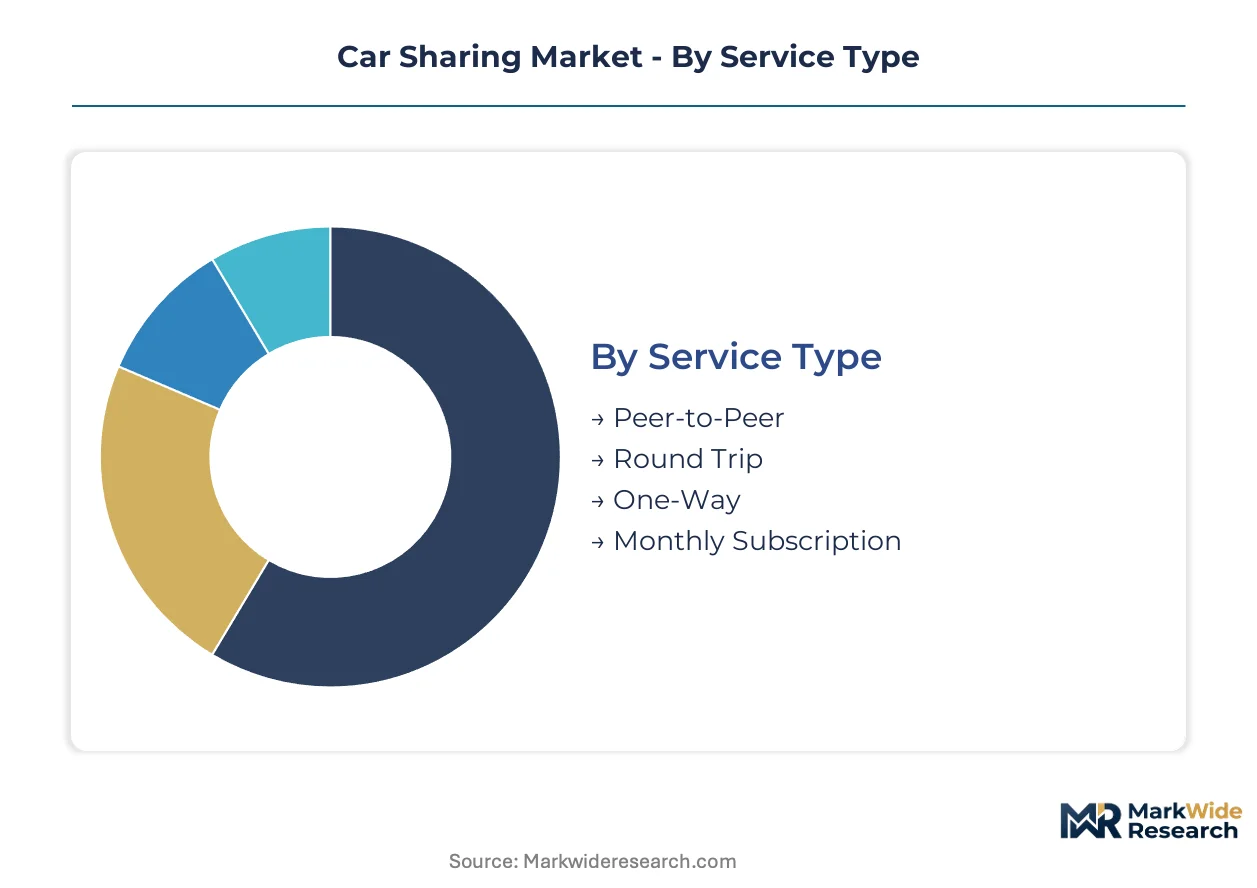
Car sharing operators configure service portfolios around trip duration patterns, user authentication methods, and fleet composition mandates. Segmentation decisions directly determine capital allocation between owned fleet assets and peer-to-peer host networks, while shaping compliance exposure to municipal electrification requirements.
Service Type:
EU Green Deal zero-emission procurement mandates apply differentially across service models, with free-floating deployments facing stricter curbside parking certification than station-based alternatives.
- Peer-to-Peer:Individual vehicle owners list private automobiles on digital platforms, eliminating operator capital burden for fleet acquisition. Demand concentrates in United States metropolitan corridors where parking scarcity and high vehicle ownership rates create structural host supply. Insurance complexity and damage liability attribution remain unresolved regulatory gaps under NHTSA guidelines.
- One-Way:Free-floating deployments enable trip origination and termination at distinct locations without return obligations. Growth is accelerating in Germany and Netherlands urban centers where municipal low-emission zone access depends on battery-electric fleet composition. Smartphone authentication and GPS-enabled fleet tracking reduce per-transaction operational overhead to minutes.
- Round Trip:Station-based models require users to return vehicles to designated pickup locations. Corporate campus contracts in China generate predictable utilization rates through fixed commuting patterns.
- Monthly Subscription:Bundled access packages integrate with public transit passes in European metropolitan corridors. Germany's transit authorities negotiate corporate rates combining rail, bus, and on-demand vehicle access.
One-Way sits at the top of the volume ranking, with Peer-to-Peer climbing the fastest.
Customer Type:
Margin profiles diverge sharply between account categories, with corporate segments delivering longer trip durations and higher per-user revenue against individual consumer price sensitivity.
- Corporate Users:Enterprise accounts generate utilization rates substantially above consumer segments through business travel and inter-campus mobility requirements. United States technology and consulting firms deploy car sharing for airport-downtown connectivity and client site visits. EPA tailpipe standards shape permissible fleet composition for corporate sustainability reporting obligations.
- Individual Consumers:Urban commuters in dense metropolitan zones substitute ownership with on-demand access for weekend trips and occasional errands. Parking scarcity in China and United States city centers creates structural demand without ownership burdens.
- Fleet Operators:Commercial vehicle lessors integrate car sharing platforms into multi-modal mobility portfolios. China's MIIT dual carbon goals pressure operators toward battery-electric procurement quotas.
- Students:University campus partnerships anchor predictable demand through semester-based subscription models. Zipcar Inc maintains location density through exclusive institutional contracts.
Corporate Users command the highest revenue per account, with Fleet Operators expanding most quickly under electrification mandates.
Technology:
Authentication and tracking infrastructure investments determine operational scalability and geographic expansion feasibility across municipal permitting regimes.
- Mobile App:Smartphone-based reservation, authentication, and payment systems consolidate user experience into single-platform access. Real-time availability displays and remote unlocking compress transaction friction to spontaneous mobility decisions. GPS-enabled fleet tracking enables free-floating deployments in Germany and Netherlands without physical key exchange.
- GPS Tracking:Telematics integration provides real-time vehicle location, utilization monitoring, and geofencing for low-emission zone compliance. Municipal authorities in China mandate tracking systems for operating license eligibility.
- Web Platform:Browser-based reservation systems serve corporate account managers and institutional procurement workflows. Enterprise CarShare competes through integrated booking portals for business travel departments.
- RFID Systems:Contactless card authentication persists in legacy station-based deployments and university campus networks. Turo Inc leverages host network flexibility without proprietary hardware requirements.
Mobile App dominates transaction volume, with GPS Tracking gaining share fastest under fleet electrification compliance requirements.
Vehicle Type:
Fleet composition decisions lock in operating rights under fragmented municipal low-emission zone regimes while exposing operators to lithium-ion battery supply chain volatility.
- Electric Vehicles:Battery-electric models unlock access to city-center low-emission zones across Germany, France, and Netherlands under EU Green Deal implementation. China's MIIT dual carbon goals accelerate metropolitan deployment timelines ahead of utilization economics. Raw material price swings in cobalt and nickel supply chains compress procurement margins.
- Compact Cars:High-density urban parking constraints favor smaller vehicle footprints for street-side availability. Demand concentrates in congested metropolitan corridors where space efficiency determines viable operating geography.
- SUVs:Larger vehicle categories serve family weekend trips and suburban-originating demand outside core city centers. United States markets show stronger relative preference against European fleet composition.
- Luxury Vehicles:Premium segments target business traveler expense account utilization and tourist experiential demand. Peer-to-peer host networks in United States coastal cities supply inventory without operator capital deployment.
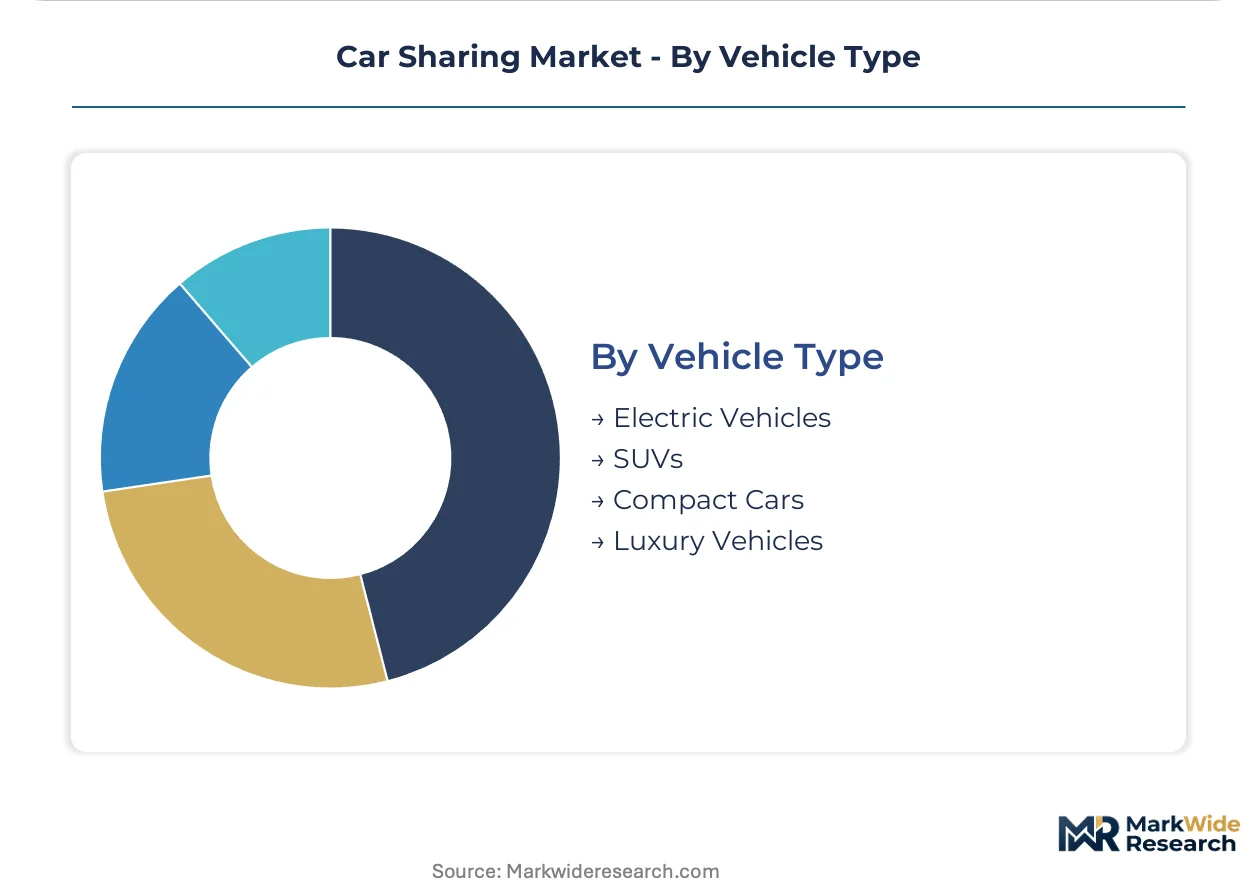
Compact Cars retain the largest fleet share, with Electric Vehicles climbing fastest under regulatory procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Car sharing originated in Switzerland and Germany during the 1980s, spreading through European university towns before scaling to North American and Asian metropolitan corridors. The industry's geographic footprint now clusters around dense urban zones with parking scarcity and emissions regulations.
Germany
Parking scarcity in Berlin, Hamburg, and Munich generates structural demand for on-demand vehicle access without ownership burdens. The EU Green Deal and F-Gas Regulation compel fleet operators toward zero-emission vehicle procurement to maintain operating rights in city-center low-emission zones. The Rhine-Ruhr metropolitan region hosts dense free-floating deployments where smartphone authentication and GPS-enabled fleet tracking reduce transaction friction.
United States
Corporate campus contracts and airport-downtown connectivity drive higher utilization rates than individual consumer segments. EPA tailpipe standards and NHTSA safety regulations shape permissible fleet composition for enterprise sustainability reporting. San Francisco, New York City, and Chicago concentrate peer-to-peer host networks where parking scarcity and high vehicle ownership rates create structural supply.
China
MIIT dual carbon goals pressure operators toward battery-electric procurement quotas ahead of utilization economics. Municipal low-emission zones in Beijing, Shanghai, and Shenzhen restrict internal combustion engine access, accelerating fleet electrification timelines. The Yangtze River Delta hosts the densest metropolitan deployments where grid connection permits and utility upgrades delay rollout schedules.
Netherlands
Subscription bundling with public transit passes displaces standalone memberships as urban buyers evaluate integrated mobility costs. EU Green Deal implementation unlocks preferential charging infrastructure allocation for operators accelerating electric vehicle integration. The Randstad conurbation concentrates free-floating deployments where telematics-enabled remote unlocking consolidates vehicle access authentication.
France
Low-emission zone restrictions in Paris, Lyon, and Marseille mandate battery-electric fleet composition for curbside parking certification. The EU Green Deal and REACH compliance frameworks shape procurement decisions for zero-emission vehicle deployment. Île-de-France anchors corporate account demand through business travel and inter-campus mobility requirements.
Car Sharing Market Vendor Landscape
Premium-margin players sit above commodity-margin players across fleet ownership intensity and regulatory compliance burden. The market structures around three tiers: capital-heavy fleet owners, asset-light peer-to-peer platforms, and integrated mobility bundlers. Strategic archetypes include university-campus specialists, free-floating urban operators, and corporate account managers. Dominant competitive moves encompass municipal permitting capture for curbside parking allocation and charging infrastructure siting partnerships.
Within the fleet ownership tier, Enterprise CarShare and Zipcar Inc represent capital-intensive archetypes with station-based and corporate campus density strategies. Turo Inc exemplifies the peer-to-peer model, leveraging host network flexibility without proprietary fleet acquisition. Share Now GmbH occupies a position bridging free-floating deployment with regulatory compliance across European low-emission zones.
| Leading Market Players |
|---|
| Enterprise CarShare |
| Free2Move |
| Zipcar Inc |
| SOCAR Group |
| Zoomcar Ltd |
| Turo Inc |
| Share Now GmbH |
| GIG Carshare |
| Getaround Inc |
| Others |
Supply Flow & Price Mechanics
Fleet electrification mandates across Germany, China, and the United States are simultaneously compressing procurement economics and concentrating supplier power among battery-electric vehicle manufacturers. Lithium-ion battery cost volatility feeds directly into operator margin structures, while municipal low-emission zone access rights determine which fleet compositions command premium positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments urban commuters, corporate accounts, and university students into distinct willingness-to-pay brackets. Quality grade differentiation rests on vehicle electrification status and real-time availability guarantees, with battery-electric fleets in EU low-emission zones extracting modest premiums over internal combustion alternatives. Cost compression in economy tiers is intensifying because peer-to-peer host networks eliminate capital-heavy fleet ownership burdens. Individual consumers exhibit highest price sensitivity against corporate accounts where expense account utilization reduces friction.
Supply Chain Analysis
Dual-sourcing requirements for lithium-ion cells are becoming standard practice among fleet operators seeking to mitigate cobalt and nickel price volatility from Democratic Republic of Congo and Indonesian supply chains. Vehicle procurement draws from China, Germany, and South Korea where battery-electric manufacturing capacity concentrates. Raw material dependencies center on cathode active materials, electrolyte formulations, and semiconductor components for telematics integration. Single-source vulnerability in cathode precursor supply creates structural exposure. Distribution runs through municipal permitting capture for curbside parking allocation and charging infrastructure siting partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Car sharing has entered a late-cycle quality phase where fleet electrification compliance and telematics integration separate viable operators from stranded assets. Demand is concentrating toward premium specifications that unlock low-emission zone operating rights.
For Market Incumbents: Extend charging infrastructure partnerships with municipal authorities to secure preferential curbside allocation under EU Green Deal implementation. Deepen backward integration into telematics platforms to reduce per-transaction authentication costs. Peer-to-peer host network expansion represents a named threat to capital-heavy fleet ownership models. For New Entrants and Emerging Players: Capture white-space in corporate campus contracts where utilization rates and trip durations exceed individual consumer segments. Target university partnerships for predictable semester-based subscription demand. One-way free-floating deployments in German and Dutch urban centers offer the most penetrable geography with lowest incumbent density. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light peer-to-peer platforms with host network scale but limited electrification compliance. Long-term viability over a multi-year window hinges on battery-electric fleet transition timelines and municipal permitting capture. Watch charging infrastructure deployment delays as the signal indicating margin compression acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Secures preferential curbside allocation from municipal authorities under EU Green Deal mandates. |
| Telematics Platform Integration | Compresses reservation-to-departure intervals through GPS-enabled fleet tracking and smartphone authentication. |
| Corporate Campus Expansion | Captures higher utilization rates and longer trip durations from enterprise account segments. |
| Peer-to-Peer Host Network Scale | Eliminates capital-heavy fleet ownership while sustaining inventory through individual vehicle listings. |
| Electric Vehicle Procurement Acceleration | Unlocks operating rights in Beijing, Shanghai, and Shenzhen municipal low-emission zones. |
Methodological Framework
Coverage spans Germany, China, the United States, Netherlands, and France, with primary inputs from each market cluster. Fleet operations directors, municipal transportation planners, corporate travel managers, and peer-to-peer platform hosts provided structured interviews. Secondary validation drew from EU Green Deal implementation documents, MIIT dual carbon goal announcements, EPA tailpipe standard filings, and municipal permitting databases. Bottom-up fleet deployment counts triangulated against top-down mobility expenditure estimates.
Granularity-level modeling disaggregated volume and value across service type, customer category, authentication technology, and vehicle propulsion architecture. CAGRs were derived from segmented growth rate reconciliation against aggregate market expansion. Electric vehicle procurement timelines, charging infrastructure deployment schedules, and subscription bundling penetration served as industry-specific forecast inputs throughout the projection horizon.
Municipal permitting fragmentation, lithium-ion battery cost volatility, and public transit substitution acceleration are the dominant revision risks to the outlook. Deviation in charging infrastructure deployment timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Micromobility Platform Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Smart Logistic Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Europe Smart Transportation Market