
 Nordic Bike Sharing Market | 2026-2036
Nordic Bike Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Bike Sharing Market Analytics
Urban commuter demand is shifting toward integrated multimodal transit networks across Nordic capitals. Smoove specializes in dock-based infrastructure systems that anchor municipal procurement contracts in French and Nordic cities. Oslo City Bike competes through seasonal subscription models that dominate Norway's capital region. Helsinki City Bikes leverages mobile-first fleet management to sustain ridership through extreme winter operating conditions.
Nordic bike sharing encompasses station-based, dockless, and electric-assisted bicycle fleets deployed for short-term urban mobility, typically integrating GPS tracking, smart locking, and app-based payment gateways for seamless user access. e-Bike segments command premium pricing due to higher capital costs and extended trip ranges across hilly Nordic topography. Subscription Services capture recurring revenue pools as commuters replace private vehicle ownership with predictable monthly mobility budgets.
EU Green Deal transport targets, national carbon-neutral frameworks in Denmark and Sweden, and municipal procurement standards collectively mandate electrified fleet minimums and winter durability certifications. The Danish Road Directorate and Swedish Transport Administration enforce safety specifications that filter market access for non-compliant hardware vendors. Stakeholders must monitor evolving battery recycling mandates and cross-border data portability rules governing user identity verification across integrated Nordic transit platforms.
Market Dynamics
Municipal procurement across Denmark, Norway, Sweden, and Finland is pivoting toward electrified fleet mandates and winter-weather durability certifications, compressing vendor qualification timelines and reshaping hardware specifications.
Growth Catalysts
- EU Green Deal transport targets:National carbon-neutral commitments in Denmark and Sweden mandate minimum electrified fleet percentages, forcing municipal tender documents to prioritize e-bike infrastructure.
- Last-mile commuter consolidation:Stockholm, Copenhagen, and Oslo metropolitan corridors are integrating bike sharing with rail and bus networks, creating bundled mobility budgets that displace private vehicle ownership.
- Battery chemistry advancement:Cold-weather lithium formulations extend operational range across Nordic winter conditions, reducing downtime and expanding viable service months.
Market Restraints
- Capital intensity of e-bike fleets:Battery replacement cycles and charging infrastructure impose higher upfront costs than mechanical bicycle systems, squeezing operator margins.
- Supply concentration in East Asian battery cells:Nordic fleet operators depend on concentrated cell manufacturing geographies, exposing procurement to logistics volatility and trade friction.
- Danish Road Directorate safety specifications:Rigorous hardware certification timelines delay vendor market entry and limit rapid fleet scaling.
Strategic Opportunities
- Finland's underpenetrated secondary cities:Tampere and Turku lack integrated bike sharing networks, presenting first-mover expansion potential outside Helsinki saturation.
- Cross-border data portability frameworks:Emerging Nordic transit platform integration enables unified user identity verification across national boundaries.
- Seasonal subscription model hybridization:Blending Oslo's winter-summer pricing with Copenhagen's year-round operations creates flexible revenue structures.
Industry Challenges
- Specialized maintenance technician scarcity:E-bike motor diagnostics and battery management systems require skills absent from traditional bicycle repair labor pools.
- Legacy municipal procurement cycles:Multi-year tender durations misalign with rapid hardware iteration, locking operators into obsolete specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Bike Sharing Market |
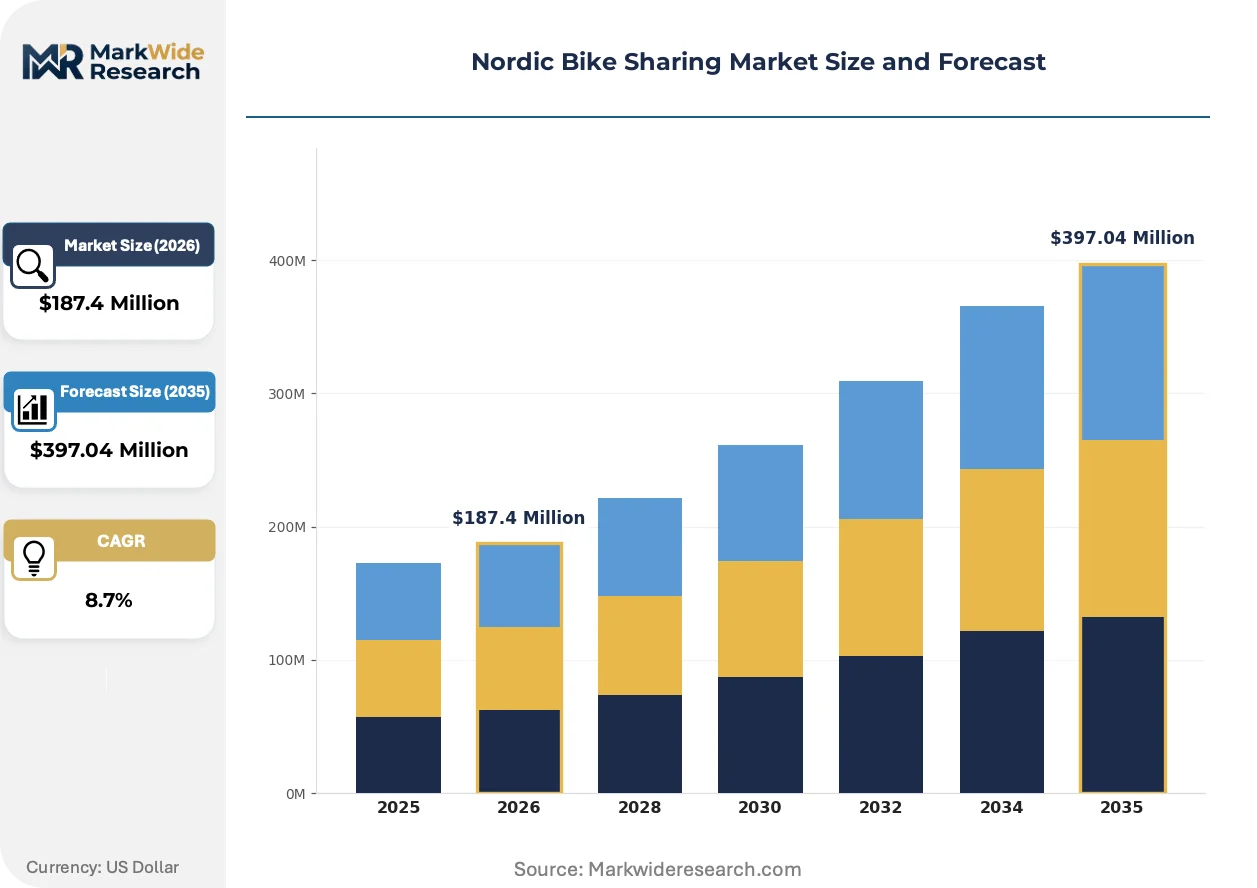
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Classic Rentals, Dockless Bikes, e-Bikes, Subscription Services End User: Commuters, Tourists, Students, Local Residents Technology: Mobile App Integration, GPS Tracking, Smart Locking, Payment Gateways Pricing Model: Hourly Rates, Daily Passes, Monthly Subscriptions, Group Discounts |
| Companies Covered | Smoove, Malmö By Bike, Oslo City Bike, Saimaa Bikes, oBike, Helsinki City Bikes, Rekola, Bycyklen, Urban Sharing, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Bike Sharing Market Evolving Landscape
Hardware durability standards and data interoperability protocols are converging to reshape how Nordic municipalities evaluate fleet vendors and structure service contracts.
Regenerative braking systems integrated with hub motors are absorbing kinetic energy during downhill urban segments, extending battery range by recapturing power that mechanical systems dissipate. Municipal operators in Oslo and Bergen are specifying this technology in tender documents to reduce charging infrastructure density. The structural consequence is compressing total cost of ownership calculations, favoring vendors with in-house motor development over component assemblers.
Sweden's Transport Administration has tightened winter durability certification requirements, mandating operational testing at minus fifteen degrees Celsius for all fleet hardware. This regulatory friction filters out Southern European and Asian vendors lacking cold-climate engineering capabilities. Danish and Norwegian procurement authorities are adopting similar test protocols, creating a harmonized Nordic hardware standard that diverges from continental European specifications.
Commuter preference is rotating toward multimodal journey bundling, with riders expecting seamless fare integration between bike sharing and rail networks. This behavioral pivot disrupts standalone app-based operators and elevates vendors with API-compatible fleet management systems. Copenhagen's transit authority is consolidating payment gateways, making interoperability a de facto procurement requirement rather than optional feature.
Nordic Bike Sharing Market Segmentation
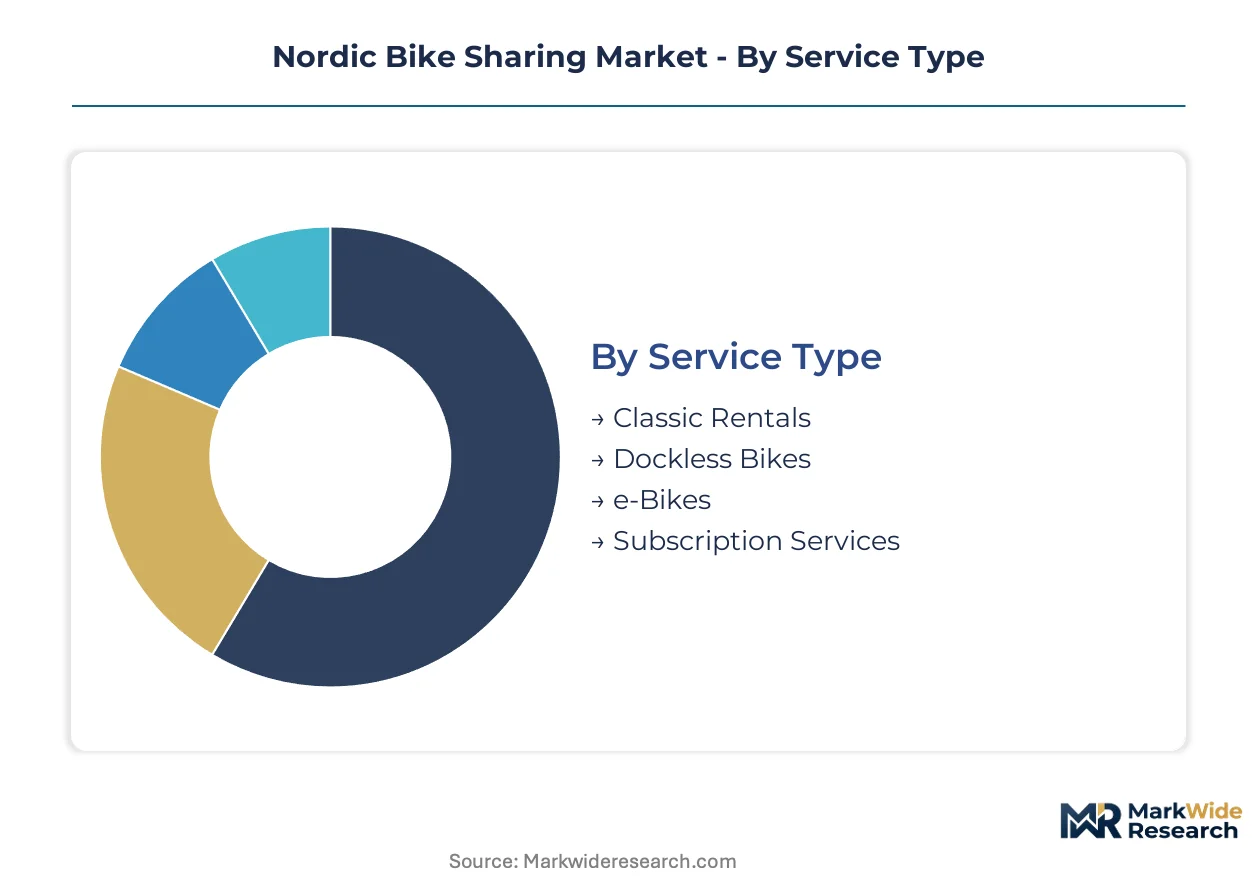
Nordic bike sharing operators configure fleet portfolios around distinct capital profiles, user behaviors, and municipal procurement requirements. Segment boundaries blur as electrification mandates and multimodal integration reshape vendor positioning across Copenhagen, Stockholm, and Oslo corridors.
Service Type:
e-Bike deployments absorb the heaviest upfront capital burden, while dockless mechanical fleets operate on leaner asset bases with higher per-unit utilization risk.
- Classic Rentals:Station-based mechanical bicycles with fixed docking infrastructure dominate legacy municipal contracts. Copenhagen's transit authority maintains these systems for cost-conscious corridor coverage, though procurement is tilting toward hybrid electrification mandates.
- Dockless Bikes:Free-floating mechanical fleets eliminate infrastructure capital but concentrate rebalancing labor costs. Norwegian operators deploy these selectively in Oslo's peripheral districts where station density proves economically unviable.
- e-Bikes:Pedal-assist bicycles with integrated battery systems command premium procurement pricing and extended operational ranges across hilly Nordic topography. Swedish Transport Administration tenders now specify minimum e-bike percentages, accelerating fleet conversion timelines.
- Subscription Services:Recurring revenue models with seasonal pricing variations anchor commuter retention. Oslo City Bike's winter-summer tiering demonstrates how subscription structures stabilize cash flow through extreme weather operating windows.
Most installed capacity flows through Classic Rentals. Expansion is steepest in e-Bikes.
End User:
Commuter segments generate predictable weekday demand patterns, while tourist and student constituencies concentrate ridership in narrow seasonal windows with divergent pricing sensitivity.
- Commuters:Daily work-trip users with multimodal transit integration requirements. Stockholm's rail-bike bundled passes demonstrate how commuter lock-in displaces private vehicle ownership across metropolitan corridors.
- Tourists:Short-duration visitors with high price elasticity and peak-season concentration. Copenhagen's waterfront tourism clusters drive weekend demand spikes that strain rebalancing algorithms.
- Students:University-affiliated riders with semester-based usage cycles. Helsinki City Bikes partners with Aalto University and University of Helsinki for campus-integrated access programs.
- Local Residents:Occasional users with erratic trip patterns and lower subscription conversion rates. Finnish secondary cities target this segment with flexible pay-per-ride structures.
Commuters deliver the highest lifetime value per account. Students are gaining share fastest through institutional partnership expansion.
Technology:
Backend system architectures differentiate vendor capabilities, with API interoperability emerging as a procurement gatekeeper for multimodal transit integration.
- Mobile App Integration:iOS and Android platforms with real-time fleet visibility and route planning. Smoove's municipal-focused interfaces prioritize transit authority control over consumer feature depth.
- GPS Tracking:Satellite-based location systems enabling theft recovery and demand heat mapping. Cold-weather battery performance in Finnish winter deployments constrains tracking refresh rates.
- Smart Locking:Bluetooth and cellular-enabled locks with automated rental termination. Oslo operators specify locks rated to minus twenty degrees Celsius after reliability failures in prior generation hardware.
- Payment Gateways:Integrated billing systems with municipal transit card compatibility. Danish Road Directorate mandates require PCI-DSS compliance for all fleet payment infrastructure.
Mobile App Integration commands the largest development budgets. Payment Gateway consolidation is climbing the fastest as transit authorities unify regional billing.
Pricing Model:
Revenue architecture separates occasional users from committed commuters, with hybrid structures emerging to capture both constituencies without cannibalization.
- Hourly Rates:Pay-per-minute or pay-per-hour structures for spontaneous trips. Tourist corridors in Bergen and Gothenburg rely on these rates to capture visitor revenue without subscription friction.
- Daily Passes:Twenty-four-hour unlimited access for short-stay visitors. Copenhagen's tourism board bundles these with hotel partnerships for seamless visitor onboarding.
- Monthly Subscriptions:Recurring flat-fee access with trip duration caps or unlimited usage. Stockholm's SL transit integration embeds bike sharing in regional mobility passes.
- Group Discounts:Corporate and institutional volume pricing for employee or student cohorts. Finnish universities negotiate semester-length group rates through centralized procurement.
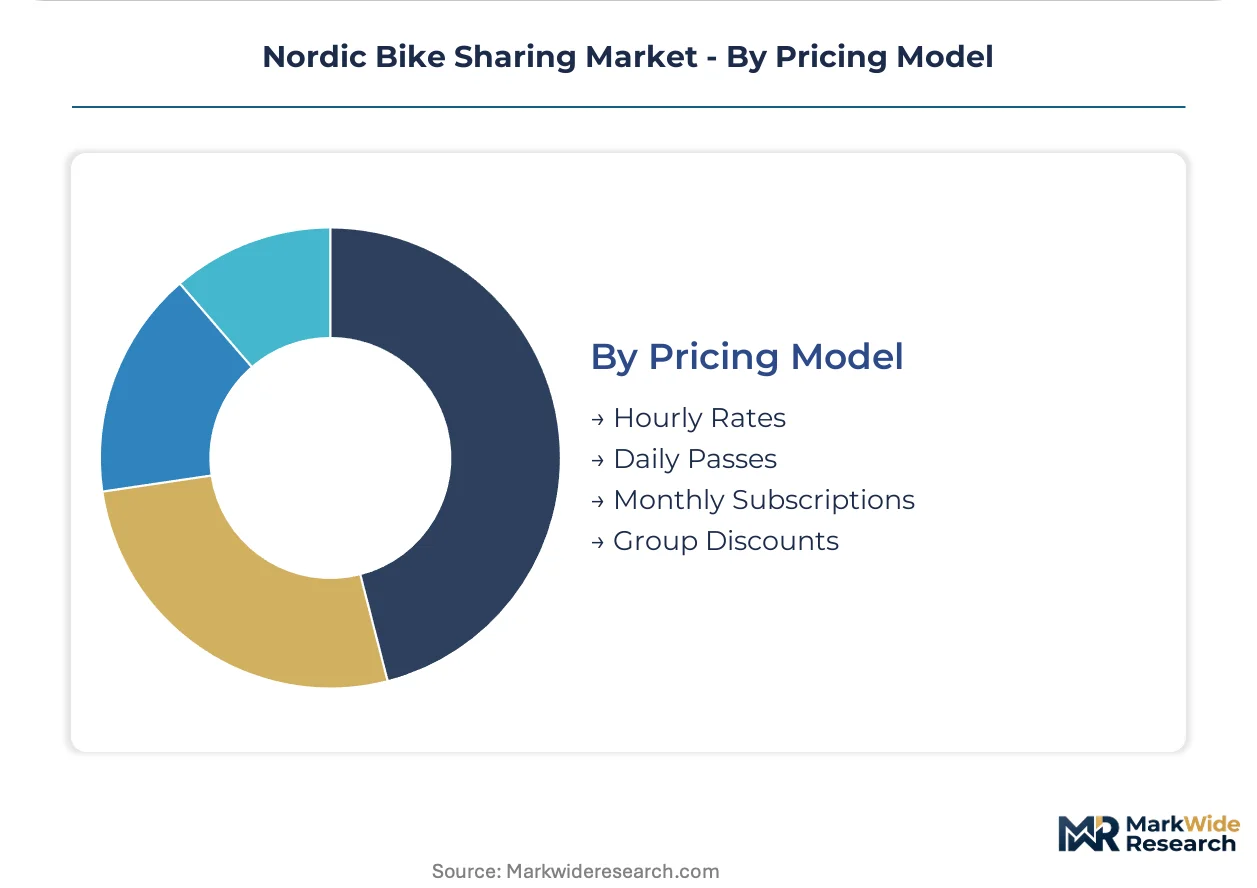
Monthly Subscriptions anchor the revenue base. Group Discounts are expanding most quickly through corporate sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copenhagen's metropolitan corridor anchors Nordic bike sharing deployment density, with procurement patterns radiating through Sweden, Norway, Denmark, and Finland under harmonized EU Green Deal transport mandates.
Denmark
Copenhagen's waterfront tourism clusters and Aarhus university corridors generate concentrated ridership demand. The Danish Road Directorate enforces rigorous hardware certification timelines that filter vendor market access. Bycyklen operates Copenhagen's station-based network while procurement authorities adopt Swedish winter durability protocols.
Sweden
Stockholm's rail-bike bundled passes and Malmö's cross-border commuter flows sustain weekday demand patterns. The Swedish Transport Administration mandates operational testing at minus fifteen degrees Celsius for all fleet hardware. Smoove anchors municipal contracts through dock-based infrastructure systems.
Norway
Oslo's electrified fleet mandates and Bergen's hilly topography accelerate e-bike procurement specifications. National carbon-neutral commitments prioritize minimum electrified fleet percentages in tender documents. Oslo City Bike dominates through seasonal subscription models with winter-summer pricing tiering.
Finland
Helsinki's mobile-first fleet management sustains ridership through extreme winter conditions while Tampere and Turku present first-mover expansion potential. The EU Green Deal's mobility targets reshape municipal procurement standards across secondary cities. Helsinki City Bikes partners with Aalto University for campus-integrated access programs.
Nordic Bike Sharing Market Competitive Landscape
Municipal contract consolidation dominates the current landscape across Nordic capitals. The vendor base organizes around three strategic archetypes: dock-based infrastructure specialists, seasonal subscription operators, and mobile-first fleet managers. Competitive positioning hinges on winter durability certifications and multimodal API interoperability rather than price undercutting.
Within the municipal-focused tier, Smoove exemplifies dock-based infrastructure anchoring, while Oslo City Bike and Helsinki City Bikes represent contrasting operational models for extreme-climate durability. These operators occupy positions shaped by national procurement cycles and EU Green Deal compliance requirements rather than direct consumer acquisition spending.
| Leading Market Players |
|---|
| Smoove |
| Malmö By Bike |
| Oslo City Bike |
| Saimaa Bikes |
| oBike |
| Helsinki City Bikes |
| Rekola |
| Bycyklen |
| Urban Sharing |
| Others |
Value Network & Pricing Analysis
Cold-weather lithium battery cells flow from East Asian manufacturing hubs through Nordic procurement channels, with cell chemistry grades separating premium e-bike fleet pricing from mechanical bicycle tiers downstream. Municipal tender documents in Denmark and Sweden translate battery durability certifications into contract award thresholds, compressing vendor margins on non-compliant hardware.
Pricing Analysis
Direct-to-municipal contracts bypass distributor markups entirely, concentrating price negotiation leverage with transit authority procurement officers. Three-tier pricing structure across premium e-bike, standard hybrid, and economy mechanical tiers reflects battery capacity and winter certification grade differentials. Pricing pressure stems from capital intensity of charging infrastructure deployment, squeezing operator margins on fixed-price seasonal subscriptions. Tourist segments exhibit highest price elasticity, while commuter bundled passes with rail networks demonstrate lowest sensitivity.
Supply Chain Analysis
Direct-to-operator channels handle fleet-scale procurement volumes for municipal contracts across Sweden, Norway, Denmark, and Finland. Battery cell manufacturing concentrates in China, South Korea, and Japan, with Nordic fleet operators drawing from concentrated East Asian supply bases. Lithium carbonate, nickel-manganese-cobalt cathodes, and cold-weather electrolyte formulations constitute critical input dependencies. Single-source vulnerability in cell chemistry suppliers exposes procurement to logistics volatility and trade friction. Distribution runs through specialized cold-chain logistics for battery transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as municipal procurement shifts toward electrified fleet mandates and winter durability certifications displace price-based vendor selection.
For Market Incumbents: Hedge against battery supply concentration by securing dual-source cell procurement agreements with South Korean and Japanese suppliers. Lock in long-term service contracts with Swedish Transport Administration and Danish Road Directorate certification timelines to delay entrant market access. Vertical integration into in-house motor development captures regenerative braking specification premiums in Oslo and Bergen tenders. For New Entrants and Emerging Players: Enter via Finland's secondary cities of Tampere and Turku, where integrated bike sharing networks remain underpenetrated and first-mover positioning is achievable. Target university partnership programs modeled on Helsinki City Bikes' Aalto University collaboration, leveraging semester-based institutional procurement cycles. Deploy mobile-first fleet management with API interoperability as the core go-to-market wedge against dock-based incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where municipal contract renewal cycles concentrate procurement volume with operators holding winter durability certifications and multimodal transit integration capabilities. Long-term viability favors vendors with in-house battery management system development and cold-climate engineering expertise over component assemblers. Monitor Swedish Transport Administration certification protocol adoption across Norwegian and Finnish procurement authorities as the inflection signal for harmonized Nordic hardware standards.| Strategic Initiative | Industry Significance |
|---|---|
| Winter Durability Certification Investment | Swedish Transport Administration minus-fifteen-degree testing mandates filter vendor market access. |
| Multimodal API Integration | Copenhagen transit authority payment gateway consolidation makes interoperability a procurement requirement. |
| Dual-Source Battery Procurement | East Asian cell supply concentration creates logistics vulnerability for Nordic fleet operators. |
| University Partnership Expansion | Helsinki City Bikes' Aalto University program demonstrates institutional subscriber acquisition models. |
| Regenerative Braking Specification | Oslo and Bergen tender documents favor vendors with in-house motor development capabilities. |
Research Methodology
Multiple input streams — municipal procurement database tracking, fleet operator financial disclosures, and regulatory filing analysis — were reconciled across primary interviews with transit authority procurement officers, fleet operations managers, battery system engineers, and municipal sustainability directors. Secondary validation drew from EU Green Deal transport target documentation, Swedish Transport Administration certification protocols, Danish Road Directorate safety specifications, and Nordic customs trade data. Bottom-up fleet deployment counts triangulated against top-down municipal mobility budget allocations.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, end-user category, technology tier, and pricing model, with additional weighting for winter operating condition severity across metropolitan corridors. CAGRs were derived from fleet replacement cycle analysis and electrification mandate compliance timelines. Battery chemistry advancement curves and multimodal transit integration adoption rates served as industry-specific forecast inputs.
The model holds under stable EU Green Deal transport target enforcement and continued national carbon-neutral commitment adherence; deviation in battery supply chain logistics or trade policy friction would shift fleet conversion timelines. Forecasts reflect documented assumptions on municipal procurement cycle duration and hardware certification timeline stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Indonesia Ride Hailing Market
Smart Transportation Solutions
Global Electric Public Transport Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
North America Traffic Signal Recognition Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
GCC Electronic Toll Collection Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Vehicle Parking Meter Market