
 5G in Automotive and Smart Transportation Market | 2026-2036
5G in Automotive and Smart Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
5G in Automotive and Smart Transportation Market Outlook
The gap between premium connected-vehicle platforms and commodity telematics hardware is repositioning how suppliers allocate engineering resources across the value chain. Qualcomm Technologies Inc. leverages its Snapdragon Automotive platform to dominate chipset supply for high-bandwidth cockpit systems. Robert Bosch GmbH anchors its position through in-house production of V2X roadside units and integrated antenna modules. Ericsson competes aggressively in network equipment, extending its 5G core contracts with European and Asian operators serving automotive clients.
5G in automotive and smart transportation denotes the integration of fifth-generation cellular networks into vehicle ecosystems, enabling ultra-reliable low-latency communication below ten milliseconds for safety-critical V2X exchanges. Its primary purpose centers on real-time data transmission supporting autonomous navigation, traffic orchestration, and predictive maintenance across moving vehicle fleets. NR (New Radio) infrastructure commands the largest capital commitment among technology segments due to dedicated spectrum requirements and base station densification needs. Edge Computing is gaining share fastest as OEMs and Fleet Operators push processing closer to vehicles to reduce backhaul dependency. Cloud-Based Solutions retain mature, stable margins in fleet analytics and over-the-air update management.
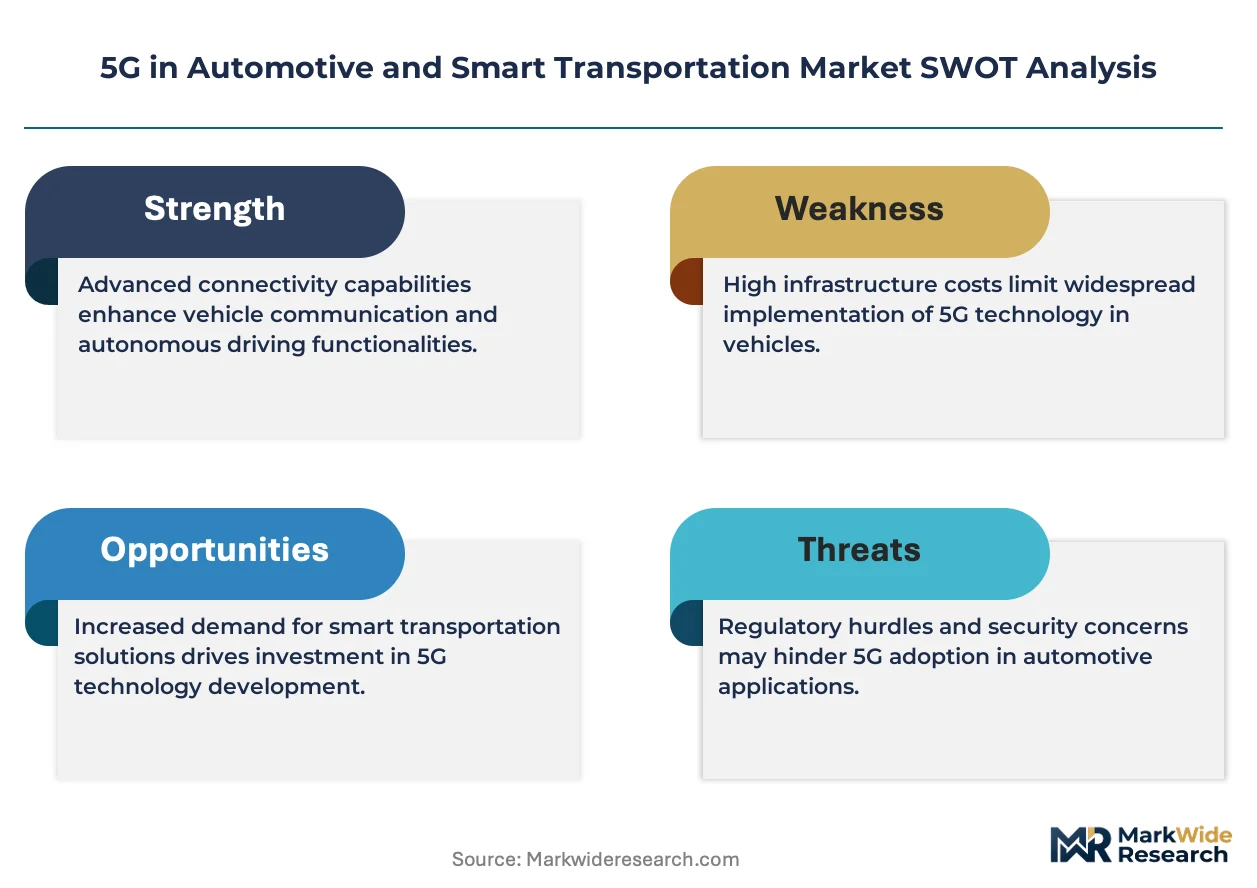
The FCC governs spectrum allocation for C-V2X deployment in the United States, while the EU AI Act and GDPR impose data governance frameworks on autonomous driving algorithms and passenger information flows. ETSI and 3GPP standards shape product certification timelines, forcing hardware vendors to synchronize roadmap compliance across multiple regulatory jurisdictions. Stakeholders must weigh spectrum harmonization risks against regional certification fragmentation when prioritizing R&D investment and partnership structures.
Market Dynamics
Spectrum harmonization pressure between the FCC's C-V2X allocation and the EU's 5.9 GHz framework is forcing chipset vendors to engineer multi-band modems before regional standards converge. This tension compresses R&D timelines while expanding validation costs for Tier-1 suppliers serving both markets.
Growth Catalysts
- EU AI Act compliance:Automotive OEMs in Germany accelerate V2X deployment to satisfy algorithmic transparency mandates for autonomous decision-making systems.
- Edge computing densification:Fleet operators install roadside units along highway corridors to achieve sub-ten-millisecond latency for collision avoidance protocols.
- Stuttgart-Munich corridor concentration:Engineering talent pools and testbed infrastructure in southern Germany attract supplier co-location investments.
Market Restraints
- Gallium nitride substrate costs:RF component fabrication depends on constrained wafer supply from specialty foundries in Taiwan and Japan.
- ETSI certification fragmentation:Hardware vendors face divergent testing protocols across EU member states that delay product launches.
- DSRC protocol substitution:Legacy dedicated short-range communication infrastructure in Japan and South Korea competes for spectrum and capital allocation.
Strategic Opportunities
- India PLI scheme:Component manufacturers qualify for production-linked incentives by establishing local 5G automotive module assembly.
- Telematics-as-a-service channels:Fleet management platforms bundle connectivity, analytics, and predictive maintenance through subscription models.
- Digital twin convergence:Automotive engineers combine 5G telemetry with simulation software to optimize vehicle performance before physical prototyping.
Industry Challenges
- Embedded systems integration:V2X modules must interface with legacy CAN bus architectures without compromising real-time safety guarantees.
- 3GPP Release 16 compliance:Engineers face compressed timelines to implement URLLC specifications before certification deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G in Automotive and Smart Transportation Market |
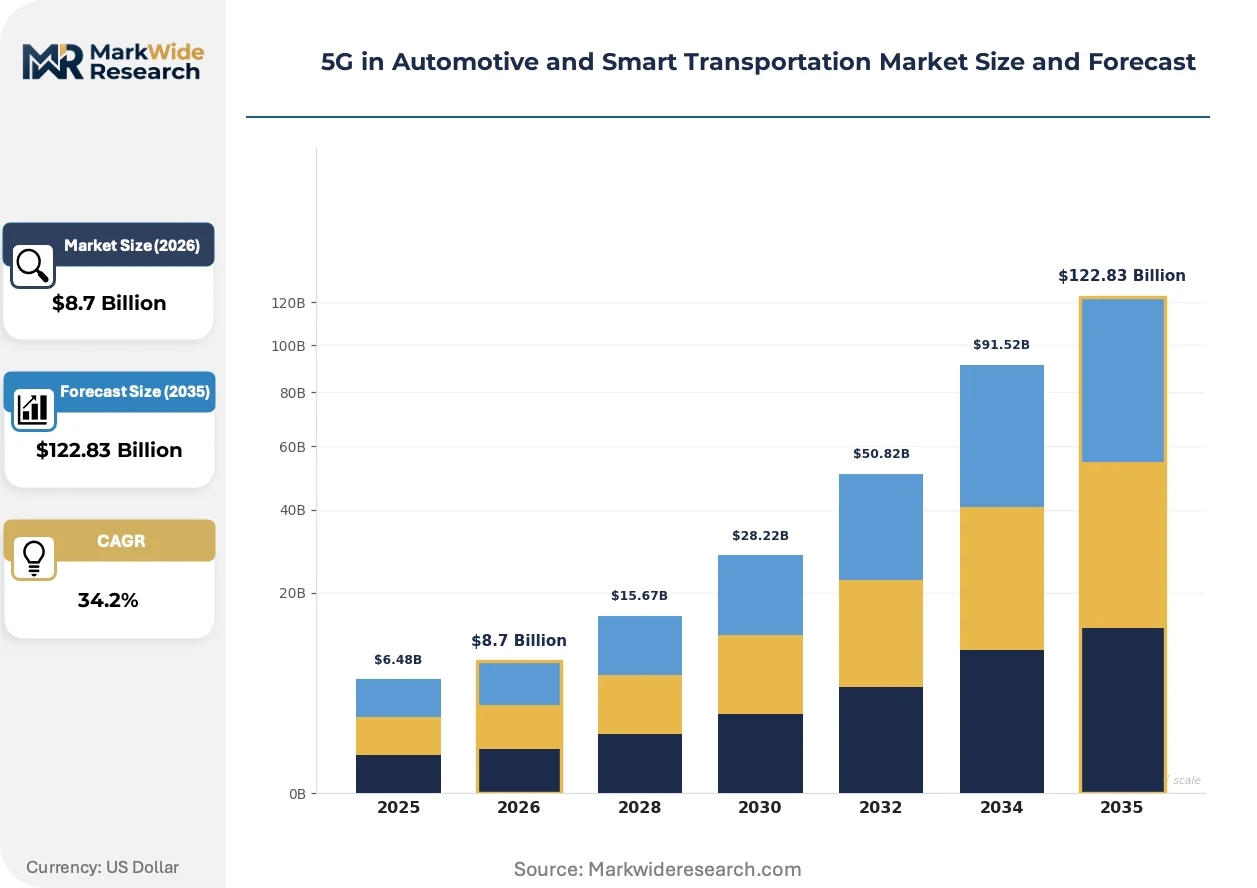
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Network Equipment, Telematics Devices, Connected Vehicles, V2X Communication Technology: NR (New Radio), Edge Computing, Network Slicing, Cloud-Based Solutions End User: OEMs, Fleet Operators, Public Transport Authorities, Ride-Sharing Services Application: Autonomous Driving, Traffic Management, Smart Parking, In-Vehicle Infotainment |
| Companies Covered | Qualcomm Technologies Inc., BMW Group, Robert Bosch GmbH, Vodafone Group, Huawei Device Co., Ericsson, Mercedes-Benz, Cisco Systems Inc., Nokia Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G in Automotive and Smart Transportation Market Strategic Shifts
Network slicing capabilities are separating safety-critical V2X traffic from infotainment data streams, enabling differential quality-of-service guarantees that reshape how automotive OEMs contract with mobile operators.
Cellular vehicle-to-everything technology is integrating direct device-to-device communication protocols that bypass base station routing for emergency braking alerts. German OEMs deploy C-V2X modems across premium vehicle lines this year. This architecture is integrating deterministic latency controls that compress reaction times below human perception thresholds.
The FCC's 2020 C-V2X spectrum reallocation forced equipment vendors to retool for 5.9 GHz operation while maintaining backward compatibility. Testing laboratories in Michigan and California face eighteen-month backlog queues. Suppliers now prioritize US-specific SKUs over unified global platforms to secure first-mover positioning.
Fleet procurement departments now mandate open API architectures that prevent vendor lock-in across telematics platforms. Third-party logistics providers in the US Midwest displace bundled hardware-software contracts with modular component sourcing. This behavior concentrates among refrigerated transport operators managing temperature-sensitive cargo monitoring.
5G in Automotive and Smart Transportation Market Segmentation
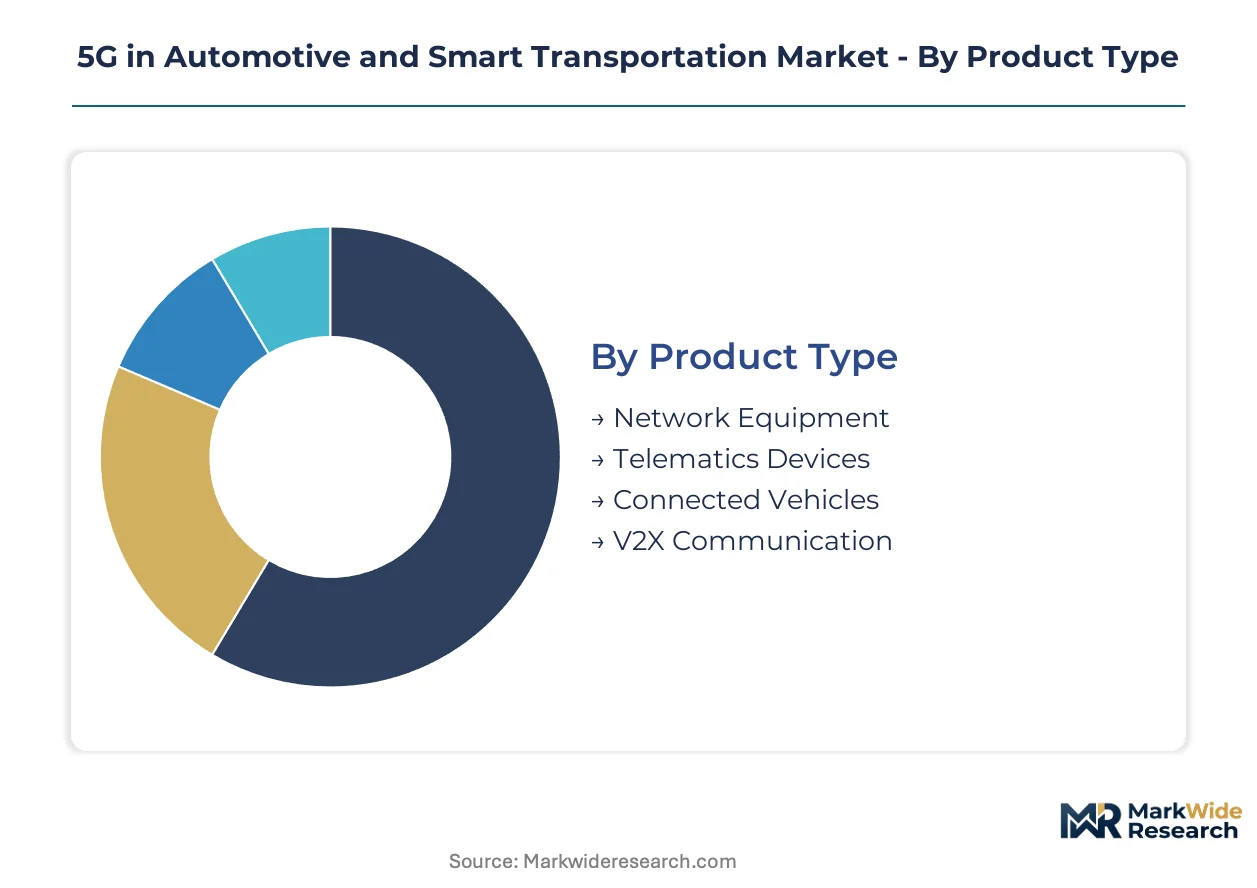
5G automotive deployments require distinct hardware-software combinations across the value chain, with each segment exhibiting different replacement cycles and integration complexity. Component suppliers must align roadmaps with divergent certification timelines and end-user procurement patterns.
Product Type:
Upgrade cycles vary dramatically across hardware categories, with infrastructure assets demanding decade-long depreciation schedules against consumer-facing devices turning every 3-4 years.
- Network Equipment:Base stations, small cells, and core network hardware form the physical layer enabling sub-ten-millisecond latency. Demand clusters along German autobahn corridors and Michigan testbed zones where public-private partnerships fund densification. FCC and EU spectrum auctions dictate procurement timing.
- Telematics Devices:Aftermarket and embedded modules transmit vehicle telemetry to fleet management platforms. Fleet operators in the US Midwest and refrigerated transport segments drive replacement demand as open API mandates displace bundled legacy contracts.
- Connected Vehicles:Factory-installed 5G modems integrate with cockpit systems and autonomous driving stacks. German OEMs in Stuttgart and Munich engineering corridors lead deployment volumes.
- V2X Communication:Roadside units and onboard units enable direct vehicle-to-infrastructure exchanges. ETSI certification requirements and 3GPP Release 16 compliance compress supplier validation timelines.
Volume placements concentrate in Network Equipment; the faster expansion belongs to Telematics Devices.
Technology:
Cost tiers separate capital-intensive physical infrastructure from software-defined layers that scale with marginal efficiency.
- NR (New Radio):The 5G physical layer standard specifies millimeter-wave and sub-6 GHz operation for automotive use cases. Base station densification requirements and dedicated spectrum allocations command the largest capital commitments across the technology stack.
- Edge Computing:Distributed processing nodes at roadside and network edge reduce backhaul dependency for safety-critical applications. OEMs and Fleet Operators push computing closer to vehicles to achieve deterministic latency for collision avoidance protocols.
- Network Slicing:Virtual network partitions isolate safety-critical V2X traffic from infotainment streams. Mobile operators in Germany and South Korea deploy slicing capabilities to support differential quality-of-service contracts with automotive clients.
- Cloud-Based Solutions:Centralized platforms manage fleet analytics, over-the-air updates, and predictive maintenance algorithms. Mature margins reflect standardized APIs and multi-tenant architectures serving dispersed vehicle populations.
Capital deployment runs heaviest through NR infrastructure; the steepest expansion trajectory belongs to Edge Computing.
End User:
Customer type determines procurement sophistication, with enterprise buyers demanding modular architectures against consumer-facing platforms prioritizing integration speed.
- OEMs:Vehicle manufacturers specify 5G modules for factory installation across premium and mass-market lines. German automotive engineering corridors concentrate supplier co-location investments to accelerate validation cycles.
- Fleet Operators:Commercial vehicle managers procure connectivity as operational infrastructure rather than consumer feature. Third-party logistics providers in refrigerated transport segments pioneer modular component sourcing to prevent vendor lock-in.
- Public Transport Authorities:Municipal and regional transit agencies deploy 5G for bus fleet monitoring and traffic signal prioritization. EU Green Deal funding and national decarbonization targets shape procurement timelines across member states.
- Ride-Sharing Services:Mobility platforms integrate 5G for real-time passenger matching, dynamic routing, and in-vehicle entertainment. Urban density and smartphone penetration determine addressable market scope.
Procurement volume aggregates through OEMs; the fastest share gains belong to Fleet Operators.
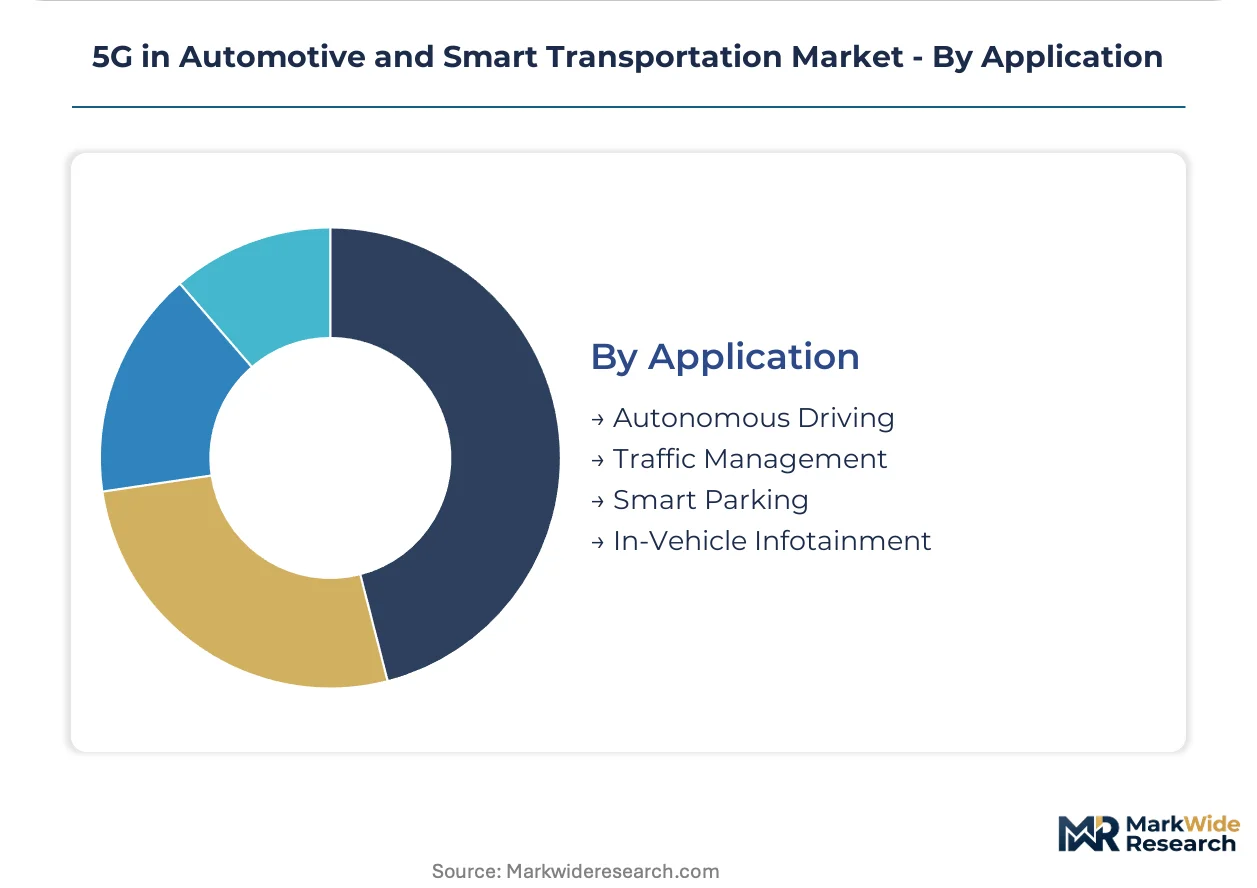
Application:
Maturity gradients separate safety-critical systems requiring deterministic performance from convenience features with tolerance for variable latency.
- Autonomous Driving:Self-navigation systems depend on V2X exchanges for hazard detection beyond sensor line-of-sight. EU AI Act algorithmic transparency mandates accelerate German OEM deployment timelines.
- Traffic Management:Municipal systems optimize signal timing and congestion flow through vehicle probe data. Public-private partnerships in Michigan and California fund corridor-scale deployments.
- Smart Parking:Sensor networks and vehicle-to-infrastructure communication reduce search time and emissions. Urban deployment concentrates in high-density European and Asian metropolitan cores.
- In-Vehicle Infotainment:High-bandwidth streaming and gaming services consume network capacity without safety-critical latency requirements. Snapdragon Automotive platforms dominate chipset supply for premium cockpit systems.
Development priority concentrates in Autonomous Driving; the broadest volume penetration belongs to In-Vehicle Infotainment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-Munich engineering corridor anchors 5G automotive deployment, concentrating testbed infrastructure and supplier R&D investments across southern Germany.
United States
Michigan and California testing laboratories face eighteen-month certification backlogs as FCC spectrum reallocation accelerates equipment retooling. The FCC's 2020 C-V2X framework governs 5.9 GHz deployment for vehicle-to-infrastructure communication. Public-private partnerships in Detroit-Warren corridor fund base station densification along interstate freight corridors.
Germany
Automotive OEMs accelerate V2X deployment to satisfy EU AI Act algorithmic transparency mandates for autonomous systems. The EU AI Act and GDPR impose data governance frameworks on passenger information flows and driving algorithms. Engineering talent pools around Stuttgart and Munich attract tier-one supplier co-location investments for validation cycles.
China
Domestic OEMs integrate C-V2X modems across mass-market electric vehicle platforms at scale. MIIT spectrum allocations and GB standards shape equipment certification timelines for roadside unit deployment. Yangtze River Delta manufacturing clusters concentrate module assembly capacity for export markets.
Japan
Legacy DSRC infrastructure competes with 5G V2X for spectrum allocation and capital commitment in urban traffic management. METI standards coordination influences regional adoption patterns for cellular vehicle-to-everything technology. Nagoya engineering corridors maintain supplier relationships with domestic tier-one electronics manufacturers.
South Korea
Mobile operators deploy network slicing capabilities to support differential quality-of-service contracts with automotive clients. MFDS and national digital infrastructure programs accelerate edge computing node installation along highway corridors. Seoul Capital Area concentrates R&D investment for millimeter-wave antenna module design.
5G in Automotive and Smart Transportation Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the 5G automotive value chain. The market exhibits tiered concentration: chipset vendors and network equipment manufacturers command consolidated positions, while telematics module suppliers fragment across price-competitive aftermarket segments. Three archetypes dominate: integrated platform providers, specialized RF component fabricators, and connectivity service bundlers. Strategic moves center on multi-band modem engineering for spectrum harmonization and roadside unit deployment partnerships with public transport authorities.
Within the integrated platform tier, Qualcomm Technologies Inc. and Robert Bosch GmbH occupy anchor positions representing divergent approaches to hardware-software integration. Ericsson exemplifies the network equipment archetype competing for 5G core contracts. These three entities sit within a competitive structure where geographic regulatory alignment determines partnership priority more than pure technology differentiation.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| BMW Group |
| Robert Bosch GmbH |
| Vodafone Group |
| Huawei Device Co. |
| Ericsson |
| Mercedes-Benz |
| Cisco Systems Inc. |
| Nokia Corporation |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent pools in Taiwan and Japan command wage premiums that widen spreads between premium V2X modules and commodity telematics hardware. Labor-cost differentials in these specialized foundry regions cascade into three-tier pricing structures across certification grades.
Pricing Analysis
Value-based pricing anchored to network uptime guarantees dominates 5G automotive contracts, with mobile operators charging premium rates for sub-ten-millisecond latency commitments. Price differentiation hinges on ETSI certification tier and volume scale, with fleet procurement departments driving standard-tier commoditization. Cost compression in entry-level telematics modules is intensifying because open API mandates displace bundled legacy contracts. Refrigerated transport operators exhibit highest price sensitivity; autonomous driving stack integrators show least.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific to European assembly plants shapes inventory positioning strategies for gallium nitride substrates and millimeter-wave antenna components. Supply concentrates in Taiwan, Japan, and South Korea for RF wafer fabrication; Germany and China for module integration. The chain draws from constrained specialty foundry capacity, ceramic substrate supply, and rare earth magnet sources. Single-source vulnerability in GaN substrate supply poses structural risk. Distribution runs through Tier-1 supplier direct contracts and aftermarket distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride wafer foundry capacity constraints prop pricing power for RF component vendors across the analysis window. Supply scarcity in substrate-grade material sustains margin premiums for qualified suppliers.
For Market Incumbents: Deploy multi-band modem engineering to neutralize spectrum harmonization risk between FCC and EU frameworks. Qualcomm Technologies Inc. and Robert Bosch GmbH should accelerate in-house production of V2X roadside units before certification deadlines compress. Lock long-term GaN substrate offtake with Taiwan foundries to defend against emerging RF specialists. For New Entrants and Emerging Players: India's PLI scheme opens a window for local 5G automotive module assembly targeting export markets. White-space exists in refrigerated transport telematics where open API mandates displace incumbent bundled contracts. Target aftermarket retrofit segments in US Midwest fleet operations with modular component sourcing models. For Investors and Strategic Acquirers: Re-rating potential sits with edge computing infrastructure specialists given OEM densification timelines for collision avoidance protocols. Long-term viability favors asset-light designers with 3GPP Release 16 compliance locked. Watch for ETSI certification backlog clearance as inflection signal for hardware vendor revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Band Modem Engineering | Enables single-SKU supply across FCC and EU spectrum allocations. |
| Roadside Unit Deployment Partnerships | Secures anchor tenant positioning with German autobahn public-private partnerships. |
| GaN Substrate Supply Agreement | Captures captive wafer capacity from Taiwan specialty foundries. |
| Edge Computing Node Installation | Supports sub-ten-millisecond latency guarantees for autonomous driving stacks. |
| Open API Architecture Certification | Unlocks fleet procurement contracts displacing bundled legacy vendors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet operations managers combined with FCC spectrum auction records, ETSI certification databases, and 3GPP release documentation. Bottom-up module shipment estimates triangulated against top-down infrastructure capex disclosures from mobile operators.
Shipment volume and value outputs reconcile across product type, technology layer, end-user archetype, and application maturity segments over the projection horizon. CAGRs derive from logistic curve modeling of V2X deployment penetration rates against regulatory milestone timing. Vehicle production forecasts from registration databases and edge computing node installation pipelines from public-private partnership announcements inform trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for DSRC-to-C-V2X substitution in Japan and South Korea would alter the outlook. Forecasts reflect assumptions around ETSI certification harmonization and GaN substrate supply expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Parking Space Management Market
Smart Transportation Solutions
Rail Internet of Things (IoT) Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global Parking Meter Apps Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Traffic Signal Controller Market