
 Long Haul Solutions Market | 2026-2036
Long Haul Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Long Haul Solutions Market Foresight
Software-defined fleet management is expanding the addressable revenue per vehicle beyond physical transport into predictive maintenance and dynamic routing subscriptions. Cisco Systems leverages its networking infrastructure to capture data-layer value across connected fleets. Nokia anchors European long-haul corridors with private wireless deployments for autonomous truck platooning. Corning Incorporated dominates fiber-optic cable supply for the backhaul networks that underpin real-time logistics visibility.
Long haul solutions encompass integrated systems for moving goods over distances exceeding 250 miles using heavy-duty vehicles, intermodal transfers, and digital coordination platforms operating across highway, rail, and port interfaces. Refrigerated vehicles command premium positioning due to pharmaceutical and perishable supply chain requirements, while telematics systems represent the fastest-growing technology dimension as mandates for electronic logging and fuel accountability harden. Freight transport maintains the largest revenue pool though logistics management software captures disproportionate margin expansion through SaaS economics and customer retention.
The EPA shapes vehicle emissions compliance timelines for US-based operators while the EU Green Deal and F-Gas Regulation constrain refrigerant choices for cross-border European cold-chain fleets. ELD mandates from the FMCSA and analogous HOS tracking requirements from Transport Canada force technology refresh cycles that benefit platform vendors. Stakeholders must weigh backward integration into proprietary fleet software against partnership models as regulatory fragmentation across North American and European jurisdictions complicates single-platform standardization.
Market Dynamics
Telematics-enabled fleet optimization is compressing operating margins for asset-heavy carriers while creating subscription revenue pools for platform vendors. The EPA's Phase 3 greenhouse gas standards force capital-intensive powertrain refreshes that favor scaled operators with balance-sheet capacity.
Growth Catalysts
- ELD Mandate Compliance:FMCSA electronic logging requirements drive replacement cycles for aging fleet management systems. Owner-operators and mid-size carriers upgrade hardware to avoid penalties.
- Cross-Border E-Commerce:Port-to-inland distribution lanes between Mexico and the United States require dedicated long-haul capacity with real-time visibility. Fulfillment networks consolidate freight onto integrated platforms.
- Refrigerated Pharmaceutical Logistics:Cold-chain integrity requirements for biologics and vaccines command premium per-mile rates. Specialized trailer fleets expand to serve temperature-sensitive healthcare distribution.
Market Restraints
- Diesel Price Volatility:Fuel represents the largest variable cost component for long-haul operators. Margin compression during price spikes limits fleet expansion capacity.
- Semiconductor Supply Concentration:Telematics control units and engine management systems depend on concentrated Asian foundry capacity. Production bottlenecks extend vehicle delivery timelines.
- Driver Availability Constraints:HOS regulations cap utilization hours per operator. Recruitment gaps in the United States and Canada restrict fleet growth regardless of equipment availability.
Strategic Opportunities
- Autonomous Platooning Corridors:Private wireless networks along designated freight routes enable reduced following distances and fuel savings. European operators pilot convoy systems on Rotterdam-Milan lanes.
- Predictive Maintenance Subscriptions:Sensor data monetization extends vendor relationships beyond hardware sales. Fleet managers pay for uptime guarantees rather than component replacements.
- Intermodal Optimization Software:Rail-highway coordination platforms reduce empty miles and detention penalties. Shippers in the United States prioritize seamless modal handoffs for transcontinental freight.
Industry Challenges
- Cybersecurity Certification Complexity:Connected vehicle platforms require ISO/SAE 21434 compliance for functional safety. Development timelines stretch as fleets validate over-the-air update protocols.
- Legacy System Integration Friction:Proprietary dispatch software resists API connectivity with modern telematics suites. Carriers face stranded asset risk from siloed data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long Haul Solutions Market |
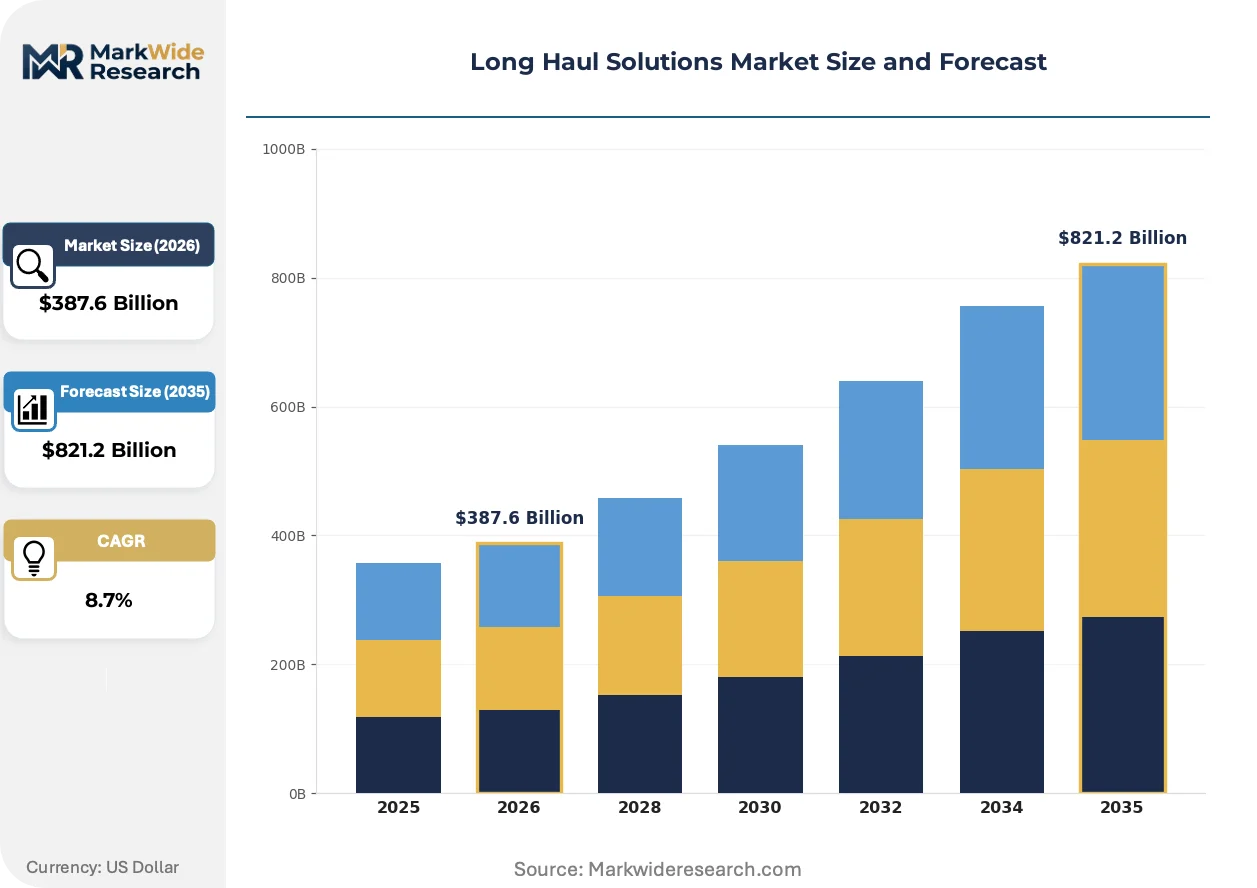
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Transport, Intermodal Services, Logistics Management, Supply Chain Solutions Vehicle Type: Tractor-Trailers, Flatbed Trucks, Refrigerated Vehicles, Tankers End User: Retailers, Manufacturers, E-commerce Businesses, Wholesale Distributors Technology: Telematics Systems, Fleet Management Software, Routing Software, ELD Systems |
| Companies Covered | Juniper Networks, OFS Fitel, Cisco Systems, Inc., IPG Photonics, Radiall, Corning Incorporated, Ceragon, CenturyLink, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long Haul Solutions Market Shifts & Advancements
Software-defined architectures are dissolving boundaries between vehicle hardware and logistics platforms. Real-time data streams now shape routing, maintenance, and compliance decisions that were previously batch-processed.
Unified fleet management platforms consolidate electronic logging, fuel optimization, and predictive maintenance into single dashboards. Large fleet operators in the United States and Canada are migrating from point solutions to integrated suites. This convergence is unifying procurement decisions around platform vendors rather than component suppliers.
The EU Green Deal and F-Gas Regulation restrict refrigerant choices for cross-border cold-chain operations. European carriers face accelerated retrofit timelines for refrigerated trailers using high-global-warming-potential coolants. Pharmaceutical and perishable shippers now specify compliant equipment in procurement contracts, forcing fleet-wide technology refreshes.
Shippers are consolidating freight procurement onto digital brokerage platforms that compress spot-market transaction cycles. Traditional freight forwarders lose volume to algorithmic matching engines that optimize for cost and transit time simultaneously. This behavior shift concentrates purchasing power among large retailers and manufacturers in the United States, squeezing intermediary margins.
Long Haul Solutions Market Segmentation
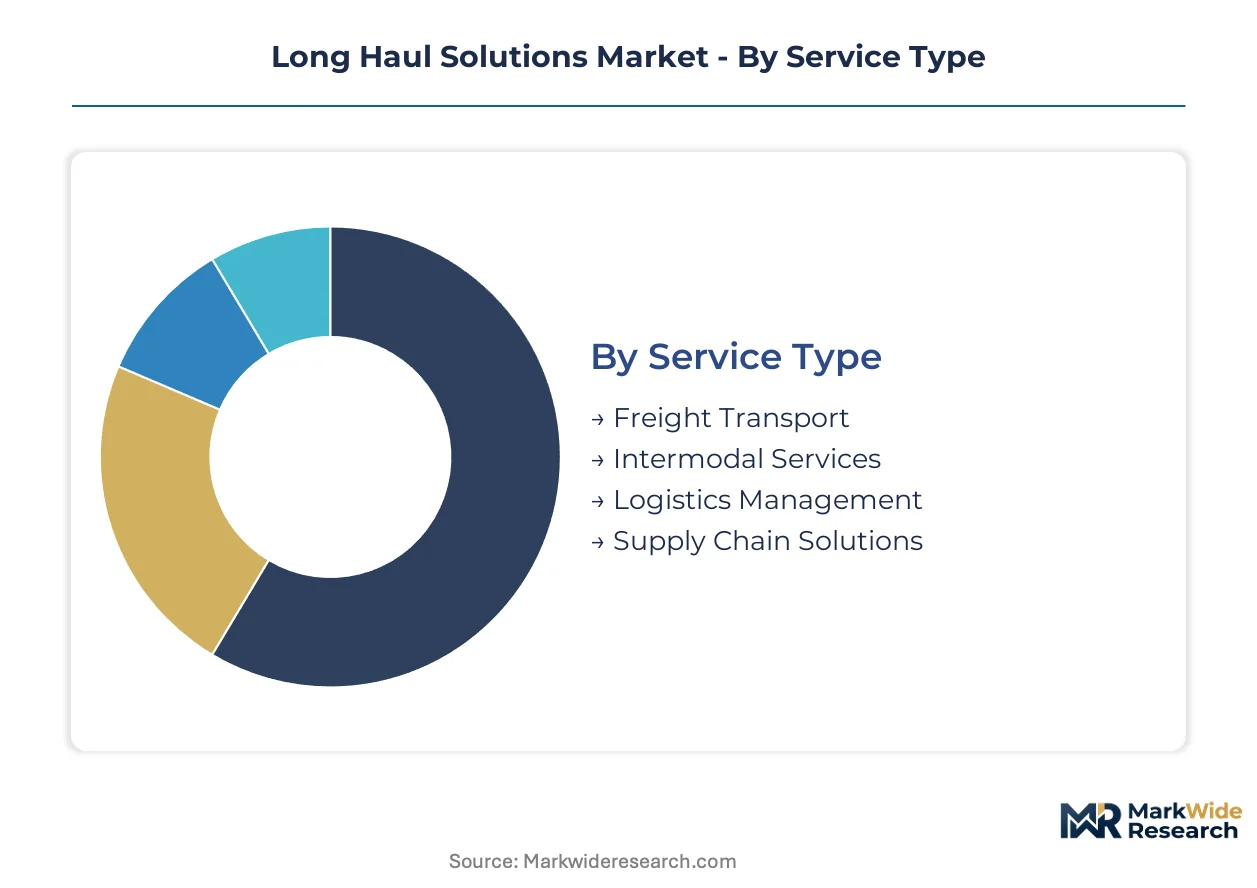
Long-haul operators structure procurement around vehicle capabilities, service integration depth, and compliance technology stacks. Segmentation reveals where capital flows concentrate and which technology layers command recurring revenue premiums.
Service Type:
Technology refresh cycles and ELD mandate enforcement are reshaping carrier procurement priorities across service categories.
- Freight Transport:Asset-heavy highway carriage of containerized and bulk cargo using owned or leased tractor-trailers. Demand concentrates among large retailers in the United States seeking dedicated lane capacity for port-to-inland distribution corridors.
- Intermodal Services:Rail-highway coordination platforms that transfer sealed containers between modes to extend reach beyond single-driver range. E-commerce fulfillment networks in the United States prioritize these services for transcontinental inventory positioning.
- Logistics Management:Third-party coordination of carrier procurement, load matching, and performance analytics.
- Supply Chain Solutions:End-to-end visibility platforms integrating warehousing, customs brokerage, and final-mile handoffs.
Volume placements concentrate in Freight Transport; the faster expansion belongs to Intermodal Services.
Vehicle Type:
Regulatory mandates and cargo-specific requirements create tiered investment cycles across fleet asset categories.
- Refrigerated Vehicles:Insulated trailers with integrated cooling units maintaining temperature bands for pharmaceuticals, fresh produce, and frozen goods. Pharmaceutical distributors in the United States specify EPA-compliant refrigerant systems to meet cold-chain integrity standards for biologics distribution.
- Tractor-Trailers:Standard dry van configurations dominating general freight volumes. Large fleet operators in the United States concentrate procurement here, though margin compression from fuel volatility limits expansion velocity.
- Flatbed Trucks:Open-deck configurations for oversized, construction, and industrial equipment cargo.
- Tankers:Specialized liquid and gas containment vessels with pressure-rated hulls for chemical and fuel transport.
Tractor-Trailers dominate fleet counts; Refrigerated Vehicles capture the steepest expansion trajectory from healthcare logistics requirements.
End User:
Customer scale and inventory velocity requirements determine technology sophistication and contract structure preferences.
- E-commerce Businesses:High-velocity shippers requiring real-time visibility and flexible capacity scaling for promotional surges. These operators in the United States consolidate freight onto digital brokerage platforms that compress spot-market transaction cycles.
- Manufacturers:Industrial shippers with predictable lane densities and just-in-time delivery constraints. Automotive and aerospace producers in the United States prioritize dedicated contract carriage with telematics-enabled ETA precision.
- Retailers:Omnichannel distributors balancing store replenishment with direct-to-consumer fulfillment.
- Wholesale Distributors:Intermediate inventory holders serving fragmented downstream customer bases.
E-commerce Businesses drive platform subscription adoption; Manufacturers anchor long-term contract volumes.
Technology:
Compliance deadlines and connectivity requirements force synchronized upgrade decisions across fleet technology stacks.
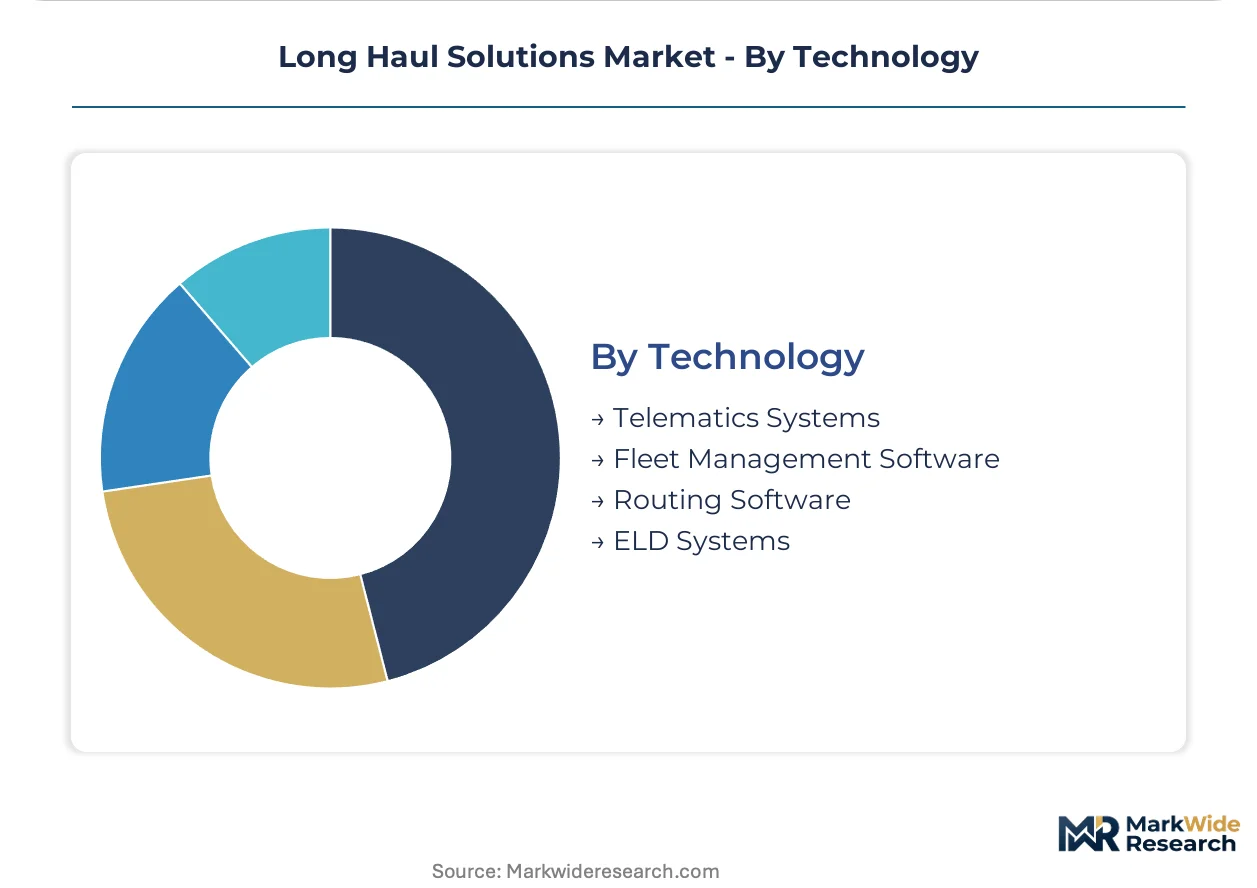
- Telematics Systems:Sensor networks capturing vehicle location, engine diagnostics, driver behavior, and cargo condition in real time. Fleet operators in the United States deploy these systems to satisfy FMCSA ELD mandates and optimize fuel consumption across highway corridors.
- Fleet Management Software:Unified dashboards consolidating dispatch, maintenance scheduling, and regulatory reporting. Large carriers in the United States migrate from point solutions to integrated suites that unify procurement around platform vendors.
- Routing Software:Algorithmic optimization of path selection, stop sequencing, and dwell time minimization.
- ELD Systems:Dedicated hours-of-service recording devices satisfying FMCSA electronic logging requirements.
ELD Systems command mandatory replacement volumes; Telematics Systems are expanding most quickly through predictive maintenance monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the dominant share of long-haul solutions capacity while manufacturing concentrates among specialized component fabricators in Germany, China, and Japan. Production geography diverges sharply from deployment patterns.
United States
Cross-border freight corridors with Mexico and port-to-inland distribution lanes drive telematics adoption among fleet operators. The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles mandate powertrain refreshes that favor scaled carriers with capital reserves. The Dallas-Fort Worth metroplex anchors national freight consolidation with major distribution centers deploying integrated fleet management platforms.
Germany
Autonomous truck platooning pilots along Rotterdam-Milan freight corridors accelerate private wireless network deployments. The EU Green Deal and F-Gas Regulation constrain refrigerant choices for cold-chain fleets serving pharmaceutical distribution. The Rhine-Ruhr industrial cluster hosts concentrated logistics technology development for cross-border European operations.
China
Domestic e-commerce fulfillment networks expand dedicated long-haul capacity for intercity parcel distribution. MIIT connectivity mandates for commercial vehicles accelerate telematics hardware refresh cycles. The Yangtze River Delta manufacturing belt supplies telematics control units and sensor assemblies for regional fleet operators.
Japan
Automotive and electronics manufacturers demand precision ETA capabilities for just-in-time component delivery. METI standards for commercial vehicle emissions shape fleet replacement timelines. The Chubu region around Nagoya anchors specialized refrigerated vehicle production for pharmaceutical cold-chain applications.
Canada
Transport Canada hours-of-service tracking requirements mirror FMCSA mandates, forcing technology upgrades among cross-border operators. Driver availability constraints in prairie provinces limit fleet expansion regardless of equipment procurement. The Greater Toronto Area concentrates logistics management platform adoption for US-Canada freight corridors.
Long Haul Solutions Market Competitive Landscape
Top-tier vendors anchor integrated platform provision, while specialized component suppliers occupy niche technology layers. Market structure tilts toward consolidation around networking infrastructure and telematics hardware, with fragmented point-solution vendors facing margin pressure. Three archetypes dominate: networking giants extending into fleet data layers, optical component specialists capturing backhaul connectivity value, and telecommunications equipment providers enabling autonomous corridor infrastructure. Competitive moves center on strategic partnerships for private wireless deployments and backward integration into predictive maintenance software.
Within the networking infrastructure tier, Cisco Systems and Nokia occupy positions exemplifying platform-scale leverage over fleet data monetization. Corning Incorporated anchors the optical fiber supply chain that underpins real-time logistics visibility across highway corridors. These three entities represent distinct strategic postures: software-defined fleet management extension, private wireless corridor enablement, and physical layer connectivity dominance.
| Leading Market Players |
|---|
| Juniper Networks |
| OFS Fitel |
| Cisco Systems, Inc. |
| IPG Photonics |
| Radiall |
| Corning Incorporated |
| Ceragon |
| CenturyLink |
| Nokia |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up fleet management specialists now control substantial telematics platform capacity, concentrating procurement leverage and enforcing disciplined subscription pricing across North American and European carrier bases. This ownership consolidation tightens vendor margins while redirecting capital toward software-layer acquisitions rather than hardware expansion.
Pricing Analysis
Margin tightening in telematics hardware reflects semiconductor foundry bottlenecks concentrated in Taiwan and South Korea. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade—FMCSA ELD compliance tiers command 15-25% premiums over baseline logging devices. Cost-down pressure on integrated fleet suites accelerates because large US retailers consolidate procurement onto unified platforms. Owner-operators exhibit highest price sensitivity, deferring upgrades until mandate deadlines force compliance expenditures.
Supply Chain Analysis
Domestic-content mandates under the US CHIPS and Science Act are reshaping sourcing patterns for telematics control units, pressuring vendors to qualify alternative foundry capacity. Component supply concentrates in China, Taiwan, and Malaysia for sensor assemblies and semiconductor packaging. Production rests on concentrated rare-earth magnet supply for electric powertrain motors and specialized refrigerant gases for European cold-chain trailers. Single-source vulnerability in Asian foundry capacity presents structural risk. Distribution runs through OEM vehicle integration channels and aftermarket retrofit networks serving mid-size carrier fleets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Long Haul Solutions Market functions as a cost-of-compliance story where EPA Phase 3 greenhouse gas standards and FMCSA ELD mandates erect barrier-to-entry moats favoring scaled platform vendors with certification resources and balance-sheet capacity for powertrain refreshes.
For Market Incumbents: Cement platform dominance by acquiring predictive maintenance software specialists before subscription revenue pools consolidate further. Defend against autonomous platooning disruptors by securing exclusive private wireless corridor partnerships with Nokia and Cisco Systems along Rotterdam-Milan and US Interstate freight lanes. Backward integration into refrigerant system manufacturing insulates margin from EU F-Gas Regulation supply constraints. For New Entrants and Emerging Players: Capture white-space in mid-size Canadian carrier fleets where Transport Canada HOS mandates force technology upgrades without incumbent platform lock-in. Target intermodal optimization software for US rail-highway coordination, where legacy dispatch systems resist API connectivity and create stranded asset vulnerability. Lead with outcome-based uptime guarantees rather than hardware sales to bypass capital-constrained procurement committees. For Investors and Strategic Acquirers: FMCSA enforcement actions against non-compliant ELD installations are the leading indicator that replacement cycle volumes will concentrate among vendors with certified platform scale. Long-term viability favors telematics providers with SaaS economics and customer retention above 85% annually. Acquisition targets should display proprietary sensor data architectures and established API ecosystems. Watch for EPA Phase 3 compliance timeline acceleration as the signal for powertrain refresh capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Private Wireless Corridor Deployment | Nokia's Rotterdam-Milan pilot enables autonomous platooning fuel savings for European freight operators. |
| Predictive Maintenance Platform Acquisition | Sensor data monetization extends vendor relationships beyond hardware into recurring subscription revenue. |
| Refrigerant System Backward Integration | EU F-Gas Regulation compliance insulates cold-chain fleets from retrofit cost volatility and supply disruption. |
| Intermodal Software API Development | Seamless rail-highway handoffs reduce empty miles for US transcontinental e-commerce fulfillment networks. |
| ELD Certification Investment | FMCSA mandate enforcement concentrates procurement among vendors with validated compliance architectures. |
Research Methodology
Multi-period observation of fleet technology refresh cycles, ELD mandate compliance rates, and telematics platform subscription metrics anchored the trend analysis, supplemented by interviews with fleet operations directors, telematics platform engineers, refrigerated trailer procurement managers, and cross-border logistics coordinators. Secondary validation drew from FMCSA enforcement databases, EPA heavy-duty vehicle certification filings, EU transport emissions registries, and customs trade data for telematics hardware imports. Bottom-up carrier spend analysis and top-down market sizing triangulated volume estimates.
Input-output matrices modeled vehicle-type deployment across service categories, technology-stack penetration by fleet size tier, and regional regulatory cluster adoption patterns. Segmentation dimensions included vehicle capability class, integration depth, compliance technology tier, and end-user inventory velocity requirements. CAGRs were derived from trend-line extrapolation of replacement cycle timing and mandate enforcement trajectories. Forecast inputs incorporated diesel price volatility scenarios and semiconductor supply normalization assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to autonomous vehicle regulatory approval timelines and alternative fuel infrastructure buildout pace. Projections reflect assumptions around ELD mandate continuity and EPA enforcement intensity that regulatory shifts could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Shared Vehicles Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market