
 Europe Hyperloop Technology Market | 2026-2036
Europe Hyperloop Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hyperloop Technology Market Intelligence
The European Green Deal's mandate for carbon-neutral mobility is decoupling regional economic activity from transport-related emissions, creating a structural tailwind for hyperloop development. Hardt B.V. leverages its European Hyperloop Center in the Netherlands to advance system testing and standardization. Hyperloop Transportation Technologies specializes in forging public-private partnerships across Italy and other member states. Meanwhile, Transpod Inc. differentiates its system for both passenger and cargo transport capabilities, targeting key logistics corridors.
Hyperloop technology encompasses a system of pods or capsules traveling at high speeds through low-pressure tubes. It primarily utilizes magnetic levitation and electromagnetic propulsion to minimize friction, enabling near-supersonic travel for passengers and cargo. Foundational technologies like Magnetic Levitation and Linear Induction Motors define system performance and cost structures. While long-distance Passenger Transport represents the ultimate vision, near-term commercialization focuses on high-value Goods Delivery applications connecting major economic hubs.
A unified regulatory framework for hyperloop systems remains in development, guided by the European Commission. Component and system safety will fall under standards like CE marking, ensuring interoperability and public trust. The EU Green Deal provides the overarching policy direction, influencing funding and political support. Stakeholder success depends on achieving cross-border regulatory harmonization to enable the construction of pan-European corridors.
Market Dynamics
The primary structural force shaping the Europe hyperloop technology market is the policy-driven mandate for sustainable transport. The European Green Deal creates a powerful tailwind, aligning massive infrastructure investment with decarbonization goals and pushing hyperloop from concept to viable alternative.
Growth Catalysts
- Sustainable Mobility Mandates:The European Green Deal's objective of a 90% reduction in transport-related emissions provides a strong policy incentive for member states to invest in and support zero-direct-emission transport technologies like hyperloop.
- Logistics and Freight Demand:Growing demand from Europe's logistics sector for faster and more reliable connections between major economic hubs, such as the port of Rotterdam and industrial centers in Germany, stimulates investment in cargo-focused hyperloop systems.
- Technology Maturation:Advances in magnetic levitation and linear induction motor technologies are improving system efficiency and reducing projected operational costs, making the business case for hyperloop more compelling for passenger and freight applications.
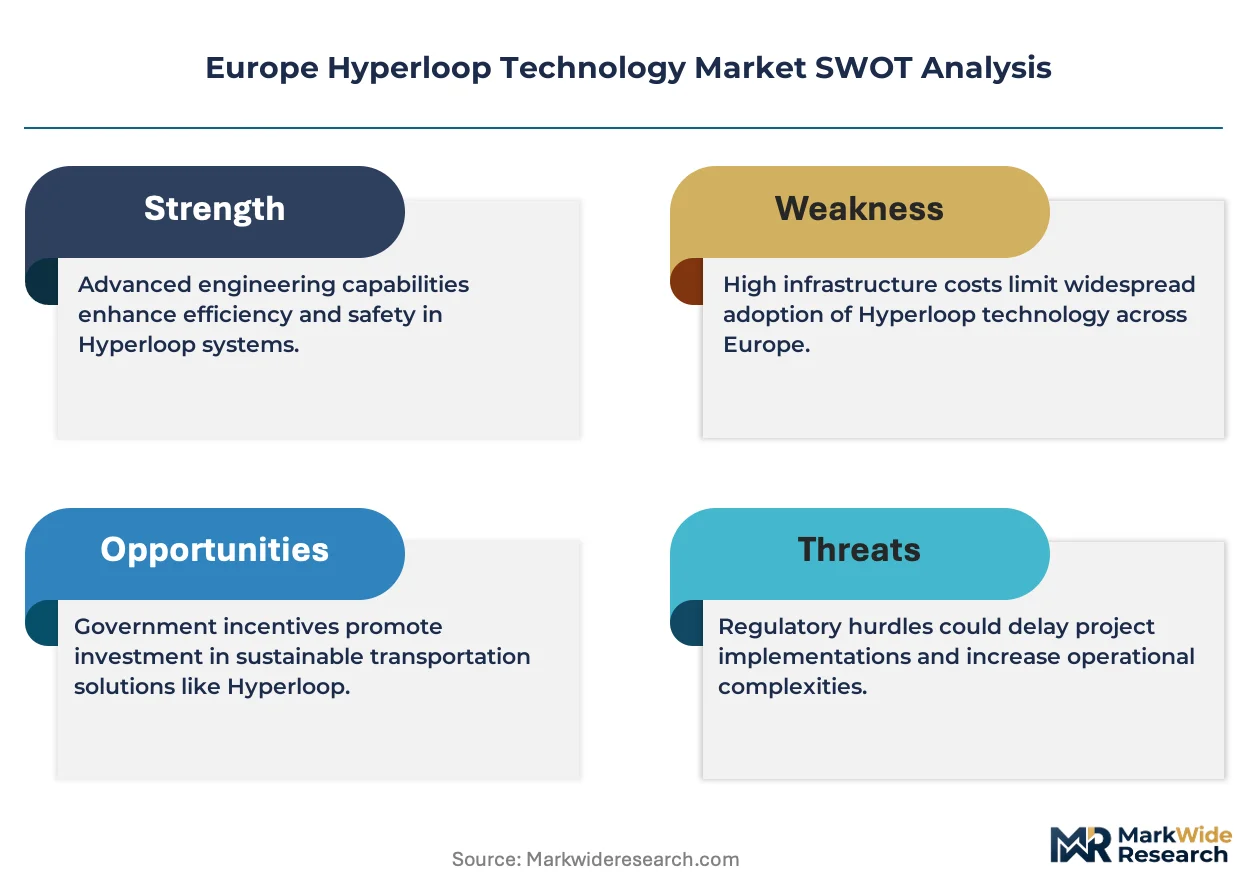
Market Restraints
- High Capital Expenditure:The immense upfront cost associated with land acquisition, vacuum tube construction, and station development represents a significant financial barrier, limiting projects to those with substantial government or consortium backing.
- Regulatory Fragmentation:The absence of a harmonized, pan-European regulatory framework for safety, certification, and cross-border operations creates uncertainty and delays the development of international corridors.
- High-Speed Rail Competition:Europe's extensive and well-established high-speed rail network presents a formidable substitution threat, offering a proven, lower-risk, and already-integrated alternative for intercity passenger transport.
Strategic Opportunities
- Dedicated Cargo Corridors:Developing freight-only hyperloop lines to connect major ports, airports, and inland logistics hubs offers a near-term commercialization path by targeting high-value, time-sensitive goods delivery without complex passenger safety regulations.
- Energy System Integration:The opportunity exists to integrate hyperloop infrastructure with renewable energy sources, such as solar panels along the tube length, creating self-sufficient transport networks that can even supply surplus energy back to the grid.
- Eastern Europe Infrastructure Modernization:Underpenetrated markets in Eastern Europe present a significant opportunity, where hyperloop can be positioned as a leapfrog technology to build modern, high-speed transport links and enhance economic integration with the rest of the EU.
Industry Challenges
- Interoperability and Standardization:Achieving consensus among competing technology developers on common standards for pods, tubes, and communication systems is a major operational hurdle for creating a truly interoperable pan-European network.
- Complex Land Acquisition:Securing contiguous, straight-line land rights for corridors spanning hundreds of kilometers across multiple countries, regions, and private properties involves complex legal and political negotiations that can stall projects indefinitely.
- Specialized Talent Scarcity:A shortage of engineers and technicians with expertise in niche fields like vacuum engineering, magnetic propulsion systems, and high-speed control systems poses a challenge to system development and maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hyperloop Technology Market |
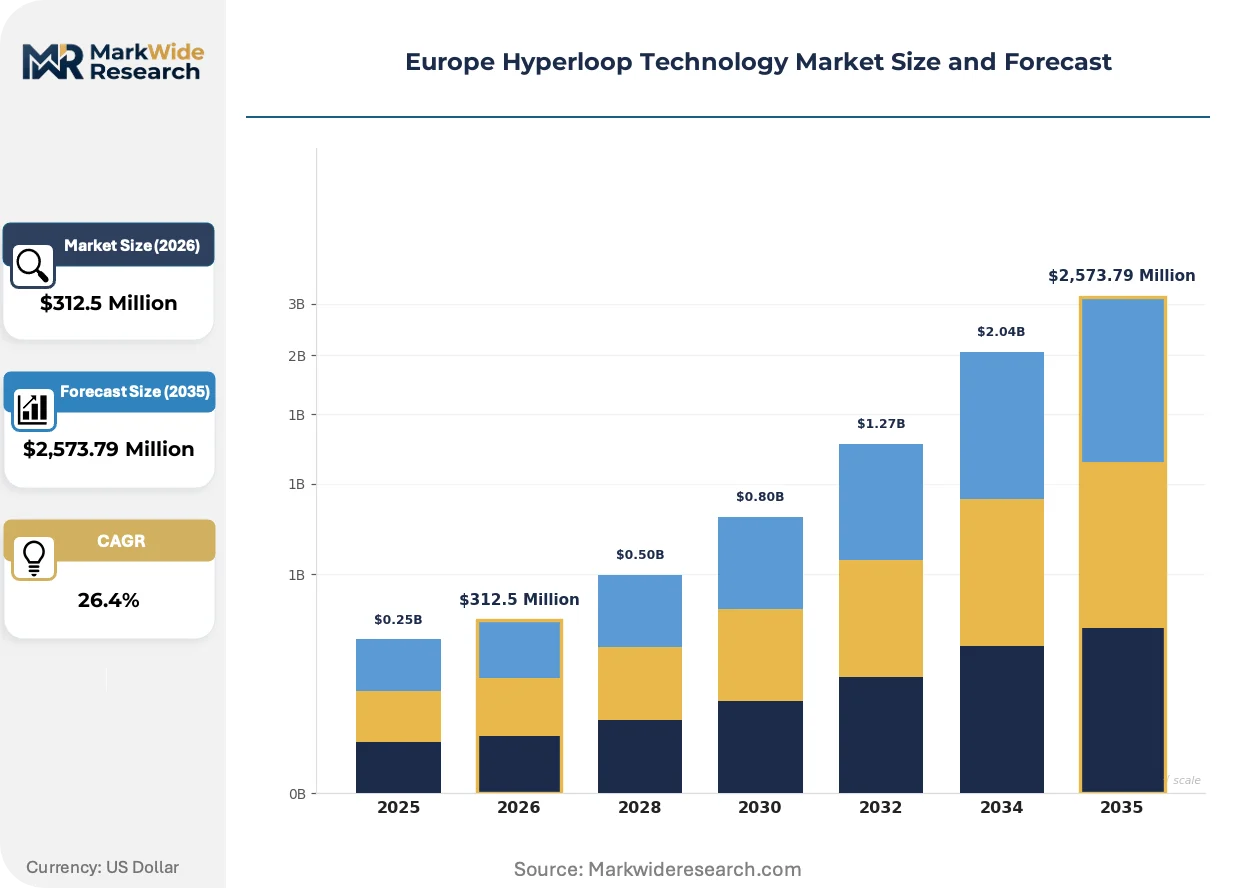
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,573.79 Million |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Levitation System, Propulsion System, Vacuum Technology, Control System, Safety System Technology: Magnetic Levitation, Electromagnetic Propulsion, Low-Pressure Tube, Linear Induction Motor Application: Passenger Transport, Goods Delivery, Emergency Services, Tourism, Data Transfer End User: Transport Operators, Logistics Providers, Infrastructure Developers, Research Organizations |
| Companies Covered | Hardt B.V., Hyperloop Transportation Technologies, Transpod Inc., AECOM, Space Exploration Technologies Corp, Dinclix Groundworks, Delft Hyperloop, TUM Hyperloop, Nevomo Poland, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hyperloop Technology Market Strategic Shifts & Innovations
The market is shifting from theoretical exploration to tangible engineering and regulatory groundwork. This transition is defined by the development of modular components, the formation of a unified regulatory path, and the evolution of project financing models away from pure speculation.
Modular component design for propulsion systems and tube sections allows for more scalable and phased project construction. Infrastructure developers and public-private partnerships across Europe are adopting this approach to manage financial risk and accelerate testing. This modularity is decentralizing system development, steering the industry away from monolithic, proprietary architectures toward a more open and interoperable component ecosystem.
The European Commission is spearheading the creation of a common regulatory framework to govern hyperloop safety and technical specifications. This initiative aims to resolve the legal and operational fragmentation hindering the approval of cross-border routes. Passenger transport systems are most impacted, as their deployment depends on achieving stringent certifications like CE marking to ensure public safety and secure operational licenses.
A definitive shift toward public-private partnership (PPP) models is defining how new projects are financed and executed. These blended financing structures, which combine government backing with private capital, are replacing purely speculative venture funding for large-scale infrastructure. This trend is most prominent in nations like Italy and the Netherlands, where governments are actively co-funding test centers and feasibility studies with technology developers.
Europe Hyperloop Technology Market Segmentation
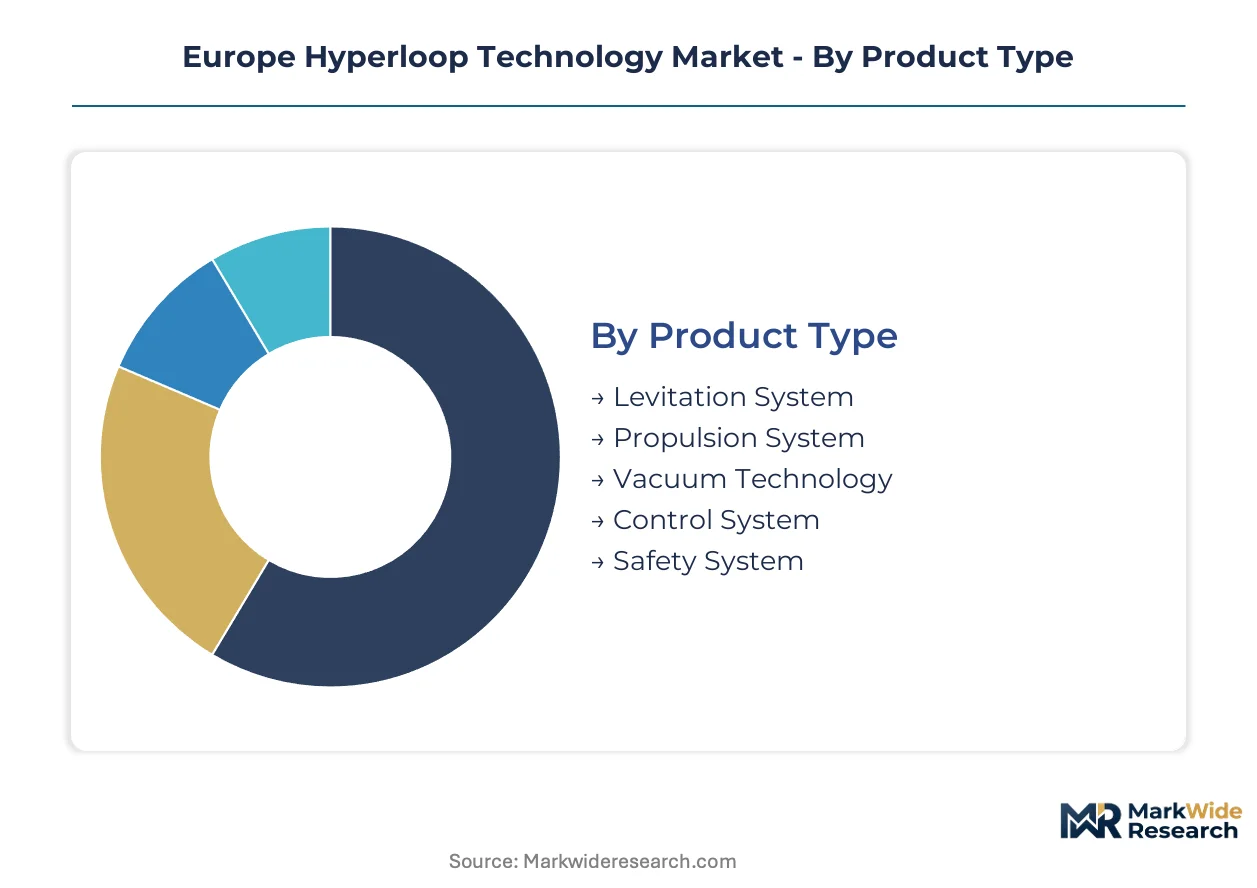
The Europe hyperloop technology market segmentation reveals the intricate components, underlying technologies, diverse applications, and key end-users shaping this nascent industry. Understanding these segments is critical for stakeholders to navigate regulatory pathways, prioritize investment, and align development efforts with the evolving demands of European transport infrastructure.
Product Type:
Segments within product type face varying certification burdens, with safety-critical components requiring stringent CE marking and operational approvals from the European Commission.
- Safety System:This segment includes emergency braking, evacuation mechanisms, and structural integrity monitoring, all vital for public and operational trust. Demand concentrates in the Netherlands and Spain, driven by active test centers and the need to meet rigorous EU safety standards.
- Propulsion System:These systems, primarily electromagnetic, provide the thrust for pods within the low-pressure tubes, dictating speed and energy efficiency. Demand is high in Germany and France, where engineering expertise and government interest in high-speed transport drive development.
- Levitation System:This technology keeps the hyperloop pod suspended, eliminating friction and enabling high speeds.
- Vacuum Technology:This segment includes pumps and seals creating and maintaining the near-vacuum environment within the tubes.
- Control System:These systems manage pod movement, scheduling, and overall network operations.
Leading the category by volume: Propulsion System. Growing fastest: Safety System.
Technology:
The application focus for each technology varies significantly, from core propulsion to infrastructure design, influencing their commercialization timelines and integration into broader transport networks.
- Magnetic Levitation:This foundational technology utilizes magnetic forces to lift and guide hyperloop pods, reducing physical contact and friction. This technology is critical for achieving near-supersonic speeds in passenger and cargo applications across Europe.
- Linear Induction Motor:These motors provide the primary propulsion for hyperloop pods, converting electrical energy directly into linear motion without rotating parts. They are essential for accelerating and decelerating pods efficiently, particularly in high-speed freight corridors.
- Electromagnetic Propulsion:This refers to the broader principle of using electromagnetic forces for movement, encompassing both levitation and linear motor functions.
- Low-Pressure Tube:These sealed, evacuated tubes form the physical infrastructure through which hyperloop pods travel.
Key technologies underpinning system performance include Magnetic Levitation and Linear Induction Motor.
Application:
The maturity of various hyperloop applications ranges from aspirational long-term visions to more immediate commercialization targets, reflecting differing technological readiness levels and regulatory complexities.
- Goods Delivery:This application focuses on high-speed, high-value cargo transport between major economic hubs like Rotterdam and industrial centers. Near-term commercialization efforts prioritize goods delivery due to less stringent human safety regulations compared to passenger transport.
- Passenger Transport:This ultimate vision involves carrying people at near-supersonic speeds over long distances, offering a new alternative to air and high-speed rail. This application requires extensive safety certifications and public acceptance for widespread deployment across European countries.
- Emergency Services:Hyperloop systems could transport emergency personnel or critical supplies rapidly across regions.
- Tourism:This application involves hyperloop routes connecting popular tourist destinations.
- Data Transfer:Hyperloop tubes could potentially house high-speed data cables, offering secure and rapid information exchange.
The market's immediate focus centers on Goods Delivery, while Passenger Transport represents a long-term vision.
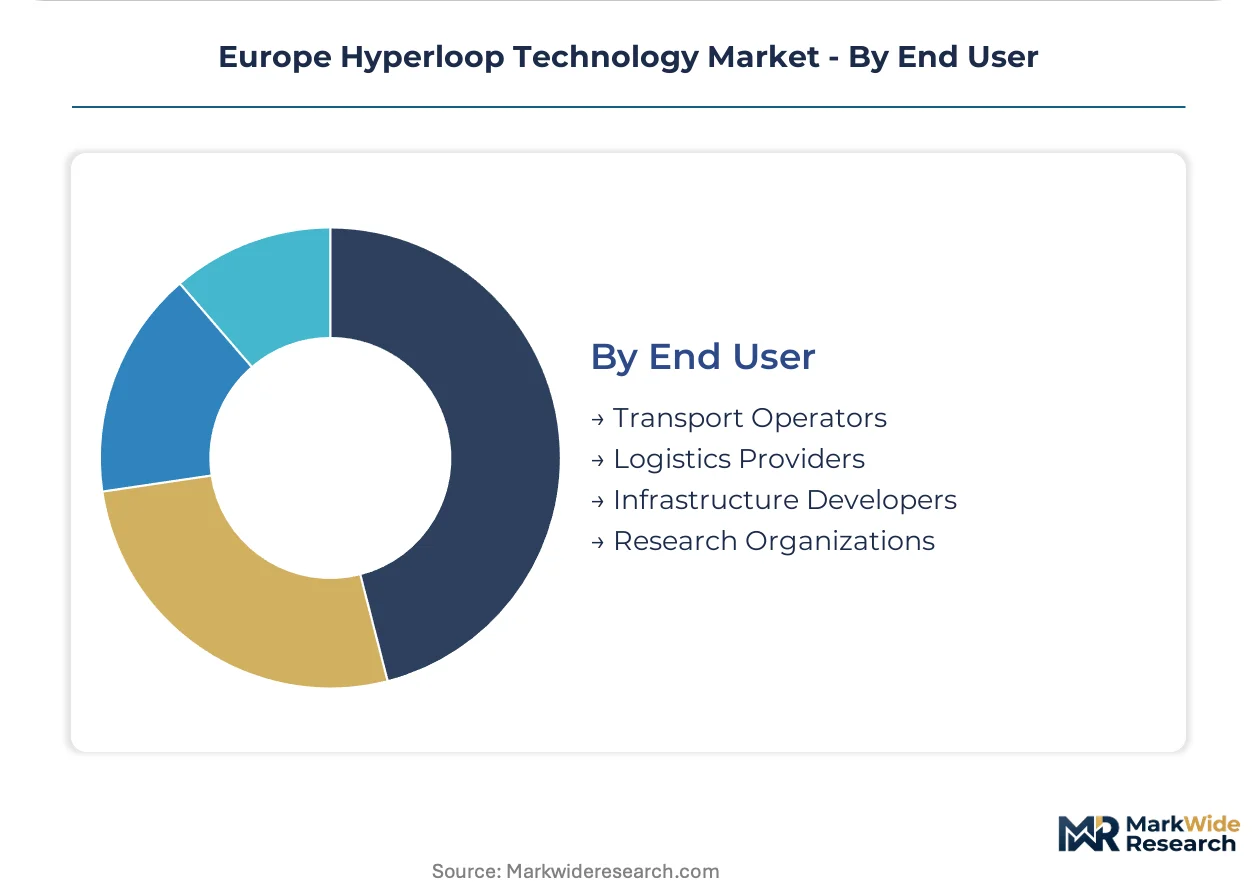
End User:
Supply concentration for hyperloop systems is heavily influenced by the specific needs and investment capabilities of different end-user groups, from infrastructure development to operational management.
- Logistics Providers:These entities seek faster, more efficient ways to move goods, particularly high-value or time-sensitive cargo, across Europe. Their demand drives the development of freight-focused hyperloop corridors.
- Infrastructure Developers:Companies specializing in large-scale construction and engineering are crucial for building the physical hyperloop network, including tubes, stations, and energy infrastructure. Their involvement is critical for project execution in countries like Italy and the Netherlands.
- Transport Operators:These organizations would manage the day-to-day running of hyperloop services, including scheduling and maintenance.
- Research Organizations:Academic institutions and specialized research bodies contribute to the technological advancement and feasibility studies of hyperloop systems.
Demand from Logistics Providers and Infrastructure Developers drives significant market activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Europe hyperloop technology market currently sees production and test center development concentrated in a few Western European nations, while the broader continent represents a significant consumption opportunity for future high-speed transport networks. Policy mandates for sustainable transport are driving investment and regulatory efforts across the region. This dynamic environment fosters both technological innovation and critical infrastructure planning.
Netherlands
The Netherlands exhibits strong demand for sustainable freight solutions and government support for transport innovation. The European Green Deal mandates carbon-neutral transport, providing a policy framework for hyperloop. The European Hyperloop Center in Delft drives system testing and standardization efforts within the country.
Spain
Spanish interest focuses on high-speed passenger transport and active test center development. CE marking is critical for safety certification, influencing local project progression. The city of Málaga hosts significant hyperloop research and development activities, attracting both public and private investment.
Germany
German engineering expertise drives demand for efficient logistics connections and advanced transport systems. National sustainable transport initiatives align with hyperloop development goals. Industrial centers like Munich contribute to propulsion system advancements and component manufacturing.
Italy
Italian infrastructure developers show demand for modern, high-speed transport links, often through public-private partnership models. The European Commission guides regulatory harmonization, impacting project timelines in Italy. Test facilities near Rome are advancing hyperloop feasibility studies and system integration.
France
French policy supports cross-border logistics solutions and advanced transport engineering. National decarbonization targets create a strong incentive for new transport technologies. The Paris-Lyon corridor represents a potential route for future hyperloop development, linking major economic hubs.
Europe Hyperloop Technology Market Key Industry Players
The competitive structure tilts toward specialized technology developers and infrastructure consortiums, rather than broad transport conglomerates. This market is characterized by a mix of established engineering firms and agile startups, each contributing to specific aspects of hyperloop development. Strategic partnerships between technology providers and infrastructure developers represent a dominant competitive move, alongside continuous technology maturation and standardization efforts.
Specialists in hyperloop system development, such as Hardt B.V., focus on advancing core technologies and establishing European test centers. Hyperloop Transportation Technologies exemplifies a model centered on forging public-private partnerships across various member states for project implementation. Transpod Inc. occupies a position among innovators differentiating their systems for both passenger and cargo transport capabilities, targeting specific logistics corridors.
| Leading Market Players |
|---|
| Hardt B.V. |
| Hyperloop Transportation Technologies |
| Transpod Inc. |
| AECOM |
| Space Exploration Technologies Corp |
| Dinclix Groundworks |
| Delft Hyperloop |
| TUM Hyperloop |
| Nevomo Poland |
| Others |
Cost & Logistics Intelligence
Certification burdens for safety-critical components drive a clear divergence in pricing and supply chain complexity across the hyperloop technology market. This stratification impacts sourcing strategies and cost structures significantly for different product types.
Pricing Analysis
Cost-down pressure on vacuum technology and low-pressure tube components accelerates due to the need for large-scale infrastructure deployment. Project-based pricing dominates for entire hyperloop systems, while per-unit transactional models apply to modular components. Certification level, particularly CE marking for safety systems, and customization requirements act as key price differentiation drivers. Logistics providers exhibit the highest price sensitivity for goods delivery applications, while infrastructure developers prioritize long-term reliability.
Supply Chain Analysis
European Green Deal mandates for local content reshape sourcing for key hyperloop components, particularly in countries like Germany and the Netherlands. The supply chain for hyperloop technology concentrates heavily in Germany, the Netherlands, and Italy, which provide engineering expertise and advanced manufacturing capabilities. Raw material dependencies include specialized alloys for tubes and rare earth magnets for propulsion systems. Single-source vulnerability for niche vacuum engineering expertise presents a structural supply chain risk. Distribution runs through direct B2B contracts with infrastructure developers and technology integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe hyperloop technology market presents a cost-of-compliance story, with stringent CE marking requirements creating a significant barrier-to-entry moat for specialized component manufacturers.
For Market Incumbents: Lock in long-term procurement contracts with infrastructure developers to secure volume and stabilize revenue streams. Incumbents should invest heavily in standardization efforts for modular components, countering the threat of fragmented proprietary systems. Expanding R&D into next-generation magnetic levitation systems further solidifies technological leadership against emerging startups.
For New Entrants and Emerging Players: Specialized engineering firms represent a penetrable channel for hyperloop technology, offering bespoke solutions for niche system components. New entrants should target Eastern Europe's underpenetrated infrastructure modernization projects, focusing on high-value goods delivery applications. A go-to-market angle centered on rapid prototyping and flexible integration with existing transport networks could secure initial market share.
For Investors and Strategic Acquirers: Re-rating potential sits with technology developers possessing validated safety system certifications, given the regulatory pathway defined by the European Commission. Long-term viability for hyperloop technology hinges on successful cross-border regulatory harmonization over the next decade. The signal to watch is the first commercial deployment of a passenger-carrying system.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure CE Marking for Safety Systems | This ensures compliance with European Union regulations and enables market access for critical components. |
| Form Public-Private Partnerships | These partnerships de-risk large capital expenditures and accelerate infrastructure development in member states. |
| Invest in Modular Component Design | This strategy reduces project complexity and allows for scalable, phased construction of hyperloop networks. |
| Develop Freight-Only Corridors | This targets near-term commercialization by leveraging less stringent safety regulations for high-value goods. |
| Expand Vacuum Engineering Talent Pool | Addressing specialized talent scarcity directly supports system development and long-term operational capabilities. |
Research Approach
European Commission reports, national transport agency studies, and academic research papers formed the secondary backbone for this analysis. This was combined with primary interviews involving hyperloop technology executives, infrastructure developers, logistics providers, and regulatory experts across Europe. Bottom-up market sizing for component demand and top-down validation against overall project investment triangulated initial data points.
Historical trendline analysis of high-speed transport infrastructure development and technology maturation informed the forecast framework across the analysis window. Segmentation dimensions modeled included product type, core technology, application, end-user, and regional development stage. Compound Annual Growth Rates were derived from an assessment of adoption rates and planned project pipelines. Key forecast inputs included projected infrastructure spending and regulatory approval timelines.
Caveats apply where geopolitical shifts or significant technological breakthroughs could materially shift the outlook for hyperloop deployment. Forecasts reflect assumptions regarding continued policy support and successful regulatory harmonization efforts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
E-Scooter Sharing Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Bike Sharing Market