
 Veterinary Suture Kit Market | 2026-2036
Veterinary Suture Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Suture Kit Market Analytics
ISO 10993 biocompatibility certification is rotating as the primary gating standard for manufacturers seeking veterinary suture kit market access. Ethicon leverages its Johnson & Johnson parent infrastructure to sustain multi-market regulatory dossiers. B. Braun Melsungen anchors European production capacity with dedicated cleanroom facilities for absorbable polymer lines. Medtronic competes through its parallel human-veterinary manufacturing protocols that streamline cross-species product development.
A veterinary suture kit comprises sterile, pre-packaged assemblies of needles and threads—typically composed of polyglycolic acid, polydioxanone, silk, or nylon—engineered for wound closure in animal patients with tensile strength profiles matched to tissue healing rates. Absorbable sutures dominate procedure volumes in soft-tissue applications where follow-up removal is impractical, while non-absorbable sutures command premium positioning in orthopedic and dental surgery where prolonged mechanical support is essential. Surgical kits integrating pre-selected needle-thread combinations are gaining traction among veterinary clinics seeking to reduce operative preparation time and inventory complexity.
FDA Center for Veterinary Medicine oversight of device sterility assurance levels combines with EMA veterinary product quality guidelines to elevate barrier packaging and ethylene oxide residual testing standards across export-oriented manufacturers. The EU MDR framework, though primarily human-focused, exerts downstream pressure through shared contract sterilization facilities that serve both medical device categories. Stakeholders must monitor evolving ISO 13485 audit expectations for veterinary-specific quality management systems as regulatory convergence between human and animal health device pathways accelerates.
Market Dynamics
ISO 10993 biocompatibility certification is tightening as the primary gating standard for veterinary suture kit manufacturers, forcing producers to revalidate polymer formulations and sterilization protocols across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- Companion animal surgery expansion:Elective procedure volumes in US and German companion animal clinics are climbing as pet insurance penetration deepens, creating sustained kit consumption.
- FDA Center for Veterinary Medicine sterility mandates:Updated device classification rules for animal health products are accelerating barrier packaging upgrades across export-oriented manufacturers.
- Absorbable polymer innovation:Polyglycolic acid and polydioxanone formulations with matched tensile strength profiles are displacing silk in soft-tissue applications.
Market Restraints
- Ethylene oxide sterilization capacity concentration:Contract sterilization facilities serving both human and veterinary device categories face queue bottlenecks in Germany and the United States.
- Raw material input volatility:Medical-grade polymer feedstock prices fluctuate with petrochemical supply chains, compressing margin predictability for kit assemblers.
- EU MDR framework spillover:Shared manufacturing infrastructure with human medical devices subjects veterinary producers to elevated audit frequency despite species-specific exemptions.
Strategic Opportunities
- Japan's underpenetrated small animal segment:Pet insurance coverage gaps in regional veterinary clinics outside Tokyo and Osaka create first-mover positioning for standardized kit portfolios.
- Pre-configured surgical kit formats:Needle-thread combinations pre-selected for common procedures reduce operative preparation time and inventory complexity for mid-sized clinics.
- EMA veterinary product quality guideline harmonization:Convergence with ISO 13485 audit expectations streamlines multi-market dossier preparation for compliant manufacturers.
Industry Challenges
- Veterinary-specific quality management system expertise:ISO 13485 auditors with animal health device experience remain scarce, extending certification timelines for new market entrants.
- Cross-species product development integration:Parallel human-veterinary manufacturing protocols require specialized cleanroom segregation and documentation trails that inflate capex requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Suture Kit Market |
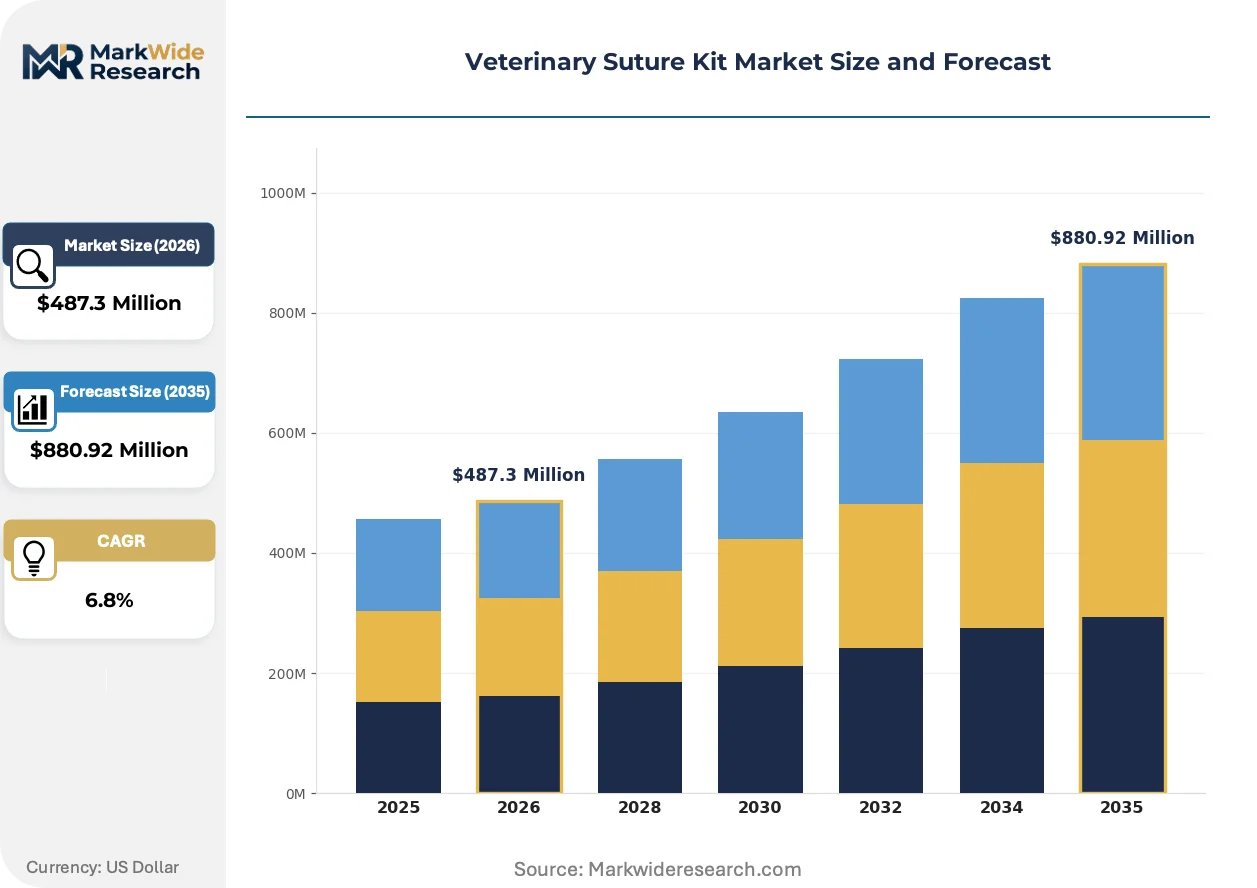
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbable Sutures, Non-Absorbable Sutures, Surgical Kits, Suture Material Application: General Surgery, Orthopedic Surgery, Ophthalmic Surgery, Dental Surgery End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Zoos Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Retail Stores |
| Companies Covered | Smith & Nephew, Betatech Medical, Ethicon (Johnson & Johnson), Boston Scientific, Changzhou Zener Medtec, Medtronic, DemeTECH, Corza Medical, B. Braun Melsungen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Suture Kit Market Evolving Landscape
Antimicrobial-coated suture materials and smart packaging with integrity indicators are actively reshaping product differentiation strategies, while regulatory convergence between human and animal health pathways accelerates validation standardization.
Antimicrobial triclosan and chlorhexidine coatings on absorbable polymer threads are bifurcating the premium kit segment from standard sterile assemblies. Large companion animal hospitals in the United States and Germany are adopting these formats for orthopedic and dental procedures where infection risk carries higher cost consequences. The technology is compressing price competition at the mid-tier while creating certification moats for early movers.
EMA veterinary product quality guidelines now explicitly reference ISO 10993 biocompatibility testing matrices previously reserved for human devices. Manufacturers serving European export markets must maintain dual dossier structures or pursue unified validation protocols that satisfy both frameworks. Small-to-mid-sized kit producers in Italy and Spain are consolidating testing partnerships to absorb compliance cost inflation.
Direct procurement from manufacturers is displacing traditional veterinary distributor networks for high-volume clinic chains. Corporate veterinary groups in the United States and United Kingdom are negotiating annual kit contracts with sterilization and lot-traceability guarantees that regional distributors cannot match. This consolidation concentrates purchasing power among fewer buyers while squeezing margin structures for intermediaries.
Veterinary Suture Kit Market Segmentation
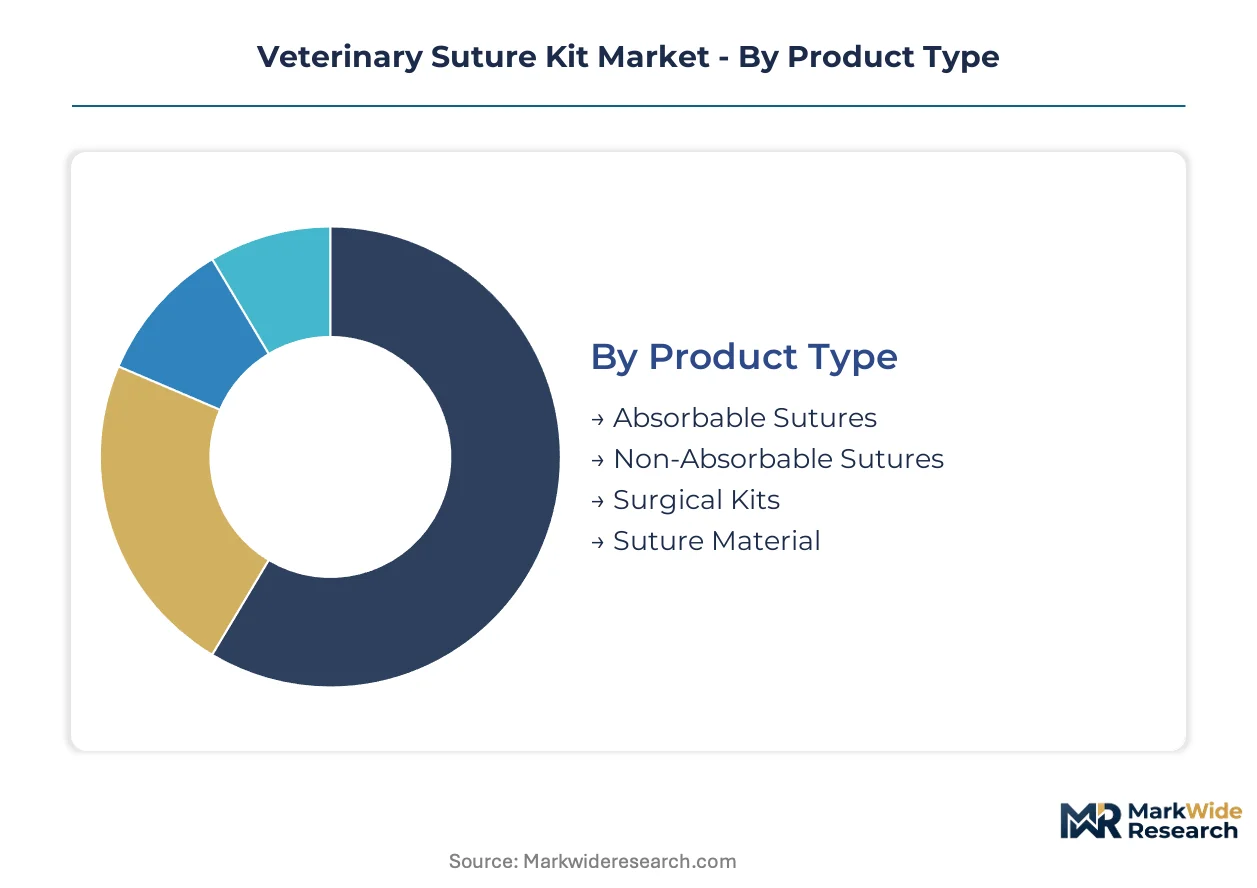
Veterinary suture kit segmentation reveals distinct margin architectures across product formats, with absorbable polymer lines commanding premium positioning in companion animal surgery while surgical kits consolidate purchasing power among corporate clinic chains. Understanding these segment boundaries enables manufacturers to align sterilization investments and regulatory dossiers with profit pool concentration.
Product Type:
Absorbable polymer formulations capture the deepest margin pools through ISO 10993 certification moats and recurring soft-tissue procedure demand.
- Absorbable Sutures:Polyglycolic acid and polydioxanone threads engineered for hydrolytic degradation within 60-90 days eliminate follow-up removal visits in companion animal soft-tissue procedures. United States and German companion animal clinics are standardizing these formats for spay-neuter and gastrointestinal surgery where tensile strength retention curves match tissue healing timelines. FDA Center for Veterinary Medicine sterility documentation requirements are compressing supplier qualification timelines for non-compliant assemblers.
- Non-Absorbable Sutures:Silk and nylon constructions maintain mechanical integrity beyond 180 days for orthopedic and dental applications requiring prolonged wound support. Demand concentrates in large animal hospitals performing fracture repair and oral surgery where suture removal scheduling is operationally feasible. Premium pricing persists against absorbable alternatives due to lower polymer R&D amortization requirements.
- Surgical Kits:Pre-configured needle-thread assemblies reduce operative preparation time for mid-sized veterinary clinics managing diverse procedure mixes.
- Suture Material:Raw polymer and natural fiber inputs supplied to kit assemblers face petrochemical price volatility that compresses margin predictability.
Absorbable Sutures holds installed capacity. Surgical Kits is rotating up the share rankings.
Application:
Procedure complexity and infection risk profiles stratify pricing power, with orthopedic and dental surgery supporting antimicrobial-coated premium formats.
- General Surgery:Spay-neuter and soft-tissue procedures generate the highest absolute kit volumes across United States and Japanese companion animal clinics. Standard absorbable suture configurations dominate this segment with limited product differentiation beyond packaging convenience.
- Orthopedic Surgery:Fracture repair and joint procedures demand non-absorbable sutures with extended tensile strength profiles matched to bone healing rates. Large companion animal hospitals in Germany and the United States are adopting antimicrobial-coated formats where infection carries higher cost consequences.
- Ophthalmic Surgery:Microsurgical needle specifications and ultra-fine thread diameters require specialized manufacturing cleanrooms with limited qualified supplier base.
- Dental Surgery:Oral wound closure in companion animals uses non-absorbable silk and synthetic alternatives where moisture exposure accelerates degradation concerns.
General Surgery anchors volume throughput. Orthopedic Surgery is climbing the fastest on value per procedure.
End User:
Customer scale determines procurement channel preference, with corporate veterinary groups consolidating direct manufacturer relationships.
- Veterinary Clinics:Independent and mid-sized companion animal practices across the United States and United Kingdom are migrating toward pre-configured surgical kits to reduce inventory SKU complexity. These facilities balance cost sensitivity against sterility assurance requirements through distributor relationships with regional sterilization guarantees.
- Animal Hospitals:Large referral and emergency centers perform the highest procedure volumes per facility, enabling annual contract negotiations with manufacturers. Direct procurement agreements with lot-traceability documentation are displacing traditional distributor intermediaries in this segment.
- Research Laboratories:Academic and contract research facilities require specialized suture formats for experimental surgery with customized tensile specifications.
- Zoos:Exotic and wildlife veterinary applications demand extended suture size ranges for species from avian to large mammal anatomy.
Animal Hospitals holds purchasing power concentration. Veterinary Clinics is gaining share fastest on kit format adoption.
Distribution Channel:
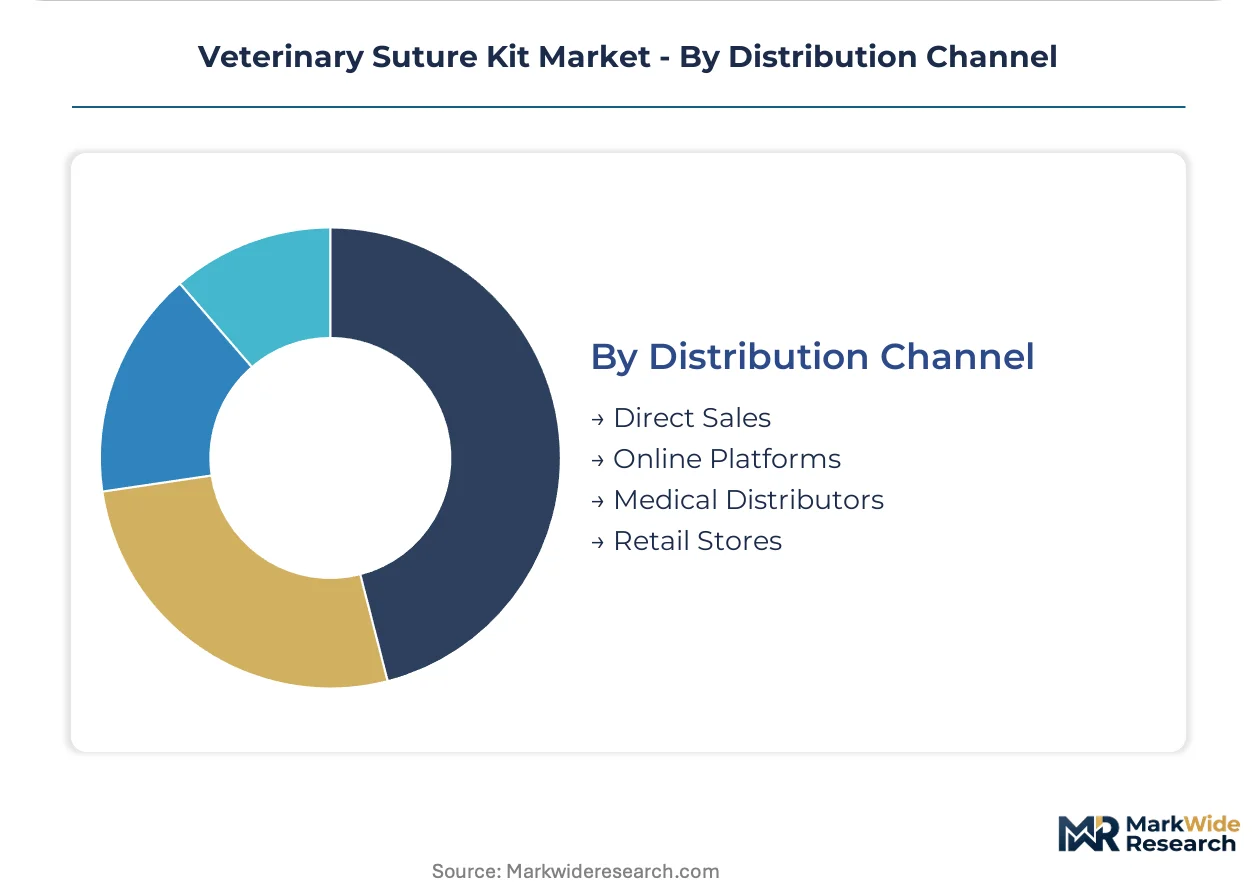
Channel economics reflect customer scale and documentation requirements, with direct sales capturing margin from high-volume accounts.
- Direct Sales:Manufacturer-to-facility relationships serve corporate veterinary groups and large animal hospitals requiring sterilization certificates and lot traceability. United States and United Kingdom clinic chains negotiate annual volume contracts with ethylene oxide residual documentation that regional distributors cannot match.
- Online Platforms:E-commerce penetration is expanding among independent clinics seeking transparent pricing and rapid reorder capabilities for standard suture configurations.
- Medical Distributors:Regional veterinary supply networks retain relevance for small clinics requiring credit terms and mixed-product basket fulfillment.
- Retail Stores:Limited suture availability through agricultural and pet retail channels serves rural mixed-animal practitioners with emergency procurement needs.
Direct Sales holds contract value concentration. Online Platforms is expanding most quickly on independent clinic digital adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large companion animal hospital chains and corporate veterinary groups in the United States, Germany, and Japan concentrate kit purchasing power through direct manufacturer contracts. These three markets anchor demand for sterile barrier packaging and ISO 10993-compliant absorbable polymer formulations.
United States
Corporate veterinary groups operating multi-site clinic networks negotiate annual volume contracts with ethylene oxide residual documentation requirements. FDA Center for Veterinary Medicine sterility assurance mandates are accelerating barrier packaging upgrades among export-oriented manufacturers serving this market. Texas and Florida host the densest concentrations of large companion animal referral hospitals driving premium kit consumption.
Germany
Specialized small animal clinics in Bavaria and North Rhine-Westphalia perform the highest per-capita orthopedic procedure volumes in Europe. EMA veterinary product quality guidelines referencing ISO 10993 biocompatibility matrices are compressing supplier qualification timelines. Contract sterilization facilities in Baden-Württemberg face queue bottlenecks serving both human and veterinary device categories.
Japan
Pet insurance penetration gaps outside Tokyo and Osaka create first-mover positioning for standardized kit portfolios targeting regional veterinary clinics. METI oversight of medical device quality systems exerts downstream pressure through shared manufacturing infrastructure with human health products. The Kansai region hosts specialized cleanroom facilities producing microsurgical needle specifications for ophthalmic applications.
United Kingdom
Independent veterinary practices across Greater London and the Southeast are migrating toward pre-configured surgical kits to reduce inventory SKU complexity. MHRA alignment with EU MDR framework expectations elevates audit frequency for veterinary producers despite species-specific exemptions. Corporate clinic chains in Manchester and Birmingham negotiate direct procurement agreements displacing traditional distributor intermediaries.
China
Domestic companion animal surgery volumes are climbing in Shanghai and Beijing as pet ownership rates deepen among urban households. NMPA medical device classification rules for animal health products are tightening sterilization documentation requirements for import-dependent manufacturers. Zhejiang and Jiangsu provinces host contract sterilization facilities serving both export-oriented veterinary kit producers and domestic distributors.
Veterinary Suture Kit Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with parallel human-veterinary manufacturing capabilities. The structure concentrates around three to five integrated manufacturers controlling premium absorbable polymer lines and sterilization infrastructure. Strategic archetypes include human-health crossover specialists leveraging existing regulatory dossiers, regional European producers with dedicated veterinary cleanroom capacity, and Asian contract manufacturers serving private-label distributors. Dominant competitive moves encompass backward integration into medical-grade polymer feedstock and geographic expansion through distributor acquisition in underpenetrated markets.
Within the diversified conglomerate tier, Ethicon and B. Braun Melsungen exemplify archetypes built on multi-market regulatory infrastructure and dedicated production capacity. Medtronic occupies a position representing parallel human-veterinary protocol integration. Among specialized producers, Changzhou Zener Medtec exemplifies the Asian contract manufacturing archetype serving export markets.
| Leading Market Players |
|---|
| Smith & Nephew |
| Betatech Medical |
| Ethicon (Johnson & Johnson) |
| Boston Scientific |
| Changzhou Zener Medtec |
| Medtronic |
| DemeTECH |
| Corza Medical |
| B. Braun Melsungen |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day polymer feedstock lead times compress margin flexibility for kit assemblers while concentrating pricing power among manufacturers with captive sterilization capacity in Germany and the United States. This inventory-to-pricing nexus rewards backward integration into medical-grade polymer production and penalizes distributors without direct manufacturer relationships.
Pricing Analysis
Cost-plus contracts indexed to petrochemical feedstock benchmarks dominate procurement agreements between kit manufacturers and corporate veterinary groups. Three-tier pricing structure across antimicrobial-coated premium, ISO 10993-certified standard, and economy uncoated tiers separates infection-risk-sensitive orthopedic procedures from routine soft-tissue applications. Cost compression in the economy tier is intensifying because contract sterilization queue bottlenecks in Baden-Württemberg and Texas inflate per-unit processing costs. Independent clinics exhibit highest price sensitivity, while large animal hospitals prioritize lot-traceability documentation over per-unit cost.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain European distribution economics for Asian polymer feedstock shipments. Manufacturing concentrates in Germany, the United States, and China, with medical-grade polyglycolic acid and polydioxanone inputs drawing from petrochemical complexes in Louisiana, Antwerp, and Singapore. Single-source vulnerability in ethylene oxide sterilization capacity creates queue risk for export-oriented assemblers. Distribution runs through direct manufacturer contracts for high-volume clinic chains, with regional veterinary distributors serving credit-dependent independent practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through post-pandemic surgical volume normalization as companion animal procedure backlogs clear and pet insurance penetration deepens elective scheduling. The recovery trajectory hinges on sterilization capacity expansion keeping pace with kit demand growth.
For Market Incumbents: Consolidate manufacturing footprint through dedicated cleanroom capacity additions in Bavaria and Texas to capture contract sterilization queue premiums. Deepen ISO 10993 certification moats against emerging Asian contract manufacturers by accelerating antimicrobial coating R&D. Channel control through direct procurement portals displaces distributor intermediaries and locks in corporate veterinary group volume commitments. For New Entrants and Emerging Players: ISO 10993 biocompatibility fast-track partnerships with established testing laboratories in Switzerland and Singapore compress regulatory timelines versus de novo validation. Japan's regional veterinary clinics outside Tokyo and Osaka present the most penetrable geography given pet insurance coverage gaps. Pre-configured surgical kit formats targeting mid-sized independent clinics offer a go-to-market angle bypassing incumbent distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underutilized veterinary-specific cleanroom capacity and dormant regulatory dossiers. Long-term viability centers on manufacturers with parallel human-veterinary protocol integration that amortizes compliance costs across species. The inflection signal to watch is EMA veterinary product quality guideline harmonization with ISO 13485 audit expectations, which would accelerate consolidation among non-compliant regional producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Captive polyglycolic acid production in Antwerp insulates margin from petrochemical volatility. |
| ISO 10993 Certification Fast-Track | Accelerated biocompatibility validation in Singapore compresses European market entry timelines. |
| Direct Procurement Portal Launch | Manufacturer-to-clinic digital platforms displace regional veterinary distributors in the United States. |
| Antimicrobial Coating R&D Partnership | Triclosan and chlorhexidine formulation alliances with German specialty chemical firms differentiate premium kits. |
| Cleanroom Capacity Expansion | Dedicated Bavaria and Texas facilities capture ethylene oxide sterilization queue premiums. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Veterinary Medicine device classification filings, EMA veterinary product quality guidelines, and ISO 13485 audit documentation. Interviews with veterinary surgical supply procurement managers, biomedical engineers at large companion animal hospitals, contract sterilization facility operators, and polymer feedstock procurement directors inform demand and supply-side dynamics. Secondary validation draws from customs trade data, pet insurance penetration statistics, and hospital procurement database extracts. Bottom-up kit volume estimates triangulate against top-down procedure volume projections across the analysis window.
Segmentation dimensions modeled include product type (absorbable sutures, non-absorbable sutures, surgical kits, raw suture material), application (general surgery, orthopedic surgery, ophthalmic surgery, dental surgery), end user (veterinary clinics, animal hospitals, research laboratories, zoos), and distribution channel (direct sales, online platforms, medical distributors, retail stores). CAGRs derive from procedure volume growth rates, kit consumption per procedure, and pricing trajectory assumptions. Forecast inputs incorporate pet insurance penetration curves, sterilization capacity expansion schedules, and regulatory harmonization milestones.
Underlying assumptions cover companion animal ownership stability, ethylene oxide sterilization capacity utilization rates, and polymer feedstock price band persistence, with deviation risk concentrated in regulatory audit frequency escalation and contract sterilization queue disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Disposable Oxygen Masks Market
Medical Supplies
North America Intravenous Solutions Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Latex Gloves Market
Medical Supplies
Middle East and Africa Medical Rubber and Balloon Products Market
Medical Supplies
Single Use Safety Lancet Market
Medical Supplies
Surgical Glue Market
Medical Supplies
Surgical Collagen Powders Market
Medical Supplies
Forensic Swabs Market
Medical Supplies
Global Surgical Kits Market
Medical Supplies
Compression Stockings Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Serum-Free Media Market