
 Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market | 2026-2036
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market Insights
EU MDR is expanding documentation and post-market surveillance obligations for dosimetry equipment manufacturers. PTW Freiburg leverages its Freiburg manufacturing base to sustain CE-marked product lines across European oncology centers. IBA Dosimetry anchors its competitive position through integrated software-hardware platforms for pencil beam scanning validation. Sun Nuclear Corporation dominates North American service contracts with its distributed calibration laboratory network.
Proton and ion beam therapy dosimetry and QA test equipment comprises ionization chambers, solid-state detectors, and scintillation systems engineered to measure absorbed dose in water or tissue-equivalent phantoms with spatial resolutions below one millimeter, primarily ensuring beam output accuracy and patient safety in particle therapy suites. Pencil beam scanning technology leads technology adoption as facilities transition from passive scattering to intensity-modulated proton delivery, while electrometer systems capture concentrated margin pools due to their irreplaceable role in traceable dose calibration chains. Radiochromic films compete in research-intensive segments where two-dimensional dose mapping validates complex beam geometries.
FDA 21 CFR Part 820 quality system regulations, EU MDR 2017/745 conformity requirements, and IEC 60601-2-64 medical electrical equipment standards collectively mandate independent third-party dosimetry verification for every clinical proton beam. Japan's PMDA enforces equivalently stringent pre-market certification for imported QA equipment serving its expanding carbon ion therapy infrastructure. Stakeholders must monitor how NMPA's evolving GB standards for particle therapy equipment reshape market access protocols for Western dosimetry vendors entering Chinese hospital procurement channels.
Market Dynamics
Pencil beam scanning technology is forcing oncology centers to replace legacy passive scattering systems, triggering wholesale recalibration of dosimetry infrastructure across particle therapy suites.
Growth Catalysts
- EU MDR post-market surveillance mandates:Germany's university hospital clusters must upgrade dosimetry documentation systems to maintain CE-marked equipment certifications, sustaining replacement demand.
- Pencil beam scanning validation protocols:Intensity-modulated proton delivery requires sub-millimeter spatial resolution detectors, expanding specification requirements for QA test equipment.
- Japan's carbon ion therapy expansion:PMDA pre-market certification requirements for imported QA equipment create captive demand for compliant dosimetry systems.
Market Restraints
- High-purity water phantom costs:Deionized water systems for beam calibration consume significant capital budgets, compressing equipment procurement flexibility.
- German manufacturing concentration:CE-marked ionization chamber production clusters in Baden-Württemberg create geographic supply vulnerability for non-European buyers.
- Radiochromic film substitution:Research-intensive segments increasingly validate complex beam geometries with disposable film arrays rather than reusable detector systems.
Strategic Opportunities
- China's NMPA GB standard evolution:Western dosimetry vendors can capture first-mover advantage in particle therapy equipment certification as hospital procurement channels open.
- Software-hardware platform convergence:Integrated electrometer-detector systems that automate traceable dose calibration chains command premium positioning.
- United States distributed service networks:Independent calibration laboratory partnerships reduce downtime for proton therapy centers operating under FDA 21 CFR Part 820 quality system regulations.
Industry Challenges
- Medical physics specialist scarcity:Qualified personnel to operate ionization chamber calibration protocols are concentrated in Heidelberg and Munich metropolitan clusters, limiting facility expansion.
- IEC 60601-2-64 certification timelines:Third-party dosimetry verification requirements for every clinical proton beam extend equipment commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market |
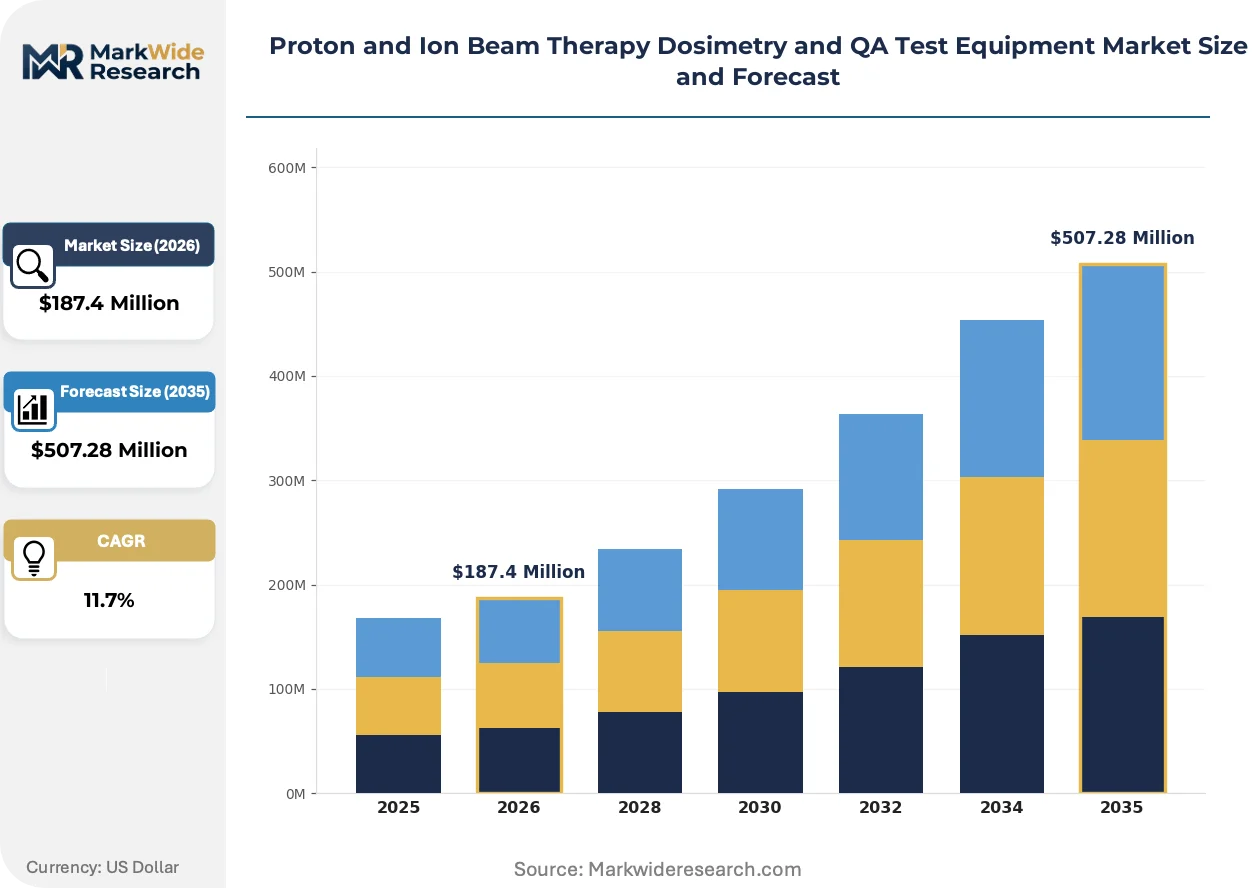
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionization Chambers, Solid State Detectors, Scintillation Detectors, Radiochromic Films, Electrometer Systems Technology: Passive Scattering, Pencil Beam Scanning, Spot Scanning, Uniform Scanning, Layered Energy Modulation Application: Dosimetry Calibration, Beam Quality Assurance, Patient Safety Verification, Treatment Planning Validation, Equipment Performance Testing End User: Oncology Centers, Research Institutes, Medical Physicists, Radiotherapy Clinics, Academic Hospitals |
| Companies Covered | PTW Freiburg, IBA Dosimetry, Sun Nuclear Corporation, Standard Imaging, Fluke Biomedical RaySafe, Radiation Products Design, Radcal, CIRS Computerized Imaging Reference Systems, Landauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market Trends and Innovations
Dosimetry equipment architecture is fragmenting into interoperable component ecosystems, enabling oncology centers to mix detector technologies rather than purchasing monolithic QA platforms.
Scintillation-based detector arrays are modularizing pencil beam scanning validation workflows. University hospitals in Germany and Japan are adopting plug-and-play scintillator modules that interface with existing electrometer systems. This architecture is modularizing vendor lock-in patterns, allowing centers to source detectors, software, and calibration services from separate suppliers.
FDA 21 CFR Part 11 digital validation requirements are compressing software release cycles for beam calibration platforms. Equipment manufacturers must maintain electronic records and audit trails for every dose measurement algorithm update. North American proton therapy centers face the steepest compliance burden, driving preference toward vendors with pre-validated software-hardware bundles.
After-sales service unbundling is disrupting traditional equipment procurement patterns. Oncology centers in the United States are separating hardware acquisition from calibration maintenance contracts, awarding multi-year service agreements to independent laboratory networks rather than original equipment manufacturers. This bifurcation is most advanced in California and Massachusetts, where proton therapy density supports third-party service specialization.
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market Segmentation
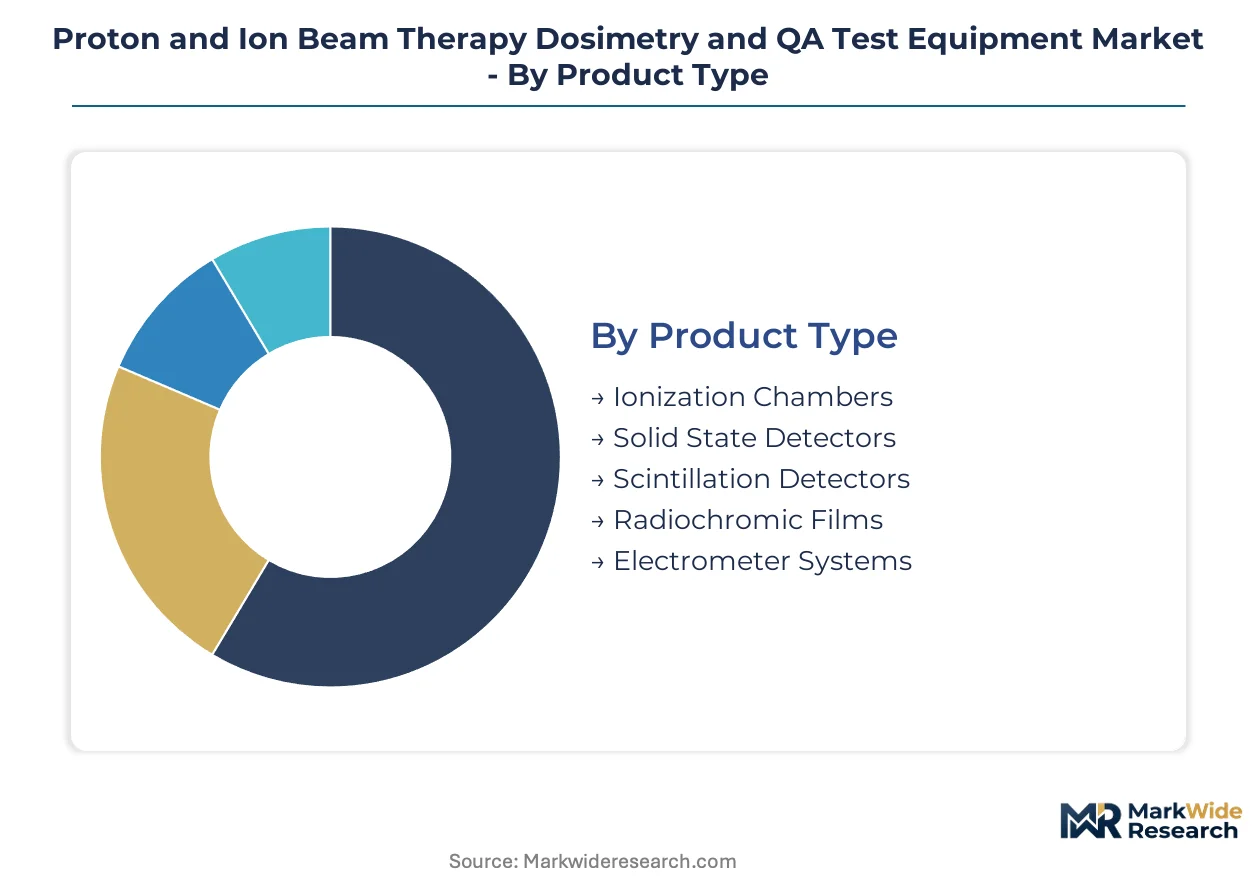
Segmentation in proton and ion beam therapy dosimetry reveals how equipment specifications diverge across clinical workflows, research demands, and regulatory compliance tiers. Understanding these divisions exposes where procurement budgets concentrate and which technology transitions reshape vendor competitive positions.
Product Type:
Supply concentration in Baden-Württemberg manufacturing clusters shapes competitive dynamics across detector categories, with CE-marked production lines favoring established European vendors.
- Ionization Chambers:Gas-filled detectors with traceable calibration chains to primary standards laboratories. Heidelberg and Munich university hospital clusters deploy these for absolute dose verification under EU MDR documentation mandates, sustaining replacement demand for water-phantom-compatible models.
- Electrometer Systems:Precision current measurement instruments serving as irreplaceable nodes in dose calibration infrastructure. North American proton therapy centers under FDA 21 CFR Part 820 regulations specify these for automated beam output verification, commanding premium positioning through software-hardware integration.
- Solid State Detectors:Semiconductor-based devices offering compact form factors for in-vivo dosimetry applications.
- Scintillation Detectors:Light-emitting crystal arrays enabling real-time beam profiling with sub-millimeter spatial resolution.
- Radiochromic Films:Disposable two-dimensional dose mapping media competing in research-intensive validation workflows.
Today's leader: Electrometer Systems. Tomorrow's challenger: Scintillation Detectors.
Technology:
Cost tier differentiation separates legacy infrastructure from next-generation installation cycles, with capital intensity varying fivefold between passive scattering retrofits and pencil beam scanning greenfield deployments.
- Pencil Beam Scanning:Intensity-modulated proton delivery using magnetically steered narrow beams. Germany's university hospital networks and Japan's carbon ion facilities specify sub-millimeter detector resolution for these systems, expanding QA equipment specification requirements.
- Passive Scattering:Double-scattering foil systems with fixed field delivery. Existing installations in United States community proton centers require ongoing dosimetry maintenance despite technology obsolescence, sustaining aftermarket service revenue.
- Spot Scanning:Discrete spot deposition sequences enabling conformal dose painting.
- Uniform Scanning:Broad beam modulation techniques for large-field treatments.
- Layered Energy Modulation:Range-compensated delivery systems for depth-dose optimization.
Pencil Beam Scanning commands the steepest expansion trajectory as passive scattering reaches end-of-life replacement windows.
Application:
Customer type stratification distinguishes high-frequency clinical verification from episodic research validation, with oncology centers purchasing on 3-5 year replacement cycles versus academic hospitals on grant-driven procurement timelines.
- Dosimetry Calibration:Traceable dose standardization protocols for beam output constancy. FDA 21 CFR Part 11 digital validation requirements compress software release cycles for these workflows, favoring vendors with pre-validated platforms.
- Beam Quality Assurance:Daily and monthly constancy checks for beam energy, symmetry, and flatness. Japan's PMDA pre-market certification requirements for imported equipment create captive demand for compliant QA systems in carbon ion therapy expansion.
- Patient Safety Verification:Pre-treatment dose validation for individual patient plans.
- Treatment Planning Validation:Algorithm verification for dose calculation accuracy.
- Equipment Performance Testing:Acceptance testing and commissioning protocols for new installations.
Beam Quality Assurance absorbs the largest share of recurring procurement spend. Dosimetry Calibration is gaining share fastest through regulatory documentation mandates.
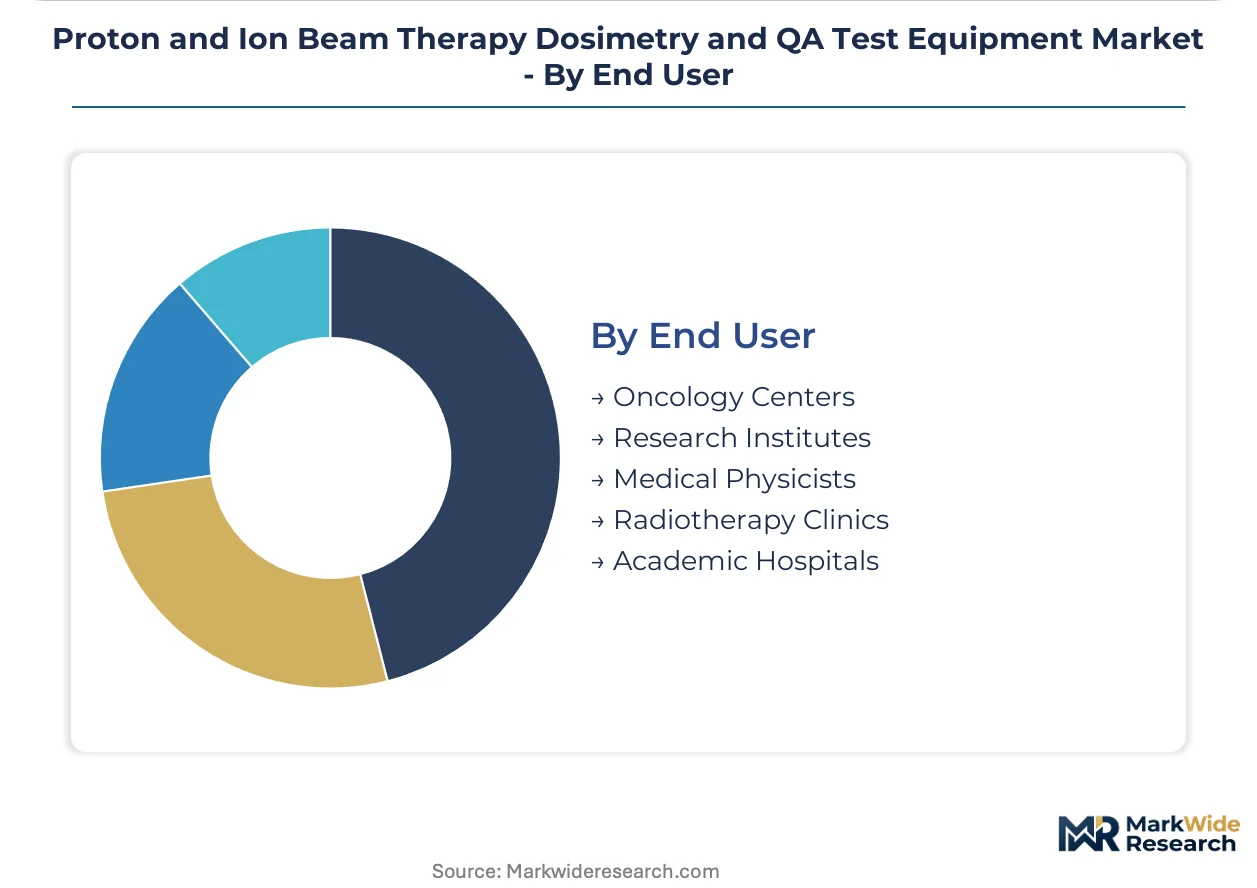
End User:
Geography determines procurement channel access, with United States oncology centers leveraging distributed calibration laboratory networks while German academic hospitals source directly from Freiburg manufacturing bases.
- Oncology Centers:Dedicated proton therapy facilities with continuous clinical operations. California and Massachusetts clusters unbundle hardware acquisition from service contracts, awarding multi-year maintenance agreements to independent laboratory networks.
- Academic Hospitals:University-affiliated institutions combining clinical service with research missions. Heidelberg and Munich metropolitan areas operate Europe's densest proton therapy networks, concentrating medical physics specialist expertise and dosimetry procurement authority.
- Research Institutes:National laboratories and beamline facilities advancing detector technology.
- Medical Physicists:Individual practitioners specifying equipment for consulting engagements.
- Radiotherapy Clinics:Multi-modality centers integrating proton therapy alongside photon capabilities.
Oncology Centers dominate current equipment volume. Academic Hospitals are expanding most quickly through Japan's carbon ion infrastructure buildout and China's emerging particle therapy procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical physics specialists concentrate in Heidelberg and Munich metropolitan clusters, anchoring European dosimetry procurement authority. Japan's carbon ion therapy expansion and China's emerging particle therapy channels reshape Asia-Pacific demand geography.
United States
Oncology centers in California and Massachusetts operate the densest proton therapy networks outside Europe. FDA 21 CFR Part 11 digital validation requirements compress software release cycles for beam calibration platforms. Distributed calibration laboratory networks in these states unbundle hardware acquisition from service contracts.
Germany
University hospital clusters in Heidelberg and Munich deploy Europe's most intensive proton therapy infrastructure. EU MDR post-market surveillance mandates force continuous documentation system upgrades for CE-marked equipment. Baden-Württemberg manufacturing bases sustain ionization chamber production for domestic and export markets.
Japan
Carbon ion therapy expansion at National Institute of Radiological Sciences and affiliated facilities drives specialized QA equipment demand. PMDA pre-market certification requirements for imported dosimetry systems create regulatory barriers favoring compliant vendors. Chiba and Hyogo prefectures host the primary treatment and research installations.
China
Hospital procurement channels in Beijing and Shanghai are opening to Western dosimetry vendors as NMPA GB standards for particle therapy equipment evolve. Domestic particle therapy installation rates accelerate across tier-one cities. Guangdong and Jiangsu provinces lead provincial-level healthcare infrastructure investment.
Switzerland
Swissmedic certification requirements for medical electrical equipment align with IEC 60601-2-64 standards, streamlining market access for compliant dosimetry manufacturers. The country's precision instrumentation heritage supports specialized detector technology development. Zurich and Geneva academic medical centers maintain active proton therapy research programs.
Proton and Ion Beam Therapy Dosimetry and QA Test Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across detector hardware, software platforms, and calibration services. The vendor base stratifies into three tiers: integrated platform providers commanding premium positioning, component specialists capturing niche specification requirements, and independent service laboratories unbundling after-sales maintenance. Dominant competitive moves include software-hardware convergence for automated calibration chains and geographic expansion through distributed service partnerships.
Within the integrated platform tier, IBA Dosimetry and PTW Freiburg exemplify European manufacturing concentration with CE-marked production lines. Sun Nuclear Corporation anchors North American service network specialization. These three entities occupy positions spanning hardware manufacturing, software validation, and multi-year maintenance contracting archetypes.
| Leading Market Players |
|---|
| PTW Freiburg |
| IBA Dosimetry |
| Sun Nuclear Corporation |
| Standard Imaging |
| Fluke Biomedical RaySafe |
| Radiation Products Design |
| Radcal |
| CIRS Computerized Imaging Reference Systems |
| Landauer |
| Others |
Pricing and Supply Chain Analysis
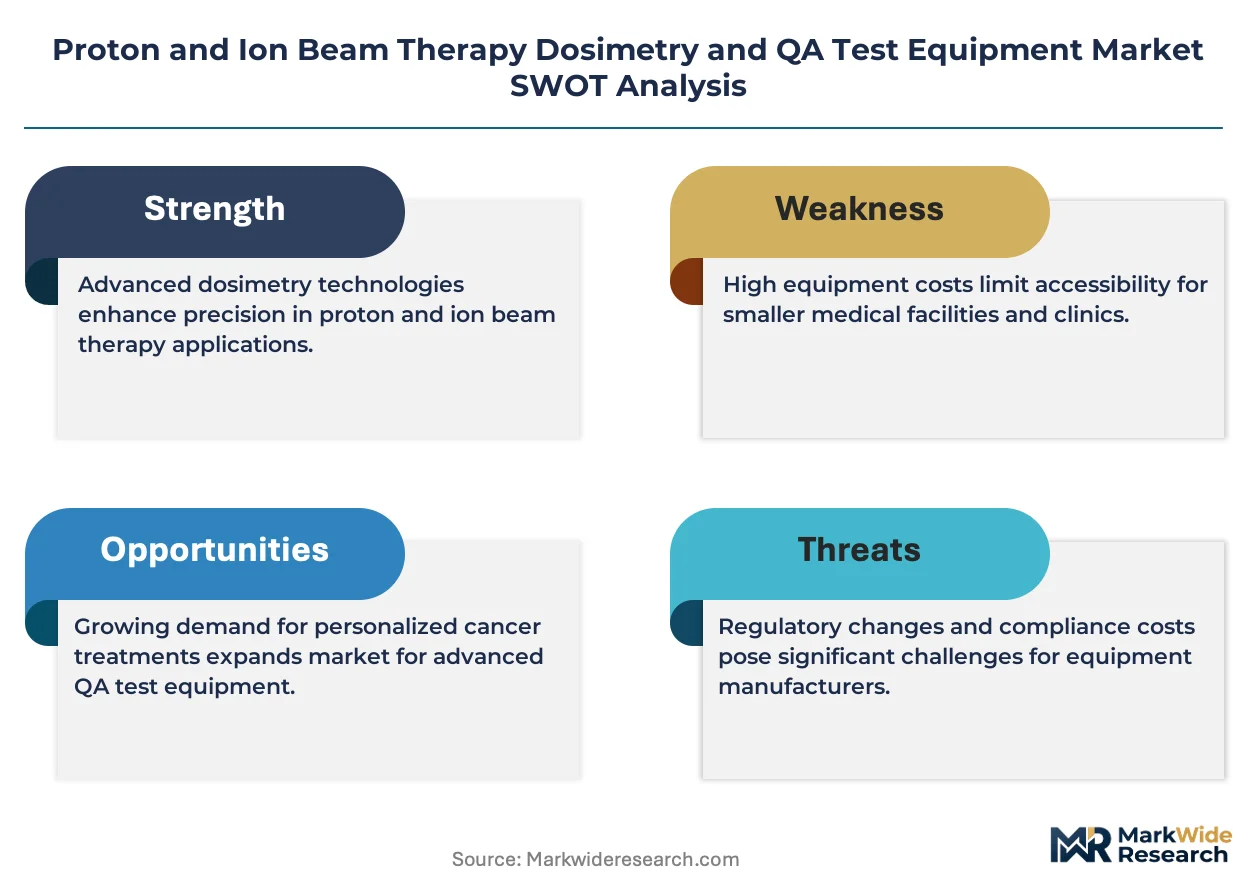
EU MDR post-market surveillance mandates gate both qualified supply and premium-tier pricing access, forcing oncology centers to source only from CE-marked manufacturers with validated documentation systems while compressing procurement flexibility for budget-constrained facilities.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across proton therapy markets. Three-tier pricing structure across premium, standard, and economy levels separates integrated software-hardware platforms with automated calibration chains from standalone detector hardware and basic electrometer units. Price differentiation stems from FDA 21 CFR Part 11 digital validation tiers and geographic service network density. Cost compression in economy-tier standalone detectors is intensifying because research institutes increasingly substitute radiochromic films for reusable systems. Academic hospitals in Heidelberg and Munich clusters show least price sensitivity due to grant-funded procurement timelines.
Supply Chain Analysis
High-purity synthetic sapphire crystal supply for scintillation detectors rests on specialty producers in Switzerland, Japan, and the United States. Manufacturing draws from precision-machined aluminum housings, medical-grade cabling assemblies, and traceable calibration reference sources. Single-source vulnerability concentrates in Baden-Württemberg ionization chamber production clusters, where CE-marked manufacturing lines serve European and export demand. Distribution runs through direct hospital procurement channels in Germany, independent laboratory networks in the United States, and emerging distributor partnerships in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR documentation mandates and FDA 21 CFR Part 11 digital validation requirements continuously refresh equipment replacement cycles regardless of underlying clinical demand trends.
For Market Incumbents: Anticipate radiochromic film substitution threats in research-intensive segments by deepening software-hardware integration for automated pencil beam scanning validation workflows. Defend margin position through captive calibration service networks in California and Massachusetts oncology clusters where third-party laboratory partnerships are unbundling traditional procurement patterns. Prioritize IEC 60601-2-64 certification pipeline acceleration to compress commissioning timelines for new installations. For New Entrants and Emerging Players: Independent calibration laboratory partnerships offer the most penetrable channel for service-only market entry, particularly in United States proton therapy centers separating hardware acquisition from multi-year maintenance agreements. Target China's emerging particle therapy procurement channels as NMPA GB standards evolve, capturing first-mover positioning before Western vendor consolidation solidifies. Lead with software companion development for existing electrometer installations rather than competing head-to-head on detector hardware manufacturing. For Investors and Strategic Acquirers: Roll-up economics work for independent calibration laboratory networks because geographic density in proton therapy clusters enables fixed-cost leverage across multi-site service contracts. Five-to-ten year viability hinges on regulatory documentation mandates sustaining replacement demand regardless of new installation rates. Target acquisition archetypes: regional service laboratories with FDA 21 CFR Part 820 quality system certifications in underserved United States markets. Watch NMPA GB standard finalization timing as inflection indicator for Chinese market access protocols.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR post-market surveillance mandates compress documentation upgrade timelines for European oncology centers. |
| Software-Hardware Platform Integration | Automated traceable dose calibration chains command premium positioning in FDA-regulated United States markets. |
| Independent Calibration Laboratory Partnership | Service unbundling in California and Massachusetts enables third-party capture of multi-year maintenance contracts. |
| Pencil Beam Scanning Validation Development | Sub-millimeter detector specifications expand addressable market as facilities transition from passive scattering systems. |
| China NMPA GB Standard Pre-Positioning | Western vendors capture first-mover advantage as Beijing and Shanghai hospital procurement channels open to compliant equipment. |
Research Methodology
Coverage spans Germany, Japan, the United States, and China, with primary inputs from each market's distinct regulatory and procurement environment. Medical physicists, hospital purchasing committee members, biomedical engineers specializing in particle therapy suites, and GPO contracts managers provided structured interviews on equipment specification workflows and replacement cycle timing. Secondary validation drew from FDA 510(k) filings for beam calibration systems, EU MDR technical documentation databases, PMDA pre-market certification records, and hospital procurement contract disclosures. Bottom-up equipment unit estimates triangulated against top-down oncology center capital expenditure benchmarks.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include product type, technology adoption stage, application workflow, and end-user procurement authority. CAGRs derive from fitted trend analysis incorporating regulatory milestone timing, facility installation pipelines, and replacement cycle compression factors. Industry-specific forecast inputs encompass pencil beam scanning transition rates and medical physics specialist availability constraints in metropolitan clusters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA GB standard evolution timing and carbon ion therapy infrastructure buildout pacing in Japan. Forecasts reflect documented assumptions on regulatory enforcement consistency and hospital capital allocation priorities. A small set of named triggers warrants ongoing watch: EU MDR audit intensity escalation, United States independent laboratory network consolidation, and China domestic equipment certification reciprocity agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Apheresis Equipment Market
Medical Equipment
US Biomedical Refrigerators and Freezers Market
Medical Equipment
Global Renal Dialysis Equipment Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Refurbished Medical Equipment Market
Medical Equipment
Medical Oxygen Gas Cylinder Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Medical Equipment Maintenance Market
Medical Equipment
US Durable Medical Equipment Market
Medical Equipment
Global Blood Viscometer Market
Medical Equipment
Solar Powered Vaccine Refrigerator Market
Medical Equipment
Electric Bed Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
North America Medical Automation Market
Medical Equipment
Europe Nuclear Medicine Equipment Market