
 Asia-Pacific Surgical Glue Market | 2026-2036
Asia-Pacific Surgical Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surgical Glue Market Insights
Capital-intensity divergence between integrated multinationals and regional specialists is reorganizing competitive dynamics across the Asia-Pacific surgical glue landscape. Johnson & Johnson (Ethicon, Inc.) leverages its captive polymer supply chain to control input costs across cyanoacrylate formulations. Medtronic PLC anchors its position through deep R&D partnerships with Japanese teaching hospitals on cardiovascular applications. Baxter International Inc competes by extending its fibrin sealant portfolio into military medical procurement channels across Australia and South Korea.
Asia-Pacific surgical glue comprises tissue-adhesive formulations—primarily cyanoacrylate, fibrin, albumin, and synthetic polymer compounds—engineered to bond biological tissues without sutures or mechanical fasteners, with curing times typically under sixty seconds and tensile strength specifications varying by substrate. These adhesives serve to reduce operative time, minimize scarring, and eliminate needle-stick risks in open and minimally invasive procedures. Cyanoacrylate products dominate current volume owing to instant polymerization and broad surgical applicability, while fibrin-based systems command premium positioning in hemostasis-critical neurosurgery and cardiovascular procedures where bioresorbability determines reimbursement eligibility. Synthetic polymer segments show the fastest structural expansion as manufacturers reformulate to meet PMDA and CDSCO biocompatibility benchmarks without animal-derived components.
Japan's PMDA, India's CDSCO, and China's NMPA collectively enforce escalating biocompatibility and sterility standards that filter subscale suppliers from hospital tender processes. The EU MDR's extraterritorial influence on CE-marked imports further compresses market access for uncertified regional manufacturers. Stakeholders must monitor regulatory harmonization timelines between ASEAN national regulators and major economy standards to anticipate which formulation categories will face accelerated approval pathways or extended clinical trial requirements.
Market Dynamics
Japan's PMDA biocompatibility tightening is compressing supplier margins and forcing reformulation investments across cyanoacrylate and fibrin product lines, redistributing market share toward polymer chemistry specialists with captive testing infrastructure.
Growth Catalysts
- Cardiac surgery volume expansion:China's tier-one cities report rising procedural counts for valve replacements and coronary bypasses, driving consumption of high-tensile sealants in thoracic applications.
- CDSCO streamlined pathways:India's regulator introduced accelerated approval tracks for Class C implantable adhesives with predicate device equivalence, shortening market entry timelines for reformulated synthetics.
- Needle-stick risk elimination:Australian occupational health mandates in surgical theaters are converting suture-dependent procedures to adhesive closure in dermatology and plastic surgery units.
Market Restraints
- Butyl cyanoacrylate monomer supply:Feedstock concentration among three Northeast Asian chemical producers creates input cost volatility that squeezes formulation margins.
- Animal-derived fibrin sourcing:Bovine and human plasma dependency exposes manufacturers to batch-to-batch inconsistency and viral screening cost escalation.
- PMDA bioresorbability documentation:Japan's regulator demands extended degradation studies for cardiovascular applications, extending clinical trial phases by eighteen to twenty-four months.
Strategic Opportunities
- Vietnam's private hospital expansion:Ho Chi Minh City and Hanoi surgical centers are upgrading to minimally invasive suites, creating first-mover advantage for synthetic polymer adhesives without animal components.
- Military medical procurement:Australia's Defence Health Program and South Korea's Armed Forces Medical Command are formalizing battlefield trauma adhesive specifications, opening dedicated supply contracts.
- 3D-printed tissue scaffold integration:Convergence of bioadhesive deposition with additive manufacturing enables patient-specific wound closure in reconstructive maxillofacial surgery.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in bioresorbable synthetic polymers concentrates in Japanese and South Korean research institutes, constraining regional expansion.
- ASEAN regulatory harmonization delays:Divergent sterility testing protocols between Thailand, Indonesia, and Malaysia force redundant certification cycles for multi-country distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surgical Glue Market |
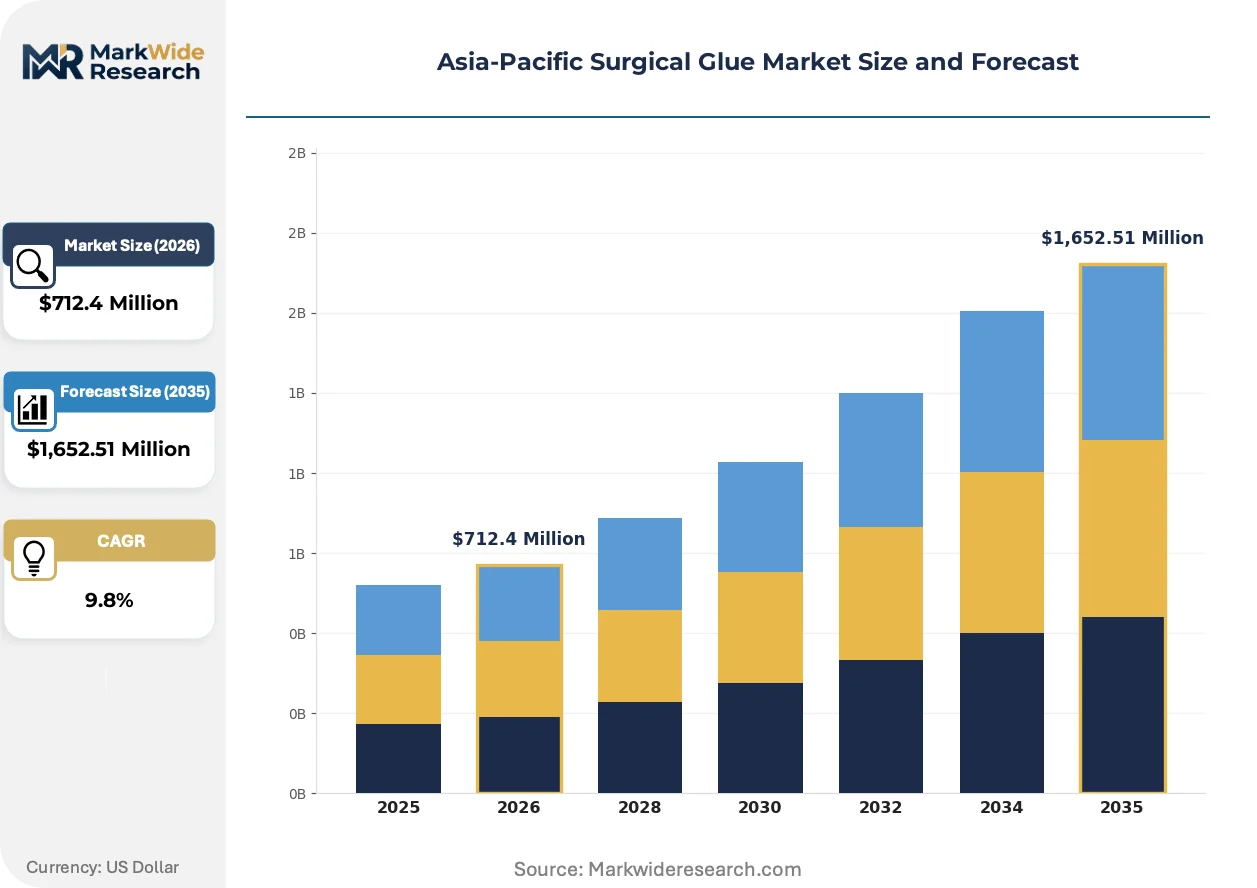
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,652.51 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cyanoacrylate, Fibrin, Albumin, Synthetic Polymer Application: Wound Closure, Bone Repair, Cardiovascular Procedures, Neurosurgery End User: Hospitals, Outpatient Surgical Centers, Ambulatory Surgical Centers, Military Medical Facilities Distribution Channel: Direct Sales, Retail Pharmacies, E-commerce, Wholesalers |
| Companies Covered | Johnson & Johnson (Ethicon, Inc.), Medtronic PLC, Baxter International Inc, B. Braun Melsungen AG, Integra LifeSciences Corporation, Artivion, Inc, Becton, Dickinson, and Company, Stryker Corporation, 3M, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surgical Glue Market Trends and Innovations
Formulation chemistry is pivoting toward animal-free synthetic platforms as biocompatibility standards harden, while procurement patterns favor suppliers with integrated sterile manufacturing rather than toll-production arrangements.
Light-activated synthetic polymer adhesives is fragmenting the instant-cure segment long dominated by moisture-triggered cyanoacrylates. Cardiac surgery departments in Tokyo and Osaka teaching hospitals are piloting these systems for precise dosing control. The technology is fragmenting procurement decisions by separating premium cardiovascular applications from commoditized skin closure.
PMDA's 2024 biocompatibility guidance revision tightened leachable testing thresholds for implantable adhesives. Manufacturers must now submit accelerated aging data under ISO 10993-6 protocols for all cardiovascular indications. Synthetic polymer categories face the steepest compliance burden, driving consolidation toward integrated chemistry-and-testing operations.
Hospital procurement committees are consolidating vendor lists to single-source contracts with full sterile manufacturing traceability. Australian and South Korean health systems are replacing multi-supplier spot purchasing with two-year framework agreements bundling adhesives, applicators, and training. This pattern concentrates volume with Ethicon, Medtronic, and Baxter while marginalizing toll-dependent regional competitors.
Asia-Pacific Surgical Glue Market Segmentation
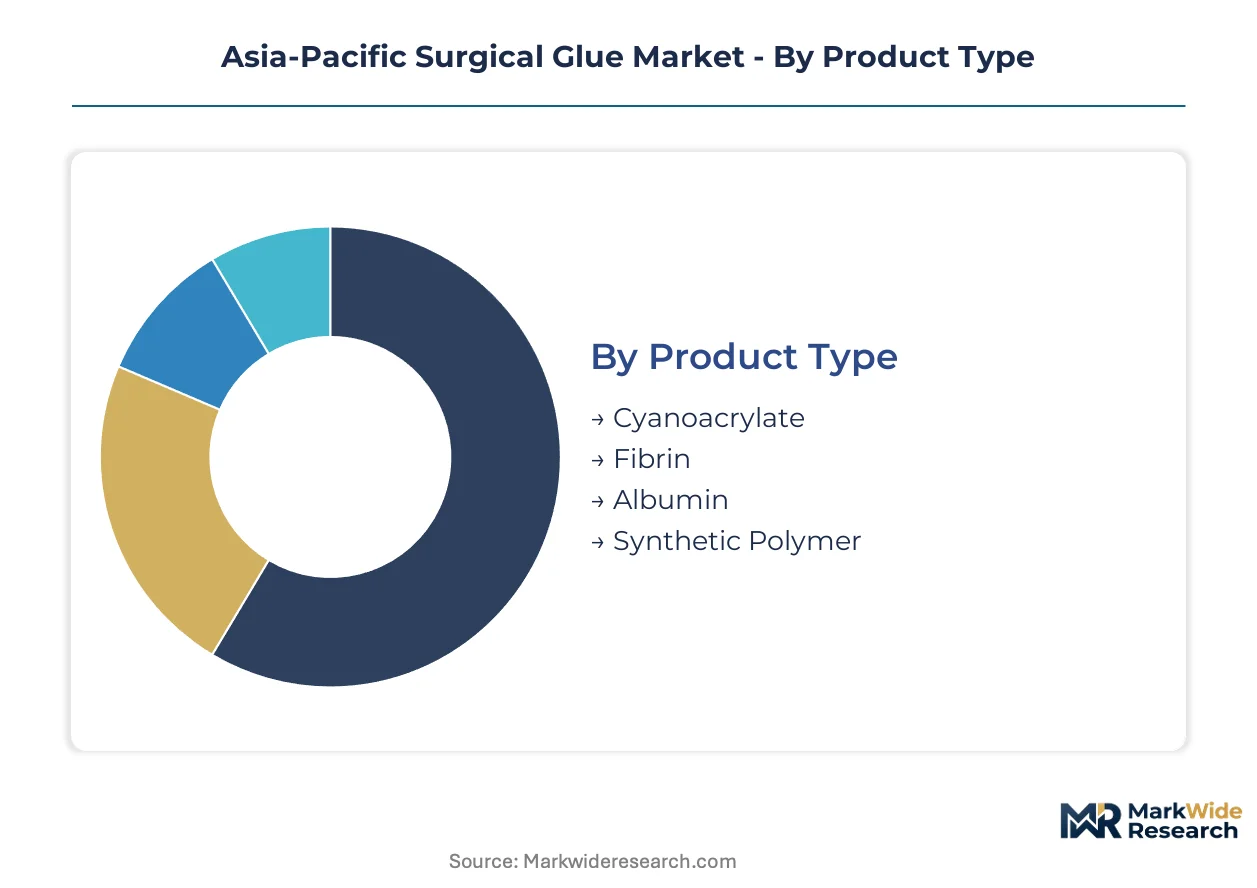
Surgical glue formulation chemistry and application specificity determine reimbursement eligibility and procurement tier placement across Asia-Pacific health systems. Segment boundaries shift as PMDA, CDSCO, and NMPA biocompatibility benchmarks force reformulation investments and redirect volume toward compliant categories.
Product Type:
PMDA's tightened leachable thresholds and CDSCO's predicate device pathways create divergent compliance costs across adhesive chemistries, filtering supplier participation by testing infrastructure depth.
- Cyanoacrylate:Butyl and octyl ester formulations deliver sub-60-second polymerization through moisture-triggered anionic chain reaction. China's tier-one cardiac surgery units in Beijing and Shanghai consume high-tensile variants for sternal closure, though butyl monomer feedstock concentration among three Northeast Asian chemical producers injects margin volatility.
- Fibrin:Bovine and human plasma-derived sealants provide bioresorbable hemostasis with natural clotting cascade integration. Tokyo and Osaka teaching hospitals anchor regional demand for cardiovascular applications where PMDA demands extended degradation studies stretching clinical timelines.
- Albumin:Cross-linked protein adhesives offer intermediate strength for soft tissue approximation without synthetic monomer leachable concerns.
- Synthetic Polymer:Light-activated and moisture-cure platforms bypass animal-derived component variability while meeting tightening biocompatibility documentation requirements.
Cyanoacrylate handles the majority of throughput; synthetic polymer is the fastest mover on share.
Application:
Procedure reimbursement rates and operative time economics concentrate adhesive selection in high-volume surgical service lines.
- Wound Closure:Skin and superficial tissue bonding in dermatology and plastic surgery units converts suture-dependent procedures under Australian occupational health mandates eliminating needle-stick exposure.
- Bone Repair:Orthopedic trauma and maxillofacial reconstruction applications demand osteoconductive adhesive properties with load-bearing cure strength.
- Cardiovascular Procedures:Valve replacement and coronary bypass volumes in China's tier-one cities drive consumption of high-tensile sealants where bioresorbability determines NMPA reimbursement eligibility. PMDA documentation requirements for implantable cardiovascular adhesives extend approval phases substantially.
- Neurosurgery:Dural closure and hemostasis-critical applications command premium positioning for fibrin-based systems with batch-to-batch consistency safeguards.
Wound closure generates the largest procedure volume; cardiovascular procedures are climbing the fastest on adhesive intensity per case.
End User:
Capital equipment integration and sterile supply chain maturity stratify purchasing authority across facility types.
- Hospitals:Integrated surgical suites with captive sterilization infrastructure command vendor consolidation to single-source contracts bundling adhesives, applicators, and training.
- Outpatient Surgical Centers:Dermatology and minor procedure focus drives spot purchasing of cyanoacrylate skin adhesives with minimal applicator complexity.
- Ambulatory Surgical Centers:Minimally invasive suite upgrades in Ho Chi Minh City and Hanoi create first-mover openings for synthetic polymer platforms.
- Military Medical Facilities:Australia's Defence Health Program and South Korea's Armed Forces Medical Command formalize battlefield trauma adhesive specifications through dedicated procurement channels.
Hospitals absorb the dominant share of volume; military medical facilities are expanding most quickly on formalized specification programs.
Distribution Channel:
Traceability requirements and sterile handling protocols determine channel viability by adhesive category.
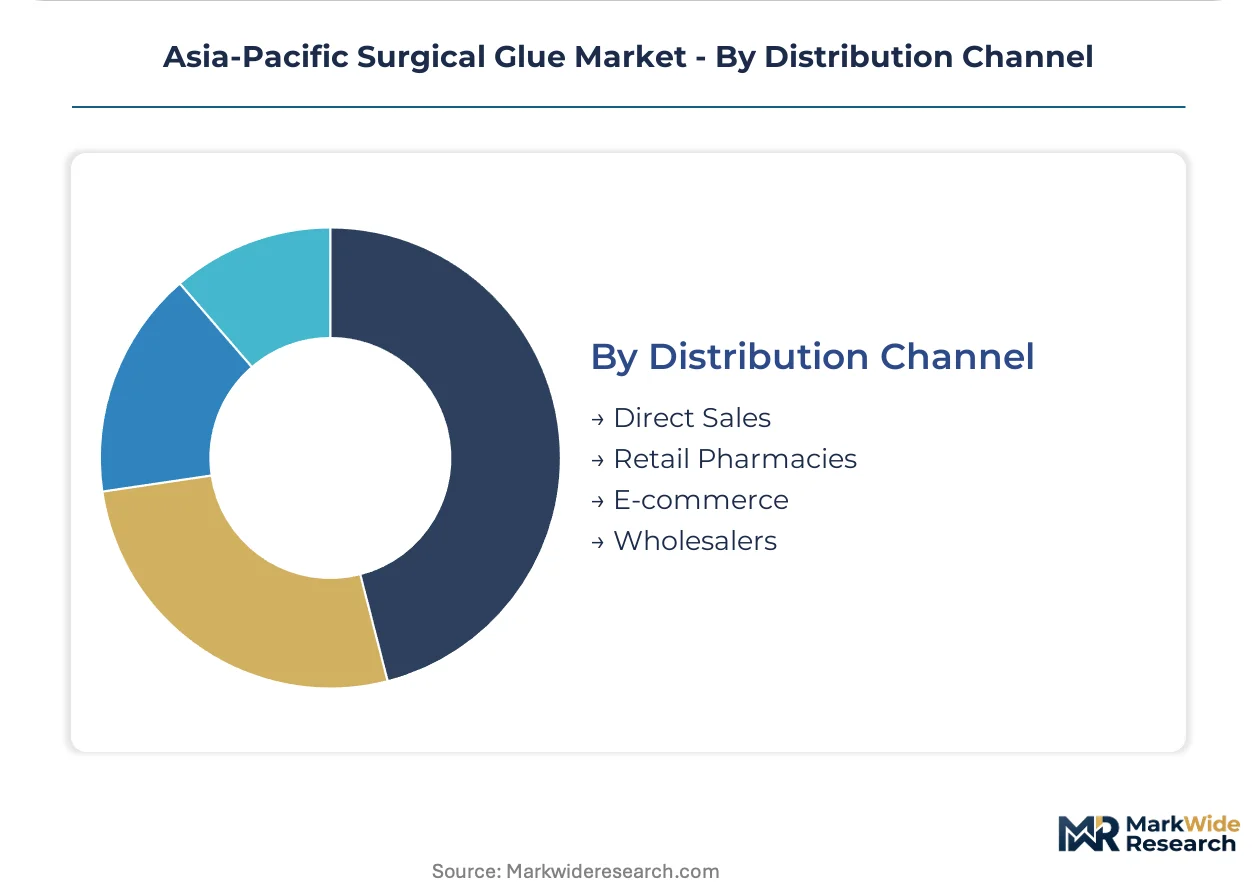
- Direct Sales:Manufacturer-to-hospital relationships support framework agreements with full sterile manufacturing documentation required by Australian and South Korean health system consolidations.
- Retail Pharmacies:Over-the-counter skin adhesive access concentrates in consumer wound care segments outside institutional procurement.
- E-commerce:Digital procurement penetration remains limited by cold-chain and sterility assurance requirements for implantable formulations.
- Wholesalers:Multi-country distribution faces redundant certification cycles from divergent ASEAN sterility testing protocols between Thailand, Indonesia, and Malaysia.
Direct sales captures the highest-value transactions; e-commerce faces the steepest structural barriers to expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's cardiac surgery units consume high-tensile sealants at intensities unmatched elsewhere in the region, while Japan's teaching hospitals anchor premium fibrin demand through extended bioresorbability documentation requirements.
China
Beijing and Shanghai cardiac centers report rising valve replacement and coronary bypass volumes that drive consumption of implantable adhesives. NMPA reimbursement eligibility hinges on bioresorbability documentation, filtering supplier participation by clinical data depth. The Yangtze River Delta surgical corridor concentrates procurement authority in tier-one hospital networks upgrading to minimally invasive suites.
Japan
Tokyo and Osaka teaching hospitals pilot light-activated synthetic polymers for precise cardiovascular dosing control. PMDA's 2024 biocompatibility guidance revision tightened leachable testing thresholds, extending clinical trial phases by eighteen to twenty-four months. Kanto region medical device clusters house integrated chemistry-and-testing operations that absorb compliance burden.
India
Maharashtra and Karnataka hospital networks scale adoption of advanced wound closure methods across dermatology and plastic surgery units. CDSCO introduced accelerated approval tracks for Class C implantable adhesives with predicate device equivalence, shortening market entry timelines for reformulated synthetics. Mumbai and Bengaluru surgical centers convert suture-dependent procedures under occupational health mandates.
Australia
New South Wales and Victoria health systems consolidate vendor lists to single-source contracts bundling adhesives, applicators, and training. Australian occupational health mandates in surgical theaters eliminate needle-stick exposure through adhesive closure conversion. The Defence Health Program formalizes battlefield trauma adhesive specifications through dedicated procurement channels.
South Korea
Seoul Capital Area cardiac surgery volumes rise alongside population aging and procedural access expansion. The Armed Forces Medical Command structures battlefield trauma adhesive procurement through formalized specification programs. Busan-Ulsan chemical manufacturing corridors supply butyl cyanoacrylate monomer feedstock to regional formulators.
Asia-Pacific Surgical Glue Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with chemistry-and-testing integration determining competitive survival. The upper tier controls captive polymer supply chains and sterile manufacturing infrastructure, while mid-scale competitors face margin compression from toll-production dependency. Two strategic archetypes dominate: integrated multinationals with backward polymer control, and regional specialists with deep teaching hospital relationships. Competitive moves concentrate on vendor list consolidation capture and military medical procurement channel formalization.
Among integrated multinational anchors, Johnson & Johnson (Ethicon, Inc.) and Medtronic PLC occupy positions defined by supply chain depth and clinical partnership density. Baxter International Inc exemplifies the military-medical procurement specialist archetype. These three entities represent the structural poles around which Australian and South Korean health system consolidations organize their framework agreements.
| Leading Market Players |
|---|
| Johnson & Johnson (Ethicon, Inc.) |
| Medtronic PLC |
| Baxter International Inc |
| B. Braun Melsungen AG |
| Integra LifeSciences Corporation |
| Artivion, Inc |
| Becton, Dickinson, and Company |
| Stryker Corporation |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Synthetic polymer feedstock substitution for animal-derived fibrin is redrawing procurement geography across the Asia-Pacific surgical glue landscape, compressing margins for bovine plasma-dependent formulators while elevating pricing power for integrated polymer chemistry specialists with captive butyl cyanoacrylate supply.
Pricing Analysis
After-sales bundling of applicator systems and surgical training programs drives lifetime value capture for adhesive suppliers. Three-tier pricing structure across premium cardiovascular sealants, standard wound closure formulations, and economy-grade skin adhesives stratifies procurement tiers, with PMDA biocompatibility certification commanding substantial brand premium. Cost compression in fibrin-based lines is intensifying because bovine plasma screening expenses escalate, while Australian hospital systems exhibit highest price sensitivity due to consolidated single-source contracting mandates.
Supply Chain Analysis
Busan-Ulsan chemical corridors and Northeast Asian monomer facilities constitute the critical chokepoint for butyl cyanoacrylate feedstock that underwrites regional formulation capacity. Manufacturing draws from South Korean petrochemical clusters, Japanese specialty chemical producers, and Chinese intermediates suppliers, with raw material flows resting on bovine plasma collection networks and synthetic polymer precursor streams. Single-source vulnerability concentrates in butyl monomer production among three Northeast Asian chemical producers. Distribution runs through direct manufacturer-to-hospital framework agreements with full sterile traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against light-activated synthetic polymer platforms that threaten to displace moisture-cure cyanoacrylates in premium cardiovascular applications.
For Market Incumbents: Compound defensive positioning through backward integration into butyl cyanoacrylate monomer production and captive biocompatibility testing infrastructure that absorbs PMDA compliance burden. Secure vendor list consolidation in Australian and South Korean health systems before regional specialists achieve sterile manufacturing certification. The light-activated polymer threat accelerates reformulation timelines. For New Entrants and Emerging Players: Military medical procurement specification gaps in Australia's Defence Health Program and South Korea's Armed Forces Medical Command present white-space targets where integrated incumbents lack dedicated battlefield trauma focus. Vietnam's private hospital expansion in Ho Chi Minh City and Hanoi offers the most penetrable geography for animal-free synthetic platforms. Pursue direct sales relationships with upgrading ambulatory surgical centers rather than contested hospital vendor lists. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators possessing CDSCO predicate device approvals but lacking sterile manufacturing infrastructure. Long-term viability hinges on chemistry-and-testing integration depth rather than formulation IP alone. Watch PMDA-ASEAN regulatory harmonization progress as the inflection signal for accelerated approval pathway access.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Biocompatibility Certification Investment | Extended degradation studies for cardiovascular applications filter subscale competitors from Tokyo teaching hospital procurement. |
| CDSCO Accelerated Approval Pathway Navigation | Predicate device equivalence for Class C implantable adhesives shortens market entry timelines for reformulated synthetics in Maharashtra networks. |
| Military Medical Procurement Channel Formalization | Australia's Defence Health Program and South Korea's Armed Forces Medical Command create dedicated supply contracts with specification barriers. |
| Synthetic Polymer Platform Development | Animal-free formulations bypass bovine plasma variability while meeting tightening PMDA leachable thresholds. |
| Single-Source Framework Agreement Capture | Hospital vendor list consolidation in New South Wales and Victoria concentrates volume with full sterile manufacturing traceability. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across surgical glue value chains, including cardiac surgeons at Tokyo and Shanghai teaching hospitals, biomedical engineers in Kanto region medical device clusters, hospital procurement committee members in Australian state health systems, and polymer chemists at South Korean research institutes. Secondary validation drew from PMDA submission databases, CDSCO device approval records, NMPA reimbursement eligibility listings, and hospital procurement contract disclosures. Bottom-up adhesive consumption modeling and top-down market sizing triangulated volume estimates.
Across the analysis window, projections segment by formulation chemistry, application specificity, end-user facility type, and distribution channel structure. CAGRs derive from procedure volume trajectories in China's tier-one cardiac centers, regulatory approval timeline assumptions for PMDA cardiovascular indications, and military medical procurement formalization patterns. Forecast inputs incorporate butyl cyanoacrylate monomer supply concentration dynamics and biocompatibility standard escalation curves.
Underlying assumptions cover PMDA-ASEAN regulatory harmonization timelines and bovine plasma supply stability, with deviation risk concentrated in synthetic polymer feedstock cost volatility and CDSCO predicate device pathway utilization rates. Practitioners should keep alternative scenarios live as biocompatibility documentation requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Ultrasound Conductivity Gels Market
Medical Supplies
Resuscitation Masks Market
Medical Supplies
United States Hospital Supplies Market
Medical Supplies
Serum Separating Tubes Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Ostomy Drainage Bags Market
Medical Supplies
Tissue Glue and Bio-Adhesive Sealants Market
Medical Supplies
Colostomy Bags Market
Medical Supplies
Smart Face Masks Market
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Cosmetic Pipette Market
Medical Supplies
Cryopreservation & Fertilization Media Market