
 Ultrasound Conductivity Gels Market | 2026-2036
Ultrasound Conductivity Gels Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound Conductivity Gels Market Outlook
ISO 13485 certification is reorganizing competitive standing in ultrasound conductivity gels, filtering out suppliers lacking quality management systems for medical device accessories. Parker Laboratories, Inc. leverages decades of clinical brand recognition to sustain hospital formulary placement across North America. Cardinal Health, Inc. anchors distribution through its integrated medical supply chain, controlling procurement channels that competitors struggle to penetrate. Eco-Med Diagnostic Imaging specializes in veterinary-specific formulations, occupying a defensible niche where regulatory requirements differ from human medical standards.
Ultrasound conductivity gels are viscous, acoustically transparent media formulated with water, propylene glycol, and humectants to eliminate air gaps between transducer and tissue, ensuring unimpeded transmission of sound waves at frequencies between two and fifteen megahertz. Water-based gel dominates hospital purchasing due to lowest cost per procedure and broad compatibility with equipment from multiple manufacturers, though silicone gel commands premium positioning in aesthetic practices where residue-free removal enhances patient experience. Diagnostic imaging applications generate the largest volume demand, while therapeutic ultrasound segments offer higher per-unit margins through specialized conductive pastes formulated for deep tissue penetration.
FDA biocompatibility requirements under ISO 10993 and the European Medical Device Regulation (MDR) compel reformulation away from parabens and synthetic fragrances, raising compliance costs but also creating barriers against low-cost imports. The EPA monitors manufacturing discharge of propylene glycol derivatives, adding environmental compliance layers that favor scaled domestic producers with wastewater treatment infrastructure. Stakeholders must monitor evolving sterilization validation standards for single-use sachets, as regulators on both sides of the Atlantic tighten microbial burden specifications for gels used in invasive-adjacent procedures.
Market Dynamics
Hospital consolidation across the United States is compressing supplier margins through standardized purchasing agreements while simultaneously filtering out regional gel manufacturers lacking ISO 13485 certification.
Growth Catalysts
- FDA biocompatibility updates:Reformulation mandates under ISO 10993 are accelerating manufacturer investment in hypoallergenic bases, raising barriers against low-cost imports.
- Diagnostic imaging centers:Infection control protocols are expanding procurement of sterile single-use gel sachets, creating volume demand for specialized packaging formats.
- Propylene glycol derivatives:Humectant chemistry advances are improving acoustic transparency across two-to-fifteen megahertz frequency ranges.
Market Restraints
- EPA wastewater discharge rules:Manufacturing facilities lacking on-site treatment infrastructure face compliance cost penalties that favor scaled domestic producers.
- Paraben elimination costs:European MDR-driven reformulation is raising per-unit production expenses without corresponding price recovery mechanisms.
- Silicone gel substitution ceiling:Premium residue-free formulations remain confined to aesthetic practices due to cost incompatibility with high-volume hospital purchasing.
Strategic Opportunities
- Veterinary diagnostic imaging:Regulatory divergence from human medical standards creates defensible niche positioning for specialized conductivity formulations.
- Single-use sachet sterilization:Tightening microbial burden specifications for invasive-adjacent procedures favor early movers in validated sterile packaging.
- Therapeutic ultrasound pastes:Deep tissue penetration formulations command higher per-unit margins than standard diagnostic gels.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation delays exclude smaller manufacturers from hospital formulary placement.
- Legacy equipment compatibility:Reformulated gel chemistries must maintain acoustic performance across transducer fleets spanning multiple equipment generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound Conductivity Gels Market |
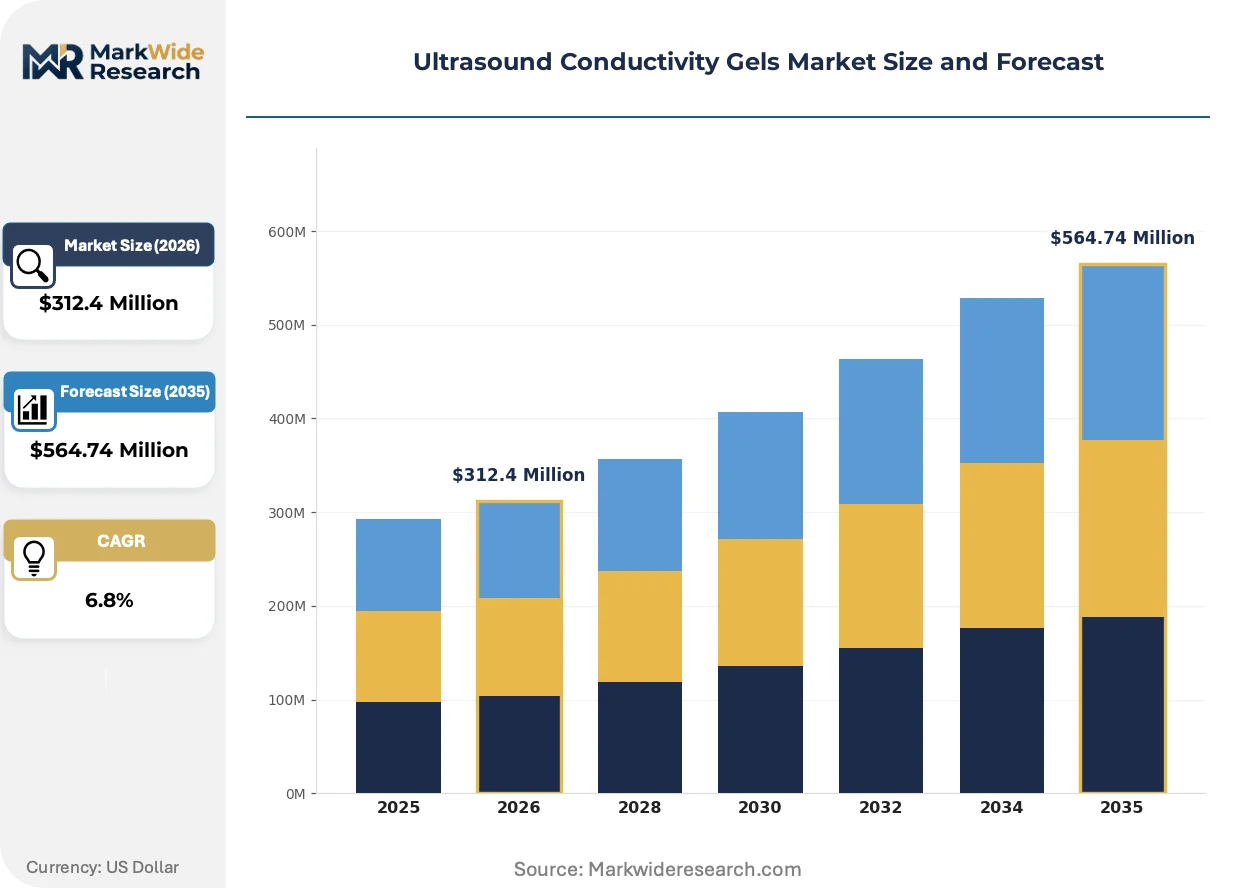
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Gel, Silicone Gel, Alcohol-Based Gel, Conductive Paste Application: Diagnostic Imaging, Therapeutic Ultrasound, Aesthetic Procedures, Veterinary Applications End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Packaging Type: Bulk Containers, Individual Sachets, Tubes, Jars |
| Companies Covered | Medline Industries Inc., Parker Laboratories, Inc., Cardinal Health, Inc., Roscoe Medical, Eco-Med Diagnostic Imaging, National Therapy Products Inc., DJO Global, Inc., Pharmaceutical Innovation Inc., Modul Diagram S.r.l, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound Conductivity Gels Market Strategic Shifts
Water-based gel chemistry is advancing alongside packaging sterilization methods, while procurement centralization is reshaping how manufacturers access hospital buyers.
Sterile single-use gel sachets are supplanting multi-use bottles in diagnostic imaging centers. Infection control officers at consolidated hospital systems are mandating unit-dose formats for invasive-adjacent procedures. This shift is compressing demand for bulk container formats while expanding specialized packaging capacity requirements.
European MDR biocompatibility standards are forcing paraben and synthetic fragrance elimination from conductivity gel formulations. Manufacturers serving EU markets are absorbing reformulation costs and extended validation timelines. Water-based gel categories face the steepest compliance burden due to preservative chemistry dependencies.
Hospital purchasing departments are consolidating supplier rosters through integrated medical supply chain partnerships. Cardinal Health and similar distributors are capturing procurement channel control, displacing direct manufacturer relationships. This concentration is most visible in United States markets where health system mergers have reduced independent buying entities.
Ultrasound Conductivity Gels Market Segmentation
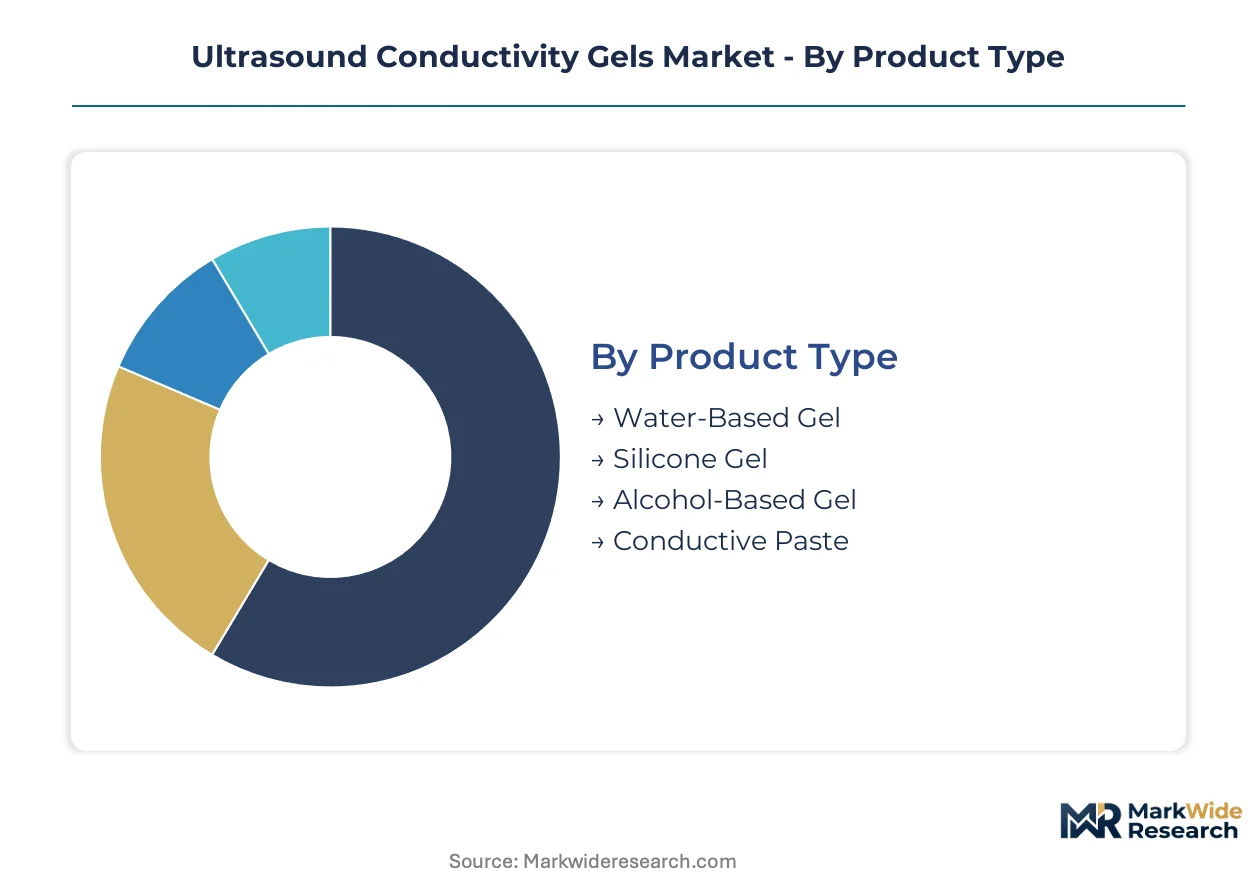
Segmentation in ultrasound conductivity gels reveals how procurement channels, clinical applications, and packaging formats fragment demand across distinct customer workflows. Understanding these divisions exposes where margin concentration and volume scale diverge most sharply.
Product Type:
Hospital procurement channels favor water-based formulations for their cost efficiency and broad equipment compatibility, while aesthetic practices and specialty clinics route premium silicone variants through distributor networks focused on patient experience.
- Water-Based Gel:Formulated with propylene glycol, humectants, and purified water to achieve acoustic transparency across two-to-fifteen megahertz frequencies. Demand concentrates in United States hospital systems where standardized purchasing agreements favor lowest cost-per-procedure options; bulk container formats dominate this channel due to high daily procedure volumes.
- Silicone Gel:Synthetic polymer base eliminates residue and enables rapid cleanup between patients. Aesthetic practices in metropolitan United States markets absorb premium pricing for residue-free removal that enhances patient satisfaction scores; this segment routes through specialty medical distributors rather than hospital supply chains.
- Alcohol-Based Gel:Rapid-drying antiseptic formulations serve point-of-care diagnostic environments where infection control protocols demand concurrent skin preparation.
- Conductive Paste:Viscous compounds formulated for therapeutic ultrasound applications requiring sustained skin contact during deep tissue penetration procedures.
By volume, water-based gel leads. By growth pace, silicone gel is gaining share fastest.
Application:
Cost tiers separate diagnostic imaging's high-volume, low-margin workflows from therapeutic and aesthetic segments where specialized formulations command pricing premiums.
- Diagnostic Imaging:Standard gel formulations serve radiology departments performing abdominal, cardiac, and obstetric ultrasound examinations. United States diagnostic imaging centers are expanding sterile single-use sachet procurement as infection control officers mandate unit-dose formats; this shift compresses bulk container demand while expanding specialized packaging requirements.
- Therapeutic Ultrasound:Deep tissue penetration pastes formulated with enhanced viscosity for sustained acoustic coupling during physical therapy and pain management protocols. Sports medicine clinics and rehabilitation centers absorb higher per-unit costs for specialized conductive media that maintains coupling through extended treatment durations.
- Aesthetic Procedures:Residue-free gel requirements for facial and body contouring applications where patient comfort ratings influence practice reputation.
- Veterinary Applications:Regulatory divergence from human medical standards permits formulation flexibility; specialized suppliers occupy defensible positioning in companion animal and livestock diagnostic markets.
Diagnostic imaging generates the steepest volume trajectory. Therapeutic ultrasound offers the widest margin expansion.
End User:
Customer type determines whether procurement flows through integrated supply chains, direct manufacturer relationships, or specialty distributor networks.
- Hospitals:Consolidated health systems in the United States compress supplier margins through standardized formulary agreements that filter out uncertified manufacturers. Cardinal Health and similar distributors capture procurement channel control, displacing direct manufacturer access.
- Diagnostic Centers:Independent imaging facilities and hospital-affiliated outpatient centers balance cost sensitivity with infection control mandates. These entities are accelerating sterile single-use sachet adoption ahead of regulatory mandates to preempt accreditation scrutiny.
- Research Laboratories:Academic medical centers and contract research organizations require gel formulations with documented biocompatibility validation for clinical trial protocols.
- Clinics:Physician-owned practices and urgent care facilities purchase through group purchasing organizations or direct from manufacturers based on procedure volume thresholds.
Hospitals anchor volume concentration. Diagnostic centers are climbing the fastest on sterile packaging conversion.
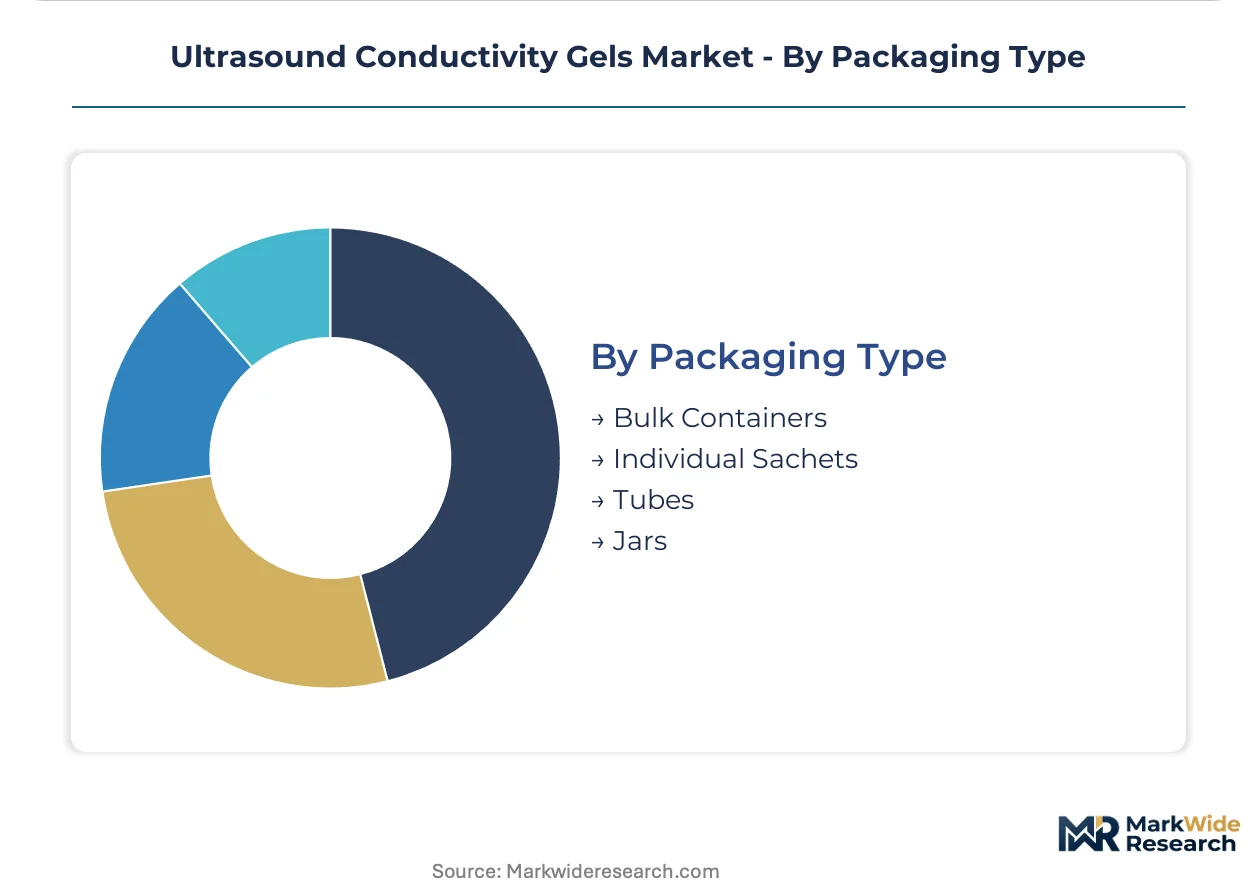
Packaging Type:
Supply concentration favors scaled domestic producers with validated sterilization infrastructure for single-use formats.
- Bulk Containers:Multi-liter bottles and pump dispensers serve high-throughput hospital radiology departments where cost-per-milliliter optimization outweighs infection control concerns. United States hospital consolidation reinforces demand for this format through centralized purchasing of standardized supplies.
- Individual Sachets:Pre-sterilized unit-dose packets eliminate cross-contamination risk in invasive-adjacent procedures. FDA microbial burden specification tightening and European MDR alignment are accelerating validation investments by early-moving manufacturers.
- Tubes:Portable squeeze formats serve mobile diagnostic services and point-of-care applications requiring controlled dispensing.
- Jars:Wide-mouth containers accommodate therapeutic paste application with spatulas in physical therapy settings.
Bulk containers maintain volume leadership. Individual sachets are expanding most quickly on infection control mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics infrastructure underwrites the Netherlands' role as a European distribution hub for sterile gel sachets bound for German and French hospital systems.
United States
Hospital consolidation across Texas, Florida, and California is compressing supplier margins through standardized formulary agreements. FDA biocompatibility updates under ISO 10993 are accelerating domestic reformulation investments. The Minneapolis-St. Paul medical device cluster anchors manufacturing capacity for hypoallergenic gel bases serving consolidated health systems.
Germany
Diagnostic imaging centers in Bavaria and North Rhine-Westphalia are expanding sterile single-use procurement ahead of EU MDR enforcement timelines. ECHA chemical registration requirements for propylene glycol derivatives are raising compliance barriers against non-EU imports. The Baden-Württemberg precision manufacturing corridor hosts specialized packaging validation facilities for medical device accessories.
China
NMPA medical device classification revisions are extending registration timelines for imported conductivity gels. The Yangtze River Delta pharmaceutical manufacturing belt is absorbing domestic production capacity for water-based formulations. Shanghai's port infrastructure enables re-export positioning for Southeast Asian diagnostic imaging markets.
Japan
PMDA quality management system inspections are filtering out uncertified suppliers from hospital procurement channels. METI medical device industry support programs are subsidizing domestic sterilization infrastructure investments. The Kansai region's Osaka-Kobe medical technology cluster concentrates formulation R&D for aging-population diagnostic applications.
India
CDSCO medical device rules are aligning with ISO 13485 certification requirements for imported gel products. The Maharashtra-Gujarat pharmaceutical manufacturing corridor is expanding domestic capacity for cost-competitive water-based formulations. Mumbai's logistics infrastructure supports distribution to diagnostic imaging centers across South Asian markets.
Ultrasound Conductivity Gels Market Competitive Environment
Listed leaders compete with private specialists across certification tiers, with ISO 13485 quality management credentials filtering the supplier base into distinct competitive strata. Hospital formulary placement concentrates around manufacturers with validated sterilization infrastructure for single-use sachet formats. Three archetypes dominate: integrated medical supply distributors, clinical brand recognition holders, and veterinary-focused niche specialists. M&A activity targets packaging sterilization capabilities, while geographic expansion concentrates on EU MDR compliance positioning.
Among North American market anchors, Parker Laboratories, Inc. exemplifies the clinical brand recognition archetype, while Cardinal Health, Inc. represents integrated supply chain control. Eco-Med Diagnostic Imaging occupies the veterinary specialization tier where regulatory divergence from human medical standards permits distinct formulation positioning. These three entities collectively illustrate how certification credentials, distribution channel control, and niche regulatory arbitrage define competitive separation in hospital procurement channels.
| Leading Market Players |
|---|
| Medline Industries Inc. |
| Parker Laboratories, Inc. |
| Cardinal Health, Inc. |
| Roscoe Medical |
| Eco-Med Diagnostic Imaging |
| National Therapy Products Inc. |
| DJO Global, Inc. |
| Pharmaceutical Innovation Inc. |
| Modul Diagram S.r.l |
| Others |
Value Chain & Pricing Dynamics
Water-based gel substitution for silicone formulations in high-volume hospital procurement is simultaneously shifting manufacturing gravity toward scaled domestic producers with wastewater treatment infrastructure and compressing per-unit margins through standardized formulary agreements. This dual restructuring concentrates pricing power among ISO 13485-certified suppliers while filtering out regional manufacturers lacking environmental compliance capabilities.
Pricing Analysis
Volume-discount tiering structures dominate hospital procurement channels, with three-tier pricing stratification across premium silicone, standard water-based, and economy bulk-container formats. Price differentiation hinges on certification grade—ISO 10993 biocompatibility validation commands measurable premiums—and geographic delivery cost differentials between domestic and imported supply. Pricing pressure stems from consolidated health system purchasing agreements that compress supplier margins without corresponding cost recovery mechanisms. Diagnostic imaging centers exhibit highest price sensitivity due to procedure-volume economics, while aesthetic practices absorb premium positioning for residue-free patient experience.
Supply Chain Analysis
Propylene glycol feedstock transit through Rotterdam's chemical logistics hub underwrites European formulation cost structures and creates single-source vulnerability for manufacturers lacking alternative humectant sourcing. Manufacturing concentrates in the United States, Germany, and China, with each node serving distinct regulatory compliance requirements. Raw material dependencies center on propylene glycol derivatives, purified water infrastructure, and sterilization-grade packaging films. Tariff exposure runs through Chinese NMPA registration delays that extend import timelines. Distribution runs through integrated medical supply chains—Cardinal Health and similar distributors capture procurement channel control, displacing direct manufacturer relationships with consolidated hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated sterilization infrastructure for single-use sachet formats represents the critical capability gap separating formulary-eligible suppliers from excluded competitors, with ISO 13485 certification timelines creating asymmetric barriers to hospital procurement access.
For Market Incumbents: Shield hospital formulary placement by accelerating sterile packaging capacity investments ahead of FDA microbial burden specification tightening. Deepen backward integration into propylene glycol supply through long-term offtake agreements with domestic chemical producers, insulating margin structures from ECHA registration cost volatility. For New Entrants and Emerging Players: Lead with veterinary diagnostic imaging as the most penetrable application segment, where regulatory divergence from human medical standards permits faster formulation iteration and defensible niche positioning. Route through specialty distributors serving companion animal clinics rather than competing directly for hospital supply chain access controlled by integrated incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed packaging sterilization specialists that lack gel formulation expertise but possess validated cleanroom infrastructure. Five-to-ten year viability depends on capturing EU MDR compliance positioning before enforcement timelines harden. Watch for FDA single-use sachet mandate signals as the inflection indicator for sterilization capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Quality management credentials filter hospital formulary access, excluding uncertified regional competitors from consolidated procurement channels. |
| Sterile Sachet Packaging Scale-Up | FDA microbial burden tightening and infection control mandates accelerate demand for validated unit-dose formats in invasive-adjacent procedures. |
| Backward Integration into Propylene Glycol | Captive humectant supply insulates margin structures from ECHA registration costs and EPA wastewater discharge compliance penalties. |
| Veterinary Formulation Specialization | Regulatory arbitrage in companion animal markets permits faster product iteration outside FDA biocompatibility validation timelines. |
| Hospital System Direct Partnership | Bypassing Cardinal Health distribution control restores manufacturer pricing power in consolidated health system procurement. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and veterinary diagnostic clinic operators; and secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital supply chain procurement records, and EPA environmental compliance disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers produced volume and value estimates.
Across the projection horizon, analytical frameworks modeled product type, application workflow, end-user procurement channel, and packaging format dimensions. CAGRs derived from procedure volume trajectories, regulatory compliance cost absorption rates, and sterilization infrastructure investment cycles. Forecast inputs incorporated FDA biocompatibility update implementation timelines and EU MDR enforcement progression patterns.
Underlying assumptions cover regulatory compliance cost pass-through rates and hospital consolidation pace, with deviation risk concentrated in FDA single-use sachet mandate timing and propylene glycol feedstock price volatility. Practitioners should keep alternative scenarios live as FDA sterilization validation standards and ECHA chemical registration requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Disposable Medical Gowns Market
Medical Supplies
US Hospital Gowns Market
Medical Supplies
Tattoo Needles Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
Pre-Packaged Medical Supplies Market
Medical Supplies
Global Burn Ointment Market
Medical Supplies
Blood Bag Tube Sealer Market
Medical Supplies
Global Safety Syringes Market
Medical Supplies
Medical Tapes and Bandages Market
Medical Supplies
Retractable Needle Safety Syringes Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Global Post Surgery Bras Market
Medical Supplies
Chlorhexidine Gluconate (CHG) Wipes Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
India Feminine Hygiene Market
Medical Supplies
Global Syringe Market