
 Latex Medical Disposables Market | 2026-2036
Latex Medical Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Latex Medical Disposables Market Outlook
Multi-source procurement strategies is realigning how hospital systems and distributors contract for latex glove volumes. Ansell leverages its vertically integrated manufacturing footprint across multiple geographies to sustain contract reliability. Hartalega Holdings Bhd anchors its competitive position through advanced nitrile-latex hybrid technologies, while Top Glove Corporation Bhd dominates bulk production scale for examination-grade disposables.
Latex medical disposables comprise single-use devices molded from natural rubber latex or synthetic polyisoprene, with tensile strength specifications typically exceeding 18 MPa and protein content controlled below detectable thresholds to minimize Type I hypersensitivity reactions. These products serve critical barrier-protection functions in surgical, diagnostic, and laboratory environments where cross-contamination prevention is non-negotiable. Gloves occupy the largest value share within product type segments, though catheters command premium pricing due to sterile manufacturing complexity and regulatory filing requirements. Hospital end users generate the most concentrated demand volume, while direct sales channels capture the highest margin pools by eliminating distributor markups on long-term supply agreements.
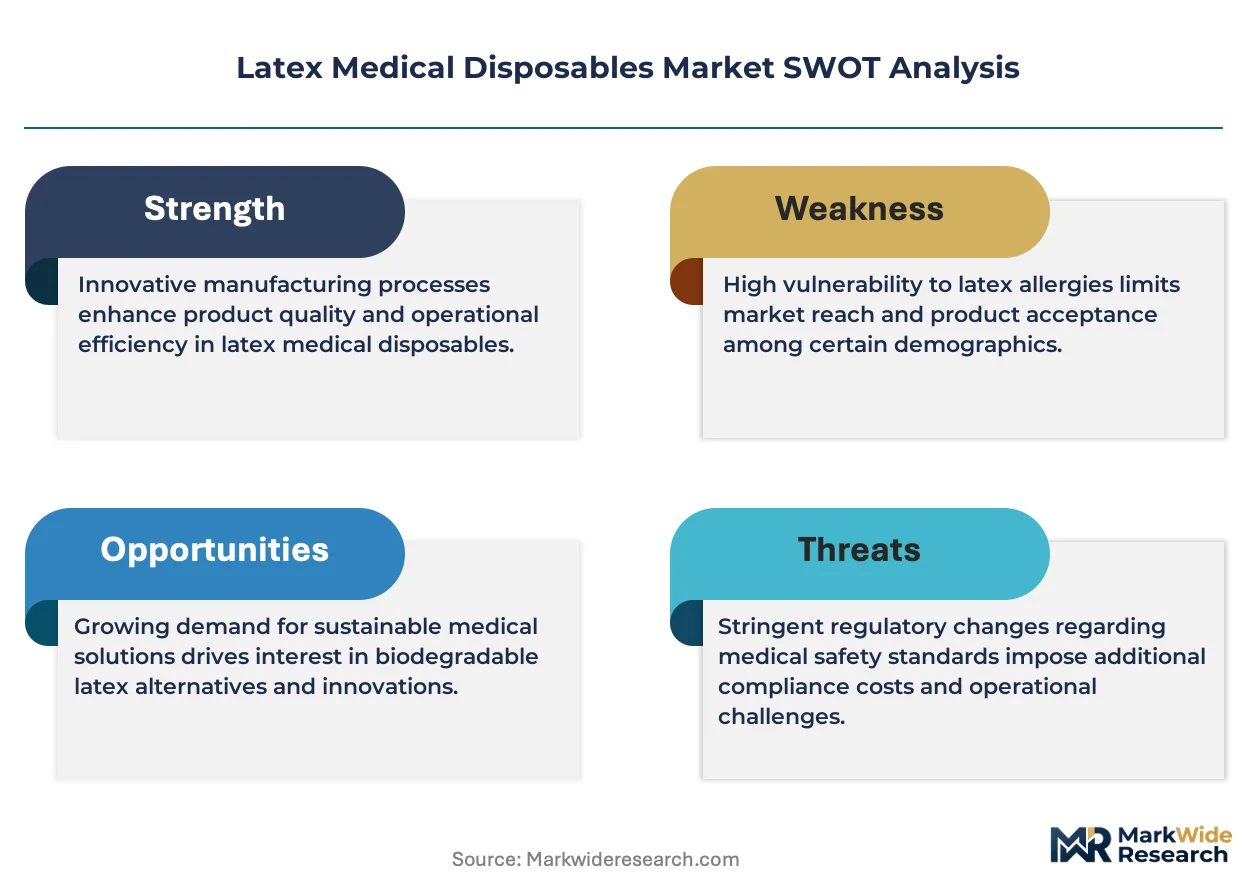
FDA enforcement of powdered glove bans and EU MDR compliance timelines are reshaping formulation standards and testing documentation burdens for manufacturers seeking market access. ISO 10993 biocompatibility testing and REACH chemical registration requirements in Europe add parallel certification layers that favor producers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving protein-labeling mandates and synthetic-alternative cost curves to calibrate portfolio transitions between natural latex and nitrile-dominant supply positions.
Market Dynamics
Malaysian glove manufacturing clusters now control upstream latex supply chains, concentrating production capacity in a narrow geographic band that amplifies price volatility when energy or labor costs fluctuate. This supply-side consolidation forces hospital procurement offices to negotiate multi-year contracts with built-in escalation clauses.
Growth Catalysts
- EU Medical Device Regulation:Powdered glove phase-out mandates are accelerating hospital procurement of powder-free latex alternatives, creating replacement demand across European healthcare systems.
- Southeast Asia infection-control protocols:Hospital systems in Thailand, Vietnam, and Indonesia are expanding examination glove inventories to meet stricter surgical hygiene standards.
- Natural rubber latex tensile performance:Surgical glove specifications requiring >18 MPa tensile strength preserve latex's position in high-risk procedural settings where barrier integrity is non-negotiable.
Market Restraints
- Crude oil-linked synthetic pricing:Nitrile feedstock costs tied to petrochemical indices create margin compression for latex producers when oil prices spike, narrowing the natural rubber cost advantage.
- Malaysian production concentration:Over 60% of global examination glove output originates in Selangor and Perak states, exposing supply chains to localized flooding, labor disputes, or energy rationing.
- Type I hypersensitivity prevalence:Protein allergen sensitivity in healthcare worker populations limits latex adoption in dermatology, oncology, and pediatric wards where staff rotation is minimal.
Strategic Opportunities
- India hospital infrastructure expansion:Ayushman Bharat health insurance expansion is creating demand for affordable examination gloves in tier-2 and tier-3 cities where latex price points outperform nitrile alternatives.
- Latex-nitrile hybrid formulations:Polymer blending technologies are opening procedural niches that combine latex elasticity with nitrile chemical resistance, targeting laboratory and chemotherapy handling applications.
- Direct-to-hospital distribution platforms:Digital procurement portals are disintermediating traditional medical distributors in Brazil and Mexico, allowing manufacturers to capture margin pools previously allocated to channel intermediaries.
Industry Challenges
- ISO 10993 biocompatibility testing backlog:Contract laboratories in Germany and Singapore face 14-18 month queues for cytotoxicity and sensitization studies, delaying product registrations for new latex formulations.
- Legacy protein detection assay standardization:ELISA and RAST testing methodologies vary across FDA, EMA, and PMDA jurisdictions, forcing manufacturers to maintain parallel validation studies for multi-regional filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latex Medical Disposables Market |
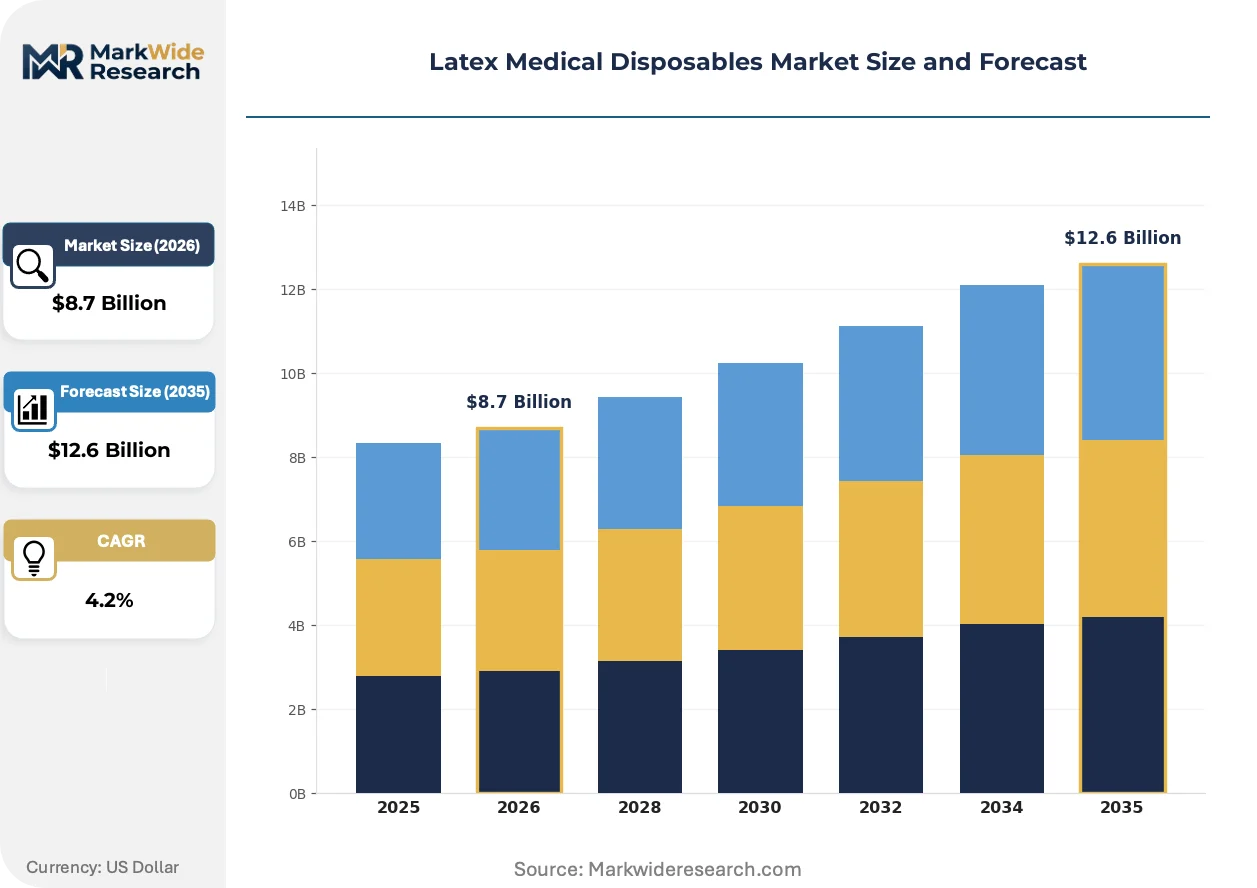
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Masks, Tubing, Catheters Application: Surgical, Examination, Industrial, Laboratory End User: Hospitals, Clinics, Pharmacies, Laboratories Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | Ansell, Dynarex Corporation, Top Glove Corporation Bhd, Kossan Rubber Industries, Rubberex, Hartalega Holdings Bhd, B. Braun Melsungen AG, C.R. Bard, Supermax Corporation Berhad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latex Medical Disposables Market Strategic Shifts
Formulation chemistry and manufacturing automation are converging to redefine barrier-performance standards while regulatory pressure on allergen content intensifies documentation burdens. These forces are compressing product development cycles and reshaping competitive differentiation.
Chlorinated latex surface treatments are absorbing the functional requirements previously addressed by powder lubricants, eliminating cornstarch particulate contamination risks in surgical suites. Academic medical centers in the United States and Germany are adopting these treated gloves for orthopedic and cardiovascular procedures where particulate embolization poses patient safety hazards. The technology is absorbing market share in premium surgical segments by delivering equivalent donning performance without FDA-banned powder additives.
REACH chemical registration requirements in Europe are forcing reformulation of accelerators and antioxidants used in latex vulcanization, with ECHA scrutiny focusing on thiuram and carbamate compounds linked to Type IV contact dermatitis. Manufacturers are substituting alternative cure systems or investing in accelerator-free production lines to maintain EU market access. The regulation is compressing supplier margins most severely among mid-scale producers lacking dedicated toxicology and dossier preparation capabilities.
Hospital group purchasing organizations are consolidating contract awards into fewer, larger-volume agreements that privilege suppliers with multi-continent manufacturing footprints and redundant production sites. Integrated delivery networks in the United States are replacing fragmented regional purchasing with national contracts that bundle gloves, gowns, and drapes under single-source arrangements. This concentration is visible most acutely in the Southeast United States, where Catholic health systems and for-profit chains have merged procurement functions into centralized supply chain entities.
Latex Medical Disposables Market Segmentation
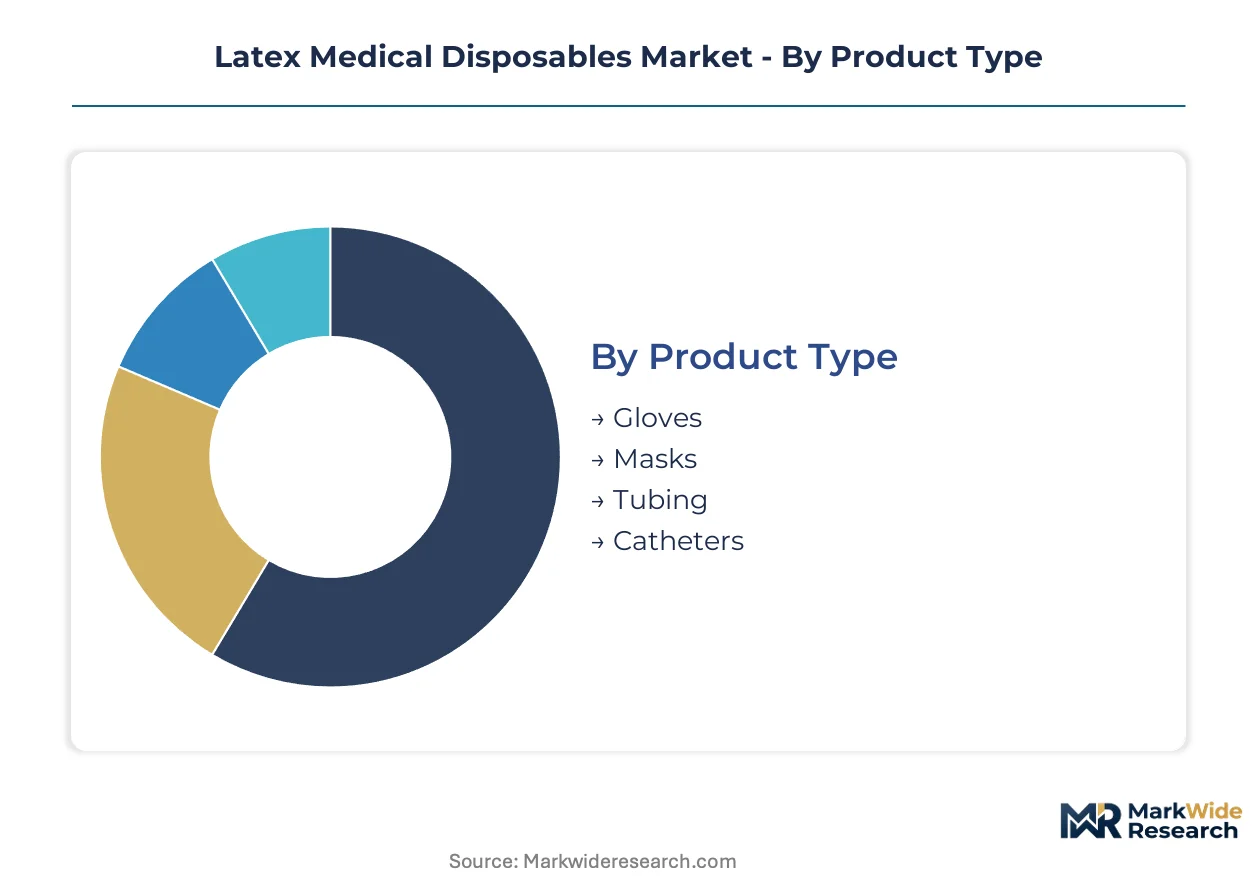
Segmentation in latex medical disposables reveals how procurement economics diverge across clinical settings. Volume concentration in examination-grade products contrasts with margin capture in sterile surgical applications, while distribution channel choices directly shape manufacturer profitability.
Product Type:
Gloves dominate unit volumes while catheters capture premium pricing tiers, creating a bifurcated revenue structure across the category.
- Gloves:Examination and surgical variants account for the majority of natural rubber latex consumption, with tensile strength specifications exceeding 18 MPa for procedural applications. Hospital systems in Thailand and Vietnam are expanding powder-free glove procurement to meet stricter infection-control protocols. Mature deployment sits with examination-grade disposables. Newer deployment is concentrated in chlorinated surface-treated surgical variants eliminating FDA-banned powder lubricants.
- Catheters:Foley, urinary, and specialty catheters require sterile manufacturing environments and extensive regulatory documentation, elevating per-unit pricing relative to barrier products. FDA biocompatibility testing and ISO 10993 certification requirements create significant entry barriers for new suppliers targeting US hospital contracts.
- Masks:Latex components in mask seals and straps serve anesthesia and respiratory applications where elasticity ensures facial conformity.
- Tubing:Drainage and irrigation tubing leverages latex coagulation properties for kink resistance in fluid management procedures.
Price differentiation between segments reflects sterile manufacturing complexity rather than raw material input costs alone.
Application:
Clinical risk profiles determine specification stringency, with sterile surgical environments demanding the highest barrier-performance standards.
- Surgical:Operating room applications require sterile, powder-free gloves with documented protein content below detectable thresholds to minimize Type I hypersensitivity reactions in patients and staff. EU Medical Device Regulation compliance timelines are accelerating hospital procurement of reformulated alternatives across German and French healthcare systems.
- Examination:Diagnostic and routine patient contact drives the highest unit volumes, with cost sensitivity strongest in emerging market hospital systems. India's Ayushman Bharat insurance expansion is creating demand for affordable examination gloves in tier-2 and tier-3 cities where latex price points outperform nitrile alternatives.
- Industrial:Non-medical manufacturing and food processing applications utilize lower-specification latex barriers where regulatory burdens diminish.
- Laboratory:Research and testing environments require chemical resistance combined with tactile sensitivity, opening niches for latex-nitrile hybrid formulations.
Surgical applications anchor premium pricing. Examination applications are expanding most quickly across Southeast Asian procurement budgets.
End User:
Procurement scale and specification authority concentrate in institutional settings, fragmenting across smaller clinical operators.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidate contract awards into large-volume agreements privileging suppliers with redundant manufacturing sites. Catholic health systems and for-profit chains in the US Southeast have merged procurement functions into centralized supply chain entities.
- Clinics:Outpatient facilities prioritize cost efficiency over premium specifications, sourcing through distributor intermediaries rather than direct manufacturer relationships.
- Pharmacies:Retail and community pharmacy channels serve consumer-directed glove purchases for home healthcare and personal protection.
- Laboratories:Diagnostic and research facilities require specialized formulations for chemical handling and precision manipulation tasks.
Contract concentration sits with hospital systems. Direct procurement adoption is climbing fastest among laboratory end users.
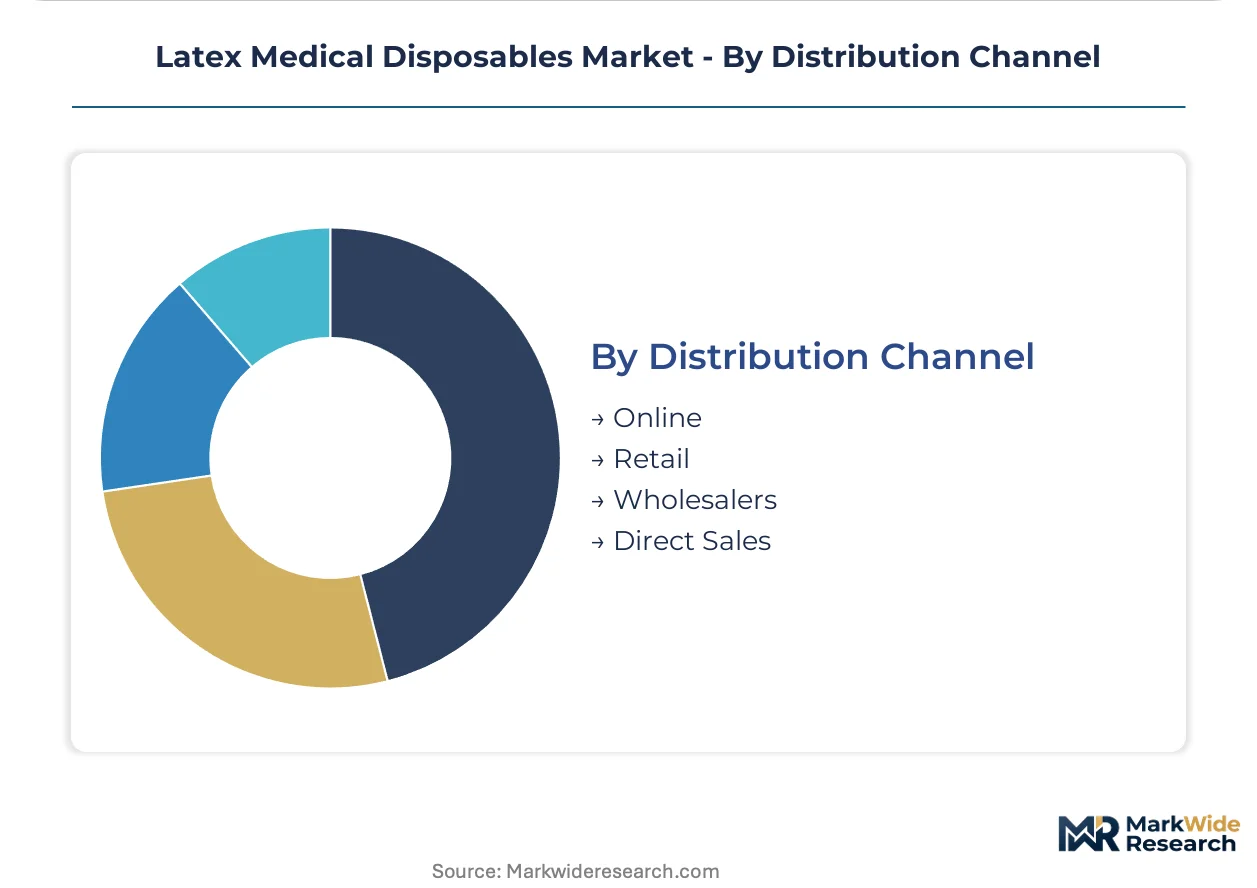
Distribution Channel:
Channel selection determines margin capture and customer relationship depth, with digital platforms disrupting traditional intermediaries.
- Direct Sales:Long-term supply agreements with hospital systems eliminate distributor markups, capturing the highest margin pools for manufacturers with dedicated contract management capacity. Digital procurement portals in Brazil and Mexico are disintermediating traditional medical distributors.
- Wholesalers:Regional and national distributors aggregate fragmented demand from smaller clinical settings, absorbing inventory risk and logistics coordination burdens.
- Retail:Pharmacy and medical supply stores serve individual practitioners and consumer markets with higher per-unit pricing and lower volume throughput.
- Online:E-commerce platforms enable price transparency and bulk purchasing for mid-sized clinics seeking to bypass traditional distributor relationships.
Established volume flows through wholesalers. Digital channel penetration is gaining share fastest in Latin American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian rubber plantations and processing facilities anchor the raw-material foundation for latex medical disposables manufacturing. Selangor and Perak states concentrate over sixty percent of global examination glove output. Energy costs and labor availability in these clusters directly transmit to international pricing dynamics.
United States
FDA enforcement of powdered glove bans drives hospital procurement toward powder-free latex alternatives. The agency's biocompatibility testing requirements under ISO 10993 create documentation burdens for market entry. Southeast integrated delivery networks in Florida and Georgia consolidate contracts through Catholic health system purchasing entities.
Germany
EMA oversight of EU Medical Device Regulation compliance accelerates hospital transitions to reformulated gloves across Bavarian and North Rhine-Westphalian healthcare systems. REACH chemical registration mandates scrutinize thiuram and carbamate accelerators in latex vulcanization. Academic medical centers in Berlin and Munich adopt chlorinated surface-treated variants for orthopedic procedures.
Malaysia
Natural rubber latex supply chains concentrate upstream production in Selangor manufacturing corridors serving global hospital contracts. The country's industrial masterplan supports glove sector energy subsidies and labor pooling arrangements. Port Klang logistics hubs enable direct container shipping to European and North American procurement offices.
India
Ayushman Bharat health insurance expansion generates examination glove demand in tier-2 and tier-3 cities across Maharashtra and Gujarat. CDSCO medical device registration requirements govern import and domestic manufacturing standards. Tamil Nadu industrial zones host emerging glove fabrication capacity targeting price-sensitive hospital procurement.
Brazil
ANVISA medical device regulations structure import documentation for latex disposables entering São Paulo and Rio de Janeiro hospital systems. Digital procurement platforms disintermediate traditional distributor relationships in Southeast and Southern regions. Local manufacturing tax incentives under industrial policy frameworks attract Malaysian joint venture investments.
Latex Medical Disposables Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to post-pandemic inventory normalization and hospital contract consolidation. The vendor base organizes into three tiers: integrated multinationals with redundant manufacturing footprints, Malaysian specialists leveraging cluster economies, and regional distributors capturing fragmented clinic demand. Strategic archetypes include scale-driven bulk producers, hybrid-technology innovators, and direct-to-hospital platform operators. Competitive moves center on backward integration into latex processing and geographic diversification of production sites.
Among Malaysian-dominant fabricators, Top Glove Corporation Bhd and Hartalega Holdings Bhd exemplify divergent positioning within the sector. Top Glove represents scale-driven bulk production archetypes optimized for examination-grade volume contracts. Hartalega occupies a technology-forward position associated with advanced formulation capabilities. Ansell, as an Australia-originated multinational, anchors the integrated global footprint tier with manufacturing dispersion across multiple geographies. These three entities collectively illustrate the competitive spectrum from cluster-dependent specialization to geographically diversified supply assurance.
| Leading Market Players |
|---|
| Ansell |
| Dynarex Corporation |
| Top Glove Corporation Bhd |
| Kossan Rubber Industries |
| Rubberex |
| Hartalega Holdings Bhd |
| B. Braun Melsungen AG |
| C.R. Bard |
| Supermax Corporation Berhad |
| Others |
Value Chain & Pricing Dynamics
EU Medical Device Regulation compliance deadlines gate qualified supply access for powder-free latex formulations, with manufacturers bearing ISO 10993 biocompatibility documentation costs that pass through to premium-tier hospital contracts. This regulatory threshold concentrates pricing power among producers with dedicated toxicology and dossier preparation capabilities.
Pricing Analysis
Long-term supply agreements bundle regulatory compliance documentation, lot traceability guarantees, and quality assurance audits into contracted pricing, while spot purchases for emergency replenishment exclude these service layers. Pricing stratifies across sterile surgical, examination-grade, and industrial-tier certifications, with FDA and EMA filing status driving the widest spreads. Cost compression in examination-grade segments is intensifying because Malaysian producers compete on volume scale for emerging market hospital contracts. Government hospital systems in India and Southeast Asia exhibit the highest price sensitivity, while academic medical centers in Germany and the United States prioritize barrier-performance specifications over per-unit cost.
Supply Chain Analysis
Direct-to-hospital digital procurement platforms in Brazil and Mexico are disintermediating traditional medical distributors, while wholesaler networks still handle fragmented clinic demand across smaller metropolitan areas. Raw material supply draws from Malaysian rubber plantations in Selangor and Perak states, Indonesian latex processing facilities, and Thai petrochemical feedstocks for synthetic alternatives. Manufacturing depends on chlorination equipment, accelerator compounds, and sterile packaging materials. Single-source vulnerability concentrates in Malaysian production corridors where localized flooding or energy rationing disrupt global examination glove availability. Distribution runs through Port Klang logistics hubs for European and North American container shipping.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysian manufacturing cluster capacity constraints prop pricing power for qualified producers, as hospital procurement offices accept escalation clauses to secure multi-year volume commitments against supply disruption risk.
For Market Incumbents: Deploy backward integration into latex processing and compounding to secure raw material margin capture against nitrile feedstock cost volatility. Accelerate accelerator-free production line investments to preempt REACH chemical registration restrictions on thiuram and carbamate compounds. Consolidate contract awards through group purchasing organization partnerships that bundle gloves, gowns, and drapes under single-source arrangements, defending share against emerging hybrid-technology specialists. For New Entrants and Emerging Players: Capture tier-2 and tier-3 city hospital demand in India's Maharashtra and Gujarat states where Ayushman Bharat insurance expansion creates volume opportunity at latex price points below nitrile alternatives. Target laboratory and chemotherapy handling niches with latex-nitrile hybrid formulations combining elasticity with chemical resistance. Establish direct-to-hospital digital procurement platforms in Latin American markets to disintermediate traditional distributor markups and capture margin pools. For Investors and Strategic Acquirers: ISO 10993 contract laboratory queue lengths extending to 14-18 months is the leading indicator that regulatory affairs capacity will determine market access viability across the analysis window. Acquisition targets should prioritize mid-scale producers with dedicated toxicology and dossier preparation capabilities rather than pure manufacturing scale. Watch for protein-labeling mandate harmonization across FDA, EMA, and PMDA jurisdictions as the signal for portfolio transition timing between natural latex and synthetic-dominant positions.| Strategic Initiative | Industry Significance |
|---|---|
| Accelerator-Free Production Line Investment | ECHA scrutiny of thiuram and carbamate compounds under REACH mandates reformulation to maintain EU market access. |
| Direct-to-Hospital Digital Platform Launch | ANVISA-registered manufacturers in Brazil bypass traditional distributor markups through disintermediated procurement portals. |
| ISO 10993 Biocompatibility Certification | FDA enforcement of powdered glove bans requires cytotoxicity and sensitization documentation for market entry. |
| Latex-Nitrile Hybrid Formulation Development | Laboratory and chemotherapy handling applications demand polymer blending technologies combining elasticity with chemical resistance. |
| Backward Integration into Latex Processing | Selangor and Perak plantation supply chains anchor cost control for examination-grade volume contracts. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hospital procurement managers, GPO contracts directors, biomedical engineers, and glove manufacturing plant managers. FDA 510(k) submissions, EMA medical device registrations, CDSCO import documentation, and ANVISA compliance records provided product-specific volume indicators. Bottom-up modeling of hospital system contract awards and top-down reconciliation with Malaysian Rubber Export Promotion Council production statistics validated market sizing.
Data-stream reconciliation across shipment manifests, hospital procurement databases, and manufacturer capacity disclosures enabled segmentation modeling by product type, application, end user, and distribution channel across the projection horizon. CAGRs were derived from weighted average of historical volume trajectories and forward-looking contract award pipelines. Forecast inputs incorporated protein-labeling mandate evolution, synthetic alternative cost curves, and infection-control protocol adoption rates in Southeast Asian healthcare systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Malaysian energy subsidy policy, crude oil-linked nitrile pricing volatility, and harmonization timelines for Type I hypersensitivity testing standards across FDA, EMA, and PMDA jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Measured Volume Burette Set Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Ostomy Care Market
Medical Supplies
Specimen Transport Bags Market
Medical Supplies
Medical Bags Market
Medical Supplies
Surgical Sealant and Adhesive Market
Medical Supplies
Continuous Ambulatory Peritoneal Dialysis Bags Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
Push-In Plug Vials Market
Medical Supplies
Histology and Cytology Consumables Supplies Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Lumbar Puncture Trays and Needles Market
Medical Supplies
Medical Procedure Tray Market
Medical Supplies
Endoscope Protective Barrier Covers Market