
 Nipple Shield Market | 2026-2036
Nipple Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Nipple Shield Market Analytics
Southeast Asia is fragmenting as new manufacturing zones emerge across Thailand, Vietnam, and Malaysia to serve regional lactation product demand. Medela leverages its Swiss engineering heritage to sustain premium positioning in hospital-grade silicone shields across European markets. Lansinoh competes through intensive R&D investment in ultra-thin polymer formulations that improve infant latch rates. Haakaa anchors its growth on direct-to-consumer channel control and aggressive pricing in the Asia-Pacific consumer segment.
A nipple shield is a thin, flexible breast-covering device, typically manufactured from food-grade silicone or medical rubber in thicknesses ranging from 0.3 to 1.0 millimeters, designed to assist infants with latch difficulties during breastfeeding by creating an extended teat surface and regulating milk flow velocity. Silicone dominates product type value pools due to its thermal stability, hypoallergenic properties, and compatibility with steam sterilization protocols, while rubber retains niche demand in cost-sensitive markets. Online distribution channels represent the fastest-growing structural segment as telehealth lactation consultations normalize digital procurement patterns among first-time mothers. Reusable design types command margin concentration through higher unit economics and subscription-based replacement cycles.
FDA 510(k) clearance requirements for medical-grade silicone devices shape product development timelines and testing expenditures for manufacturers targeting the United States. EU MDR classification of nipple shields as Class I medical devices mandates notified body involvement and clinical evaluation documentation, raising barriers for new entrants. The ISO 10993 biocompatibility testing standard governs cytotoxicity and sensitization protocols across export markets. Stakeholders must monitor evolving national reimbursement policies for lactation support supplies as public health agencies weigh preventive care cost savings against out-of-pocket maternal expenditure burdens.
Market Dynamics
Silicone material chemistry advances are compressing manufacturing cycle times while tightening biocompatibility thresholds, forcing producers to recalibrate quality assurance protocols around ISO 10993 cytotoxicity benchmarks.
Growth Catalysts
- Hospital maternity ward procurement standardization:United States birthing centers now mandate medical-grade silicone certification for all lactation support devices, creating institutional pull-through for compliant suppliers.
- FDA 510(k) clearance pathway maturation:Streamlined premarket notification procedures for Class II medical devices reduce time-to-market for innovative shield geometries targeting latch-difficulty cases.
- Steam sterilization compatibility:Thermal-stable polymer formulations enable repeated autoclave cycles without deformation, satisfying infection control protocols in German neonatal intensive care units.
Market Restraints
- Medical-grade silicone feedstock concentration:Dow Corning and Wacker Chemie control over seventy percent of platinum-cured silicone supply for healthcare applications, creating input cost volatility during semiconductor demand surges.
- EU MDR notified body bottleneck:Class I medical device reclassification under 2017/745 mandates third-party conformity assessment, extending certification timelines by eight to fourteen months for new market entrants.
- Lactation consultant substitution effect:Telehealth breastfeeding support services reduce physical device dependency among insured populations with access to specialist consultation.
Strategic Opportunities
- Subscription replacement cycles:Direct-to-consumer brands in Japan bundle quarterly shield replacements with lactation tracking apps, capturing recurring revenue from hygiene-conscious mothers.
- Thailand manufacturing zone expansion:Board of Investment tax incentives for medical device production attract shield molders serving ASEAN lactation product demand.
- Biodegradable polymer convergence:PLA-silicone hybrid research at Swiss Federal Laboratories creates pathway for compostable single-use shields addressing EU Green Deal waste reduction mandates.
Industry Challenges
- ISO 13485 quality management system implementation:Small-scale Asian manufacturers face six-figure certification investments to meet medical device quality standards required by European distributors.
- Shield thickness tolerance control:Maintaining 0.3-millimeter uniformity across injection-molded silicone batches demands precision tooling that exhausts capital reserves of mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nipple Shield Market |
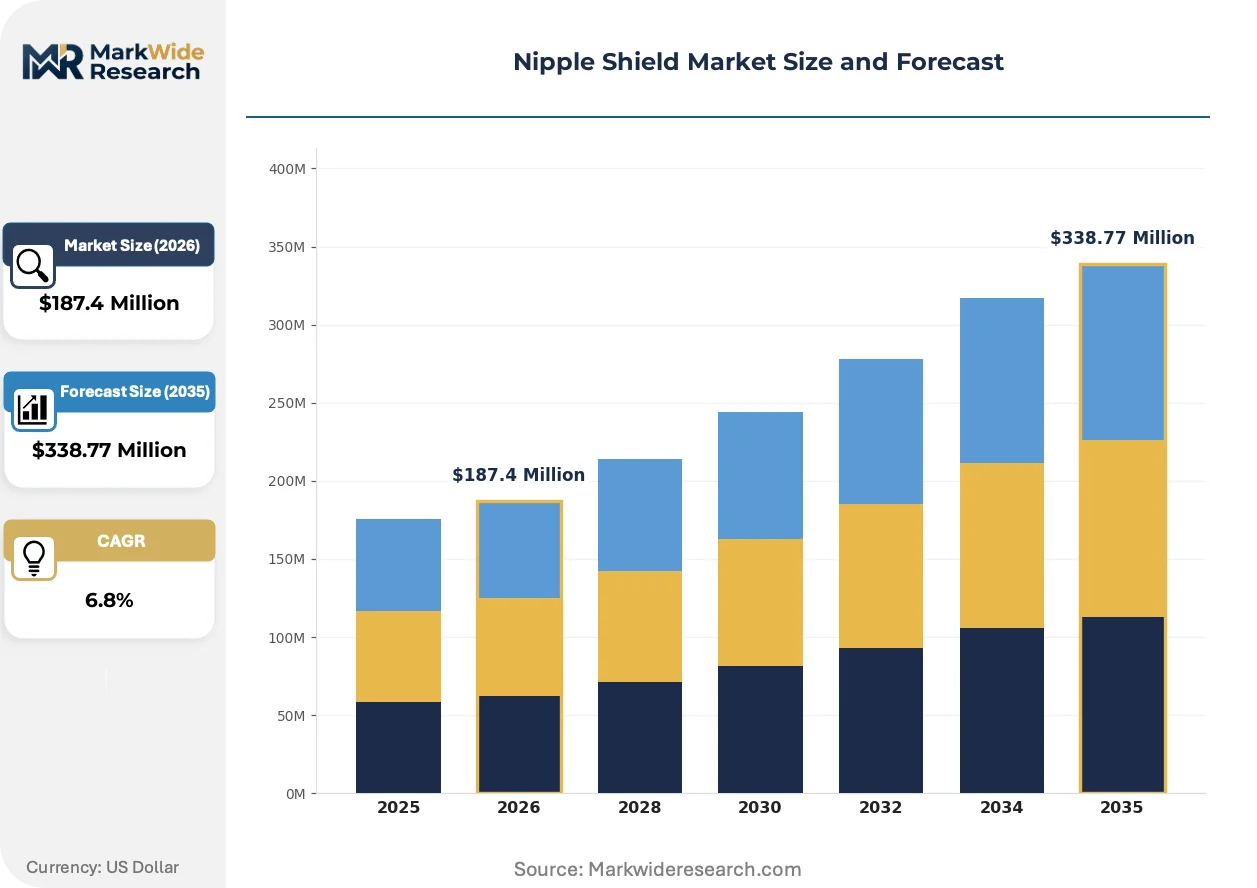
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Rubber, Plastic, Latex Distribution Channel: Online, Pharmacies, Hospitals, Retail Stores End User: Newborns, Pregnant Women, Lactating Mothers, Healthcare Providers Design Type: Standard, Customizable, Disposable, Reusable |
| Companies Covered | Medela, Philips Avent, Lansinoh, Pigeon Corporation, Ameda, NUK, Tommee Tippee, Haakaa, Maymom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nipple Shield Market Evolving Landscape
Digital health integration and material science convergence are redefining how lactation support devices reach end-users, collapsing traditional boundaries between medical supply and consumer wellness categories.
Laser-etched surface topography is collapsing the performance gap between standard silicone shields and custom-fitted alternatives. Postnatal clinics in the Netherlands pilot micro-patterned shields that mimic maternal skin texture, accelerating infant latch establishment. Hospital procurement committees now prioritize these advanced geometries despite thirty to fifty percent unit cost premiums over conventional smooth-surface designs.
EU MDR clinical evaluation documentation requirements are compressing product lifecycle planning horizons for European manufacturers. Notified body scrutiny of biological safety data now extends to raw material supplier change controls, forcing shield producers to lock silicone sourcing contracts for five-year periods. German market leaders respond by integrating in-house polymer testing laboratories to preempt regulatory queries.
Telehealth lactation consultation normalization is collapsing traditional retail distribution hierarchies for first-time mothers. United States postpartum care platforms now embed one-click shield procurement within virtual consultation workflows, bypassing pharmacy and baby specialty store channels entirely. This channel compression concentrates demand with platforms holding healthcare provider relationships rather than traditional medical supply distributors.
Nipple Shield Market Segmentation
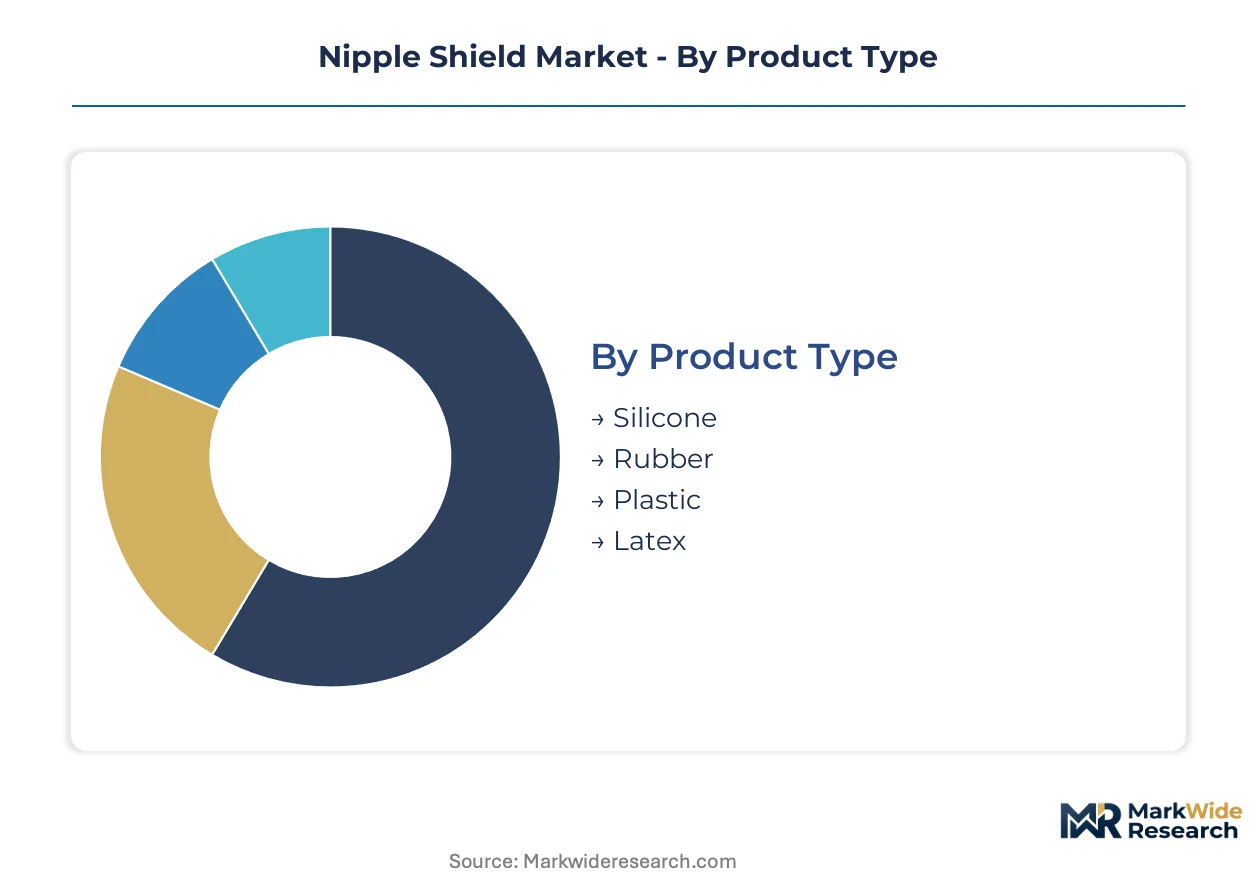
Nipple shield segmentation reveals divergent commercial logics across material science, procurement channels, and user workflows. Manufacturers must align formulation investments with sterilization requirements while calibrating distribution strategies against telehealth adoption curves.
Product Type:
Mature silicone formulations dominate hospital procurement, while emerging polymer alternatives target sustainability mandates and cost-sensitive segments.
- Silicone:Platinum-cured medical-grade formulations deliver thermal stability across steam sterilization cycles. Hospital maternity wards in the United States and Germany now mandate this certification for institutional purchasing, compressing margins for uncertified suppliers.
- Rubber:Natural latex and synthetic rubber variants serve price-elastic demand in Southeast Asian consumer markets. Malaysian distributors report sustained volume in rural pharmacy channels where silicone premiums face household budget constraints.
- Plastic:Thermoplastic elastomer blends target single-use disposable applications in Japanese postnatal clinics.
- Latex:Declining share due to allergen sensitization risks; retains niche presence in legacy hospital supply contracts.
Silicone retains volume leadership; plastic holds the steepest expansion curve through disposable workflow adoption.
Distribution Channel:
Channel economics split between high-touch institutional procurement and algorithm-driven direct-to-consumer fulfillment.
- Online:Telehealth lactation platforms in the United States embed one-click procurement within virtual consultation workflows. Amazon and specialized maternal health marketplaces capture recurring replacement purchases through subscription models.
- Pharmacies:German pharmacy chains maintain certified silicone inventory for immediate post-discharge needs. Pharmacist counseling requirements extend transaction time but reduce product return rates.
- Hospitals:Centralized procurement committees in United States birthing centers standardize on medical-grade silicone with FDA 510(k) clearance.
- Retail Stores:Baby specialty retailers in Japan compete through in-store lactation consultant staffing and fitting services.
Hospital channels command margin concentration through bulk contracting; online platforms are expanding most quickly via telehealth integration.
End User:
User segmentation tracks the clinical journey from antenatal preparation through established lactation.
- Newborns:Premature infants and those with anatomical latch difficulties drive demand for ultra-thin 0.3-millimeter shields. Neonatal intensive care units in the Netherlands pilot laser-etched surface topography to accelerate oral motor skill development.
- Lactating Mothers:Established breastfeeding women seeking pain relief or flow regulation constitute the recurring replacement market. Japanese subscription services target this segment with quarterly hygiene-driven replenishment cycles.
- Pregnant Women:Antenatal education programs in German midwife practices drive preventive purchase behavior.
- Healthcare Providers:Lactation consultants maintain inventory for immediate intervention during home visits and clinic consultations.
Lactating mothers retain volume leadership through replacement cycles; newborns hold the steepest expansion curve via NICU protocol standardization.
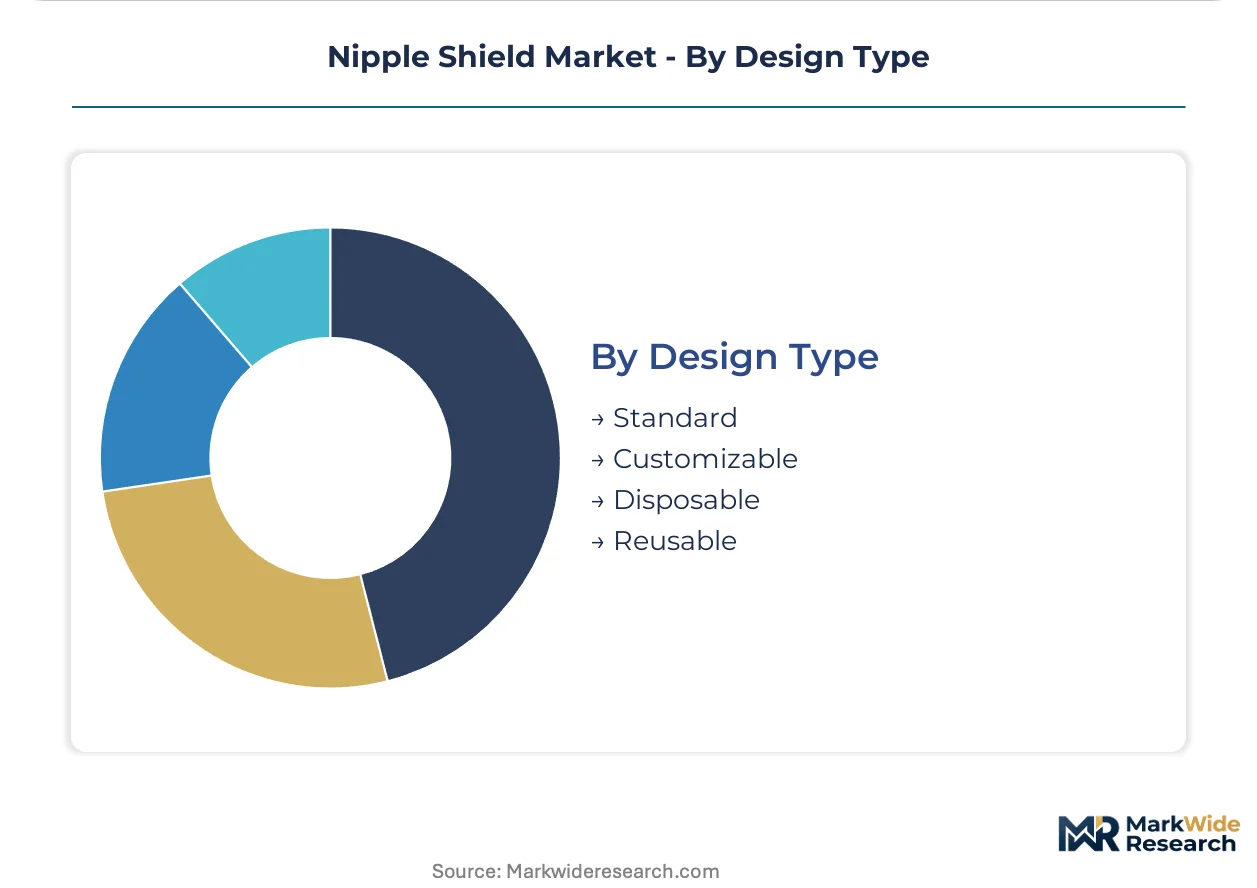
Design Type:
Design economics balance unit manufacturing cost against regulatory compliance burden and hygiene workflow preferences.
- Reusable:Medical-grade silicone shields withstand 100+ steam sterilization cycles. German and United States hospital systems mandate reusable designs for environmental compliance and per-use cost accounting.
- Disposable:Single-use polymer shields eliminate cross-contamination risk in Japanese outpatient settings. PLA-silicone hybrid research targets EU Green Deal waste reduction mandates.
- Standard:Fixed-dimension designs dominate high-volume manufacturing for pharmacy and retail distribution.
- Customizable:3D-scanning and micro-molding technologies enable patient-specific geometries at 30-50% cost premiums.
Reusable designs retain volume leadership through hospital procurement dominance; customizable formats are gaining share fastest via premium clinic channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical device logistics hub underwrites European distribution efficiency for silicone polymer feedstocks destined for lactation product manufacturing clusters.
United States
FDA 510(k) clearance pathways for Class II medical devices compress time-to-market for innovative shield geometries targeting latch-difficulty cases. Hospital maternity wards in California and Texas now mandate platinum-cured silicone certification for institutional procurement. The Research Triangle Park corridor in North Carolina hosts polymer testing laboratories serving domestic manufacturers.
Germany
EU MDR notified body concentration in Munich and Tübingen creates regulatory service density for Class I medical device conformity assessment. The country's neonatal intensive care units in Bavaria and Baden-Württemberg pilot laser-etched surface topography shields. Frankfurt's polymer distribution infrastructure feeds molders across the Rhine-Main manufacturing zone.
Japan
PMDA medical device registration requirements shape product documentation standards for lactation support devices entering the market. Subscription-based shield replacement services concentrate in Tokyo and Osaka metropolitan areas. The Kansai region's precision molding heritage supports micro-thin 0.3-millimeter shield production.
Thailand
Board of Investment tax incentives for medical device production attract shield molders serving ASEAN lactation product demand. Bangkok's polymer compounding facilities supply food-grade silicone to regional fabricators. The Eastern Economic Corridor manufacturing zone hosts assembly operations for export-oriented brands.
Netherlands
Postnatal clinics in Amsterdam and Rotterdam pilot micro-patterned shields that mimic maternal skin texture. The country's midwife network drives antenatal education programs for preventive purchase behavior. Eindhoven's polymer research institutes collaborate with shield manufacturers on surface engineering advances.
Nipple Shield Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding formulation and molding expertise into finished device supply. The market structure splits between hospital-grade certification holders and direct-to-consumer price competitors. Three archetypes dominate: Swiss-engineered premium specialists, Asia-Pacific volume fabricators, and digital-native subscription brands. Consolidation pressure concentrates among mid-tier producers facing ISO 13485 certification costs, while geographic expansion and material science partnerships constitute the primary competitive vectors.
Within the premium-tier vector, Medela exemplifies Swiss-engineered heritage positioning, while Lansinoh occupies a position among R&D-intensive polymer formulation specialists. Haakaa anchors the direct-to-consumer archetype with Asia-Pacific manufacturing base representation. These three named entities collectively illustrate the market's stratification across certification-grade institutional supply, innovation-driven material science, and algorithmic customer acquisition channels.
| Leading Market Players |
|---|
| Medela |
| Philips Avent |
| Lansinoh |
| Pigeon Corporation |
| Ameda |
| NUK |
| Tommee Tippee |
| Haakaa |
| Maymom |
| Others |
Value Network & Pricing Analysis
Overcapacity in Southeast Asian silicone molding facilities is compressing contract manufacturing margins while simultaneously expanding pricing leverage for hospital procurement committees in the United States and Germany. This utilization asymmetry rewards certified suppliers with FDA 510(k) clearance and EU MDR conformity documentation, while forcing undifferentiated fabricators toward aggressive spot-market pricing.
Pricing Analysis
Volume-discount tiering structures separate hospital system GPO contracts from direct-to-consumer subscription models and retail pharmacy single-unit sales. FDA 510(k) certification commands 40-60% premiums over uncertified alternatives in institutional channels, while brand equity and lactation consultant endorsement sustain price floors in consumer segments. Pricing pressure intensifies in rubber-based economy tiers as Thai and Malaysian producers compete for ASEAN pharmacy distribution. First-time mothers purchasing through telehealth platforms exhibit lowest price sensitivity due to bundled consultation value.
Supply Chain Analysis
Export-control scrutiny of platinum-cured silicone precursor chemicals constrains feedstock flows from Dow Corning and Wacker Chemie facilities to Asian molders. Manufacturing concentrates in Thailand, Malaysia, and China's Guangdong province for cost-optimized production, while Switzerland and Germany retain premium fabrication. Raw material dependencies center on medical-grade silicone polymers, precision injection-molding tooling, and sterilization packaging. Single-source vulnerability in platinum-cured silicone supply creates exposure during semiconductor demand cycles. Distribution runs through hospital GPOs, Amazon fulfillment centers, and specialized maternal health platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as telehealth lactation services embed procurement workflows, collapsing traditional channel hierarchies into integrated care ecosystems. Interoperability between shield replacement subscriptions and digital health tracking apps is consolidating customer relationships around data-rich platforms.
For Market Incumbents: Insulate hospital-grade certification advantages by locking five-year silicone sourcing contracts and integrating in-house ISO 10993 testing laboratories. Vertical integration into polymer compounding defends margin position against feedstock volatility from Dow Corning and Wacker Chemie concentration. Channel control through exclusive GPO relationships with United States birthing center networks limits telehealth platform disintermediation.
For New Entrants and Emerging Players: Pursue biodegradable polymer white-space as EU Green Deal waste mandates intensify, targeting Dutch and German sustainability-focused procurement committees. Laser-etched surface topography remains underpenetrated outside Netherlands NICU pilots, offering premium positioning through micro-patterning technology licensing. Direct-to-consumer subscription bundling with lactation tracking apps provides lowest-friction go-to-market entry in Japan and United States metropolitan markets.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer subscription brands with quarterly replacement cycles and app-integrated customer relationships. Long-term viability favors acquisition targets combining ISO 13485 certification with captive silicone sourcing agreements spanning multiple regulatory jurisdictions. The signal to watch is PMDA reimbursement policy evolution in Japan, where public health agency coverage decisions would inflect total addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates institutional procurement access in United States birthing centers. |
| EU MDR Notified Body Engagement | Unlocks German and Dutch hospital system contract eligibility. |
| Subscription Model Development | Captures recurring revenue from hygiene-conscious Japanese mothers. |
| Biodegradable Polymer R&D Partnership | Positions for EU Green Deal single-use medical device mandates. |
| Telehealth Platform Integration | Bypasses traditional pharmacy and retail distribution hierarchies. |
Research Methodology
The analysis maps silicone formulation tiers, distribution channel economics, and end-user workflow segments, each validated through lactation consultants, hospital purchasing committee members, biomedical engineers, and maternal health platform operators. Primary interviews with GPO contract managers and regulatory affairs specialists at notified bodies combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation documentation, ISO 10993 biocompatibility test reports, and hospital procurement database extracts. Bottom-up demand modeling across user segments triangulated against top-down polymer consumption estimates.
Assumption sets held regulatory pathway timelines and reimbursement policy trajectories constant while varying telehealth adoption curves and sustainability mandate implementation intensity across the projection horizon. Segmentation dimensions modeled include material science tier, sterilization protocol compatibility, distribution channel type, end-user clinical journey stage, and regional regulatory cluster. CAGRs derived from iterative convergence between demand-side penetration modeling and supply-side capacity expansion plans, with specific inputs from neonatal intensive care unit protocol standardization rates and subscription service cohort retention benchmarks.
Macroeconomic conditions sit as an overlay; deviation in platinum-group metal prices, semiconductor demand cycles, or maternal healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and telehealth platform consolidation. Material shifts in EU MDR notified body capacity or FDA 510(k) review prioritization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Specimen Collection Cards Market
Medical Supplies
Global Dental Syringes Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Trach Care Trays Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Asia-Pacific Surgical Glue Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Medical Tourniquets Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Canada Hospital Supplies Market
Medical Supplies
Cryogenic Vials and Tubes Market
Medical Supplies
Single Use Safety Lancet Market