
 Global IV Flush Syringe Market | 2026-2036
Global IV Flush Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Global IV Flush Syringe Market Foresight
Prefilled syringe manufacturing is fragmenting across single-use polymer platforms and ready-to-use sterile formats. Becton, Dickinson and Company leverages its integrated sterilization infrastructure to dominate North American hospital supply contracts. B. Braun Melsungen AG anchors European demand through regional production hubs that bypass cross-border tariff exposure. Cardinal Health competes on distribution density, positioning its logistics network to replenish ambulatory surgical centers within twenty-four hours.
An IV flush syringe is a sterile, single-use device designed to clear intravenous catheters and maintain patency using saline or heparin solution, typically manufactured from medical-grade polypropylene or polycarbonate with Luer Lock or Luer Slip connection standards. Prefilled syringes lead product type demand by eliminating compounding errors and reducing pharmacy labor, while safety syringes capture fastest-growing share as needlestick prevention mandates tighten. Material selection stratifies by clinical setting: polypropylene dominates high-volume hospital procurement for cost efficiency, whereas TPE elastomer variants penetrate home healthcare channels requiring plunger seal flexibility at lower injection forces.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product entry timelines and clinical evidence requirements for flush syringe manufacturers. ISO 80369 small-bore connector standards are displacing legacy Luer designs, forcing redesign investments across the supplier base. Stakeholders must monitor regulatory divergence between FDA and EMA prefillable container requirements when configuring multi-region product platforms.
Market Dynamics
The FDA's updated 510(k) premarket notification requirements for prefilled syringes are compressing supplier margins while accelerating consolidation among sterilization-capable manufacturers. This regulatory recalibration is forcing dual investments in compliance infrastructure and ISO 80369 connector redesign.
Growth Catalysts
- Catheterization volume expansion:Rising inpatient surgical procedures across tertiary hospitals in the United States, Germany, and Japan are expanding routine flush protocol utilization.
- ISO 80369 small-bore connector mandate:The international standard's displacement of legacy Luer designs is creating replacement demand across installed base equipment.
- Needlestick prevention legislation:OSHA bloodborne pathogen enforcement and EU sharps directive implementation are accelerating safety-engineered syringe procurement in acute care settings.
Market Restraints
- Medical-grade polymer cost volatility:Polypropylene and polycarbonate resin prices fluctuate with petrochemical feedstock markets, compressing margins on high-volume hospital contracts.
- Sterilization capacity concentration:Gamma and e-beam sterilization services cluster in the United States and Germany, creating cross-border dependency for manufacturers lacking in-house capability.
- EU MDR clinical evidence requirements:The conformity assessment's expanded documentation demands are extending product entry timelines by twelve to eighteen months for prefilled formats.
Strategic Opportunities
- Home healthcare channel penetration:TPE elastomer syringes requiring lower injection forces address aging patient populations managing infusion therapy outside acute settings.
- Ready-to-use sterile format expansion:Elimination of pharmacy compounding steps aligns with Joint Commission medication management standards in US ambulatory surgical centers.
- Japanese PMDA fast-track pathway:The regulator's priority review designation for infection control devices offers accelerated market access for novel connector designs.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face laboratory capacity constraints, delaying 510(k) submission readiness.
- Legacy Luer inventory stranding:Hospitals must coordinate connector transition timelines with existing catheter stockpiles, complicating supplier conversion programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IV Flush Syringe Market |
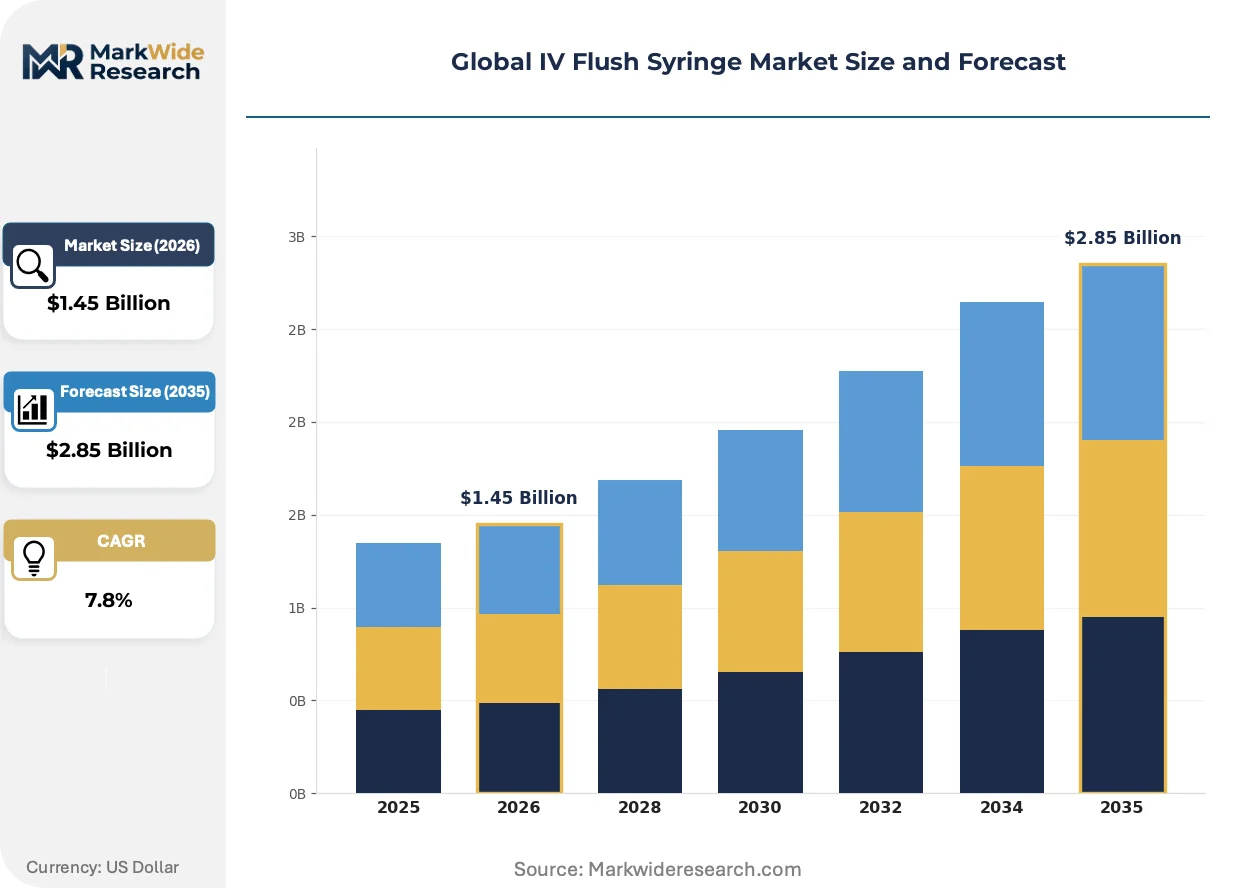
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luer Lock Syringe, Luer Slip Syringe, Prefilled Syringe, Catheter Tip Syringe, Safety Syringe Material: Polypropylene, Polycarbonate, Glass, Medical-Grade Silicone, TPE Elastomer Application: Hospital Procedures, Ambulatory Care, Home Healthcare, Diagnostic Centers, Research Laboratories End User: Hospitals, Ambulatory Surgical Centers, Clinics, Diagnostic Labs, Home Care Providers |
| Companies Covered | Becton, Dickinson and Company, B. Braun Melsungen AG, Cardinal Health, Nipro Corporation, Medline Industries, LP, Medefil, Inc., Polymedicure, Aquabiliti, SteriCare Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IV Flush Syringe Market Shifts & Advancements
Product architecture is bifurcating between polymer platform standardization and application-specific material customization, with regulatory harmonization efforts lagging technical advancement. This divergence is compressing development cycles while expanding compliance overhead.
Pre-filled saline and heparin syringes incorporating closed-system transfer device compatibility are rendering obsolete conventional vial-and-syringe compounding in US oncology infusion centers. Hospital pharmacy directors are adopting these formats to eliminate preparation errors and meet USP <797> sterile compounding requirements. The shift is compressing contract manufacturing organization margins as vertical integration becomes essential for sterility assurance.
EU MDR Article 10 technical documentation requirements are mandating clinical performance data for all Class IIa flush devices previously cleared under legacy directives. German notified bodies are enforcing stricter biological evaluation protocols, forcing manufacturers to reconstruct predicate device histories. Small-cap suppliers without established post-market surveillance infrastructure are exiting the European market rather than absorbing compliance costs.
Consolidated procurement through US hospital group purchasing organizations is displacing individual facility contracting for standard flush syringes. Premier and Vizient members are negotiating multi-year sole-source agreements that bundle prefilled saline, heparin, and specialty flush formats. This concentration is visible most acutely in the southeastern United States, where health system mergers have reduced independent purchasing entities by forty percent since 2020.
Global IV Flush Syringe Market Segmentation
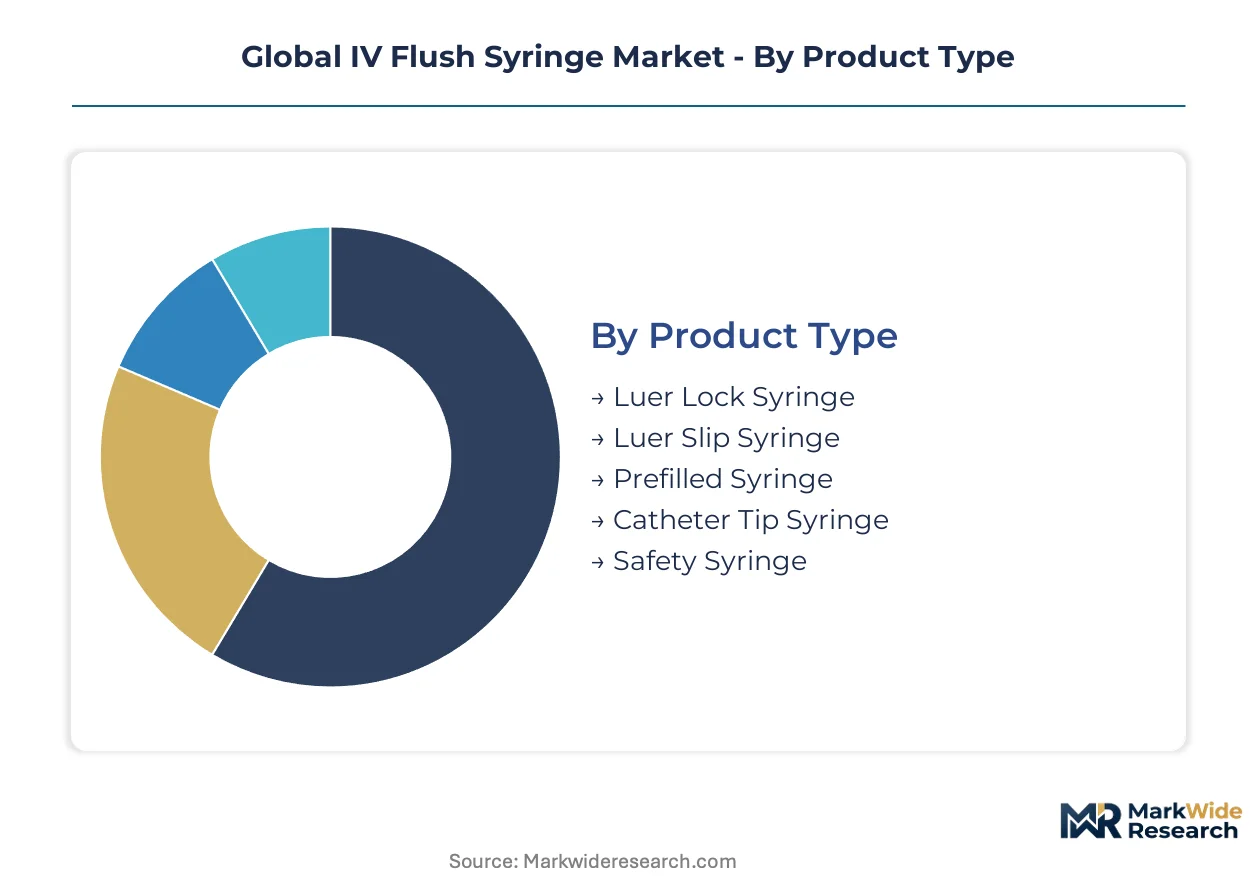
IV flush syringe procurement stratifies across four dimensions that determine pricing power, regulatory burden, and channel access. Product architecture and material selection govern manufacturing economics, while application setting and end-user type dictate volume concentration and compliance requirements.
Product Type:
Cost tier separation across flush syringe formats reflects automation levels, sterilization complexity, and pharmacy labor substitution potential.
- Prefilled Syringe:These sterile, ready-to-use devices arrive pre-loaded with saline or heparin solution, eliminating compounding errors and reducing pharmacy preparation time. Demand concentrates in United States tertiary hospitals where Joint Commission medication management standards drive adoption, though FDA 510(k) clearance pathways extend development timelines.
- Safety Syringe:Engineered with needlestick prevention mechanisms including retractable needles or protective shields, these devices incorporate passive activation features that comply with OSHA bloodborne pathogen standards. Fastest-growing demand appears in acute care settings across Germany and Japan where sharps directive enforcement has tightened.
- Luer Lock Syringe:Threaded collar mechanisms prevent accidental disconnection during high-pressure injections.
- Luer Slip Syringe:Friction-fit designs suit low-pressure flush protocols in cost-sensitive procurement environments.
- Catheter Tip Syringe:Bulbous distal ends accommodate enteral and irrigation applications outside standard IV lines.
Prefilled formats command the established base. The steepest expansion runs through safety-engineered variants.
Material:
Application requirements and injection force specifications drive polymer selection across clinical versus home care channels.
- Polypropylene:This thermoplastic polymer dominates high-volume hospital procurement for its cost efficiency, chemical resistance, and compatibility with gamma sterilization. United States group purchasing organizations specify polypropylene for standard saline flushes in merged health systems across the Southeast.
- TPE Elastomer:Thermoplastic elastomer variants deliver plunger seal flexibility at reduced injection forces, addressing aging patient populations managing infusion therapy outside acute settings. Japanese home healthcare channels show particular appetite for these formats as METI promotes aging-in-place policies.
- Polycarbonate:Transparent, impact-resistant polymer suits applications requiring visual confirmation of fluid clarity.
- Glass:Borosilicate formats persist in specialty compounding and research settings demanding inert contact surfaces.
- Medical-Grade Silicone:Lubricious coatings reduce plunger break-loose and glide forces in precision delivery applications.
Polypropylene anchors current procurement volumes. TPE elastomer formulations are climbing the fastest as home infusion expands.
Application:
Volume scale and sterility assurance requirements separate institutional acute care from distributed outpatient and residential settings.
- Hospital Procedures:Tertiary inpatient facilities in the United States, Germany, and Japan generate concentrated demand for prefilled and safety formats as catheterization volumes rise with surgical caseloads. Infection control protocols mandate single-use sterile devices with documented lot traceability.
- Home Healthcare:Patients managing chronic infusion therapy outside acute settings require syringes with reduced injection forces and intuitive handling. German regional insurers have expanded reimbursement for home infusion supplies, accelerating format diversification.
- Ambulatory Care:Same-day surgical centers prioritize ready-to-use formats that eliminate pharmacy compounding steps.
- Diagnostic Centers:Imaging and interventional suites require flush syringes compatible with contrast injection protocols.
- Research Laboratories:Preclinical and clinical trial settings demand lot-controlled, non-pyrogenic formats with extensive documentation.
Hospital procedures retain the dominant share. Home healthcare applications are gaining share fastest as population aging shifts care delivery models.
End User:
Customer type determines contract structure, with consolidated procurement displacing individual facility purchasing across integrated delivery networks.
- Hospitals:These institutions negotiate multi-year sole-source agreements through group purchasing organizations, bundling prefilled saline, heparin, and specialty flush formats. United States health system mergers have reduced independent purchasing entities substantially since 2020.
- Ambulatory Surgical Centers:Freestanding facilities require twenty-four-hour replenishment cycles and compact inventory footprints. Cardinal Health's logistics network targets these customers with distribution density advantages.
- Clinics:Physician office settings prioritize cost efficiency over feature complexity for routine catheter maintenance.
- Diagnostic Labs:Reference laboratories specify flush syringes compatible with automated sample handling systems.
- Home Care Providers:Durable medical equipment suppliers manage patient-direct distribution with insurance documentation requirements.
Hospitals command the established base. Ambulatory surgical centers represent the steepest expansion trajectory as surgical migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in IV flush syringes tilt toward surplus positions in Germany and the United States, while Japan and emerging Asian manufacturing hubs absorb technology licensing to build sterile fill-finish capacity. Cross-border sterilization services concentrate in the United States and Germany, creating dependency patterns for manufacturers lacking captive gamma or e-beam infrastructure.
United States
Tertiary hospital surgical volumes drive prefilled saline and heparin syringe procurement through consolidated group purchasing organizations. FDA 510(k) premarket notification requirements for prefilled formats compress supplier margins while accelerating consolidation among sterilization-capable manufacturers. The southeastern United States exhibits acute procurement concentration as health system mergers have reduced independent purchasing entities substantially since 2020.
Germany
Regional production hubs anchor European demand, bypassing cross-border tariff exposure through distributed manufacturing footprints. EU MDR Article 10 technical documentation requirements mandate clinical performance data for Class IIa flush devices, with German notified bodies enforcing stricter biological evaluation protocols. The Baden-Württemberg medical technology cluster hosts sterilization infrastructure serving prefilled syringe manufacturers across the continent.
Japan
Aging-in-place policies under METI direction expand home healthcare channel penetration for TPE elastomer syringes requiring reduced injection forces. PMDA fast-track pathway designation for infection control devices offers accelerated market access for novel connector designs aligned with ISO 80369 standards. The Kanto region surrounding Tokyo concentrates demand from high inpatient admission rates and stringent infection control protocols in tertiary facilities.
China
Domestic catheterization volume expansion in tier-one hospital systems creates import substitution pressure on prefilled flush syringe categories. NMPA regulatory harmonization efforts with ISO 80369 small-bore connector standards force redesign investments among multinational suppliers seeking market access. The Yangtze River Delta medical device manufacturing corridor develops sterile fill-finish capacity to serve both domestic consumption and regional export markets.
India
Cost-sensitive procurement environments favor Luer Slip friction-fit designs in high-volume government hospital tenders. CDSCO medical device rules implementation creates compliance bifurcation between notified body-certified imports and domestic manufacturers transitioning to quality management system requirements. The Maharashtra pharmaceutical and medical device cluster around Mumbai-Pune hosts contract manufacturing organizations serving export markets with polypropylene-based standard flush formats.
Global IV Flush Syringe Market Competitive Landscape
On the supply side, the industry is consolidating around sterilization-capable manufacturers capable of absorbing FDA 510(k) compliance costs and EU MDR technical documentation burdens. Three strategic archetypes dominate: integrated sterilization infrastructure operators, regional production hub specialists, and distribution-density logistics players. Competitive moves center on backward integration into captive sterilization capacity and strategic partnerships to secure ISO 80369 connector technology licensing.
Within the integrated infrastructure tier, Becton, Dickinson and Company represents North American hospital supply contract dominance through sterilization asset control. B. Braun Melsungen AG exemplifies the regional hub archetype, anchoring European demand through production distribution that mitigates tariff exposure. Cardinal Health occupies a position defined by logistics network density, targeting ambulatory surgical center replenishment cycles as a differentiation vector.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| B. Braun Melsungen AG |
| Cardinal Health |
| Nipro Corporation |
| Medline Industries, LP |
| Medefil, Inc. |
| Polymedicure |
| Aquabiliti |
| SteriCare Solutions |
| Others |
Supply & Pricing Matrix
Sterilization infrastructure concentration in the United States and Germany funnels margin pools toward manufacturers with captive gamma or e-beam capacity, squeezing contract manufacturers dependent on third-party sterilization services. This upstream bottleneck amplifies pricing power for integrated suppliers while fragmenting procurement leverage among buyers lacking vertical sterilization control.
Pricing Analysis
Hospital group purchasing organizations anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on ISO 80369 connector certification grade and sterilization assurance documentation, with safety-engineered formats commanding premiums over conventional Luer designs. Pricing pressure stems from EU MDR compliance cost absorption among smaller manufacturers exiting the European market. Ambulatory surgical centers exhibit highest price sensitivity due to compact inventory budgets, while tertiary hospital systems prioritize lot traceability over unit cost.
Supply Chain Analysis
Contract manufacturing for prefilled formats concentrates among sterilization-capable facilities in the United States, Germany, and Japan. Raw material dependencies center on medical-grade polypropylene resin, polycarbonate for transparent variants, and TPE elastomers for home healthcare channels. Supply chain risk manifests as single-source vulnerability for gamma sterilization services clustered in Baden-Württemberg and the American Midwest. Distribution runs through group purchasing organization networks serving merged health systems, with twenty-four-hour replenishment cycles for ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IV Flush Syringe Market represents a high-growth disruption propelled by ISO 80369 small-bore connector mandates displacing legacy Luer designs across installed base equipment. This regulatory inflection compresses development cycles while expanding compliance overhead, rewarding manufacturers with established sterilization infrastructure and predicate device histories.
For Market Incumbents: Build regulatory data moats through predicate device reconstruction and post-market surveillance infrastructure. Invest in backward integration into captive sterilization capacity to bypass third-party service bottlenecks. Consolidate position by acquiring contract manufacturers lacking EU MDR technical documentation capabilities, as German notified bodies enforce stricter biological evaluation protocols that smaller suppliers cannot absorb.
For New Entrants and Emerging Players: Japanese home healthcare channels offer underpenetrated white-space as METI aging-in-place policies expand reimbursement for TPE elastomer formats requiring reduced injection forces. Target PMDA fast-track pathway designation for novel connector designs aligned with ISO 80369 standards. Pursue licensing partnerships with established sterilization infrastructure operators rather than building captive capacity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across prefilled syringe manufacturing as FDA 510(k) clearance pathways extend development timelines and compliance documentation burdens. Prioritize acquisition targets with established GPO contract relationships and hospital system sole-source agreements. Monitor sterilization service pricing as the primary inflection indicator for margin compression among non-integrated manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369 Connector Redesign | Regulatory compliance with FDA and EU MDR standards displaces legacy Luer inventory across hospital installed bases. |
| Captive Sterilization Capacity Expansion | In-house gamma and e-beam infrastructure eliminates cross-border dependency and compresses supplier qualification timelines. |
| Home Healthcare Channel Development | TPE elastomer formats address aging patient populations managing infusion therapy outside acute settings per METI policy direction. |
| GPO Contract Consolidation | Multi-year sole-source agreements with Premier and Vizient members bundle prefilled saline, heparin, and specialty flush formats. |
| EU MDR Technical Documentation Investment | Article 10 clinical performance data requirements extend product entry timelines for Class IIa flush devices in European markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body guidance documents, hospital procurement databases, and GPO contract disclosures. Interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and sterilization service operators informed demand-side validation. Secondary sources include ISO standard documentation, OSHA enforcement records, and CMS Medicare utilization data. Bottom-up volume modeling triangulates against top-down market sizing across product type, material, application, and end-user segments.
Forecast inputs incorporate catheterization volume trajectories, regulatory approval pathway timelines, and sterilization capacity expansion plans across the projection horizon. Segmentation dimensions modeled include product architecture, polymer material grade, clinical versus home care setting, and consolidated versus independent procurement structure. CAGRs derive from regression analysis of historical volume trends against surgical procedure growth and infection control protocol adoption. Industry-specific forecast inputs encompass Joint Commission medication management standard updates and PMDA priority review designation patterns.
Practitioners should monitor sterilization service pricing volatility, EU MDR notified body backlog duration, and polypropylene resin cost movements for early signals of forecast revision. Assumptions reflect current regulatory enforcement patterns and hospital merger trajectories. Quarterly review of GPO contract renewal rates and ISO 80369 connector transition timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Cell Freezing Media Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Middle East and North Africa Disposable Gloves Market
Medical Supplies
Healthcare Adhesive Tapes Market
Medical Supplies
Biodegradable Hemostat Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Suture Wire Market
Medical Supplies
Petri Dishes Market
Medical Supplies
Europe Medical Gloves Market
Medical Supplies
Oral Dosing Cups Market
Medical Supplies
Port Access Needles Market
Medical Supplies
Crutch Pads Market
Medical Supplies
US Healthcare Personal Protective Equipment Market
Medical Supplies
Disposable Gloves Market
Medical Supplies
OTC Braces and Supports Market
Medical Supplies
Europe Ostomy Drainage Bags Market