
 Global Antimicrobial Dressings Market | 2026-2036
Global Antimicrobial Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antimicrobial Dressings Market Foresight
Hospital procurement departments are unwinding their historical preference for basic gauze and shifting budget toward advanced antimicrobial formats. Smith+Nephew leverages its specialized negative pressure wound therapy integration to capture complex case volumes. Mölnlycke Health Care anchors its position through proprietary soft silicone technology that minimizes trauma during dressing changes. Cardinal Health competes on distribution scale, supplying extensive hospital networks with private-label antimicrobial portfolios.
Antimicrobial dressings are advanced wound care materials engineered with biocidal agents such as silver ions, iodine, or polyhexamethylene biguanide to suppress bacterial colonization while maintaining a moist healing environment. These products typically incorporate controlled-release mechanisms that sustain antimicrobial activity for 72 hours or longer, serving primarily to prevent infection in acute surgical wounds and manage bioburden in chronic lesions. Foam dressings embedded with silver currently dominate value generation due to superior exudate management and extended wear time, while alginate formats represent the fastest-expanding category as clinicians adopt them for heavily draining cavity wounds. Honey-based delivery technology occupies a premium niche driven by patient demand for natural alternatives and favorable reimbursement coding in select European markets.
FDA clearance pathways for antimicrobial claims require rigorous clinical evidence under 510(k) or PMA frameworks, while the EU Medical Device Regulation mandates notified body involvement for all active substance-containing dressings. Japan's PMDA enforces stringent stability testing that limits market entry to manufacturers with validated cold-chain documentation. Stakeholders must monitor evolving resistance surveillance data from CDC and ECDC to anticipate which antimicrobial modalities retain clinical utility.
Market Dynamics
Hospital procurement departments are unwinding their historical preference for basic gauze and shifting budget toward advanced antimicrobial formats. Smith+Nephew leverages its specialized negative pressure wound therapy integration to capture complex case volumes. Mölnlycke Health Care anchors its position through proprietary soft silicone technology that minimizes trauma during dressing changes. Cardinal Health competes on distribution scale, supplying extensive hospital networks with private-label antimicrobial portfolios.
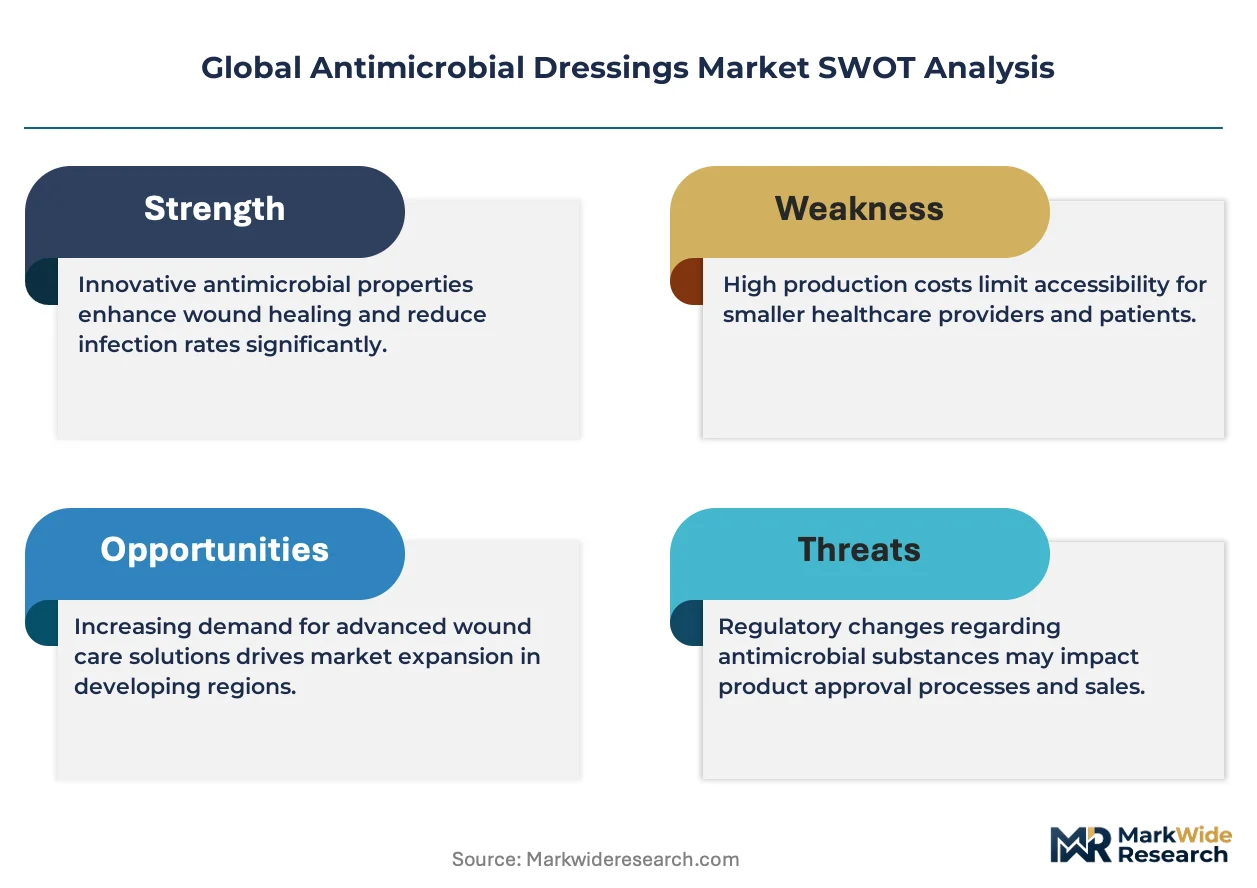
Growth Catalysts
- Silver-ion delivery systems:Controlled-release silver technology addresses rising antibiotic resistance while meeting FDA 510(k) clinical evidence requirements for antimicrobial claims.
- Chronic wound burden:Aging populations in the United States, Germany, and Japan drive hospital adoption of advanced dressings that reduce infection rates and accelerate healing timelines.
- EU Medical Device Regulation:Stricter notified body oversight for active substance-containing dressings creates competitive moats for manufacturers with validated quality systems.
Market Restraints
- Silver price volatility:Fluctuations in precious metal markets directly compress margins for ionic silver dressing producers.
- PMDA stability requirements:Japan's cold-chain documentation mandates limit market entry to manufacturers with validated logistics infrastructure.
- Traditional antibiotic coatings:Low-cost generic alternatives retain share in price-sensitive emerging markets despite resistance concerns.
Strategic Opportunities
- Home care transition:Post-acute settings in the United States present underpenetrated demand as insurers push wound care outside hospital walls.
- Honey-based modalities:Natural antimicrobial alternatives command premium positioning where European reimbursement codes recognize bioactive wound management.
- Alginate-silver convergence:Hybrid formats for heavily draining cavity wounds address unmet clinical needs in surgical and trauma applications.
Industry Challenges
- Clinical evidence generation:FDA PMA pathways for novel antimicrobial mechanisms require multi-year prospective studies with substantial capital commitment.
- Resistance surveillance integration:Manufacturers must continuously monitor CDC and ECDC pathogen data to validate ongoing clinical utility of biocidal agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antimicrobial Dressings Market |
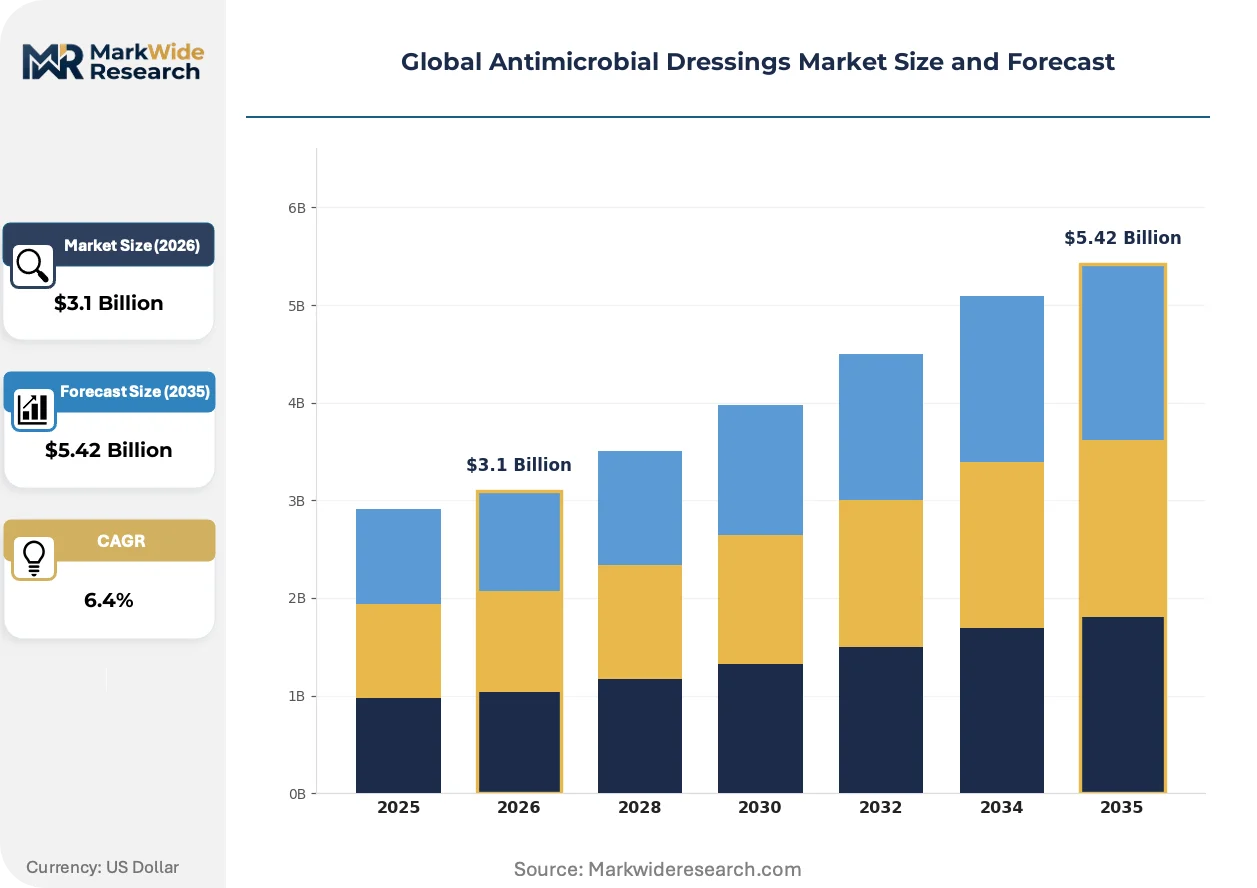
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid, Foam, Alginate, Hydrogel, Transparent Film, Silicone Application: Chronic Wounds, Surgical Wounds, Burn Care, Trauma Care, Ulcers, Diabetic Foot Care End User: Hospitals, Ambulatory Surgical Centers, Wound Care Clinics, Home Healthcare Providers, Nursing Facilities Delivery Technology: Silver Based, Iodine Based, Honey Based, Antibiotic Based, PHMB Based, Polyhexamethylene Biguanide |
| Companies Covered | 3M, Smith+Nephew, Mölnlycke Health Care, ConvaTec, Coloplast, Cardinal Health, B. Braun, Medline Industries, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antimicrobial Dressings Market Shifts & Advancements
Antimicrobial dressing technology is converging with advanced wound bed preparation modalities, creating integrated care protocols that extend product lifecycle value beyond simple infection control.
Electrospun nanofiber matrices loaded with silver nanoparticles are displacing conventional foam substrates in surgical applications. Academic medical centers in Germany and the United States are piloting these formats for complex reconstructive cases. The shift is compressing addressable volume for legacy hydrocolloid producers while opening premium pricing tiers.
REACH restrictions on biocidal active substances are forcing reformulation of iodine-based delivery systems across European manufacturing. The European Chemicals Agency's ongoing substance evaluations are extending compliance timelines for existing product registrations. Dressing suppliers with diversified antimicrobial portfolios are accelerating silver and polyhexamethylene biguanide alternatives.
Group purchasing organizations are consolidating hospital antimicrobial dressing contracts around outcome metrics rather than unit cost. Integrated delivery networks in the United States are unbundling legacy distributor relationships to secure direct manufacturer partnerships. The restructuring concentrates procurement influence among three national GPOs while fragmenting local supplier access.
Global Antimicrobial Dressings Market Segmentation
Antimicrobial dressing manufacturers configure product portfolios across four intersecting dimensions to match wound bed characteristics, care settings, and reimbursement pathways. Each segmentation axis carries distinct margin profiles and regulatory burdens that shape competitive positioning.
Product Type:
Foam and alginate formats concentrate manufacturing in the United States and Germany for domestic hospital supply, while hydrocolloid and transparent film production serves broader export markets from Ireland and Malaysia.
- Foam:Polyurethane substrates embedded with silver ions manage exudate across moderate-to-heavy drainage wounds. Hospital procurement in the United States and Germany prioritizes these formats for surgical site management and pressure injury protocols.
- Alginate:Calcium-sodium fibers derived from brown seaweed form gels upon contact with wound fluid, enabling conformable packing of cavity wounds. Demand concentrates in trauma centers across Japan and the United Kingdom where heavily draining lesions require frequent dressing changes.
- Hydrocolloid:Carboxymethylcellulose and gelatin matrices maintain autolytic debridement for low-exudate wounds.
- Hydrogel:Cross-linked polymer networks deliver moisture to dry necrotic tissue.
- Transparent Film:Semi-permeable polyurethane membranes enable moisture vapor transmission and visual monitoring.
- Silicone:Soft silicone adhesives minimize trauma during dressing removal for fragile periwound skin.
Foam holds the largest share; momentum sits with alginate as trauma and surgical cavity applications expand.
Application:
Chronic wound management commands premium pricing tiers due to extended treatment durations, while burn care applications require specialized regulatory clearance pathways.
- Chronic Wounds:Venous leg ulcers, pressure injuries, and non-healing surgical wounds drive recurring dressing consumption. Wound care clinics in Germany and the United States account for disproportionate volume as integrated care pathways extend treatment outside hospital walls.
- Surgical Wounds:Post-operative incision management requires antimicrobial protection during the critical healing window. Ambulatory surgical centers in Japan and France favor advanced formats that reduce nursing intervention frequency.
- Burn Care:Partial-thickness thermal injuries demand dressings that maintain moist environments while preventing colonization.
- Trauma Care:Acute mechanical wounds from accidents or combat require rapid antimicrobial intervention.
- Ulcers:Arterial and neuropathic ulcers in elderly populations necessitate gentle adhesion systems.
- Diabetic Foot Care:Limb-threatening infections in diabetic patients require aggressive bioburden management.
Surgical wounds generate the highest absolute revenue; diabetic foot care is climbing the fastest as prevalence rises in aging populations.
End User:
Hospital purchasing power consolidates around national group purchasing organizations, while home healthcare providers fragment across regional service networks.
- Hospitals:Acute care facilities maintain formulary control through pharmacy and therapeutics committees. Integrated delivery networks in the United States negotiate direct manufacturer contracts that bypass traditional distributor markups.
- Ambulatory Surgical Centers:Outpatient procedure volumes drive demand for single-use antimicrobial dressings with simplified application protocols. German day-surgery clinics favor pre-cut formats that reduce nursing time.
- Wound Care Clinics:Specialized facilities manage complex cases requiring advanced dressing rotations.
- Home Healthcare Providers:Visiting nurse services deliver wound care outside institutional settings.
- Nursing Facilities:Long-term care settings manage pressure injury prevention across immobile resident populations.
Hospitals retain the dominant share; home healthcare providers are gaining share fastest as reimbursement shifts toward post-acute settings.
Delivery Technology:
Silver-based systems face REACH substance evaluation in Europe, prompting manufacturers to diversify toward PHMB and honey alternatives for regional compliance.
- Silver Based:Ionic silver and silver nanoparticles provide broad-spectrum antimicrobial activity through multiple bacterial killing mechanisms. FDA 510(k) clearance requirements favor established release kinetics demonstrated in clinical literature.
- PHMB Based:Polyhexamethylene biguanide offers cationic biocidal action with lower cytotoxicity profiles than silver. European manufacturers accelerate PHMB adoption as ECHA evaluations complicate silver substance registrations.
- Iodine Based:Slow-release iodine formulations maintain antimicrobial activity in highly exudative environments.
- Honey Based:Medical-grade Manuka honey provides osmotic wound healing effects and natural antimicrobial enzymes.
- Antibiotic Based:Traditional coatings retain niche applications despite resistance surveillance concerns.
Silver-based technology commands the largest installed base; PHMB-based delivery is expanding most quickly as regulatory pressure reshapes European product portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German wound care manufacturers export advanced silver-ion dressings to hospital systems across the United States and Japan, establishing the primary trade-flow corridor in antimicrobial wound management.
United States
Aging demographics and diabetic foot ulcer prevalence drive hospital procurement of advanced dressings. FDA 510(k) pathways for antimicrobial claims enforce rigorous clinical evidence standards. Wound care clusters in Minnesota and Massachusetts concentrate negative pressure therapy integration development.
Germany
Integrated care pathways for chronic wounds expand reimbursement for bioactive dressings outside acute settings. ECHA REACH evaluations on silver substances accelerate manufacturer diversification toward PHMB alternatives. Industrial concentration in North Rhine-Westphalia supports electrospun nanofiber pilot programs for surgical applications.
Japan
Super-aging society demographics sustain premium pricing for extended-wear antimicrobial formats. PMDA cold-chain stability documentation mandates limit market entry to validated logistics operators. Tokyo and Osaka medical centers anchor adoption of alginate-silver hybrids for trauma cavity management.
United Kingdom
NHS wound care pathway reforms shift treatment volumes toward community nursing settings. NICE technology appraisals influence formulary positioning for honey-based modalities. Manufacturing activity clusters in Yorkshire and the Humber supply medical-grade Manuka dressings for European export.
China
Expanding hospital infrastructure in tier-two cities generates demand for cost-optimized antimicrobial formats. NMPA medical device registration timelines compress for established silver-release mechanisms. Yangtze River Delta manufacturing bases scale output of foam substrates for domestic and Southeast Asian markets.
Global Antimicrobial Dressings Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with wound care divisions, creating a tiered structure where scale-driven procurement leverage coexists with specialized technology niches. Strategic archetypes include integrated negative pressure therapy developers, soft silicone adhesion specialists, and distribution-scale private-label suppliers. Competitive moves concentrate on direct hospital contracting through group purchasing organization partnerships and geographic expansion via regulatory pathway optimization.
Within the diversified medical technology tier, 3M, Smith+Nephew, and Mölnlycke Health Care occupy positions that exemplify contrasting strategic vectors. 3M represents scale-driven manufacturing breadth across adhesive and substrate technologies. Smith+Nephew anchors complex case volume capture through therapy system integration. Mölnlycke Health Care exemplifies premium positioning via proprietary gentle adhesion platforms that minimize periwound trauma.
| Leading Market Players |
|---|
| 3M |
| Smith+Nephew |
| Mölnlycke Health Care |
| ConvaTec |
| Coloplast |
| Cardinal Health |
| B. Braun |
| Medline Industries |
| McKesson Corporation |
| Others |
Supply & Pricing Matrix
Silver-ion substitution for traditional antibiotic coatings is redrawing raw-material sourcing maps from Indian API hubs toward German electroplating facilities while compressing margin structures for legacy coating producers. This input shift simultaneously elevates cold-chain logistics costs and concentrates pricing power among validated European manufacturers.
Pricing Analysis
Next-generation electrospun nanofiber formats command 40-60% premiums over conventional foam substrates, while prior-generation hydrocolloid products face accelerating price erosion in hospital procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and silver-release validation documentation. Pricing pressure stems from group purchasing organization consolidation around outcome metrics rather than unit cost. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement schedules, while integrated delivery networks in the United States demonstrate lowest sensitivity where total cost of care contracts dominate.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for Malaysian hydrocolloid substrate producers serving European converters. Manufacturing concentrates in Germany, the United States, and Ireland for advanced formats, while China and Malaysia supply cost-optimized foam and film substrates. Raw material dependencies span silver nitrate from Mexican mining operations, polyurethane precursors from German chemical complexes, and medical-grade honey from New Zealand apiaries. Single-source vulnerability concentrates in ionic silver active pharmaceutical ingredient supply. Distribution runs through national group purchasing organizations in the United States and regional hospital service networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where FDA 510(k) clearance archives and PMDA cold-chain validation create switching costs that entrench incumbents. Network effects concentrate in integrated delivery network contracting relationships that fragment local supplier access.
For Market Incumbents: Compound defensive positioning by deepening backward integration into silver-ion active pharmaceutical ingredient production and securing exclusive alginate fiber supply agreements with Norwegian seaweed processors. Emerging PHMB-based entrants from European specialty chemical players threaten silver-format margins. Capacity addition in North Rhine-Westphalia electrospun nanofiber pilot facilities anchors next-generation surgical format control. For New Entrants and Emerging Players: Differentiate on honey-based natural antimicrobial positioning where European reimbursement codes recognize bioactive wound management in community nursing settings. Home healthcare providers in post-acute United States markets represent the most penetrable channel given reimbursement shifts toward outpatient wound care. Direct-to-clinic distribution partnerships bypass entrenched group purchasing organization gatekeeping. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified medical technology conglomerates with existing hospital system relationships over pure-play dressing specialists. Long-term viability hinges on therapy system integration capabilities and software companion development for wound monitoring. Acquisition target archetype: mid-cap soft silicone adhesion specialists with validated European quality systems. Monitor ECHA REACH substance evaluation timelines as inflection indicator for antimicrobial modality switching costs.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Antimicrobial Claim Submission | Clearance under FDA 510(k) pathway unlocks hospital formulary access and GPO contract eligibility. |
| CE Marking Pathway under EU MDR | Notified body involvement for active substance-containing dressings creates compliance moats for validated manufacturers. |
| Hospital System Direct Partnership | Integrated delivery network contracts bypass distributor markups and secure recurring volume commitments. |
| Software Companion Development | Wound imaging and monitoring apps extend product lifecycle value beyond physical dressing replacement. |
| Reimbursement Strategy Optimization | Favorable coding for bioactive formats in select European markets commands premium positioning. |
Research Methodology
A standing panel of wound care clinicians, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers provided ongoing calibration across the research program. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA medical device registrations, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up unit demand modeling and top-down market sizing triangulation ensured consistency.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions including product format, wound type, care setting, delivery technology, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to penetration-adjusted addressable populations. Forecast inputs incorporated aging demographic projections, diabetic foot ulcer prevalence trajectories, and regulatory pathway timeline assumptions.
Forecasts assume regulatory continuity in FDA 510(k), EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Specific risk factors include ECHA REACH substance evaluation outcomes, silver price volatility, and hospital procurement centralization pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Chronic Wound Care Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Wound Retractor Market
Wound Care
Wound Care Centers Market
Wound Care
Wound Drainage Devices Market
Wound Care
Philippines Wound Care Market
Wound Care
Wound Irrigation Solutions Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Wound Care Biologics Market
Wound Care
Maggot Debridement Market
Wound Care
Global Burn Care Market
Wound Care
Burn Care Centers Market
Wound Care
Wound Closure Strips Market
Wound Care
Biopatches Market
Wound Care
Advanced Wound Care Market
Wound Care
North America Advanced Wound Care Market