
 Glenoid Fossa Prosthesis Market | 2026-2036
Glenoid Fossa Prosthesis Market Size, Share, and Industry Trends Forecast 2026-2036
Glenoid Fossa Prosthesis Market Analytics
Orthopedic clinics is expanding their share of glenoid fossa prosthesis procedures as ambulatory surgical centers gain capacity for complex shoulder arthroplasty. Zimmer Biomet leverages its comprehensive shoulder portfolio to sustain leadership across cemented and uncemented implant lines. Stryker anchors its position through integrated surgical navigation systems that pair with glenoid component placement. Exactech specializes in biologic-augmented fixation technologies that differentiate its hybrid implant offerings in revision-heavy settings.
A glenoid fossa prosthesis is a synthetic implant that replaces the shallow socket of the scapula in total shoulder arthroplasty, typically manufactured from ultra-high molecular weight polyethylene articulating surfaces backed by titanium or cobalt-chromium trays with porous coating for osseointegration. The device restores glenohumeral joint congruity and load distribution in patients with osteoarthritis, rotator cuff tear arthropathy, or post-traumatic deformity. Cemented polyethylene implants dominate current procedural volumes due to established surgical technique and predictable initial fixation, while uncemented porous-coated designs represent the fastest-growing category as surgeons pursue biologic fixation in younger, higher-demand patients. Biocompatible alloys command premium positioning in revision constructs where bone stock deficiency demands enhanced structural support.
The FDA's 510(k) and PMA pathways govern market entry for glenoid fossa prostheses in the United States, while the EU Medical Device Regulation imposes enhanced clinical evidence requirements for CE marking across European markets. ISO 5832 standards for implant materials and ASTM F2028 testing protocols for glenoid component loosening resistance shape baseline product specifications that manufacturers must satisfy for regulatory clearance. Stakeholders should monitor evolving CMS reimbursement determinations for outpatient shoulder arthroplasty and the trajectory of patient-specific instrumentation adoption as these forces reshape procurement priorities across hospital and clinic settings.
Market Dynamics
Patient-specific instrumentation is compressing operative time and implant malposition rates, forcing manufacturers to integrate 3D planning software with glenoid component portfolios or cede procedural influence to independent surgical navigation vendors.
Growth Catalysts
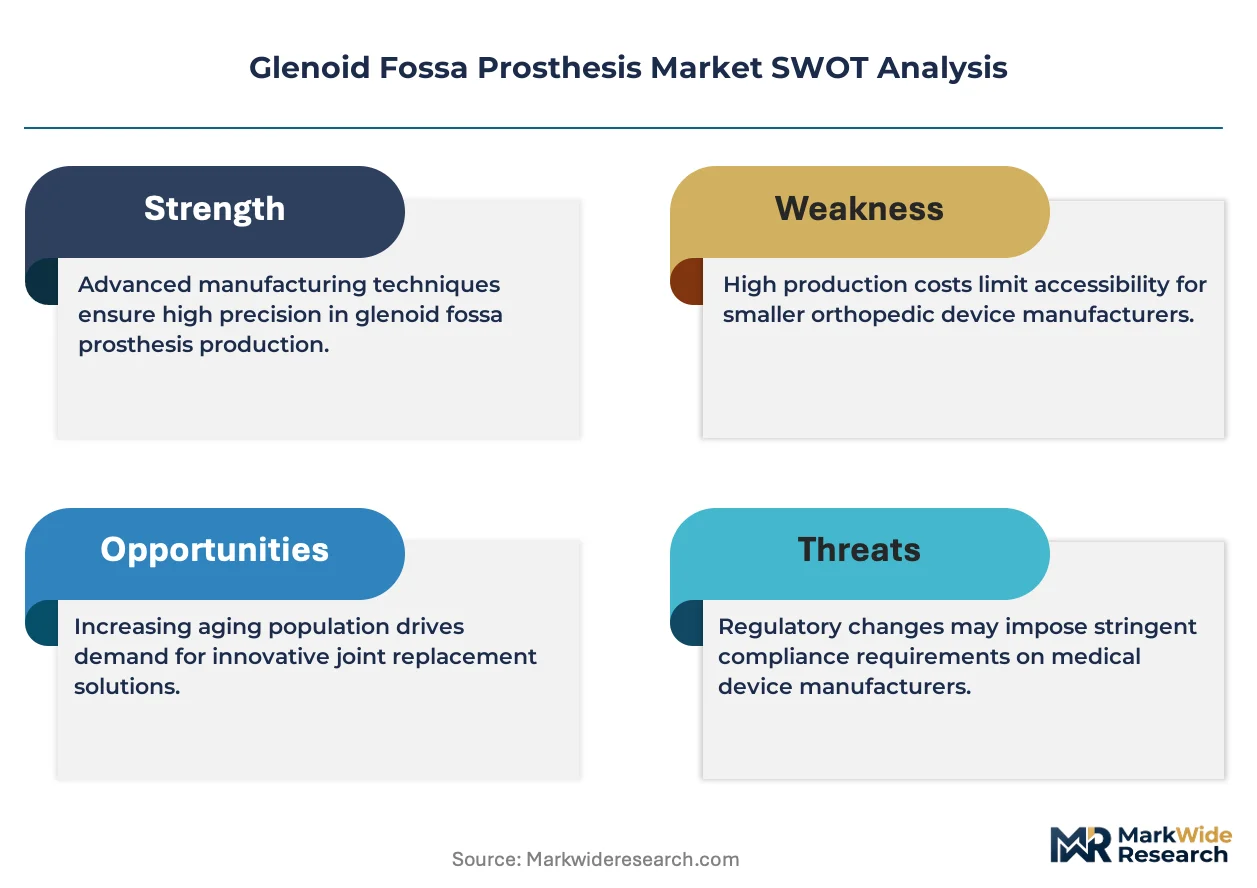
- Ambulatory Surgical Center Expansion:CMS reimbursement determinations for outpatient shoulder arthroplasty enable orthopedic clinics to capture complex procedures previously restricted to inpatient settings.
- Biologic Fixation Demand:Younger, higher-demand patients drive surgeon preference toward uncemented porous-coated designs that achieve osseointegration without cement mantle complications.
- Aging Demographics:United States population over 65 sustains procedural volume growth through established Medicare reimbursement pathways for primary and revision shoulder replacement.
Market Restraints
- Polyethylene Wear Debris:Osteolysis from particulate generation limits implant longevity in younger patients, constraining addressable market for standard polyethylene articulations.
- FDA Premarket Approval Timelines:PMA pathway requirements for novel fixation surfaces extend development cycles 18-36 months beyond 510(k) cleared alternatives.
- Titanium Alloy Supply Concentration:Aerospace and medical device competition for ASTM F136 certified bar stock creates input cost volatility for porous-coated tray manufacturers.
Strategic Opportunities
- Revision Arthroplasty Constructs:Bone stock deficiency in failed primary cases creates demand for augmented fixation with trabecular metal augments and graft containment systems.
- EU MDR Clinical Evidence Pathways:Enhanced post-market surveillance requirements favor incumbent manufacturers with established clinical registries over new market entrants.
- Orthopedic Clinic Direct Contracting:Large ambulatory chains negotiate implant bundles that bypass traditional hospital procurement committees, opening channel access for differentiated portfolios.
Industry Challenges
- Glenoid Component Positioning Accuracy:Surgeon learning curves for navigation-assisted implantation create operative time penalties that offset efficiency gains from patient-specific guides.
- Cross-Reference Compatibility:Modular humeral stem and glenoid tray interface standardization gaps force hospitals to maintain redundant inventory across manufacturer ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glenoid Fossa Prosthesis Market |
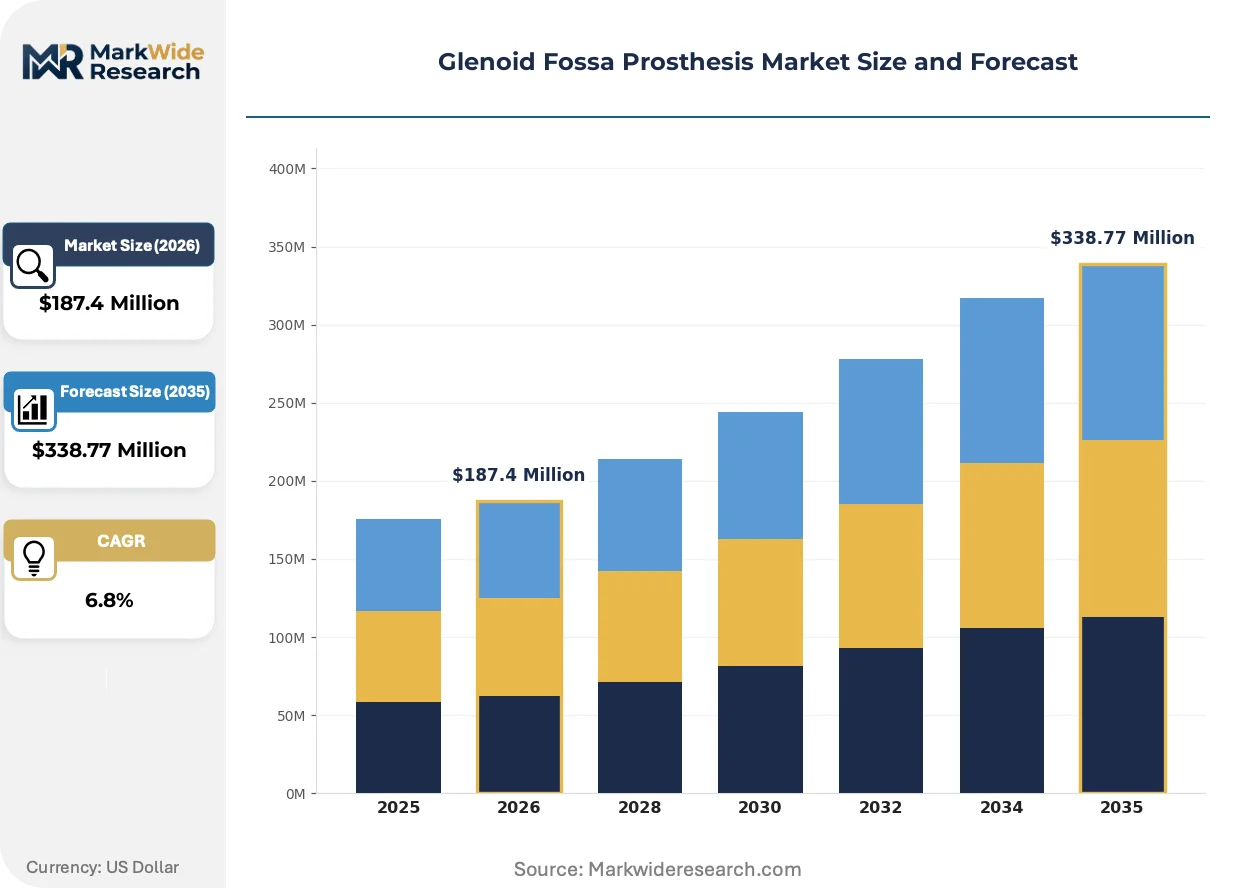
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cemented, Hybrid, Uncemented, Resurfacing End User: Hospitals, Orthopedic Clinics, Rehabilitation Centers, Outpatient Facilities Material: Polyethylene, Titanium, Cobalt-Chromium, Biocompatible Alloys Distribution Channel: Direct Sales, Online Retail, Medical Distributors, Wholesalers |
| Companies Covered | Johnson & Johnson, Zimmer Biomet, Arthrex, Smith & Nephew, Stryker, Exactech, Lima Corporate, DePuy Synthes, Integra LifeSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glenoid Fossa Prosthesis Market Evolving Landscape
Shoulder arthroplasty is bifurcating into high-volume cemented primary procedures and complex uncemented revisions, with technology investment concentrating on tools that improve glenoid component positioning accuracy regardless of fixation method.
Trabecular titanium structures with engineered pore geometries are electrifying biologic fixation performance in uncemented glenoid components. Academic medical centers and high-volume orthopedic groups are adopting these surfaces for patients under 60 at accelerating rates. This material transition is compressing market share for conventional plasma-sprayed coatings while elevating raw material qualification burdens on suppliers.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class III permanent implants are extending CE marking timelines for novel glenoid tray designs. Manufacturers must now maintain post-market clinical follow-up registries that track implant survival and patient-reported outcomes. European orthopedic device divisions are responding by consolidating product pipelines around proven fixation platforms rather than proliferating SKU counts.
Hospital purchasing committees are unbundling implant procurement from instrument and navigation system contracts that historically locked facilities into single-source relationships. Large health systems now negotiate component pricing separately from capital equipment acquisitions, enabling mixed-vendor environments in operating rooms. This behavioral shift is most visible in United States integrated delivery networks that centralize orthopedic spend across 10-plus facility footprints.
Glenoid Fossa Prosthesis Market Segmentation
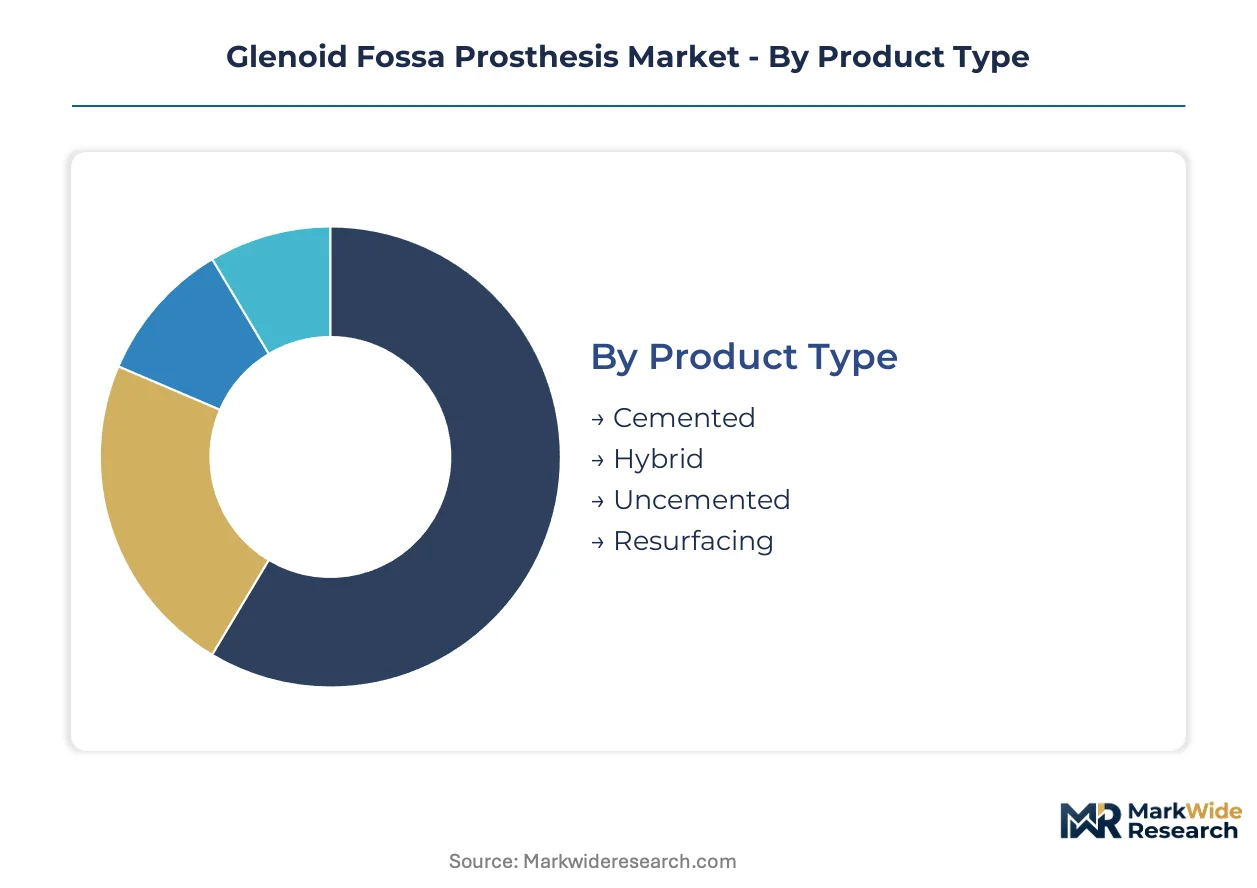
Shoulder arthroplasty procurement patterns diverge sharply across fixation philosophy, care setting, and material specification. Surgeons select glenoid components based on patient bone quality, age, and revision risk, creating distinct demand clusters that manufacturers must address through specialized product lines.
Product Type:
Upgrade cycles from cemented to biologic fixation are compressing as younger patients demand longer implant survival. Each fixation approach carries distinct surgical learning curves and revision implications.
- Cemented:Polyethylene components fixed with polymethylmethacrylate bone cement dominate current procedural volumes due to predictable immediate fixation and established surgical technique. Demand concentrates in United States hospitals serving Medicare populations where surgeon familiarity and reimbursement stability support high-volume primary arthroplasty.
- Uncemented:Porous-coated titanium trays achieve biological osseointegration without cement mantle complications. Academic medical centers in Germany and the United States deploy these designs for patients under 60 seeking activity preservation, though longer operative times and steep learning curves constrain adoption.
- Hybrid:Combines cemented polyethylene articulation with uncemented metal-backed tray for selective fixation. French and Swiss orthopedic groups favor this configuration in revision settings with compromised glenoid bone stock.
- Resurfacing:Bone-preserving implants for young patients with focal cartilage defects. Limited to specialized shoulder centers in London and Boston with advanced arthroscopy integration.
Volume placements concentrate in Cemented; the faster expansion belongs to Uncemented.
End User:
Care setting economics reshape procurement authority and implant selection criteria. Reimbursement differentials between inpatient and outpatient channels drive vendor contracting strategies.
- Hospitals:Integrated delivery networks in Texas and California maintain centralized orthopedic implant committees that negotiate multi-year contracts spanning cemented and uncemented portfolios. OR block scheduling and resident training programs sustain cemented polyethylene dominance despite longer case times.
- Orthopedic Clinics:Ambulatory surgical centers in Florida and Arizona capture complex shoulder arthroplasty through CMS outpatient reimbursement expansion. These facilities prioritize instrument standardization and rapid turnover, favoring cemented systems with streamlined tray configurations.
- Rehabilitation Centers:Post-acute facilities coordinate with implanting surgeons on motion protocols but do not directly procure glenoid components.
- Outpatient Facilities:Stand-alone surgery centers in North Carolina and Ohio exploit geographic carve-outs from hospital systems, demanding price transparency and consignment inventory models.
Procedure volume clusters in Hospitals; Orthopedic Clinics are climbing the fastest as site-of-service migration accelerates.
Material:
Raw material qualification burdens and supply concentration shape component economics and regulatory pathway complexity.
- Polyethylene:Ultra-high molecular weight polyethylene articulating surfaces remain the standard bearing material due to wear characteristics and decades of clinical surveillance. United States manufacturers source resin from certified suppliers meeting ASTM F648 specifications.
- Titanium:ASTM F136 certified bar stock for porous-coated trays faces aerospace competition, creating input cost volatility. German and Japanese orthopedic device divisions maintain strategic inventory buffers.
- Cobalt-Chromium:High-strength alloys for revision constructs with severe bone deficiency. Limited to specialized trauma centers in Paris and Vienna.
- Biocompatible Alloys:Tantalum and trabecular metal augments for graft containment in revision arthroplasty. Premium positioning restricts deployment to quaternary referral centers.
Component fabrication concentrates on Polyethylene; Titanium alloys are gaining share fastest through uncemented fixation expansion.
Distribution Channel:
Channel structure determines pricing transparency and inventory carrying costs across manufacturer and provider balance sheets.
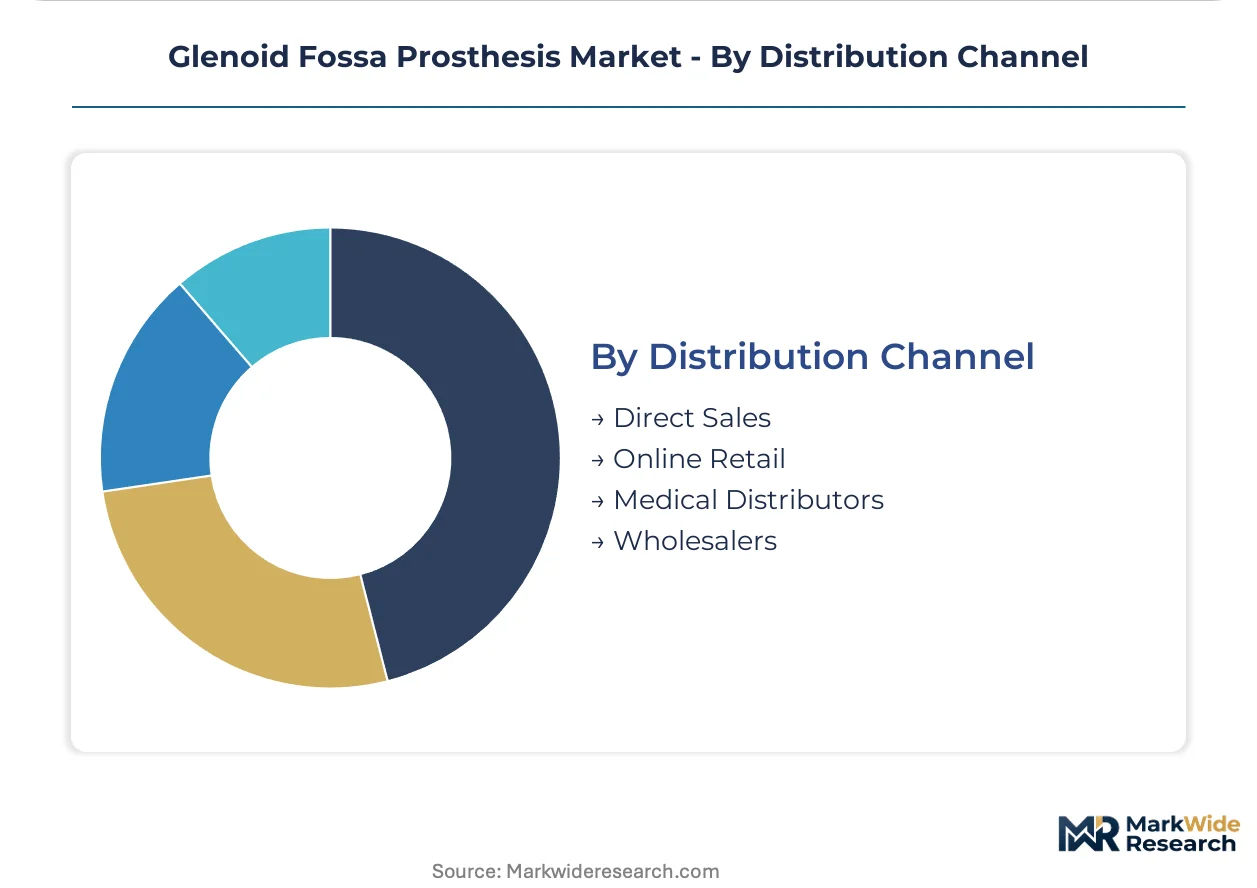
- Direct Sales:Manufacturer representatives maintain consignment inventory at high-volume hospital accounts, providing case coverage and technical support. Zimmer Biomet and Stryker field teams dominate United States metropolitan markets.
- Medical Distributors:Regional orthopedic specialists in Italy and Spain manage logistics for mid-tier hospitals lacking direct manufacturer relationships.
- Online Retail:Limited to disposable instrumentation and consumables; permanent implants require regulatory traceability incompatible with e-commerce models.
- Wholesalers:Generic tray components for emerging markets where brand premium is unsustainable.
Revenue flow concentrates through Direct Sales; Medical Distributors are expanding fastest in European secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while procedural demand clusters in aging Western economies with established shoulder arthroplasty reimbursement pathways. Production capacity for porous-coated titanium trays runs ahead of consumption in several Asian markets.
United States
Medicare reimbursement stability and ambulatory surgical center expansion drive procedural volume in Florida and Arizona. The FDA's PMA pathway for novel fixation surfaces extends approval timelines for innovative designs. High-volume orthopedic groups in Texas and California negotiate centralized implant contracts across integrated delivery networks.
Germany
Academic medical centers in Bavaria and Baden-Württemberg pioneer uncemented porous-coated adoption for patients under sixty. The EU Medical Device Regulation imposes enhanced clinical evidence requirements for CE marking of Class III permanent implants. Berlin-based research consortia coordinate post-market surveillance registries tracking implant survival outcomes.
France
Hybrid fixation configurations gain traction in revision settings with compromised glenoid bone stock. ANSM oversees premarket conformity assessment for shoulder arthroplasty systems under MDR transition timelines. Parisian quaternary referral centers deploy biocompatible alloy augments for complex reconstructive cases.
Switzerland
Swissmedic maintains stringent quality system audits for orthopedic device manufacturers seeking market authorization. Zurich and Geneva orthopedic clinics emphasize patient-specific instrumentation integration with glenoid component placement. Premium positioning of trabecular metal constructs supports above-average implant pricing in private hospital channels.
Japan
PMDA's pharmaceutical and medical device agency evaluates shoulder arthroplasty systems through structured Sakigake fast-track pathways for innovative technologies. Tokyo and Osaka metropolitan hospitals concentrate revision arthroplasty expertise for complex glenoid deficiency cases. Aging demographics exceed Western European rates, sustaining long-term procedural demand projections.
Glenoid Fossa Prosthesis Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through integrated surgical navigation and comprehensive shoulder portfolios, while mid-scale specialists concentrate on biologic-augmented fixation technologies. The vendor base stratifies across three archetypes: diversified orthopedic conglomerates with navigation system integration, mid-cap specialists with hybrid implant differentiation, and regional fabricators serving price-sensitive secondary markets. Consolidation pressure intensifies as hospitals unbundle implant procurement from instrument contracts. Technology licensing agreements for trabecular titanium surfaces represent a dominant competitive move alongside direct contracting with large ambulatory surgical center chains.
Within the diversified orthopedic tier, Zimmer Biomet and Stryker exemplify scale-driven portfolio breadth, while Exactech occupies a position among mid-cap specialists emphasizing biologic fixation differentiation. These three entities represent distinct strategic postures: comprehensive shoulder system integration, surgical navigation pairing, and hybrid implant technology specialization respectively.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Zimmer Biomet |
| Arthrex |
| Smith & Nephew |
| Stryker |
| Exactech |
| Lima Corporate |
| DePuy Synthes |
| Integra LifeSciences |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks in Texas and California anchor procurement volume for glenoid fossa prostheses, concentrating purchasing power around contract-based long-term offtake agreements that compress margin structures for manufacturers lacking comprehensive shoulder portfolios.
Pricing Analysis
Margin tightening in standard cemented polyethylene components reflects hospital purchasing committees unbundling implant procurement from instrument and navigation system contracts. Three-tier pricing structure across premium trabecular metal constructs, standard porous-coated titanium trays, and economy cemented polyethylene dominates vendor negotiations. Price differentiation hinges on FDA PMA pathway certification and geographic delivery cost differentials between domestic and imported tray substrates. Ambulatory surgical centers in Florida and Arizona exhibit highest price sensitivity due to CMS reimbursement compression, while quaternary referral centers in Paris and Boston absorb premium positioning for revision constructs.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume cemented polyethylene demand through manufacturer representative consignment models, while medical distributors manage logistics for mid-tier European accounts. Production concentrates in Germany, the United States, and Switzerland for porous-coated titanium tray fabrication. Raw material sourcing draws from ASTM F136 certified bar stock suppliers facing aerospace competition, ultra-high molecular weight polyethylene resin meeting ASTM F648 specifications, and biocompatible tantalum for revision augments. Single-source vulnerability in titanium alloy supply creates input cost volatility for uncemented component manufacturers. Distribution runs through direct sales for metropolitan hospital systems and regional orthopedic specialists for secondary European cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glenoid fossa prosthesis manufacturing is consolidating around vendors with integrated surgical navigation and comprehensive shoulder portfolios, as hospital unbundling of procurement contracts eliminates single-product specialists lacking capital equipment ecosystems.
For Market Incumbents: Anticipate ambulatory surgical center direct contracting expansion by securing consignment inventory agreements with large orthopedic chains in Florida and Arizona before competitors establish tray standardization. Backward integration into trabecular titanium surface manufacturing reduces raw material qualification burdens and defends margin position against aerospace demand for certified bar stock. For New Entrants and Emerging Players: Digital-channel route through patient-specific instrumentation software partnerships offers lower regulatory barrier entry than PMA pathway implant submissions. Target hybrid fixation configurations for French and Swiss revision markets where bone stock deficiency creates demand for biologic-augmented constructs. Pursue technology licensing agreements for trabecular metal surfaces rather than proprietary surface development. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with hybrid implant differentiation and established European clinical registries under EU MDR compliance. Long-term viability rests on consolidation plays capturing ambulatory surgical center procurement authority as site-of-service migration accelerates. Monitor CMS reimbursement determinations for outpatient shoulder arthroplasty as volume inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | PMA pathway for novel trabecular titanium surfaces extends approval timelines 18-36 months beyond 510(k) alternatives. |
| CE Marking Pathway | EU MDR enhanced clinical evidence requirements favor incumbent manufacturers with established post-market surveillance registries. |
| Hospital System Partnership | Integrated delivery networks in Texas and California negotiate multi-year implant contracts spanning cemented and uncemented portfolios. |
| Software Companion Development | Patient-specific instrumentation integration compresses operative time and implant malposition rates in academic medical centers. |
| Reimbursement Strategy | CMS outpatient shoulder arthroplasty determinations enable orthopedic clinics to capture complex procedures previously restricted to inpatient settings. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with shoulder arthroplasty surgeons, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and orthopedic device manufacturer regulatory affairs leads. FDA 510(k) and PMA submission databases, EU MDR notified body conformity assessments, CMS Medicare reimbursement determinations, and hospital procurement contract registries provided validation anchors. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue segmentation.
Granularity-level modeling addressed fixation philosophy, care setting economics, material specification tiers, and geographic regulatory clusters across the projection horizon. Segmentation dimensions included cemented versus uncemented versus hybrid versus resurfacing configurations, hospital versus orthopedic clinic versus outpatient facility end users, polyethylene versus titanium versus cobalt-chromium versus biocompatible alloy materials, and direct sales versus medical distributor channels. CAGRs derived from procedural volume growth trajectories, reimbursement pathway stability assessments, and technology adoption curve analysis for patient-specific instrumentation and surgical navigation pairing.
The model holds under stable Medicare reimbursement and continued ambulatory surgical center site-of-service migration; deviation in FDA PMA pathway stringency or titanium alloy supply disruption would shift volume and value projections. Forecasts reflect base-case assumptions regarding EU MDR compliance timelines and orthopedic clinic consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Dental Implants Market
Dental Devices
United Kingdom Dental Devices Market
Dental Devices
Dental Radiometer Market
Dental Devices
Dental Scalers Market
Dental Devices
Latin America Dental Devices Market
Dental Devices
United States Dental Implants Market
Dental Devices
Italy Dental Devices Market
Dental Devices
Dental Regeneration Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Crown Removal Market
Dental Devices
GCC Dental Implants Market
Dental Devices
Global Dental Laboratory Welders Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Aligners Market
Dental Devices
Dental Restoration Market