
 Dental Restoration Market | 2026-2036
Dental Restoration Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Restoration Market Analysis
Modular chairside bundling is hardening as the dominant procurement pattern for dental practices. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to control digital workflow margins from scan to mill. Institut Straumann AG anchors its position through backward integration into implant abutment manufacturing. Henry Schein competes on distribution density, sustaining same-day delivery networks across urban dental clusters.
Dental restoration encompasses the clinical repair and replacement of damaged or missing tooth structure using biocompatible materials engineered to withstand occlusal forces between 150 and 350 Newtons. Porcelain-fused-to-metal systems and monolithic zirconia dominate structural load-bearing applications, while resin composites serve aesthetic anterior repairs through layered photopolymerization. Material selection drives margin architecture, with zirconia commanding premium positioning against commoditized metal alloys in posterior crown fabrication. Application segmentation reveals implants as the fastest-expanding revenue pool, though direct restorations retain volume leadership due to recurring caries treatment cycles.
FDA 510(k) clearance pathways govern permanent implant abutments in the United States, while the EU MDR and CE marking framework impose post-market surveillance obligations across European member states. ISO 6872 standards for ceramic materials and ISO 10477 for polymer-based restoratives establish baseline mechanical property benchmarks that manufacturers must document for market access. Stakeholders must monitor convergence between regulatory data requirements and real-world evidence collection systems as payers tighten reimbursement verification protocols.
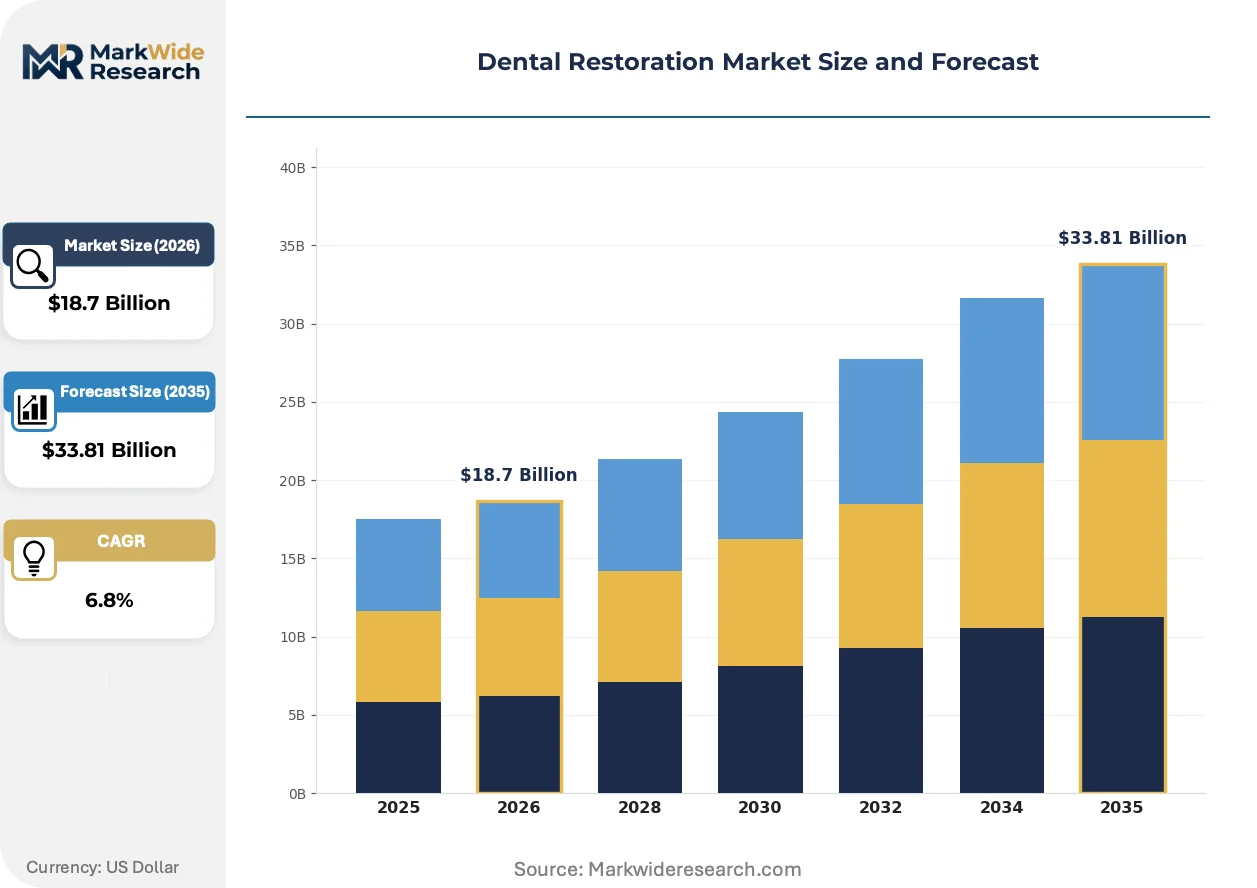
Market Dynamics
Digital workflow adoption in European dental clinics is compressing traditional laboratory turnaround times and redistributing value capture from independent labs toward integrated chairside systems.
Growth Catalysts
- EU MDR Material Traceability Mandates:Permanent implant manufacturers must document supply chain provenance, favoring vertically integrated producers with captive zirconia sourcing and internal milling capabilities over fragmented suppliers.
- Resin Composite Layering Advances:Photopolymerization protocols now achieve aesthetic anterior repairs matching porcelain translucency, expanding indications for direct restorations in Germany's high-volume caries treatment market.
- Germany Laboratory Outsourcing Acceleration:Dental practices in Bavaria and Baden-Württemberg increasingly outsource crown fabrication to centralized digital production hubs, reducing per-unit labor costs and equipment depreciation burdens.
Market Restraints
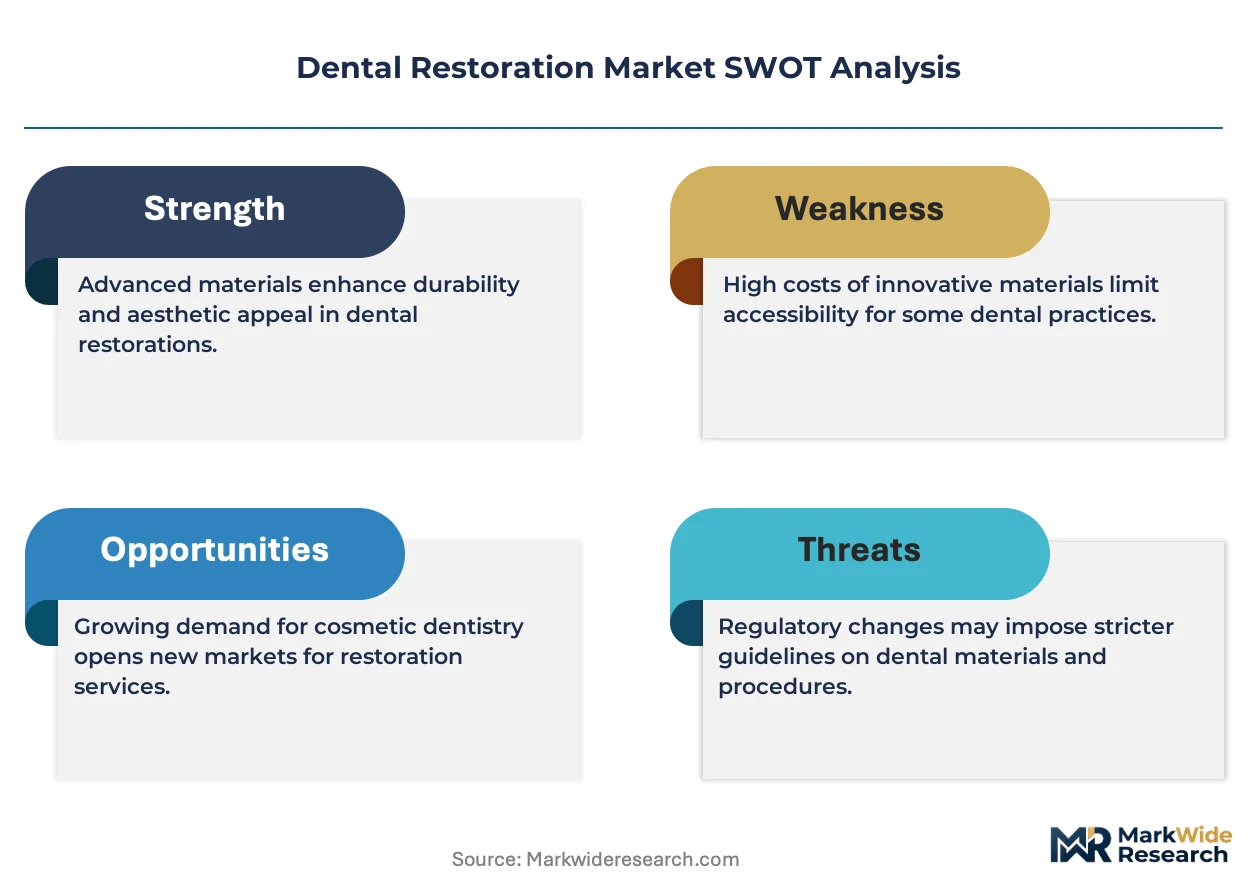
- Zirconia Powder Supply Concentration:High-purity yttria-stabilized zirconia feedstock concentrates among three Asian chemical processors, exposing European restoration manufacturers to input cost volatility and geopolitical supply interruptions.
- ISO 6872 Mechanical Testing Burden:Ceramic material certification requires extensive flexural strength documentation and fracture toughness validation, extending product development timelines by 12-18 months for novel formulations.
- Metal Alloy Commoditization Pressure:Non-precious cobalt-chrome and nickel-chrome substrates face pricing compression from Asian foundry exports, eroding margins for European producers lacking premium zirconia positioning.
Strategic Opportunities
- Poland and Czech Republic Dental Clinic Expansion:Private practice density remains 40% below German levels, creating whitespace for CAD/CAM system vendors and consumable distributors to establish early workflow standardization.
- AI-Assisted Occlusal Design Convergence:Machine learning algorithms integrated with intraoral scanning software reduce remill rates and chairside adjustment time, opening premium pricing tiers for algorithm-enabled restoration planning.
- EU Green Deal Biomaterial Incentives:Bio-ceramic and plant-derived resin research receives Horizon Europe funding priority, positioning early movers for preferential procurement in sustainability-focused Nordic public health systems.
Industry Challenges
- CAD/CAM Technician Skill Scarcity:Digital design expertise lags hardware deployment, forcing practices to retain legacy technicians for complex implant abutment cases while training staff on chairside milling protocols.
- Legacy Practice Management Integration Friction:New digital workflows require API connectivity with existing patient record systems, creating implementation delays and temporary productivity losses during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Restoration Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crowns, Bridges, Inlays, Onlays Material: Porcelain, Resin, Metal, Composite Application: Implants, Direct Restorations, Indirect Restorations, Cosmetic Procedures End User: Dentists, Dental Clinics, Hospitals, Laboratories |
| Companies Covered | Dentsply Sirona, Envista Holdings Corporation, 3M Company, Institut Straumann AG, Ivoclar Vivadent AG, Henry Schein, Zimmer Biomet Holdings, Danaher Corporation, Coltene Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Restoration Market Emerging Trajectories
Workflow digitization is compressing the traditional boundary between clinical diagnosis and laboratory fabrication, enabling same-day restoration delivery while redistributing technical competencies across the value chain.
Monolithic zirconia is consolidating posterior crown applications through improved translucency grades and simplified cementation protocols. German dental clinics now specify high-translucency zirconia for 80% of molar restorations, displacing layered porcelain-fused-to-metal systems that require separate metal substructure fabrication and multiple patient appointments. This consolidation is enabling single-visit crown delivery and reducing laboratory outsourcing volumes.
EU MDR post-market surveillance obligations are tightening adverse event reporting requirements for permanent implant abutments. Manufacturers must establish systematic vigilance procedures documenting long-term biocompatibility outcomes, increasing compliance staffing and IT infrastructure investments. German notified bodies interpret these requirements most strictly, creating regulatory friction for smaller producers seeking CE marking renewal.
Subscription-based consumable bundling is displacing transactional procurement in urban dental clusters. Practices in Frankfurt, Munich, and Hamburg increasingly contract for monthly zirconia block and milling bur replenishment tied to scanner hardware leases, replacing spot purchasing from independent dental distributors. This shift locks in supply relationships and reduces price transparency for competing material suppliers.
Dental Restoration Market Segmentation
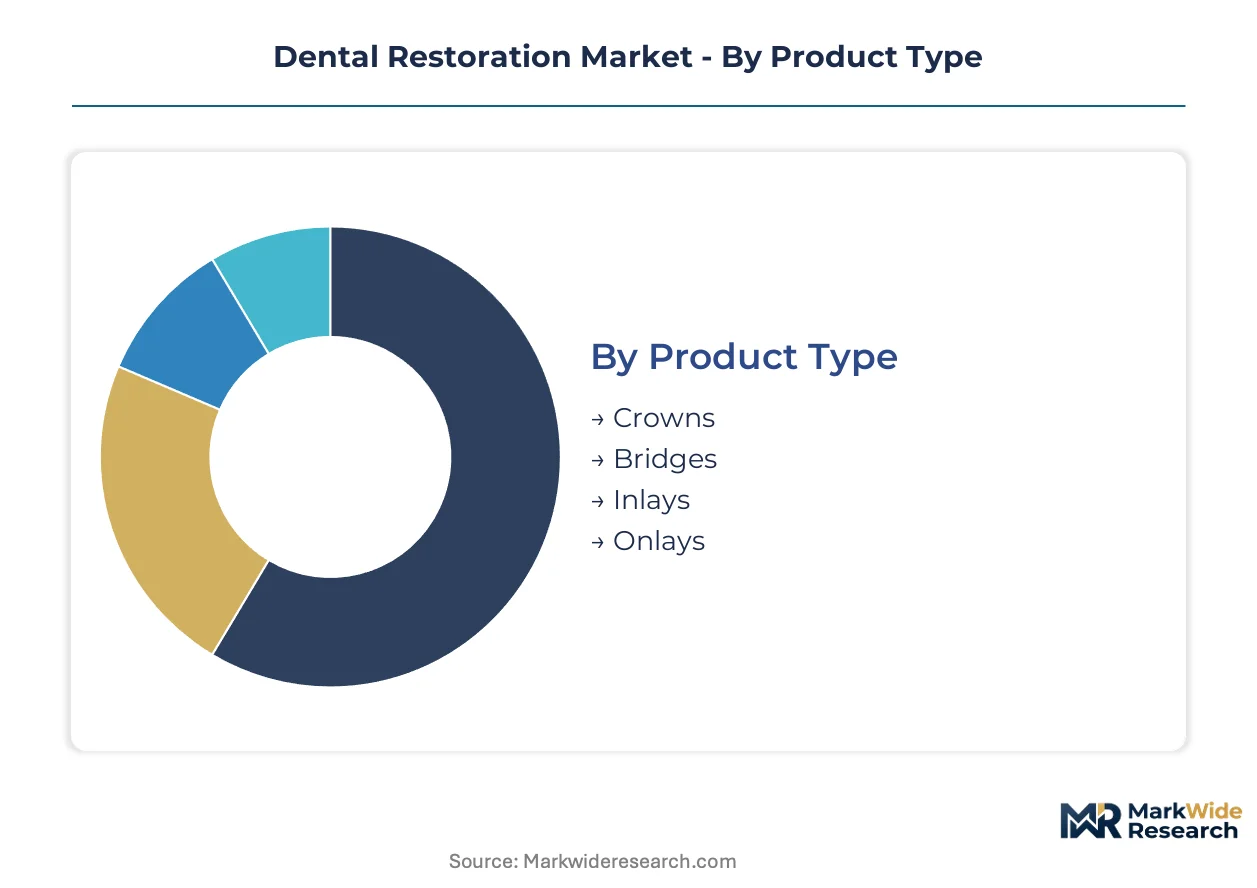
Dental restoration segmentation reveals how regulatory pathways and reimbursement structures fragment procurement decisions across clinical settings. Material selection drives certification requirements, while end-user type determines whether FDA 510(k) or EU MDR compliance costs dominate vendor economics.
Product Type:
FDA 510(k) clearance governs permanent crown and bridge systems in the United States, while EU MDR technical documentation requirements vary by restoration complexity and patient contact duration.
- Crowns:Full-coverage restorations fabricated from monolithic zirconia or porcelain-fused-to-metal substructures. German dental clinics now specify high-translucency zirconia variants for molar applications, compressing traditional laboratory outsourcing volumes through chairside milling adoption.
- Bridges:Multi-unit fixed prostheses spanning edentulous spaces with biomechanical load distributed across abutment teeth. Demand concentrates in Bavaria and Baden-Württemberg where centralized digital production hubs reduce per-unit fabrication costs for multi-tooth reconstructions.
- Inlays:Intracoronal restorations preserving cuspal integrity through adhesive cementation protocols.
- Onlays:Partial-coverage options extending over one or more cusps for moderate structural compromise.
Crowns sit at the top of the volume ranking, with bridges climbing the fastest as laboratory outsourcing accelerates across German metropolitan clusters.
Material:
Cost stratification separates premium ceramic systems from commoditized metal substrates, with ISO 6872 mechanical testing burden falling heaviest on novel formulations.
- Porcelain:Feldspathic and leucite-reinforced glass-ceramics engineered for aesthetic anterior layering. Frankfurt and Munich practices specify porcelain for 80% of visible restorations, though zirconia displacement threatens volume share in posterior applications.
- Resin:Photopolymerized methacrylate composites for direct chairside placement. Photopolymerization protocols achieving porcelain-matching translucency are expanding indications in Germany's high-volume caries treatment market.
- Metal:Cobalt-chrome and nickel-chrome substrates facing pricing compression from Asian foundry exports.
- Composite:Particle-filled hybrid materials balancing strength and polishability for load-bearing posterior repairs.
Porcelain maintains volume leadership in aesthetic applications, while resin gains share fastest through direct restoration workflow compression.
Application:
Patient contact duration and invasiveness determine whether EU MDR post-market surveillance obligations apply, with permanent implants triggering the strictest vigilance requirements.
- Implants:Osseointegrated titanium fixtures with custom abutments and superstructures. EU MDR material traceability mandates favor vertically integrated producers with captive zirconia sourcing over fragmented suppliers serving Hamburg and Berlin implantology centers.
- Direct Restorations:Chairside-placed resin composites and glass ionomers without laboratory fabrication. Recurring caries treatment cycles in Poland and Czech Republic private practices sustain volume leadership despite lower per-procedure revenue.
- Indirect Restorations:Laboratory-fabricated crowns and inlays requiring multiple patient appointments.
- Cosmetic Procedures:Veneers and aesthetic reconstructions driven by patient-funded elective demand.
Direct restorations command the highest procedure volume, with implants expanding most quickly through subscription-based consumable bundling in urban German clusters.
End User:
Procurement sophistication varies sharply, with dental clinics adopting scanner-hardware leases while independent dentists resist capital equipment transitions.
- Dentists:Solo and small-group practices representing fragmented purchasing power across European markets.
- Dental Clinics:Multi-chair facilities with standardized digital workflows. Frankfurt, Munich, and Hamburg clinics increasingly contract monthly zirconia block replenishment tied to hardware leases, locking supply relationships and reducing price transparency.
- Hospitals:Academic and public health institutions with centralized procurement and sustainability mandates.
- Laboratories:Independent fabrication centers facing margin compression from chairside milling adoption.
Dental clinics lead absolute spending, with hospitals gaining procurement influence fastest through EU Green Deal biomaterial incentives in Nordic public health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dental restoration industry traces its modern scaling to Switzerland's precision machining heritage and Germany's ceramics engineering tradition, with these foundations now diffusing across European digital workflows and Asian manufacturing clusters.
Germany
Bavarian and Baden-Württemberg dental clinics drive laboratory outsourcing acceleration, compressing traditional fabrication timelines through centralized digital production hubs. The EU MDR imposes strictest material traceability interpretations through German notified bodies, favoring vertically integrated producers with captive zirconia sourcing. Frankfurt, Munich, and Hamburg practices now contract monthly consumable bundles tied to scanner hardware leases.
United States
FDA 510(k) clearance pathways govern permanent implant abutments, with reimbursement verification protocols tightening across commercial payers. The agency's post-market surveillance requirements concentrate compliance investments among multi-product manufacturers. Urban dental clusters in Texas and California sustain same-day delivery network competition among distribution-focused suppliers.
Switzerland
Precision implantology heritage anchors high-value abutment manufacturing, with domestic producers leveraging backward integration into ceramic material processing. Swissmedic maintains stringent biocompatibility documentation requirements for permanent implants. The Lake Geneva corridor concentrates R&D facilities for next-generation zirconia formulations.
China
High-purity yttria-stabilized zirconia feedstock concentrates among domestic chemical processors, exposing downstream European manufacturers to input cost volatility. NMPA regulatory pathways for imported dental materials create friction for foreign suppliers seeking market access. The Yangtze River Delta hosts foundry capacity for non-precious metal alloy substrates pressuring European margin structures.
Poland
Private practice density remains 40% below German levels, creating whitespace for CAD/CAM system vendors establishing early workflow standardization. EU structural funds support clinic infrastructure modernization across metropolitan centers. Warsaw and Krakow dental clusters show accelerating adoption of chairside milling systems as equipment financing terms improve.
Dental Restoration Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification and digital workflow integration depth. The vendor base stratifies into three tiers: integrated CAD/CAM ecosystem controllers, implant-focused precision manufacturers, and distribution-density competitors. Strategic archetypes include backward-integrated material processors, hardware-software bundlers, and logistics-optimized distributors. Dominant competitive moves encompass subscription-based consumable locking and AI-assisted design algorithm differentiation.
Within the integrated ecosystem tier, Dentsply Sirona and Institut Straumann AG exemplify contrasting approaches to value capture—one through scanner-to-mill workflow control, the other through implant abutment manufacturing integration. Henry Schein occupies a position among distribution-anchored competitors competing on urban cluster density. These three structures illustrate how geographic origin and corporate form—Sirona's US-listed status, Straumann's Swiss AG structure, Schein's American incorporation—map to distinct margin architectures without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Dentsply Sirona |
| Envista Holdings Corporation |
| 3M Company |
| Institut Straumann AG |
| Ivoclar Vivadent AG |
| Henry Schein |
| Zimmer Biomet Holdings |
| Danaher Corporation |
| Coltene Holding AG |
| Others |
Supply Flow & Price Mechanics
CAD/CAM technician scarcity in Bavaria and Baden-Württemberg compresses labor-cost differentials into three-tier pricing spreads across premium zirconia systems, standard chairside bundles, and commoditized metal alloy alternatives.
Pricing Analysis
Subscription-based hardware-software bundling now dominates procurement in Frankfurt, Munich, and Hamburg dental clusters. Price differentiation separates ISO 6872-certified high-translucency zirconia from uncertified ceramic alternatives and Asian-sourced metal substrates. Cost compression in non-precious cobalt-chrome segments intensifies because foundry exports from the Yangtze River Delta undercut European producers. Independent dentists exhibit highest price sensitivity, while multi-chair dental clinics absorb premium positioning for same-day delivery guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean chemical processors controlling high-purity yttria-stabilized zirconia feedstock. European restoration manufacturers draw from concentrated Asian feedstock, German precision milling equipment, and Swiss implant abutment components. Tariff exposure on ceramic powder imports threatens margin stability for producers lacking captive sourcing. Distribution runs through Henry Schein's urban cluster networks and Dentsply Sirona's direct scanner-hardware lease channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental restoration market functions as a regulatory compounder where EU MDR material traceability mandates accelerate demand for vertically integrated production systems and certified supply chain documentation.
For Market Incumbents: Anchor market position through backward integration into zirconia powder processing and captive milling capability expansion in Germany. Dentsply Sirona's scanner-to-mill ecosystem control and Institut Straumann AG's abutment manufacturing integration demonstrate defensible moats against Asian foundry price erosion. Prioritize ISO 6872 certification maintenance and German notified body relationship investment as EU MDR renewal friction intensifies. For New Entrants and Emerging Players: EU MDR in Europe opens a window for AI-assisted occlusal design software vendors to penetrate Poland and Czech Republic dental clusters where private practice density lags German benchmarks. Target Warsaw and Krakow metropolitan areas with equipment financing partnerships and chairside milling workflow standardization. Pursue Horizon Europe bio-ceramic research funding to position for Nordic public health system procurement preference. For Investors and Strategic Acquirers: Dental clinic chains and private equity consolidators are the most active acquirers in this space, pursuing multi-chair facility rollups in underpenetrated Central European markets. Long-term viability hinges on digital workflow adoption rates and subscription consumable retention metrics. Monitor German notified body CE marking renewal backlogs as an inflection indicator for regulatory compliance cost escalation and vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zirconia Processing | Captive supply of high-purity feedstock insulates EU MDR-compliant producers from Asian chemical processor volatility. |
| AI-Assisted Occlusal Design Deployment | Machine learning algorithms integrated with intraoral scanning software reduce remill rates and enable premium pricing tiers. |
| Subscription-Based Consumable Bundling | Monthly zirconia block replenishment tied to hardware leases locks supply relationships and reduces price transparency. |
| CE Marking Renewal Infrastructure Investment | German notified body vigilance procedures require systematic biocompatibility documentation and IT compliance staffing. |
| Horizon Europe Bio-Ceramic R&D Funding | EU Green Deal biomaterial incentives position early movers for preferential procurement in Nordic public health systems. |
Methodological Framework
Coverage spans Germany, Switzerland, the United States, China, and Poland, with primary inputs from each market cluster. The research combines structured interviews with dental clinic procurement managers, biomedical engineers at implantology centers, GPO contracts managers, and CAD/CAM technician training program directors with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, ISO certification registries, and hospital procurement contract disclosures. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchor market sizing.
Granularity-level modeling disaggregates revenue across material type, application complexity, end-user procurement sophistication, and regional regulatory cluster. The analytical framework projects value evolution across the analysis window through procedure volume forecasting and per-procedure revenue compression assumptions. Segmentation dimensions include restoration product type, ceramic versus metal versus resin material grade, direct versus indirect versus implant application, and dental clinic versus independent dentist versus hospital end-user. CAGRs derive from installed base penetration curves and replacement cycle analysis.
Revisions become necessary when EU MDR enforcement intensity shifts, zirconia powder supply disruptions materialize, or AI-assisted design adoption accelerates beyond baseline assumptions. Forecasts reflect documented assumptions about laboratory outsourcing velocity and chairside milling hardware deployment rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Healing Caps Market
Dental Devices
Global Endodontics Market
Dental Devices
3D Printed Clear Dental Aligners Market
Dental Devices
Dental Anaesthetic Market
Dental Devices
Dental Diamond Burs Market
Dental Devices
Intraoral Dental Sensors Market
Dental Devices
3D-Printed Dental Restoration Market
Dental Devices
Dental Handpieces Market
Dental Devices
Global Veterinary Dentistry Instruments and Equipment Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Air Abrasion Market
Dental Devices
Europe Dental Aligners Market
Dental Devices
Prophy Dental Handpiece Market
Dental Devices
North America Dental Aligners Market
Dental Devices
Dental Caries Market