
 Africa LED and OLED Displays and Lighting Products Market | 2026-2036
Africa LED and OLED Displays and Lighting Products Market Size, Share, and Industry Trends Forecast 2026-2036
Africa LED and OLED Displays and Lighting Products Market Outlook
Multi-source component procurement is decoupling from single-brand lighting system contracts across African infrastructure projects. Signify N.V. leverages its Philips distribution partnerships to dominate municipal streetlight tenders in Cairo and Johannesburg. ams OSRAM AG sustains R&D intensity in horticultural LED spectra for East African greenhouse operators. Samsung Electronics Co., Ltd. anchors premium display supply through direct-to-hotel contracts in Cape Town and Casablanca.
Africa LED and OLED Displays and Lighting Products encompass electroluminescent diode assemblies fabricated on sapphire or silicon substrates, emitting photons through electron-hole recombination in gallium nitride or organic emissive layers, with typical luminous efficacy ranging from 120 to 200 lumens per watt for inorganic LEDs and contrast ratios exceeding 1,000,000:1 for active-matrix OLED panels. These devices serve commercial illumination, digital signage, residential ambiance, and mobile screen applications where energy efficiency and visual performance determine procurement decisions. The Lighting Fixtures segment captures the deepest margin pools through retrofit-driven volume in South African office parks and Nigerian retail chains. OLED technology leads display value concentration in luxury hospitality installations across Morocco and Egypt, while Control Systems segment growth accelerates with smart-city pilots in Kigali and Addis Ababa.
South Africa's National Regulator for Compulsory Specifications enforces SANS energy-performance thresholds that block non-compliant LED imports at Durban and Cape Town ports. Egypt's Egyptian Organization for Standardization and Quality aligns with IEC 62717 for LED module safety, conditioning market access for European and Asian suppliers. Kenya's Energy and Petroleum Regulatory Authority mandates minimum efficacy standards for public lighting contracts, directing procurement toward certified manufacturers. Stakeholders must monitor how divergent national certification timelines reshape cross-border supply routing and inventory positioning.
Market Dynamics
South Africa's SABS energy-efficiency labeling rules are forcing rapid LED retrofit cycles across government buildings, while Lagos and Nairobi commercial signage pulls imported display modules through fragmented procurement channels.
Growth Catalysts
- SANS Performance Thresholds:South Africa's National Regulator for Compulsory Specifications enforces efficacy minimums that accelerate replacement demand in Durban and Cape Town office parks.
- Urban Commercial Signage:Nigerian and Kenyan retail clusters in Lagos, Abuja, and Nairobi drive bulk import of high-brightness LED modules for outdoor digital billboards.
- Horticultural Spectra Development:East African greenhouse operators adopt tunable LED arrays for crop-specific light recipes, expanding addressable fixture demand beyond general illumination.
Market Restraints
- Import Duty Volatility:Egyptian and Nigerian customs regimes impose unpredictable tariff swings on gallium nitride substrates and driver ICs, compressing landed margins for distributors.
- Asian Supply Concentration:Over 70 percent of OLED panel fabrication concentrates in East Asian facilities, exposing African integrators to shipping delays and currency mismatch risks.
- Grid Instability:Frequent voltage fluctuation in Lagos and Kinshasa suburbs degrades LED driver lifespan, forcing warranty reserve inflation that deters premium product positioning.
Strategic Opportunities
- Rwanda Smart-City Pilots:Kigali's networked streetlight control systems create reference installations for neighboring East African municipal tenders.
- Moroccan Luxury Hospitality:Casablanca and Marrakech hotel developments specify active-matrix OLED panels for lobby and suite installations, anchoring premium display value pools.
- Pay-As-You-Go Solar-LED Bundles:Off-grid distributors in rural Tanzania and Kenya merge mobile payment platforms with efficient lighting kits, opening non-grid addressable households.
Industry Challenges
- Certification Timeline Divergence:Egypt's EOS alignment with IEC 62717, Kenya's EPRA efficacy mandates, and South Africa's SANS labeling create non-harmonized testing burdens that fragment inventory positioning.
- Technical Workforce Scarcity:Installation and commissioning of networked control systems in Addis Ababa and Kigali outpaces available certified technician supply, delaying project handovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa LED and OLED Displays and Lighting Products Market |
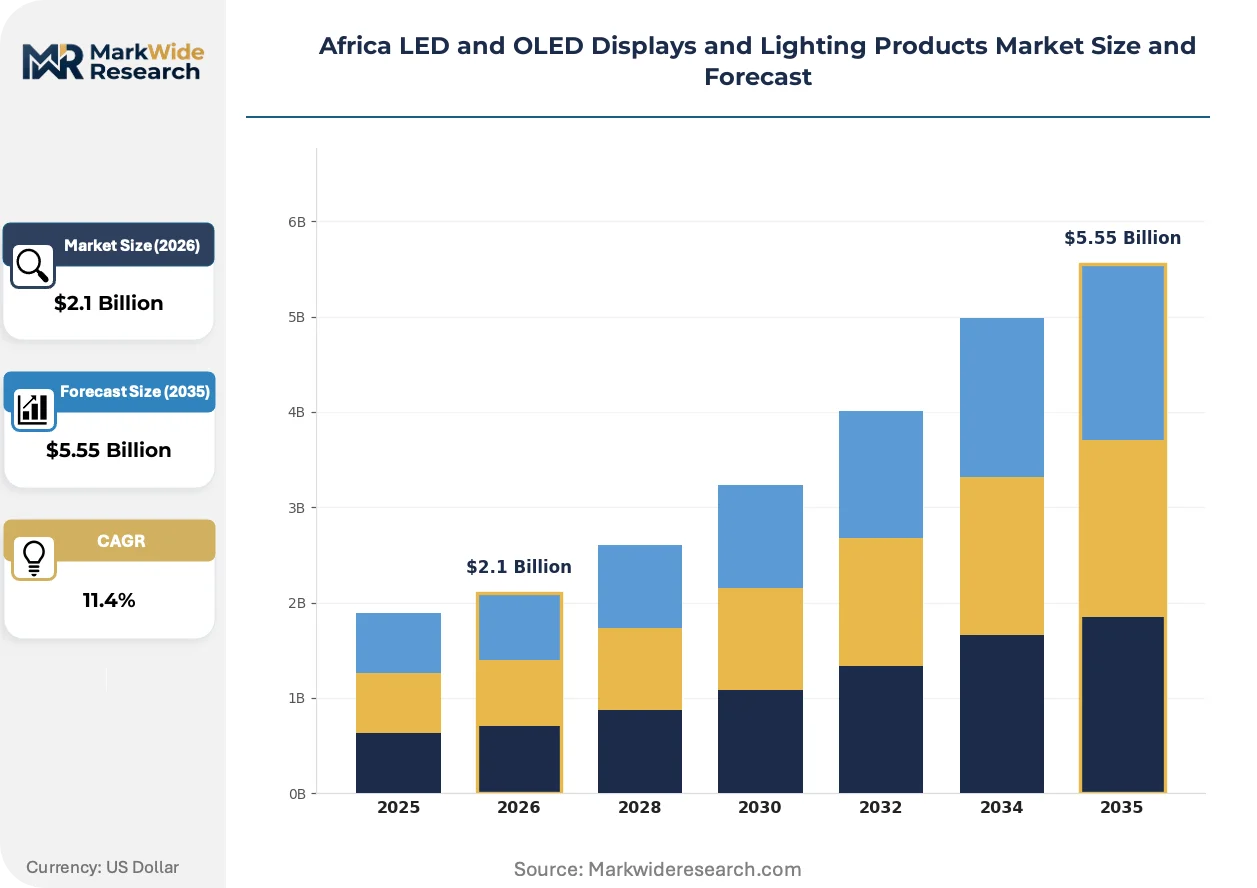
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Displays, Lighting Fixtures, Control Systems, Components Technology: LCD, MicroLED, Quantum Dot, OLED End User: Commercial, Residential, Industrial, Hospitality Application: Signage, General Lighting, Automotive Lighting, Entertainment |
| Companies Covered | Signify N.V., ams OSRAM AG, Acuity Brands Lighting Inc., Cree Lighting, Opple Lighting Co., Ltd., Samsung Electronics Co., Ltd., LG Display Co., Ltd., Sharp Corporation, GE Lighting, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa LED and OLED Displays and Lighting Products Market Strategic Shifts
Three intersecting developments are restructuring how display and lighting products reach African end-users: automated manufacturing integration, divergent national certification regimes, and procurement channel fragmentation.
Micro-LED transfer printing is automating the assembly of fine-pitch display tiles for Nigerian banking halls and South African broadcast studios. Equipment suppliers in Shenzhen and Seoul now ship turnkey bonding systems to Lagos integrators, collapsing the skill barrier that previously confined high-resolution signage to imported finished goods. This automation is compressing lead times for custom-sized video walls from fourteen weeks to under six.
Kenya's Energy and Petroleum Regulatory Authority has tightened minimum efficacy standards for public lighting contracts, directing municipal procurement toward certified manufacturers with third-party test documentation. The industrial consequence is a two-tier supplier base: accredited vendors capture Nairobi and Mombasa tenders, while uncertified traders retreat to informal retail channels. Streetlight segments in East African capitals are responding by consolidating specification documents around EPRA-recognized test houses.
Hotel chains in Cape Town and Casablanca are unbundling display procurement from AV installation contracts, awarding screen supply to direct manufacturer relationships while outsourcing mounting and calibration to local integrators. This behavior change disrupts the traditional distributor-cum-installer model that dominated African hospitality fit-outs. The shift is most visible in Moroccan and South African luxury properties where brand-standard consistency overrides single-source convenience.
Africa LED and OLED Displays and Lighting Products Market Segmentation
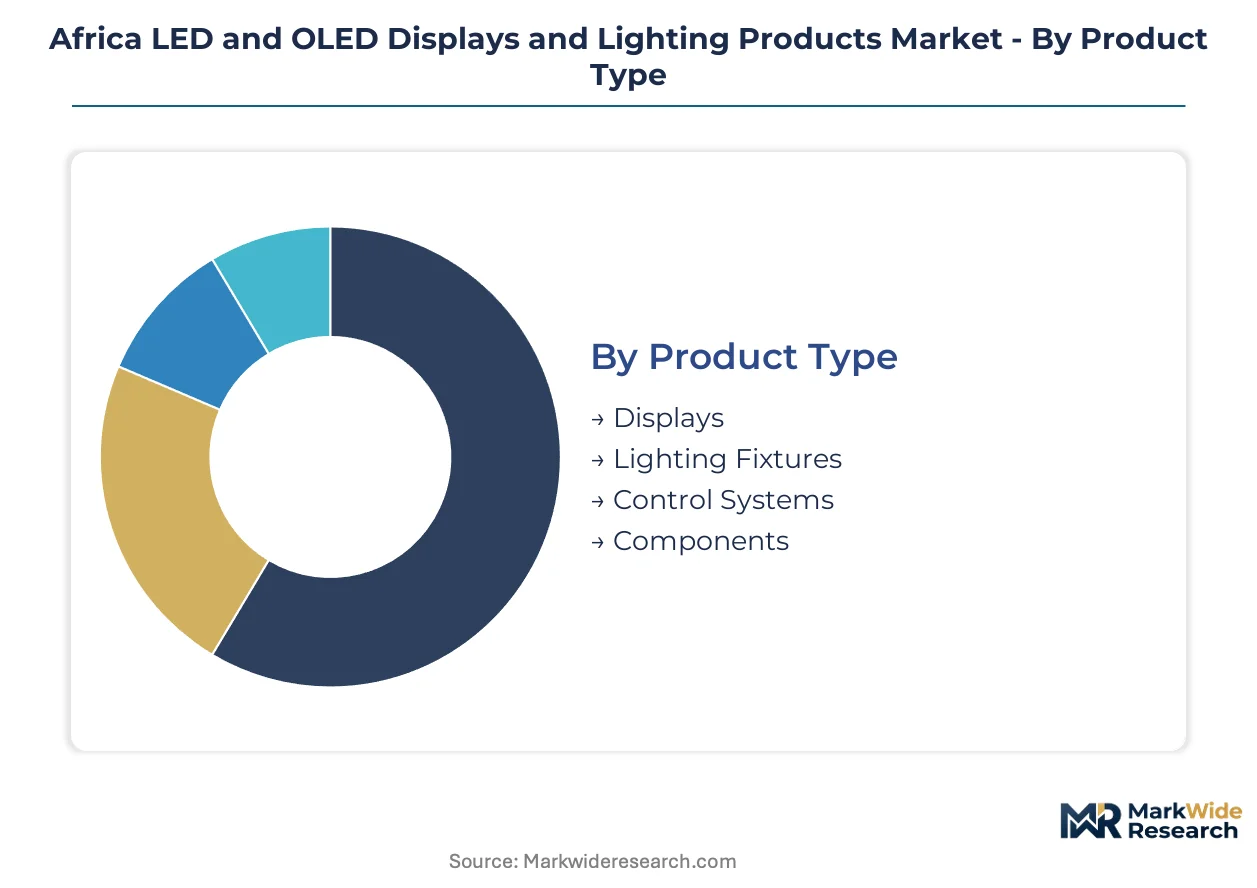
Segmentation in the Africa LED and OLED Displays and Lighting Products Market exposes how procurement patterns diverge across technology readiness, infrastructure maturity, and end-use sophistication. Each axis reveals distinct margin structures and certification burdens that reshape competitive positioning.
Product Type:
Technology specifications and integration depth define how each product category captures value across African commercial and infrastructure projects.
- Displays:Electroluminescent panels fabricated on glass or flexible polymer substrates, spanning LCD backlit modules to emissive OLED matrices. Lagos and Nairobi banking halls drive demand for fine-pitch LED video walls, while Moroccan luxury hotels specify premium OLED panels for lobby installations. Grid instability in Nigerian suburbs compresses warranty terms for outdoor display operators.
- Lighting Fixtures:Complete luminaire assemblies integrating LED modules, thermal management systems, and optical diffusers. South African government retrofit programs under SANS efficacy mandates accelerate volume procurement for Durban and Cape Town office parks, with pay-as-you-go solar-LED bundles penetrating rural Tanzania and Kenya.
- Control Systems:Networked dimming infrastructure and smart-city management platforms. Kigali's streetlight automation pilots create reference architectures for neighboring East African municipalities.
- Components:Discrete LED packages, driver integrated circuits, and substrate materials. Egyptian and Nigerian customs volatility on gallium nitride imports fragments distributor inventory positioning.
Lighting Fixtures leads on scale; Control Systems leads on momentum.
Technology:
Cost tier and performance differentiation separate adoption pathways across African consumer and commercial segments.
- LCD:Transmissive display technology relying on cold-cathode or LED backlighting through liquid crystal matrices. Entry-level television and monitor demand in Nigerian and Kenyan retail channels sustains volume, though margins compress against newer emissive alternatives.
- MicroLED:Chip-scale LED arrays with individual pixel control and superior luminance efficiency. South African broadcast studios and Nigerian corporate headquarters pilot fine-pitch tiles as Shenzhen equipment suppliers automate bonding processes, collapsing lead times from fourteen weeks to under six.
- Quantum Dot:Nanocrystal-enhanced backlighting delivering expanded color gamut without emissive panel costs. Mid-tier hospitality installations in Casablanca and Cape Town adopt quantum dot televisions as brand-standard compromises between LCD economy and OLED performance.
- OLED:Organic emissive layers enabling self-illuminated pixels with contrast ratios exceeding 1,000,000:1 and sub-millimeter form factors. Moroccan and Egyptian luxury hotel developments specify active-matrix panels for suite entertainment systems, anchoring the technology's premium value concentration.
LCD dominates installed base; OLED commands premium positioning.
End User:
Application maturity and procurement sophistication determine how each customer type sources display and lighting technology.
- Commercial:Retail chains, banking institutions, and corporate facilities requiring high-brightness signage and efficient ambient illumination. Lagos and Nairobi outdoor digital billboard clusters drive bulk LED module imports through fragmented procurement channels.
- Residential:Household consumers purchasing replacement lamps, decorative fixtures, and consumer electronics. Off-grid distributors in rural East Africa merge mobile payment platforms with solar-LED kits, opening non-grid addressable households.
- Industrial:Manufacturing facilities, warehouses, and logistics centers specifying high-bay and task lighting. South African industrial parks under ESKOM pricing pressure accelerate LED retrofit cycles to reduce operational expenditure.
- Hospitality:Hotels, restaurants, and entertainment venues prioritizing aesthetic differentiation and guest experience. Cape Town and Casablanca properties unbundle display procurement from AV installation contracts, awarding screen supply to direct manufacturer relationships.
Commercial leads on volume; Hospitality leads on specification intensity.
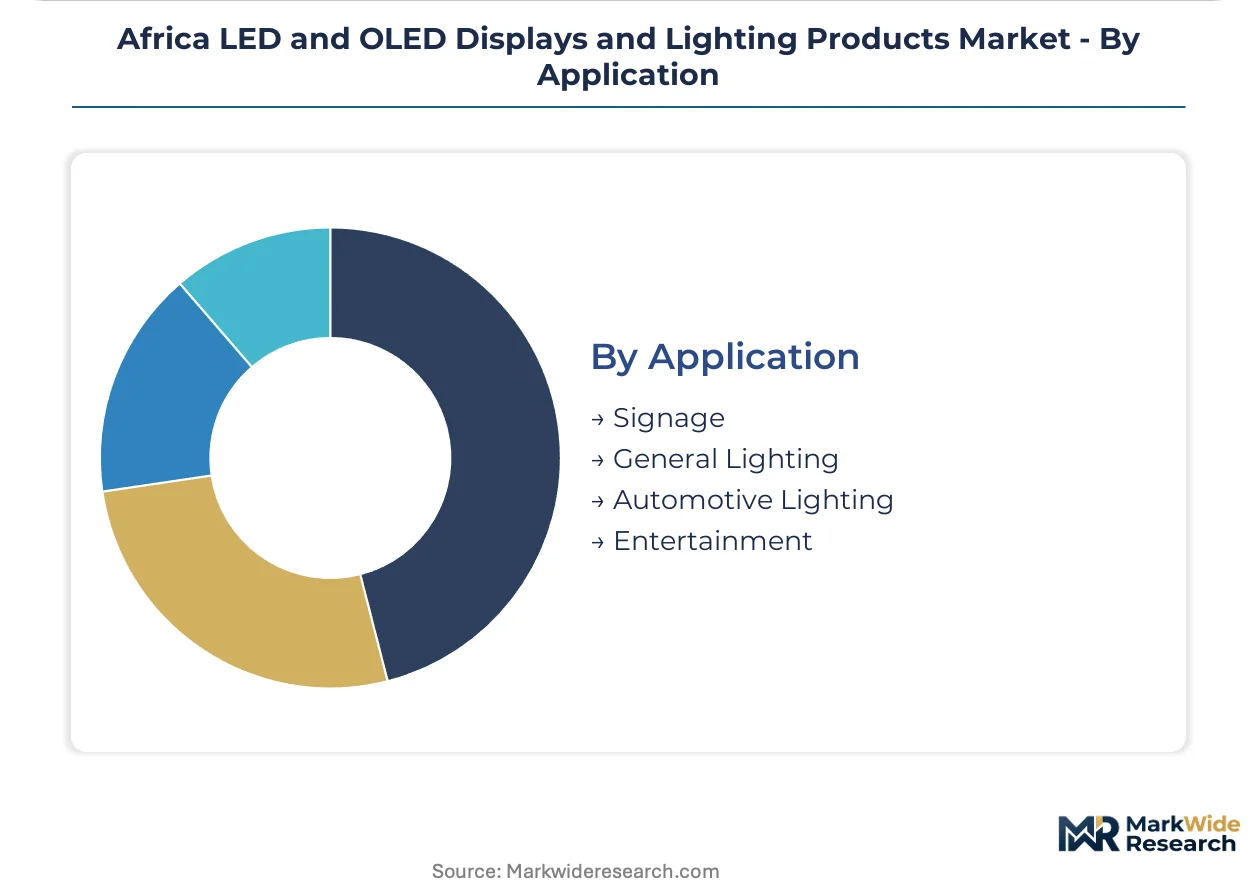
Application:
Geographic clustering and infrastructure investment patterns concentrate demand across distinct use cases.
- Signage:Outdoor and indoor digital display installations for advertising, wayfinding, and brand communication. Urban commercial corridors in Lagos, Abuja, and Nairobi pull imported high-brightness LED modules through independent integrator networks.
- General Lighting:Ambient and task illumination for built environments. South African SABS labeling rules and Kenya's EPRA efficacy mandates redirect procurement toward certified manufacturers, fragmenting uncertified traders into informal retail channels.
- Automotive Lighting:Headlamp, taillamp, and interior illumination systems for vehicle manufacturing and aftermarket. North African assembly plants serving European export markets adopt LED exterior lighting to meet EU regulatory requirements.
- Entertainment:Stage, studio, and immersive experience lighting requiring tunable spectra and dynamic control. South African broadcast facilities and Nigerian event production companies drive demand for professional-grade LED fixtures.
General Lighting anchors revenue scale; Signage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lagos and Nairobi commercial corridors anchor display module demand, while South African government retrofit programs concentrate lighting procurement in Durban and Cape Town office clusters.
South Africa
Durban and Cape Town office parks drive LED fixture volume under SABS energy-efficiency labeling mandates. The National Regulator for Compulsory Specifications enforces SANS performance thresholds that block non-compliant imports at major ports. ESKOM pricing pressure accelerates industrial park retrofit cycles to reduce operational expenditure.
Nigeria
Lagos and Abuja retail clusters pull high-brightness LED modules for outdoor digital billboards through fragmented procurement channels. Nigerian customs regimes impose unpredictable tariff swings on gallium nitride substrates, compressing landed margins for distributors. Grid instability in Lagos suburbs degrades LED driver lifespan, forcing warranty reserve inflation.
Kenya
Nairobi banking halls and Mombasa municipal tenders concentrate demand for certified lighting fixtures. The Energy and Petroleum Regulatory Authority mandates minimum efficacy standards for public lighting contracts, directing procurement toward manufacturers with third-party test documentation. Uncertified traders retreat to informal retail channels as EPRA-recognized test houses consolidate specification documents.
Egypt
Cairo municipal streetlight tenders and Casablanca-facing North African export channels anchor fixture demand. The Egyptian Organization for Standardization and Quality aligns with IEC 62717 for LED module safety, conditioning market access for European and Asian suppliers. Hotel developments in coastal zones specify premium display installations for luxury hospitality fit-outs.
Rwanda
Kigali smart-city pilots create reference installations for networked streetlight control systems across neighboring East African municipalities. Government-backed urban automation programs test integrated dimming infrastructure before regional scale-out. Technical workforce scarcity for commissioning networked systems delays project handovers despite hardware availability.
Africa LED and OLED Displays and Lighting Products Market Competitive Environment
Global majors compete with regional champions across municipal tender participation and distribution network depth. The supplier base organizes around three tiers: European-heritage lighting conglomerates with established African distribution, East Asian display panel fabricators serving premium hospitality direct, and emerging Chinese fixture exporters penetrating price-sensitive retail channels. Consolidation pressure concentrates around certification compliance capabilities and port-side inventory positioning.
Among European-heritage lighting specialists, Signify N.V. and ams OSRAM AG exemplify the certification-heavy municipal tier. Samsung Electronics Co., Ltd. anchors the display-direct segment. These three occupy positions that span the regulatory-compliance-to-premium-technology spectrum, with each archetype facing distinct margin pressures from divergent national certification timelines and import duty volatility.
| Leading Market Players |
|---|
| Signify N.V. |
| ams OSRAM AG |
| Acuity Brands Lighting Inc. |
| Cree Lighting |
| Opple Lighting Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| LG Display Co., Ltd. |
| Sharp Corporation |
| GE Lighting |
| Others |
Value Chain & Pricing Dynamics
Skilled bonding technicians concentrated in Shenzhen and Seoul compress assembly cost differentials, enabling three-tier pricing structure across premium, standard, and economy levels for display modules serving Lagos banking halls and Nairobi municipal tenders.
Pricing Analysis
Input-cost pass-through from gallium nitride substrate volatility and driver IC tariff swings compresses landed margins for Egyptian and Nigerian distributors, forcing cost absorption in economy-tier fixtures while premium OLED panels for Casablanca hotels maintain brand-premium insulation. Price differentiation hinges on SANS certification grade and after-sales warranty bundling. Pricing pressure stems from Asian supply concentration exposing integrators to currency mismatch risks. Municipal procurement officers in Kenya and South Africa show lowest price sensitivity due to efficacy mandate compliance requirements, while informal retail channels in Lagos suburbs compete on unit cost alone.
Supply Chain Analysis
Reverse-logistics flows for failed LED drivers in Kinshasa and Lagos suburbs remain underdeveloped, forcing premature landfill disposal rather than refurbishment recovery. Manufacturing concentration centers on China, South Korea, and Taiwan for OLED panel fabrication and LED chip production. Raw material dependencies include sapphire substrates, gallium nitride wafers, and rare-earth phosphors. Single-source vulnerability from East Asian fabrication exposure creates shipping delay risks for African integrators. Distribution runs through port-side bonded warehouses in Durban, Cairo, and Mombasa before fragmentation into independent integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as urbanization across African capitals sustains retrofit-driven replacement cycles in government buildings and commercial signage infrastructure.
For Market Incumbents: Lock in certification compliance capabilities ahead of divergent national timelines—Egypt's EOS alignment with IEC 62717, Kenya's EPRA efficacy mandates, and South Africa's SANS labeling create testing burdens that smaller traders cannot shoulder. Deepen port-side inventory positioning in Durban and Mombasa to hedge customs volatility on gallium nitride imports. For New Entrants and Emerging Players: Independent integrators in Lagos and Nairobi represent the most accessible channel partners for breaking into commercial signage without established municipal tender relationships. Target pay-as-you-go solar-LED bundles in rural Tanzania and Kenya where mobile payment platforms reduce credit risk. Pursue white-label fixture supply to East African greenhouse operators seeking tunable horticultural spectra. For Investors and Strategic Acquirers: European lighting conglomerates are the most active acquirer in this space, consolidating distribution networks to defend municipal tender participation against Chinese fixture exporters. The 5-10 year viability window favors targets with SANS or EPRA pre-certification and existing relationships with Cairo or Johannesburg procurement offices. Monitor Kigali smart-city pilot scale-out as inflection indicator for regional control-system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early alignment with SANS, EPRA, and EOS standards secures port access before competitors complete testing cycles. |
| Port-Side Inventory Positioning | Bonded warehousing in Durban and Mombasa reduces landed cost exposure to Nigerian and Egyptian customs volatility. |
| Horticultural Spectra R&D Partnership | Collaboration with East African greenhouse operators opens fixture demand beyond general illumination into crop-specific lighting. |
| Direct-to-Hospitality Contracting | Bypassing traditional AV installers captures premium display value in Casablanca and Cape Town hotel developments. |
| Mobile Payment Platform Integration | Embedding pay-as-you-go functionality reaches off-grid rural households in Tanzania and Kenya without traditional credit infrastructure. |
Study Parameters
Multiple input streams—structured interviews with municipal procurement officers, technical discussions with greenhouse operators and hotel AV managers, and trade data analysis—were reconciled to construct segment-level demand estimates. Primary fieldwork engaged lighting fixture distributors, port customs brokers, and smart-city project engineers across Lagos, Nairobi, Cairo, and Kigali. Secondary validation drew from SABS regulatory filings, EPRA tender documentation, Egyptian customs records, and UN Comtrade import statistics. Bottom-up channel checks and top-down macroeconomic triangulation anchored volume projections.
Data-stream reconciliation applied across the analysis window modeled product type, technology tier, end-user sophistication, and application intensity as core segmentation dimensions. CAGRs were derived from fitted growth curves against urbanization rates and retrofit policy implementation schedules. Industry-specific forecast inputs included ESKOM pricing trajectories for South African industrial demand and mobile payment penetration rates for East African off-grid lighting adoption.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to harmonization of national certification timelines and resolution of gallium nitride import tariff disputes. Practitioners should monitor Kigali smart-city control-system deployment velocity and Cairo municipal tender award patterns for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Asia Pacific Outdoor LED Lighting Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Superluminescent Diodes Market
LED
Europe Outdoor LED Lighting Market
LED
LED Mask Market
LED
Bi-Color LED Ring Light Market
LED
Indonesia LED Market
LED
LED Flip Chip Market
LED
Germany LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Dual-Digit 7 Segment LED Displays Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Europe Indoor LED Lighting Market
LED
LED Panel Market
LED
LED Modules and Light Engines Market
LED
Europe LED Packaging Market