
 Japan LED Market | 2026-2036
Japan LED Market Size, Share, and Industry Trends Forecast 2026-2036
Japan LED Market Intelligence
Chip-scale packaging and miniaturized flip-chip architectures is rewriting the cost-performance equation for high-lumen density applications. Nichia Corporation leverages its phosphor-converted blue LED platform to sustain dominance in general illumination. Toshiba Lighting and Technology Corporation anchors its position through captive control over epitaxial wafer supply chains. Sharp Corporation competes aggressively in smart LED modules with integrated sensor arrays for commercial building automation.
Light-emitting diodes are semiconductor p-n junction devices that emit incoherent narrow-spectrum light when forward-biased, with gallium nitride-based blue emitters serving as the foundational platform for white-light conversion via cerium-doped yttrium aluminum garnet phosphors or quantum dot down-converters. Their primary purpose spans energy-efficient illumination, optical signaling, and backlighting for liquid crystal displays across residential, commercial, and transportation infrastructure. LED panels command the highest value density in commercial retrofit projects due to thin-form integration and dimming compatibility. Smart LED technology is expanding fastest as building management systems demand networked luminaires with occupancy sensing and daylight harvesting protocols. Automotive lighting maintains premium margin pools through stringent reliability certifications and thermal management requirements.
METI enforces the Energy Conservation Act and Top Runner standards that mandate minimum luminous efficacy thresholds for domestically sold luminaires, directly shaping product development roadmaps and factory retooling schedules. JIS standards for LED module interchangeability and electromagnetic compatibility create technical barriers that filter non-compliant imports from regional competitors. PMDA oversight applies to medical-grade phototherapy devices using LED sources, adding a secondary regulatory layer for specialized applications. Stakeholders must monitor how METI's evolving carbon neutrality roadmaps will tighten embodied energy requirements across the full LED manufacturing value chain.
Market Dynamics
METI's Top Runner Program is compressing product lifecycles as domestic manufacturers race to meet tightening luminous efficacy thresholds before mandatory compliance deadlines. This regulatory pressure cascades through factory retooling schedules and R&D prioritization across the Kanto industrial corridor.
Growth Catalysts
- Adaptive driving beam mandates:Japanese OEMs are converting headlamp assemblies to LED-based ADB platforms, creating sustained demand for high-reliability automotive emitters with precision thermal management.
- Building automation convergence:Commercial real estate operators in Tokyo and Osaka are specifying smart LED modules with integrated occupancy sensing and daylight harvesting protocols.
- Carbon neutrality roadmaps:METI's embodied energy requirements are accelerating factory upgrades and material sourcing reforms across the domestic manufacturing value chain.
Market Restraints
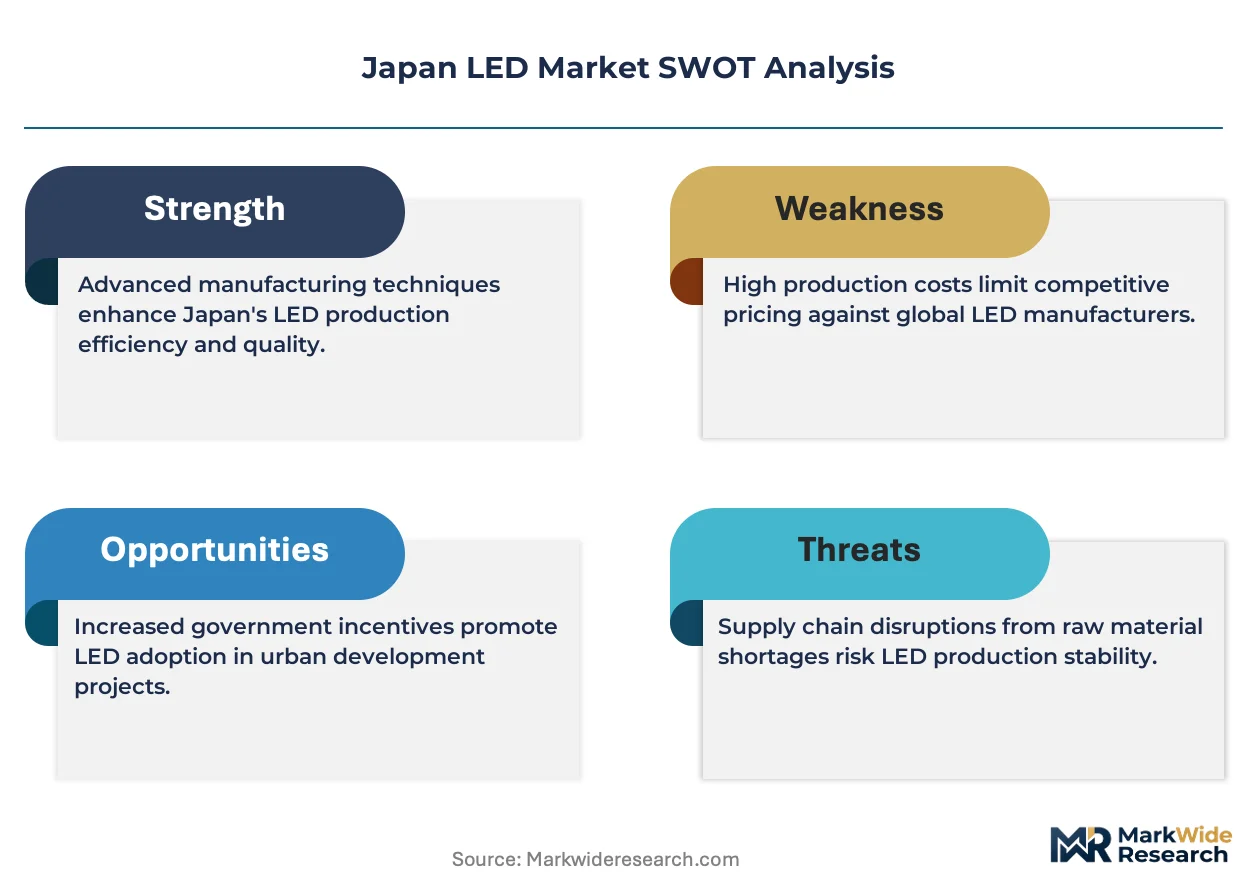
- Epitaxial wafer supply concentration:Captive control over gallium nitride substrate production by integrated conglomerates limits independent module manufacturers' input flexibility.
- Phosphor material cost volatility:Cerium-doped yttrium aluminum garnet supply faces pricing pressure from rare earth processing bottlenecks.
- JIS interchangeability standards:Technical barriers for electromagnetic compatibility and module specifications filter non-compliant imports from regional competitors.
Strategic Opportunities
- Medical phototherapy expansion:PMDA oversight of LED-based therapeutic devices creates a specialized high-margin segment with distinct certification pathways.
- Quantum dot down-conversion:Convergence of semiconductor nanocrystal technology with solid-state lighting architectures enables superior color rendering indices for premium residential applications.
- Flip-chip architecture adoption:Miniaturized packaging formats are penetrating high-lumen density retrofit projects in Saitama prefecture's industrial zones.
Industry Challenges
- Phosphor-conversion IP complexity:Patent thickets around blue-pump white LED architectures constrain design freedom for second-tier module assemblers.
- Legacy halogen replacement cycles:Extended fixture lifespans in commercial buildings compress near-term retrofit revenue windows.
- Thermal management certification timelines:Stringent automotive reliability testing protocols extend product qualification periods for headlamp suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan LED Market |
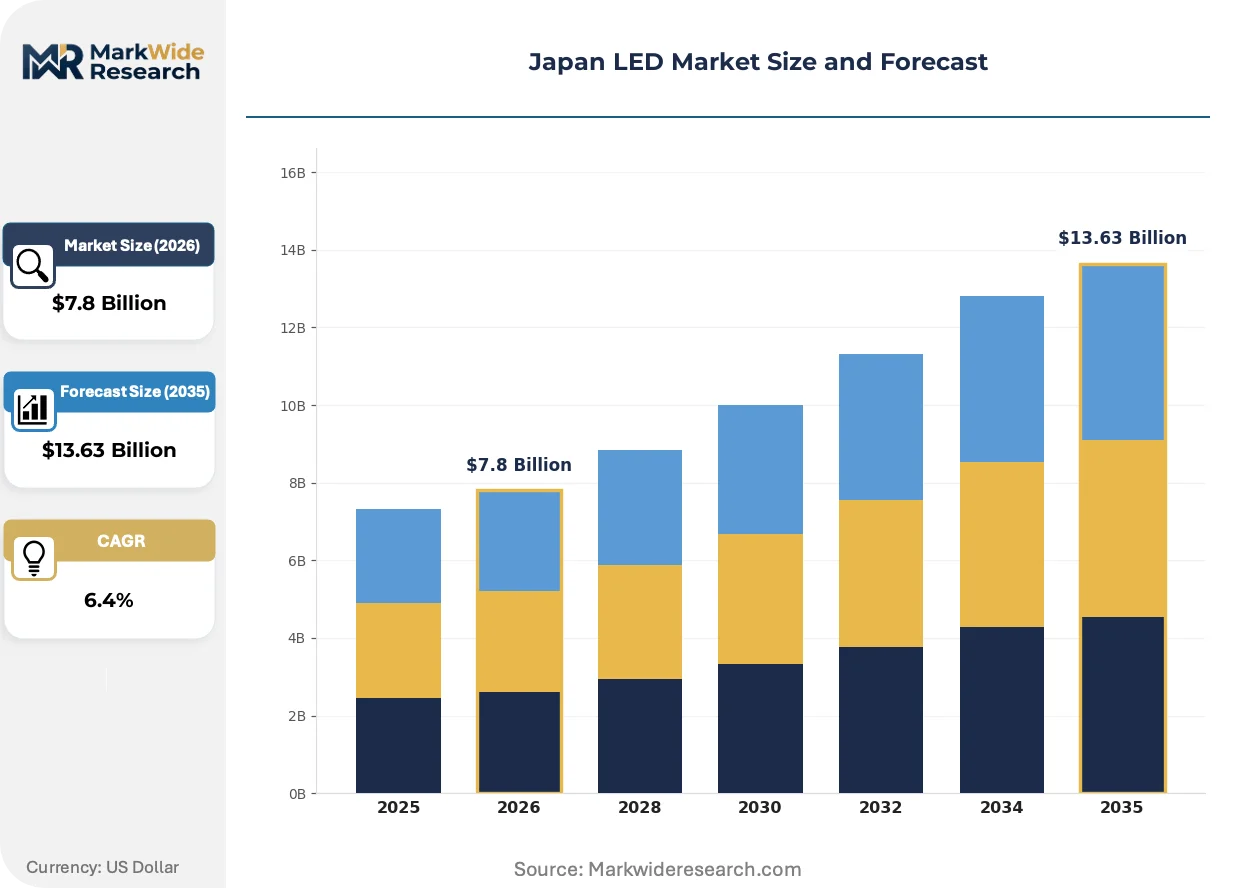
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Bulbs, LED Tubes, LED Strips, LED Panels Application: Indoor Lighting, Outdoor Lighting, Automotive Lighting, Display Lighting End User: Residential, Commercial, Industrial, Government Technology: Organic LED, Quantum Dot LED, Standard LED, Smart LED |
| Companies Covered | ENDO Lighting Corporation, Toshiba Lighting and Technology Corporation, Nichia Corporation, Toyoda Gosei Co., Ltd., Sharp Corporation, Panasonic Holdings Corporation, Koito Manufacturing Co., Ltd., Mitsubishi Electric Corporation, Stanley Electric Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan LED Market Strategic Shifts & Innovations
Chip-scale packaging architectures are compressing form factors while expanding application boundaries across transportation and built environments. Three convergent developments are restructuring competitive positioning.
Miniaturized flip-chip LED architectures are digitizing luminaire design by embedding driver electronics directly within emitter substrates. Automotive tier-1 suppliers in Kanagawa prefecture are adopting these formats for headlamp assemblies with space-constrained thermal envelopes. The technology is digitizing traditional discrete-component supply chains into integrated semiconductor fabrication models.
METI's Energy Conservation Act amendments are tightening minimum efficacy thresholds for domestically sold luminaires on accelerated schedules. Domestic manufacturers are reconfiguring product roadmaps to preempt compliance cliffs. General illumination segments face the steepest retooling requirements as legacy phosphor-converted platforms approach their theoretical efficiency limits.
Building management system integration is restructuring procurement patterns for commercial lighting. Facility managers in Tokyo's central business district are specifying networked luminaires with embedded sensor arrays as standard rather than upgrade options. This specification shift is most visible in Class-A office retrofits where LEED-equivalent certifications drive technology selection.
Japan LED Market Segmentation
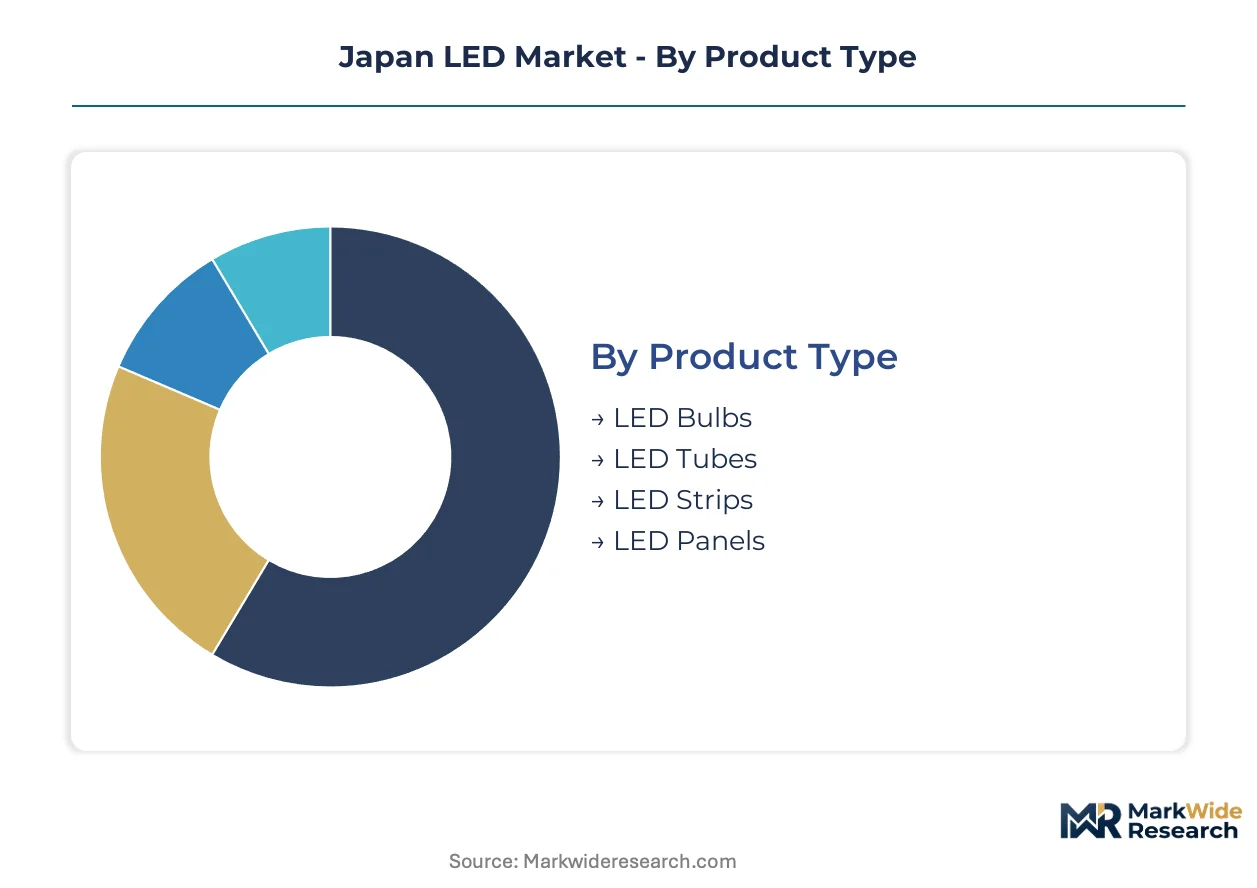
Segmentation reveals how procurement patterns diverge across technical specifications and use environments in Japan. Service intensity varies sharply between retrofit-ready residential products and integrated commercial systems requiring ongoing calibration support.
Product Type:
After-sales service intensity escalates from simple bulb replacement through panel-integrated driver diagnostics, with warranty complexity tracking form factor sophistication.
- LED Panels:Thin-form surface-mount luminaires with integrated heat sinks and driver electronics command premium retrofit budgets in Tokyo commercial real estate. Facility managers in Chiyoda and Minato wards specify these for Class-A office certifications requiring dimming compatibility and networked control integration.
- LED Bulbs:Standard A19 and E26 base replacements for legacy incandescent sockets dominate residential channel volume through home centers and e-commerce platforms. METI Top Runner efficacy mandates are compressing SKU variety as manufacturers consolidate around high-efficacy platforms.
- LED Tubes:Linear T8 and T5 retrofits for fluorescent fixture replacement concentrate in Saitama prefecture industrial facilities.
- LED Strips:Flexible tape configurations with adhesive backing serve architectural accent and cove lighting applications.
By volume, LED Bulbs leads. By growth pace, LED Panels is ahead.
Application:
Cost tier stratification separates commodity indoor retrofits from thermally engineered automotive assemblies requiring reliability certification.
- Automotive Lighting:Adaptive driving beam headlamp modules with precision thermal management and vibration resistance command premium margin pools through JASO and OEM qualification protocols. Tier-1 suppliers in Kanagawa prefecture are converting production lines to LED-based platforms as Japanese OEMs phase out halogen architectures.
- Indoor Lighting:General illumination spanning residential ambient, commercial task, and industrial high-bay configurations represents the largest addressable base. Building automation convergence in Osaka's central business district is accelerating specification of sensor-integrated luminaires.
- Outdoor Lighting:Street and area lighting with IP65+ ingress protection faces municipal procurement cycles.
- Display Lighting:Backlighting and edge-lit configurations for commercial signage and retail fixtures.
By revenue concentration, Automotive Lighting leads. By specification velocity, Indoor Lighting is expanding most quickly.
End User:
Customer type determines procurement channel structure, with direct specification authority varying from distributed residential choice through centralized government tender processes.
- Commercial:Office, retail, and hospitality operators in Tokyo and Osaka metropolitan areas drive smart LED module adoption through building management system integration. Lease structure incentives align landlord and tenant interests around energy efficiency upgrades.
- Residential:Individual households purchasing through retail and online channels respond to METI energy labeling and subsidy programs for high-efficacy replacements.
- Industrial:Manufacturing facilities in the Kanto corridor prioritize high-bay efficacy and maintenance interval reduction.
- Government:Municipal and national procurement for public buildings and infrastructure operates through competitive bidding with domestic preference provisions.
By project scale, Government leads. By specification autonomy, Commercial is climbing the fastest.
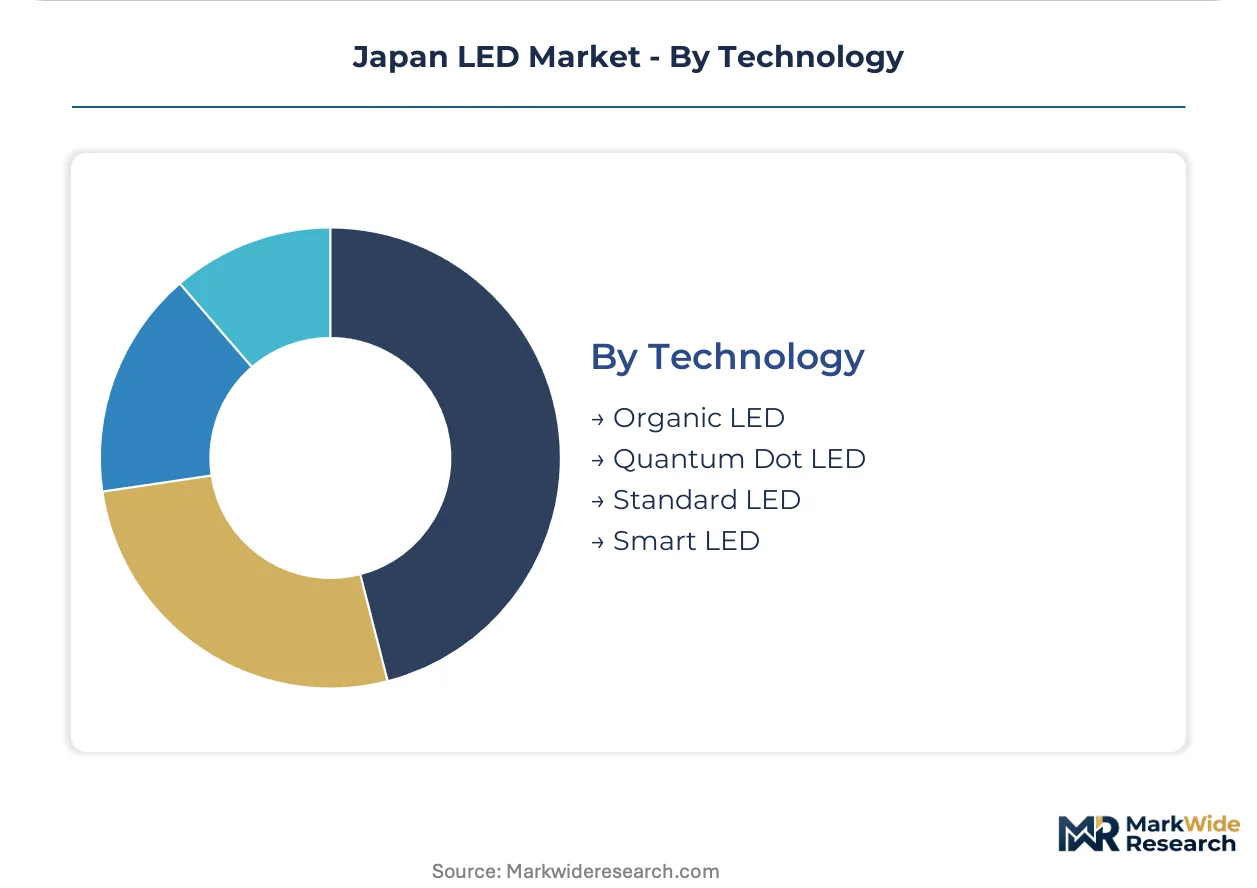
Technology:
Margin structure diverges between mature phosphor-converted platforms and emerging architectures requiring specialized manufacturing equipment.
- Smart LED:Networked luminaires with embedded occupancy sensors, daylight harvesting protocols, and wireless connectivity interfaces are penetrating Class-A commercial retrofits. Sharp Corporation and domestic competitors are integrating sensor arrays directly into module substrates to capture building automation procurement.
- Quantum Dot LED:Semiconductor nanocrystal down-conversion enables superior color rendering indices for premium residential and gallery applications. Manufacturing scale constraints limit current penetration to high-end segments.
- Standard LED:Phosphor-converted blue pump architectures dominate general illumination volume.
- Organic LED:Thin-film electroluminescent panels for specialized display and decorative lighting applications.
By installed base, Standard LED leads. By roadmap priority, Smart LED is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facility managers and commercial real estate operators concentrate procurement authority across Japan's major metropolitan manufacturing belts. Kanto corridor buyers drive premium specifications for smart building integration. Automotive tier-1 suppliers in central Japan anchor high-reliability emitter demand.
Kanto/Tokyo
Class-A office retrofits in Chiyoda and Minato wards specify networked LED panels with daylight harvesting protocols. METI's Top Runner Program mandates minimum efficacy thresholds for luminaires sold through Tokyo distribution channels. Manufacturing facilities in Saitama prefecture adopt miniaturized flip-chip architectures for high-bay industrial lighting.
Kansai/Osaka
Commercial building automation convergence accelerates smart LED module procurement across Osaka's central business district. JIS interchangeability standards for electromagnetic compatibility filter non-compliant imports from regional competitors. Facility managers in Kyoto and Kobe prioritize sensor-integrated luminaires for LEED-equivalent certifications.
Chubu/Nagoya
Automotive tier-1 suppliers concentrate adaptive driving beam headlamp assembly production in Toyota City and surrounding Aichi prefecture industrial zones. OEM qualification protocols under JASO standards extend product certification timelines for LED emitters. Thermal management requirements for precision headlamp modules command premium margin pools.
Kyushu
Semiconductor fabrication clusters in Fukuoka prefecture support epitaxial wafer supply chain nodes for domestic LED manufacturers. Regional industrial parks attract backend packaging operations seeking proximity to gallium nitride substrate processing. Municipal street lighting procurement cycles operate through competitive bidding with domestic preference provisions.
Hokkaido
Cold-climate lighting specifications drive demand for high-efficacy outdoor luminaires with extended operating temperature ranges. Regional infrastructure projects prioritize IP65+ ingress protection for harsh winter conditions. Sapporo municipal procurement channels favor established domestic suppliers with proven reliability records.
Japan LED Market Key Industry Players
Channel-controlling players compete with product-specialist players across distinct procurement pathways in the Japan LED market. Integrated conglomerates with captive epitaxial wafer supply chains dominate high-volume general illumination through direct specification relationships with facility managers. Specialist module assemblers carve position in architectural accent and medical phototherapy niches requiring customized optical engineering. Competitive moves center on backward integration into phosphor material sourcing and strategic partnerships for quantum dot down-conversion technology licensing.
Among integrated lighting conglomerates, Nichia Corporation and Toshiba Lighting and Technology Corporation exemplify divergent strategic positioning. Nichia occupies a position representing phosphor-converted blue LED platform dominance in general illumination volume. Toshiba Lighting anchors a tier characterized by captive control over epitaxial wafer supply chains. Sharp Corporation sits within the smart module specialist archetype, competing through integrated sensor arrays for building automation procurement. Panasonic Holdings Corporation represents the diversified electronics conglomerate model with cross-divisional technology leverage.
| Leading Market Players |
|---|
| ENDO Lighting Corporation |
| Toshiba Lighting and Technology Corporation |
| Nichia Corporation |
| Toyoda Gosei Co., Ltd. |
| Sharp Corporation |
| Panasonic Holdings Corporation |
| Koito Manufacturing Co., Ltd. |
| Mitsubishi Electric Corporation |
| Stanley Electric Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Kanto industrial corridor capacity dynamics determine downstream pricing power for Japanese LED manufacturers. Gallium nitride epitaxial wafer throughput constraints at captive fabs in Saitama and Tokyo prefectures create supply inelasticity that supports premium pricing for high-efficacy emitters. METI Top Runner compliance deadlines compress product lifecycles and accelerate factory retooling, shifting cost structures toward R&D amortization rather than unit production scale.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate phosphor-converted LED procurement. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified automotive emitters from commercial retrofit modules and residential bulb replacements. Cost compression in standard-grade general illumination intensifies because Chinese module assemblers compete on volume scale. Municipal procurement offices exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize reliability certification over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with captive fabs at Nichia, Toshiba Lighting, and Sharp rather than third-party EMS providers. Japan, Taiwan, and South Korea anchor gallium nitride substrate and epitaxial wafer supply. Cerium-doped yttrium aluminum garnet phosphors and quantum dot nanocrystals constitute critical material dependencies. Single-source vulnerability concentrates in rare earth processing nodes for phosphor precursors. Distribution runs through direct specification relationships with facility managers and automotive OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's LED market represents early-cycle expansion as adaptive driving beam mandates penetrate the remaining halogen-equipped vehicle fleet. Building automation convergence in Tokyo and Osaka commercial real estate creates sustained specification pull for sensor-integrated luminaires.
For Market Incumbents: Build regulatory compliance moats by preempting METI efficacy threshold escalations through phosphor-conversion R&D. Capture backward integration into cerium supply through offtake agreements with rare earth processors. Expand flip-chip packaging capacity in Saitama prefecture to defend against emerging Chinese miniaturization specialists. For New Entrants and Emerging Players: Kyushu semiconductor fabrication clusters offer underpenetrated backend packaging opportunities for quantum dot down-conversion specialists. Target medical phototherapy device OEMs in Osaka with PMDA-prevalidated LED modules as the most penetrable segment. Pursue licensing partnerships with Nichia or Toyoda Gosei for phosphor-conversion IP rather than independent patent development. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart LED module providers with building management system integration contracts. Five-to-ten year viability favors specialists with captive epitaxial capacity and JIS certification infrastructure. Monitor METI carbon neutrality roadmap announcements for embodied energy requirement inflections that would trigger factory upgrade capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Material Backward Integration | Secures cerium supply chains against rare earth processing bottlenecks and price volatility. |
| Flip-Chip Architecture Scale-Up | Captures high-lumen density retrofit demand in Saitama prefecture industrial zones. |
| Smart Module Platform Integration | Aligns with Tokyo Class-A office building automation procurement specifications. |
| Quantum Dot Down-Conversion Licensing | Enables premium residential color rendering without infringing phosphor-conversion patent thickets. |
| Automotive ADB Thermal Management Certification | Qualifies suppliers for Japanese OEM headlamp assembly conversion programs under JASO standards. |
Research Approach
A spread of perspectives from LED module design engineers, commercial facility managers, automotive tier-1 procurement leads, and METI regulatory officials converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through JIS standard documentation, METI Energy Conservation Act amendments, and customs trade records for gallium nitride substrate imports. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology architecture. CAGRs derived from fitted growth curves incorporating METI compliance deadline impacts and automotive platform conversion schedules. Industry-specific inputs encompassed epitaxial wafer capacity utilization rates and phosphor material spot pricing indices.
Practitioners should monitor rare earth export quota announcements and METI carbon neutrality roadmap revisions for early signals of supply cost or compliance threshold shifts. Cross-checking against IEA energy efficiency technology deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
China LED Market
LED
China Indoor LED Lighting Market
LED
Global Waterproof LED Module Market
LED
LED Display Control Card Market
LED
Middle East LED Lights Market
LED
Smart LED Indoor Signage Market
LED
Japan LED Lighting Market
LED
Indonesia LED Market
LED
North America Commercial LED Lighting Market
LED
Gan Substrate Market
LED
Asia Pacific LED Lighting Market
LED
LED Driver Market
LED
India Indoor LED Lighting Market
LED
Global Outdoor LED Lighting Market
LED
Global Industrial and Commercial LED Lighting Market
LED
LED Power Supplies Market