
 India LED Lighting Market | 2026-2036
India LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
India LED Lighting Market Outlook
Market Context
The India LED Lighting Market is repositioning around a widening gap between premium smart-enabled systems and mass-market commodity bulbs. Wipro Lighting leverages its institutional channel strength to dominate commercial office retrofits, while Havells India Ltd sustains manufacturing scale across both tier-one cities and secondary towns through captive distribution. Syska LED Lights Pvt Ltd competes aggressively on price in the residential replacement cycle, occupying the volume-driven end of the spectrum.
Technical Definition and Segment Structure
India LED lighting encompasses solid-state luminaires using semiconductor diodes with typical efficacy ratings exceeding 100 lumens per watt, designed to replace incandescent and fluorescent sources across residential, commercial, and infrastructure applications. Bulbs and tubes retain the largest volume share as legacy replacement demand persists, while smart lighting and solar LED segments command expanding margin pools through integration with building automation and off-grid rural electrification programs. The outdoor end-user category anchors government-driven procurement through municipal street-lighting tenders, whereas commercial buyers increasingly specify fixture-integrated controls for energy-code compliance.
Regulatory Framework and Outlook
BIS mandates compulsory registration for LED products under the Compulsory Registration Scheme, while the Bureau of Energy Efficiency enforces star-labeling thresholds that disqualify low-efficacy imports from SAMR-regulated supply chains. CEA technical standards for grid-connected solar LED systems further segment product qualification requirements across urban and rural deployment contexts. Stakeholders must monitor state-level tender design evolution, as procurement authorities in Maharashtra and Gujarat shift toward performance-contracting models that privilege vendors with demonstrated maintenance networks.
Market Dynamics
Municipal smart-city procurement is compressing replacement cycles and forcing vendors to absorb lifetime maintenance risk, while BIS certification mandates raise fixed costs for new entrants.
Growth Catalysts
- Street-lighting tenders:Maharashtra, Gujarat, and Tamil Nadu municipalities are bundling LED retrofits with 10-year maintenance contracts, locking in multi-year revenue streams for qualified vendors.
- BIS Compulsory Registration Scheme:Quality thresholds now exclude substandard imports, creating protected domestic volume for certified manufacturers.
- Solar LED convergence:CEA technical standards for off-grid rural electrification are opening parallel product lines that bypass urban grid dependency.
Market Restraints
- Driver IC supply concentration:Taiwan and China-based semiconductor foundries control critical LED driver components, exposing assemblers to input volatility.
- Aluminum heat-sink cost structure:Raw material price swings directly compress fixture margins, particularly in mass-market bulb segments where differentiation is minimal.
- Fluorescent residual stock:Institutional buyers in cost-constrained sectors continue specifying T5/T8 tubes for large-scale retrofits, delaying full LED conversion.
Strategic Opportunities
- Rural Bihar and Uttar Pradesh electrification:Saubhagya scheme saturation creates replacement demand as initial subsidized bulbs reach end-of-life.
- Human-centric lighting:Circadian-tunable systems are penetrating premium commercial office fit-outs in Bengaluru and Hyderabad IT corridors.
- Performance contracting:Energy Service Company (ESCO) models allow vendors to capture savings-share revenue rather than upfront hardware margins.
Industry Challenges
- Optical design talent scarcity:Thermal management and light-distribution engineering skills concentrate in legacy lighting firms, constraining new entrant product development.
- Multi-standard compliance burden:Concurrent BIS, BEE star-label, and state tender specifications force redundant testing cycles that extend time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India LED Lighting Market |
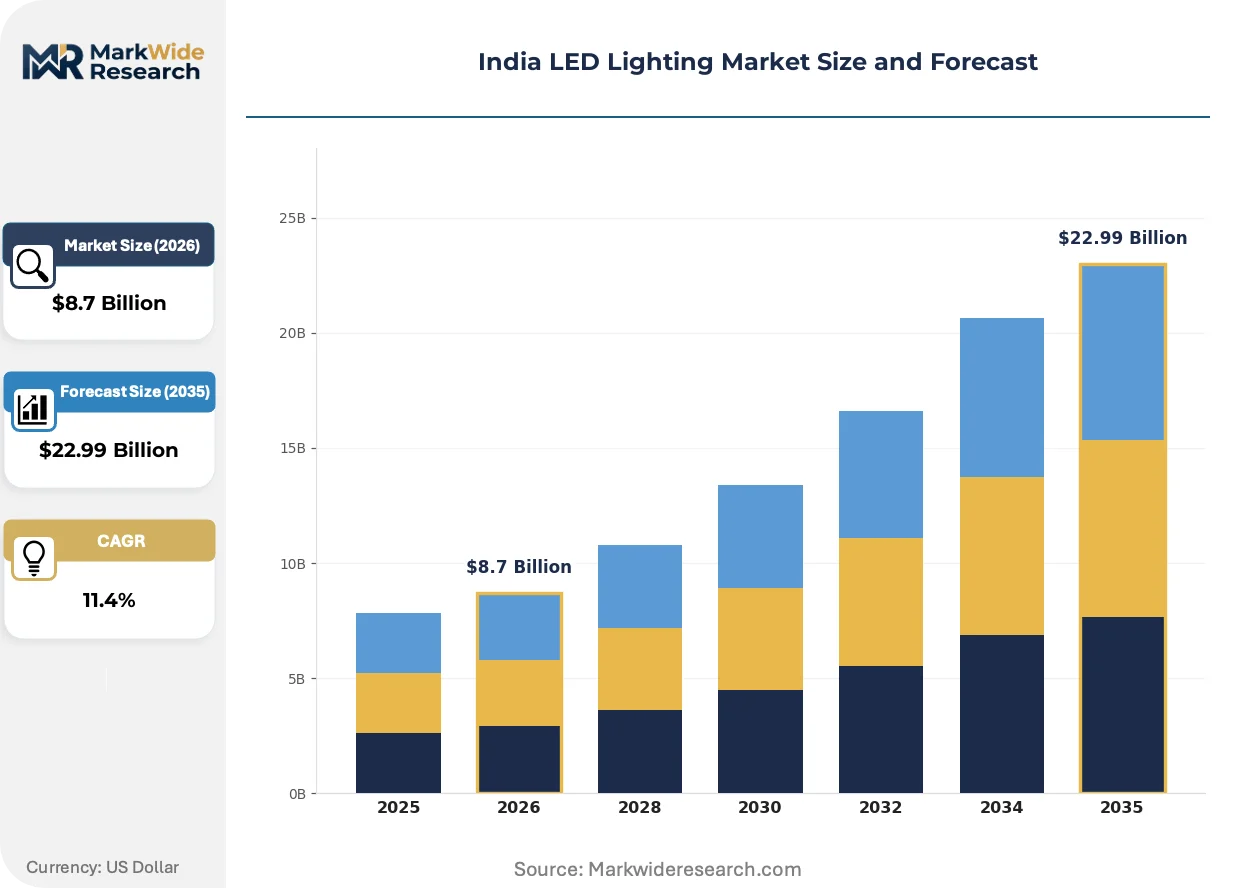
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Panels, Tubes Technology: Smart Lighting, Solar LED, OLED, Hybrid End User: Residential, Commercial, Industrial, Outdoor Distribution Channel: Online Retail, Direct Sales, Wholesalers, Others |
| Companies Covered | Wipro Lighting, Crompton Greaves Consumer Electricals Ltd, Philips Electronics India Ltd, Polycab India, Osram India Pvt Ltd, Havells India Ltd, Syska LED Lights Pvt Ltd, Surya Roshni Ltd, Bajaj Electricals Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India LED Lighting Market Strategic Shifts
Connected lighting architectures and policy-mandated efficiency floors are separating vendors into maintenance-network operators versus commodity assemblers.
Li-Fi visible light communication is rewriting connectivity assumptions for data-sensitive environments. Defense installations and financial trading floors in Mumbai and Delhi are piloting secure, interference-free networks embedded in existing luminaires. This convergence of illumination and data transmission is compressing the addressable market for separate Wi-Fi infrastructure in high-security zones.
Bureau of Energy Efficiency's revised star-labeling thresholds are disqualifying efficacy tiers that dominated the market three years ago. Manufacturers must now redesign optics and driver electronics to maintain retail shelf access. The commercial segment bears the steepest redesign burden, as office retrofit specifications increasingly mandate five-star ratings for code compliance.
Direct factory-to-municipality tendering is disintermediating traditional electrical wholesale channels for large infrastructure projects. State nodal agencies in Gujarat and Tamil Nadu now specify vendor-managed inventory and localized spare-part depots as mandatory bid criteria. This channel compression privileges manufacturers with captive logistics networks over import-dependent traders.
India LED Lighting Market Segmentation
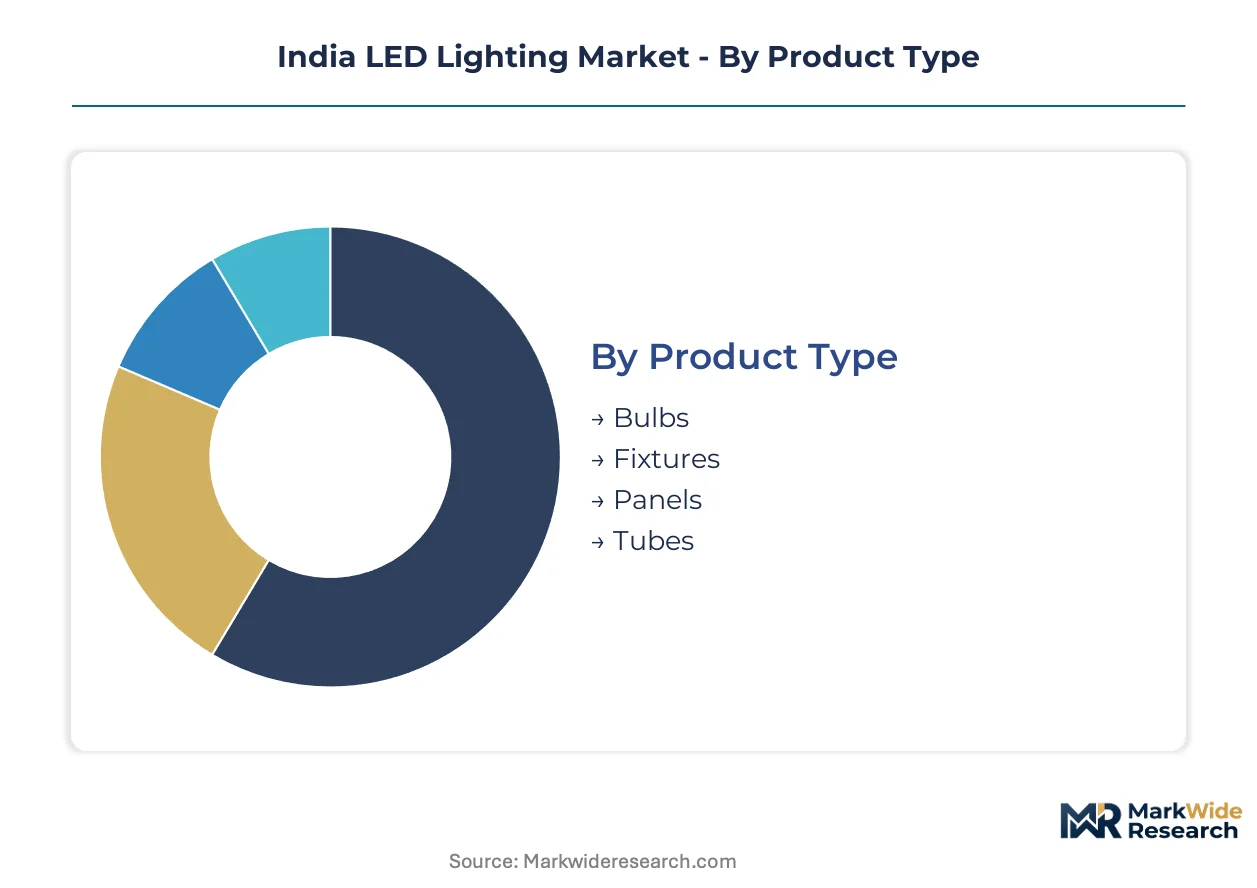
Segmentation in the India LED lighting market reveals divergent margin architectures across product maturity curves. Procurement concentration in municipal infrastructure and residential replacement cycles creates distinct competitive arenas with varying certification burdens and channel requirements.
Product Type:
Volume-weighted procurement favors standardized form factors, while premium fixtures capture margin through BEE star-label differentiation and architectural specification.
- Bulbs:Standard A19 and E27 base configurations dominate residential replacement cycles under UJALA scheme saturation. Demand concentrates in Uttar Pradesh and Bihar as Saubhagya-connected households enter replacement phases. BIS certification costs compress assembler margins below 15% in this commoditized tier.
- Fixtures:Downlights, spotlights, and architectural housings integrate thermal management and optical design for commercial retrofits. Maharashtra and Gujarat office developments specify five-star BEE ratings as mandatory, locking out uncertified competitors. Procurement runs through ESCO performance contracts that shift revenue toward maintenance streams.
- Panels:Edge-lit and back-lit flat panels serve false-ceiling installations in IT corridors and healthcare facilities. Bengaluru and Hyderabad account for disproportionate specification volume.
- Tubes:T8 retrofit tubes and integrated batten fixtures compete against residual fluorescent stock in cost-constrained institutional sectors. Tamil Nadu educational infrastructure tenders specify tubes over panels for budget compliance.
Mature deployment sits with bulbs. Newer deployment is concentrated in fixtures.
Technology:
Connectivity premiums separate vendors with firmware capabilities from pure hardware assemblers, while solar integration opens rural markets beyond grid dependency.
- Smart Lighting:Zigbee and Bluetooth mesh-enabled systems with tunable white and occupancy sensing command 40-60% price premiums over conventional equivalents. Commercial office fit-outs in Mumbai and Delhi NCR specify fixture-integrated controls for energy-code compliance. BEE's revised star-label thresholds now credit connected load management as an efficacy multiplier.
- Solar LED:DC-native luminaires with integrated photovoltaic panels and lithium-ion storage serve off-grid rural electrification under CEA technical standards. Bihar and Rajasthan villages with unreliable grid access represent the primary addressable base. MNRE subsidies compress end-user pricing but extend payment tenors for vendors.
- OLED:Organic electroluminescent panels with surface-area emission characteristics penetrate premium architectural accent applications. Mumbai luxury retail and hospitality projects specify OLED for uniform glare-free illumination.
- Hybrid:Grid-tied systems with battery backup bridge reliability gaps in tier-two commercial centers. Gujarat industrial estates specify hybrid emergency lighting for continuous process protection.
Established volume flows through conventional LED. Connected and solar-integrated systems are expanding most quickly.
End User:
Procurement authority concentration varies sharply across buyer types, from centralized municipal tenders to fragmented household replacement.
- Residential:Individual household purchases through electrical retail and e-commerce platforms dominate volume. Replacement demand from UJALA-distributed bulbs now exceeds new-connection installations. Price sensitivity limits specification to three-star BEE ratings in most states.
- Commercial:Corporate facility managers and landlord entities specify integrated lighting systems for LEED and GRIHA compliance. Bengaluru and Hyderabad IT parks mandate human-centric circadian tuning for employee wellness certification. Procurement runs through annual maintenance contracts rather than spot purchases.
- Industrial:Manufacturing facilities prioritize high-bay efficacy and ingress protection for harsh environments. Gujarat chemical corridors and Tamil Nadu automotive clusters specify IP65-rated fixtures with 50,000-hour rated life.
- Outdoor:Municipal corporations and state nodal agencies tender street-lighting retrofits with decade-long maintenance obligations. Maharashtra, Gujarat, and Tamil Nadu municipalities bundle LED conversion with smart-city command center integration. Vendor qualification requires demonstrated spare-part depot networks within 50 kilometers of installation sites.
Fragmented procurement characterizes residential. Consolidated tendering dominates outdoor.
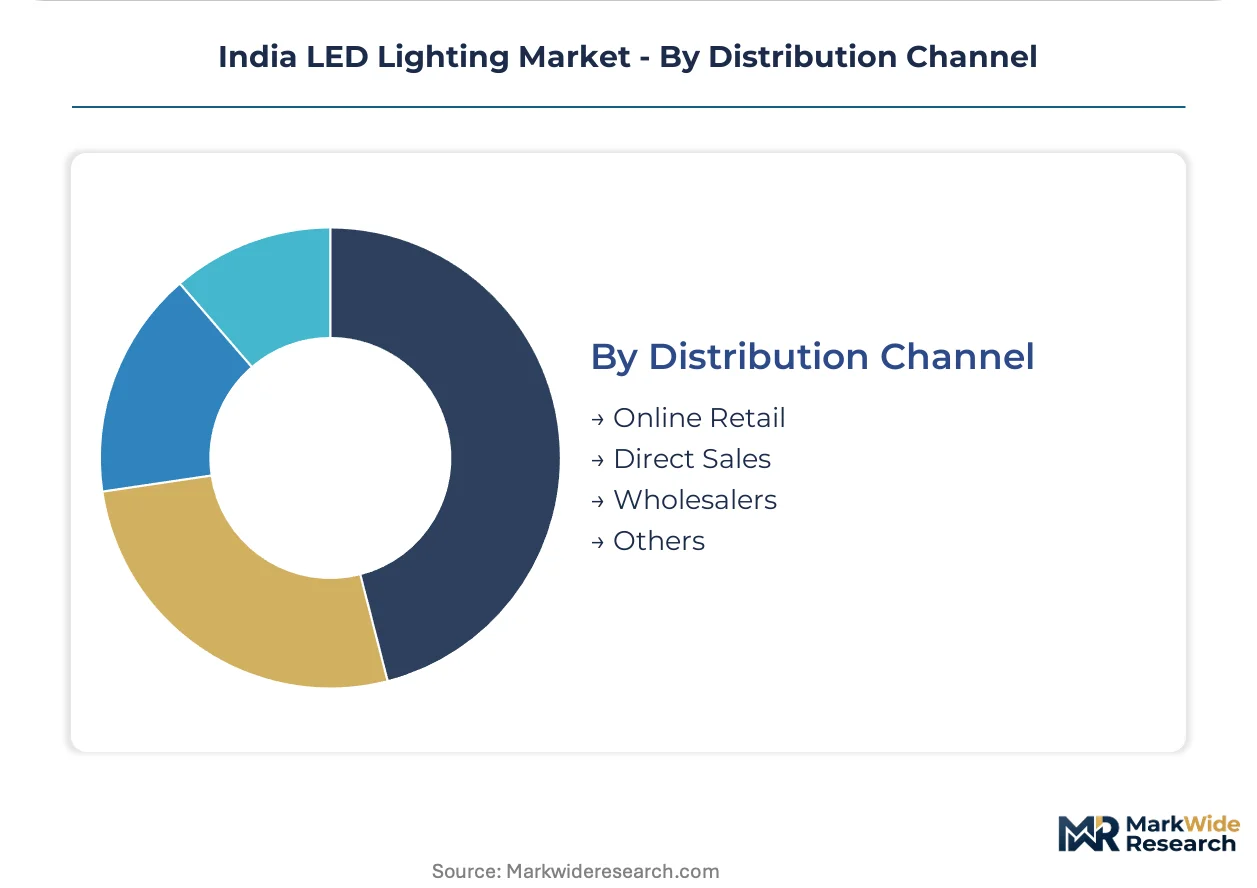
Distribution Channel:
Channel selection determines working capital intensity and brand control, with direct models capturing margin at the cost of inventory risk.
- Online Retail:Amazon India and Flipkart aggregate residential replacement demand with next-day delivery promises. Price transparency compresses brand premiums to 10-15% over unbranded equivalents. BEE star-label visibility in product listings influences conversion rates.
- Direct Sales:Manufacturer-owned specification teams serve commercial and industrial accounts with project engineering support. Wipro Lighting and Havells maintain captive direct channels for institutional retrofit contracts. Payment terms extend to 90-120 days for municipal and corporate accounts.
- Wholesalers:Electrical distribution networks in Lohar Chawl (Mumbai) and Chandni Chowk (Delhi) aggregate contractor procurement for residential and small commercial projects. Inventory risk sits with distributors in this credit-dependent channel.
- Others:ESCO-led performance contracting and vendor-managed inventory for municipal tenders represent emerging channel structures. Gujarat and Tamil Nadu nodal agencies mandate localized spare-part depots as bid prerequisites.
Traditional wholesale handles established residential volume. Direct and ESCO channels are gaining share fastest in commercial and infrastructure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai and the Pune-Nashik industrial corridor anchor Maharashtra's LED procurement volume through municipal smart-city tenders and commercial office retrofits.
Maharashtra
Street-lighting conversions in Mumbai, Pune, and Nagpur drive bulk procurement under 10-year maintenance contracts. State Urban Development Department mandates BEE five-star ratings for new municipal installations. The Mumbai Metropolitan Region concentrates specification activity for human-centric circadian systems in premium commercial fit-outs.
Gujarat
Surat, Ahmedabad, and Vadodara municipalities bundle LED retrofits with smart-city command center integration. Gujarat Energy Development Agency enforces localized spare-part depot requirements as mandatory bid criteria. The Sanand-Vithalapur industrial corridor specifies IP65-rated high-bay fixtures for automotive and chemical process protection.
Tamil Nadu
Chennai, Coimbatore, and Madurai tender street-lighting upgrades with decade-long vendor obligations. Tamil Nadu Generation and Distribution Corporation links commercial building codes to BEE star-label compliance. The Sriperumbudur-Oragadam automotive cluster drives demand for ingress-protected industrial luminaires with 50,000-hour rated life.
Karnataka
Bengaluru's IT corridor and Mysuru's educational infrastructure anchor fixture demand for panel and tube retrofits. Karnataka Renewable Energy Development Ltd promotes solar-hybrid LED systems for grid-unreliable districts. The Whitefield-Electronic City corridor mandates circadian-tunable systems for LEED and GRIHA wellness certification.
Delhi-NCR
Municipal Corporation of Delhi tenders compress replacement cycles through performance-contracting models. Delhi Electricity Regulatory Commission mandates BIS-certified products for all government procurement. The Gurugram-Noida commercial corridor specifies fixture-integrated controls for energy-code compliance in Grade A office developments.
India LED Lighting Market Competitive Environment
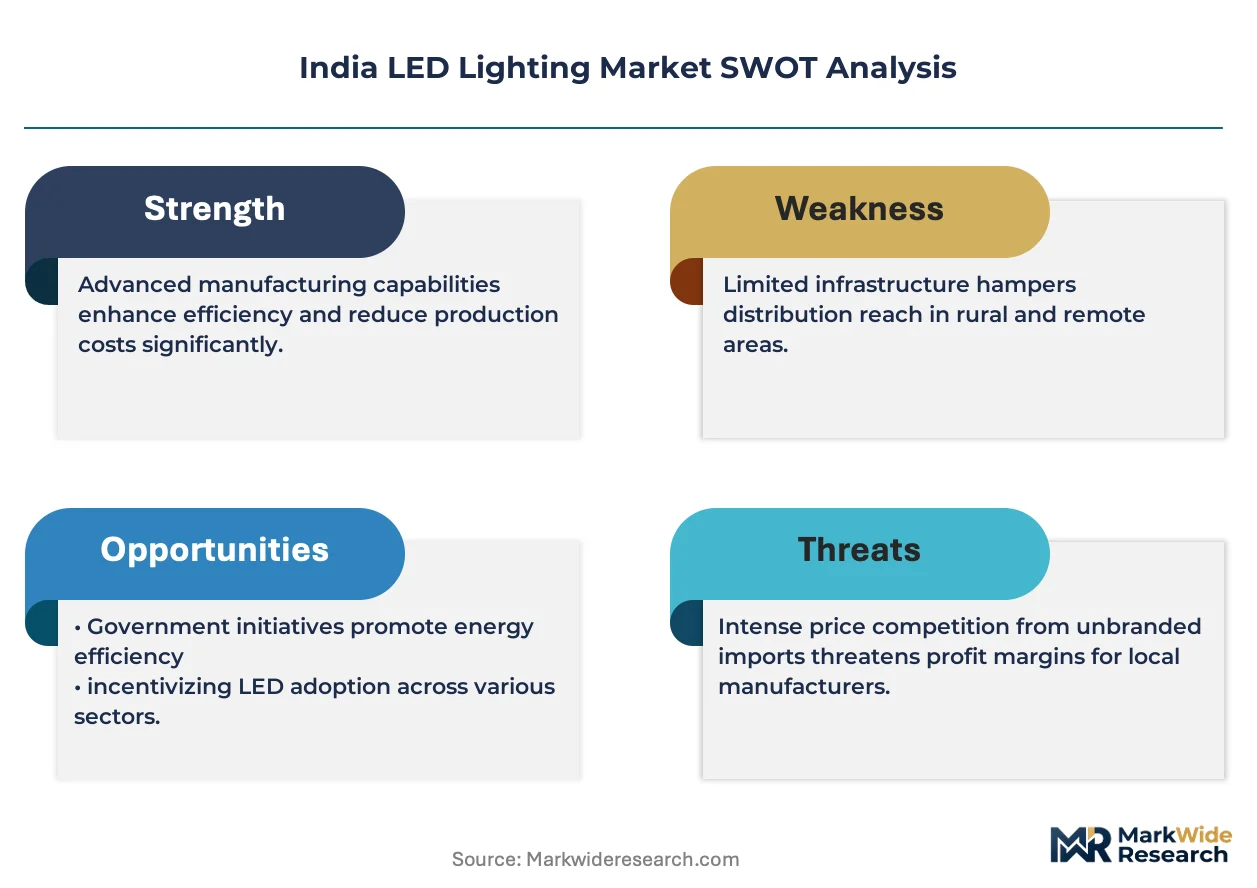
Premium-margin players sit above commodity-margin players across certification tiers and channel control depth. The vendor base stratifies into three tiers: institutional specification specialists with captive direct sales forces, mass-market assemblers competing through electrical wholesale networks, and import-dependent traders facing BIS registration barriers. Strategic moves concentrate on backward integration into driver electronics, expansion of maintenance depot networks for municipal tender qualification, and ESCO partnership structures that capture recurring revenue streams.
Within the institutional specification tier, Wipro Lighting and Havells India Ltd exemplify channel-integrated archetypes with project engineering capabilities and municipal maintenance networks. Syska LED Lights Pvt Ltd occupies the volume-driven commodity position, competing through price-aggressive positioning in residential replacement cycles and electrical wholesale distribution. These three anchors illustrate the market's divergence between premium specification power and mass-market scale economics.
| Leading Market Players |
|---|
| Wipro Lighting |
| Crompton Greaves Consumer Electricals Ltd |
| Philips Electronics India Ltd |
| Polycab India |
| Osram India Pvt Ltd |
| Havells India Ltd |
| Syska LED Lights Pvt Ltd |
| Surya Roshni Ltd |
| Bajaj Electricals Ltd |
| Others |
Value Chain & Pricing Dynamics
Driver IC localization efforts under India's PLI scheme for electronics manufacturing are simultaneously compressing landed costs for domestic assemblers and redrawing procurement maps away from Taiwan-dependent supply lines. This dual shift rewards vendors with captive sourcing arrangements while penalizing traders exposed to semiconductor foundry volatility.
Pricing Analysis
Performance-based contracting anchors municipal street-lighting tenders, where vendors price decade-long maintenance obligations against guaranteed lumen-output thresholds rather than hardware unit costs. Three-tier pricing structure across premium smart-enabled systems, certified standard fixtures, and unbranded economy bulbs reflects BEE star-label differentiation and channel control depth. Pricing pressure stems from aluminum heat-sink cost volatility feeding directly into mass-market bulb margins. Residential replacement buyers through electrical wholesale channels exhibit highest price sensitivity, while commercial facility managers prioritizing LEED compliance accept 40-60% premiums for connected systems.
Supply Chain Analysis
BIS Compulsory Registration Scheme mandates are forcing import-dependent traders to establish domestic assembly footprints or exit the market entirely. Taiwan and China-based semiconductor foundries supply critical LED driver ICs, while domestic aluminum extruders and optical-grade polycarbonate molders feed fixture housing demand. Single-source vulnerability concentrates in Taiwan's foundry capacity for driver electronics. Distribution runs through direct factory-to-municipality tendering for infrastructure projects, electrical wholesale networks for residential replacement, and manufacturer-owned specification teams for commercial retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's LED lighting market is consolidating around certification-compliant manufacturers with captive logistics networks, as BIS registration barriers and municipal tender qualification requirements force smaller assemblers toward acquisition or exit.
For Market Incumbents: Extend maintenance depot networks into Bihar and Uttar Pradesh to capture Saubhagya replacement demand before competitors establish localized spare-part presence. Deepen backward integration into driver electronics manufacturing to insulate margins from Taiwan foundry pricing volatility. Wipro Lighting and Havells demonstrate this playbook through captive semiconductor sourcing and municipal performance-contracting dominance.
For New Entrants and Emerging Players: Capture solar-hybrid LED segments in Rajasthan and Bihar villages with unreliable grid access, where CEA technical standards create qualification barriers for established urban-focused vendors. Target ESCO partnership structures rather than hardware spot sales to bypass working capital intensity of municipal tendering. Position through MNRE subsidy navigation expertise rather than manufacturing scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by institutional specification specialists seeking regional maintenance network density. Long-term viability favors manufacturers with demonstrated BIS certification portfolios and state-level tender track records in Maharashtra, Gujarat, or Tamil Nadu. Watch for BEE star-label threshold revisions that force redesign cycles—vendors with in-house optical engineering capabilities will absorb these costs more efficiently than import-dependent assemblers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver Electronics | Captive semiconductor sourcing insulates margins from Taiwan foundry pricing volatility and supply disruptions. |
| Maintenance Depot Network Expansion | Localized spare-part depots within 50 kilometers of installation sites satisfy mandatory Gujarat and Tamil Nadu tender criteria. |
| ESCO Performance Contracting Partnerships | Revenue share models convert upfront hardware margins into recurring maintenance streams with municipal clients. |
| BEE Five-Star Certification Investment | Maharashtra and Delhi NCR commercial codes mandate top-tier ratings, disqualifying uncertified competitors from premium segments. |
| Solar-Hybrid Product Line Development | CEA-compliant DC-native systems access MNRE-subsidized rural electrification programs beyond grid-dependent urban markets. |
Study Parameters
Document review covered BIS registration databases, Bureau of Energy Efficiency star-label records, and state nodal agency tender documents, complemented by interviews with municipal procurement officers, electrical wholesale distributors, commercial facility managers, and LED fixture manufacturing executives. Secondary validation drew from CEA technical standards filings, SEC disclosures by listed lighting manufacturers, and customs import data for LED driver components. Bottom-up segment sizing triangulated against top-down macroeconomic indicators for infrastructure and construction activity.
Cross-referencing historical procurement volumes from Maharashtra Urban Development Department and Gujarat Energy Development Agency against panel input from ESCO operators and specification engineers informed the analytical framework. Segmentation dimensions modeled include product form factor, connectivity architecture, end-user procurement authority, and regional regulatory cluster. CAGRs were derived through slope analysis of replacement cycle compression and smart-city deployment trajectories, incorporating aluminum price elasticity and semiconductor lead time assumptions.
The model holds under continued BIS enforcement and PLI scheme continuity for electronics manufacturing; deviation in tariff treatment for Taiwan-sourced driver ICs or suspension of municipal smart-city funding would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
United States Micro LED Market
LED
Global Outdoor LED Lighting Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Single-Digit 7 Segment LED Displays Market
LED
India Indoor LED Lighting Market
LED
LED Encapsulation Market
LED
Indonesia LED Market
LED
Superluminescent Diodes Market
LED
Asia Pacific Indoor LED Lighting Market
LED
UK Indoor LED Lighting Market
LED
Mini LED Market
LED
Middle East LED Lighting Market
LED
LED Tube Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Japan LED Lighting Market