
 North America Underground Mining Equipment Market | 2026-2036
North America Underground Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Underground Mining Equipment Market Analytics
Canadian hard-rock mining capacity is expanding across Ontario and Quebec, drawing renewed investment in mechanized extraction fleets. Caterpillar Inc. leverages its integrated powertrain architecture to anchor large-scale loader and haul truck deployments in Canadian base metal operations. Komatsu Ltd. sustains competitive pressure through autonomous haulage system integration, while Epiroc AB specializes in battery-electric drill platforms designed for zero-emission development headings.
Underground mining equipment encompasses specialized mechanized systems engineered for ore extraction, ground support, and material transport in subterranean operations, typically operating within confined headings of 3 to 6 meters in width and under ventilation-limited conditions where diesel particulate exposure must be controlled. These systems serve primary industrial functions in metal, mineral, and coal recovery where surface extraction proves economically or geologically unviable. Haul trucks and loaders dominate current fleet value owing to their central role in production cycle economics and replacement intensity in deep operations. Automation technology commands disproportionate capital allocation as operators pursue remote mucking and haulage to reduce ventilation burdens and labor exposure in seismically active ground.
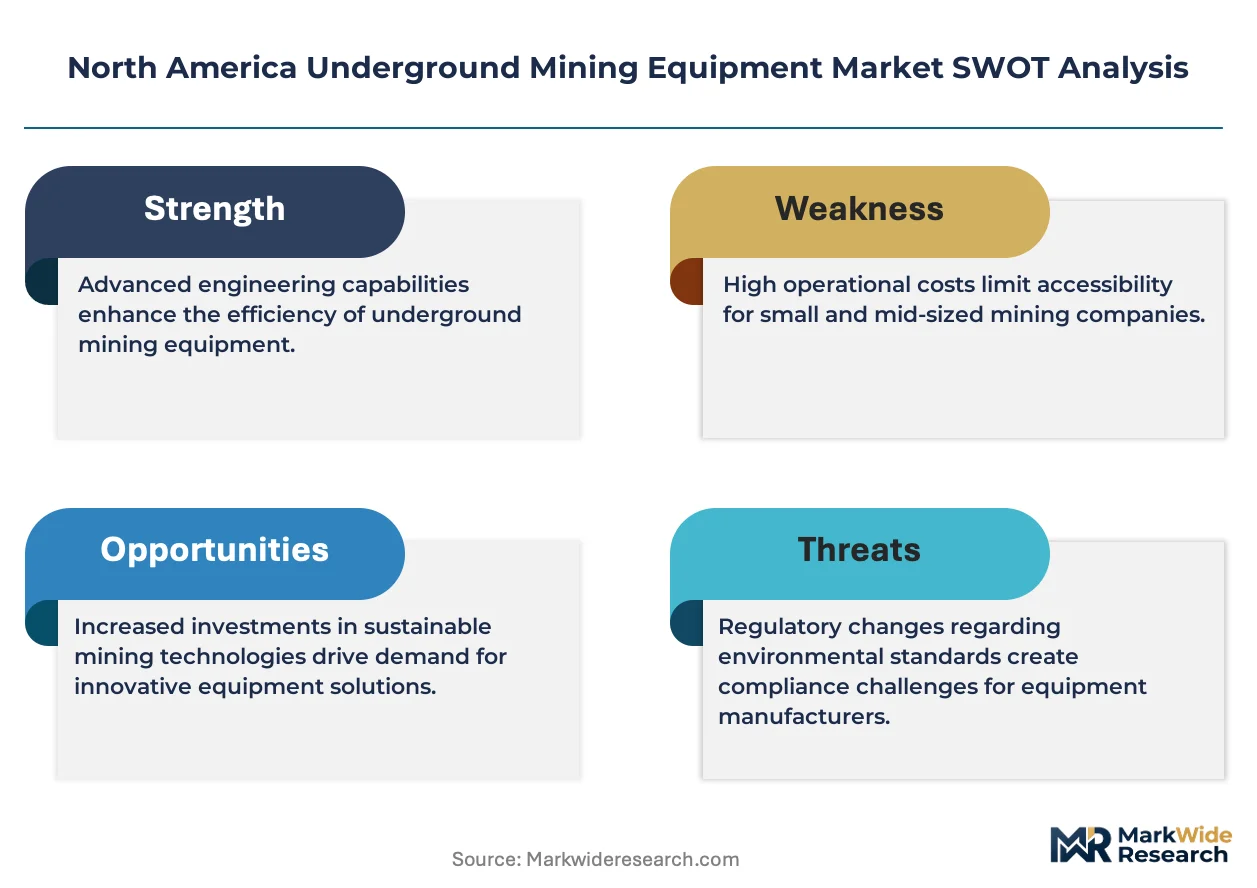
MSHA ventilation and diesel particulate standards, EPA Tier 4 Final emissions requirements, and Ontario's Mining Act modernization collectively compress allowable equipment specifications and accelerate electrification timelines. Canadian provincial regulators and U.S. federal mine safety inspectors are tightening conformance windows for particulate exposure and noise attenuation, effectively filtering non-compliant legacy fleets from active operations. Stakeholders must monitor the pace of charging infrastructure deployment in remote mine sites and the interoperability standards governing mixed autonomous-conventional fleet operations.
Market Dynamics
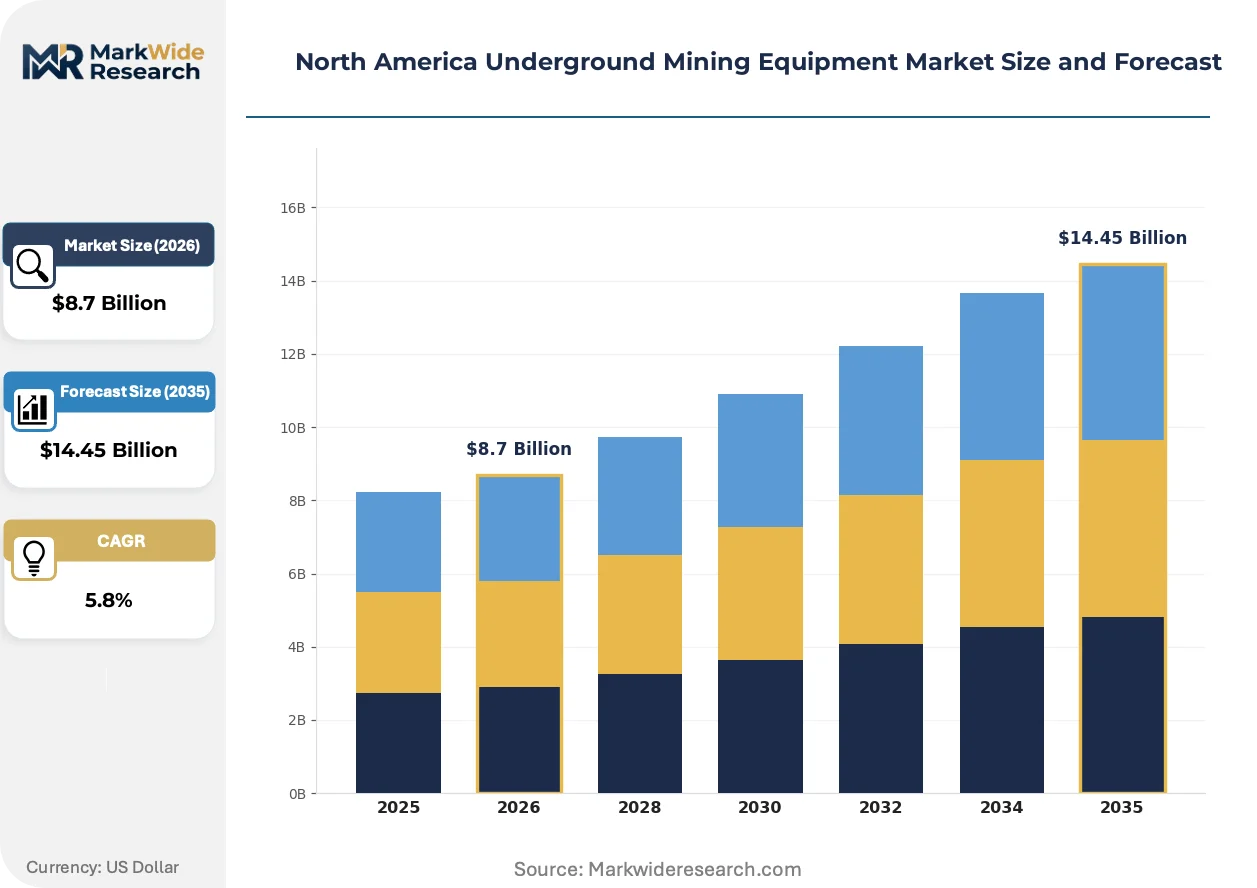
Battery-electric powertrain adoption is compressing fleet replacement cycles across North American underground operations as MSHA ventilation constraints and EPA Tier 4 Final compliance deadlines force capital reallocation from diesel to zero-emission platforms.
Growth Catalysts
- MSHA Diesel Particulate Standards:Stricter exposure limits in metal and non-metal mines are accelerating equipment turnover toward battery-electric loaders and haul trucks that eliminate diesel exhaust in confined headings.
- Lithium-Copper Extraction Surge:Nevada's Thacker Pass and Ontario's Ring of Fire developments are expanding mechanized fleet deployments for hard-rock extraction in previously marginal deposits.
- Autonomous Haulage Integration:Remote operation capabilities are reducing ventilation requirements and labor exposure in seismically active ground, driving capital investment in retrofit-ready platforms.
Market Restraints
- Charging Infrastructure Capital Intensity:Remote mine sites require substantial grid reinforcement and battery-swap station deployment before electrified fleets achieve operational parity with diesel refueling cycles.
- Critical Mineral Supply Concentration:Permanent magnet and lithium-ion cell supply chains concentrate in Asia-Pacific jurisdictions, exposing North American equipment manufacturers to input cost volatility and trade policy friction.
- Interoperability Standards Gap:Mixed autonomous-conventional fleet operations face protocol fragmentation between OEM telematics systems, complicating integration timelines.
Strategic Opportunities
- Ontario Mining Act Modernization:Streamlined permitting for critical mineral projects is opening development corridors in the James Bay Lowlands for mechanized extraction fleet deployment.
- Remanufacturing and Retrofit Services:Existing diesel fleets in Arizona and Nevada copper operations present addressable white space for powertrain conversion to battery-electric configurations.
- 5G Private Network Deployment:Underground connectivity infrastructure is enabling real-time telematics and predictive maintenance platforms that differentiate aftermarket service offerings.
Industry Challenges
- Battery Thermal Management Expertise:Underground operations lack sufficient maintenance technicians trained in high-voltage battery systems and thermal runaway containment protocols.
- MSHA Type Approval Timelines:Battery-electric vehicle certification processes lag procurement schedules, creating fleet deployment delays during compliance transition windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Underground Mining Equipment Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loaders, Drills, Haul Trucks, Rock Bolters Technology: Automation, Hydraulic, Electric, Pneumatic End User: Coal Mining, Metal Mining, Mineral Mining, Precious Metals Application: Development, Production, Transportation, Construction |
| Companies Covered | Komatsu Ltd., J.H. Fletcher & Co., Caterpillar Inc., Liebherr Group, Getman Corporation, Epiroc AB, Boart Longyear, AB Volvo, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Underground Mining Equipment Market Evolving Landscape
Electrification and automation are converging to redefine fleet economics in North American underground mining, with technology suppliers prioritizing integrated powertrain-telemetrics platforms over standalone mechanical systems.
Battery-electric load-haul-dump units are overtaking diesel equivalents in new fleet specifications for Canadian base metal operations. Gold and copper producers in Ontario and Quebec are specifying zero-emission platforms for development headings to reduce ventilation infrastructure costs. This transition is compressing the addressable market for Tier 4 Final diesel powertrains and redirecting R&D investment toward energy density optimization and fast-charge protocols.
EPA Tier 4 Final emissions requirements are eliminating non-compliant legacy equipment from active U.S. metal mining operations. Underground coal and metal producers face accelerated replacement schedules for diesel haul trucks and loaders that cannot meet particulate and NOx thresholds. The Southwestern United States copper belt is responding with concentrated procurement of battery-electric and hybrid platforms to maintain operating permits.
Equipment-as-a-service contracting is displacing traditional capital purchase models in Nevada gold operations. Mid-tier producers are unbundling fleet ownership from maintenance and upgrade obligations, transferring residual value risk to OEM financing arms. This shift is most visible in the Carlin and Battle Mountain trends where operators prioritize operational expenditure predictability over balance sheet asset control.
North America Underground Mining Equipment Market Segmentation
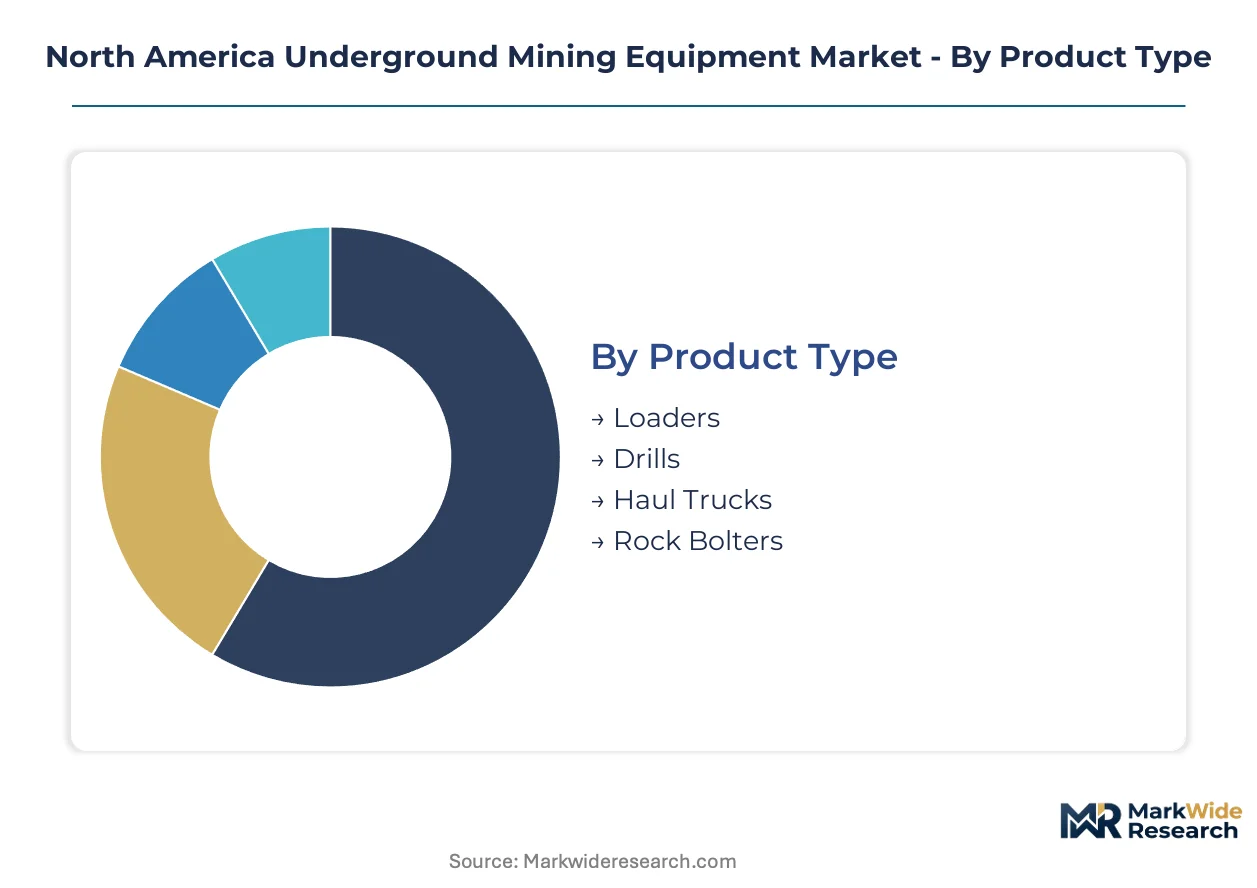
Equipment segmentation in North American underground mining tracks how capital cycles align with MSHA compliance deadlines and electrification roadmaps. Fleet managers prioritize segments offering retrofit compatibility and charging infrastructure interoperability.
Product Type:
Upgrade cycles vary sharply by equipment category, with ventilation-constrained headings driving differential replacement timelines.
- Loaders:Load-haul-dump units constitute the highest-value fleet component in base metal operations, with bucket capacities ranging from 6 to 21 cubic meters. Procurement concentrates in Nevada's gold-copper belt and Ontario's Sudbury Basin as operators phase out Tier 4 Final non-compliant diesel units. Battery-electric variants command premium positioning where ventilation infrastructure costs exceed electrification premiums.
- Haul Trucks:Articulated underground trucks handle ore transport from extraction faces to shaft systems, with payload ratings spanning 30 to 60 tonnes. Demand clusters in Arizona porphyry copper operations and Quebec zinc-lead districts where deep mining intensifies fleet utilization rates. Autonomous retrofit compatibility now filters procurement specifications.
- Drills:Mechanized drilling platforms execute blasthole and bolting functions in development headings.
- Rock Bolters:Ground support equipment installs pattern bolting for seismic ground control in seismically active mining districts.
Haul trucks sit at the top of the volume ranking, with battery-electric loaders climbing the fastest.
Technology:
Technology selection hinges on powertrain architecture decisions made at the mine planning stage, with electrification timelines compressing hydraulic equipment's remaining service window.
- Electric:Battery-electric powertrains eliminate diesel particulate exposure in confined headings while reducing ventilation infrastructure capital. Adoption accelerates in Nevada lithium projects and Ontario critical mineral corridors where EPA and provincial emissions frameworks tighten conformance windows.
- Automation:Remote and autonomous operation capabilities reduce labor exposure in seismically active ground while compressing ventilation requirements. Integration concentrates in Saskatchewan potash and Michigan nickel operations where labor availability constraints intersect with safety mandates.
- Hydraulic:Fluid-power systems dominate legacy fleet compositions in Appalachian coal and Rocky Mountain metal districts.
- Pneumatic:Compressed-air drive systems persist in specialty drilling and small-scale development applications.
Electric systems anchor current procurement volumes, with automation expanding most quickly as retrofit protocols mature.
End User:
End-use segmentation reflects ore body geology and regulatory exposure, with metal mining outpacing coal in fleet modernization intensity.
- Metal Mining:Copper, nickel, and zinc operations in Arizona, Nevada, and Quebec drive mechanized fleet investment as deposits deepen and ore grades decline. MSHA metal/non-metal mine standards apply distinct particulate exposure limits that accelerate battery-electric specification.
- Precious Metals:Gold and silver producers in Nevada's Carlin Trend and Ontario's Red Lake district prioritize automation to reduce labor costs in remote locations. Electrification aligns with corporate sustainability commitments and permitting requirements.
- Coal Mining:Underground bituminous operations in Appalachia and Illinois Basin face divergent regulatory pressures and capital constraints.
- Mineral Mining:Potash, salt, and trona extraction in Saskatchewan and New Mexico maintains steady equipment demand.
Metal mining commands the largest equipment volume, with precious metals gaining share fastest on automation adoption.
Application:
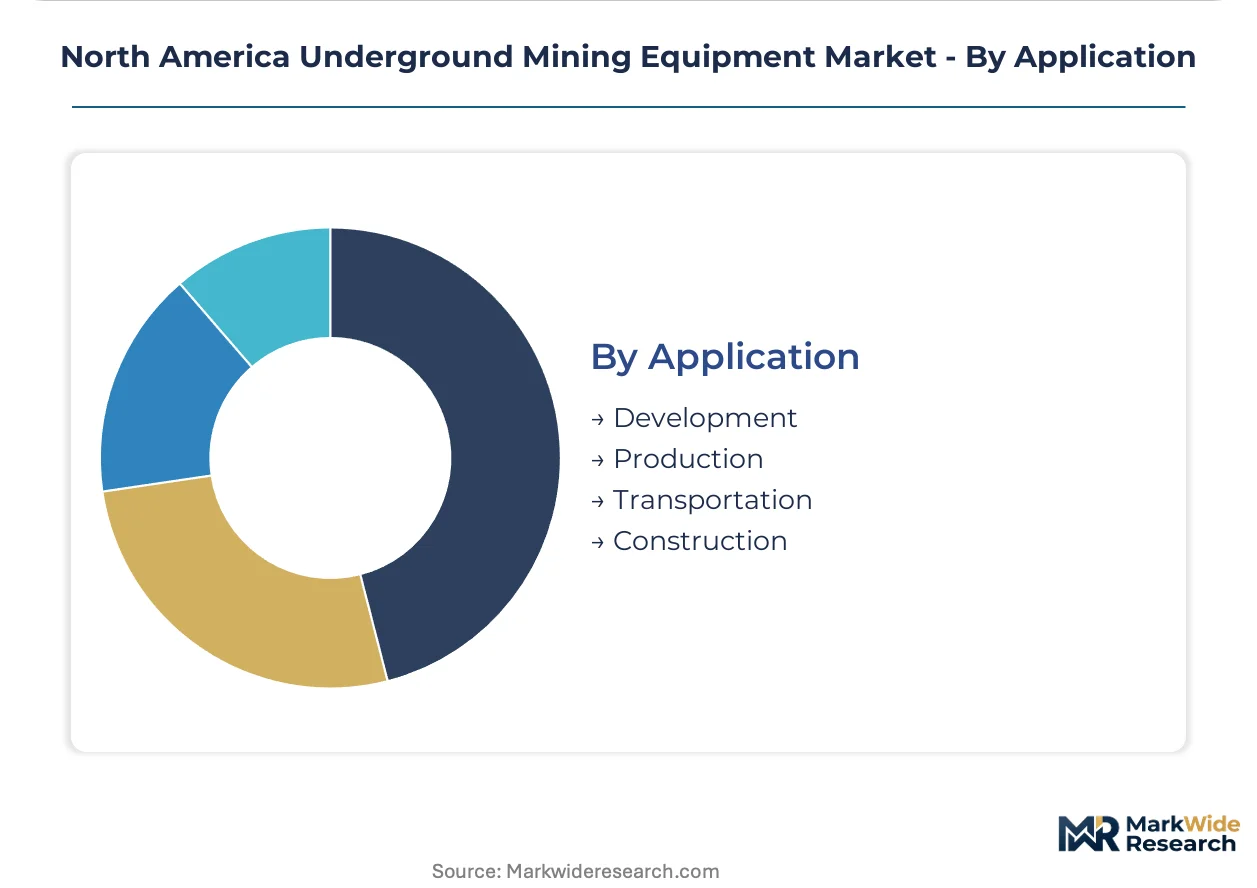
Application segmentation tracks the mining cycle from initial development through sustained production, with development-phase equipment facing tighter emissions constraints.
- Development:Ramp and drift excavation equipment operates in advancing headings where ventilation is most constrained. Battery-electric specification is near-mandatory in new Canadian base metal projects under provincial emissions frameworks.
- Production:Extraction-phase equipment at active faces handles ore loading and initial transport. Haul trucks and loaders in this segment face compressed replacement cycles as EPA Tier 4 Final deadlines eliminate diesel alternatives.
- Transportation:Materials handling systems move ore from extraction levels to shaft hoisting infrastructure.
- Construction:Mine infrastructure development employs specialized equipment for shaft sinking and lateral development.
Production applications anchor equipment volumes, with development-phase electrification climbing fastest on ventilation cost pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement patterns as operators migrate capital toward jurisdictions with faster permitting timelines and clearer electrification mandates. The cost-of-compliance gap between MSHA-regulated U.S. operations and provincially governed Canadian sites is accelerating cross-border investment flows.
United States
Nevada's lithium-copper belt and Arizona's porphyry copper districts are driving concentrated demand for battery-electric loaders and autonomous haul trucks. EPA Tier 4 Final emissions requirements are eliminating non-compliant diesel fleets from active metal mining operations. The Carlin Trend and Battle Mountain clusters see accelerated equipment turnover as operators pursue MSHA ventilation cost reductions through electrification.
Canada
Ontario's Ring of Fire development corridor and Quebec's critical mineral projects are expanding mechanized fleet deployments for hard-rock extraction. The Ontario Mining Act modernization is streamlining permitting timelines for battery-electric equipment procurement in the James Bay Lowlands. Sudbury Basin nickel-copper operations anchor Canadian base metal demand for zero-emission development headings.
Mexico
Sonora's lithium clay deposits and Zacatecas silver-gold districts are drawing equipment investment as North American supply chain localization intensifies. Mexican federal mining regulations under Secretaría de Economía oversight are aligning emissions frameworks with U.S. EPA benchmarks. The Sierra Madre Occidental mining belt is emerging as a procurement corridor for electrified underground fleets.
North America Underground Mining Equipment Market Competitive Landscape
North American producers anchor the premium-tier equipment segment; European and Japanese specialists hold positions in automation and battery-electric platforms. Market structure concentrates around integrated powertrain architects, autonomous system integrators, and regional fabrication specialists. Strategic archetypes include full-line OEMs with captive financing arms, technology licensors specializing in telematics, and regional rebuild centers offering powertrain conversion services. Competitive moves center on charging infrastructure partnerships and MSHA type approval acceleration.
Within the full-line OEM tier, Caterpillar Inc. and Komatsu Ltd. occupy positions defined by integrated powertrain architectures and autonomous haulage capabilities. Epiroc AB exemplifies the battery-electric specialization archetype, anchoring zero-emission platform development for confined headings. These three companies represent distinct competitive vectors: scale-driven manufacturing, automation system integration, and electrification technology leadership.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| J.H. Fletcher & Co. |
| Caterpillar Inc. |
| Liebherr Group |
| Getman Corporation |
| Epiroc AB |
| Boart Longyear |
| AB Volvo |
| Sandvik AB |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between MSHA type-approved battery-electric platforms and legacy diesel equipment manifests in both procurement premiums and supply chain sourcing patterns, with Tier 4 Final compliance deadlines compressing the addressable market for non-certified powertrains while concentrating component sourcing among qualified electrification suppliers.
Pricing Analysis
Distributor margins on battery-electric loaders and haul trucks run 12-18 points above diesel equivalents due to specialized commissioning requirements and charging infrastructure bundling. Three-tier pricing structure across premium zero-emission platforms, Tier 4 Final diesel, and remanufactured legacy units reflects MSHA certification timelines and energy density specifications. Cost compression in mid-tier diesel equipment is intensifying because EPA compliance deadlines eliminate non-conforming inventory. Mid-tier copper operators in Arizona exhibit highest price sensitivity, while Nevada lithium developers prioritize electrification premiums for permitting acceleration.
Supply Chain Analysis
Remanufacturing flows from Arizona and Nevada copper districts back to Ontario and Quebec rebuild centers anchor circular supply chain economics for legacy diesel fleets. Permanent magnet motors and lithium-ion cells draw from China, South Korea, and Japan, while steel castings and hydraulic systems source from domestic U.S. and Mexican fabrication hubs. Single-source vulnerability in rare-earth magnet supply creates exposure to trade policy friction. Distribution runs through OEM captive financing arms and regional equipment dealers with MSHA-certified service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where fleet modernization toward battery-electric specifications commands premium positioning, justified by the demand-shift toward zero-emission development headings under provincial and federal emissions frameworks.
For Market Incumbents: Hedge exposure to legacy diesel inventory obsolescence by accelerating powertrain conversion service capabilities in Southwestern U.S. rebuild centers. Channel control through captive financing arms defends margin position against emerging retrofit specialists. Backward integration into battery thermal management training programs addresses technician scarcity as a competitive moat.
For New Entrants and Emerging Players: Mid-tier gold operators in Nevada's Battle Mountain trend represent an underserved buyer archetype seeking equipment-as-a-service contracting without legacy OEM dependency. White space concentrates in autonomous retrofit kits for existing haul truck fleets and 5G private network deployment services. A go-to-market angle anchored to charging infrastructure partnerships with utility cooperatives bypasses incumbent dealer lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where MSHA type approval capabilities concentrate among a narrowing set of qualified electrification suppliers. Long-term viability favors integrated powertrain architects with autonomous system integration depth over standalone mechanical fabricators. Acquisition target archetype: regional rebuild centers with MSHA certification and battery-electric conversion expertise. The signal to watch is charging infrastructure deployment velocity at remote mine sites as fleet electrification inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Electric Platform Certification | MSHA type approval accelerates procurement timelines for Nevada lithium developers under EPA Tier 4 Final deadlines. |
| Autonomous Haulage Integration | Komatsu's retrofit protocols reduce ventilation burdens in Ontario's seismically active Sudbury Basin operations. |
| Charging Infrastructure Partnership | Grid reinforcement agreements with utility cooperatives enable fleet electrification at remote Arizona copper sites. |
| Powertrain Conversion Services | Remanufacturing diesel fleets to battery-electric configurations extends asset life for mid-tier Nevada gold producers. |
| 5G Private Network Deployment | Underground connectivity infrastructure enables predictive maintenance platforms that differentiate aftermarket service offerings. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combining interviews with mine operations directors, OEM procurement teams, MSHA compliance officers, and aftermarket service heads with secondary validation from EPA emissions filings, MSHA accident and injury databases, provincial mining ministry records, and SEC equipment manufacturer disclosures. Bottom-up fleet inventory analysis triangulates against top-down capital expenditure tracking across the analysis window.
Rate-of-change decomposition separates volume effects from mix-shift toward premium electrified platforms across the projection horizon. Segmentation dimensions modeled include equipment category, powertrain architecture, autonomy integration level, end-use mineral type, and regional regulatory cluster. CAGRs derive from equipment replacement cycle compression analysis and electrification adoption curve calibration, with forecast inputs incorporating MSHA ventilation standard enforcement timelines and provincial permitting velocity in Ontario's Ring of Fire corridor.
Inputs from mine operators and OEM product planners were available through the study window; gaps in pre-commercial battery-electric fleet performance data introduce uncertainty bands around utilization rate assumptions. Forecasts reflect documented assumptions regarding charging infrastructure deployment schedules and MSHA certification processing timelines. Practitioners should monitor permanent magnet supply chain disruptions and autonomous fleet interoperability standard developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Mechanical Mine Clearance System Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Pin Drilling Unit Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Drilling Stabilizers Market
Mining Equipment
Global Large Mining Shovels Market