
 Drill Pipe Market | 2026-2036
Drill Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Pipe Market Intelligence
API 5DP certification is unwinding the competitive landscape by disqualifying smaller mills that lack in-house heat-treating capacity. Tenaris S.A. leverages its seamless pipe mills in Veracruz to dominate premium connections for high-pressure drilling. NOV Inc. anchors North American supply through backward integration into tool joint forging and hardbanding operations. Vallourec S.A. competes via specialized sour-service grades certified to NACE MR0175 for H2S-rich formations.
Drill pipe consists of hollow steel tubes with threaded tool joints at each end, typically manufactured from AISI 4145H modified alloy steel with yield strengths ranging from 75,000 to 150,000 psi to transmit torque and convey drilling fluid in rotary drilling assemblies. Heavy weight drill pipe occupies the highest margin pool as operators specify proprietary double-shoulder connections for extended-reach laterals. Alloy steel commands structural priority over carbon grades in shale basins where fatigue resistance determines replacement cycles. The oil and gas end-user segment sustains dominant volume absorption despite mining and utility sector diversification.
API 5DP, NACE MR0175, and ISO 11960 collectively govern material selection, sour-service qualification, and dimensional traceability for drill pipe deployed in critical wells. The EPA's methane emissions rules and OSHA's crystalline silica standards shape field handling protocols and drive demand for corrosion-resistant alloys that reduce replacement frequency. Stakeholders must monitor API specification ballot activity and rig fleet electrification timelines to align alloy development with next-generation drilling power requirements.
Market Dynamics
Extended-reach lateral drilling in North American shale basins is forcing a structural upgrade cycle in drill pipe specifications, as operators push beyond 15,000-foot laterals that exceed the fatigue limits of conventional API-grade materials.
Growth Catalysts
- EPA methane emissions rules:Tighter leak-detection mandates accelerate replacement of corroded pipe strings, driving demand for sour-service alloys that extend operational life in H2S-rich formations.
- Permian Basin lateral extension:Unconventional operators in West Texas and southeastern New Mexico are consuming premium double-shoulder connections as wellbore complexity outpaces legacy equipment capabilities.
- API 5DP specification revisions:Tightened dimensional tolerances for sour service applications are disqualifying non-compliant inventory, forcing fleet-wide upgrades among independent drilling contractors.
Market Restraints
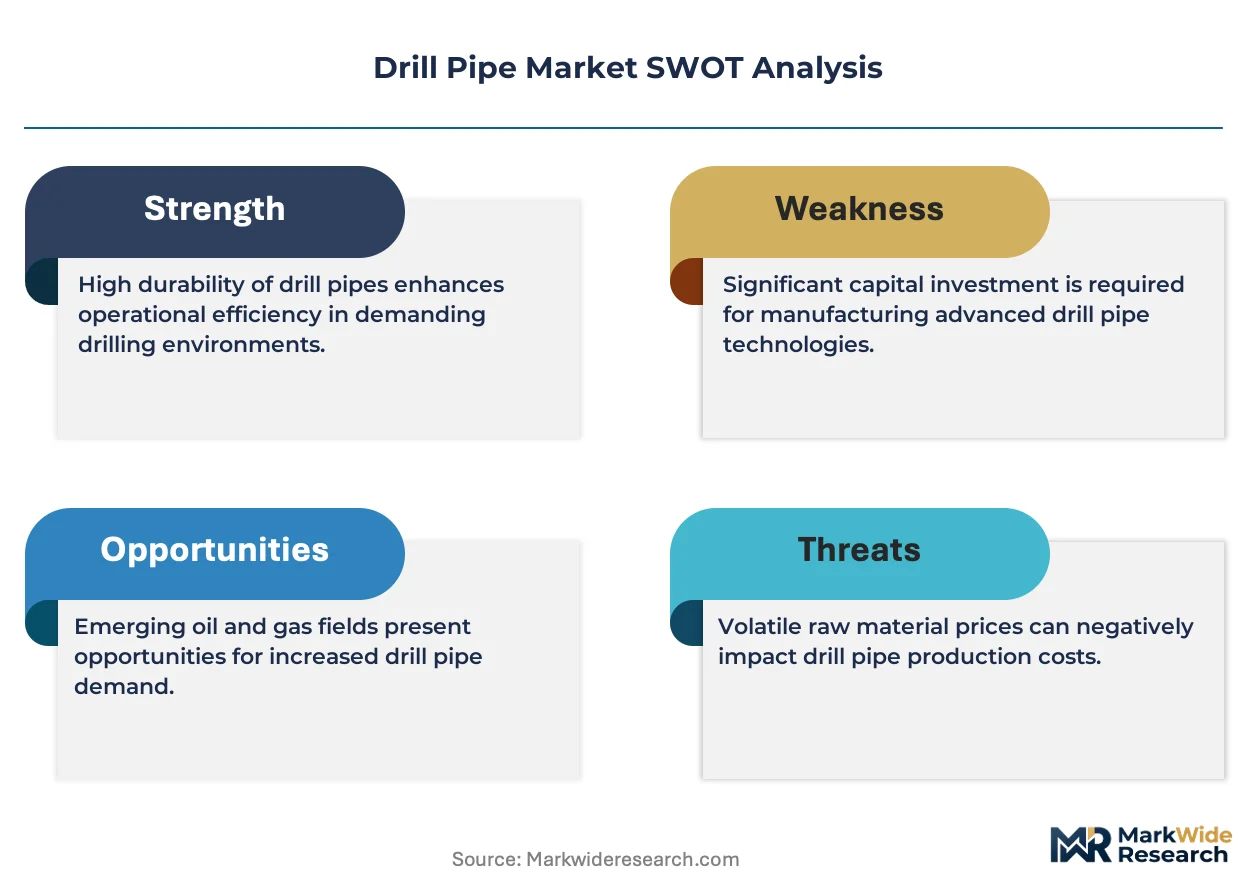
- Alloy steel input volatility:Nickel and molybdenum price swings compress margins for mills without long-term ore offtake agreements or captive scrap recycling.
- Heat-treating capacity concentration:In-house quenching and tempering capabilities cluster among integrated producers, leaving smaller mills dependent on third-party processors with extended lead times.
- Carbon-grade substitution ceiling:Standard carbon steel cannot meet fatigue requirements beyond 12,000-foot laterals, structurally capping its addressable market regardless of price competitiveness.
Strategic Opportunities
- Argentina Vaca Muerta development:State-backed drilling campaigns in Neuquén Province are importing premium connection expertise as international operators enter the unconventional shale play.
- Rig fleet electrification:Land-based AC-powered rigs generate distinct torque signatures that favor specialized alloy formulations, creating specification white space for metallurgy-first suppliers.
- Direct mill-to-rig distribution:Bypassing traditional oilfield service distributors reduces handling damage and traceability gaps, appealing to super-spec rig operators with integrated supply chains.
Industry Challenges
- NACE MR0175 certification timelines:Sour-service qualification protocols require 90-day hydrogen-induced cracking tests that delay new product launches and tie up R&D capital.
- Tool joint hardbanding skill scarcity:Automated welding of tungsten carbide overlays demands certified technicians that training programs have failed to replenish at replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Pipe Market |
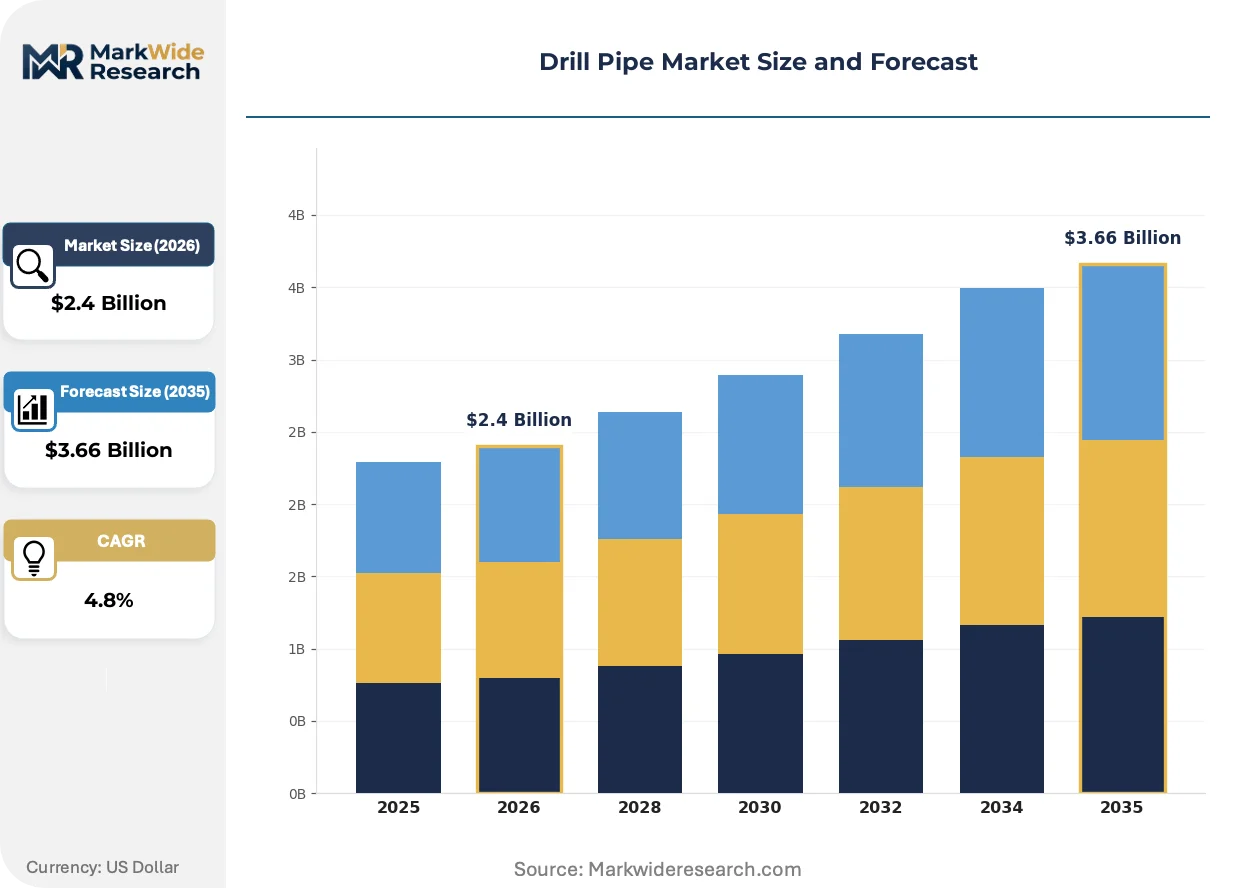
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Weight Drill Pipe, Drill Collars, Standard Pipe, Tool Joint Material: Carbon Steel, Alloy Steel, Stainless Steel, Composite Materials End User: Oil & Gas, Mining, Construction, Utility Sector Delivery Mode: Direct Supply, Warehousing, On-Demand, Third-Party Logistics |
| Companies Covered | NOV Inc., Tenaris S.A., Vallourec S.A., TMK Group, Hilong Group, Oil Country Tubular Limited, Superior Drill Pipe Manufacturing Inc., DP Master Manufacturing Pte Ltd., Drill Pipe International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Pipe Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are fragmenting the drill pipe market into parallel premium and standard tiers, with specification divergence now outpacing price-based competition.
Advanced chromium-molybdenum alloy formulations are bifurcating the product landscape between fatigue-rated premium strings and commodity-grade inventory. Super-spec rig operators in the Permian and DJ Basins are specifying proprietary modified-AISI compositions for 20,000-foot measured-depth wells. This metallurgical stratification is compressing resale values of non-compliant used pipe and concentrating procurement authority among integrated mills with in-house metallurgy labs.
OSHA crystalline silica exposure limits are reshaping field handling protocols for pipe inspection and refurbishment operations. The standard mandates engineering controls and respiratory protection during abrasive blasting of used tool joints, adding capital intensity to reclamation services. Independent repair shops in Texas and Oklahoma are consolidating or exiting as compliance costs exceed the economics of small-batch reconditioning.
Buyer concentration among super-independent drilling contractors is collapsing the traditional distributor layer in North American supply chains. Large fleet operators in the Permian Basin now negotiate direct volume commitments with Veracruz and Baytown mill complexes, displacing oilfield service intermediaries that historically managed logistics and inspection. This channel compression is most visible among top-20 US land drillers with 50-plus rig fleets and in-house supply chain teams.
Drill Pipe Market Segmentation
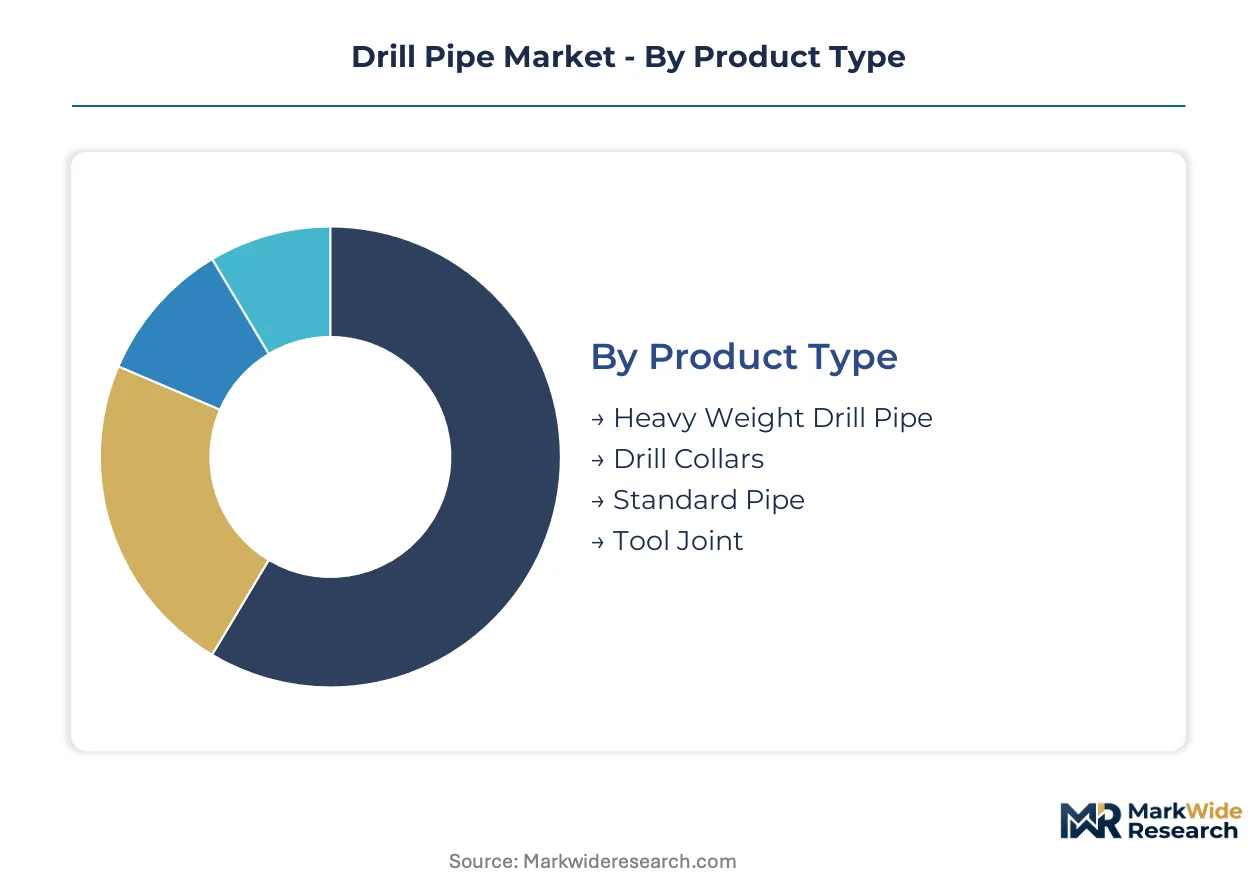
Drill pipe procurement patterns fragment sharply across material grades and connection specifications, with API 5DP certification tiers creating irreversible stratification between premium alloy strings and commodity carbon inventory. Specification divergence now dictates replacement cycles more than price elasticity, forcing segmentation logic to center on fatigue performance and sour-service qualification rather than traditional dimensional categories.
Product Type:
API 5DP dimensional tolerances and proprietary connection geometries separate premium strings from standard inventory, with specification tiers directly determining field deployment limits for extended-reach laterals.
- Heavy Weight Drill Pipe:Manufactured with thickened wall sections and proprietary double-shoulder connections to manage bending stress in high-angle wellbores. Permian Basin operators specify these strings for laterals exceeding 15,000 feet where conventional pipe fatigues prematurely. The segment commands the highest margin pool as super-spec rig fleets standardize on fatigue-rated configurations.
- Drill Collars:Solid steel bars with threaded connections provide compressive weight on bit for directional steering. Demand concentrates in unconventional shale plays where rotary steerable systems require precise weight transfer through doglegs and horizontal sections.
- Standard Pipe:Conventional API-grade tubulars with single-shoulder tool joints serve vertical and low-complexity deviated wells. Carbon-grade substitution limits addressable market to formations under 12,000-foot measured depth regardless of price competitiveness.
- Tool Joint:Forged alloy connectors with hardbanding overlays protect against thread wear and external abrasion. NACE MR0175-certified variants dominate sour-service procurement as H2S exposure mandates material upgrades.
Heavy Weight Drill Pipe handles the majority of throughput in premium procurement; Tool Joint is gaining share fastest as hardbanding automation reshapes repair economics.
Material:
Cost tiers stratify procurement authority between integrated mills with captive metallurgy and distributors trading commodity grades.
- Alloy Steel:Modified AISI 4145H and chromium-molybdenum formulations deliver 75,000 to 150,000 psi yield strength for high-cycle fatigue resistance. West Texas operators mandate these grades for 20,000-foot measured-depth wells where conventional materials fail.
- Carbon Steel:Standard grades serve low-stress vertical drilling and workover operations. Price volatility in scrap and ore markets compresses margins for non-integrated suppliers without long-term offtake agreements.
- Stainless Steel:Corrosion-resistant formulations address CO2-rich formations and geothermal applications. Niche deployment limits volume despite superior chemical resistance profiles.
- Composite Materials:Fiber-reinforced polymers reduce weight for coiled-tubing integration and corrosive environments. Early-stage qualification delays mainstream adoption in pressure-critical well construction.
Alloy Steel dominates replacement-driven procurement; Composite Materials show the steepest expansion trajectory as weight reduction targets intensify.
End User:
Application severity determines specification stringency, with hydrocarbon extraction imposing material standards that mining and construction segments rarely require.
- Oil & Gas:Rotary drilling assemblies for exploration and production transmit torque, convey drilling fluid, and withstand cyclic loading in high-pressure formations. EPA methane rules and OSHA silica standards mandate corrosion-resistant alloys that extend string life and reduce handling exposure.
- Mining:Raise boring and exploration coring operations demand robust tool joints for intermittent high-torque applications. Lower duty cycles permit carbon-grade deployment absent sour-gas constraints.
- Construction:Foundation drilling and micropile installation utilize shorter strings with simplified connection geometries. Price sensitivity favors standard API grades over premium sour-service specifications.
- Utility Sector:Geothermal and water well drilling present moderate corrosion challenges without H2S exposure. Regional procurement patterns mirror local drilling contractor fleet compositions.
Oil & Gas absorbs dominant volume; Utility Sector is expanding most quickly as geothermal development accelerates.
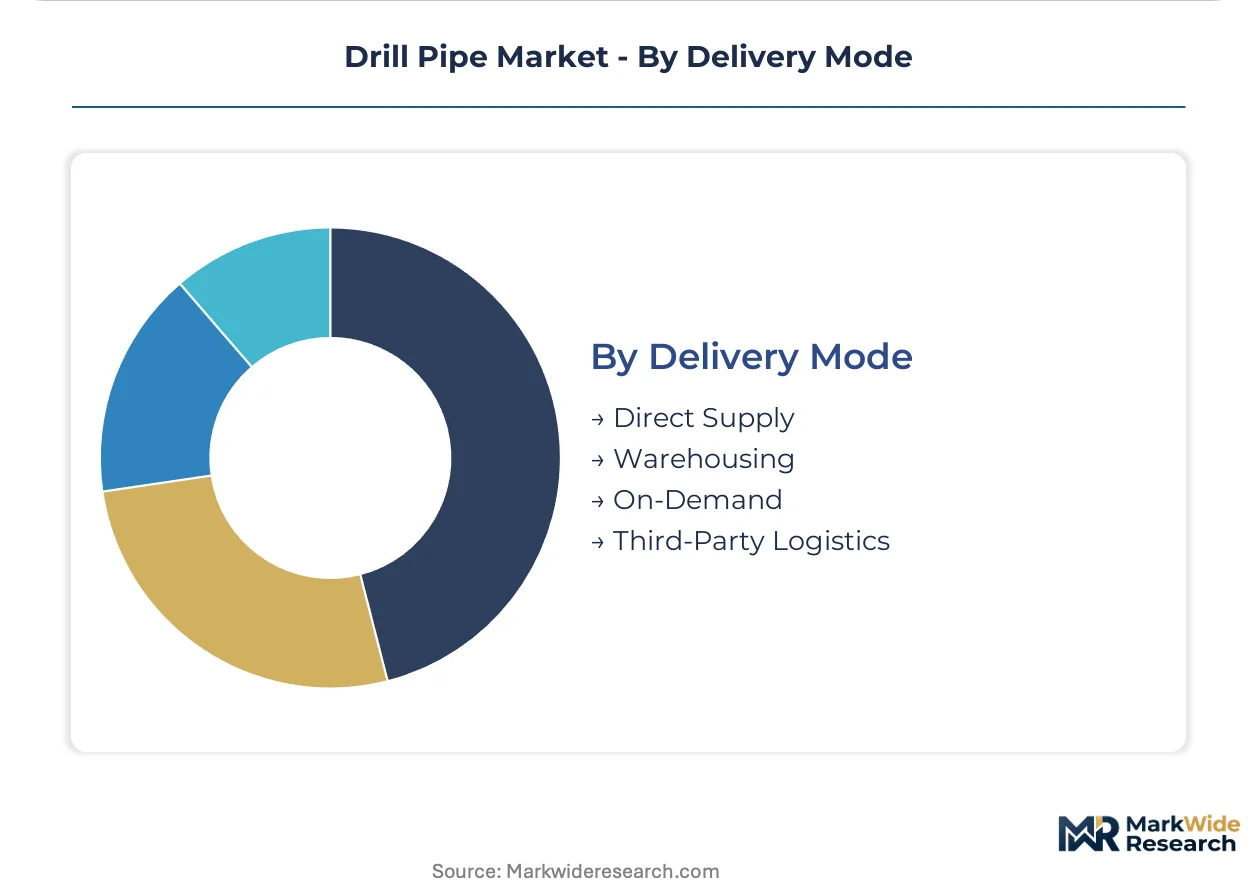
Delivery Mode:
Customer scale and supply chain integration determine channel selection, with fleet operators bypassing traditional intermediaries.
- Direct Supply:Mill-to-rig shipments eliminate handling damage and traceability gaps for super-independent drilling contractors with 50-plus rig fleets. Integrated procurement teams in the Permian Basin negotiate volume commitments directly with Veracruz and Baytown complexes.
- Warehousing:Regional stocking points buffer lead time volatility for independent operators without predictive demand planning. Third-party inspection services add cost but reduce field receipt delays.
- On-Demand:Emergency replacement strings for fatigue failures or inspection condemnations command premium pricing. Limited availability of NACE-certified inventory constrains responsiveness.
- Third-Party Logistics:Oilfield service distributors manage logistics and inspection for smaller contractors lacking in-house supply chain capabilities. Channel compression among top-20 US land drillers erodes this segment's historical role.
Direct Supply captures the majority of premium alloy movement; On-Demand is climbing the fastest as just-in-time inventory discipline tightens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Corpus Christi underwrites United States dominance in drill pipe logistics, handling seamless tubular imports from Veracruz while exporting finished strings to Permian Basin drilling contractors. Pipeline networks connecting Gulf Coast steel mills to West Texas rig yards compress delivery windows for premium alloy grades.
United States
Super-spec rig fleets in the Permian Basin consume fatigue-rated heavy weight drill pipe for laterals exceeding 15,000 feet. EPA methane emissions rules mandate corrosion-resistant alloys that extend string life in H2S-rich formations. Midland-Odessa drilling contractors negotiate direct mill commitments with Baytown and Veracruz complexes, bypassing traditional oilfield distributors.
China
Domestic shale development in Sichuan Basin drives procurement of API 5DP-certified strings for high-pressure sour gas wells. MIIT steel quality standards enforce traceability requirements that align with ISO 11960 dimensional protocols. Baoshan-based seamless pipe mills supply PetroChina drilling units operating in the Fuling shale play.
Saudi Arabia
Aramco unconventional gas campaigns in Jafurah Basin specify premium double-shoulder connections for extended-reach laterals in tight carbonate formations. SFDA industrial material certifications govern sour-service qualification for H2S-bearing reservoirs. Dammam manufacturing clusters produce tool joints for integration with imported alloy pipe bodies.
Argentina
Vaca Muerta shale operators in Neuquén Province import premium connection expertise as international entrants deploy horizontal drilling technology. The national hydrocarbons regulator enforces well integrity standards that mandate NACE MR0175-certified materials for high-pressure formations. Mendoza-based service companies coordinate logistics for mill-direct shipments from Brazilian and Mexican suppliers.
United Arab Emirates
ADNOC drilling expansion in offshore sour gas fields drives demand for chromium-molybdenum alloy formulations certified to NACE standards. MOHAP industrial safety protocols shape handling requirements for hydrogen sulfide exposure during pipe deployment. Jebel Ali free zone warehouses buffer lead times for rig operators across the Arabian Peninsula.
Drill Pipe Market Key Industry Players
Listed leaders compete with private specialists across certification tiers, with publicly traded mills leveraging capital markets to fund in-house heat-treating capacity while independent fabricators concentrate on regional repair services. The vendor base stratifies between integrated producers controlling metallurgy from ore to finished string and assembly-focused operators dependent on third-party steel supply. Three archetypes dominate: seamless pipe mills with captive tool joint forging, hardbanding specialists with automated welding capabilities, and regional reconditioners serving legacy carbon-grade inventory. Capacity expansion and backward integration into alloy supply represent the dominant competitive vectors as specification tightening disqualifies non-compliant competitors.
Within the integrated mill tier, Tenaris S.A. and Vallourec S.A. exemplify seamless pipe producers with metallurgical control spanning raw material to finished connection geometry, while NOV Inc. anchors North American supply through tool joint manufacturing and hardbanding operations. These three companies occupy positions that reflect the industry's structural division between alloy-grade premium strings and commodity carbon inventory, with each representing distinct approaches to specification compliance and supply chain configuration.
| Leading Market Players |
|---|
| NOV Inc. |
| Tenaris S.A. |
| Vallourec S.A. |
| TMK Group |
| Hilong Group |
| Oil Country Tubular Limited |
| Superior Drill Pipe Manufacturing Inc. |
| DP Master Manufacturing Pte Ltd. |
| Drill Pipe International LLC |
| Others |
Cost & Logistics Intelligence
Carbon-grade substitution for sub-12,000-foot wells simultaneously redraws procurement geography toward Permian Basin super-independents and compresses margin pools for non-integrated distributors lacking alloy-grade access. This displacement dynamic concentrates pricing power among mills with captive heat-treating capacity while stranding legacy inventory in secondary markets.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with super-spec rig operators negotiating direct mill commitments for premium alloy strings while independent contractors absorb distributor markups on standard API grades. Price differentiation hinges on NACE MR0175 certification status and in-house hardbanding capability, with sour-service premiums widening as EPA methane rules accelerate replacement cycles. Cost compression in carbon-grade segments is intensifying because scrap volatility erodes non-integrated supplier margins. Price sensitivity concentrates among independent drilling contractors with sub-20 rig fleets, while super-independents prioritize fatigue performance over unit economics.
Supply Chain Analysis
Ninety-day NACE certification lead times constrain inventory agility, forcing super-spec operators to pre-position certified strings near Permian drilling clusters. Supply concentrates in the United States, Mexico, and China, with Veracruz seamless mills and Baytown forging complexes anchoring North American premium alloy flows. Raw material dependencies draw from nickel and molybdenum ore markets, with mills lacking long-term offtake agreements exposed to input volatility. Single-source vulnerability clusters around in-house quenching capacity, as third-party heat-treating bottlenecks delay sour-service qualification. Distribution runs through direct mill-to-rig channels for fleet operators, while smaller contractors rely on regional warehousing with third-party inspection overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story, where API 5DP certification entrenchment and NACE MR0175 qualification timelines create switching costs that protect incumbent positions against commodity-grade challengers.
For Market Incumbents: Shield premium positioning by accelerating backward integration into tool joint forging and captive hardbanding automation, neutralizing the technician scarcity that constrains repair-shop competitors. Expand heat-treating capacity in Veracruz or Baytown to capture direct-commitment volume from super-independent fleets, while monitoring alloy input volatility through long-term nickel and molybdenum offtake structures. For New Entrants and Emerging Players: Lead with composite material qualification for geothermal and coiled-tubing integration, exploiting the specification white space where weight reduction targets outpace incumbent metallurgy cycles. Argentina Vaca Muerta offers the most penetrable geography, where state-backed drilling campaigns import connection expertise absent domestic sour-service infrastructure. A mill-direct distribution partnership with Neuquén logistics coordinators bypasses established channel layers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hardbanding specialists and regional reconditioners facing OSHA silica compliance cost escalation. Long-term viability favors integrated mills controlling metallurgy from ore to finished string, with inflection signaled by API specification ballot activity around electrified rig torque requirements and next-generation alloy formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tool Joint Forging | Captures margin pool and eliminates third-party forging bottlenecks for sour-service strings. |
| NACE MR0175 Certification Expansion | Entrenches competitive position as EPA rules accelerate H2S-rich formation replacement cycles. |
| Direct Mill-to-Rig Distribution | Bypasses distributor handling damage and traceability gaps for super-spec fleet operators. |
| Automated Hardbanding Capacity Buildout | Addresses certified technician scarcity constraining regional repair shop economics. |
| Composite Material Qualification Program | Opens geothermal and weight-sensitive applications where alloy fatigue limits create specification white space. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across drilling contractor procurement teams, seamless mill metallurgy directors, tool joint forging specialists, and third-party inspection service managers. Primary interview insights were cross-validated against API specification ballot records, EPA regulatory filings, customs trade data for seamless tubular imports, and SEC disclosures from listed pipe manufacturers. Bottom-up rig fleet composition analysis was triangulated with top-down alloy consumption estimates from Gulf Coast steel mill production reports.
Across the analysis window, forecasts were constructed by modeling replacement cycle dynamics against lateral extension trends, with segmentation by material grade, connection specification, and end-user application severity. CAGRs were derived from elasticity-adjusted demand projections tied to super-spec rig deployment schedules and sour-service qualification timelines. Key inputs included Permian Basin measured-depth well counts, NACE certification backlog estimates, and electrified rig torque signature specifications.
The analysis sits within stated boundaries; outcomes outside sustained unconventional shale investment, stable alloy input pricing, or unchanged API specification timelines would require recalibration. Forecasts reflect documented assumptions around regulatory enforcement intensity and fleet electrification adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Auger Drilling Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Rock Duster Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Global Smart Mining Solution Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Drilling Rigs Market
Mining Equipment
Global Dozers Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Mining Drill Market
Mining Equipment
Global Autonomous Mining Equipment Market