
 Reverse Circulation Drill Pipes Market | 2026-2036
Reverse Circulation Drill Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Circulation Drill Pipes Market Analytics
Australia is rewriting competitive dynamics in reverse circulation drill pipe supply as Perth-based fabrication hubs expand alloy-hardening capacity to serve Pilbara iron ore and Chilean copper contracts. Sandvik leverages captive metallurgy R&D in Sandviken to sustain premium alloy pipe output for deep-hole mineral programs. Atlas Copco anchors its position through integrated rig-and-pipe bundling across African and Latin American mining corridors. Epiroc competes via automation-ready pipe designs compatible with autonomous drill fleets.
Reverse circulation drill pipes are double-wall tubular structures comprising an outer pipe and inner drill rod that channel cuttings upward through an annular gap, typically manufactured from API-grade alloy steel with hardened tool joints rated for 15,000+ psi operating pressure to enable continuous sample recovery without fluid contamination. Mineral exploration commands the dominant application share as tier-one miners prioritize high-definition ore body delineation, while water well drilling represents the fastest-expanding segment amid aquifer stress in sub-Saharan Africa and the southwestern United States. Steel maintains material dominance due to fatigue resistance in abrasive formations, though composite-reinforced variants are capturing margin pools in corrosive geothermal and deep-salt environments.
API 5DP and ISO 11961 govern dimensional tolerance and Charpy impact requirements for drill pipe bodies, while EPA spill prevention rules and MSHA ground control standards shape field deployment specifications in the United States. Australia's Work Health and Safety Act and Chile's Superintendencia de Minería enforcement of DS 132 standards elevate product certification burdens for market entry. Stakeholders must monitor evolving alloy substitution economics as carbon border adjustments and Scope 3 disclosure mandates recalibrate sourcing decisions across extraction supply chains.
Market Dynamics
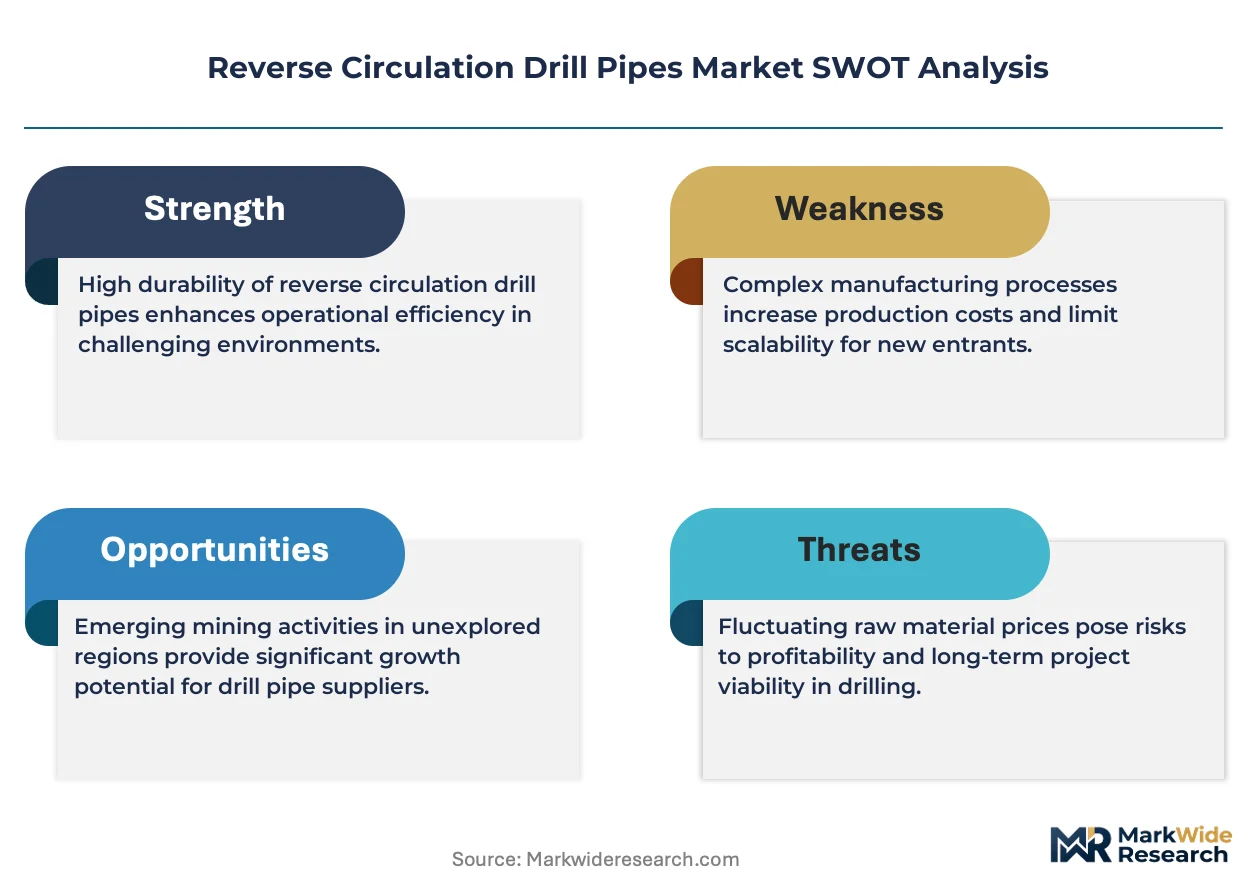
API 5DP and ISO 11961 material traceability mandates are forcing alloy-hardening investments across fabrication hubs, compressing lead times for certified pipe while elevating entry barriers for uncertified suppliers.
Growth Catalysts
- Pilbara Expansion:Western Australia's iron ore majors are extending RC drilling campaigns into deeper horizons, requiring higher-pressure-rated pipe strings.
- DS 132 Enforcement:Chile's Superintendencia de Minería is mandating enhanced tool joint certification for copper belt operations.
- Geothermal Corrosion Resistance:Composite-reinforced pipe variants are penetrating high-salinity formations where steel fatigue accelerates.
Market Restraints
- Alloy Cost Volatility:Molybdenum and chromium price swings destabilize margins for API-grade alloy steel producers.
- Perth Hub Concentration:Fabrication capacity clustering in Western Australia creates single-point vulnerability for Australasian supply.
- Charpy Impact Thresholds:ISO 11961 low-temperature toughness requirements disqualify legacy heat-treatment processes.
Strategic Opportunities
- Sub-Saharan Water Wells:Aquifer stress in Kenya and Ethiopia is opening RC drilling demand outside traditional mineral exploration.
- Autonomous Rig Integration:Drill pipe designs compatible with automated handling systems are capturing specification premiums.
- Carbon Border Adjustments:EU CBAM implementation favors low-carbon alloy sourcing from certified circular supply chains.
Industry Challenges
- Welding Inspector Scarcity:API 5DP-qualified ultrasonic testing technicians command 40% wage premiums, constraining throughput.
- Legacy Rig Retrofit Costs:Dual-wall pipe handling systems require capital outlays that marginal operators defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Circulation Drill Pipes Market |
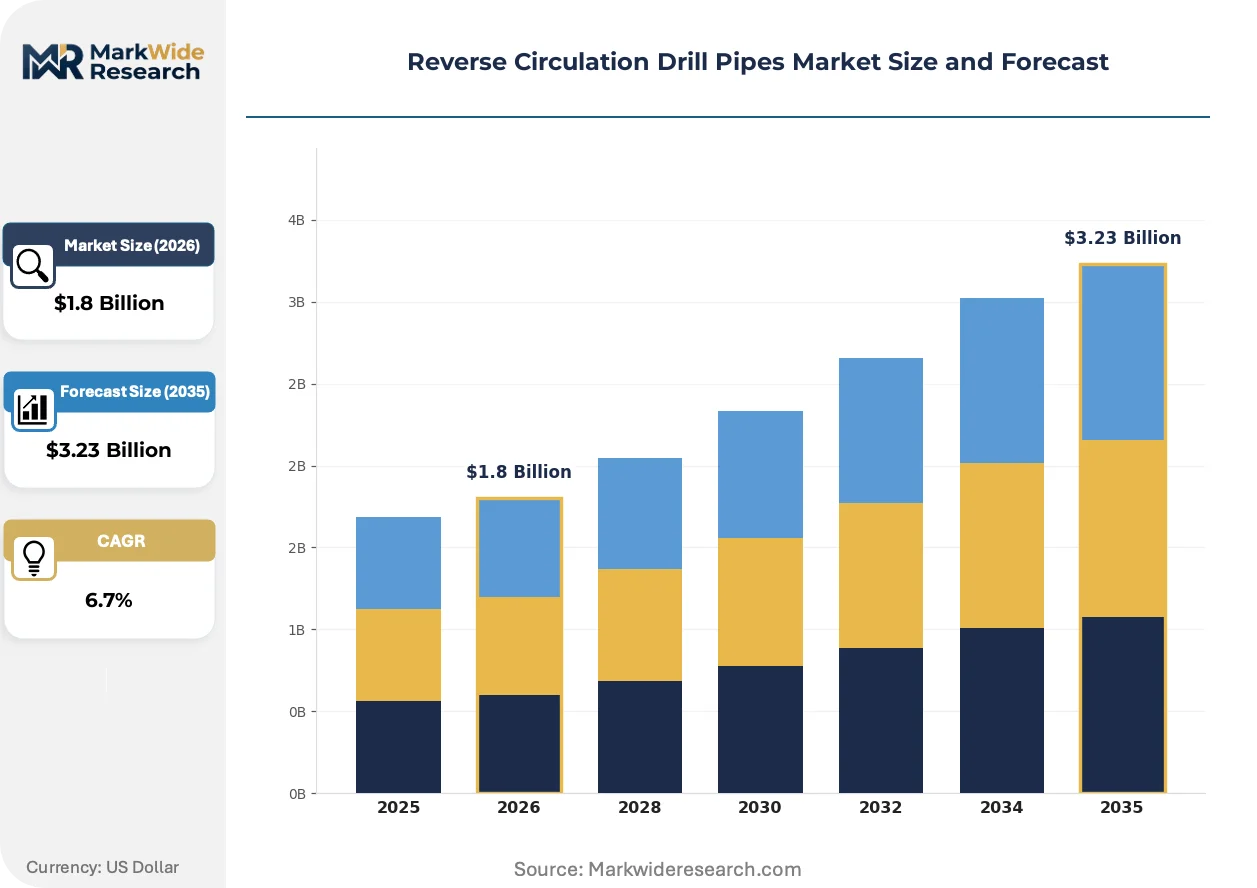
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pipes, Collars, Reducers, Accessories Material: Steel, Composite, Alloy, Carbon Fiber Application: Mineral Exploration, Water Well Drilling, Environmental Monitoring, Oil & Gas Extraction End User: Mining Companies, Drilling Contractors, Environmental Agencies, Oilfield Services |
| Companies Covered | Sandvik, Atlas Copco, Epiroc, Foremost, Technidrill, Holte Manufacturing, Tube Technologies, Matrix Drilling, Hardab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Circulation Drill Pipes Market Evolving Landscape
Active transformation centers on material substitution pathways, regulatory compliance automation, and procurement model restructuring that favors certified bundled supply over spot purchasing.
Composite-reinforced drill pipe is migrating from niche geothermal applications toward mainstream copper-gold exploration in corrosive Atacama and Pilbara environments. Tier-one miners are specifying hybrid construction for holes exceeding 800 meters depth. The shift is compressing traditional steel-only supply relationships while opening specification windows for metallurgy specialists.
REACH substance-of-very-high-concern listings are restricting certain hard-facing alloy chemistries in EU-sourced tool joints. Manufacturers are reformulating wear-resistant overlays to maintain Charpy ratings without restricted cobalt content. German and Swedish fabricators are accelerating alternative coating qualification to preserve market access.
Buyers are consolidating procurement through rig-and-pipe bundled contracts that internalize failure liability and maintenance scheduling. African and Latin American mining corridors are seeing fastest uptake of integrated service agreements. The model displaces fragmented spot purchasing and locks in multi-year alloy supply commitments.
Reverse Circulation Drill Pipes Market Segmentation
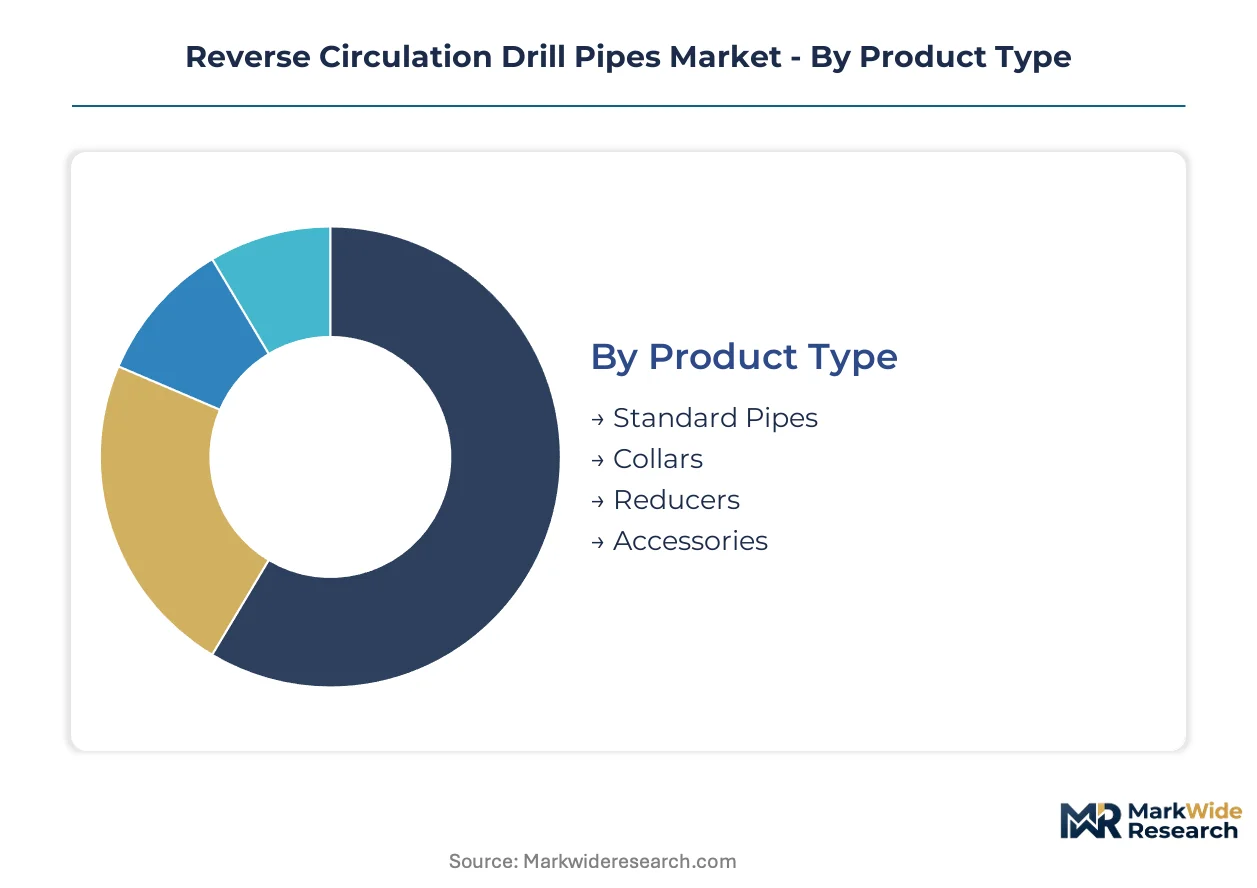
Reverse circulation drill pipe procurement varies sharply by operational intensity, with high-rotation consumables turning over in months while capital-grade strings persist for years. Segment-specific sourcing patterns determine supplier relationships, inventory financing structures, and certification renewal cycles across extraction programs.
Product Type:
Cycle times diverge dramatically within pipe systems, with consumable joints rotating fastest and structural components anchoring multi-year deployment schedules.
- Standard Pipes:Double-wall tubular sections form the operational core of RC strings, typically replaced on 18-24 month intervals in Pilbara iron ore programs due to abrasive wear at 15,000+ psi operating pressure. Australian mining majors are consolidating procurement through multi-year framework agreements that bundle pipe supply with inspection services.
- Collars:Heavy-walled connection elements distribute torsional loads and maintain annular geometry through directional changes. Chilean copper operators specify premium alloy collars for deep-hole programs exceeding 800 meters, where thread fatigue drives replacement cycles shorter than standard pipe bodies.
- Reducers:Diameter transition fittings accommodate mixed string configurations when integrating legacy pipe with new acquisitions. Kenyan water well contractors favor standardized reducer dimensions to minimize field inventory complexity across dispersed drilling sites.
- Accessories:Includes stabilizers, crossovers, and handling subs that experience accelerated wear from automated rig handling systems. Ethiopian geothermal programs specify corrosion-resistant accessory packages for high-salinity formations.
Standard pipes dominate installed base. Collars are where expansion concentrates.
Material:
Cost tiering separates commodity-grade supply from premium metallurgy, with certification premiums widening as API 5DP traceability mandates tighten.
- Steel:API-grade alloy steel maintains fatigue resistance in abrasive hard-rock formations, with Perth fabrication hubs supplying Pilbara and Chilean contracts through integrated heat-treatment lines. Carbon border adjustments are pressuring high-emission steel sourcing.
- Composite:Fiber-reinforced variants capture specification premiums in corrosive geothermal and deep-salt environments where steel corrosion accelerates. Atacama copper operators are piloting hybrid construction for holes exceeding 800 meters depth.
- Alloy:Molybdenum-enhanced grades deliver Charpy impact ratings required for ISO 11961 low-temperature certification. Molybdenum price volatility destabilizes margins for certified producers.
- Carbon Fiber:Emerging lightweight construction for automated handling compatibility in autonomous drill fleets. African mining corridors show early specification interest for reduced manual handling requirements.
Steel commands volume leadership. Composite is climbing the fastest on specification premiums.
Application:
Customer maturity varies by sector, with mineral exploration demanding highest certification rigor and water well drilling accepting broader supplier qualification.
- Mineral Exploration:Tier-one miners prioritize high-definition ore body delineation through continuous sample recovery, driving demand for pressure-rated strings with hardened tool joints. Western Australia's Pilbara region and Chile's Atacama Desert anchor global procurement volume.
- Water Well Drilling:Aquifer stress in sub-Saharan Africa and the southwestern United States is opening RC drilling demand outside traditional mineral exploration. Kenyan and Ethiopian programs favor standardized pipe dimensions to reduce field technical complexity.
- Environmental Monitoring:Contaminated site characterization requires fluid-isolated sample recovery without cross-contamination. EPA spill prevention rules shape deployment specifications in the United States.
- Oil & Gas Extraction:Geological verification drilling for unconventional reservoirs employs modified RC strings with pressure-control adaptations. Permian Basin operators specify dual-wall construction for dry gas formations.
Mineral exploration dominates installed base. Water well drilling is gaining share fastest.
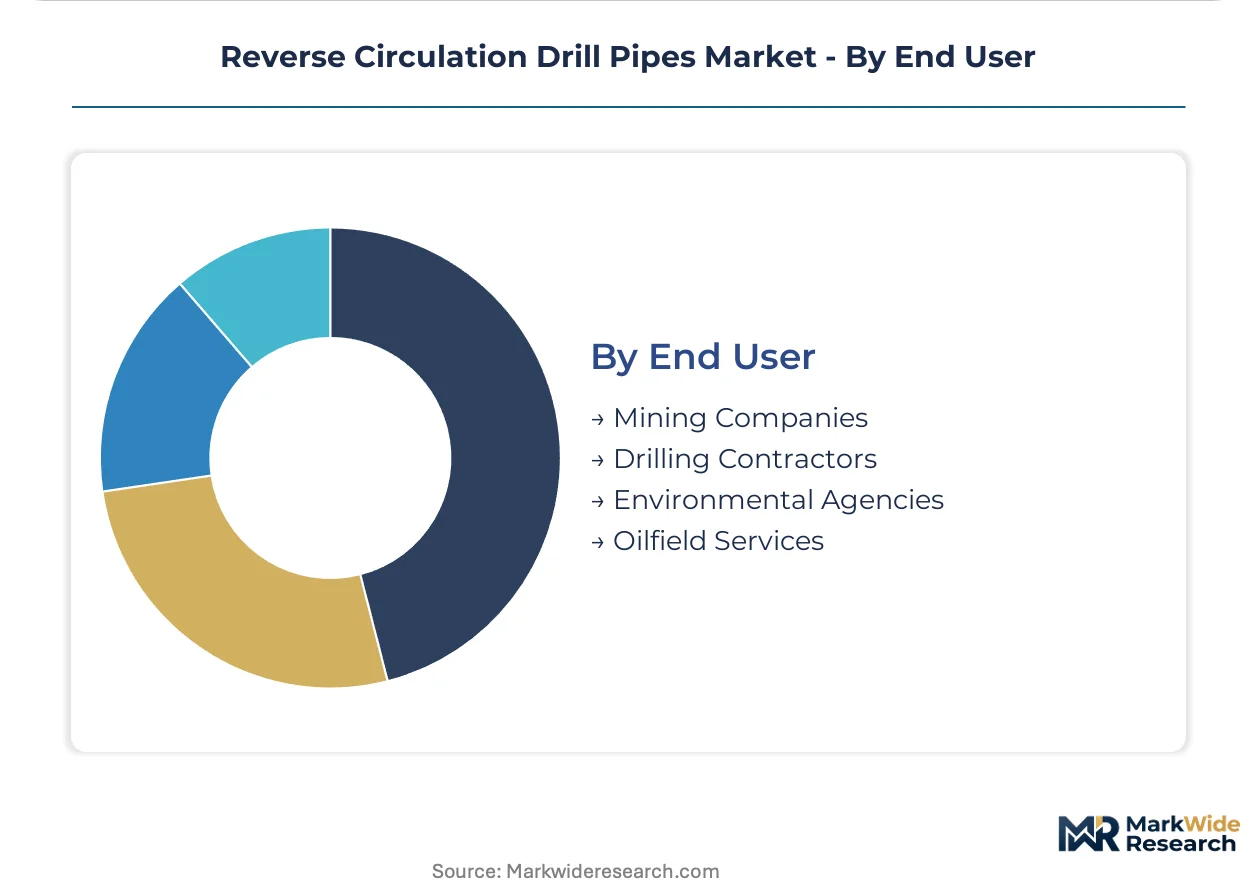
End User:
Procurement authority concentration separates integrated miners from fragmented contractor markets, with service bundling penetrating most quickly in African and Latin American corridors.
- Mining Companies:Tier-one operators internalize failure liability through rig-and-pipe bundled contracts that lock in multi-year alloy supply commitments. BHP and Rio Tinto framework agreements set pricing benchmarks for Australasian supply.
- Drilling Contractors:Asset-light operators favor rental and inspection-inclusive arrangements to minimize capital deployment. Perth hub concentration creates single-point vulnerability for contractor supply security.
- Environmental Agencies:Public-sector procurement emphasizes certified traceability and documented chain of custody for litigation-defensible sampling. US EPA enforcement actions elevate documentation requirements.
- Oilfield Services:Diversified service companies leverage existing rig fleets to cross-sell RC capabilities into geothermal and carbon storage verification markets. Schlumberger and Halliburton pilot programs target Permian Basin geological verification.
Mining companies dominate installed base. Drilling contractors are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Western Australia and Scandinavia concentrate premium alloy pipe supply, while demand disperses across mineral belts in Chile, Canada, and sub-Saharan Africa. Regulatory divergence between API jurisdictions and ISO-centric markets is fragmenting certification requirements for cross-border suppliers.
Australia
Pilbara iron ore majors are extending RC drilling campaigns into deeper horizons, requiring higher-pressure-rated pipe strings. Australia's Work Health and Safety Act elevates product certification burdens for market entry. Perth-based fabrication hubs are expanding alloy-hardening capacity to serve both domestic Pilbara contracts and Chilean copper export demand.
Chile
Atacama Desert copper belt operators are piloting composite-reinforced pipe for holes exceeding 800 meters depth. The Superintendencia de Minería is mandating enhanced tool joint certification through DS 132 enforcement. Antofagasta and Calama sub-regions anchor procurement volume for deep-hole mineral programs.
Canada
Gold and copper exploration in Ontario's Abitibi belt and British Columbia's Golden Triangle is expanding RC drilling programs. Health Canada and provincial mining regulators enforce MSHA-aligned ground control standards for field deployment. Sudbury and Vancouver serve as procurement coordination points for northern mining corridors.
United States
Permian Basin operators specify dual-wall construction for dry gas formation geological verification. EPA spill prevention rules and MSHA ground control standards shape deployment specifications. Southwestern water well drilling amid aquifer stress is opening RC demand outside traditional mineral extraction.
Kenya
Aquifer stress in the Turkana and Athi River basins is driving RC drilling demand for water well programs. The country's national water regulator emphasizes documented chain of custody for litigation-defensible drilling contracts. Nairobi-based contractors favor standardized pipe dimensions to reduce field technical complexity across dispersed sites.
Reverse Circulation Drill Pipes Market Competitive Landscape
Integrated metallurgy specialists and rig-system bundlers split the market between premium certified supply and integrated service contracts. Sandvik leverages captive R&D in Sandviken to sustain premium alloy output, while Atlas Copco anchors position through rig-and-pipe bundling across African and Latin American mining corridors. Two strategic archetypes dominate: metallurgy-integrated fabricators with in-house heat-treatment lines, and diversified mining equipment suppliers extending into consumables. Competitive moves center on capacity expansion in Perth and Santiago hubs, plus strategic partnerships for autonomous rig compatibility.
Among Sweden-based metallurgy specialists, Sandvik AB exemplifies the premium-tier fabricator archetype through its Sandviken R&D concentration. Atlas Copco AB and Epiroc AB represent the diversified equipment-bundler model, with both Stockholm-headquartered entities occupying positions across integrated rig-and-pipe service agreements. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Sandvik |
| Atlas Copco |
| Epiroc |
| Foremost |
| Technidrill |
| Holte Manufacturing |
| Tube Technologies |
| Matrix Drilling |
| Hardab |
| Others |
Value Network & Pricing Analysis
Perth fabrication hub capacity expansion is compressing lead times for API 5DP-certified pipe while elevating pricing power for metallurgy-integrated suppliers serving Pilbara iron ore and Chilean copper contracts. Alloy cost pass-through mechanics favor captive heat-treatment operators over spot-market fabricators.
Pricing Analysis
API 5DP and ISO 11961 dictate the pricing tier structure across reverse circulation drill pipe procurement, separating certified premium alloy supply from uncertified commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels hinges on Charpy impact certification, molybdenum-enhanced grade specifications, and bundled inspection services. Cost compression in standard-grade steel pipe is intensifying because carbon border adjustment exposure pressures high-emission sourcing. Drilling contractors exhibit highest price sensitivity due to asset-light rental models, while tier-one mining companies absorb certification premiums through multi-year framework agreements.
Supply Chain Analysis
Dual-use technology export controls on advanced alloy hardening equipment constrain capacity expansion outside established fabrication clusters. Supply concentrates in Australia, Sweden, and Germany for premium API-grade output, with Chinese fabricators dominating economy-tier commodity pipe. Raw material flows draw from molybdenum concentrates, chromium ferroalloys, and API-certified steel billet. Single-source vulnerability concentrates in Perth hub concentration for Australasian demand. Distribution runs through rig-and-pipe bundled contracts displacing fragmented spot purchasing across African and Latin American mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite-reinforced pipe substitution threatens steel-dominant supply relationships as Atacama and Pilbara operators pilot hybrid construction for deep-hole programs. Incumbents must navigate material transition economics while defending certified alloy positions.
For Market Incumbents: Insulate premium positioning through captive metallurgy R&D investments in Sandviken-style concentration and backward integration into alloy billet supply. Defend against composite substitution by accelerating hybrid pipe qualification for 800-meter-plus geothermal and copper-gold programs. Prioritize Perth hub capacity expansion to capture Chilean copper belt export demand. For New Entrants and Emerging Players: Pursue sub-Saharan water well drilling corridors in Kenya and Ethiopia where aquifer stress opens RC demand outside traditional mineral exploration certification barriers. Target standardized pipe dimensions and inspection-inclusive rental models to reduce field technical complexity for Nairobi-based contractors. Anchor go-to-market through national water regulator procurement frameworks emphasizing documented chain of custody. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metallurgy-integrated fabricators with in-house heat-treatment lines over equipment-bundlers facing autonomous rig compatibility transition costs. Long-term viability rests on alloy substitution defense capability and circular supply chain certification for EU carbon border adjustment exposure. Watch composite-reinforced pipe specification penetration in Atacama deep-hole programs as inflection indicator for steel demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Alloy-Hardening Capacity Expansion | Captive heat-treatment lines in Perth secure API 5DP certification throughput for Pilbara and Chilean contracts. |
| Composite Pipe Qualification | Hybrid construction pilot programs with Antofagasta operators open specification windows for corrosion-resistant alternatives. |
| Autonomous Rig Compatibility Design | Automation-ready pipe geometries capture specification premiums from Epiroc and Atlas Copco integrated fleet deployments. |
| Carbon Border Adjustment Certification | Low-carbon alloy sourcing documentation preserves EU market access as CBAM implementation tightens. |
| Water Well Drilling Market Entry | Kenyan and Ethiopian aquifer stress programs offer RC demand outside mineral exploration certification barriers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drilling contractors, mining company procurement directors, metallurgy R&D leads, and aftermarket service managers. Secondary validation drew from API 5DP certification registries, ISO 11961 compliance databases, customs trade flows for alloy steel pipe, and SEC filings from diversified mining equipment suppliers. Bottom-up segment sizing triangulated against top-down mineral exploration expenditure tracking.
Calibration against historical replacement cycle data and announced capacity expansion timelines anchored volume projections across the analysis window. Segmentation modeling captured product type, material grade, application intensity, and end-user procurement authority dimensions. CAGRs derived from weighted average of equipment fleet growth, drilling meterage forecasts, and pipe consumption rates per program. Alloy price volatility scenarios and carbon border adjustment implementation timelines fed sensitivity testing.
Macroeconomic conditions sit as an overlay; deviation in mining capex cycles, molybdenum price bands, or Chilean regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on replacement interval compression and composite substitution pace. Material shifts in DS 132 enforcement stringency or EU CBAM scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Locomotive Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Global Dozers Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Stone Crushing Equipment Market