
 Air Core Drilling Market | 2026-2036
Air Core Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Air Core Drilling Market Analysis
The EU Green Deal is repositioning European mineral exploration priorities toward domestic critical raw material sourcing, directly benefiting air core drilling contractors serving greenfield programs. Schlumberger Limited leverages its integrated drilling services portfolio to compete across multiple exploration basins simultaneously. Boart Longyear anchors its market presence through specialized reverse circulation and air core rig manufacturing alongside contract drilling operations. Atlas Copco sustains technology leadership in compressor and drill rig systems that define penetration rates and sample recovery quality.
Air core drilling employs high-velocity compressed air to transport cuttings through an inner tube, achieving penetration rates of 30-50 meters per hour in unconsolidated overburden while preserving sample integrity for geochemical analysis. The technique serves primarily as a cost-efficient precursor to diamond core programs, enabling rapid target evaluation across large tenement holdings. Reverse circulation systems dominate volume deployment in mineral exploration, where sample representativity determines resource confidence categories under JORC and NI reporting standards. Dual wall configurations command premium positioning in geotechnical investigation, where contaminated site assessments demand sealed sample pathways. Mining companies represent the most concentrated end user segment, with exploration budgets cyclically tied to commodity price trajectories and reserve replacement imperatives.
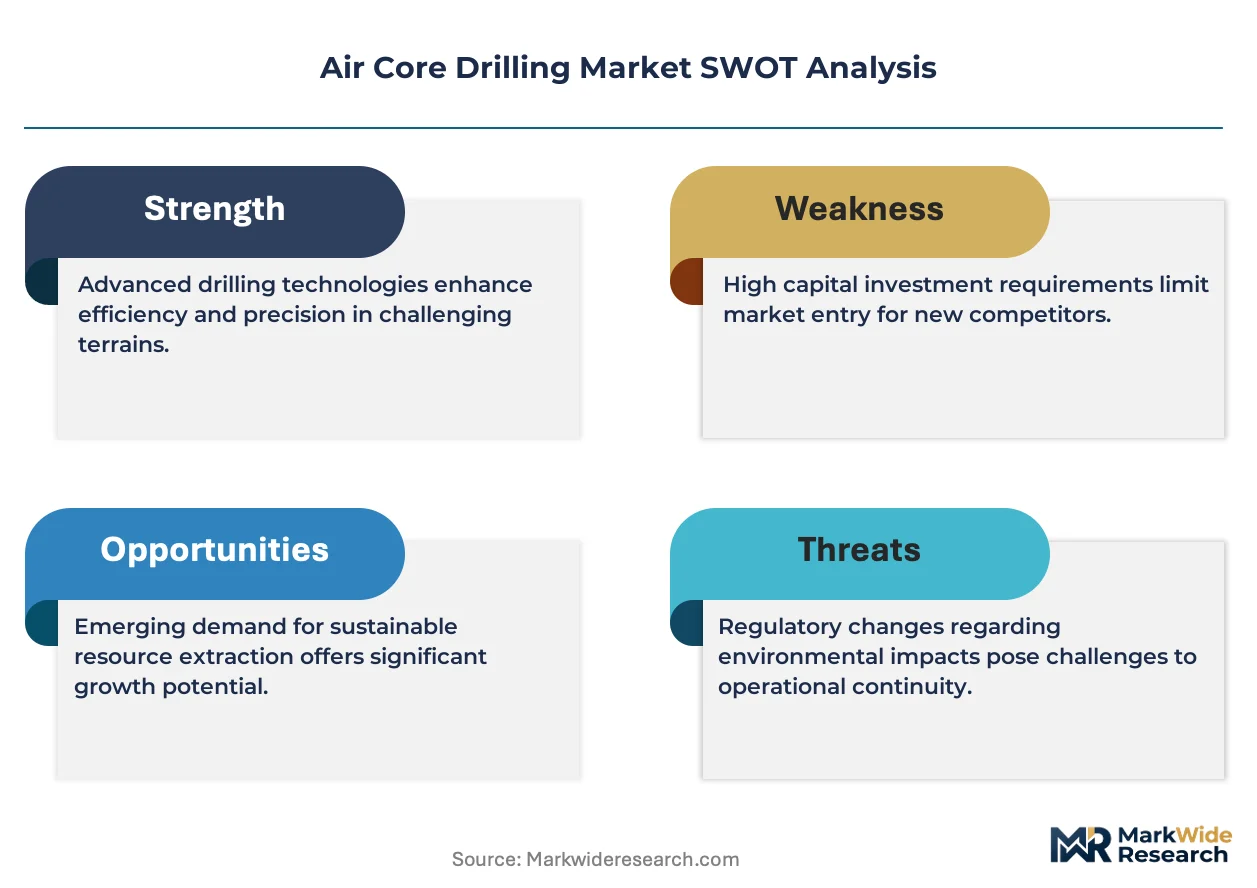
EPA guidelines in the United States govern drilling fluid management and cuttings disposal on federal lands, while Australia's state-based mineral resources regulators enforce tenement work program commitments that mandate minimum exploration expenditure. ISO 14001 environmental management certification increasingly gates contract eligibility for major mining company procurement panels. Stakeholders must monitor how critical minerals list expansions across multiple jurisdictions reshape exploration incentive structures and rig allocation patterns.
Market Dynamics
Exploration rig availability in Western Australia's Pilbara and Yilgarn cratons has tightened to a structural chokepoint, forcing junior miners into longer mobilization queues and compressing drilling program timelines for greenfield gold and base metal targets.
Growth Catalysts
- EU Green Deal critical raw materials framework:The security of supply provisions are accelerating domestic exploration permitting timelines across European member states, directly expanding contract drilling demand for domestic sourcing programs.
- Greenfield gold targets:Australian mining companies are expanding air core programs across underexplored tenements, prioritizing rapid target generation over immediate resource definition to secure land positions ahead of competitors.
- Unconsolidated overburden penetration:Air core systems achieve 30-50 meters per hour in soft cover, enabling cost-efficient pre-collaring that preserves capital for follow-up diamond core programs on prioritized anomalies.
Market Restraints
- Drill rig supply concentration:Manufacturing of specialized reverse circulation and air core rigs concentrates among a limited set of equipment fabricators, creating allocation bottlenecks during commodity upswings.
- Compressor input cost volatility:Diesel-powered mobile compressors face fuel price exposure that drilling contractors struggle to pass through on fixed-price exploration contracts.
- Technical limitation in hard rock:Air core drilling loses effectiveness in consolidated formations, forcing premature program transitions to diamond core and eroding the cost advantage that justifies initial deployment.
Strategic Opportunities
- Geotechnical investigation expansion:Dual wall air core configurations command premium positioning in contaminated site assessments, where sealed sample pathways meet EPA guidelines for environmental liability determination.
- Critical minerals list expansions:Multiple jurisdictions are broadening designated critical raw materials, reshaping exploration incentive structures and redirecting rig allocation toward battery metal and rare earth targets.
- ISO 14001 certification gates:Environmental management certification is becoming a mandatory procurement filter for major mining company drilling panels, creating differentiation value for compliant contractors.
Industry Challenges
- Driller skill scarcity:Experienced air core drillers capable of maintaining sample integrity at high penetration rates are in short supply, constraining fleet utilization rates even where rigs are available.
- Tenement work program commitments:Australian state regulators enforce minimum exploration expenditure mandates that force capital deployment regardless of commodity price troughs, stretching contractor credit terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Core Drilling Market |
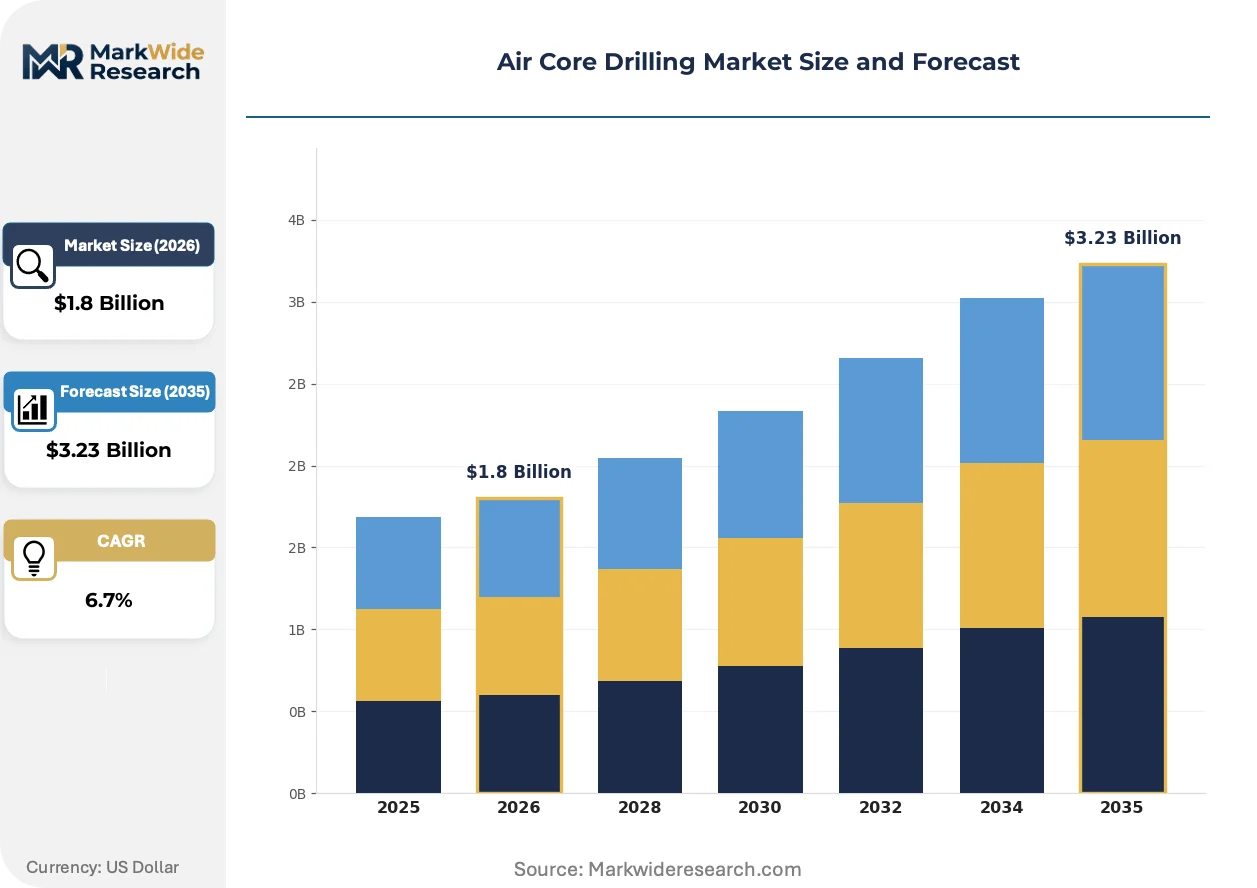
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drilling Technology: Reverse Circulation, Dual Wall, Air Core, Diamond Core Application Type: Mineral Exploration, Geotechnical Investigation, Environmental Sampling, Water Well Drilling End User: Mining Companies, Construction Firms, Environmental Agencies, Research Institutions Deployment Method: Onsite, Offshore, Remote, Urban |
| Companies Covered | Schlumberger Limited, Atlas Copco, Halliburton Company, Boart Longyear, Bostech Drilling Australia, Perenti, Geodrill, Ausdrill Limited, Ranger Drilling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Core Drilling Market Emerging Trajectories
Compressed air sample transport technology is evolving toward real-time geochemical integration, with automated cuttings analysis systems beginning to compress the feedback loop between drilling and target refinement decisions.
Downhole sensor integration with air core strings is decentralizing the traditional separation between drilling operations and immediate assay feedback. Junior exploration companies operating in remote tenements are adopting these hybrid systems fastest, enabling same-day target abandonment or follow-up commitment without waiting for laboratory turnaround. This compression of the exploration decision cycle is reshaping how drilling programs are budgeted and staged across large land holdings.
EPA guidelines governing drilling fluid management and cuttings disposal on federal lands are tightening enforcement thresholds for surface disturbance containment. The industrial consequence is accelerated investment in closed-loop mud systems and cuttings solidification technologies by contractors seeking to maintain access to federally permitted exploration acreage. Operators in the western United States are responding fastest, retrofitting existing fleets ahead of anticipated rulemaking expansion.
Exploration procurement teams are unbundling after-sales service from equipment supply contracts, treating maintenance and consumables as separately negotiable spend categories. Major mining houses are consolidating these services through multi-year framework agreements with regional drilling contractors, displacing the traditional rig-by-rig spot market. This consolidation is most visible in Western Australia, where tier-one producers have centralized drilling procurement through dedicated supply chain functions.
Air Core Drilling Market Segmentation
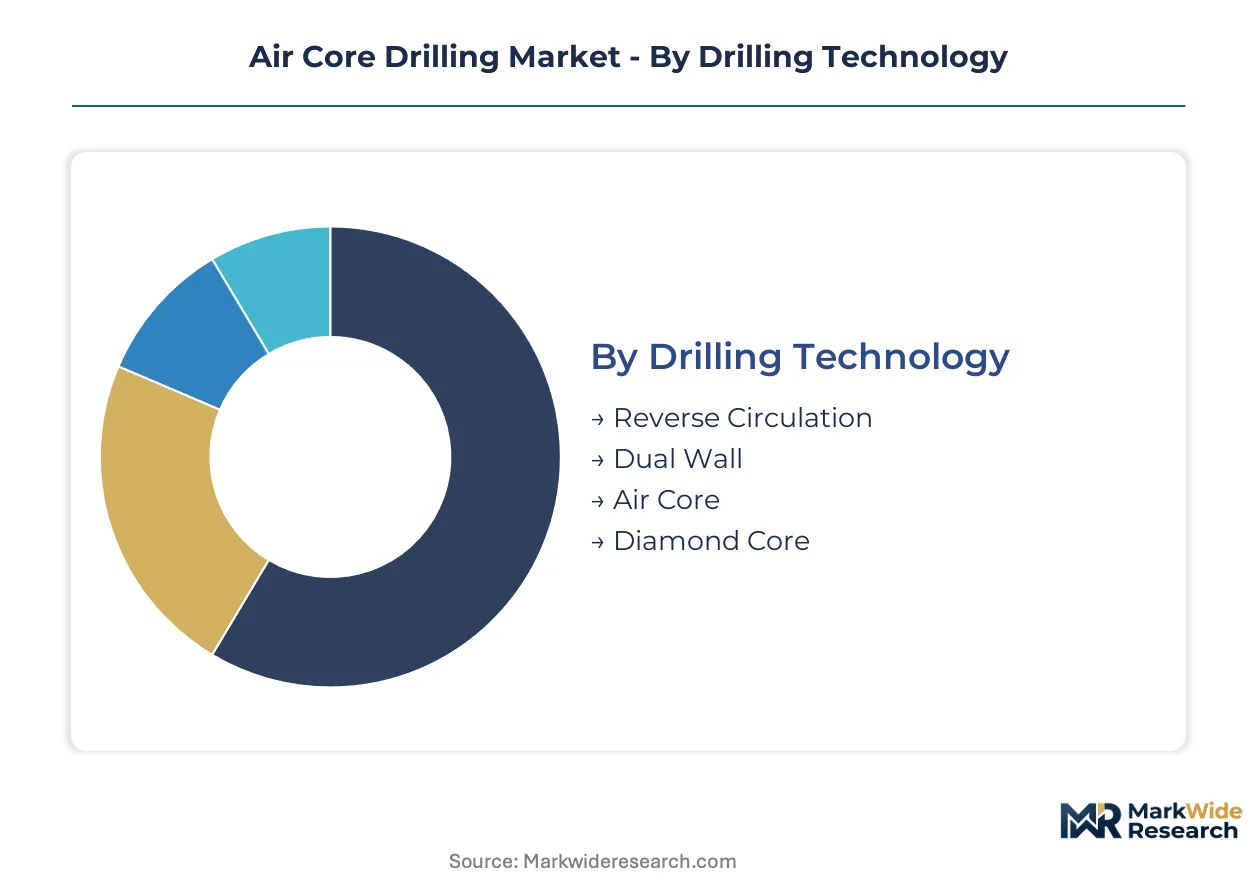
Air core drilling procurement decisions hinge on formation characteristics, sample integrity requirements, and mobilization constraints. Segment boundaries blur when contractors configure hybrid systems or when mining companies bundle multiple applications under framework agreements. Understanding how technology, application, end user, and deployment preferences intersect reveals where contract value concentrates and where fleet specialization pays.
Drilling Technology:
Formation hardness and sample representativity requirements drive technology selection, with cost per meter and program stage determining the optimal configuration.
- Reverse Circulation:Dual-wall drill strings return cuttings through an inner tube using compressed air, preserving sample integrity for JORC-compliant resource estimation. Western Australia's Pilbara and Yilgarn cratons concentrate demand, where major miners and junior explorers compete for rig availability during commodity upswings.
- Dual Wall:Sealed sample pathways enable contaminated site assessments under EPA guidelines, commanding premium day rates in geotechnical and environmental applications. Urban brownfield investigations and former industrial sites in the United States generate concentrated procurement volume.
- Air Core:High-velocity compressed air transports cuttings through a single inner tube, achieving 30-50 meters per hour in unconsolidated overburden for rapid target generation.
- Diamond Core:Impregnated diamond bits retrieve solid core samples from consolidated formations, serving as the definitive follow-up to air core pre-collaring programs.
Volume sits with Reverse Circulation; growth tilts toward Dual Wall as environmental liability assessments expand.
Application Type:
Program economics and regulatory compliance requirements reshape how drilling budgets allocate across application categories.
- Mineral Exploration:Greenfield gold and base metal targets in Western Australia drive the dominant share of air core deployment, with junior explorers prioritizing rapid tenement evaluation over immediate resource definition. The EU Green Deal's critical raw materials security framework is accelerating domestic exploration permitting timelines across European member states.
- Geotechnical Investigation:Foundation design and slope stability assessments require sealed sample pathways that Dual Wall configurations provide, particularly in urban infill developments where contaminated soil liability drives investigation depth.
- Environmental Sampling:EPA guidelines on federal lands mandate specific cuttings handling protocols, with closed-loop systems gaining procurement preference for sensitive watershed proximity.
- Water Well Drilling:Rural and agricultural groundwater development employs air core techniques for rapid casing installation in unconsolidated aquifers.
Mineral Exploration commands the rig fleet; Environmental Sampling is climbing the fastest as enforcement thresholds tighten.
End User:
Procurement sophistication and contract structure preferences diverge sharply across buyer categories.
- Mining Companies:Tier-one producers centralize drilling procurement through dedicated supply chain functions, displacing spot-market rig allocation with multi-year framework agreements. Exploration budgets cycle with commodity price trajectories and reserve replacement imperatives.
- Construction Firms:Infrastructure project timelines drive demand for rapid mobilization and fixed-price contracts, with geotechnical investigation bundled into broader engineering procurement.
- Environmental Agencies:Federal and state entities enforce compliance-driven investigation mandates with stringent ISO 14001 certification requirements for contractor eligibility.
- Research Institutions:Academic and government geological surveys operate on constrained budgets with extended mobilization tolerances for remote scientific drilling programs.
Mining Companies anchor contract value; Environmental Agencies are gaining share fastest as regulatory enforcement expands.
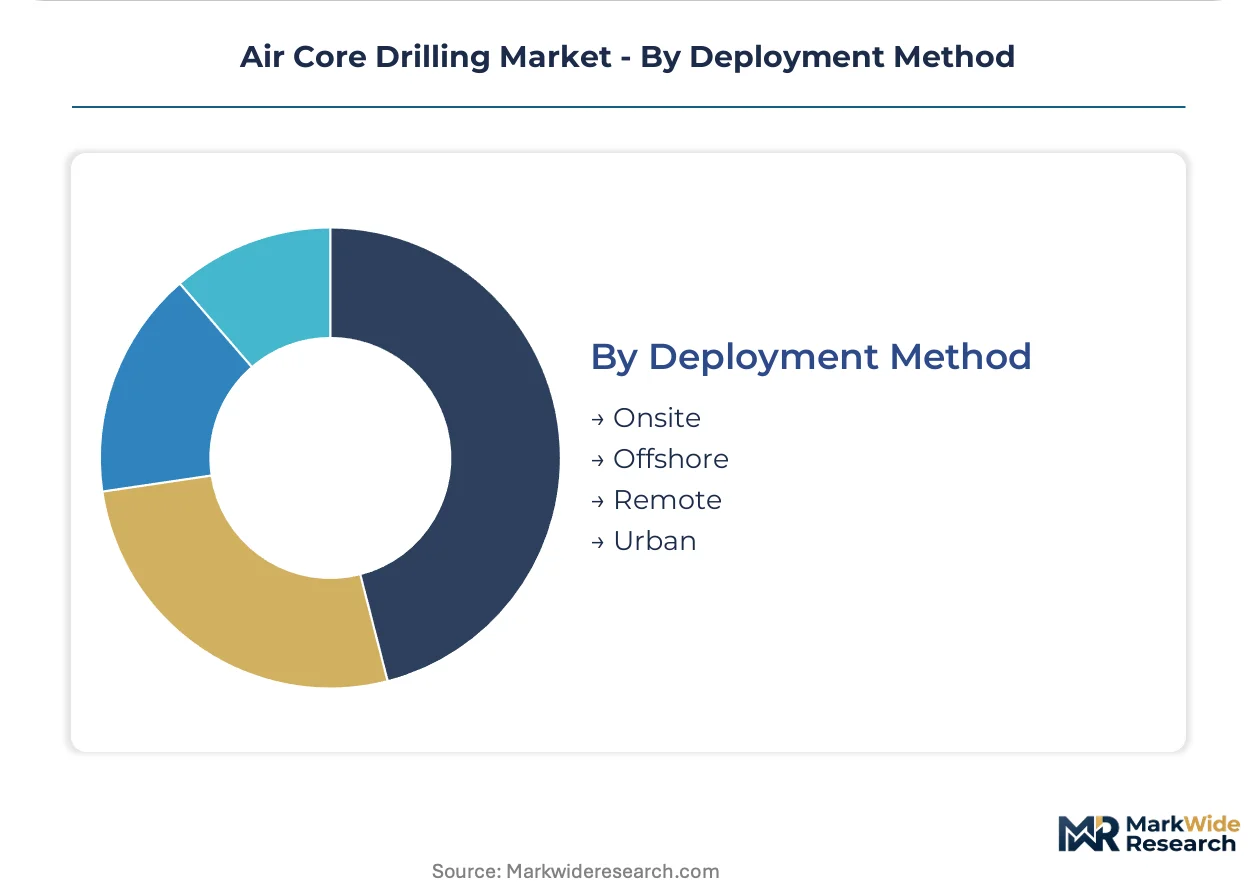
Deployment Method:
Logistics complexity and infrastructure availability determine mobilization economics and fleet configuration requirements.
- Onsite:Established mine sites and processing facilities enable rapid rig repositioning between drill pads, minimizing non-productive time and supporting continuous shift operations.
- Remote:Helicopter-portable rigs and self-contained support systems serve underexplored tenements lacking road access, particularly in the Canadian Shield and Scandinavian Arctic.
- Offshore:Jack-up platforms and drill ships accommodate island or coastal mineral targets, with specialized marine air core systems commanding substantial day rate premiums.
- Urban:Noise restrictions, traffic management, and contaminated site protocols constrain equipment selection and operating hours in metropolitan investigation programs.
Onsite deployment dominates utilization; Remote access programs are expanding most quickly as greenfield frontiers attract exploration capital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Perth anchors the world's densest concentration of air core drilling activity, with the Pilbara and Yilgarn cratons hosting the dominant share of exploration rig deployment. Western Australia's junior explorers and major miners compete fiercely for contractor availability, creating mobilization queues that stretch program timelines.
Australia
Western Australia's Pilbara and Yilgarn cratons concentrate greenfield gold and base metal exploration, with state-based mineral resources regulators enforcing tenement work program commitments that mandate minimum exploration expenditure. TGA environmental guidelines intersect with state mining codes to govern drilling fluid management. Perth-based contractors coordinate fleet movements across remote tenements lacking road infrastructure.
United States
Nevada's Carlin Trend and Arizona's copper porphyry belts drive air core deployment for rapid overburden penetration ahead of diamond core programs. EPA guidelines on federal lands govern drilling fluid management and cuttings disposal, with enforcement thresholds tightening for surface disturbance containment. Contractors in the western states retrofit fleets with closed-loop mud systems ahead of anticipated rulemaking expansion.
Canada
The Canadian Shield's underexplored greenstone belts attract helicopter-portable rig programs targeting lithium and rare earth elements. Health Canada and provincial mining regulators coordinate environmental assessment requirements for remote exploration. Ontario's Abitibi greenstone belt and Quebec's James Bay region concentrate junior explorer activity.
Sweden
Scandinavia's battery metal frontier is accelerating under the EU Green Deal's critical raw materials security framework, with domestic exploration permitting timelines compressing across member states. ECHA REACH compliance governs drilling chemical use in sensitive watersheds. Sweden's Bergslagen mining district and Finland's Central Lapland greenstone belt attract rig allocation from European contractors.
Chile
The Atacama Desert's lithium triangle and northern copper porphyry belts deploy air core systems for rapid salar basement and overburden evaluation. ANVISA environmental regulations intersect with mining ministry permitting for water-stressed regions. Antofagasta and Calama serve as logistics hubs for remote salar drilling programs.
Air Core Drilling Market Vendor Landscape
The competitive structure tilts toward integrated drilling services conglomerates competing against specialized regional contractors. Tier-one producers centralize procurement through multi-year framework agreements, displacing spot-market rig allocation. Two strategic archetypes dominate: diversified energy services conglomerates with cross-basin capabilities, and pure-play exploration drilling specialists with fleet concentration in mineral belts. Competitive moves concentrate on vertical integration into rig manufacturing and compressor technology, alongside geographic expansion through regional contractor acquisitions.
Within the diversified energy services tier, Schlumberger Limited and Halliburton Company occupy positions spanning multiple exploration basins simultaneously. Atlas Copco anchors equipment supply through compressor and drill rig system manufacturing. Boart Longyear sits within the specialized drilling contractor archetype, combining rig manufacturing with contract drilling operations. Among Australia-based contractors, Perenti and Ausdrill Limited exemplify regional fleet operators with concentrated presence in Western Australia's Pilbara and Yilgarn cratons.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Atlas Copco |
| Halliburton Company |
| Boart Longyear |
| Bostech Drilling Australia |
| Perenti |
| Geodrill |
| Ausdrill Limited |
| Ranger Drilling |
| Others |
Supply Flow & Price Mechanics
Mining company procurement consolidation into multi-year framework agreements is compressing spot-market premiums and forcing drilling contractors toward cost-plus contracting with fuel price pass-through clauses. This buyer-driven restructuring redistributes margin risk upstream to rig manufacturers and compressor suppliers while rewarding fleet scale and geographic concentration.
Pricing Analysis
Value-based pricing anchored to meters drilled and sample recovery rates dominates contract structures across Western Australia's Pilbara and Yilgarn cratons. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified contractors from uncertified regional operators and spot-market independents. Pricing pressure stems from diesel cost volatility that fixed-price exploration contracts struggle to absorb. Junior explorers exhibit highest price sensitivity, while tier-one producers prioritize uptime guarantees over day rate differentials.
Supply Chain Analysis
Direct-to-mine-site channels handle hyperscale drilling demand from BHP and Rio Tinto, bypassing distributor markups for rig allocation and consumables. Manufacturing concentrates in Sweden, Australia, and the United States for specialized reverse circulation and air core rigs. Component sourcing draws from China for steel drill strings, Germany for high-pressure compressors, and Japan for downhole sensors. Single-source vulnerability concentrates in hydraulic system suppliers serving the mobile rig fleet. Distribution runs through Perth-based logistics hubs coordinating helicopter-portable equipment to remote tenements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as contractors pursue captive manufacturing of drill rigs and compressor systems to defend margins against equipment fabricator pricing power.
For Market Incumbents: Cement fleet utilization rates through multi-year framework agreements with tier-one miners, locking out spot-market competitors during commodity upswings. Secure backward integration into compressor technology to offset diesel fuel cost volatility exposure. Prioritize ISO 14001 certification investment to maintain procurement panel eligibility as environmental compliance gates tighten. For New Entrants and Emerging Players: Environmental agencies enforcing EPA guidelines on federal lands represent the most penetrable buyer archetype, with compliance-driven investigation mandates outpacing established contractor capacity. Target contaminated site assessment programs in the western United States where dual wall air core configurations command premium positioning. Lead with closed-loop mud system capabilities as the go-to-market differentiator against legacy fleet operators. For Investors and Strategic Acquirers: The window for entry favors specialized regional contractors with concentrated presence in Western Australia's Pilbara and Yilgarn cratons, where rig availability bottlenecks sustain pricing power. Acquisition candidates should demonstrate helicopter-portable fleet capabilities and established relationships with junior exploration companies. Monitor critical minerals list expansions across multiple jurisdictions as the signal for redirected exploration capital and rig allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Rig Manufacturing Integration | Captive supply of reverse circulation systems insulates Boart Longyear from equipment allocation bottlenecks during commodity upswings. |
| ISO 14001 Certification Program | Environmental management certification gates contract eligibility for BHP and Rio Tinto procurement panels. |
| Helicopter-Portable Fleet Expansion | Remote access capabilities unlock greenfield tenements in the Canadian Shield and Scandinavian Arctic. |
| Real-Time Geochemical Integration | Downhole sensor deployment compresses exploration decision cycles for junior miners operating on constrained budgets. |
| Multi-Year Framework Agreements | Centralized drilling procurement through dedicated supply chain functions displaces spot-market rig allocation. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with drilling contractors, mining company exploration managers, and mineral resources regulators. Drilling fleet operators, compressor manufacturers, and geotechnical engineering consultants provided operational validation. Australian Bureau of Statistics trade data, EPA enforcement databases, and EU Green Deal implementation documents supplied quantitative foundations. Bottom-up rig count modeling triangulated against top-down exploration expenditure estimates.
Segmentation-level granularity modeled drilling technology, application type, end user category, and deployment method across the projection horizon. Formation hardness and sample integrity requirements shaped technology substitution dynamics. CAGRs derived from historical rig utilization rates and exploration budget cyclicality patterns. Critical minerals security frameworks and tenement work program commitments served as policy-driven demand inputs.
Revisions become necessary when critical minerals list expansions accelerate beyond modeled permitting timelines or when diesel price volatility exceeds historical bands. Forecasts reflect assumptions about commodity price trajectories and reserve replacement imperatives sustaining exploration budgets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Impact Crusher Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
Africa Mining Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Automation in Mining Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Surface Mining Machinery Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
Mining Drill Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market