
 Industrial Lift Ladder Market | 2026-2036
Industrial Lift Ladder Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lift Ladder Market Foresight
Buyer fragmentation across e-commerce fulfillment networks is repositioning volume toward smaller, fleet-scale orders rather than bulk construction procurement. Zhejiang Dingli Machinery leverages aluminum alloy R&D to anchor its position in lightweight industrial access equipment. Sinoboom Heavy Industry sustains manufacturing scale advantages across Asian distribution channels. Louisville Ladder competes on brand recognition and channel control through established retail and contractor supply relationships.
An industrial lift ladder is a mobile or fixed elevating access device constructed from aluminum, fiberglass, or steel, incorporating rung spacing of 12 inches and load ratings between 250 and 375 pounds to enable personnel elevation in maintenance and material handling tasks. Platform ladders integrate guardrail systems and tool trays for extended-duration work, while telescopic ladders address space-constrained warehousing environments through collapsible stow profiles. Fiberglass configurations command margin premiums in electrical utility applications due to dielectric insulation properties, whereas aluminum dominates construction and general maintenance segments on weight and cost efficiency.
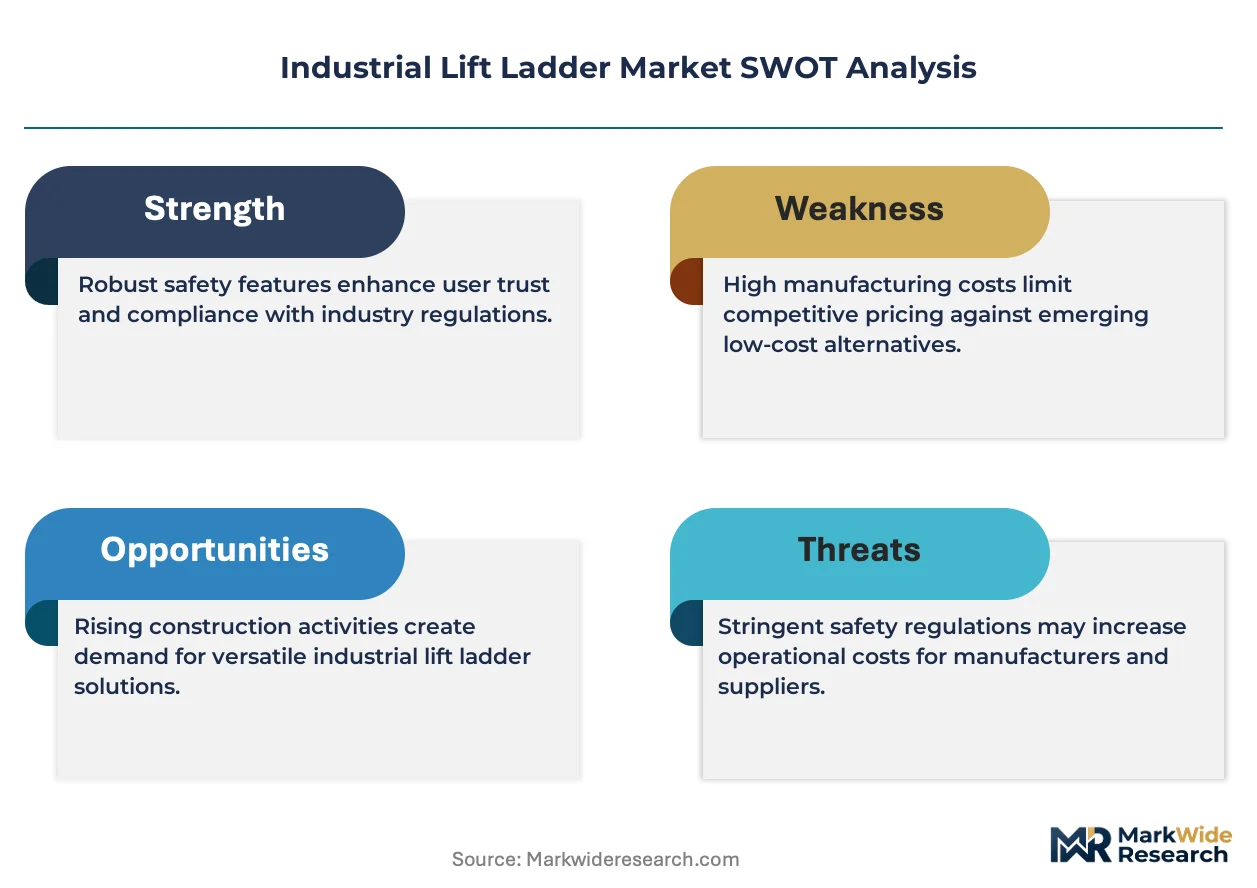
OSHA standards under 29 CFR 1910.27 and 1926.1053 govern rung design, load testing, and inspection intervals for workplace deployment in the United States, while the EU Machinery Directive 2006/42/EC mandates CE conformity assessment and traceability documentation for European market access. The EPA oversees coating and finishing emissions from manufacturing facilities, adding compliance cost layers to domestic production. Stakeholders must monitor evolving state-level warehouse safety legislation and third-party certification requirements to align product portfolios with fragmented regulatory timelines.
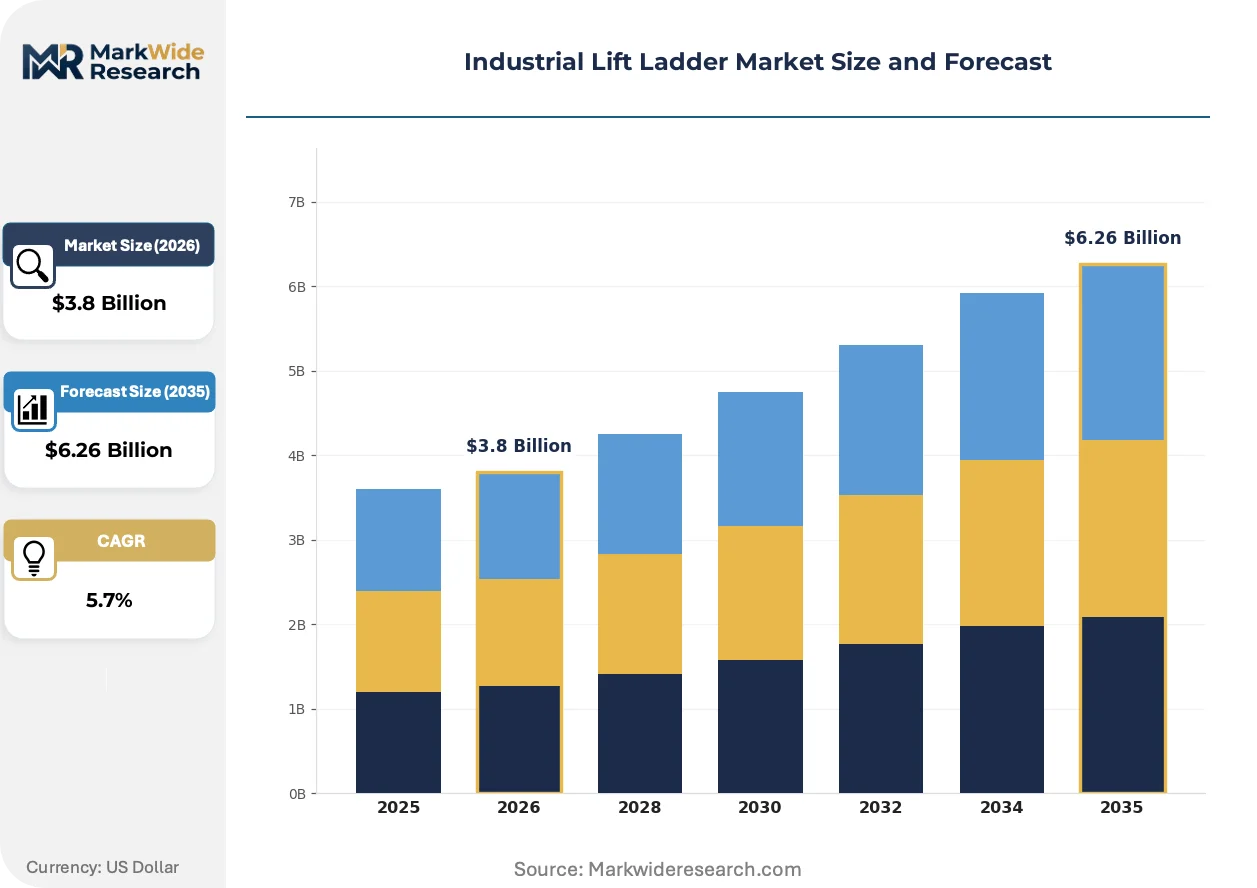
Market Dynamics
Warehouse automation investments by third-party logistics providers are compressing replacement cycles and fragmenting order sizes across industrial lift ladder procurement networks.
Growth Catalysts
- OSHA fall-protection mandates:Updated 29 CFR standards in the United States are forcing facility upgrades across distribution centers and manufacturing plants, accelerating replacement demand for certified platform configurations.
- EU Machinery Directive alignment:CE marking requirements under Directive 2006/42/EC are raising certification thresholds for European market access, filtering out non-compliant suppliers and concentrating volume among certified manufacturers.
- German industrial corridor density:Manufacturing maintenance cycles in Baden-Württemberg and Bavaria are driving sustained replacement volume for telescopic ladder configurations in automotive and machinery sectors.
Market Restraints
- Aluminum alloy price volatility:Raw material cost swings for 6061-T6 and 6063-T5 aluminum grades compress margin predictability for lightweight ladder producers.
- Fiberglass supply concentration:Dielectric-grade fiberglass reinforcement production clusters in China create import dependency for electrical utility-grade ladder manufacturers in North America and Europe.
- Steel weight disadvantage:Structural steel ladders face displacement pressure in mobile applications where aluminum and fiberglass alternatives deliver superior transport efficiency.
Strategic Opportunities
- Indian warehouse infrastructure buildout:Cold chain and e-commerce fulfillment investments under the PLI scheme are creating first-time demand for fleet-scale industrial access equipment.
- Carbon fiber hybrid platforms:Convergence of aerospace-grade composite manufacturing with industrial access equipment is enabling ultra-lightweight configurations for aviation maintenance applications.
- Rental channel expansion:Equipment-as-a-service models through national rental networks are displacing direct purchase patterns among mid-sized contractors.
Industry Challenges
- Certification timeline compression:CE conformity assessment and third-party testing bottlenecks are extending product launch cycles by four to six months for multi-market introductions.
- Integration complexity with automated storage systems:Lift ladder fleets must coordinate with robotic vertical lift modules and automated guided vehicles in modernized warehouses, requiring protocol standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lift Ladder Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platform Ladders, Extension Ladders, Step Ladders, Telescopic Ladders Material: Aluminum, Fiberglass, Steel, Plastic End User: Manufacturing, Construction, Warehousing, Maintenance Safety Feature: Non-slip Rungs, Stabilizing Bars, Locking Mechanisms, Pintle Hooks |
| Companies Covered | Safety Hoist Company, GEDA-USA, Wildeck, Ziamatic Corporation, E.S. Industries, Sinoboom Heavy Industry, Zhejiang Dingli Machinery, BIL-JAX, Louisville Ladder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lift Ladder Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are compressing product development timelines while expanding performance differentiation across industrial access equipment categories.
Carbon fiber-reinforced polymer (CFRP) hybrid construction is expanding into platform ladder architectures for weight-critical applications. Aviation maintenance operations at Frankfurt Airport and Dallas-Fort Worth International are piloting CFRP platforms that reduce single-operator transport weight below 35 pounds. This material transition is expanding into premium segments previously dominated by aluminum, compressing the performance gap between mobile and fixed access solutions.
REACH regulation amendments governing chemical substance registration are tightening traceability requirements for coating systems used in ladder manufacturing. Industrial finish suppliers must now document SVHC content across supply tiers, adding documentation layers to European market entry. German and French industrial buyers are prioritizing suppliers with pre-certified coating chains, concentrating procurement among vertically integrated manufacturers.
Fleet telemetry integration is reshaping procurement criteria for multi-site logistics operators. Amazon and DHL supply chain divisions are specifying ladder assets with RFID tagging and usage-tracking compatibility for centralized maintenance scheduling. This specification pattern is most visible in the United States, where OSHA record-keeping requirements intersect with corporate risk management systems to create demand for connected access equipment.
Industrial Lift Ladder Market Segmentation
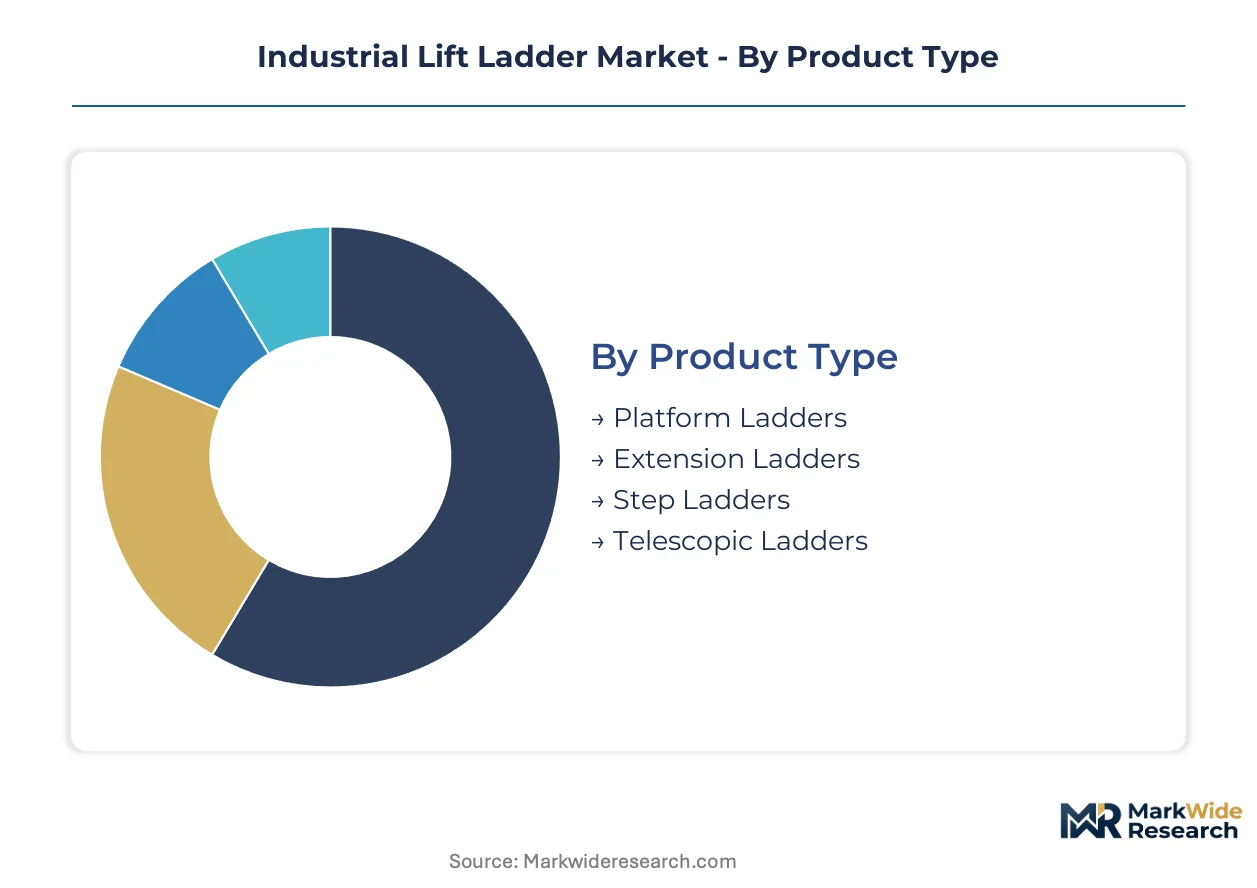
Industrial lift ladder procurement patterns fragment sharply across material specifications and end-use environments, with certification requirements and duty-cycle intensity driving divergent product selection criteria.
Product Type:
Platform configurations dominate fleet-scale deployments through integrated guardrail systems and extended-duration work positioning.
- Platform Ladders:Enclosed guardrail systems and tool tray integration support multi-hour maintenance tasks. German automotive plants in Stuttgart and Wolfsburg specify these for assembly line access, with OSHA 29 CFR compliance mandating rail heights above 42 inches for fall protection.
- Telescopic Ladders:Collapsible stow profiles address space-constrained warehousing environments. E-commerce fulfillment centers in the United States and India deploy these for vertical lift module adjacency, where floor space premiums exceed $200 per square meter annually.
- Extension Ladders:Multi-section reach extension for exterior maintenance applications.
- Step Ladders:Self-supporting A-frame designs for interior facility tasks.
Platform ladders lead on scale; telescopic ladders lead on momentum.
Material:
Weight-to-strength ratios and dielectric properties determine material selection across electrical versus general industrial applications.
- Aluminum:6061-T6 and 6063-T5 alloys deliver weight efficiency below 15 pounds for single-operator transport. Construction contractors in Texas and Florida favor aluminum for daily mobility, though LME price volatility compresses margin predictability for fabricators.
- Fiberglass:Dielectric-grade reinforcement commands premium positioning in electrical utility maintenance. Lineworkers at Pacific Gas and Electric and Consolidated Edison specify fiberglass for live-line work, with dielectric testing to 100kV creating certification barriers for non-specialized suppliers.
- Steel:Structural durability for fixed installations where weight is secondary.
- Plastic:Polymer composites for lightweight residential and light-commercial applications.
Aluminum dominates volume; fiberglass captures margin concentration.
End User:
Duty-cycle intensity and regulatory exposure differentiate procurement specifications across facility types.
- Warehousing:Fleet-scale procurement for e-commerce and third-party logistics operators. Amazon and DHL supply chain divisions specify RFID-tagged assets for centralized maintenance scheduling, with replacement cycles compressing to 18 months in high-velocity facilities.
- Manufacturing:Automotive and machinery sectors in Baden-Württemberg drive replacement volume through scheduled maintenance cycles. BMW and Bosch facilities specify platform configurations with load ratings above 375 pounds for tooling access.
- Construction:Project-based procurement with mobility prioritization.
- Maintenance:Facility management contracts with standardized inspection protocols.
Warehousing expands most quickly; manufacturing anchors replacement volume.
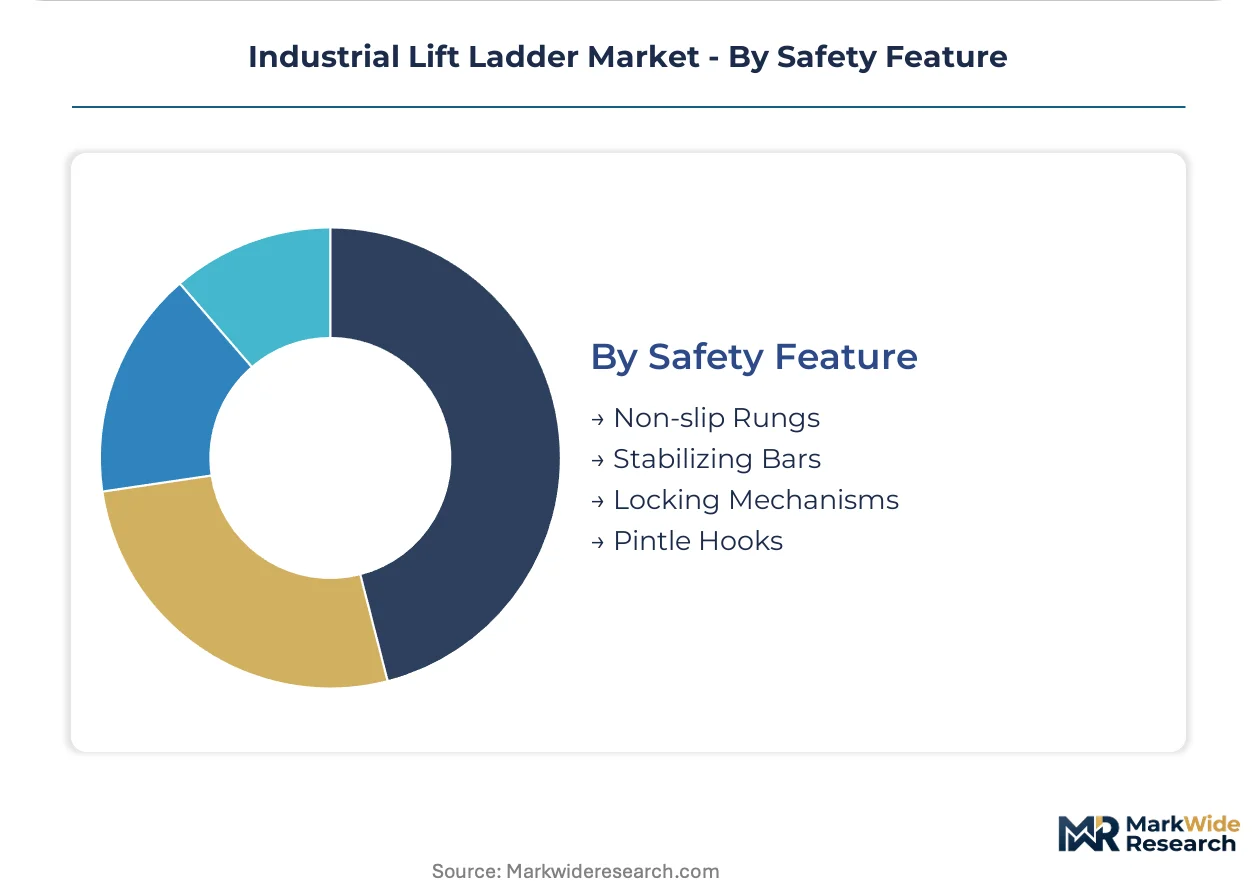
Safety Feature:
Fall-protection mandates and liability exposure are elevating specification minimums across institutional buyers.
- Locking Mechanisms:Automatic engagement systems prevent collapse during load bearing. ANSI A14 standards mandate positive-lock verification for extension and telescopic configurations, with third-party testing to 4x rated load creating compliance cost layers.
- Stabilizing Bars:Outrigger systems extend base width for uneven surface deployment. Utility contractors specify these for transmission tower access in rural terrain, where ground conditions vary across job sites.
- Non-slip Rungs:Serrated or coated surfaces for wet environment traction.
- Pintle Hooks:Vehicle mounting systems for mobile service fleets.
Locking mechanisms lead on regulatory mandate density; stabilizing bars lead on application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates replacement volume for platform configurations while India generates first-time fleet demand through warehouse infrastructure buildout. The United States anchors certification-driven procurement through OSHA mandates. China supplies dielectric-grade fiberglass reinforcement for electrical utility applications across multiple continents.
United States
OSHA 29 CFR fall-protection standards mandate rail heights above 42 inches for platform ladder deployment in distribution centers. The EPA oversees coating emissions from manufacturing facilities in Ohio and Pennsylvania. Amazon and DHL supply chain divisions specify RFID-tagged assets for centralized maintenance scheduling in high-velocity fulfillment facilities.
Germany
Automotive maintenance cycles in Baden-Württemberg and Bavaria drive sustained replacement volume for telescopic configurations. CE marking requirements under EU Machinery Directive 2006/42/EC filter non-compliant suppliers from European market access. BMW and Bosch facilities in Stuttgart and Wolfsburg specify platform ladders with load ratings above 375 pounds for assembly line tooling access.
China
Dielectric-grade fiberglass reinforcement production clusters create supply concentration for electrical utility-grade ladder manufacturers globally. MIIT oversees industrial equipment standards alignment with export market requirements. Zhejiang and Jiangsu provinces anchor aluminum alloy R&D for lightweight industrial access equipment serving Asian distribution channels.
India
Cold chain and e-commerce fulfillment investments under the PLI scheme generate first-time demand for fleet-scale industrial access equipment. BIS certification requirements govern product safety standards for domestic market entry. Maharashtra and Karnataka warehouse corridors specify telescopic ladder configurations for vertical lift module adjacency in space-constrained facilities.
Industrial Lift Ladder Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material-grade and certification-tier segments. The vendor base separates into three strategic archetypes: aluminum alloy specialists leveraging lightweight R&D, fiberglass dielectric-grade producers serving electrical utilities, and scale-driven fabricators optimizing Asian distribution density. M&A activity concentrates among mid-cap specialists seeking CE certification capabilities, while capacity expansion targets Indian warehouse infrastructure buildout.
Within the scale-driven tier, Sinoboom Heavy Industry and Zhejiang Dingli Machinery exemplify manufacturing concentration advantages across Asian channels. Louisville Ladder occupies a position representing brand-recognition and channel-control archetypes through established retail and contractor supply relationships. These three anchors illustrate how competitive positioning fragments across material specialization, geographic manufacturing scale, and distribution network density rather than converging on unified market leadership.
| Leading Market Players |
|---|
| Safety Hoist Company |
| GEDA-USA |
| Wildeck |
| Ziamatic Corporation |
| E.S. Industries |
| Sinoboom Heavy Industry |
| Zhejiang Dingli Machinery |
| BIL-JAX |
| Louisville Ladder |
| Others |
Supply & Pricing Matrix
Aluminum alloy 6061-T6 and 6063-T5 feedstock costs cascade through three-tier pricing structures across premium, standard, and economy levels, with LME volatility compressing margins for lightweight ladder fabricators while dielectric-grade fiberglass reinforcement secures premium positioning for electrical utility suppliers.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for aluminum-configured industrial access equipment. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE certification status and load rating tier, with OSHA-compliant platform configurations commanding sustained premiums. Cost compression in standard-grade telescopic ladders intensifies because of raw material pass-through pressure. Fleet-scale warehousing buyers exhibit highest price sensitivity; electrical utility procurement teams prioritize dielectric certification over unit cost.
Supply Chain Analysis
Dielectric-grade fiberglass reinforcement supply rests on production clusters in Jiangsu and Zhejiang provinces, creating import dependency for North American and European electrical utility-grade ladder manufacturers. Aluminum billet draws from Chinese smelters and Canadian primary production; steel structural components source from domestic mills in Ohio and Pennsylvania. Single-source vulnerability concentrates in dielectric-grade resin systems. Distribution runs through national rental networks, contractor supply houses, and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial lift ladders hinges on carbon fiber hybrid platform adoption for aviation maintenance, where weight-critical specifications justify premium positioning above aluminum alternatives.
For Market Incumbents: To counter carbon fiber hybrid disruption from aerospace composite suppliers, aluminum specialists should deepen backward integration into 6061-T6 billet casting and secure captive supply of dielectric-grade fiberglass resin systems. CE certification investment in European notified bodies creates switching costs against Asian competitors. For New Entrants and Emerging Players: RFID-enabled fleet telemetry systems offer a technology-first wedge into Amazon and DHL supply chain divisions, where connected asset specifications are hardening into procurement mandates. Target Indian warehouse infrastructure buildout under PLI scheme incentives for fleet-scale first-mover positioning. Pursue rental channel partnerships rather than direct sales to bypass incumbent distributor lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap specialists lack CE conformity assessment capabilities and face four-to-six month product launch delays. Long-term viability favors vertically integrated manufacturers with pre-certified coating chains under REACH amendments. Acquisition target archetype: German automotive corridor suppliers with BMW and Bosch facility relationships. Watch OSHA state-level warehouse safety legislation adoption as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Hybrid Platform Development | Aviation maintenance operations at Frankfurt Airport and Dallas-Fort Worth International pilot CFRP configurations below 35 pounds transport weight. |
| CE Conformity Assessment Investment | Notified body certification filters non-compliant suppliers from EU Machinery Directive 2006/42/EC market access. |
| Rental Channel Partnership Expansion | Equipment-as-a-service models through national networks displace direct purchase patterns among mid-sized contractors. |
| RFID Fleet Telemetry Integration | Amazon and DHL supply chain divisions specify usage-tracking compatibility for centralized maintenance scheduling. |
| Indian Manufacturing Footprint Establishment | Cold chain and e-commerce fulfillment investments under PLI scheme generate first-time fleet-scale demand in Maharashtra and Karnataka corridors. |
Research Methodology
Multiple input streams — primary interviews with maintenance directors and plant engineers at BMW and Bosch facilities, procurement leads at third-party logistics operators, and aftermarket service heads at national rental networks — were reconciled against customs and trade data, SEC 10-K filings from diversified industrial conglomerates, and OSHA enforcement records. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Historical shipment patterns were cross-referenced against panel input from industry stakeholders across the projection horizon. Segmentation dimensions modeled include product type, material specification, end-use environment, and safety feature tier. CAGRs were derived from replacement cycle analysis and warehouse automation investment trajectories. Forecast inputs incorporated aluminum LME price scenarios and CE certification timeline assumptions.
The model holds under stable regulatory enforcement intensity; deviation in OSHA state-level adoption timelines or REACH amendment acceleration would shift replacement demand patterns. A small set of named triggers — aluminum alloy price volatility spikes, dielectric-grade fiberglass supply disruptions, and warehouse automation protocol standardization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Belt Weigh Feeder Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Vibrating Screen Market
Material Handling Equipment
Cut-To-Length Line Systems Market
Material Handling Equipment
Apron Feeder Market
Material Handling Equipment
Linear Slide Units Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Global Telescopic Boom Forklift Truck Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Trash Chute Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Europe Forklift Truck Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Industrial Counterweights Market