
 Magnetic Sweepers Market | 2026-2036
Magnetic Sweepers Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Sweepers Market Analytics
OSHA workplace safety enforcement is consolidating compliance budgets around debris-control equipment across American manufacturing zones. Industrial Magnetics leverages its captive magnet supply chain to sustain pricing stability in the towed sweeper segment. Shields Magnetics anchors its position through specialized road maintenance attachments engineered for municipal fleet compatibility. Bunting Magnetics competes by extending its magnetic circuit designs into high-temperature foundry applications where foreign object damage risks escalate.
Magnetic sweepers are industrial cleaning devices employing permanent or electromagnet arrays—typically constructed from ceramic ferrite or rare-earth neodymium compositions rated between 1,000 and 12,000 gauss—to attract and retain ferrous debris from floors, roadways, and production surfaces. These systems prevent tire punctures, equipment damage, and personnel injuries across facilities where machining, demolition, or material handling generates metallic waste. The handheld category dominates unit volumes due to low capital thresholds and broad contractor accessibility, while ride-on configurations capture disproportionate margin pools through integrated dust suppression and hydraulic lift mechanisms. Warehouses represent the fastest-growing application vector as e-commerce fulfillment centers impose stricter foreign object control protocols to protect automated guided vehicle fleets.
The EPA regulates magnet manufacturing waste streams under Resource Conservation and Recovery Act provisions, elevating compliance costs for domestic producers. ISO 9001 quality management certification functions as a de facto market access requirement for municipal procurement tenders across North American and European jurisdictions. Stakeholders must monitor rare-earth magnet price volatility and corresponding shifts in sweeper magnetic circuit design philosophy.
Market Dynamics
Neodymium supply concentration in China is forcing magnetic sweeper manufacturers toward alternative magnet compositions and redesigned magnetic circuits, compressing margins for rare-earth-dependent product lines while opening design space for ferrite-based systems.
Growth Catalysts
- OSHA workplace debris standards:Updated enforcement protocols in the United States mandate systematic ferrous waste removal from active construction zones, consolidating compliance budgets around towed and ride-on sweeper procurement.
- Automated guided vehicle fleet protection:E-commerce fulfillment centers across North America and Europe impose foreign object damage protocols, creating specification pull for high-gauss handheld and walk-behind units in warehouse aisles.
- Great Lakes industrial corridor replacement cycles:Concentrated automotive and aerospace maintenance clusters in Michigan, Ohio, and Indiana drive systematic equipment refresh programs for magnetic debris control systems.
Market Restraints
- Rare-earth magnet price volatility:Neodymium oxide supply disruptions originating from Chinese export quotas elevate raw material uncertainty, compressing gross margins for manufacturers without captive magnet sourcing.
- EPA Resource Conservation and Recovery Act compliance:Magnet manufacturing waste stream regulations elevate domestic production costs, disadvantaging US-based fabricators against imported assemblies from jurisdictions with lighter environmental enforcement.
- Ferrite magnetic performance ceiling:Ceramic ferrite compositions top out at approximately 4,000 gauss, limiting their deployment in high-lift applications where neodymium arrays above 10,000 gauss remain technically necessary.
Strategic Opportunities
- India warehouse infrastructure buildout:PLI scheme incentives for logistics and e-commerce fulfillment create virgin demand territory for foreign object control equipment in automated distribution centers.
- Electromagnet-hydraulic convergence:Integration of switchable electromagnet arrays with hydraulic lift mechanisms enables load-release automation, opening premium positioning for ride-on sweeper variants in municipal fleet tenders.
- ISO 9001 certification arbitrage:Quality management certification functions as a de facto municipal procurement gatekeeper across North America and Europe, creating margin differentiation for certified versus uncertified suppliers.
Industry Challenges
- Magnetic circuit design talent scarcity:Specialized expertise in finite element analysis for flux density optimization resides with a narrow cohort of aging engineers, constraining product development velocity for mid-tier manufacturers.
- Foundry application thermal tolerance:High-temperature environments above 150°C degrade standard neodymium grades, requiring costly dysprosium doping or complete electromagnetic redesign for steel mill and casting floor deployments.
- Municipal procurement cycle elongation:Budget approval timelines for road maintenance equipment in US city and county governments extend 18-24 months, compressing cash conversion for sweeper vendors dependent on public sector revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Sweepers Market |
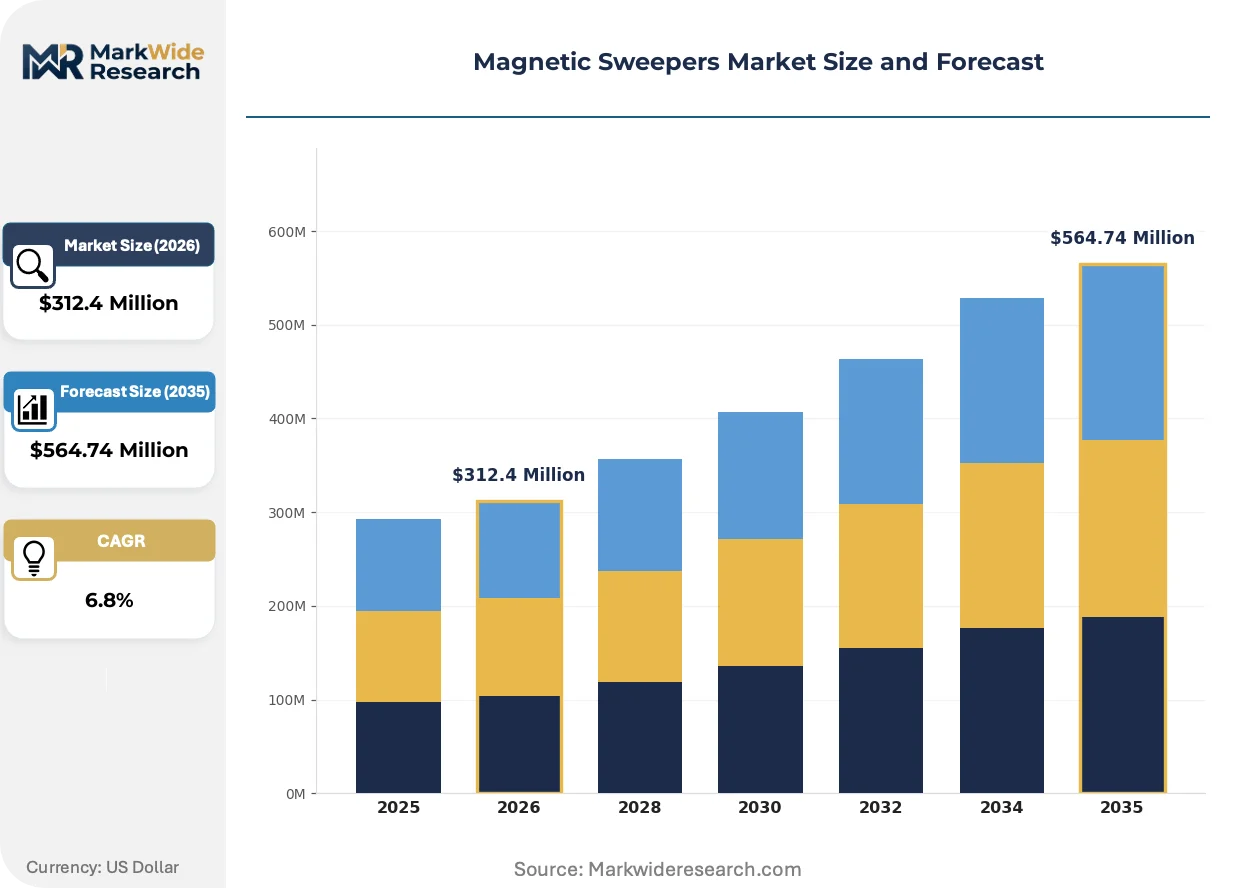
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Towed, Ride-On, Industrial Application: Construction Sites, Parking Lots, Warehouses, Road Maintenance End User: Contractors, Facility Managers, Municipalities, Retailers Deployment: On-Site, Off-Site, Rental, Purchase |
| Companies Covered | Master Magnetics, Industrial Magnetics, Magnetool, Goudsmit Magnetics, Monroe, Eriez, Bunting Magnetics, Shields Magnetics, Ohio Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Sweepers Market Evolving Landscape
Active redesign of magnetic circuit architectures is compressing the performance gap between rare-earth and ceramic systems, while regulatory enforcement tightens debris-control mandates across industrial jurisdictions.
Electromagnetic sweeper technology is electrifying municipal and industrial procurement specifications through switchable flux control that eliminates manual debris release. German road maintenance fleets are adopting these systems at accelerated pace to reduce operator strain during continuous debris collection cycles. This capability is electrifying competitive positioning by enabling automated dump mechanisms that integrate with existing hydraulic lift infrastructure.
REACH substance restriction pre-notifications are elevating compliance documentation burdens for European magnetic sweeper distributors sourcing neodymium-containing assemblies from non-EU fabricators. Industrial buyers in Germany and France now demand full material substance declarations upstream of purchase authorization. The towed sweeper segment bears disproportionate impact, with municipal tender specifications increasingly mandating RoHS-compliant magnetic circuit documentation.
Buyer preference is rotating toward certified-refurbished equipment channels as capital expenditure scrutiny intensifies across North American manufacturing facilities. Third-party remanufacturers with ISO 9001 credentials are capturing share from OEM new-equipment sales in the handheld and walk-behind categories. This pattern concentrates most visibly in the US Great Lakes automotive supplier base, where production engineering teams prioritize operational expenditure reduction over capital deployment.
Magnetic Sweepers Market Segmentation
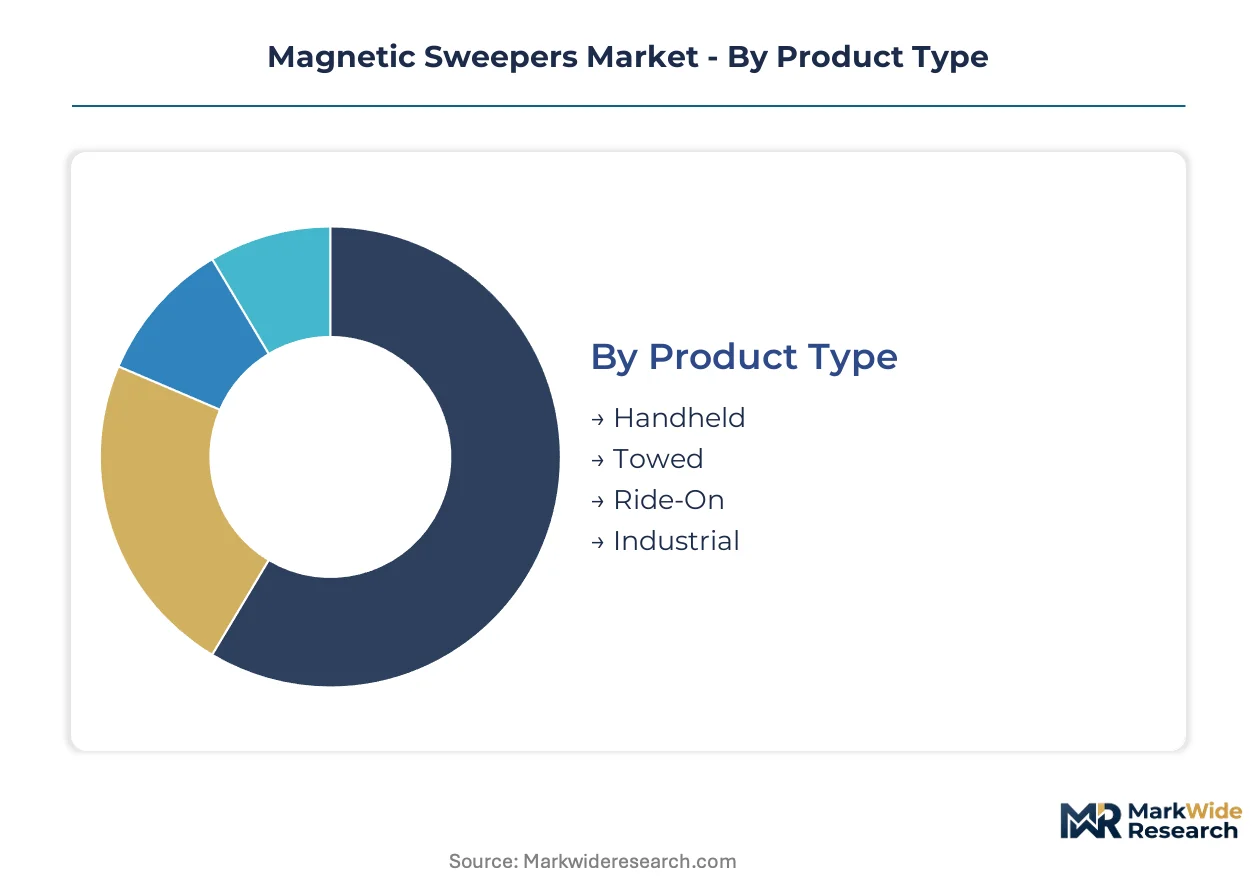
Magnetic sweeper procurement patterns diverge sharply across capital-intensity thresholds, with ride-on systems demanding fleet infrastructure while handheld units penetrate through distributor networks. The segmentation architecture reveals how compliance mandates and automation trends reshape equipment specifications across end-use environments.
Product Type:
Capital requirements stratify dramatically across product architectures, from sub-thousand-dollar handheld units to six-figure ride-on platforms with integrated hydraulic systems.
- Handheld:Compact permanent-magnet assemblies rated 1,000–3,000 gauss dominate contractor tool inventories due to minimal capital barriers and immediate deployment flexibility. Demand concentrates in US construction zones where OSHA debris enforcement mandates systematic ferrous waste removal from active work areas.
- Ride-On:Self-propelled platforms incorporating neodymium arrays above 10,000 gauss, hydraulic lift mechanisms, and dust suppression systems command premium positioning. Great Lakes automotive maintenance clusters in Michigan and Ohio drive replacement cycles as aging fleets face stricter foreign object damage protocols.
- Towed:Trailer-mounted magnetic bars engineered for municipal road maintenance compatibility attach to standard fleet vehicles. German procurement specifications increasingly favor switchable electromagnet variants to reduce operator strain during continuous collection cycles.
- Industrial:Fixed-installation electromagnetic systems with automated debris release mechanisms serve high-volume foundry and steel mill floors. Thermal tolerance above 150°C requires dysprosium-doped neodymium or complete electromagnetic redesign.
Handheld sweepers absorb the bulk of installed capacity; ride-on configurations are expanding most quickly.
Application:
Site-specific debris generation rates and regulatory exposure determine equipment specification intensity across deployment environments.
- Construction Sites:Active demolition and machining operations generate concentrated ferrous waste streams requiring systematic removal protocols. US site managers face escalating OSHA enforcement pressure.
- Parking Lots:Surface-area coverage requirements favor towed sweepers with wide magnetic bar spans. Municipal fleet tenders in Japan specify ferrite-based systems amid neodymium supply constraints.
- Warehouses:Automated guided vehicle fleet protection protocols in North American e-commerce fulfillment centers create specification pull for high-gauss handheld and walk-behind units. ISO 9001 certification functions as a de facto procurement gatekeeper.
- Road Maintenance:Continuous debris collection cycles strain operator ergonomics, accelerating German adoption of electromagnetic-hydraulic convergence with automated dump mechanisms.
Construction sites retain the largest equipment base; warehouse applications are climbing the fastest.
End User:
Procurement authority structures and budget cycle timing differentiate purchasing behavior across organizational types.
- Contractors:Price-sensitive equipment acquisition through distributor networks prioritizes handheld and towed categories with rapid depreciation schedules. Capital expenditure scrutiny intensifies refurbishment channel preference.
- Facility Managers:Operational expenditure frameworks in automotive and aerospace maintenance clusters favor systematic replacement programs. Great Lakes corridor facilities impose foreign object control protocols protecting production equipment.
- Municipalities:Extended 18–24 month budget approval timelines compress cash conversion for vendors. Road maintenance specifications increasingly mandate RoHS-compliant magnetic circuit documentation.
- Retailers:E-commerce fulfillment center operators specify warehouse-grade sweepers to protect automated guided vehicle fleets from tire puncture damage. India PLI scheme incentives for logistics infrastructure create virgin demand territory.
Contractors deploy the widest unit count; facility managers are gaining share fastest.
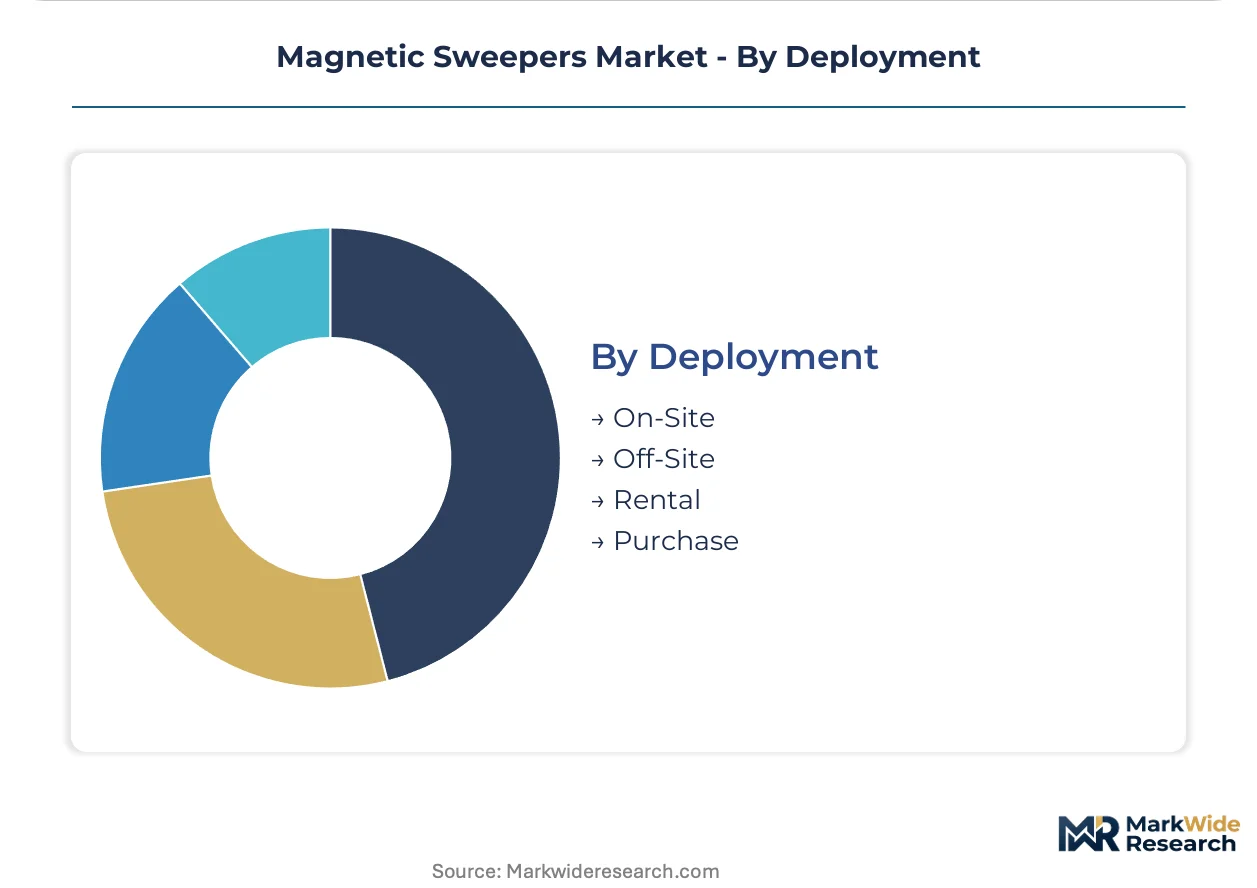
Deployment:
Asset ownership models reflect capital availability, utilization predictability, and maintenance capability across user segments.
- On-Site:Permanent installation at fixed industrial facilities with continuous debris generation. Foundry applications require thermal-tolerant magnetic circuits.
- Off-Site:Mobile deployment patterns serving multiple client locations characterize contractor equipment utilization. Towed sweepers dominate this mobility requirement.
- Rental:Third-party equipment providers capture share from capital-constrained users through short-term access models. ISO 9001-certified remanufacturers penetrate this channel.
- Purchase:Direct acquisition predominates among municipalities and large facility operators with predictable utilization and in-house maintenance capabilities. Electromagnetic-hydraulic systems command premium positioning.
Purchase transactions anchor revenue concentration; rental channels are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and China's coastal manufacturing belts are concentrating new magnetic sweeper demand as warehouse infrastructure expands. Tax incentives in these zones attract logistics operators specifying foreign object control equipment. Regional procurement patterns diverge sharply based on magnet supply chain access and regulatory enforcement intensity.
United States
OSHA workplace debris enforcement drives systematic sweeper procurement across active construction zones in Texas and Florida. The EPA Resource Conservation and Recovery Act elevates compliance costs for domestic magnet fabricators. Great Lakes automotive clusters in Michigan and Ohio impose foreign object damage protocols triggering replacement cycles for aging equipment.
Germany
Municipal road maintenance fleets specify switchable electromagnet systems to reduce operator strain during continuous collection cycles. REACH substance restriction pre-notifications burden distributors sourcing neodymium-containing assemblies from non-EU fabricators. Industrial buyers in Bavaria and North Rhine-Westphalia now demand full material substance declarations upstream of purchase authorization.
Japan
Neodymium supply constraints are shifting procurement patterns toward ferrite-based systems for parking lot and road maintenance applications. METI industrial standards shape equipment specifications for high-gauss applications where ceramic compositions prove inadequate. Manufacturing clusters in Aichi Prefecture and the Kansai region prioritize operational expenditure reduction through certified-refurbished equipment channels.
India
PLI scheme incentives for logistics and e-commerce fulfillment create virgin demand territory for foreign object control equipment in automated distribution centers. BIS quality certification functions as a de facto procurement gatekeeper for municipal and industrial tenders. Warehouse infrastructure buildout concentrates in Maharashtra and Karnataka where fulfillment center operators protect automated guided vehicle fleets.
China
Neodymium oxide supply concentration forces magnetic sweeper manufacturers toward alternative magnet compositions and redesigned magnetic circuits. MEE environmental regulations on magnet manufacturing waste streams elevate production compliance burdens. Yangtze River Delta industrial corridors drive specification pull for high-lift electromagnetic systems in steel mill and foundry applications.
Magnetic Sweepers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across product tiers, creating a bifurcated market structure where scale-driven manufacturers anchor municipal procurement while niche fabricators capture premium industrial segments. The vendor base stratifies into three strategic archetypes: captive magnet producers leveraging upstream supply control, electromagnetic technology specialists, and regional fabrication houses serving price-sensitive contractor channels. Competitive moves concentrate on backward integration into magnet sourcing and ISO 9001 certification acquisition to unlock municipal tender access.
Among North American fabricators, Industrial Magnetics and Bunting Magnetics exemplify the captive-supply archetype, while Shields Magnetics occupies a position within the specialized road maintenance attachment tier. Goudsmit Magnetics represents European electromagnetic technology positioning. These companies anchor competitive dynamics through divergent magnet sourcing strategies and certification-based differentiation in public sector procurement channels.
| Leading Market Players |
|---|
| Master Magnetics |
| Industrial Magnetics |
| Magnetool |
| Goudsmit Magnetics |
| Monroe |
| Eriez |
| Bunting Magnetics |
| Shields Magnetics |
| Ohio Magnetics |
| Others |
Value Network & Pricing Analysis
Neodymium oxide spot pricing volatility transmits downstream through three distinct equipment tiers, compressing margins for rare-earth-dependent ride-on configurations while ferrite-based handheld units absorb procurement shifts from price-sensitive contractor segments.
Pricing Analysis
Short lead-time premiums of 15-20% separate certified inventory from standard production slots across municipal procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 certification status, magnet composition grade, and after-sales service bundling. Pricing pressure stems from Chinese export quota uncertainty forcing manufacturers toward dysprosium-doped neodymium or electromagnetic redesigns. Contractors exhibit highest price sensitivity, while Great Lakes automotive facility managers prioritize thermal tolerance specifications over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive and aerospace clusters, while distributor networks serve fragmented contractor procurement. Magnet raw materials concentrate in China, with secondary processing in Germany and Japan. Ceramic ferrite and neodymium ingot dependencies anchor cost structures, alongside hydraulic lift mechanism sourcing from Italian and US suppliers. Single-source vulnerability in rare-earth oxide refining creates tariff exposure through export control unpredictability. Distribution runs through regional fabrication houses for price-sensitive segments and captive-supply manufacturers for premium municipal tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA workplace debris enforcement functions as a cost-of-compliance barrier, elevating capital requirements for certification-holding incumbents while squeezing uncertified competitors from municipal tender participation.
For Market Incumbents: Deepen backward integration into magnet sourcing to insulate margin structures from Chinese export quota volatility. Secure ISO 9001 credentials across all production facilities to lock out uncertified rivals from 18-24 month municipal procurement cycles. Expand electromagnetic-hydraulic convergence R&D to capture German road maintenance fleet specifications ahead of ferrite performance ceiling constraints. For New Entrants and Emerging Players: Electromagnetic switchability technology offers a technology-first wedge against permanent-magnet incumbents in high-temperature foundry applications above 150°C. Target India's PLI-subsidized warehouse infrastructure buildout where virgin demand lacks established supplier relationships. Pursue certified-refurbishment channel partnerships with ISO-credentialed remanufacturers to bypass capital-intensive OEM positioning. For Investors and Strategic Acquirers: German municipal fleet adoption of electromagnet-hydraulic systems is the leading indicator that premium ride-on configurations will displace towed segments in European specifications. Five-to-ten year viability favors captive-supply manufacturers with in-house magnet production and thermal-tolerant circuit design capabilities. Monitor REACH substance restriction pre-notification timelines as inflection signals for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Sourcing | Captive neodymium supply insulates margins from Chinese export quota volatility. |
| ISO 9001 Certification Acquisition | Quality credentials unlock municipal tender access across North American jurisdictions. |
| Electromagnetic-Hydraulic Convergence | Switchable flux arrays capture German road maintenance fleet replacement cycles. |
| India Warehouse Infrastructure Entry | PLI scheme incentives create virgin demand territory for automated distribution centers. |
| Certified-Refurbishment Channel Partnership | ISO-credentialed remanufacturers penetrate capital-constrained contractor segments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant engineers, municipal procurement officers, aftermarket service heads, and distribution channel partners. OSHA enforcement bulletins, EPA Resource Conservation and Recovery Act compliance databases, and ISO certification registries provided regulatory tracking. Bottom-up equipment unit estimates triangulated against top-down construction spending and warehouse automation capex disclosures.
Data-stream reconciliation across product type, application environment, end-user procurement authority, and regional regulatory cluster produced volume and value outputs. CAGRs derived from segment-level growth drivers including OSHA mandate expansion, e-commerce fulfillment center buildout, and automotive cluster replacement cycles. Magnet composition mix shifts and thermal tolerance specification trends informed equipment tier trajectories.
Several conditions sit outside the modeled scope, including unforeseen rare-earth export embargoes, abrupt EPA waste stream regulation tightening, and municipal budget freeze scenarios. Forecasts reflect base-case assumptions regarding OSHA enforcement continuity and PLI scheme incentive persistence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Global Underground Mining Vehicles Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Hydraulic Drilling Rig Market