
 Rotary Drilling Rig Market | 2026-2036
Rotary Drilling Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Drilling Rig Market Outlook
Software-defined rig automation and predictive maintenance subscriptions is consolidating vendor-customer relationships beyond hardware transactions. Schlumberger leverages its digital drilling platform to anchor long-term service contracts across offshore fleets. Baker Hughes competes through integrated well construction solutions that bundle top-drive systems with real-time analytics. Nabors Industries specializes in automated land rig deployments, sustaining contract density in North American shale basins.
A rotary drilling rig is a mechanized assembly that rotates drill pipe and bit to bore cylindrical holes into subsurface formations, typically achieving depths from hundreds to tens of thousands of feet depending on mast configuration and power rating. Its primary purpose is to create wellbores for hydrocarbon extraction, mineral recovery, or geothermal energy access. Land rigs occupy the largest installed base globally, though offshore rigs command disproportionate margin pools due to technical complexity and day-rate premiums. Top drive technology leads newbuild specifications, displacing legacy rotary table configurations across both jack-up and deepwater floaters. Mining applications represent a growing secondary demand channel as mineral exploration intensifies for copper and lithium.
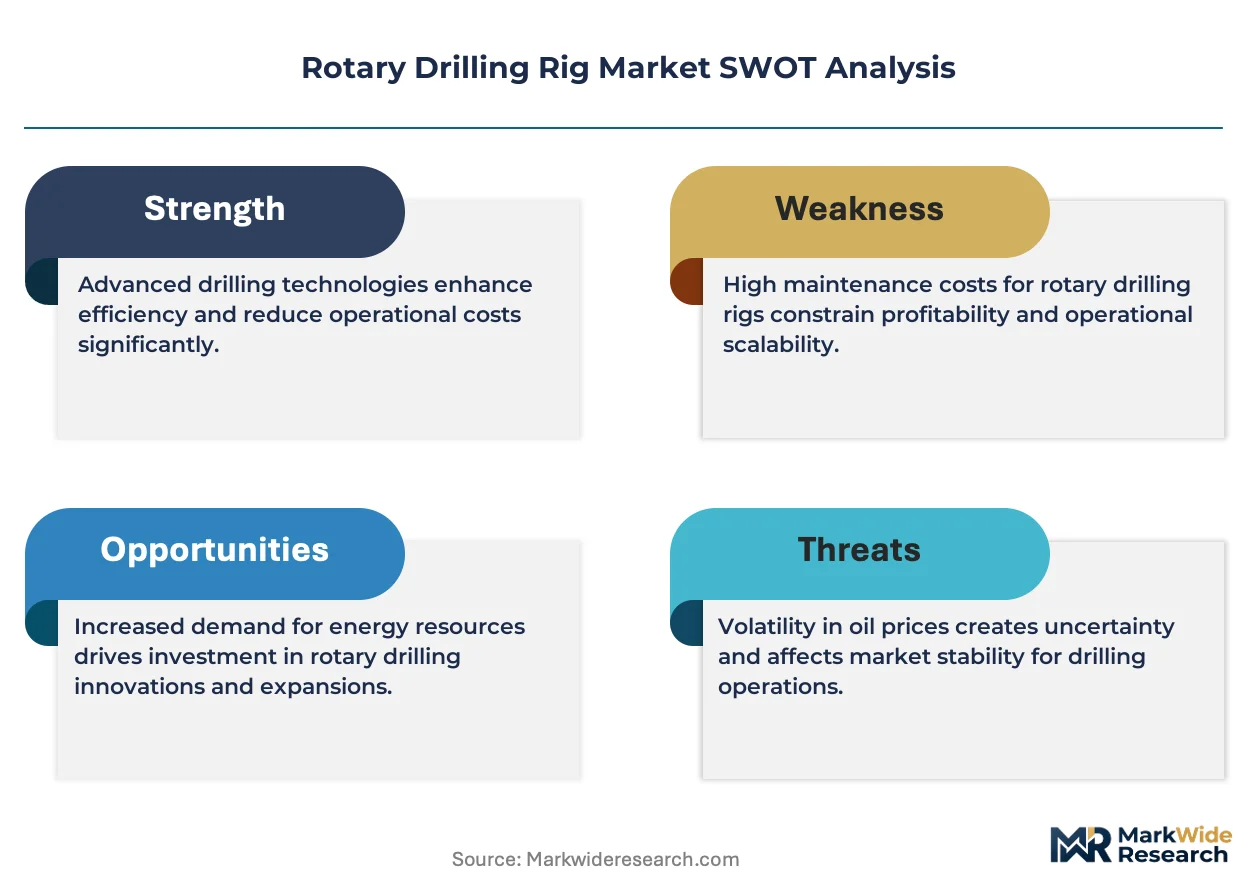
API standards govern blowout preventer certification and drilling equipment ratings across US jurisdictions, while the EPA regulates emissions from diesel-powered rig engines through Tier 4 compliance mandates. Offshore operations face additional scrutiny from BSEE well control rules, forcing capital allocation toward dual-activity systems and closed-loop mud handling. Stakeholders must weigh the payback period of automation retrofit packages against the operational risk of retaining mechanically intensive legacy fleets in an environment of tightening safety enforcement.
Market Dynamics
API blowout preventer certification tightening is forcing fleet-wide hardware refresh cycles across offshore contractors, compressing payback timelines for automation retrofits and redrawing vendor-customer contracting relationships around long-term service agreements rather than equipment sales alone.
Growth Catalysts
- Deepwater Day-Rate Premiums:US Gulf Coast operators command sustained pricing power for seventh-generation drillships with dual-activity configurations, incentivizing newbuild investment despite capital intensity.
- Tier 4 EPA Compliance:Diesel engine retrofit mandates on land rigs accelerate replacement demand in North American shale basins as legacy fleets face operational restrictions.
- Copper-Lithium Exploration:Mining sector rig utilization is expanding into Chilean and Australian hard-rock deposits, diversifying revenue streams beyond hydrocarbon extraction.
Market Restraints
- Steel Input Volatility:Mast and derrick fabrication costs fluctuate with alloy pricing, squeezing fixed-price newbuild margins for Korean and Singaporean yards.
- Top-Drive Supplier Concentration:Critical power transmission components source from a narrow base of European and North American specialists, creating single-source vulnerability.
- Geothermal Technical Ceiling:Ultra-high temperature formations beyond 300°C exceed current elastomer and electronics specifications, limiting addressable reservoir depth.
Strategic Opportunities
- Brazil Pre-Salt Expansion:Petrobras development plans in the Santos Basin require additional harsh-environment floaters, opening fleet deployment contracts for contractors with BSEE-equivalent safety systems.
- Geothermal District Heating:European municipal energy projects in Germany and the Netherlands create demand for smaller-footprint land rigs with closed-loop mud systems.
- Digital Twin Convergence:Integration of physics-based modeling with real-time sensor streams enables predictive maintenance subscriptions, anchoring recurring revenue alongside hardware.
Industry Challenges
- Automation Technician Scarcity:Mechatronics specialists capable of servicing integrated top-drive and robotics systems command wage premiums that inflate operating cost structures.
- Dual-Certification Timelines:Simultaneous API and BSEE approval processes for modified blowout preventer stacks extend commissioning windows by 4-8 months on average.
- Legacy Fleet Integration:Retrofitting mechanically intensive rotary table rigs with automated pipe handling requires structural mast reinforcement incompatible with original engineering specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Drilling Rig Market |
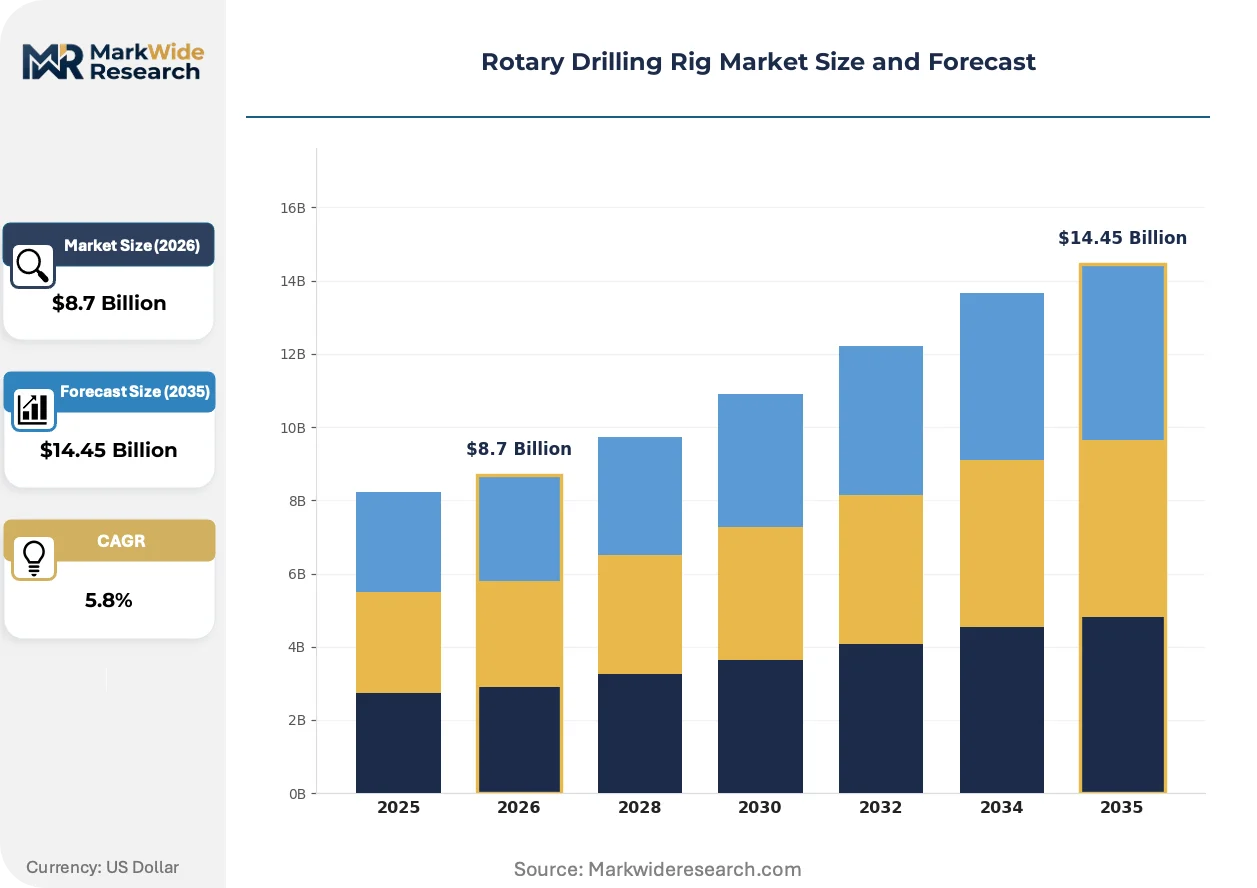
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Land Rigs, Offshore Rigs, Modular Rigs, Portable Rigs Application: Oil Exploration, Natural Gas Extraction, Geothermal Drilling, Mining End User: Energy Companies, Mining Corporations, Government Agencies, Contractors Technology: Rotary Table, Top Drive, Wireline, Downhole |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes, Caterpillar Inc., Sandvik AB, SANY Group Co. Ltd, Nabors Industries, Epiroc AB, Bauer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Drilling Rig Market Strategic Shifts
Software-defined rig control architectures are collapsing the traditional boundary between mechanical hardware and digital service layers, enabling vendors to capture value through recurring analytics subscriptions rather than one-time equipment sales.
Electrified top-drive systems with integrated permanent magnet motors are expanding into deepwater floater newbuilds, replacing conventional AC induction configurations. Offshore contractors in the US Gulf Coast and Brazil pre-salt basins specify these packages for torque precision and maintenance interval extension. The technology is expanding into marginal field economics by reducing fuel consumption and enabling smaller generator footprints.
EPA Tier 4 Final and EU Stage V emission frameworks are mandating aftertreatment systems on land rig power plants, adding capital cost and physical envelope requirements. Engine OEMs respond with integrated selective catalytic reduction and diesel particulate filter packages purpose-built for high-load drilling cycles. US onshore contractors face the steepest compliance timeline, with California CARB rules preceding federal implementation.
Performance-based contracting is displacing day-rate structures in North American shale plays, transferring subsurface risk from operators to drilling contractors. Nabors Industries and Helmerich & Payne pilot footage-based or well-delivery guarantees in the Permian Basin, aligning vendor incentives with operator production targets. This model concentrates in pad drilling developments where geological consistency supports predictable performance benchmarking.
Rotary Drilling Rig Market Segmentation
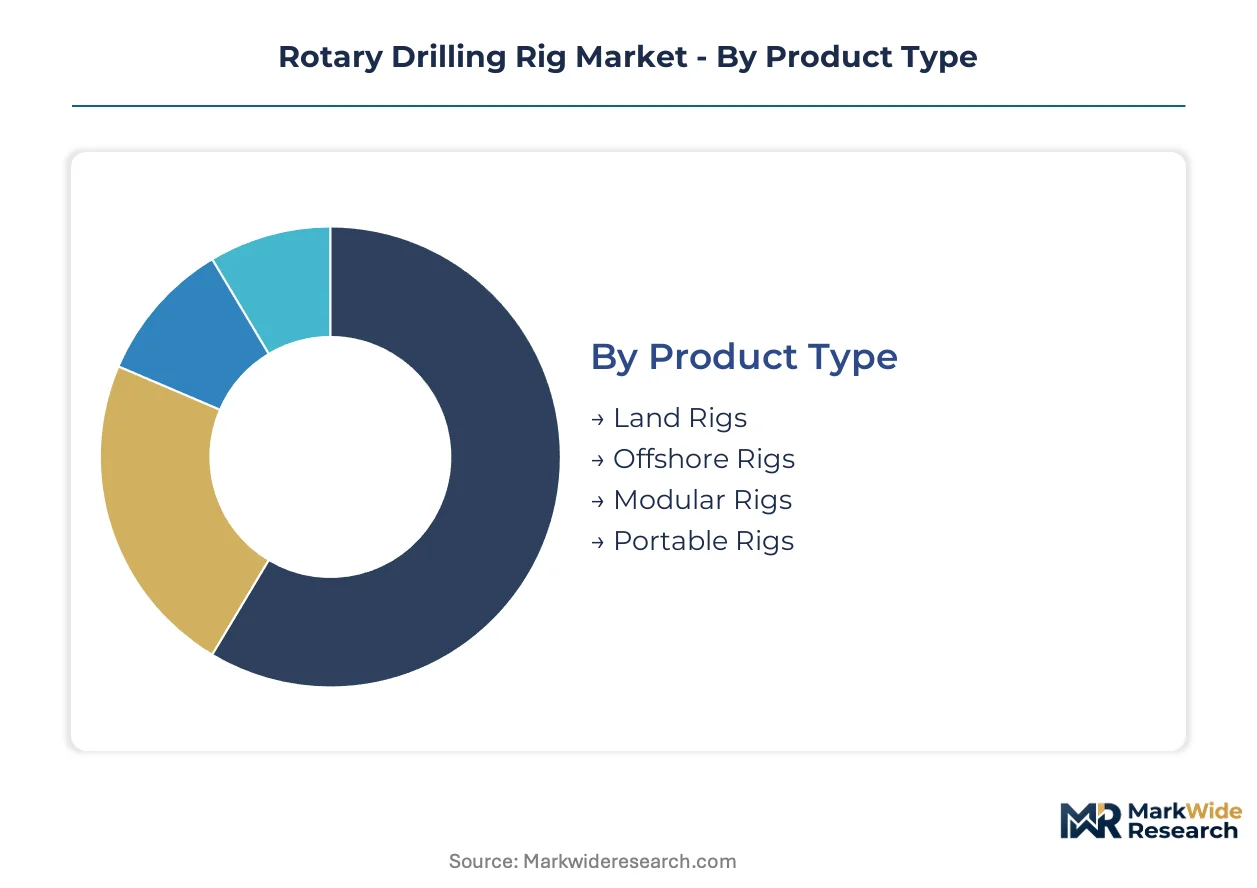
Segmentation in rotary drilling rigs reveals how capital allocation, regulatory exposure, and technical specifications diverge across operating environments. Buyers select configurations based on mobility requirements, water depth, and automation integration rather than generic power ratings alone.
Product Type:
Capital intensity and mobility requirements drive buyer selection more than nominal depth capacity.
- Land Rigs:Mast and substructure assemblies mounted on skids or walking systems for multi-well pad drilling. Demand concentrates in Permian and Bakken shale basins where contractors prioritize rapid rig-up times and Tier 4 engine compliance.
- Offshore Rigs:Jack-up platforms and drillships engineered for water depths exceeding 10,000 feet with dynamic positioning. US Gulf Coast deepwater projects command premium day-rates for dual-activity configurations that reduce flat time between operations.
- Modular Rigs:Component-based assemblies designed for helicopter transport or restricted-access terrain. Chilean copper exploration programs favor these systems for high-altitude Andean deployments where road infrastructure is absent.
- Portable Rigs:Compact mast and power packages mounted on truck or trailer chassis for wildcat and workover applications. Australian mineral exploration contractors specify these for rapid relocation between tenements.
Volume sits with Land Rigs; growth tilts toward Offshore Rigs.
Application:
Reservoir characteristics and commodity pricing cycles determine specification intensity across use cases.
- Oil Exploration:Extended-reach horizontal drilling in unconventional formations requiring high-torque top-drive systems and managed pressure control. Brazilian pre-salt carbonate formations drive demand for harsh-environment floaters with 15,000 psi well control ratings.
- Natural Gas Extraction:Dry gas and liquids-rich shale development favoring pad-optimized land rigs with automated pipe handling. Appalachian Basin operators specify these configurations to minimize surface footprint and accelerate multi-well sequences.
- Geothermal Drilling:High-temperature hard-rock penetration for electricity generation and district heating. German municipal projects in the Upper Rhine Graben require closed-loop mud systems to manage thermal degradation of drilling fluids.
- Mining:Core recovery and blasthole drilling for copper, lithium, and rare earth exploration. Chilean and Australian hard-rock deposits are expanding rig utilization beyond hydrocarbon applications.
Revenue concentrates in Oil Exploration; steepest expansion trajectory appears in Geothermal Drilling.
End User:
Contracting structure and risk allocation preferences separate procurement behavior across buyer types.
- Energy Companies:Integrated oil majors and independents that own or bareboat-charter rigs for proprietary drilling programs. US Gulf Coast operators favor long-term service agreements with embedded predictive maintenance subscriptions.
- Mining Corporations:Diversified resource extraction firms expanding exploration budgets for energy transition minerals. Australian and Chilean copper-lithium developers are establishing captive drilling capabilities.
- Government Agencies:State-owned enterprises and geological surveys conducting strategic resource assessment. Brazil's Petrobras dominates pre-salt development through direct fleet ownership and local content mandates.
- Contractors:Independent drilling service providers supplying rigs and crews on day-rate or performance-based contracts. North American shale specialists are piloting footage-based pricing to align operator and contractor incentives.
Contractor procurement dominates fleet utilization; Energy Companies are expanding fastest through integrated service models.
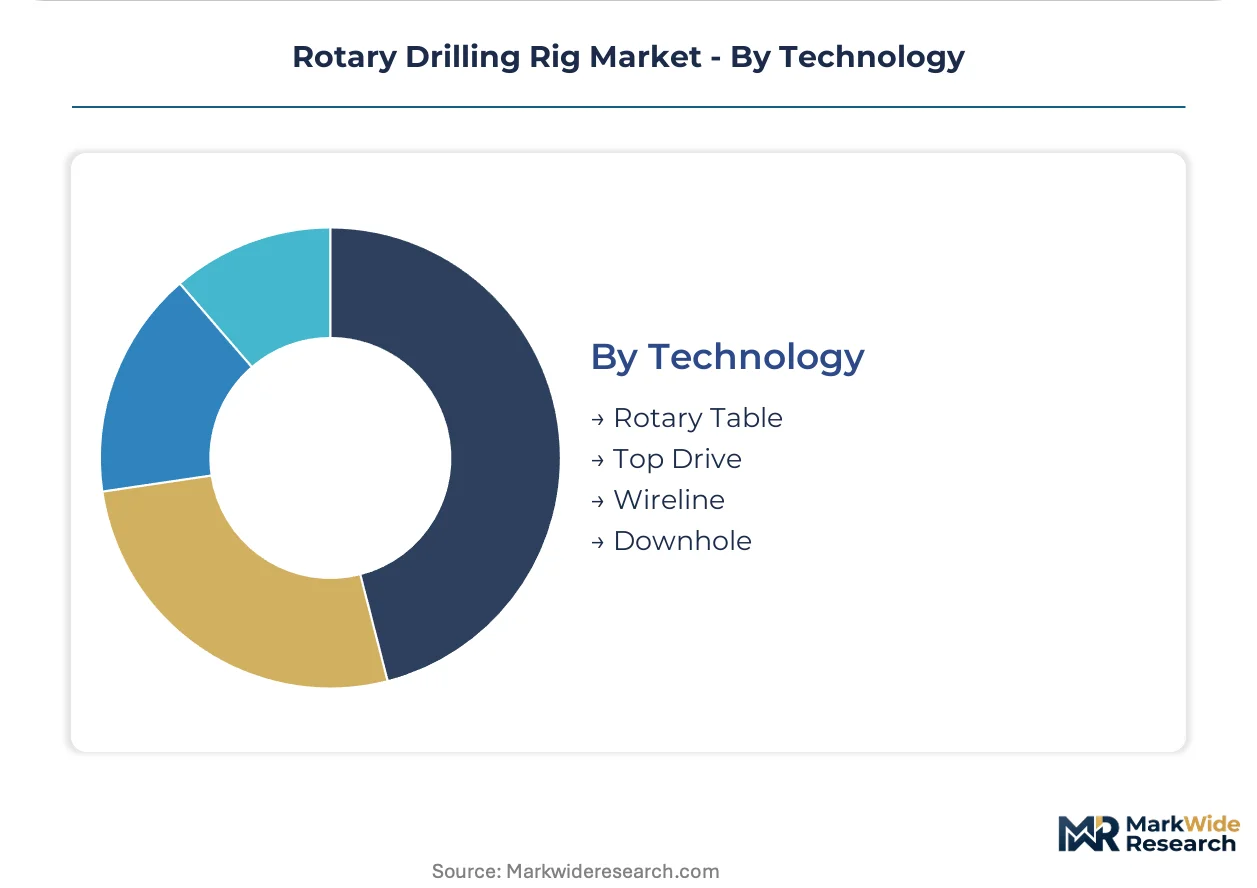
Technology:
Power transmission architecture determines maintenance intervals, torque precision, and automation compatibility.
- Rotary Table:Legacy mechanical systems rotating drillstring through kelly bushing and master bushing assemblies. Declining share in newbuild specifications due to limited automation integration and extended connection times.
- Top Drive:Electric or hydraulic motors suspended from mast crown providing continuous rotation and automated pipe handling. Offshore newbuilds in the US Gulf Coast and Brazil specify permanent magnet variants for torque precision and fuel efficiency.
- Wireline:Cable-conveyed logging and intervention systems for formation evaluation and well completion. Deepwater floaters integrate these with dual-activity derricks to eliminate rig downtime for data acquisition.
- Downhole:Measurement-while-drilling and logging-while-drilling tools embedded in bottomhole assemblies. Real-time telemetry enables geosteering in complex shale reservoirs where lateral placement determines production rates.
Installed base remains with Rotary Table; specification momentum favors Top Drive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors global rig demand through its concentration of offshore drilling contractors and equipment fabricators along the Gulf Coast corridor. The metropolitan area hosts engineering headquarters for deepwater fleet operators and top-drive system integrators supplying seventh-generation drillships.
United States
US Gulf Coast deepwater projects drive specification intensity for dual-activity drillships with 15,000 psi well control ratings. EPA Tier 4 Final mandates accelerate land rig replacement cycles in Permian and Bakken shale basins. Houston-Galveston corridor contractors dominate offshore fleet management and predictive maintenance service deployment.
Brazil
Petrobras pre-salt development in the Santos Basin requires harsh-environment floaters with BSEE-equivalent safety certification. ANP local content mandates force foreign contractors into joint ventures with Brazilian fabricators. Macaé industrial cluster hosts subsea equipment assembly yards serving pre-salt drilling programs.
Norway
North Sea electrification targets spur demand for battery-hybrid offshore rigs with shore power connectivity. Petroleum Safety Authority well integrity rules exceed API standards for blowout preventer redundancy. Stavanger-Bergen corridor contractors specialize in harsh-environment jack-ups for Barents Sea frontier drilling.
China
State-owned energy groups expand deepwater fleet capacity for South China Sea gas development. MIIT equipment certification standards govern domestic rig fabrication quality for export markets. Yantai-Qingdao shipbuilding cluster produces jack-up platforms for Middle East and Southeast Asian contractors.
Saudi Arabia
Aramco unconventional gas programs in Jafurah Basin require high-specification land rigs with automated pipe handling. Saudi Standards, Metrology and Quality Organization aligns rig certification with API specifications for contractor qualification. Dhahran-Ras Tanura industrial corridor hosts rig maintenance facilities serving onshore and offshore Arabian Gulf operations.
Rotary Drilling Rig Market Competitive Environment
Capital-heavy rig fabricators compete with asset-light drilling service integrators for value capture across the equipment lifecycle. The vendor base concentrates among integrated oilfield service groups, specialized rig contractors, and industrial equipment conglomerates with energy divisions. Two strategic archetypes dominate: full-service well construction providers bundling hardware with digital subscriptions, and pure-play rig operators leasing automated fleets on performance-based contracts. Competitive moves center on automation retrofit partnerships and predictive maintenance subscription anchoring.
Among US-based integrated service providers, Schlumberger, Halliburton, and Baker Hughes occupy positions spanning equipment manufacturing through real-time drilling analytics. These entities exemplify the convergence archetype collapsing hardware and software boundaries. Specialist rig contractors including Nabors Industries represent the fleet-operator archetype focused on automated land rig deployment and footage-based contracting models. Industrial conglomerates with energy divisions, such as Caterpillar Inc., anchor the power systems supply tier without direct rig assembly exposure.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Caterpillar Inc. |
| Sandvik AB |
| SANY Group Co. Ltd |
| Nabors Industries |
| Epiroc AB |
| Bauer AG |
| Others |
Value Chain & Pricing Dynamics
Alloy steel mast and derrick fabrication costs cascade from Korean and Singaporean shipyards through three distinct pricing tiers, with API-certified blowout preventer packages commanding premiums over standard configurations and unmodified legacy rigs facing accelerated depreciation in regulated basins.
Pricing Analysis
Day-rate and footage-based guarantees anchor contract economics for seventh-generation drillships with dual-activity configurations, while land rig procurement stratifies across premium, standard, and economy tiers based on Tier 4 engine certification status and automation integration depth. Price differentiation rests on BSEE-equivalent safety ratings and predictive maintenance subscription bundling. Cost compression in legacy rotary table retrofits is intensifying because structural mast reinforcement requirements exceed original engineering specifications. North American shale operators exhibit highest price sensitivity, whereas deepwater Gulf Coast contractors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Regional distribution centers in Houston, Singapore, and Stavanger orchestrate hub-and-spoke patterns for top-drive power transmission components, with permanent magnet motor assemblies drawing from European specialist foundries and mast substructures sourcing from Korean fabrication yards. Critical dependencies include high-strength alloy plate, permanent magnet rare earth materials, and elastomer compounds rated for 300°C geothermal thresholds. Single-source vulnerability concentrates in European and North American top-drive specialists. Distribution runs through contractor-owned logistics networks and OEM-authorized service depots positioned near active drilling basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API blowout preventer certification tightening constructs a cost-of-compliance moat where fleet-wide hardware refresh cycles favor capitalized incumbents with established BSEE approval track records over mechanically intensive legacy operators facing operational restrictions.
For Market Incumbents: Lock in long-term service agreements with embedded predictive maintenance subscriptions across offshore fleets, anchoring recurring revenue streams against Schlumberger and Baker Hughes digital platform consolidation. Prioritize backward integration into permanent magnet motor supply through captive partnerships with European specialists. Defensive positioning requires accelerating automation retrofit partnerships before Tier 4 compliance deadlines eliminate legacy land rig competitiveness in North American shale basins. For New Entrants and Emerging Players: The mid-tier pricing gap between premium dual-activity drillships and economy jack-up configurations creates entry space for harsh-environment floater specialists targeting Brazil pre-salt joint venture mandates. Chilean copper-lithium exploration programs and German geothermal district heating projects represent penetrable white-space segments with lower certification barriers than deepwater hydrocarbon basins. Go-to-market execution should emphasize modular rig portability for high-altitude Andean deployments where road infrastructure constraints exclude conventional land rig configurations. For Investors and Strategic Acquirers: Petrobras fleet expansion announcements are the leading indicator that Santos Basin contractor utilization will tighten sufficiently to support day-rate recovery for BSEE-equivalent certified floaters. Long-term viability concentrates in automated land rig operators with footage-based contract pilots and offshore specialists with dual-activity newbuild pipelines. Acquisition screening should prioritize contractors with closed-loop mud system capabilities for geothermal and emission-regulated European markets. Monitor ANP local content enforcement intensity as a signal for joint venture structuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Retrofit Partnership | Extends mechanically intensive fleet economic life ahead of API certification deadlines. |
| Predictive Maintenance Subscription Launch | Anchors recurring revenue alongside hardware through Schlumberger-style digital platform deployment. |
| BSEE-Equivalent Safety Certification Investment | Unlocks Brazil pre-salt contracting opportunities under ANP local content frameworks. |
| Permanent Magnet Motor Backward Integration | Reduces single-source vulnerability to European top-drive specialist concentration. |
| Geothermal District Heating Rig Development | Captures European municipal energy project demand with closed-loop mud system configurations. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with offshore drilling contractors, top-drive system integrators, EPC project managers, and aftermarket service heads. Bottom-up rig fleet inventories from IHS Markit and Baker Hughes rotary rig counts combined with top-down energy capex projections from EIA and IEA sources. SEC 10-K disclosures from Nabors Industries and Helmerich & Payne provided contract structure validation.
Granularity-level modeling disaggregated volume and value outputs across land, offshore, modular, and portable product types; oil exploration, natural gas extraction, geothermal drilling, and mining applications; and rotary table, top drive, wireline, and downhole technology tiers. CAGRs were derived from rig day-rate trajectories, newbuild order backlogs at Korean and Singaporean yards, and EPA Tier 4 compliance-driven replacement cycles across Permian and Bakken basins. Forecast inputs incorporated Petrobras pre-salt development timelines and copper-lithium exploration budget allocations from Australian and Chilean mining corporations.
Inputs from BSEE incident databases and API certification registries were available through the study window; gaps in real-time contractor fleet utilization rates introduce uncertainty bands around offshore day-rate projections. Forecasts reflect documented assumptions regarding ANP local content enforcement intensity and permanent magnet motor supply expansion timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Underground Mining Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Africa Mining Market
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Surface Mining Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mining Locomotive Market